October 2026

From /Hour to 3 Rental Properties and Traveling the World

From $12/Hour to 3 Rental Properties and Traveling the World


Anyone can invest in real estate. You don’t need a fancy degree, a big bank account, or a high-paying job to get started. Arden Williams and his then-girlfriend were both making just $12 an hour when they bought their first house.

How did they do it? They got uncomfortable, slashed their expenses, and threw every extra dollar toward a down payment. Then, they brought that same approach to real estate investing—jumping from one house hack to the next and sharing space with multiple tenants.

These “small” sacrifices paid off in a big way. Today, Arden owns three rental properties, and he just broke ground on his first accessory dwelling unit (ADU). But that’s not even the best part. With this simple strategy, Arden and his wife quit their jobs and used their rental income to fund a year-long trip around the world.

Whatever financial freedom means to you—retiring early, spending more time with family, or traveling the world—real estate makes it possible. And in this episode, Arden will give you a repeatable blueprint for building the life you’ve always wanted.

Henry:
Anyone can invest in real estate. You don’t need a fancy degree, a big bank account, or a high paying job to get started. Arden Williams and his wife were both making just $12 an hour when they bought their first house. So how’d they do it? They got uncomfortable. They slashed their expenses and they threw every extra dollar toward a down payment. Then they brought that same approach to real estate investing, jumping from one house hack to the next and sharing space with multiple tenants. But these small sacrifices paid off in a big way. Today, Arden owns three rental properties and he just broke ground on his first ADU, but that’s not even the best part. With this simple strategy, Arden and his wife quit their jobs and used their rental income to fund a year-long trip around the world. Whatever financial freedom means to you, retiring early, spending more time with family, or following your passion, real estate can make that possible.
And in this episode, Arden will give you a repeatable blueprint for building the life you’ve always wanted. What’s going on, everybody? I’m Henry Washington, co-host of the BiggerPockets Podcast. And today we’re bringing you an investor story with Arden Williams from Wilmington, North Carolina. So let’s jump in. Mr. Arden Williams, welcome to the BiggerPockets Podcast.

Arden:
Thank you. Thank you. I’m honored to be here, honestly. Why

Henry:
Don’t you tell us a little bit about your background and how the heck you got into real estate in the first place?

Arden:
Back in 2017, I graduated college and after college I didn’t really have much of a plan besides all I wanted to do was travel and be outside. Still something I do today. So I ended up getting a job out in Hawaii and worked there for about six months and then somehow found my way to the US Virgin Islands where I ended up moving there with my now wife. And then after COVID, we decided we needed some stability and I ended up getting a job as a firefighter in Wilmington, North Carolina, where I am today. So November of 2021, I was finishing up the fire academy and at the time we were both making like 13, $14 an hour, if that. And me and my wife ended up getting a house and ended up house hacking it with two of my fellow firefighters.

Henry:
Did you purposefully buy that deal as a house hack investment because you had been researching real estate or did you buy a single family and house hack it because that’s what you needed to do to be able to afford a place?

Arden:
Maybe a little bit of both. Back in Hawaii, I found a YouTube video of Brandon riding out buy a house every 10 years, one house every year, and ended up just kind of having it in the back of my mind of like, “That’s a great idea. Should probably look at doing that.” I remember telling my wife about it. I was like, “Hey, we could just get roommates and we’ll save a bunch of money. And if we want to rinse and repeat this, we could and hopefully continue to go and travel and do all the things we love to do.” We were basically breaking even on our mortgage with just our two roommates and it worked out great for us.

Henry:
So there was some intentionality in the kind of home you selected because I assume you planned on keeping it after you moved out.

Arden:
Yeah. So we pretty much only look at three bed, two bath, single family homes in our area for our price point. That’s kind of all we could afford. So we ended up getting it for 285, which was 20K over asking at the time, which we though we were absolutely insane, but it was 2021. It was

Henry:
2021. That was the game

Arden:
You had to play buddy. Yeah, it was the game we had to play.

Henry:
What’s your interest rate though?

Arden:
We got 3%.

Henry:
Okay, that’s awesome. So 285, paid over asking was a little scary. Got a 3% interest rate. Boo. Yeah, that’s amazing.

Arden:
Yeah.

Henry:
What was your mortgage payment?

Arden:
So at the time, I think it was like 1300 something.

Henry:
Did you put 5% down or did you put 20% down?

Arden:
So when we left the US Virgin Islands, we had saved up a good amount for our down payment. So it wasn’t our plan to save it. We were just both, me and my wife are really frugal. So we ended up putting down about $30,000 actually.

Henry:
What were you renting each room out for?

Arden:
So since they were my friends, I was trying not to gouge them on prices, but I think we ended up renting both out for about $700 a month.

Henry:
So you’re living for free essentially?

Arden:
Basically. I think we ended up basically just paying the utilities, insurance, and stuff like that.

Henry:
That’s really cool. That’s the whole point of a house hack. Well, that’s half the point of a house hack. The second part of house hacking is it’s only financially beneficial if you don’t let life creep come in. So in other words, you’ve got to pretend to pay yourself rent or mortgage so that you can actually realize the savings, not just absorb it into your lifestyle. Awesome. So that was 2021. House hack, conventional mortgage, put about 30,000 down, obviously living for free. I assume you moved out and kept it. So what kind of rent does the entire house pull in now that you’re not living there?

Arden:
Yeah, so we actually just lost our original tenants from three years ago after we and my roommates moved out. They just left and so we just got new tenants and they are renting it for 2,450 a month. Our mortgage has gone up to about 1,550 a month with insurance and taxes and hurricane stuff. That’s

Henry:
Still pretty cool. I mean, debt service of 1,550, but that includes taxes and insurance and you’re bringing in 2,450. So that’s a $900 surplus if you count a little bit for maintenance and some expenses. That’s a decent amount of cash flow for a property that you just buy on the MLS that you got to live in for free. I’d say that’s a win.

Arden:
Yeah, we’re very happy with that house.

Henry:
I’m curious to know how that led to your second deal and how different those deals are, but we’re going to dive into that right after the break. All right, we are back on the BiggerPockets podcast. I’m speaking with investor Arden Williams who successfully pulled off one of my favorite strategies, which is the house hack. I house hacked when I first got started. It was absolutely game changing. So I love hearing stories of people house hacking. So you pulled off your successful first one, you bought a three bed, two bath, paid 285. You’re pulling in about 900 bucks a month in cash flow now. Did you do it again or did you change strategies on your next one?

Arden:
We basically did the exact same thing.

Henry:
How long in between them? Was it a year, two years? How long did it take you?

Arden:
So it took us about a year and a half. So we bought November of 2021 and bought our next one in July of 2023.

Henry:
All right. Tell me about this one. Give me the stats. Beds, bath, square footage. What’d you pay?

Arden:
We have a 3-2, 1,100 square foot house downtown Wilmington. Nothing super special. It’s actually 123 years old now. Oh

Henry:
Wow. Yeah.

Arden:
Remodeled, paid 325 for it. I think at the time we had a 6.8% interest rate, but then we did something really silly about a year later, but it came with an additional lot.

Henry:
Oh, dope. I love deals like that.

Arden:
I still feel like I overpaid for that house, but then I have to remind myself that I got a lot basically for free because when we split it, they valued it as we paid like $5,000 for it and there’s lots that size are selling for $70,000 now.

Henry:
Oh yeah.

Arden:
Right now it’s funny because when we got it appraised when we first bought it to when we got the Zestimate now, it’s almost the exact same, but that doesn’t have the allot attached anymore.

Henry:
That’s super cool. Sweet. So you paid a little more for this one, 325, 6.8% interest rate for the time being. Who’d you get to live in the house with you and your wife this time?

Arden:
We had a friend of a friend move in and then we found random one we put up on Zillow and we had them both renting from us. I think one was $800 a month and the other one was $700 because one was a smaller bathroom.

Henry:
Okay. And so what was your debt service on that mortgage?

Arden:
So we ended up putting a lot down on that one. We saved as much as we could from the last house hack. We knew that interest rates had gone up. I didn’t realize how big of a deal that was until after we bought this one. And we ended up putting like $52,000 down. I think at the time it was around a little over $1,900 for the mortgage.

Henry:
Looks like you were bringing in 15. The mortgage was 19, so you had to pay a couple hundred dollars a month this time. But still you got an additional lot. So I love that you repeated it for your second one. Even though you paid a little more, you had a higher interest rate, you had high debt service, you were still able to offset your income, you were only paying a couple hundred dollars a month. On this one when you moved out, were you able to rent it for a similar amount to the other one or is this one rent for more because it’s downtown?

Arden:
So it rents only for a little bit more. We’ve had the same tenant since we left. Now they’re great. I’m also a realtor now as well. And they’re my clients and they’re actually looking to purchase a house now, which is a shame because they’re great tenants.

Henry:
You’re like, “Oh, I’ve been looking. I just can’t find anything for you guys. I guess you have to

Arden:
Stay for them.” So they paid $2,500 a month, but it has gone up. We did the silly thing of refinancing.

Henry:
Did you pull cash out?

Arden:
No. So what we did is, so we had to split the lot off.

Henry:
Oh, got it. So you got a

Arden:
New home

Henry:
And you did the lot split.

Arden:
Yeah. So we ended up splitting it and we didn’t really think… Again, we were like, “What’s one point? That’s not going to be anything.” So we split the lot off because we were going to build on it the next year. That was our plan was to build and then move on.

Henry:
Can I give you a piece of advice? Do not do the math on what the price difference is in what you’re going to pay over the life of the loan when you paid that extra 1% interest versus where you were. Just don’t look at it. It’s

Arden:
Done. Yeah.

Henry:
It’s done.

Arden:
Yep. Yeah.

Henry:
Okay. So let’s focus on the good part. The good part is another successful house hack. I assume you were just finding these on the market with an agent. You buy them. I like that you’re putting a substantial amount of money down because then you’re essentially manufacturing cash flow, you’re buying equity. And then I love the back-to-back house hack method, and I’m very curious what the next deal looked like.

Arden:
Yeah, so the next deal was actually a little different. So we actually decided to do a flip, reno, burr kind of live in flip was ultimately what it was.

Henry:
Hey, again, I think this is another great owner occupied strategy, but it’s not as cut and dry as a buying a house hack because now you have to figure out how to take on a renovation. You have to figure out how you’re going to fund that renovation. Did you have a plan in mind of what size of a renovation you wanted to take on ahead of time? Did you know what you’re looking for or were you just perusing, hoping to find something you thought might be decent?

Arden:
We wanted to do a cosmetic flip. So we wanted to do floors, paint, and then there was a… It’s actually the room I’m in now. There was a wall literally right where the computer is, and we just wanted to tear that down, but we did get a contractor for that one. And then we ended up adding some projects on and now I’m redoing the things that I didn’t know how to do the first time.

Henry:
Classic. Okay. So

Arden:
First

Henry:
Question, the obvious question is what did you pay for the property?

Arden:
So for the property, we ended up getting it for 270.

Henry:
Is it a three-two like the other ones or did you make it a three-two?

Arden:
3-2. This one’s about the same size, 11, 1200 square feet. And it’s on a half acre lot in Wilmington, which is pretty rare. Oh

Henry:
Wow. That’s

Arden:
Pretty cool. Which is going into our next strategy with this house. Actually, we just got a permit to build an ADU on the back.

Henry:
All right. So you paid 270. How much did you budget for the renovation and then did you stay on budget?

Arden:
So I think we budgeted $30,000 for a renovation and we actually did 25,000, just over 25,000.

Henry:
Nice.

Arden:
Nice. Half of that was just the contractor blowing out the wall and putting drywall on the vaulted

Henry:
Ceilings. Awesome. What kind of loan did you use to purchase this? Did you just buy it on a conventional and then fund the renovation yourself or did you use a 203K loan?

Arden:
30 year fixed.

Henry:
Because there are live-in flip loans. We’ve talked about them before. They’re pretty tedious, but are very helpful.

Arden:
Yeah. I just was listening the other day to one of those and I was like, “Well, that would’ve been good to know a year ago.”

Henry:
Okay. Okay. So you bought it conventional. How much did you put down on this one?

Arden:
So we ended up putting $40,000 down on this one as well.

Henry:
Great. So I mean, I don’t think there’s anything wrong with the strategy. I think if you’ve got the capital to be able to pull it off, this is a great way to do it. If you don’t have as much capital, yes, you can use things like a FHA 203K loan. There’s a home path renovation loan that either Sally or Freddie has that you can use. So there’s definitely options for you if you want to do a live and flip. This is cool because you’re kind of doing all of the owner-occupied real estate investment strategies. So it’s really fun to hear somebody that’s pulled that off. So have you had it appraised since you’ve done it? Do you have an idea of what it might sell for if you were to sell it soon?

Arden:
So we actually just got appraisal done for the HELOC for the ADU that we ended up pulling out and it appraised for 300, which I was less than thrilled about, but I’m long-term investor, so I’m not planning on selling it anytime soon.

Henry:
Okay. So it appraised at 300, you’re all in just under 300. But for the people that are listening, on paper, he’s all in for less than that because the renovation money was your own money and you put $50,000 down. So your actual loan balance is lower than 300, but in real dollars, you’re in it about 295.

Arden:
So

Henry:
When you say you were able to appraise for enough to do the HELOC, you had equity, you have equity because of how much money you put down and because you funded the renovation out of your pocket.

Arden:
Yeah.

Henry:
All right. So it’s on this half acre lot. You said you have started the process of doing an ADU. Did this come up after you bought it when you realized the potential or did you see the potential for ADU when you purchased it? Because this was, it looks like 2024. ADUs were just kind of becoming a thing around then, well, popularity-wise.

Arden:
Yeah, so it wasn’t really the original idea. I was probably listening to BiggerPockets and I probably heard something come up about it and I was like, “That’s a good idea.” And shortly after the city of Wilmington changed the zoning rules that basically almost any lot in Wilmington can build an ADU. So I was like, “Game on.”

Henry:
Where are you in the process of building the ADU?

Arden:
We actually just got our permit today.

Henry:
Oh, wow.

Arden:
So I have to go tear down a shed and get the lot opened up for it.

Henry:
What are the steps you had to go through to get to essentially the step where you are today? Because I am willing to bet there are tons of people listening to this episode who either are interested in buying a house that has a lot where they can put an ADU on it or probably already have property and their city is now allowing them to build ADUs and are pretty curious about how the process all works. Now keep in mind everybody, every city municipality is going to operate a little differently. So just because this is the way Arden’s done it doesn’t mean it’s going to be the way that you are going to be able to pull it off in your market, but I think this will be still helpful. So you’ve got the house, it’s sitting on a half acre lot, you know you can do an ADU.
What was your first step?

Arden:
Yeah, so the first step is really one, just determining whether or not you can build because at least the way Wilmington works, it can’t be bigger than half the size of your main structure. So if you’re going to build a 300-foot ADU, it’s kind of nothing to it. Next is quotes. We talked to, I don’t know, every general contractor in town who does it and then some specific ADU companies now that it’s been our thing for about a year, there’s a few companies I’ve opened up and we talked to all of them, got quotes from all of them, and finally found one that we just meshed with the best, wasn’t necessarily the cheapest, but just seemed like the highest quality for the best price. Next is their site planning. They have to figure out exactly what they need to do, if there’s utilities that are going to need to be ran or where that’s going to come from.
And then from there, for us, it was financing, figuring out exactly how we’re going to get the funds. Is it going to be cash? Is it going to be a HELOC? And then from there, at least in my book, the third party company has really taken it on to go to the city, get the permits and all of that. So for us, hopefully now it’s just choosing the color of the cabinets.

Henry:
Yeah. Well, that’s the benefit to hiring a third party to do it. So if you’re shopping around for third parties to do it, finding a contractor who’s going to go fight all the battles with the city and get the permits for you is definitely the way to go. And I like that you got multiple bids from multiple contractors. When you were getting bids, did you already have to know your floor plan or what you wanted to build when you were going to these people? Or did you just go to them and say, “Hey, I have this lot. I can build an ADU. Can you show me what you can do or what I can do here?”

Arden:
Yeah, so I knew about the rule of ADUs. I looked into it, especially with our other lot. I was looking at what we could build there and found the ADUs. Funny enough, I actually stole one of the ADU guys’ free plans that was on the show and took it because it fit almost perfectly in our lot. Oh, man. We ended up having to not go with it because it was a little more expensive than what we wanted to spend. But I took them that plan and was like, “I want something roughly this size and I know it needs to be under 600 square feet.” And then they would come back with a quote on exactly that plan or exactly a plan that was the most similar to it. Most of them had a plan that was close enough. Oh,

Henry:
That’s pretty cool, man. Shout out to Derek, man, the ADU guy on Instagram. If you haven’t checked out what the ADU guy does, he’s such a great resource for being able to build ADU. See this is what he does for a living. He’s been on the BiggerPockets podcast. Great resource. Sweet, man. Thank you for taking us through that. So now you’re at the step where hopefully you can break ground soon, it sounds like. So do you have a timeline on when you expect it to be finished?

Arden:
So they said 150 days from permit, so 150 days from today.

Henry:
Hey, start the clock.

Arden:
Yeah, start it right now.

Henry:
Okay. And do you mind sharing the specs? How big of an ADU, one story, two story, and what’s the total build going to cost?

Arden:
So the total build is going to cost $128,000.

Henry:
That’s amazing.

Arden:
Yeah. So I think it has to be exactly 570 feet, but that doesn’t include the outside area. So we have two outside patios we’re putting, front and back, and it’s going to be a one bed, one bath.

Henry:
Is it like a studio or is it going to be actual bedroom, bathroom, living room?

Arden:
Actual bedroom, bathroom, living room. And right now, one bed, one baths in our area, at least rent from 14, $1,500 a month.

Henry:
That’s cool.

Arden:
Yeah.

Henry:
The next question is the question everybody wants an answer to, which is how the heck did you go about financing this thing? Because that’s the struggle I think people have with building ADUs is there’s not a lot of ADU specific loans out there yet. I think we’re going to get some of that in the future as this becomes more popular, but right now you kind of have to figure out how to bootstrap the money to do these builds. So I’m guessing that’s what part of that HELOC was for, you know?

Arden:
Yeah, so we ended up getting a HELOC for about $45,000, and then the rest is on us. Okay. I don’t really have any other magic way of getting money. Yeah, no,

Henry:
That’s the thing people need to hear. It takes capital to do this, and I would encourage anybody who’s curious about this is don’t just research ADUs, but research any loan programs, grants, help from your cities or municipalities. There are options out there to help supplement some of the financing, but if you’re building an ADU on a property you already have, it’s going to take some cash. You’re going to have to shell out some money to do it because there just aren’t a ton of loans out there for this

Arden:
Yet. We’re actually in talks about getting a roommate again, so we’re going right back to our original strategy of, all right, if we’re here, we got to have a roommate.

Henry:
Yeah. Okay. And do you have any concept of what the entire property might appraise for after it’s all said and done?

Arden:
What I’ve seen is about 70% of the cost of the ADU seems to be added to the home, which would put us probably roughly at 380, 390, which that’s the hard part, but we’re realistically going to be making almost a thousand dollars a month in rent just from the ADU.

Henry:
If your goal is to rent it out and cash flow it, you will absolutely be cashflow positive because you’re going to be able to get around $1,200 a month on the ADU, plus you’re going to be living in the house, so you’re going to be able to have less of a mortgage, especially if you get another roommate. And then if you move out down the road or when you move out down the road, you rent the house, you rent the ADU, and you’re super cashflow positive. So I think that that works. You have to understand real estate’s not a short-term gain. It’s a long-term play. And so in the future, your equity’s going to continue to build, your debt service will continue to go down. I don’t think that that’s a bad thing at all.

Arden:
Yeah. And we actually have an alternative strategy that if depending on finances, we’re actually debating moving into our ADU and renting out the main house because it’s more expensive.

Henry:
All right, Arden, thank you for sharing that story and thank you for being so transparent. I do have a few more questions for you. I want to dive just a little bit into this concept of living frugally and living a little uncomfortably in the short term so that you can truly live the life you want to for the long term, but we’re going to do that right after the break. All right, we are back on the BiggerPockets podcast. I’m speaking with investor Arden Williams, who has pulled off two house hacks and now a living flip and is now taking on an ADU. Before we get out of here on the investment side, I want to talk a little bit about this concept of living frugally. What did living frugally look like for you? What kind of sacrifices did you make in your lifestyle? And then how has making those sacrifice manifested itself in your life now?

Arden:
Living frugally has been probably one of our key strategies. I have a great wife who’s also just as frugal as I am and very conscious on money. She’s our spreadsheet guru, so she tracks all of our spending, which is amazing. We’ve had lots of different ways of just saving a little money. Some of them I don’t recommend at all. House hacking is probably actually the least uncomfortable because if you find someone who you actually generally get along with, it’s not that bad. It could actually be a lot of fun. Doing a live in flip is probably the next step into rough. You come in, your kitchen’s destroyed and your floor is destroyed and the only thing you can do is work after you get off work. That’s not great. But other than that, we’ve always been very mindful on what we spend eating out. And then there for about four years while I was a firefighter, I strictly drove a motorcycle, rain, shine, snow, sleet.
That’s intense. Yeah.

Henry:
Did you have any rules of thumb you lived by in terms of how much you were spending in relation to what you were making? And remind everybody that’s listening, what were you guys making when you first started this real estate investment journey and what were you spending versus what you were making?

Arden:
At the time when I first started, I was making 12, $13 an hour as a firefighter. And then my wife was at the time a teaching assistant and making 12, $13 an hour. And now both of us make roughly about $60,000 a year, so not crazy. We don’t really have a key target that we follow, but we mostly just really focus heavily on not eating out. That’s our biggest, that’s the hardest one for us.

Henry:
People ask me what I do. I eat all my money, guys. That’s what

Arden:
Happens. Yeah. So the big thing is just figuring out what works and the things that you want to spend your money on, and then just trying to limit the things that you’re like, “I don’t actually need this.”

Henry:
And I think the other thing that keeps people from living frugally is this fear of missing out on the fun parts of life or the things that you enjoy. After living frugally for so long, do you feel like you’ve missed out on life or missed out on adventures or missed out on experiences?

Arden:
No, not at all. So between the time we got our first property to the end of 2024, we had three houses. We ended up renting them all out and we actually got just off the money that we were making, we ended up getting to go travel the world for almost a year.

Henry:
That’s really cool. So while both making 60,000 a year?

Arden:
No. So we both quit our jobs.

Henry:
Just traveled?

Arden:
Yeah.

Henry:
That’s super frugal.

Arden:
So after traveling across the country, we were like, “We want to do something cool every five years.” I don’t know if that’ll stay forever, but it just happened to be right at five years. We ended up being like, “Okay, this could be our last chance to do a big adventure.” And so we just saved and saved and saved and saved and saved, cut as many expenses as we could. And this was also during the renovations. So we’re renovating the house, trying to save money because we knew we were going to quit our jobs, and we ended up just saving as much as we could. And then the income we were making from just three properties was enough to cover half of our year of travel.

Henry:
I love it, man. I mean, this is why people invest, right? Being a little uncomfortable so that you can invest in real estate allows you to bring in an income that allows you to live the life that you want to live. And I love that you are the walking embodiment of that. This has been really cool. Before we get out of here, why don’t you give us just a quick recap of what your total portfolio looks like? How many units?

Arden:
Yeah, so all we have is three single family units, and we’re breaking ground on an ADU, hopefully in the next week or two, and we’ll have four units and a piece of dirt.

Henry:
And I like that. And you started in 2021. It’s now 2026, so you didn’t have to scale super fast. You’ve been able to enjoy your life. What are the plans for the future? Are you going to do more real estate deals? Are you going to house hack again? It sounds like you might not do another live and flip, but

Arden:
What’s the plan? Yeah, we’ll see about that one. That one will probably be the hardest to convince my wife of. Yeah, so the plan, definitely to keep doing real estate. I just got my real estate license back in February, so it was mostly for me and my wife in case we wanted to sell something, save us a little money. But I also really enjoy talking to people about this. And a lot of our friends who know us and know what we do have asked us questions about it. So it’s something that we’re definitely pushing. And then realistically, my goal is six to 10 properties. We self-manage everything, so we don’t want a huge headache all the time. Anything more than that, I don’t really need. I’m just looking to make enough money that I can continue to do the trips I want to do and just try and live a little bit.

Henry:
All right. Well, thank you so much, Arden, for sharing your journey, for sharing your experiences. What I love about your story is it is such an achievable path. Anybody can go down this route. You should be proud of what you built. And again, thank you for being open and honest with us and sharing your journey. And I wish you nothing but success as you continue to grow and scale your business.

Arden:
Thank you so much. It was great talking to you.

Henry:
And if you’re listening and you think you’ve got a pretty cool story you’d like to share on the BiggerPockets podcast, then go on over to biggerpockets.com/guest and fill out the form. We could select you, and before you know it, you could be right here on the podcast with Dave or I sharing your story for the benefit of our BiggerPockets community. Once again, thank you everyone for listening to the BiggerPockets Podcast. We’ll see you on the next episode.


Help us reach new listeners on iTunes by leaving us a rating and review! It takes just 30 seconds and instructions can be found here. Thanks! We really appreciate it!

Interested in learning more about today’s sponsors or becoming a BiggerPockets partner yourself? Email [email protected].


Source link

From $12/Hour to 3 Rental Properties and Traveling the World Read More »

Are You Wasting Your Startup’s Runway With the Wrong Product?

Are You Wasting Your Startup’s Runway With the Wrong Product?


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Most product teams struggle because the structure around ideas and team talent isn’t optimized for impact.
  • A framework is a set of best practices, not an ironclad rulebook. The teams that get this right understand why each step exists, but also know when to use judgment instead.
  • Orient everything toward impact because that’s the only metric that actually matters.

The most common way startups burn through financial runway isn’t a bad hire or a botched launch. It’s building the right product, but for the wrong reason, at the wrong time and without enough validation that customers will actually want it. I’ve seen it happen at companies with great teams, strong funding and real market opportunity. 

Here’s what we’ve learned about keeping a product team oriented toward impact and away from the kind of well-intentioned “busywork” that can kill off startups.

1. Prototype the process itself

Most founders are rigorous about validating products before launching them. Fewer apply that same discipline to how their product team actually operates. They convene large groups, whiteboard a process, roll it out… and then watch it fall apart under real conditions because nobody pressure-tested it first.

The solution is to treat your process itself like a product. Start with a small group — perhaps two or three people with genuine cross-functional exposure — then run through real decisions fast. What you’re looking for are the questions that surface every single time you evaluate an opportunity. Those recurring questions become the foundation of the evaluation framework. As CEO, your job is to help make sure that framework exists and that the team is working within it, not to be in every room where decisions get made.

For example, a two-person team at a software development company might discover that every feature discussion comes back to one question: “Will our enterprise clients’ legal teams actually approve this?” Surfacing issues like this early and building them into the evaluation framework saves weeks of wasted effort. 

Or consider a consumer app team that kept building features users said they wanted in surveys, only to see flat adoption at launch. This could be because they never validated whether each feature fit the actual usage context and wasn’t just answers to a survey.

The goal is a process blueprint you can pressure-test and evolve as needed.

2. Put cross-functional generalists at the center of the process

From a founder’s perspective, one of the most consequential hiring and organizational decisions you’ll make is who sits at the center of your product process. Product teams naturally play a connector role between engineering, client success, legal, marketing and operations. But that role only works if the people filling it have genuine exposure across those domains, not just a passing familiarity. 

The most valuable contributors in your product process aren’t necessarily the most senior people in a function. Instead, the people who wear enough hats and can represent multiple perspectives, anticipate friction from teams they don’t officially belong to and make judgment calls that account for a fuller picture are the ones you want driving the conversation.

Be intentional about identifying those types of team members. They’re often not the ones with the most obvious titles. But they are often the ones identifying early issues in your roadmap.

3. Front-load validation

Runway is finite, and every build decision is actually a capital allocation decision. One of the most expensive mistakes is a well-built feature that nobody wants. By the time teams discover a post-launch product-market fit problem, they’ve already spent the time building it, absorbed the opportunity cost and potentially confused target customers.

Before committing serious build time, pressure-test every idea against a few essential questions: Does this solve a real problem your customer actually has and not just one they described in a survey? Is there a plausible path to revenue generation? And relative to the level of effort, does it have meaningful revenue potential?

Rank ideas by impact divided by effort. It doesn’t need to be a sophisticated formula; a simple high/medium/low estimate on both axes can get you most of the way there. And complete the customer validation before you build, not after. By the time the product ships, you should already know who will want it.

4. Measure the machine, not just the output

CEOs monitor revenue. But if you’re only measuring what ships and what it earns, you’re seeing the outcome without understanding the process behind it. The health of your product function shows up earlier in the pipeline. If you’re not watching those signals, problems compound before they show up in the P&L. 

The most useful process signal to track is adoption rate at launch. If validation was done correctly upfront, customers should already be lined up when it ships. A feature with no adoption is basically just sitting in a “warehouse;” unsold and unused. 

Earlier in the product pipeline, track the volume and quality of ideas moving through each product validation stage. A well-functioning product team should be like a machine, consistently outputting impact. And as CEO, you should be able to see how well this machine is running before it impacts your financials.

5. Process should accelerate throughput, not create bureaucracy

The word “process” makes founders cringe, because processes can often be bureaucracy in disguise.

The only process worth keeping is one that makes your team faster at value creation. Every checkpoint in a process should exist because it demonstrably reduces wasted effort downstream. If it doesn’t, cut it. And trust your team to interpret process frameworks intelligently. Empower them to skip a step when it’s warranted, as long as it’s flagged so everyone stays aligned. 

The common thread

The common thread across all five of these principles is intentionality: being intentional about who’s in the room, what gets built, in what order and why. Most product teams struggle because the structure around ideas and team talent isn’t optimized for impact. As CEO, it’s ultimately your responsibility to get structure right. 

A framework is a set of best practices, not an ironclad rulebook. The teams that get this right understand why each step exists, but also know when to use judgment instead. Orient everything toward impact because that’s the only metric that actually matters.

Key Takeaways

  • Most product teams struggle because the structure around ideas and team talent isn’t optimized for impact.
  • A framework is a set of best practices, not an ironclad rulebook. The teams that get this right understand why each step exists, but also know when to use judgment instead.
  • Orient everything toward impact because that’s the only metric that actually matters.

The most common way startups burn through financial runway isn’t a bad hire or a botched launch. It’s building the right product, but for the wrong reason, at the wrong time and without enough validation that customers will actually want it. I’ve seen it happen at companies with great teams, strong funding and real market opportunity. 

Here’s what we’ve learned about keeping a product team oriented toward impact and away from the kind of well-intentioned “busywork” that can kill off startups.

1. Prototype the process itself

Most founders are rigorous about validating products before launching them. Fewer apply that same discipline to how their product team actually operates. They convene large groups, whiteboard a process, roll it out… and then watch it fall apart under real conditions because nobody pressure-tested it first.


Source link

Are You Wasting Your Startup’s Runway With the Wrong Product? Read More »

Dad’s Baby-Focused Company Grew to  Million in Year 1: Owlet

Dad’s Baby-Focused Company Grew to $20 Million in Year 1: Owlet


Key Takeaways

  • Workman and his co-founders launched wearable baby monitor Owlet in 2015.
  • In 2021, the company went public — then received an FDA warning letter.
  • Owlet got FDA clearance, focused on lean profitability and has monitored over 2.5 million infants.

This as-told-to story is based on a conversation with Kurt Workman, co-founder and CEO of Owlet, the only over-the-counter, FDA-cleared wearable baby monitor. Workman and his co-founders Zach Bomsta, Jordan Monroe and Jacob Colvin met in college and launched Owlet in 2015, building it from $0 to $20 million in revenue in its first year. The company went public in 2021.

Owlet has served more than 2.5 million babies, monitored more than 21 trillion heartbeats and collected two billion hours of sleep data, per the company. Additionally, Owlet just launched its new Baby Safety Task Force, a committee created to raise baby safety standards across the category, in partnership with legislators, clinicians and other brands. This piece has been edited for length and clarity. 

Image Credit: Owlet. Kurt Workman.

 I’m a dad of three. My oldest is 12, almost 13, and my youngest is seven. So this product really came from a dad’s perspective, not from an engineer’s or clinician’s. I studied chemical engineering, but it was the wrong kind of engineering for what I ended up doing with the rest of my life.

When my wife was a baby, she had an undiagnosed congenital heart defect. They sent her home from the hospital, and she had a coarctation of the aorta and then a bunch of holes in her heart. Ten days later, her mom just happened to check on her when she was going into cardiac arrest, and they rushed her to the hospital. Luckily, they were able to do heart surgery that saved her life. 

So when we were thinking about having kids, we visited my wife’s cardiologist to see if it was okay for her to get pregnant because she’s had three heart surgeries and will likely have more. They said she would be okay, but our kids were at risk of the same thing. I’m the worrier in the relationship, and I couldn’t let it go. How would I know? What exists for parents at home to monitor the health of their baby? At the time, you had a video monitor and a thermometer. That was the tool set for new parents. Neither of those could help.

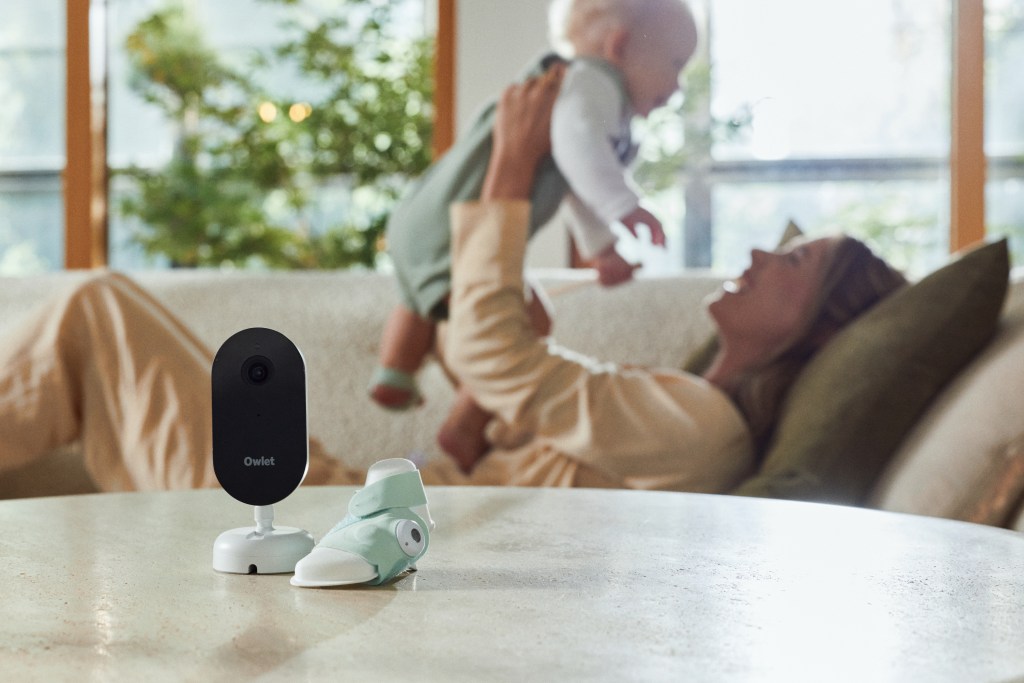
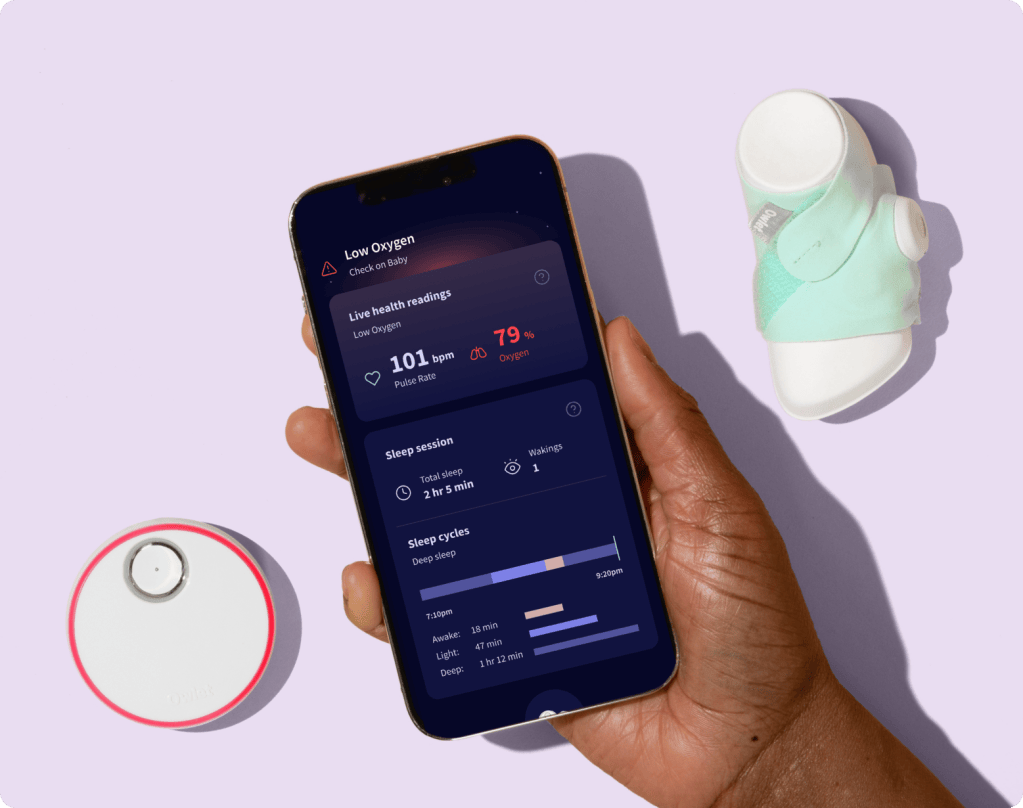
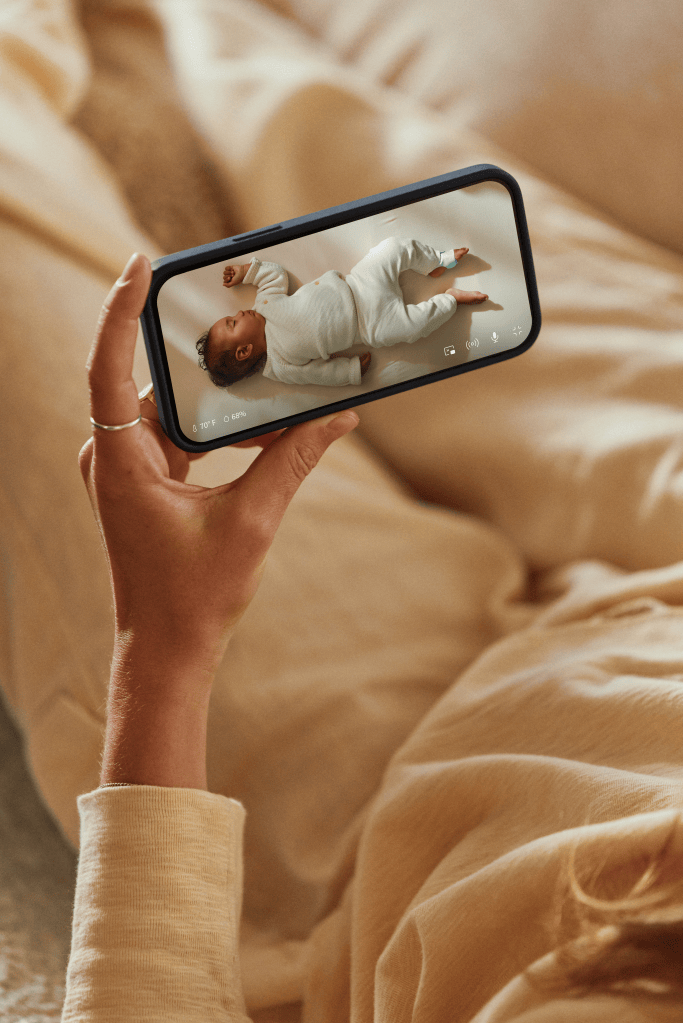
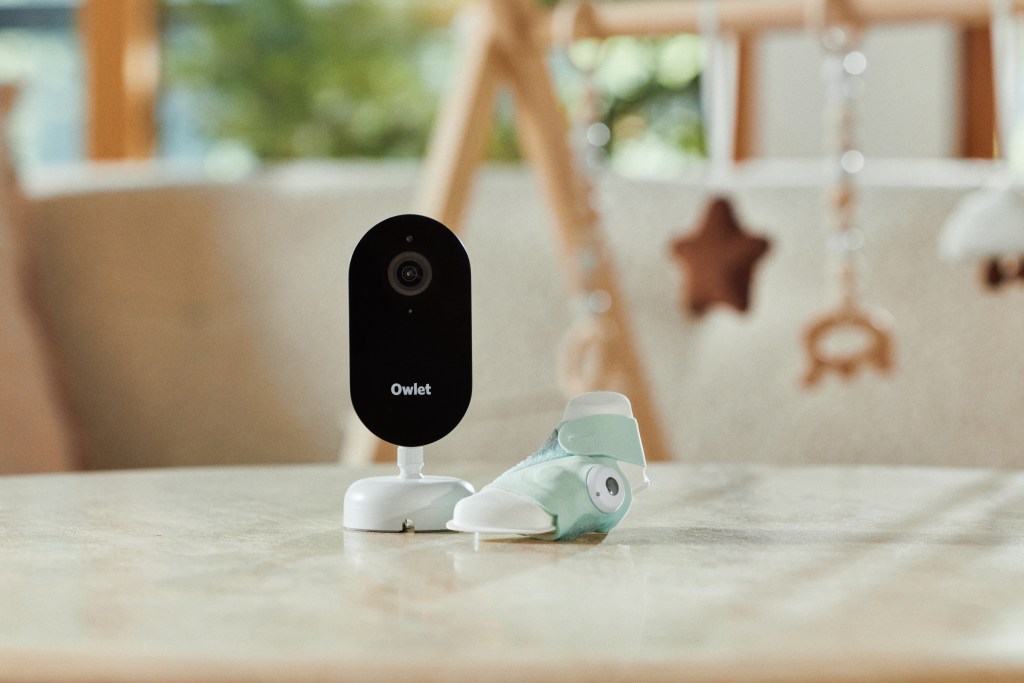
Then I learned about this technology that they used in the hospital called pulse oximetry, which is now in every Apple Watch and Fitbit. It’s an incredible tool that, through light, tracks the pulse rate and the oxygen levels in the blood. In the hospital, with babies, most of the time they put pulse oximeters on the foot. So we came up with this idea of a little sock. 

Image Credit: Owlet

When we showed it to a few parents, their eyes lit up. I remember going to a home where the mom had one of these big, clunky hospital monitors that does the same thing, and she just started crying. I was totally taken aback because I hadn’t actually used one of these hospital monitors before. I’m like, What’s going on? Did we offend her? And she was just like, “It’s awful trying to move this thing around. There’s alarms going off all day. I can’t sleep. I would give anything for that.”

We spent three years developing the product. We did six different beta tests. The first one failed miserably. It just kept getting a little bit better. 

It was hard to raise money at first because my co-founders and I had very little experience in that area. On top of that, there was a startup out of MIT that was developing a onesie babies could wear with a sensor that would sense the motion of the belly while they were breathing, and it had already raised money. Then there was another similar company out of San Francisco. Everybody kind of looked at us like, Why would we invest in you? 

Crowdfunding, then meeting investors through Techstars

We launched a crowdfunding campaign, and from the dollars in pre-sales, it was okay. We didn’t have a lot of views on our video. There just wasn’t a lot of awareness. But our conversion rate was much higher than some of our competitors because we were focused on this core element — the heart rate and oxygen — and notifying parents if something changed. 

That focus allowed Owlet to gain some traction. Then we went through the Techstars program in New York. That got us outside of Salt Lake City into a broader network. We met our first investors. One was a woman named Milena Adamian. She’s a cardiologist out of New York City. She had a medical device-focused fund called Azimuth Ventures. Then the other one is John Frankel with ff Ventures out of New York City. He had a strong thesis around IoT and connected hardware. So it was a perfect blend.

When we launched in 2015, we thought that the best strategy would be to buy ads when somebody searched for “baby monitor” on Google. Because millions of parents search for a baby monitor. That failed miserably because they already knew that they wanted a video monitor and audio monitor. So our bounce rate was terrible; our conversion rate was awful. 

Image Credit: Owlet

Pivoting to educate parents on Owlet’s new category

We pivoted pretty quickly and realized it was all about education. This was a new category. We couldn’t assume that biometric monitoring for babies was obvious — because it wasn’t. We switched the strategy to heavily focus on PR, influencer partnerships, video content to educate, and that started to get some traction. 

Also, we avoided retail the first year. We had interest from Target, Buy Buy Baby and some other retailers. But we wanted to spend all the margin dollars on building awareness and education. We ended up driving 50 million video views that first year. We had a ton of great press. That first year, we went from $0 to $20 million in revenue — with no retail, no partners, no Amazon, just on our website. 

That then opened the door to retailers. We got better placement on the shelf. We had better margins, so we could do more marketing to support the retailers. Owlet just started to explode in retail. This was a new category, so every dollar for retailers was incremental to their baby category.

Image Credit: Owlet

Going public and receiving an FDA warning letter

Then, in 2021 Owlet went public. That was intense. There were a lot of companies going public through stocks, so there was just a lot of activity happening in the market. We went from going out to raise a round of capital, our Series C, to getting this offer to go public at a great valuation with a lot of money attached to it. The offer was so much better than anything we were looking at raising privately that we decided to go for it. It was an expensive and time-consuming process to go public. Then, right after going public, we got a warning letter from the FDA. 

The FDA said that we had not classified the product correctly. Most of these wearables are wellness devices, and we had positioned our product in that way. All of our labeling, all of our claims, the feature set. The FDA disagreed with that, so for one quarter, we had to take the product off the shelf. We were able to negotiate with the FDA to get it back on the market, prior to getting clearance, with a changed feature set. Then we worked on getting FDA clearance over the next year and a half. 

Image Credit: Owlet

Getting FDA clearance and regaining sales momentum

In that period of time, our sales dropped by about 30%, then dropped again, before they started to climb back. We got clearance at the end of 2023 — and saw sales double overnight. It was a huge win for the company. But by that point, not only had the stock market kind of crumbled, and you lose a lot of investors through that, but also this FDA overhang created a lot of overhang for the business, and that was a scary time where we had to get to profitability. 

So we built a leaner business. We learned that our biggest expense was marketing. We’d thought that our marketing was efficient and contributing to sales. When we cut marketing by 80% out of necessity — we were spending about $3 million a year — we learned that 85% of the traffic still came to our website, and the other 15% went to our page on Amazon or Target. We were just paying a $3 million tax to Google.

Owlet bridges the gap between hospital and home

Since then, we’ve doubled down on our focus: How do we help bridge the gap between the hospital and the home? Unfortunately, more than 4,000 babies pass away unexpectedly in the home every year. Babies are naturally vulnerable. We’re using healthcare as this giant triage clinic, and our goal was to bring that home. We launched our data subscription platform that built out that data, and this year, we integrated telehealth into our service. So we’re trying to build that ecosystem. We also launched our first hospital partnerships and opened up medical record integrations so that data can flow seamlessly to physicians. 

Even though we’ve had ups and downs in our journey, the level of adoption from parents is amazing. Almost one in eight babies in the U.S. now has an Owlet. We think pretty soon that will be one in five. So the adoption of this new category has been incredible. It’s higher than any other from an adoption percentage basis, higher than any other new wearable. So we’re really proud of that. We’re also seeing incredible adoption of our subscription, which means this data is empowering parents. And, again, we’re the first and only FDA-cleared monitor. It’s amazing what we’ve been able to move in this category.

Key Takeaways

  • Workman and his co-founders launched wearable baby monitor Owlet in 2015.
  • In 2021, the company went public — then received an FDA warning letter.
  • Owlet got FDA clearance, focused on lean profitability and has monitored over 2.5 million infants.

This as-told-to story is based on a conversation with Kurt Workman, co-founder and CEO of Owlet, the only over-the-counter, FDA-cleared wearable baby monitor. Workman and his co-founders Zach Bomsta, Jordan Monroe and Jacob Colvin met in college and launched Owlet in 2015, building it from $0 to $20 million in revenue in its first year. The company went public in 2021.

Owlet has served more than 2.5 million babies, monitored more than 21 trillion heartbeats and collected two billion hours of sleep data, per the company. Additionally, Owlet just launched its new Baby Safety Task Force, a committee created to raise baby safety standards across the category, in partnership with legislators, clinicians and other brands. This piece has been edited for length and clarity. 

Image Credit: Owlet. Kurt Workman.

 I’m a dad of three. My oldest is 12, almost 13, and my youngest is seven. So this product really came from a dad’s perspective, not from an engineer’s or clinician’s. I studied chemical engineering, but it was the wrong kind of engineering for what I ended up doing with the rest of my life.


Source link

Dad’s Baby-Focused Company Grew to $20 Million in Year 1: Owlet Read More »

Why Leaders Blame Culture Instead of Their Own Behavior

Why Leaders Blame Culture Instead of Their Own Behavior


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Leaders tend to blame cultural problems when performance stalls because it’s broad enough to describe everything and specific enough to implicate no one.
  • Leaders who have stopped spending hands-on time with their people often don’t know what’s standing in their way. Ask how they’re feeling about the work, the pace and the environment.
  • Ask people above you, your peers and your direct reports what they see as your strengths and your weaknesses.
  • Reward people who raise problems before having a solution. Otherwise, issues stay hidden until they’re harder to trace and solve.

According to iHire’s 2026 Toxic Workplace Trends Report, 79% of employees who experienced a toxic workplace pointed to poor leadership and management as the cause, citing leaders who were unethical, unaccountable or unsupportive. Executives rarely see it the same way. When performance dips, the diagnosis that gets reached for first is almost always “culture,” a word

I have spent close to 20 years inside companies watching leaders reach for that same explanation. Culture is safe to blame because it points everywhere at once. Naming your own decisions points back at exactly one person.

Fixing performance starts with a tougher question: “What have I been doing, specifically, that’s producing this?” Here’s where to start looking:

1. Notice the distance before diagnosing culture

Executives rarely think of themselves as the reason performance stalls — they’ve usually stopped being close enough to the work to see their own fingerprints on it. In an interview, Jana Boone, SVP of growth enablement at full-funnel digital marketing agency Intero Digital, told me the behavior executives overlook in themselves is almost always the same one: “Poor performance gets labeled a culture problem when it’s often just distance.”

Boone said the more common issue isn’t culture at all, but a leader who hasn’t spent hands-on time with their people in a while and whose instinct is to solve rather than listen. The job has changed since that leader last did it themselves, she said, and they often don’t know what’s actually standing in someone’s way.

Boone’s point cuts against the instinct that made most of these leaders successful in the first place: solving fast. Before assuming a capability gap, she recommended asking a person directly how they’re feeling about the work, the pace and the environment. “And then be quiet long enough to hear the real answer,” she said.

2. Trace the label back to a decision

Boeing‘s regulator ended up saying the quiet part out loud, even while reaching for the same word everyone else does. After a door panel blew off an Alaska Airlines 737 Max mid-flight in January 2024, an FAA audit found that Boeing’s culture had placed more emphasis on mass production than safety standards, Administrator Michael Whitaker told NBC News.

But the specifics he pointed to weren’t cultural in any vague sense. Boeing’s own protocols, he said, weren’t what you’d expect “if safety is the first priority.” The failures traced back to a specific, correctable set of leadership decisions: what got rewarded, what got skipped and what got signed off without a safety briefing.

The lesson scales down well below aircraft manufacturing. Before a team’s output gets filed under “culture,” name the actual decision behind it, including what got approved, what got ignored and what got rewarded that shouldn’t have been. A culture is hard to fix because it’s everywhere and nowhere. A decision has a name attached to it.

3. Ask the question you don’t want answered

Most leaders who genuinely want to audit their own habits don’t know where to start, and that uncertainty is often reason enough to quit before trying. Boone said the self-examination most leaders skip starts with a simple, uncomfortable request: Ask people above you, your peers and your direct reports what they see as your strengths and your weaknesses.

“You’ll get three different answers, and the gaps between them are the point,” she said. The instruction that follows is the hard part. “Don’t explain, don’t contextualize, don’t defend — just take it, and pay attention to where the three groups disagree as much as where they agree,” she explained.

She recommended writing down a personal read on what’s going well and what needs work, and then holding it against what came back from the three groups. The distance between those two lists, Boone said, is the actual audit. Most leaders skip this step for the reason she named directly: “A culture diagnosis produces a workshop, while an honest look at your own habits produces a list of conversations you now have to have.”

4. Reward the problem before demanding a fix

A University of Iowa study found that management teams respond with more urgency to employees who point out a problem than to those who show up with a proposed fix for it, according to researcher Daniel Newton. Newton said the instinct to demand a solution alongside every problem is backward. When people learn they need a fix in hand before they can speak up, they often stay quiet instead, so problems go unreported and unresolved.

That same filter operates at the top of an organization, not just on the front line. If a leader only takes a concern seriously once someone arrives with a solution attached, the leader is training people to withhold the exact information that would trace a performance problem back to a specific decision instead of a vague mood.

Loosen that filter — ask what’s going wrong before asking what to do about it — and problems get named earlier, closer to the source and easier to trace back to something a leader controls instead of a culture that implicates no one.

You don’t need a workshop, a survey or a new deck to fix this. You need to notice the distance, name the decision, ask the people who actually see you and reward the person who tells you something’s wrong before they know how to fix it.

Pick one of those four things and do it this week. Your team already knows which one you’ve been avoiding.

Key Takeaways

  • Leaders tend to blame cultural problems when performance stalls because it’s broad enough to describe everything and specific enough to implicate no one.
  • Leaders who have stopped spending hands-on time with their people often don’t know what’s standing in their way. Ask how they’re feeling about the work, the pace and the environment.
  • Ask people above you, your peers and your direct reports what they see as your strengths and your weaknesses.
  • Reward people who raise problems before having a solution. Otherwise, issues stay hidden until they’re harder to trace and solve.

According to iHire’s 2026 Toxic Workplace Trends Report, 79% of employees who experienced a toxic workplace pointed to poor leadership and management as the cause, citing leaders who were unethical, unaccountable or unsupportive. Executives rarely see it the same way. When performance dips, the diagnosis that gets reached for first is almost always “culture,” a word

I have spent close to 20 years inside companies watching leaders reach for that same explanation. Culture is safe to blame because it points everywhere at once. Naming your own decisions points back at exactly one person.

Fixing performance starts with a tougher question: “What have I been doing, specifically, that’s producing this?” Here’s where to start looking:


Source link

Why Leaders Blame Culture Instead of Their Own Behavior Read More »

I’ve Mentored People for 20 Years. I Use These 4 Steps to Help Them Advance

I’ve Mentored People for 20 Years. I Use These 4 Steps to Help Them Advance


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • The best mentors treat every conversation as a two-way exchange, asking questions that sharpen the other person’s thinking while staying open to having their own views challenged.
  • A four-step process of building self-awareness, gathering feedback from five people, separating perception from reality and refining your defining stories creates growth for both mentor and mentee.

Early in the evolution of social media marketing, I was interviewing a recent college graduate for an entry-level position. During the conversation, I found myself explaining how organizations were beginning to embrace social media as an important marketing channel. I spoke confidently about how brands could connect with consumers in new ways and believed I had a strong understanding of where the industry was heading.

Then something unexpected happened.

The candidate began building on several of my points and offered insights that went far beyond anything I had discussed. She understood the platforms, user behaviors and emerging trends at a level I simply did not. While I had learned about social media through corporate training programs, agencies and industry experts, she had grown up immersed in these platforms every day.

Within minutes, the dynamic shifted. I stopped trying to teach and started asking questions. What platforms were gaining traction? How were younger consumers using them differently? What trends did she see that marketers were overlooking? By the end of the conversation, I realized I had learned far more than I had taught.

That experience eventually inspired a reverse mentoring initiative where younger employees shared expertise with senior leaders. More importantly, it taught me a lesson that has shaped every mentoring relationship since. The greatest value of mentoring is rarely the advice being shared. It is the perspective being gained.

Stop treating mentoring like a one-way conversation

The best mentors enter conversations with the belief that they have something to teach and something to learn. They understand that every person sees the world through a different set of experiences, challenges and assumptions. Those differences often create insights that would never emerge otherwise.

This shift in thinking is important because it changes the goal of the relationship. Instead of trying to provide the perfect answer, great mentors focus on helping people think more clearly. They use questions to uncover assumptions, identify blind spots, and encourage deeper reflection. At the same time, they remain open to having their own perspectives challenged. Curiosity creates better mentoring conversations than expertise ever will.

The framework I use to create growth on both sides of the relationship

Over the last 20 years, I have coached and mentored people across every stage of their careers. One thing I learned early is that mentoring becomes far more effective when it is tailored to where someone is in their professional journey.

The challenges facing an employee in their first few years of work look very different from those facing a senior leader. Early in a career, individual wins and setbacks can feel defining. Later in a career, experience often provides a broader perspective that changes how people evaluate opportunities and challenges. Because of this, I rarely begin a mentoring relationship by offering advice. Instead, I focus on creating a deeper understanding of the individual sitting across from me. The process generally follows four steps.

1. Start with self-awareness

Most people are eager to discuss goals, promotions and career aspirations. I prefer to begin somewhere else. The first step is helping people understand themselves more clearly. We explore strengths, development opportunities, motivations and long-term aspirations. The objective is to establish a baseline understanding of who they are today before discussing where they want to go tomorrow.

This step creates value for mentors as well. It forces us to listen carefully rather than assume we already understand someone’s challenges based on our own experiences.

2. Gather perspectives you cannot see yourself

One of the most valuable exercises I use involves gathering feedback from five people within the individual’s network. I encourage them to compare that feedback against their own self-assessment and look for patterns. Where do the perceptions align? Where do they differ? What strengths appear consistently? What development opportunities keep surfacing?

Many professionals spend years relying exclusively on self-reflection. Feedback introduces perspectives that are often impossible to uncover on your own.

3. Separate perception from reality

This is where many mentoring conversations become transformational. Whether we agree with feedback or not, perception influences opportunities, relationships and career progression. The goal is not to debate what people think. The goal is to understand how others experience us.

I encourage people to resist the urge to explain or defend feedback immediately. Instead, sit with it. Look for recurring themes. Ask yourself why multiple people may have reached similar conclusions. Some of the greatest career breakthroughs happen when people stop arguing with perceptions and start learning from them.

4. Refine the stories that define you

Every professional has stories that shape how others perceive their leadership potential. These stories often involve successes, failures, setbacks, difficult decisions and lessons learned. Yet many people struggle to communicate them effectively. The final step focuses on identifying those experiences and learning how to share them with intention.

When people can clearly articulate what they learned from challenges and how those experiences shaped their growth, they become far more effective at communicating their value, leadership style and potential.

Treat every mentoring conversation as leadership practice

One reason mentoring accelerated my own career is that it gave me an opportunity to practice leadership long before I had a leadership title.

Early in my career, I proactively sought out coaching and mentoring opportunities because I knew I wanted to become a people leader. Those experiences taught me how to listen, build trust, provide feedback and help others navigate challenges. More importantly, they taught me how to influence people without relying on authority.

Many aspiring leaders spend years waiting for a promotion before developing leadership skills. I would argue the opposite approach is more effective. Develop the skills first and let the title catch up later. Mentoring allows you to practice leadership every time you help someone. By the time formal leadership opportunities appear, you have already developed many of the capabilities required to succeed.

The question every mentor should ask

Before ending any mentoring conversation, ask yourself one simple question. What did I learn from this person today?

That habit changes the nature of the relationship. Mentoring stops being an exercise in sharing expertise and becomes an opportunity for mutual growth.

Every mentoring relationship begins with the assumption that one person has knowledge to share. The most powerful mentoring relationships end with both people seeing something they could not see before. That is why the best mentors ask more questions than they answer and use the experience to mutually grow.

Key Takeaways

  • The best mentors treat every conversation as a two-way exchange, asking questions that sharpen the other person’s thinking while staying open to having their own views challenged.
  • A four-step process of building self-awareness, gathering feedback from five people, separating perception from reality and refining your defining stories creates growth for both mentor and mentee.

Early in the evolution of social media marketing, I was interviewing a recent college graduate for an entry-level position. During the conversation, I found myself explaining how organizations were beginning to embrace social media as an important marketing channel. I spoke confidently about how brands could connect with consumers in new ways and believed I had a strong understanding of where the industry was heading.

Then something unexpected happened.

The candidate began building on several of my points and offered insights that went far beyond anything I had discussed. She understood the platforms, user behaviors and emerging trends at a level I simply did not. While I had learned about social media through corporate training programs, agencies and industry experts, she had grown up immersed in these platforms every day.


Source link

I’ve Mentored People for 20 Years. I Use These 4 Steps to Help Them Advance Read More »

When Growth Stalls, I Don’t Spend More on Marketing. I Reset the Business

When Growth Stalls, I Don’t Spend More on Marketing. I Reset the Business


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • When revenue levels off, review your financials and talk to frontline employees to find where you’re losing time, money and accountability before you launch another campaign.
  • Use the following weeks to collect outstanding invoices and cut unneeded expenses, align every leader on the same 90-day priorities and give each fix an owner, a deadline and a measure of progress.

Every entrepreneur eventually reaches a season when growth slows. Revenue levels off, referrals become less predictable and sales meetings run longer because everyone is searching for answers. Before long, someone around the table says the same thing: “We need more marketing.”

I’ve learned to resist that instinct.

Over the years, my brother and I have built companies in healthcare, staffing, consulting and hospice. We’ve experienced periods of rapid growth and seasons when the numbers refused to move. Early in my career, I viewed every plateau as a sales and marketing problem. Today, I see it differently.

Growth has a way of hiding operational weaknesses. When business is booming, inefficiencies stay buried beneath new revenue. Once growth slows, those weaknesses become impossible to ignore. The plateau is a signal that your business has outgrown its current operating model. Whenever that happens, I spend the next 30 days looking inward before I look outward.

Here’s the operational reset I recommend.

Week one: Listen

The first mistake many leaders make is trying to solve a problem they haven’t fully understood.

My background is in accounting and finance. Numbers tell a story, but only if you slow down long enough to read it. During the first week, I tell leadership teams to stop introducing new initiatives. Hold off on launching another campaign or changing compensation plans. Your only assignment is to understand what your business is trying to tell you.

I start with the financials because cash rarely lies. Revenue may appear stable while profit quietly disappears. Accounts receivable may have doubled even though sales have stayed flat. Labor costs may have crept up because processes have become less efficient, not because people are working less effectively.

Then I leave the spreadsheets. Some of the best operational insights come from the people closest to the work. I sit with department leaders. I ask frontline employees where they lose time every day. I ask managers which decisions keep getting pushed back because nobody owns them.

One lesson I’ve learned while growing multiple businesses is that leaders often diagnose symptoms instead of causes. Someone says scheduling is the issue. Another believes it’s hiring. Finance blames collections, and operations blames staffing. Usually, they’re all describing different symptoms of the same operational breakdown.

By the end of the week, I want three answers:

  • Where are we losing time?
  • Where are we losing money?
  • Where are we losing accountability?

Everything else can wait.

Week two: Stabilize

Once you understand the business, protect its foundation.

Cash flow has always been one of my biggest priorities because I’ve watched profitable companies fail while less profitable ones survived. The difference was rarely demand. It was liquidity.

Healthcare taught us that lesson early. Reimbursement cycles can stretch for weeks or even months, but payroll comes due every two weeks whether insurance payments have arrived or not. If leaders fail to manage cash aggressively, growth can create more financial pressure than stability does.

During this second week, I focus on operational leaks:

  • Outstanding invoices get immediate attention.
  • Recurring expenses get challenged.
  • Projects that consume resources without producing measurable value get paused.
  • Inventory, software subscriptions, vendor agreements and purchasing habits all get another look.

This is also when I ask a difficult question: “If I were building this company today, would I spend money on this?” The answer is no, surprisingly often. Businesses accumulate expenses the same way houses accumulate clutter. Every year something new gets added, but very little gets removed. A plateau is the right time to simplify before complexity becomes expensive.

Week three: Align

I’ve sat in leadership meetings where every executive had a different idea of the company’s priorities. Sales wanted growth. Operations wanted efficiency. Human resources wanted hiring. Finance wanted stronger margins. Every goal made sense on its own, yet together they created friction.

As we expanded into multiple businesses, we found that leadership alignment matters more than leadership talent. A room full of talented executives moving in different directions creates confusion much faster than progress.

This is the week I realign KPIs. Too many organizations measure activity instead of outcomes. Instead of asking whether people stayed busy, ask whether the work moved the business forward. Every department should understand exactly how its scorecard contributes to the company’s larger objectives. If finance measures one thing, operations another and sales something else entirely, people will naturally optimize for their own department instead of the business.

I also ask every leader the same question individually: “What are our three most important priorities over the next 90 days?” If the answers differ, communication needs work before execution can improve.

Week four: Accelerate

By the fourth week, the focus shifts from identifying problems to executing solutions. Every priority should have a clear owner, a deadline and a way to measure progress. Otherwise, the reset becomes another productive conversation that never changes the business.

Accountability drives momentum. Every leader should leave the reset knowing exactly what they own and how success will be measured. Once that clarity is in place, the business is ready to invest in growth again. Marketing, hiring and expansion produce far better results when the operation behind them is aligned and prepared.

The real work of sustainable growth

I appreciate business plateaus much differently than I did earlier in my career. What I once treated as a sales and marketing problem, I now see as valuable feedback. A plateau reveals where communication has broken down, accountability has weakened and systems have failed to keep pace with the company’s growth.

That’s why I resist the urge to solve every slowdown with more marketing. The strongest companies pause long enough to listen, stabilize, align and accelerate with discipline. In my experience, sustainable growth comes from strengthening the business behind the numbers before chasing the next opportunity.

Key Takeaways

  • When revenue levels off, review your financials and talk to frontline employees to find where you’re losing time, money and accountability before you launch another campaign.
  • Use the following weeks to collect outstanding invoices and cut unneeded expenses, align every leader on the same 90-day priorities and give each fix an owner, a deadline and a measure of progress.

Every entrepreneur eventually reaches a season when growth slows. Revenue levels off, referrals become less predictable and sales meetings run longer because everyone is searching for answers. Before long, someone around the table says the same thing: “We need more marketing.”

I’ve learned to resist that instinct.

Over the years, my brother and I have built companies in healthcare, staffing, consulting and hospice. We’ve experienced periods of rapid growth and seasons when the numbers refused to move. Early in my career, I viewed every plateau as a sales and marketing problem. Today, I see it differently.


Source link

When Growth Stalls, I Don’t Spend More on Marketing. I Reset the Business Read More »

She Grew Up on Food Stamps. Now She Runs an 8-Figure Startup.

She Grew Up on Food Stamps. Now She Runs an 8-Figure Startup.


Key Takeaways

  • Christina Qi started a hedge fund as an undergraduate at MIT, building it to trade $7 billion per day.
  • A “really bad year in 2020” caused the hedge fund to shut down.
  • Qi then started her current venture, a market data provider called Databento.

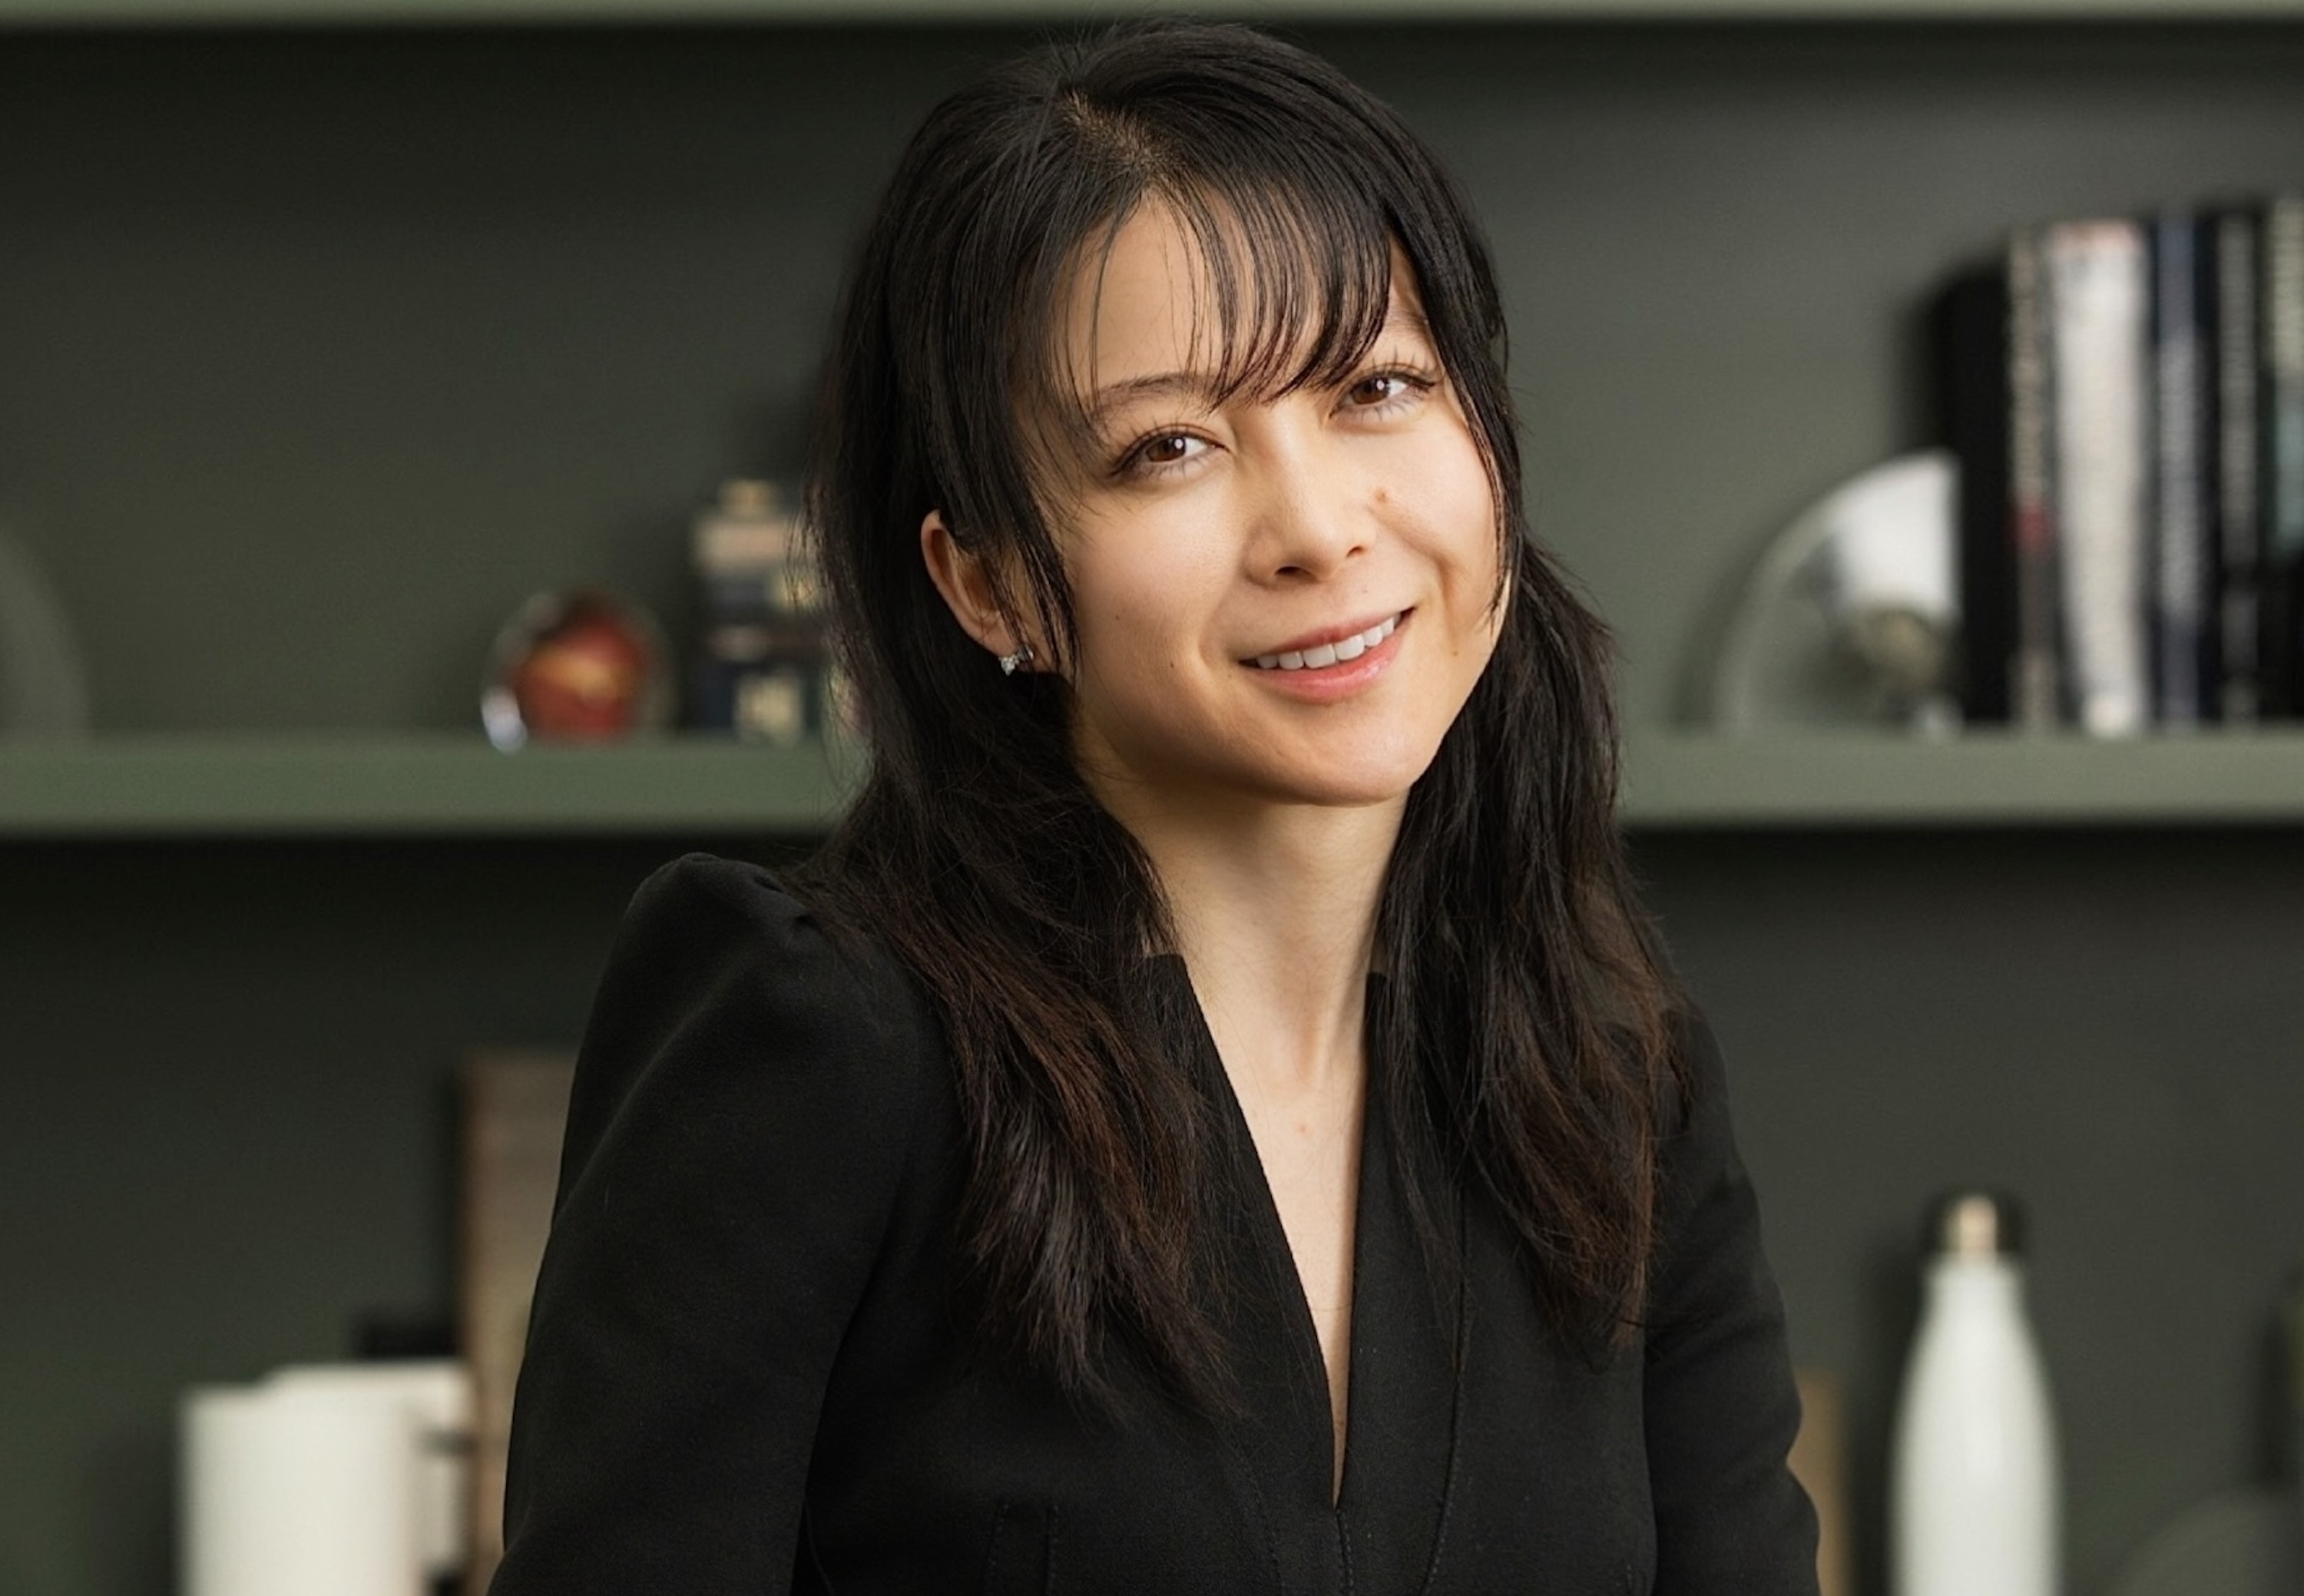
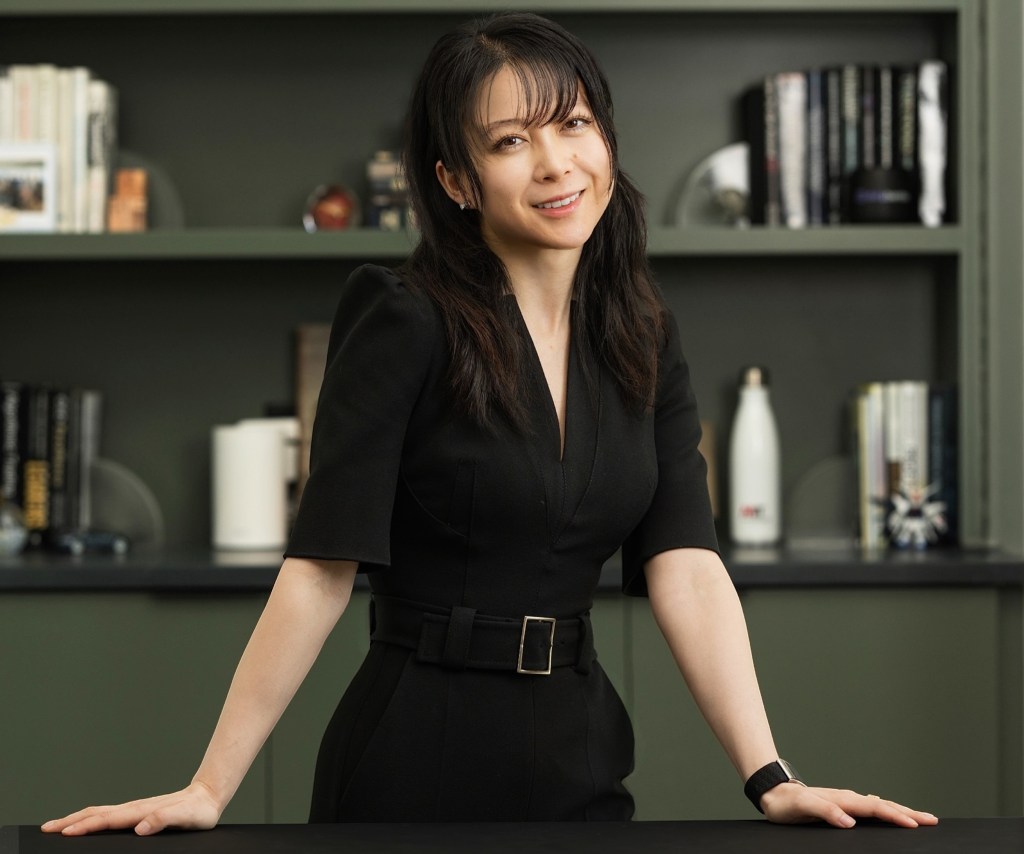
Christina Qi boasts an impressive resume. As a 21-year-old undergraduate at MIT, she quietly did something most finance veterans spend decades attempting: She started her own hedge fund. At its height, the fund, Domeyard, traded $7 billion in volume per day. 

In 2020, after eight years of running Domeyard, Qi and her fellow founding partners realized that the fund was not scalable, and performance was suffering. “We had a really bad year in 2020; performance was down 12%, and so we told our investors that we were shutting down,” Qi tells Entrepreneur in a new interview. 

Christina Qi. Credit: Databento

She started fresh that year with a different idea, co-founding and serving as CEO of a new startup called Databento. The company strives to become “the single source of truth for financial information,” Qi explains. It provides market data for researchers at hedge funds and AI labs and now has 70,000 customers, including Nvidia and OpenAI. 

Databento raised $97 million in a Series B funding round in July, bringing the startup’s total disclosed funding to about $127 million. Qi has not made the startup’s valuation public. Earlier this year, Databento’s head of quantitative analytics, Lou Lindley, disclosed that the startup had 8-figure annual recurring revenue.

“We grew our revenue almost tenfold from a base well above single-digit millions,” Qi says. “We have a lot of competitors in this industry, which is probably why we don’t share exact figures.”

Despite having customers concentrated in Wall Street and Silicon Valley, Qi chooses to reside in her home state of Utah. She runs the business, which employs 38 people, remotely. Instead of seeing coworkers when she steps outside, she looks out at her 10 chickens, two turtles and 15-year-old dog. 

An unconventional founder

Qi explains her entrepreneurial journey “does feel like the American dream to an extent.” She grew up on food stamps and welfare in a low-income household in Utah before attending MIT. 

“Was it harder? Maybe. Look, the starting line might have been a few steps back,” Qi says. “It might have been a little bit more difficult as a result because of where I’m from.”

She adds that people don’t consider her “CEO material” in social settings.

“When I go to a networking event, people sometimes ask if I can speak English,” Qi says. “Or people think I’m a waitress. I got mistaken for a waitress eight or nine times now in my career. Even two weeks ago, I got mistaken as a waitress at a cafeteria.”

People ask Qi where she is “really from” all the time and aren’t satisfied when she tells them she’s from Utah. “People also say my English is great all the time, but it’s my native language,” she says. 

Qi notes that these experiences were frustrating and demonstrated that she had a “disadvantage” compared to her peers.

“I still managed to raise a lot of funding, hire a fantastic team and run a tech business selling to quants, who are mostly men in finance,” she says. “I’m in a very male-dominated industry, and I’ve managed to still be fine.”

Qi points out that her story proves it is possible to achieve startup success even when you start at a disadvantage. She hopes to inspire more people to pursue their dreams and be unafraid of starting their own ventures.

In 2019, Qi was elected co-chair of the board of Invest in Girls, a nonprofit organization focused on financial literacy for high school girls.  She has also held board and committee roles with the MIT Sloan Boston Alumni Association and 100 Women in Finance, a nonprofit that helps women advance their finance careers.

A shift in mindset

Qi says in the Asian American culture she grew up in, admitting to failure is something to avoid at all costs.

She experienced this firsthand at MIT. As a freshman, she applied to her first internship and received a rejection within 24 hours. “I cried,” Qi says. “I just remember that core memory.”

She applied to 100 internships after that, and then it just became like clockwork. “You realize, Oh, rejection is just normal,” Qi says. “The first time, it hurts the most.” 

Now, Qi considers failure a part of her daily life. Investors and customers reject her every day, and she considers it a part of her job. If she is not facing failure, then she is not doing enough or putting herself out there enough, she says. 

“Part of your job description as a founder, as a CEO, is to put yourself out there, embarrass yourself on stage and get rejected,” Qi says. 

That mindset applied when Qi closed down Domeyard. She wrote in a July 2023 LinkedIn announcement that shutting down the hedge fund “felt like losing a part of my identity.”

“Domeyard will always be my first venture — letting go was one of the most difficult decisions we’ve ever made,” she wrote.

Qi said earlier, in a 2020 MIT Sloan interview, that her friends “inspired” her to step away from Domeyard after a “particularly rough year” in 2020. They urged her to take a break and evaluate her career trajectory.

Databento arose out of that self-reflection. Qi worked up the courage to start the venture despite Domeyard shutting down. She was able to learn from that setback.

The founder archetype

Qi also asserts that it is okay to be vulnerable as a founder. She says there’s a certain archetype of founder who is very cutthroat and steps over other founders to obtain funding and attention. Qi encourages founders to follow a different path and be the kind of leader who supports other founders. 

“You can succeed and raise each other up and support each other, even as competitors in this industry,” she says. “That is absolutely possible. That’s what I have done and strive to do with a lot of our competitors in this space, with other founders.”

Key Takeaways

  • Christina Qi started a hedge fund as an undergraduate at MIT, building it to trade $7 billion per day.
  • A “really bad year in 2020” caused the hedge fund to shut down.
  • Qi then started her current venture, a market data provider called Databento.

Christina Qi boasts an impressive resume. As a 21-year-old undergraduate at MIT, she quietly did something most finance veterans spend decades attempting: She started her own hedge fund. At its height, the fund, Domeyard, traded $7 billion in volume per day. 

In 2020, after eight years of running Domeyard, Qi and her fellow founding partners realized that the fund was not scalable, and performance was suffering. “We had a really bad year in 2020; performance was down 12%, and so we told our investors that we were shutting down,” Qi tells Entrepreneur in a new interview. 

Christina Qi. Credit: Databento

She started fresh that year with a different idea, co-founding and serving as CEO of a new startup called Databento. The company strives to become “the single source of truth for financial information,” Qi explains. It provides market data for researchers at hedge funds and AI labs and now has 70,000 customers, including Nvidia and OpenAI. 


Source link

She Grew Up on Food Stamps. Now She Runs an 8-Figure Startup. Read More »

5 Things to Ask a Credit Card Processor Before Signing a Contract

5 Things to Ask a Credit Card Processor Before Signing a Contract


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • U.S. merchants paid a record $198.25 billion in card processing fees in 2025, up 219% since 2009.
  • The card networks’ top interchange rates have barely moved in that time. Much of what merchants overpay is processor markup and add-on fees, and those can be negotiated.
  • Five questions, answered in writing, can expose the markup before you sign and protect you after.

In 2009, U.S. merchants paid $62.1 billion to accept credit and debit cards. In 2025, they paid $198.25 billion, according to Nilson Report figures published by the Merchants Payments Coalition. For most businesses, card acceptance is now the largest operating cost after labor.

You would think the rates themselves must have exploded. They haven’t. When the Government Accountability Office studied interchange in 2009, Mastercard’s highest interchange rate was 3.25%. Today it is 3.30%, five basis points in 17 years. Visa’s top rate was 2.95%. It is now 3.15%, but that increase is recent, and most Visa transactions still clear at 2.95% or less. More people paying by card explains much of the growth in that $198 billion total. It does not explain why so many merchants watch their own effective rate creep up year after year while the networks’ published rates barely move.

That gap is the processor’s markup and the fees stacked on top of it. I know, because I helped collect them. I spent more than a decade in the credit card processing division of a commercial bank, as an executive at Fifth Third Processing Solutions, later Vantiv and Worldpay, now part of Global Payments. During the Great Recession, merchants processed less, so our revenue fell.

Instead of riding it out, the answer was new fees. The day we announced another one, a monthly charge of about $8.95 per merchant ID, the mood was celebration, not regret. I could no longer do it. I blurted out in a boardroom meeting I got into banking to make my mother proud, and I’m leaving because I could no longer tell my mother what I did for a living. That was January 2009.

Later that year, three other former executives and I founded a credit card processing auditing firm to protect merchants from unethical billing practices. Our audits reveal overbilling in about 99% of the statements we review, and more than 90% of the accounts we audit aren’t set up properly from the start. 

Here’s the important math: Interchange, the wholesale cost every processor pays, accounts for 80% to 90% of what a merchant should typically pay. A competitive markup over interchange can be as low as 0.02% to 0.05%. However, commonly reported markups range from 0.15% to 0.90%. For example, on $2 million in annual card sales, the difference between a 0.50% markup and a 0.05% markup is $9,000 a year, not even accounting for additional junk fees.

Before you sign, ask these five questions. Get every answer in writing, signed by an officer of the company, on paper. Not an email, not a phone call. You want something that will hold up in court.

Question 1: “Is my rate fixed, or can you raise it without my signature?”

Nearly every merchant agreement lets the processor change its fees, and even its terms, at any time with nothing more than notice. That notice usually arrives as a line of fine print in the message box on your monthly statement, which almost nobody reads. Visa and Mastercard release rate changes twice a year, in April and October, with more than 200 rules and rates changing at once. A processor increase that lands in the same cycle disappears into that noise. A signed rate is a starting position, not a guarantee.

Question 2: “Will you show me your markup separately from interchange?”

This is the single most revealing question on the list. Interchange-plus pricing shows interchange on one line and the processor’s markup on another. Tiered and flat-rate pricing blend the two, so you can never tell what the processor is keeping. If a processor won’t unbundle it, it is hiding the markup. Then ask the follow-up: Is interchange passed through at cost, or padded?

Question 3: “What happens if I want to leave?”

Look for early termination fees, liquidated damages clauses that bill you for the processor’s projected profit on the rest of the term, and equipment leases that survive after the processing contract ends. Then find the auto-renewal clause. Many require you to cancel inside a narrow window years in the future, and some processors have pushed that notice period out to 90 days before renewal. By the time most merchants look, the window has closed and they are locked in for another term.

Question 4: “Which fees on my statement do you control?”

The card brands set interchange and network assessments. The processor sets much of what sits on top, even when it is named to sound official. “Annual PCI fee,” “regulatory compliance fee” and similar line items sound like government or card-brand charges, and are often pure margin. Ask the processor to label every line on your statement as either a pass-through or its own. Anything it controls, you can negotiate. That $8.95 fee I watched get invented never appeared on anyone’s statement as “extra profit.”

Question 5: “Will you put every verbal promise in writing?”

The classic pitch is a rep quoting a low effective rate that disappears after 90 days, or a promise to match any offer that nobody can find a year later. If the promise isn’t in the contract, it doesn’t exist.

The contract is your only protection

It does not matter how good your rates are if the contract lets the processor change them whenever it wants. Negotiate the contract as hard as the pricing: strike or cap the termination fees, shorten or remove the auto-renewal and lock the markup in writing.

Then keep watching. Processors know most merchants have no idea what the codes and acronyms on a statement mean, and the ones who do have too many other fires to spend hours each month checking for overbilling. That is how accounts drift.

Remember, this is not like other vendor agreements where you validate the bill and then pay it. With merchant processing, you are giving them unvetted access to your bank account — which I often refer to as the “keys to the kingdom.” They take what they want, and then they send you a statement that you can’t read or validate.

Whether you’re negotiating a contract or having an attorney vet it to ensure you are not signing a bad contract that could cost you a lot of money, you should use a firm that is an expert in this space. 

Yes, our firm can help with that, but many others can as well. However, do your homework, too. Make sure they are not a credit card processor pretending to be a credit card processing auditing firm. Check out their BBB, their LinkedIn profiles, etc., and make sure you dont sign anything that is not month-to-month and has a money-back guarantee.  

Key Takeaways

  • U.S. merchants paid a record $198.25 billion in card processing fees in 2025, up 219% since 2009.
  • The card networks’ top interchange rates have barely moved in that time. Much of what merchants overpay is processor markup and add-on fees, and those can be negotiated.
  • Five questions, answered in writing, can expose the markup before you sign and protect you after.

In 2009, U.S. merchants paid $62.1 billion to accept credit and debit cards. In 2025, they paid $198.25 billion, according to Nilson Report figures published by the Merchants Payments Coalition. For most businesses, card acceptance is now the largest operating cost after labor.

You would think the rates themselves must have exploded. They haven’t. When the Government Accountability Office studied interchange in 2009, Mastercard’s highest interchange rate was 3.25%. Today it is 3.30%, five basis points in 17 years. Visa’s top rate was 2.95%. It is now 3.15%, but that increase is recent, and most Visa transactions still clear at 2.95% or less. More people paying by card explains much of the growth in that $198 billion total. It does not explain why so many merchants watch their own effective rate creep up year after year while the networks’ published rates barely move.

That gap is the processor’s markup and the fees stacked on top of it. I know, because I helped collect them. I spent more than a decade in the credit card processing division of a commercial bank, as an executive at Fifth Third Processing Solutions, later Vantiv and Worldpay, now part of Global Payments. During the Great Recession, merchants processed less, so our revenue fell.


Source link

5 Things to Ask a Credit Card Processor Before Signing a Contract Read More »

I Retired at 36 and Started Over at 41. Here Are 5 Lessons I Learned About Time.

I Retired at 36 and Started Over at 41. Here Are 5 Lessons I Learned About Time.


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • More free time does not automatically bring fulfillment. You have to learn how you like to spend it.
  • Money improves happiness when it buys back time and you decide deliberately where that time goes.

At 36, I sold the fintech company I had spent years building and walked away with an eight-figure exit. No client needed an answer. No product roadmap demanded a decision. No inbox confirmed that I was useful. I thought it would feel like freedom. It felt like an identity crisis.

As CEO, I had been time-starved but important. My calendar told me where to go, and my business card told me who I was. Then both disappeared. I had achieved the exit many entrepreneurs dream about, yet I had never stopped to ask how I actually liked to spend my time.

It took therapy, experimentation, motherhood and eventually another company to understand that the goal is not simply more time. The goal is time choice: the ability to decide how your hours are spent before someone or something else decides for you.

Don’t wait for retirement to discover what makes you happy

During my first year of time abundance, I treated my life like a research project. I learned chess. I attempted sewing. I tried yoga and Zumba. I took MasterClass courses for no practical reason at all. I was not trying to earn a credential, impress an investor or turn a hobby into a side hustle. I was simply exploring.

That was surprisingly uncomfortable. Entrepreneurs are trained to value activities with measurable returns, and time invested purely in joy is hard to quantify.

That is exactly why it pays to find out what lights you up now. Put leisure on your calendar with the same seriousness you give a board meeting. You don’t need an exit to get curious about yourself.

Being needed is not the same as being valuable

Eventually, there will be no email requiring your attention. It may happen after an exit, a career change or retirement. If being needed has become your main source of identity, the silence can be destabilizing.

I had to separate my value from my speed at solving other people’s problems. Therapy helped. So did doing things badly. Pole dancing class did not care that I had been a CEO. Singing lessons humbled me; I do not sound like Taylor Swift, even when I use my diaphragm as instructed. No art gallery called about my adult coloring.

Each experience taught me something about myself and added a layer of confidence. None of them advanced a business objective. They simply interested me.

Schedule joy before life schedules over it

My mother died when I was 27. She was 65 and had only recently taken her first flight in first class, something she had put off until the timing felt right. Her death taught me that later is not guaranteed. Even so, I kept planning my time reactively.

Becoming a parent made the lesson concrete. Within a year of selling my company, I welcomed a child, and my calendar filled again, this time with sleep schedules, feedings and more household duties. The time abundance disappeared, but the insight remained: Joy does not protect its own place on your calendar. You have to plan for it.

Spend money to buy back time

At 41, I returned to entrepreneurship with a provocative question: Are wealthy parents happier?

The short answer is yes, when money buys back time. Harvard Business School professor Ashley Whillans found that couples who paid for housekeeping, meal delivery and other time-saving services reported happier relationships. What mattered was how they used the hours they recovered.

I had lived the research before I read it. A night nurse gave me sleep. A nanny gave me more patient time with my children. Grocery delivery, meal preparation and laundry help kept weekends from disappearing. I was investing in the energy to enjoy the life I had built.

Delegate the thinking, not only the doing

That belief led me to found Peacock Parent, a company built around delegating at home without guilt. After talking with thousands of parents, I learned something I had not expected: They were as overwhelmed by anticipating and planning the work of a household as they were by doing it, even when the tasks themselves were handed off well.

I felt it too. I worried about forgetting details. I wanted future needs flagged before they landed on me. And I felt the strain of the sandwich generation: I missed my own mom looking out for me while I cared for my 81-year-old dad.

The lesson for anyone buying back time is to hand off the mental load along with the task. When you outsource something, give away the remembering, the scheduling and the follow-up too, whether to a person, a shared system or a tool. If you are still the one keeping track, you have not bought back much.

Choose how you spend the time you buy

Buying back time only works if you are intentional about where it goes. I will gladly pay an extra $50 for an in-home appointment so that someone else does the driving. I skip the rush out the door, the traffic and the search for parking, and I get my lash extensions at home in my pajamas. I am buying calm as much as convenience.

Then I decide what the recovered time is for. Sometimes it is adult coloring, an audiobook or a hip-hop lesson. Sometimes it is posting on social media, but only when I have something meaningful to share, not to feed an algorithm.

Don’t wait for retirement to decide how you want to spend your life. You can start planning for joy today.

Key Takeaways

  • More free time does not automatically bring fulfillment. You have to learn how you like to spend it.
  • Money improves happiness when it buys back time and you decide deliberately where that time goes.

At 36, I sold the fintech company I had spent years building and walked away with an eight-figure exit. No client needed an answer. No product roadmap demanded a decision. No inbox confirmed that I was useful. I thought it would feel like freedom. It felt like an identity crisis.

As CEO, I had been time-starved but important. My calendar told me where to go, and my business card told me who I was. Then both disappeared. I had achieved the exit many entrepreneurs dream about, yet I had never stopped to ask how I actually liked to spend my time.

It took therapy, experimentation, motherhood and eventually another company to understand that the goal is not simply more time. The goal is time choice: the ability to decide how your hours are spent before someone or something else decides for you.


Source link

I Retired at 36 and Started Over at 41. Here Are 5 Lessons I Learned About Time. Read More »