First Black Woman to Co-Found a Unicorn Company Shares Advice

First Black Woman to Co-Found a Unicorn Company Shares Advice


Key Takeaways

  • Collins co-founded automated pizza parlor Zume Pizza, which hit unicorn status in 2018.
  • She left the company to focus on Planet FWD, a sustainability platform for brands.
  • Collins has raised more than $500 million in venture capital and extols authentic leadership.

“ I’ve always been deeply interested in how businesses come to life,” says Julia Collins, a serial entrepreneur based in San Francisco, California. “This is something that was taught to me through my family. My grandparents and parents were entrepreneurs. So I didn’t even think there was anything special or different, let alone strange, about wanting to be someone who built my own business.”

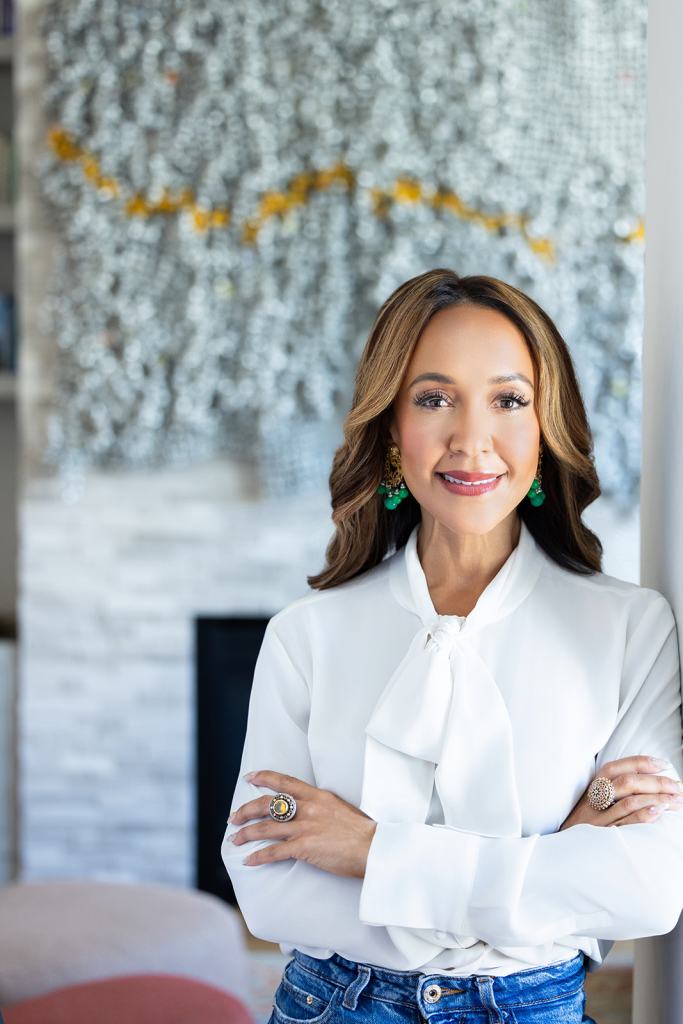
Image Credit: Courtesy of Planet FWD. Julia Collins.

Over the years, Collins, who holds an MBA from Stanford University, has raised more than $500 million in venture capital and built companies spanning hospitality, consumer products, robotics, artificial intelligence and climate technology. 

In 2015, Collins and Alex Garden co-founded Zume Pizza, a venture-backed Silicon Valley startup focused on the automated production and delivery of pizzas. She became the first Black woman to co-found a unicorn company when Zume surpassed a valuation of $1 billion in 2018. 

That year, Collins left Zume to found Planet FWD, a sustainability platform helping brands measure, reduce and report their carbon footprint. 

Entrepreneur sat down with Collins to learn more about her business journey and the advice aspiring entrepreneurs can take into their own. 

Be the first hire on an early-stage team 

In 2010, Collins became the first employee to work at Mexicue, a Mexican-American barbecue chain founded by her friends Thomas Kelly and David Schillace. The concept began as a food truck in New York City before expanding into brick-and-mortar locations. 

Being the first hire on an early-stage team is an effective way to understand if the beginning stages of entrepreneurship are a good fit for you — and involves less risk than immediately founding your own company, Collins says. 

“ That experience taught me a tremendous amount about capital efficiency,” Collins adds. “We didn’t have venture backing or a small business loan. We just had to be profitable out of the gate and fund our growth through the ongoing profitable operations of our business.” 

As a result, Collins also learned a lot about product-market fit: how easy it is to grow a business when it fills a real need, and how difficult it is when it doesn’t. 

The experience also taught her the value of building the right team.

“ No matter what business you’re in, no matter what product you think you’re selling, it is always about the people behind that product,” Collins says. “Even in a world where AI is disrupting the way that we think about value creation and intelligence, at the end of the day, it is all about the humans who are coming up with the solution.”

Don’t conflate your value with the value of your company 

As someone who’s raised more than $500 million in venture capital, Collins acknowledges it can be a difficult experience, especially for founders new to the scene. 

One common mistake she always cautions founders against? Conflating your value as a person with the value of your company.

“ Because almost certainly, that valuation is either too high or too low,” Collins explains. “Therefore, you will be valuing your own success in an unrealistic way on either side. So you cannot value yourself based on the valuation of your company. You have to really separate those two.”

More money isn’t always better either. 

“When  you see these term sheets come in with more zeros than you’re accustomed to, it can really boggle your mind,” Collins says. “And there’s often a temptation to take the term sheet that’s the most money or has the best terms.”

Instead, Collins encourages founders to take a step back and consider their potential investor. How have they treated other founders? Get references from founders who saw big exits, medium-term outcomes and even failures. 

Figure out where capital can meet impact — then lean in

When Collins stepped away from Zume to found Planet FWD in 2018, she had a clear goal: She wanted to focus on the climate-related impacts of the food system. 

“ When most people think about addressing climate change, they think about windmills and solar panels and decarbonization,” Collins says. “All of those things are incredibly important. But most people don’t realize that between a quarter and a third of all greenhouse gas emissions come from land use and food systems.” 

Planet FWD raised a total of $16.8 million with its Series A round in 2022 and has expanded its mission beyond food brands to help fashion and beauty companies and other major retailers. 

What’s more, Collins put Planet FWD’s impact to the test when she founded Moonshot Snacks in 2019. Inspired by Collins’ son, the sustainable snack line for kids was built on an organic and regenerative supply chain.  

“ We took off like a rocket ship,” Collins says. “I could not have predicted the growth around Moonshot.” 

Moonshot even caught Patagonia’s attention. Patagonia Provisions, the company’s food and beverage division, acquired the brand for an undisclosed amount in 2023. It was Patagonia’s first acquisition in more than 20 years. 

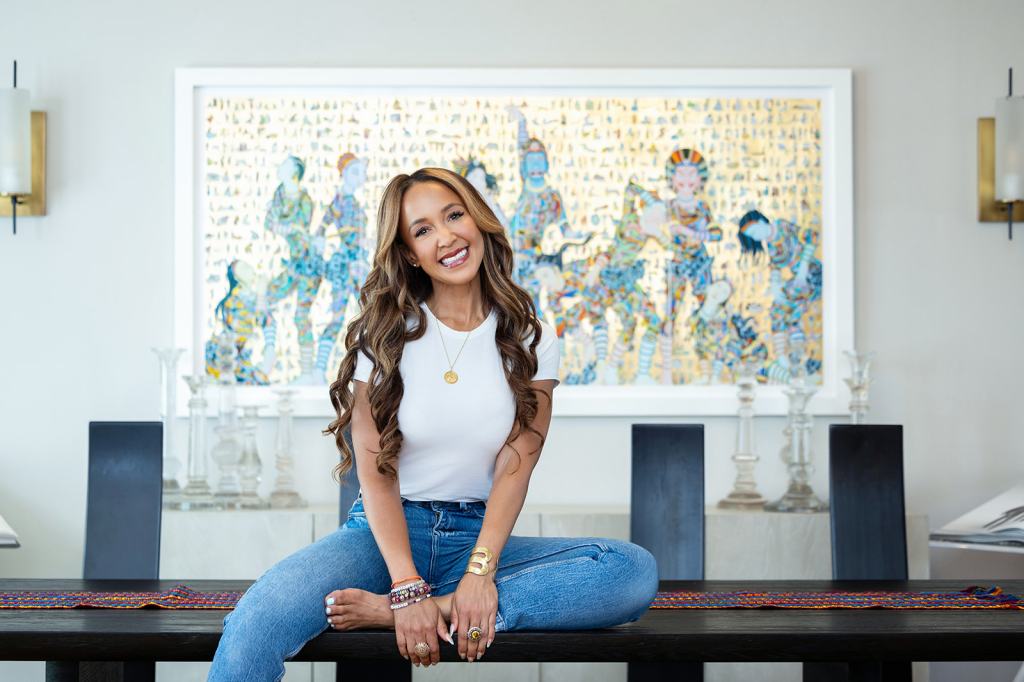
Image Credit: Courtesy of Planet FWD. Julia Collins.

Be a purpose-driven leader who gives people permission

Early in her career, Collins received a lot of leadership coaching from people who meant well — but tried to dissuade her from being too nice. 

“And even some subtle coaching around being too feminine,” Collins recalls. “But when I tried to be less nice, and I tried to be less feminine, I sounded ridiculous.” 

Over time, Collins realized she would be the most powerful leader if she stayed true to her values: being kind and caring deeply about people.

 If you have employees and investors who share your passion for purpose, you’ll do very well.

Although it’s important to deliver your best and hold yourself to a high standard, you should always lead from a truly authentic place, Collins says. 

“ When you do that, you give people permission to also be who they are, and I think that is how people give their best work, when they feel safe, when they feel valued, and when they feel like they can show up in their own skin,” she explains. 

Leading with purpose comes with advantages across the board — whether you’re managing employees or raising capital.

“ If you have employees and investors who share your passion for purpose, you’ll do very well,” Collins says. “If you don’t, it will become increasingly hard to put the purpose with the profit.” 

Key Takeaways

  • Collins co-founded automated pizza parlor Zume Pizza, which hit unicorn status in 2018.
  • She left the company to focus on Planet FWD, a sustainability platform for brands.
  • Collins has raised more than $500 million in venture capital and extols authentic leadership.

“ I’ve always been deeply interested in how businesses come to life,” says Julia Collins, a serial entrepreneur based in San Francisco, California. “This is something that was taught to me through my family. My grandparents and parents were entrepreneurs. So I didn’t even think there was anything special or different, let alone strange, about wanting to be someone who built my own business.”

Image Credit: Courtesy of Planet FWD. Julia Collins.

Over the years, Collins, who holds an MBA from Stanford University, has raised more than $500 million in venture capital and built companies spanning hospitality, consumer products, robotics, artificial intelligence and climate technology. 

In 2015, Collins and Alex Garden co-founded Zume Pizza, a venture-backed Silicon Valley startup focused on the automated production and delivery of pizzas. She became the first Black woman to co-found a unicorn company when Zume surpassed a valuation of $1 billion in 2018. 


Source link

First Black Woman to Co-Found a Unicorn Company Shares Advice Read More »

6 Steps to Rebuilding Your Reputation After Online Defamation


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Many business owners are making the same mistake. They’re focusing entirely on removing the original defamatory post while overlooking the much larger challenge: rebuilding the accurate online narrative that search engines, AI platforms and prospective customers rely on every day.
  • Investing in a proactive online reputation management strategy gives Google, AI-powered search platforms and prospective customers a broader, more accurate understanding of who you are.

Remove defamatory content as quickly as possible

Evaluate your online reputation

Strengthen your online reputation management strategy

Understand how Google and AI shape reputation

Build authority before a crisis occurs

Protect your reputation before the next attack

Key Takeaways

  • Many business owners are making the same mistake. They’re focusing entirely on removing the original defamatory post while overlooking the much larger challenge: rebuilding the accurate online narrative that search engines, AI platforms and prospective customers rely on every day.
  • Investing in a proactive online reputation management strategy gives Google, AI-powered search platforms and prospective customers a broader, more accurate understanding of who you are.


Source link

6 Steps to Rebuilding Your Reputation After Online Defamation Read More »

Women’s Equality Day Is More Than a Celebration — It’s a Reminder of the Cost It Took to Get Here

Women’s Equality Day Is More Than a Celebration — It’s a Reminder of the Cost It Took to Get Here


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • You can have every tool, every plan, every intention. When you are wearing this many hats the gap between setup and follow through is enormous.
  • You finally got there. The feeling you worked toward did not show up. And someone told you to be grateful.
  • Whatever got you to the finish line has no idea what to do once you cross it. And neither do you.

Last weekend, I sat in a chair for 10 hours a day and wrote four articles. I did not eat properly. I did not stretch. I did not drink enough water. I did not take my vitamins. I was completely lit up and completely destroying myself at the same time. By Monday, I had a scratchy throat and could barely move. I knew it was coming. I watched myself keep pushing anyway.

Four years of research, and I still did that.

On Aug. 26, 1920, the 19th Amendment was certified, and American women won the right to vote. It had taken more than 70 years of organizing, marching, arrests, hunger strikes and suffragettes being force-fed in prison cells to get there. Women’s Equality Day marks that win. What it does not mark is what it cost the women who got there. What the fight left in the body long after the battle was over.

One hundred years later, women are building businesses at record rates. Female entrepreneurship rose 69% from 2019 to 2024; 83% of female founders experience high stress; and 54% face burnout. The conversation about why always points to the system. The funding gap. The invisible labor. The double standard. All of it is real, and none of it is the whole story.

I know exactly what to do, but I don’t always do it

I am a founder in a mission-forward company, partner in a global company, mother of two teenagers, spouse and friend who surfaces like a groundhog every so often.

I know I should exercise. I have a dedicated corner of my home with kettlebells, a skipping rope, stretching tools and an iPad loaded with Pilates videos. I wake up and put my workout clothes on first thing so nothing can get in the way. And more often than not, I sit in them all day at my computer and never work out.

Most people would call that laziness. It is not. It is what happens when everything you are already doing has consumed every resource you had available. The account is overdrawn before the workout ever had a chance.

And we are not talking about small things. Every company decision. Every school pickup. Every conversation that needed more of you than you had left. Every night you stayed up finishing something because there was no other time. We start wearing our shoulders like bloody earrings and calling it ambition.

Neuroscientist Bruce McEwen called it allostatic load. The crash that follows was always coming. The workout clothes are just the most honest evidence of it.

What nobody tells you about finally getting there

We fight so hard to get there. The goal. The milestone. The number. The thing we told ourselves would finally feel like enough. And when we cross it, when we actually get there, a lot of us feel absolutely nothing. Or worse, we feel flat. Lost. Empty. Like something is wrong with us for not celebrating the thing we just spent years building toward.

Harvard psychologist Tal Ben-Shahar has a name for it. The arrival fallacy. Here is what it means in plain language. While you are chasing something, your brain is already rehearsing what it will feel like to get there. It plays the moment over and over in anticipation. By the time you actually arrive, the brain has already lived it 100 times. The real moment lands flat because your brain already moved on.

And then someone tells you to be grateful. I am calling bullshit on that.

For women carrying everything we carry, this hits harder and faster. The recovery window between milestones is shorter because the invisible labor fills every gap. The body barely processes one finish before the next thing is already waiting. And the culture that celebrated you crossing the line has already moved on to asking what you are going to do next. You were never taught how to finish. Only how to chase.

Women’s Equality Day is supposed to celebrate how far we have come. I think it should also be an honest conversation about what getting here actually cost us.

We were taught to fight for the right to show up. We were never taught what to do when the thing we fought for finally arrives and feels like nothing. Nobody built anything for the moment after the finish line. Not for the flatness. Not for the crash. Not for the woman standing at the top of what she built wondering why it does not feel the way she thought it would.

Nobody taught us how to land. Until now.

That is the conversation I have dedicated my work to starting. Because ambitious women deserve more than the win. They deserve to actually feel it when they get there.

The next time someone tells you to be grateful for what you built, ask yourself this instead. What did it actually cost me? Not the business cost. The personal one. That is the question nobody is asking. And it is the only one worth answering.

Key Takeaways

  • You can have every tool, every plan, every intention. When you are wearing this many hats the gap between setup and follow through is enormous.
  • You finally got there. The feeling you worked toward did not show up. And someone told you to be grateful.
  • Whatever got you to the finish line has no idea what to do once you cross it. And neither do you.

Last weekend, I sat in a chair for 10 hours a day and wrote four articles. I did not eat properly. I did not stretch. I did not drink enough water. I did not take my vitamins. I was completely lit up and completely destroying myself at the same time. By Monday, I had a scratchy throat and could barely move. I knew it was coming. I watched myself keep pushing anyway.

Four years of research, and I still did that.

On Aug. 26, 1920, the 19th Amendment was certified, and American women won the right to vote. It had taken more than 70 years of organizing, marching, arrests, hunger strikes and suffragettes being force-fed in prison cells to get there. Women’s Equality Day marks that win. What it does not mark is what it cost the women who got there. What the fight left in the body long after the battle was over.


Source link

Women’s Equality Day Is More Than a Celebration — It’s a Reminder of the Cost It Took to Get Here Read More »

5 Hidden Speed Bumps That Keep Good Companies From Becoming Great

5 Hidden Speed Bumps That Keep Good Companies From Becoming Great


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Chasing your “fair share” of the market is a comfort trap that guarantees mediocrity — real growth comes from defining your company by the unmet needs of your clients, not the boundaries of your industry.
  • The biggest threats to breakout growth aren’t your competitors but five internal drag factors — complacency, fear of failure, giant intimidation, legacy reflex and the illusion of exhaustive effort — that leaders must actively dismantle.

If you watch a NASCAR race, you’ll see a tight pack of cars traveling at 200 miles per hour, rubbing paint, turning left and fighting over inches of asphalt. To the casual observer, it looks like intense, cutthroat competition. But in the business world, a dangerous parallel occurs when every company mirrors its competitors’ offerings, operates on identical terms and chases the same core customers. Leaders frequently mistake this frantic, localized activity for true market competition — it isn’t. It’s just a high-speed traffic jam where they’re seeking refuge in industry homogeneity, misinterpreting sameness as safety and viewing genuine disruption as an unnecessary risk.

I addressed this corporate complacency during my recent keynote address at CIBC’s Global Corporate and Investment Banking Offsite in Detroit. The summit operated under the banner of “Full Throttle” — the precise mindset required to break free from a crowded field. During the presentation, my goal was to upend a deeply entrenched business concept: the polite, passive pursuit of your “fair share.”

In high-performance environments, fighting for your fair share is a guaranteed recipe for mediocrity. Average leaders comfort themselves by settling for a market slice that matches their historic footprint. Yet, an elite sports team never aims to finish the season with a mediocre record just to remain comfortable in the middle of the standings. Instead, high-performing leaders focus on a dominant season and a definitive spot on the podium.

Moving beyond the homogeneous herd

The underlying problem stems from how organizations view their core identity. Most companies define themselves strictly by the products they sell or the traditional boundaries of their legacy industry. This narrow focus forces them into a baseline where they look and act like everyone else.

The remaining few choose a completely different strategic orientation: they define themselves by an unyielding commitment to solving the unmet needs of their clients. By dedicating themselves entirely to the client’s problem, these market disruptors naturally venture outside traditional industry boxes. They step away from conventional playbooks to deliver solutions that more conservative competitors consider impossible.

Lessons from a billion-dollar growth run

When I assumed leadership at my last CEO role, the company was a regional player sitting at eighth in their industry. The sector was growing at a sleepy 2% a year, but our team wanted to grow at 100% a year. To achieve that, we had to stop running the same race as everyone else. We shifted from being a service provider of last resort to the most innovative brand in the space, transforming the business from a $500 million operation into a $2.7 billion national leader, culminating in a historic billion-dollar-plus exit.

This level of exponential scale requires building a fundamentally different vehicle from the ground up. We crafted a simple, powerful story that aligned everyone from the first-year receptionist to the vice president, anchoring it with three non-negotiable client promises: service, flexibility and innovation.

We executed our commitment to service so intensely that clients openly wished they could replicate our responsiveness within their own organizations. Flexibility meant saying “yes” to a client’s complex request right there in their boardroom, then spending the entire flight home figuring out the operational mechanics of how to deliver. Innovation allowed us to completely modernize an old-world, slow-moving industry that had resisted structural change for decades.

But as any seasoned executive knows, the real challenge lies in the execution. Throughout my career leading organizations through rapid transformation, I’ve found that the greatest obstacles rarely originate from external competitors. Instead, internal drag factors routinely stall championship teams before they even arrive at the standing grid.

The 5 institutional speed bumps

That’s why, in order to get an organization operating at full throttle, leaders must systematically diagnose and eliminate these five institutional speed bumps:

  1. Historic success complacency: Strong financial performance can trick a team into assuming yesterday’s momentum guarantees tomorrow’s survival. A glance at the Fortune 100 list from a decade ago proves how quickly dominant giants vanish when they stop evolving.
  2. Fear of failure: When an environment penalizes missteps, employees instinctively choose safe, homogeneous paths. True disruption requires an ecosystem where calculated failure is embraced as a necessary step toward innovation.
  3. Giant intimidation: Mid-market companies often look at massive competitors and assume the industry hierarchy is permanent. In reality, giants fall regularly because legacy infrastructure makes them slow and rigid.
  4. The legacy reflex: Organizations naturally develop deep muscle memory that fiercely resists change. Overriding this default behavior takes fearless leadership to empower teams to challenge old processes and forge a new path
  5. The illusion of exhaustive effort: When teams claim they have “tried everything,” they have typically only exhausted options within their traditional playbook. Real innovation hinges on looking entirely outside your immediate industry sandbox to discover what the client actually needs.

Recognizing these limitations represents a diagnostic victory, but eliminating them requires a fundamental shift in leadership behavior. Corporate drag is subtle, frequently disguising itself as prudence, tradition or risk mitigation. When leaders actively dismantle these internal barriers, they unlock a latent capacity for speed and agility, allowing the team to stop looking over its shoulder at competitors and focus entirely on the open track ahead.

Play for the podium

In the end, sustaining a full-throttle trajectory is simply an intentional choice to reject a mediocre finish. It means refusing to settle for a comfortable spot inside the pack. Leaders must commit to a clear corporate narrative, fiercely protect their core customer promises and systematically clear the institutional drag holding their people back

Because the grid is crowded, and the stakes are high. So when the green flag drops, remember: average goals yield average results. But true market leaders play for the podium.

Key Takeaways

  • Chasing your “fair share” of the market is a comfort trap that guarantees mediocrity — real growth comes from defining your company by the unmet needs of your clients, not the boundaries of your industry.
  • The biggest threats to breakout growth aren’t your competitors but five internal drag factors — complacency, fear of failure, giant intimidation, legacy reflex and the illusion of exhaustive effort — that leaders must actively dismantle.

If you watch a NASCAR race, you’ll see a tight pack of cars traveling at 200 miles per hour, rubbing paint, turning left and fighting over inches of asphalt. To the casual observer, it looks like intense, cutthroat competition. But in the business world, a dangerous parallel occurs when every company mirrors its competitors’ offerings, operates on identical terms and chases the same core customers. Leaders frequently mistake this frantic, localized activity for true market competition — it isn’t. It’s just a high-speed traffic jam where they’re seeking refuge in industry homogeneity, misinterpreting sameness as safety and viewing genuine disruption as an unnecessary risk.

I addressed this corporate complacency during my recent keynote address at CIBC’s Global Corporate and Investment Banking Offsite in Detroit. The summit operated under the banner of “Full Throttle” — the precise mindset required to break free from a crowded field. During the presentation, my goal was to upend a deeply entrenched business concept: the polite, passive pursuit of your “fair share.”

In high-performance environments, fighting for your fair share is a guaranteed recipe for mediocrity. Average leaders comfort themselves by settling for a market slice that matches their historic footprint. Yet, an elite sports team never aims to finish the season with a mediocre record just to remain comfortable in the middle of the standings. Instead, high-performing leaders focus on a dominant season and a definitive spot on the podium.


Source link

5 Hidden Speed Bumps That Keep Good Companies From Becoming Great Read More »

Adding This One-Liner to Your Resume Could Help You Get the Job

Adding This One-Liner to Your Resume Could Help You Get the Job


Key Takeaways

  • Job-seekers are adding a one-line section to the end of their resumes.
  • The goal is to make a hiring manager sit up and take notice.
  • One recruiter said that the section adds character to resumes in a time when AI is “pushing out” resumes that look identical to one another.

In a tough job market, white-collar workers are doing everything they can to stand out. Lawyers and bankers are even emphasizing creative hobbies like building birdhouses on their resumes.

According to a recent report from The Wall Street Journal, job-seekers are adding a hobbies section to their resumes to humanize their applications and attract hiring managers’ interest. These candidates have worked at prestigious firms and gone to top schools, but beneath the accolades are human beings who have trained miniature dachshunds and worked on “perfecting restaurant-quality scrambled eggs.”

The goal is to make a hiring manager sit up and take notice. They should think, “Yes, this is somebody I’d like to be in the trenches with at 3 o’clock in the morning on a deadline,” Reder Sheikh, a partner at recruiting agency Major, Lindsey & Africa, told the Journal

Sheikh added that more than half of the legal associates she matched with jobs last year had a hobbies section on their resumes, an increase from just a few years ago. She said that a unique side hobby can encourage recruiters to take a second look at a candidate’s application and make it easier to connect in interviews. 

According to Sheikh, the section should come at the end of a resume and take up only a single line. 

Meanwhile, another recruiter says hobbies add character to resumes. “AI is pushing out resumes that all look the same,” Richard King, who runs a corporate recruitment agency, told the Journal. “Let’s bring the human back.”

King noted that it was fairly normal to list hobbies and interests until the mid-2010s. Recruiters then told job-seekers that they shouldn’t include the section in order to reduce bias in hiring, calling it irrelevant. Now the section is making a comeback. 

Why people are talking about it now

The topic of including hobbies and interests became relevant earlier this year, when a post on X, which the poster has since deleted, went viral. 

“I reviewed a resume that listed ‘olive oil’ as an interest,” the anonymous poster wrote, per Business Insider. “That is not an interest. It’s been hours and I cannot stop thinking about it. There will not be an interview.”

Some X users claimed that the reference was quirky and unique, while others said it could have benefitted from adding more detail

Fred Cibelli, a New York-based technology principal at EY, told the Journal that interview conversations can benefit from a subject beyond the usual talking points, provided the applicant meets the role’s core qualifications. He said that he would welcome talking about a candidate’s appreciation for olive oil. 

Still, candidates must decide which personal details feel appropriate to share. When Dawn Choo applied to Meta several years ago, the data scientist hesitated before including a note about performing in the Washington Ballet’s production of The Nutcracker.

Choo questioned whether highlighting an interest that felt distinctly feminine was wise in a male-dominated industry. She decided to include it anyway. The response was uniformly positive, and she got the job.

Key Takeaways

  • Job-seekers are adding a one-line section to the end of their resumes.
  • The goal is to make a hiring manager sit up and take notice.
  • One recruiter said that the section adds character to resumes in a time when AI is “pushing out” resumes that look identical to one another.

In a tough job market, white-collar workers are doing everything they can to stand out. Lawyers and bankers are even emphasizing creative hobbies like building birdhouses on their resumes.

According to a recent report from The Wall Street Journal, job-seekers are adding a hobbies section to their resumes to humanize their applications and attract hiring managers’ interest. These candidates have worked at prestigious firms and gone to top schools, but beneath the accolades are human beings who have trained miniature dachshunds and worked on “perfecting restaurant-quality scrambled eggs.”

The goal is to make a hiring manager sit up and take notice. They should think, “Yes, this is somebody I’d like to be in the trenches with at 3 o’clock in the morning on a deadline,” Reder Sheikh, a partner at recruiting agency Major, Lindsey & Africa, told the Journal


Source link

Adding This One-Liner to Your Resume Could Help You Get the Job Read More »

3 Mindset Shifts That Turn a Career Plateau Into Your Next Breakthrough

3 Mindset Shifts That Turn a Career Plateau Into Your Next Breakthrough


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Plateaus signal that your current capabilities have maxed out — breakthroughs come from widening your perspective from individual contributor to enterprise thinker.
  • Say yes to stretch assignments before you feel ready, because the challenge itself is what transforms you into the leader it requires.

Success teaches valuable lessons, including some that quietly hold us back. When you’re hitting revenue targets, earning promotions and receiving awards, it’s natural to double down on the behaviors that got you there. Then progress slows, and you no longer experience the same rate of growth. You’ve reached what I call the plateau paradox.

You’re succeeding by every conventional measure, yet you feel stuck. I’ve experienced that unsettling feeling several times throughout my career. But this feeling, as unpleasant as it is, can be the reality check you need to take the next step in your career. I knew it was time to expand my capabilities, challenge my assumptions and redefine what the next level of leadership required of me.

Entrepreneurs don’t fear plateaus. Plateaus are simply the beginning of what’s next. My own breakthroughs began when I embraced three mindset shifts that continue to shape how I lead today.

Widen your perspective

I love mentoring. It’s what inspired me to help launch the Louisiana Impact Fund’s CXO Leadership Program. When an emerging leader tells me they’ve hit a plateau, I share a simple truth: Every new level of leadership demands new capabilities. It’s a sobering realization, especially when you’ve built a reputation for strong execution. I know because I was that leader.

My breakthrough came when I stopped asking, “How do I contribute more?” and started asking, “How can we scale an enterprise capable of achieving far more together?” I made a fundamental shift from a high-performing individual contributor to an enterprise mindset. I stopped measuring success by quarterly execution and started setting the vision for where the business needed to be 24 to 36 months ahead. That perspective quickly revealed an entirely new set of leadership capabilities to master.

Success was no longer defined solely by driving sales growth or leading technology transformation. It demanded organizational design, strategic planning, talent development, partnership building and driving organizations on a global scale. That’s what happens when your perspective widens. Your next stage of growth begins.

Growth gets worse before it gets better

As an endurance athlete, I’ve learned that every climb begins with discomfort. Reaching the next peak requires mental fortitude to embrace it and the discipline to stay the course. Every meaningful breakthrough begins with uncertainty. Progress will get worse before it gets better. Don’t let a dip in progress derail your growth trajectory, but embrace it as part of the learning curve.

When I transitioned from a long career in technology leadership to co-founding a new venture, I knew I was stepping into unfamiliar territory. In many ways, I had become a student again. Because I expected and embraced the dip, I didn’t fall back on old habits when progress slowed — and it did. I stayed curious, kept learning, adapted quickly and made sound decisions aligned with a long-term vision.

That’s the power of embracing the dip. The leaders who break through aren’t the ones who avoid uncertainty. They prepare for it, stay open to learning and emerge stronger because of it.

Raise your hand before you’re ready

In the early hours of the morning, a life-changing email from my CEO landed in the inbox of our business unit executive. He posed a challenge that would change the trajectory of my career. If Intel was truly going to become a technology-first company, every employee around the world — from the U.S. to China to the Philippines — must have access to a PC and the internet. It was an ambitious initiative that would help lay the foundation for our digital transformation, and the CEO wanted to be ambitious with the impact.

So, I raised my hand – I wanted to be part of the team. The next day, I had one thought: “What did I just sign up for?” Over the next two years, that assignment became one of the greatest leadership accelerators of my career. The challenge wasn’t addressing the technology alone. It was leading a global transformation across different cultures, regulatory environments and organizational structures while aligning people around the world behind a shared vision.

That’s when my CEO’s words took on a whole new meaning: “Success breeds complacency. Complacency breeds failure. Only the paranoid survive.” I didn’t have all the answers, but I volunteered because I believed the challenge would help me become the leader it required. That single decision expanded my thinking, accelerated my transformation into an enterprise leader and reshaped how I’ve approached every opportunity since. The next time a stretch assignment presents itself, don’t ask, “Am I ready?” Ask instead: “Who will I become if I say yes?”

Make the plateau your runway

If there’s one lesson my career has taught me, it’s that growth requires forward momentum before it creates lift. Entrepreneurship often works the same way. When you widen your perspective, embrace the dip and raise your hand before you’re ready, you’ll stop mistaking temporary discomfort for failure. You’ll recognize it is the momentum required for your next breakthrough. Many people experience the dip and turn back. The best leaders persevere. If you’ve reached a plateau, remember that this is not where your growth ends. It’s the next runway from which your next breakthrough takes flight.

Key Takeaways

  • Plateaus signal that your current capabilities have maxed out — breakthroughs come from widening your perspective from individual contributor to enterprise thinker.
  • Say yes to stretch assignments before you feel ready, because the challenge itself is what transforms you into the leader it requires.

Success teaches valuable lessons, including some that quietly hold us back. When you’re hitting revenue targets, earning promotions and receiving awards, it’s natural to double down on the behaviors that got you there. Then progress slows, and you no longer experience the same rate of growth. You’ve reached what I call the plateau paradox.

You’re succeeding by every conventional measure, yet you feel stuck. I’ve experienced that unsettling feeling several times throughout my career. But this feeling, as unpleasant as it is, can be the reality check you need to take the next step in your career. I knew it was time to expand my capabilities, challenge my assumptions and redefine what the next level of leadership required of me.

Entrepreneurs don’t fear plateaus. Plateaus are simply the beginning of what’s next. My own breakthroughs began when I embraced three mindset shifts that continue to shape how I lead today.


Source link

3 Mindset Shifts That Turn a Career Plateau Into Your Next Breakthrough Read More »

I Was Hired to Crack the U.S. Market. I Turned Down the Mission — and Doubled Down on the Market Hiding in Our Data

I Was Hired to Crack the U.S. Market. I Turned Down the Mission — and Doubled Down on the Market Hiding in Our Data


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Read your own data honestly, then commit before your competitors update their assumptions.
  • The opening is hiding in the data you already have — the winners are the ones who see it and move before anyone else does.

When I was hired as CEO of Builderall, I inherited one mission: crack the U.S. market. The company had originally been built by a Brazilian team, and they believed an American CEO who spoke English without an accent was the missing piece to unlock the biggest market in the world. I took the job. Then I turned down the mission. Instead of pointing the company at the United States, I doubled down on Latin America.

That wasn’t a bet on my instincts. It was a bet on the data, and specifically on the difference between where the opportunity looked like it was and where it actually was. Every entrepreneur today is running some version of that same decision: an industry is shifting under you, AI is rewriting how your customers behave, and you’re being told to chase the market everyone else is chasing. The winners in this cycle will be the ones who look at the ground they’re already standing on, see the opening most people miss and commit to it while everyone else wanders.

If you’re looking to expand, scale into a new market, or find the blue ocean opportunity in your industry, here’s how I’ve learned to find that opening in mine. Four moves, in the order I’ve learned to run them.

1. Read your own data before you chase someone else’s story

You don’t need decades of industry experience to see an opportunity. You need the willingness to look at your own numbers and ask what they’re actually saying, not what you want them to say.

At Builderall, we had a growing U.S. customer base and had never spent a dollar to acquire those users. On the surface, that looked like a green light to invest heavily in the U.S. But when we studied who those American customers were, we found something different. They almost all had Spanish surnames. They clustered in South Florida, Texas and Southern California. They weren’t Americans discovering a Latin American product. They were Latin Americans who had moved north and stayed plugged into the ecosystem back home.

The sign flipped. What looked like early U.S. traction was actually proof that Latin American marketing was already winning U.S. customers as a downstream effect. The right move wasn’t to enter the U.S. It was to go deeper into Latin America, and let the U.S. footprint compound as a byproduct.

The muscle you’re building is asking what your data actually says versus what you wish it would say. Most people project the story they want onto the numbers. The opening tends to be hiding in the story they didn’t expect.

2. Watch for the macro shift that rewrites a market

The richest openings appear right after something fundamental changes. When the ground moves, whoever notices first has a window before everyone else recalibrates.

Years before I joined Builderall, I worked in a role targeting Latin America and the region’s problems were structural. Most people didn’t have bank accounts. Credit cards were rare. Internet access was unreliable. Then a compressed few years rewrote all of it.

According to a 2023 Mastercard study conducted with Americas Market Intelligence, the share of Latin American consumers without an account at any financial institution dropped from 45% in 2019 to 21% in 2023. The World Bank’s Global Findex recorded a 19% jump in financial inclusion across the region between 2017 and 2021, the largest gain anywhere in the world during that window. Internet penetration climbed from 43% in 2012 to 78% in 2022.

It wasn’t the same market anymore. It had quietly become a new one, and most competitors were still running strategies built for the old one. That’s the pattern to look for. Wherever human behavior changes dramatically and quickly, an opening is forming. AI is doing this right now to nearly every industry that touches content, coding or customer support. The job is to notice the shift before your competitors update their assumptions.

3. Refuse to fight the strongest opponent

Once you’ve spotted the opening, the next question is who else is already there and whether you can beat them.

Going after the U.S. market meant going head-to-head with Wix and Squarespace. According to Wix’s 2024 annual report filed with the SEC, Wix alone spent $175.6 million on advertising in 2024. Roughly $14.6 million every month, from one competitor, before you count Squarespace or anyone else with a marketing budget aimed at the same buyer. Meeting that head-on with our resources was never going to work.

In soccer, you don’t try to break the defensive line where it’s thickest. You look for the seam. The goal on the other end is the same regardless of where you cross through. Business is the same. There’s no bonus for beating the strongest defender. There’s only a penalty for trying.

4. Protect your core, and resist adjacency hubris

This is the move most operators get wrong, and the one that quietly undid the U.S. plan for me.

Being excellent at one thing doesn’t guarantee that every adjacent move will work. And the true cost of the new bet is rarely just the money spent pursuing it. It’s the attention, investment and organizational energy pulled away from what made the company excellent in the first place.

Nike is a case study playing out in real time. The company remains the global leader in athletic footwear, but over several years it aggressively prioritized direct-to-consumer sales while reducing its dependence on the wholesale partners that had helped build its reach and cultural relevance. The strategy didn’t fail in isolation. Nike also faced product, competitive and regional challenges during the same period. But the channel shift proved costly. According to Nike’s fiscal 2025 annual report, revenue fell 10% year over year, from $51.4 billion to $46.3 billion, while Nike Direct revenue declined 13%. By mid-2026, the stock had fallen to its lowest level in more than 11 years.

Nike is now working to restore balance. In fiscal 2026, wholesale revenue grew 6% to $27.5 billion, while Nike Direct declined another 6% to $17.7 billion. The company is rebuilding retailer relationships and reinvesting in the broader marketplace it had previously deemphasized.

Even a company as dominant as Nike can’t redirect attention from a core strength without consequences. When evaluating a new opportunity, the honest question isn’t “can we win over there?” It’s “what will pursuing it cause us to neglect here?” When “here” is where more than 90% of your customers, revenue or competitive advantage currently lives, the burden of proof for the adjacent bet should be extremely high.

That was exactly the choice at Builderall. A parallel vertical (the U.S.) versus going deeper into a core (Latin America) where more than 90% of our customer base already lived and where the ground was finally solid enough to compound. I chose depth. Then I chose specific countries inside that continent as beachheads instead of blanketing all of it at once.

Making it real: test wide, commit narrow, let the numbers decide

We didn’t start with Mexico, Colombia and Peru specifically. We blanketed Spanish-speaking Latin America, ran small structured tests across the board and let the strongest markets bubble up from the data.

The mechanics that made this work are simple. Set your guardrails before you enter anything. Define your KPIs. Run small focus-grouped tests. Put a time horizon on the experiment up front so you don’t slide into testing forever.

That last one is where most entrepreneurs get stuck. Between the ages of 18 and 27, I started roughly 22 businesses. Not all of them were serious, but enough of them were that I learned the lesson the hard way: at some point you have to stop ideating and start operating. Testing is a phase, not a lifestyle. If your test is running past its own deadline, either the test is broken or you’re avoiding the decision the test was supposed to make for you.

The way out is to let the numbers be the boss. Set your win metric from your unit economics: what it costs to acquire a customer, what it costs to deliver, what you make. Decide the exact number a market has to hit to count as a win. The moment it hits, the decision is made for you. You’re not the boss. The numbers are.

Macro disruption isn’t going away. The operators who thrive in this cycle will be the ones who read their own data honestly, notice the shift before their competitors do, refuse the fights they can’t win, protect the core they’ve already built, and commit while everyone else is still wandering.

I was hired to chase the crowded market. I went the other direction. That decision has shaped how I think about growth strategy ever since. Find the seam in the line, drive hard into it, and the same logic will work for you.

Key Takeaways

  • Read your own data honestly, then commit before your competitors update their assumptions.
  • The opening is hiding in the data you already have — the winners are the ones who see it and move before anyone else does.

When I was hired as CEO of Builderall, I inherited one mission: crack the U.S. market. The company had originally been built by a Brazilian team, and they believed an American CEO who spoke English without an accent was the missing piece to unlock the biggest market in the world. I took the job. Then I turned down the mission. Instead of pointing the company at the United States, I doubled down on Latin America.

That wasn’t a bet on my instincts. It was a bet on the data, and specifically on the difference between where the opportunity looked like it was and where it actually was. Every entrepreneur today is running some version of that same decision: an industry is shifting under you, AI is rewriting how your customers behave, and you’re being told to chase the market everyone else is chasing. The winners in this cycle will be the ones who look at the ground they’re already standing on, see the opening most people miss and commit to it while everyone else wanders.

If you’re looking to expand, scale into a new market, or find the blue ocean opportunity in your industry, here’s how I’ve learned to find that opening in mine. Four moves, in the order I’ve learned to run them.


Source link

I Was Hired to Crack the U.S. Market. I Turned Down the Mission — and Doubled Down on the Market Hiding in Our Data Read More »

Billions in Deferred Capital Gains Become Taxable This Year. Here’s Where That Capital Lands Next.

Billions in Deferred Capital Gains Become Taxable This Year. Here’s Where That Capital Lands Next.


Most tax strategies operate in the background. You set them up, they work quietly and you don’t think about them until tax season.

The Qualified Opportunity Zone program doesn’t work like that. It has a hard deadline. And for a specific group of investors sitting on deferred capital gains right now, that deadline arrives at the end of 2026.

Here’s why this matters even if you have no Opportunity Zone position yourself… and what the capital displaced by that deadline is likely to do next.

The QOZ program launched as part of the 2017 Tax Cuts and Jobs Act. The basic idea: if you sell an asset and realize a capital gain, you can defer paying tax on that gain by rolling the proceeds into a Qualified Opportunity Fund within 180 days. The fund invests in designated distressed communities, the “Opportunity Zones” and if you hold long enough, a portion of that original gain gets reduced and any appreciation on the new investment becomes tax-free.

It was a genuinely attractive structure for the right investor. Someone who sold a business, a property or a large stock position and faced a significant capital gains bill suddenly had a way to keep that money working rather than writing a check to the IRS.

Billions of dollars flowed in. Funds launched in markets across the country. Sponsors built ground-up projects in designated zones specifically to attract QOZ capital.

And then Congress added a wrinkle that’s now coming due.

Current QOZ designations expire at the end of 2026. The gains that investors deferred become taxable at that point regardless of whether they’ve exited their fund position.

The One Big Beautiful Bill Act made the Opportunity Zone program permanent going forward which sounds like good news. But it comes with a catch: entirely new zone designations take effect starting in 2027. The zones investors poured capital into since 2017 don’t automatically carry over. There’s a rolling redesignation process beginning in mid-2026 and the new rules introduce different thresholds and enhanced benefits for rural areas that didn’t exist under the original program.

What this means in practice: investors who rolled gains into QOZ funds between 2017 and roughly 2022 face a taxable event at end of 2026 on their original deferred gain. The tax bill they postponed for years is arriving whether they’re ready or not.

For some of those investors, that creates a decision they need to make right now.

Let me walk through the situation a real investor faces today.

Say someone sold their small business in 2021 and realized a $2 million capital gain. They rolled those proceeds into a Qualified Opportunity Fund within the 180-day window. They deferred the tax, the fund invested in a mixed-use development in a designated zone and they’ve been holding while the project was built out and stabilized.

End of 2026 arrives. That original $2 million gain becomes taxable. They owe capital gains tax on it regardless of what they do next. The appreciation they’ve accumulated inside the QOZ fund since 2021 still has potential for tax-free treatment if they hold their fund position for 10 years …  but that 10-year clock started when they invested, not when the original gain was deferred.

So they have a few options and none of them are simple.

They can accept the tax bill, pay it from other liquidity and continue holding the fund position toward the 10-year mark for tax-free appreciation on the gain inside the fund.

They can exit the fund position, trigger whatever gain or loss they’ve accumulated and move that capital somewhere else.

Or they can look at the new program rules taking effect in 2027 and evaluate whether reinvesting into a newly designated zone makes sense for their situation.

Each of those paths has different tax consequences, different liquidity implications and different assumptions about what the fund’s underlying assets will do over the next several years. It’s not a decision to make without a CPA and probably a tax attorney.

Here’s what I find interesting about this from an investing perspective, though. The decision thousands of investors are quietly working through right now has a second-order effect that most people aren’t tracking.


Source link

Billions in Deferred Capital Gains Become Taxable This Year. Here’s Where That Capital Lands Next. Read More »

From Waiting Tables to ,000+/Month in Just 3 Years (Thanks to Rentals)

From Waiting Tables to $13,000+/Month in Just 3 Years (Thanks to Rentals)


Three years ago, Andres Martinez was waiting tables. Today, he owns 10 rental properties, manages another four, and has a rental portfolio that brings in over $13,000 in monthly cash flow. He’s even been able to quit his job and focus on his rentals full-time. But how did he pull all of this off—and in such little time?

Early on, Andres had one goal: maximize the cash flow on every property he bought. This led him to co-living, an investing strategy where you have multiple tenants under the same roof. The cash flow was so strong that he has deployed this strategy across his entire portfolio.

But the journey hasn’t been easy. In today’s episode, Andres shares all the growing pains—from making 200 cold calls a day to find off-market deals to working with shady contractors and navigating difficult tenant disputes.

Through it all, his pure hustle and grit have paid off. Whether you’re looking for creative ways to scale your real estate portfolio or create enough cash flow to replace your salary, Andres has a blueprint that works—even here in 2026!

Henry:
Three years ago, Andres Martinez was waiting tables. Today, he owns 10 rental properties, manages another four, and has a rental portfolio that brings in over $13,000 in monthly cashflow. He’s even been able to quit his job and focus on his rentals full-time. So how’d he pull all this off starting in 2024? Early on, Andres had one goal, maximize the cashflow on every property he bought. This led him to co-living, a strategy where you have multiple tenants living under the same roof. The cashflow was so strong that he deployed this strategy across his entire portfolio, but the journey hasn’t been easy. In today’s episode, Andres shares all the growing pains from making 200 cold calls a day to find off-market deals, to working with shady contractors and navigating difficult tenant disputes. Through it all, his pure hustle and grit have paid off. Whether you’re looking for creative ways to scale your portfolio or create enough cashflow to replace your salary, Andres has the blueprint that works even here in 2026.
What’s going on everybody? I am Henry Washington. And today on the BiggerPockets Podcast, we’re bringing you an investor story with Andres Martinez from Dallas, Texas. Let’s jump right in. Mr. Andres Martinez, welcome to the BiggerPockets Podcast. How you

Andres:
Doing, Henry? Thanks so much for having me.

Henry:
Glad to have you, man. Excited for you to be here. Now, I understand you’ve been on the rookie podcast before, but for those who haven’t heard your story, why don’t you give us a little bit of your background and how you first got into real estate?

Andres:
I’ve been doing real estate since January 2023. I was working full-time as a waiter. I went to college for music. I studied jazz, as you can tell from my

Henry:
Albums

Andres:
Here. That did not go well. I realized a starving artist. I was working as a full-time in a restaurant business. And then I started making pretty good money as a waiter, honestly. I was very close to the six figures on the years. And then I got married and my wife is like, “You need to buy a house.” Perfect. We need to buy a house. And then even though I was reporting all my income because it was cash, we couldn’t really qualify for the house that we wanted. This is the time where the interest rates are just starting to go high. So we missed the three or 4%, but now there are seven

Henry:
And a half. Oh, so this was like 2023, late 2023. Late

Andres:
2023, exactly. November, December. And we missed it because we couldn’t find the right lender. So now when we find the lender in December, he’s like, “Well, sorry, now it’s 7%.”

Henry:
Oh, wow. So

Andres:
I was like, “Okay, how do you buy a house without a mortgage?” So I fell into the rabbit hole of creative finance. I jump into there. I didn’t know what wholesaling was back then. I just started making calls. I found my first deal in two weeks, take my wife to see the house. She’s like, “Absolutely not.” So I was like, “Okay.” So I told her agent, “Look, it didn’t work for us. Thank you.” So now I was part of a real estate mastermind. So I go to our local meetup and I told the guys like, “Yeah, I found this deal. I just didn’t know what to do with it.” And this guy’s like, “Why don’t you wholesale it?” I said, “What do you mean?” He was like, “You can make money just by flipping the contract.” And I was like, “Teach me.” So we call the agent again on that same meetup, called the agent.
I was like, “We’ll see the property again tomorrow.” We go, he runs the numbers and he’s like, “This is a good deal, man. We can make some money here.” He get under contract and he showed me how to flip that paper. And I was like, “We just make $10,000 in a few phone calls?”
At that time when I was doing the waiter stuff, I was flipping furniture online. I was trying to start any type of side hustle, flipping phones, washers, dryers, clothing on eBay, anything I could get my hands off, make money. But I never really thought I could make money on real estate because I don’t come from a family with money. I’m an immigrant. I’ve been here since I was 18 only. So when that happened and I was like, okay, this is it. I saw Dr. Strange and the Marvel movies.This is the one. And I went straight ahead, started calling nonstop.

Henry:
Okay. So you said you found that first deal in two weeks that you ended up eventually wholesaling. How’d you find that deal? Just calling agents on the MLS? Calling

Andres:
Agents on the MLS. Wow. Imagine three days into real estate. Yeah, do you want to do seller finance or sub two? No, I getting 500 calls every day. I was like, okay. And then eventually this girl’s like, “Yeah, we had this property on a contract with somebody else, but they couldn’t perform. Do you want to come see it?” And she sends me the terms, she sends me the mortgage sheet. I got lucky. After

Henry:
500,

Andres:
600 calls, somebody say yes.

Henry:
You called 500 to 600 people?

Andres:
Every single listing on Zillow.

Henry:
Folks, if you are listening right now, that is absolutely not luck. That is hard work paying off. Yes, that seems like a long shot. Sure. But if you sit down and you put effort in and you call 600 people determined to get a deal, you’re probably going to get a deal. And that goes for almost anyone. If you are in a market and you call the right list and you have that much dedication, you’re going to stumble across a deal. So no, that’s not luck. I call that positioning. You put yourself in the position to be ready to capitalize on a deal. You got paid to get an education in how to do a wholesale deal. So how long did it take you to land your

Andres:
Next one? Nine

Henry:
Months. Nine months. I didn’t

Andres:
Know that you can pull lists of low equity or seller finance. I was just calling every single listing.

Henry:
So

Andres:
Now I’m pulling lists. I’m making calls. I’m getting better at sales. I’m getting better at my pitch. Nothing, nothing, nothing, nothing, nothing, nothing. Nine months later, it was a very humbling lesson because I was about to give up. Actually, I had given up two weeks prior to that because we went to the doctor with my wife and we found out she was having some health leisure. So I need a lot of money. I was about to sell the house. All my savings were about to go there. No more wholesaling. Because at this point, these nine months, I got fired from my job twice because every time a seller calls me back on a Friday night, instead of having fajitas on my hand, I have my phone.

Henry:
And a

Andres:
Manager’s yelling at me. I was like, “Hold on. If this is the 10K call, I’m about to walk out. This is my real proof of concept.” It never happened. So we’re driving back from the doctor’s appointment and I’m just like, “Okay.” I tried. I tried. I made two, 300 calls every day manually and somebody pick up the phone. It didn’t work. I really did my best. I didn’t take days off Monday to Sunday. It’s not for me. And then on that drive home, I get a text message back. “Hey, Andres, this is Andre. You called me a few months ago. You explained to me about the seller financing and you were right. The person who got me in their contract for this price, they couldn’t close. Can you help me out? Because now I already moved out of the house and I am behind one month of the payments.
And I’m a human person and we got under contract and that was my first wholesale assignment fee of $10,000. A week later, I got another message back. Hey, do you still want to buy this house? And then the cycle of wholesaling, you need to build a pipeline. The pilot came back to me. So

Henry:
I

Andres:
Started making money now.

Henry:
This is how direct-to-seller marketing typically works for anything, whether you’re going to wholesale it, whether you’re going to keep them for yourself. When you’re doing direct-to-seller marketing, sometimes what you’re doing is you’re starting to roll that snowball, right? Because you’re putting in effort and people are saying no, but you’re also giving them the idea that working with you or your creative strategy or even the idea to think about selling is just now popped in their head because they weren’t thinking about it before until you called. And so they said no, maybe because they didn’t understand it, maybe because it wasn’t the right time. But once you plant that seed, it starts to grow. And then at some point they may decide, oh, let me call Andreas. He called. He said he could do this. Now I’m in the right space. So you got to get the snowball started.
And where people fail with direct to sell and marketing is they quit before their snowball gets big enough to start producing results for them. And so they say it doesn’t work and they’re done. And then they miss their opportunity because maybe somebody else starts marketing in the meantime to that same list. And then those leads that they started to foster end up going to somebody else, man. So that’s super cool. So you’re wholesaling, your proof of concept worked, then you start popping off $10,000 checks, $7,000 checks, $9,000 checks. So it’s working. What did you move into after that?

Andres:
When I got it started, even before real estate, the reason I was doing the side hustles is because I’ve always wanted to achieve the point that I achieve now where I have enough cash flow. I don’t have to leave my house. I leave my house right now once or twice a month. I don’t pick up the phone for anybody except if it’s an emergency for my tenants because now I have AI running everything. That level of freedom for somebody like me who had to start working at 14, who has always, depending on somebody else, I wanted to flavor that. And once I did, I realized I really like it and I don’t want to go back to being on the hustle. A lot of people think because I hustle hard, it’s because I have the alpha type. I want to be the big CEO. I want to make the billion dollars.
I am very okay making my 20, 30K a month passive income, working maybe 20, 30 hours a month. Not having to talk to anybody on the phone. I don’t have to talk to sellers. I don’t have to talk to agents. But the transition was, it’s very interesting. So going back to the beginning, on that deal with the real estate investor, we went to the home and he’s like, “Okay, I will make this work, but I need to put 10 rooms.” I was like, “Absolutely not. You’re not going to raise money for that. You’re going to borrow from somebody money. You’re going to steal it. Then you’re going to walk away.”

Henry:
No,

Andres:
I pass on that deal, but I got me thinking, hold on, maybe there’s something here I don’t know about room rentals. And I’m already part of a mastermind, so I start talking with people, “Have you heard of this?” I was like, “Oh yeah, I’ve heard about this. I have that. Yeah. This, this and that.” I was like, “Holy shit, look, okay, that’s it. That’s the end goal, cashflow.”

Henry:
So I have several more questions about how you transitioned from this, but I want to get into those right after this break. All right, we are back on the BiggerPockets podcast with investor Andreas Martinez. Andres started off wholesaling, did several wholesale deals, made good money, and then decided, you know what? I’m not going to do that anymore because I want to try this co-living thing. So you started to research, you learned about co-living. Did that deal that you were trying to wholesale become your first co-living property or did you end up wholesaling that?

Andres:
No. That same meetup that I went where I made my first wholesale deal for $500, it happens every Saturday of the first month. I was on the way there and I got a call from my boss because I’m still working at the restaurant. I was like, “I need you.” And I was like, it was like January 2nd, brand new year. I woke up early, I shave a workout. I was like, “I’m going to go meet a lot of people. This is my year. And I miss a meetup.” And I get a text message from another guy that I was kind of coaching, teaching how to do wholesale. He was like, “Hey, this agent was walking around the meetup.” And this is a creative finance meetup, full of creative finance investors. He was describing this property, these five rooms, three bedrooms, and the seller is in pre-foreclosure and he doesn’t really want to make a lot of money.
He just wants to help the seller. But nobody else pay attention to it. And I automatically, nobody pay attention because they don’t know co-living. Text the agent, I was like, “I’ll call you as soon as I get out of work.” I was supposed to get out at four. I didn’t get out until 110. I gave him a call. He was like, “I was waiting for your call.” I was like, “Can we jump on a Zoom?” Saturday at 11:30 at night, we’re on a call for an hour. The next morning, we’re meeting at the property with the seller before I go to work. Property under contract. $3,000 down. I got a 2019 house, corner lot, five bedrooms, three bathrooms, ready to go for co-living.

Henry:
And so you essentially take over payments on this property and you convert it to co-living. Did you have to add any bedrooms or did you just do it co-living as it sat?

Andres:
So I bring the deal to my mastermind to make sure that, even though I already knew it was a good deal, I just needed. I was about to put a lot of money in the conversion. It was about $40,000 to add three more rooms. We needed to redo the flooring because it was carpet. I needed to put now LVP paint. I don’t know anything about construction yet. And the guy who’s hosting the mastermind, he’s like, “Andres, do you want to sell me this?” And I was like, “Oh, I really got a deal. I really got a deal.” And he was like, “This works long-term rental, section eight, meantime rental, Airbnb, and you’re going to go for the world strategical living.” I was like, “That’s what I want to try because it’s in a great area. It has already five rooms, but I need to put three more to make maximum profit.” And on that call, I was like, “It’s going to be a lot of money, but I wish I could partner with somebody.
I don’t have to use my money.”

Henry:
So the money you were raising was the money for the renovation because you bought it sub two, but when you buy it sub two, that just gives you the money to buy it. If you’re going to renovate it, that’s got to come out of your pocket. You

Andres:
Need the renovation, you need the furniture, you need the refrigerators and stuff, holding costs.

Henry:
So about how much were you trying to raise to get all this done?

Andres:
58,000. And on that Zoom chat, somebody text me. He was like, “Hey, Andres, we have money. Can we partner?” I was like, “Okay, let’s talk about it. You bring all the money. I’ll bring everything else. I’ll manage it and then we’ll go from there.” We go under contract, we close, we start renovations. My contractors end up stealing a lot of money, no performing. I lost at that point because it was my responsibility, $40,000 out of my pocket to rebuy all the flooring. Oh, boy. The guys who were doing the work at the house, she never paid them. So they were trying to come back and to destroy the bathrooms that they had built. I had to stay at the property. Oh

Henry:
My goodness.

Andres:
Heart attack after heart attack. I was going to Home Depot in the morning, doing the renovation myself at the end, going back to work all day, double shift because now I needed money. Everything that I went from home selling was kind of gone.

Henry:
Going

Andres:
Back at night. Anyways, we went live on March 1st. I was fooled in two weeks.

Henry:
Oh my goodness. And how much were you renting each bedroom for? At

Andres:
The beginning, it was between eight and 850. The private bathroom was for $1,000. So the total income was somewhere around 6,500.

Henry:
$6,500 a month. And what was your mortgage taxes insurance?

Andres:
2,100.

Henry:
Oh my goodness. After

Andres:
Expenses and everything, the net was at the beginning, somewhere around 27, 2,800.

Henry:
Yeah, man, that’s a phenomenal cash flowing deal. What area of the country or what city are these deals being done in?

Andres:
Mainly Fort Worth, Texas. Now I’m in DFW, but at that point I started mainly in Fort Worth, Texas.

Henry:
So what did the next deal look like and how long did it take you to get that? Well,

Andres:
I was finished the renovation. I contacted everybody that I knew. I need help. I end to meet this investor who already had another property coming up. And he was like, “Hey, since you know how to operate, you can get the properties, you can find the tenants, let’s partner up.” Because I’m already partners with a contractor. And I was like, “Okay, perfect. That’s the second property.” We jump into it. Turns out the contractor ends up scamming him and scamming me. Boy.

Henry:
Oh for two on contractors. The

Andres:
Main guy who was working for the contractor ends up renting a room in the second house.
So I’m walking through the house. I was like, “Hey bro, you’re still missing trim here and there and there.” Eventually three days later, I was like, “Hey, rent is due.” And then he explodes like, “You haven’t paid my boss. She says you haven’t paid her for a month.That’s why she doesn’t have money, blah, blah, blah.” And I showed him the receipts like, “We already pay her.” She was gone. So he was like, “I don’t have money.” And I was like, “Okay, let’s get to work.” And then I started just asking people, “Do you need a contractor?” He did a good job. And he’s the main guy.

Henry:
Find

Andres:
Him a job, find a second one. I was like, “Okay, can you find bigger houses?” I was like, “Yeah, let me keep buying them.” So now I was doing my food renovation. I learned a lot of construction there because he’s been doing construction for 20 years. So we started doing more co-living for me, co-living for other investors, working with code enforcement, learning how to do permits. Now I had an already under contract that was a fix and flip. We did the flip, we did another flip. I bought another co-living. So now instead of doing the wholesaling, now the contractor gig took up. And if you ask me between being a contractor and a wholesaler, I would say being the contractor.

Henry:
So that first co-living deal, you had a partner because the partner gave you the money for the renovation, the furniture, and then you guys were fifty fifty. Second deal was a different investor than who you were partnered with before? Yes,

Andres:
It was a different investor. He already wanted to invest in co-living, but he was missing the operations because operations is very heavy in co-living. So it was the same deal, fifty fifty. But he was like, since you are messing up on the contractor stuff, let me bring my partner because she’s the contractor and then the whole thing. Got it.

Henry:
So that ended up being a debacle from the contractor side. But it sounds like you were still able to get the house fixed up. And then were you able to get that one rented out? And how many bedrooms were in that one?

Andres:
That one was eight bedrooms with an ADU in the back. And

Henry:
You were renting the rooms in that one for about how much? A little

Andres:
Bit less, between 750 and 800.

Henry:
So give us the breakdown on that. What was your mortgage, taxes, insurance, and what were you bringing in a month?

Andres:
Gross income was around 64, 6,500 as well. Pretty similar because we didn’t have the ADU fully functional yet. That would’ve been an extra thousand.

Henry:
Wow. We

Andres:
Would kill it. PITI on that one was like 2,300, but we had a HELOC that we also took on second position because the star had a HILOC. So it was like an extra 300. But the net was still around the same, 22, 2300 at that time.

Henry:
Yes. That’s super cool. You were finding the people who either have the deals or can find the deals, and you bring the operations and the experience. And then you’re typically fifty fifty in those deals. So either somebody brings the money or the deal, you bring the operations, the experience, and then you fifty fifty. But it sounds like you realized after two failed renovation projects with contractors running off with some money that you were like, “This is a gap that I need to fill.” So tell me about that. Did you go out and hire guys that you keep in-house or do you have just other GCs that you work with that mainly only work for you? What does that structure look like?

Andres:
So what I realized at that point was this contractor, she didn’t know anything about a contractor. She just happened to find her main guy and his team was doing the stuff. So I was like, “I can do the same. I can find the deals, I can find the houses. With the difference, I can work because I already finished my house. I did the flooring, I did the tile, I did drywall.” I have a better understanding of that. So I was like, “Look, if you help me learn this more, I can get you jobs.” Because as a wholesaler, if I come with a contractor, at that point I was still thinking about wholesaling. It’s a double win. So we started doing that.

Henry:
So this was the guy who was living in the place. You said he did good work. So you said, “I’ll be your new GC if you start working for me.” And so you kept him busy. So now you’re able to manage the renovation and then manage operating the property. So that’s the value that you bring to the deal. And then somebody else either brings the deal or brings the money and then you fifty fifty on the co-living.

Andres:
Yes. So we did that one a month after I did one more because I still had the leads coming from wholesaling. So I bought one more house, I raised the money, I did my own construction. Usually contractors are telling six to eight weeks. I was able to do it in two weeks. And I started realizing, okay, all these people are just talking bullshit because they need to split their teams here and need to split their damn. If you keep a group in one house, framing takes one or two days. Drywall takes two more. Then you put the texture, it dries, it paints. That’s done.Because the electrician can come in the morning, can come at nine, the AC. So it doesn’t take unless you’re doing plumbing, electrical course, all of that. So I started keeping the guys busy. I started making money there. Slowly fade away from wholesaling.

Henry:
So you’re GCing for other investors either on flips or other co-living properties? Mainly

Andres:
Co-living. I’ve done 29 now.

Henry:
That’s really cool, man. I love to see that transition. So that’s on the GC side. Would you mind just giving us a total breakdown of your portfolio as a whole to get an idea of what your business looks like?

Andres:
Yes. So I have right now 14 properties. I own 10 of them and I have four under management. On average, each one nets 1,900, 2,000 right now. All

Henry:
Right. So across that portfolio, Andreas, what is the net cashflow? What do you put in your pocket every month?

Andres:
So all the properties net around 26, 28,000 a month, depending on the vacancies and all of that. And I take 50% of that. So I take home myself 12 to $14,000 a month. Man,

Henry:
That’s super cool. Congrats on building that. I do have some more questions because I know there’s people listening who are very curious about co-living. So I’d love to get some of your thoughts around best practices, things people should avoid if they’re getting into this business. And also just thoughts around the management because it is a very management heavy business. Leases are a big thing and making sure all that’s sorted out. And so I’d like to dive into that, but first I want to take a quick break. All right, we are back on the BiggerPockets Podcast with investor Andreas Martinez, who started off in this business wholesaling, but transitioned into a niche called co-living. Now, co-living has been a buzzword for the past couple of years. It’s really started to pick up steam. More people are getting into this space mostly because affordability of housing is tough, especially in larger metro areas where real estate prices are higher.
And so for people who are interested, what are some of the most important things they need to be thinking about when operating a co-living business? This

Andres:
Is not a passive strategy at all.

Henry:
You’re

Andres:
Having the complexity of having multiple personalities living under one building. So everything that you’re thinking right on your head that is a red flag, it is a red flag. But there are ways to go around it. There are ways to fix it. There are ways to manage it. So you need to develop a lot of systems to be able to run this because for people who are starting it out, if you’ve never run a side hustle, if you’ve never run a business on the side, if you’ve never had that mentality, it could be overwhelming for you if you start growing your portfolio a lot. So just to start with one, start with two, give it a few months, see if you like it, and then decide to move forward.

Henry:
Okay. Let’s play a game of myth busters because there’s a lot of assumptions that people make with co-living. Myth number one or truth is that co-living’s going to have high turnover. So you’re going to have people moving in and out all the time, short leases. It

Andres:
Depends what type of business you want to run. If you allow somebody to come for three months in your house because they are on an internship or just because they’re getting divorced, then yes, you’re going to have turnovers. And this is what I try to explain to people when they come to my groups and want to learn about co-living. I am focused on co-living because of the affordability issue. I don’t want to have people out of state coming here for a month or two. I am targeting the guy that works at the gas station, the lady that works down at the McDonald’s. They don’t make enough to rent their own studio, but they have a job here. They have their family here, and they want to be independent. So they come to my house. I always start on a month-to-month lease because in Texas, if I don’t like them, I can let them go.
If they don’t like me, we can just part ways amicably. And I always tell them that, look, it’s a month, maybe two months, make sure you like it. And at that point, either you sign a 12-month lease or you’re out.
So once you stabilize the property, you don’t have turnovers. And it’s 107 rooms that I have. It will be impossible for me to run all of these by myself with no BAs if I had high turnover. The problem of the weekly rental and all of that, imagine you have to move so many people

Henry:
Weekly.

Andres:
You need a big team. And every time you bring a personality into the house, like, oh my God, who’s coming now? It’s a big gamble.

Henry:
Given this method, do you find that you usually have people that stay there entire term and then re-lease up with you? I have

Andres:
Five people that I’ve had since my first house. Actually, three of them on my first house just signed in January an order one-year lease.

Henry:
Oh man, that’s really cool. You

Andres:
Have to think about it. And that’s what I tell people. Why would they leave? They have the same job. They haven’t gotten a pay raise. They are not going to college. They’re not going to get a higher paying job. And they have not found a partner yet. And this is people between 25 and 35. We’re not talking about elderly or any people disabled. The house runs well, the house is clean, the house is safe. They know that management is on top of everything. Why would they leave?

Henry:
All right. Myth number two or truth is that there’s too many people issues and my phone is going to be going off all day long with tenants complaining about their housemates. Yes,

Andres:
If you don’t know what you’re doing. For example, a lot of people don’t want to talk to them upfront. They want to have a message and auto approval ratings, like no background checks. If you allow that type of people in your house and then you get mad because they didn’t wash the dishes, that’s on you. You’re a terrible operator, you’re a terrible manager because you have to realize everybody comes from a different background. For this person, that means clean. If you rent the same house and you have somebody else who comes from a different background who they know what clean is and they come in and they see dishes all the time, I’m out of here, bro. The model that we run is we are very upfront. Before they even come to see the house, there’s eight people here. You’re going to have to be extremely clean, especially in the bathrooms.
If you don’t like it, just let me know, cancel the showing. And a lot of people do. And that’s good. Go leave somewhere else. I want to have people here who need it in my houses. And when they come, they follow the rules. I really have almost no problems with dirty dishes or people fighting in the house or that they don’t take the trash. It’s all about pre-screening, man. It’s every landlord’s secret is pre-screening. We

Henry:
As landlords have to stop putting off our failures on our tenants. Our job as landlords, no matter what type of landlord, is to be great at tenant selection. The better we are at tenant selection, the more profitable that we’re going to be. All right, here’s one that you may not have had to experience yet, but it is one that people think about. When going to sell a property, do you have to un-renovate and put it back in its original condition? You

Andres:
Can sell it as a co-libian to another investor. But you heard me say, I bought a five bedroom house and I added three rooms. That’s only two by fours on drywall that can be taken out in one day. Maybe going to cost me three to 4,000 to report a house and put it back to normal. Now I can resell my property to the normal world. I don’t have to wait for a Collibian investor to come and buy this house because if you’re buying a house that is already renovated, if the investment was so good, why are you selling? On top of that, an appraiser walks into the house and they don’t see a living room. They’re like, “What is this? How do I compete?” So there are very few lenders who will help you finance a ready converted co-libian. But as an investor, I want to keep my options open.
The

Henry:
Other myth slash truth is parking is going to be an issue. Everybody’s going to fight over parking spots. The neighbors are going to complain because there’s cars on the street.

Andres:
Yes, that’s true.

Henry:
And how do we deal with it? My first

Andres:
House, my neighbor, he wanted to call the city on me. He was very mad that we were going to rent. And I was like, “I have my own parking in my corner lot, bro. And all my houses are either corner lot. I have parking in my backyard. So there is absolutely no reason why my tenants would park against their houses. In fact, it is in my lease. If you own to any more houses, we have parking pictures there where they’re supposed to park. I check the cameras once a week at the beginning. Once the tenants are on their behavior like, okay, we only park in our house. They stick to it. So I don’t have parking issues after that. But it’s true. If I didn’t buy the right house with parking, I will be struggling. All right,

Henry:
Andreas, thank you so much for playing that game. I know a lot of people have similar questions. There’s probably even more questions. So if you’re listening and you’ve got questions, drop a comment below and maybe we can help you get some answers to those questions. Or check out the BiggerPockets forums and make a post in there and there will be tons of investors who can help you with some of these ideas. Andreas, is there a way people can find you if they want to learn more about co-living or just learn more about you in general?

Andres:
Yes. My name is Andres Martinez, REI on YouTube and Instagram. I have a lot of free content on YouTube. So for people who are curious and want to hear more about the actual Colibean, you can go in there. If you want to message me, you can find me on Instagram, Andres Martinez REI. And also I have a school group now that is free to join. We meet once a week and I hold two or three hour calls for people to come ask me because my inbox is full of the same questions over and over and over. And it’s not that I don’t want to answer, but I don’t have time. So if you want to get free game, I host a call once a week, come in, ask me. I’m live for two or three hours. And then after that, go home.

Henry:
Awesome. Thank you so much, Andreas. Thank you for sharing your journey. Thank you for the lessons and being open and honest with us. And thank you so much to the BiggerPockets community for listening. We’ll see everybody on the next episode of BiggerPockets. Thanks

Help us reach new listeners on iTunes by leaving us a rating and review! It takes just 30 seconds and instructions can be found here. Thanks! We really appreciate it!

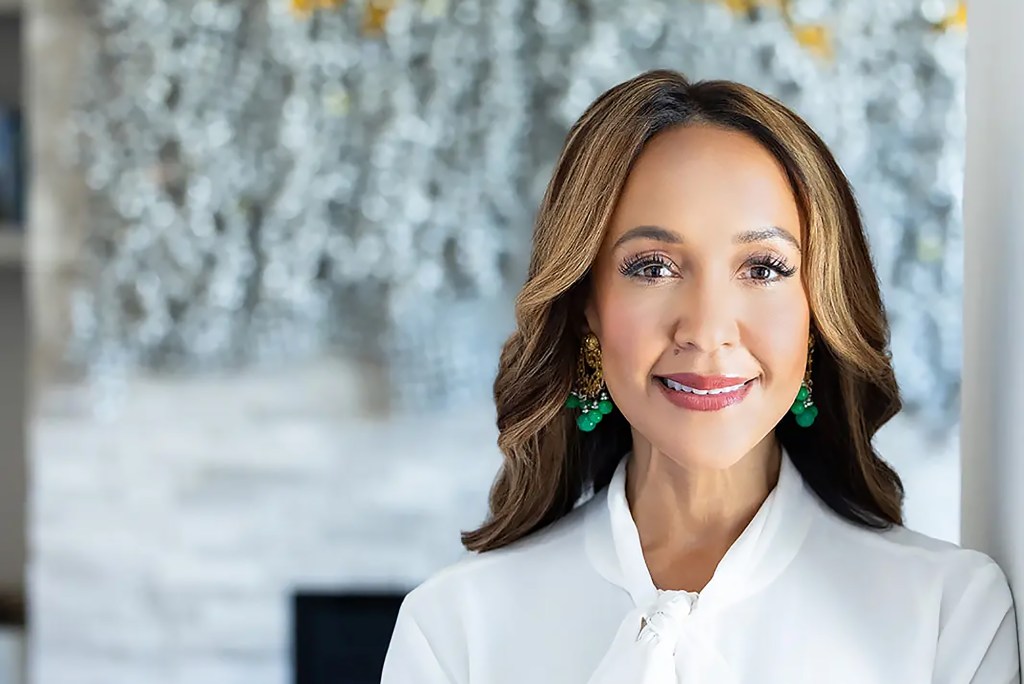
Interested in learning more about today’s sponsors or becoming a BiggerPockets partner yourself? Email [email protected].


Source link

From Waiting Tables to $13,000+/Month in Just 3 Years (Thanks to Rentals) Read More »

How George Vrban built a reverse pipeline at Movement Mortgage

How George Vrban built a reverse pipeline at Movement Mortgage


How George Vrban built a reverse pipeline at Movement Mortgage


What’s New?

Updated 32 minutes ago

manage feed


Source link

How George Vrban built a reverse pipeline at Movement Mortgage Read More »