Larry Ellison Quietly Spent  Million on Homes for His Staff

Larry Ellison Quietly Spent $10 Million on Homes for His Staff


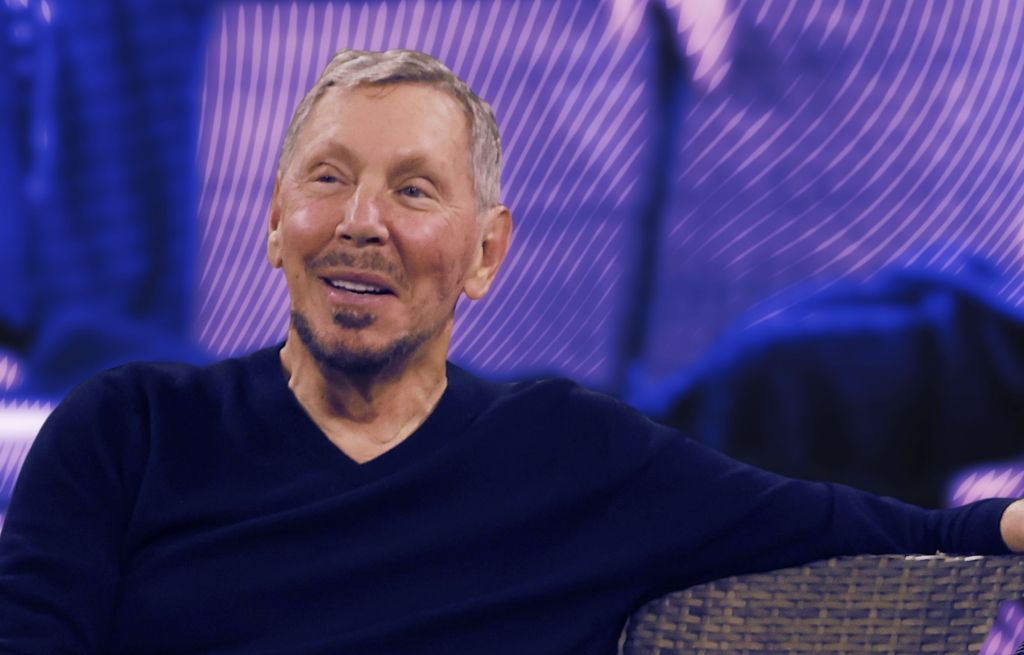
Billionaire Larry Ellison, 82, has a $173 million oceanfront compound in Manalapan, Florida. About 30 minutes away, he owns eight more homes. They’re all for his family’s staff, including tutors for some of the five young children he shares with his wife, Jolin.

The purchase was shrouded in secrecy. In 2023, an LLC bought the houses in Palm Meadows Estates, a gated community in Boynton Beach, for almost $10 million, The Wall Street Journal reports. Nosy neighbors guessed it was Mark Zuckerberg or Elon Musk. Even the local agent who helped line up the deals didn’t know who the mystery buyer was until Ellison arrived to tour the homes, flanked by bodyguards.

The real estate grab is part of a larger trend among the ultrarich to buy up housing for their employees. It helps them recruit top talent in pricey markets while keeping staff close enough to help, far enough to stay out of the way. “Investing in lodging can be a very smart decision,” said Peter Mahler of Mahler Private Staffing.


Source link

Larry Ellison Quietly Spent $10 Million on Homes for His Staff Read More »

Company Helps People Find Over 0M Hidden at Home: Unvault

Company Helps People Find Over $150M Hidden at Home: Unvault


Key Takeaways

  • After graduating with her MBA, Singhvi wanted to tap into a $750 billion business opportunity.
  • She co-founded Unvault, which allows users to track the value of their jewelry and sell it, in 2025.
  • Now, she looks forward to listening to her customers and introducing more in-demand features.

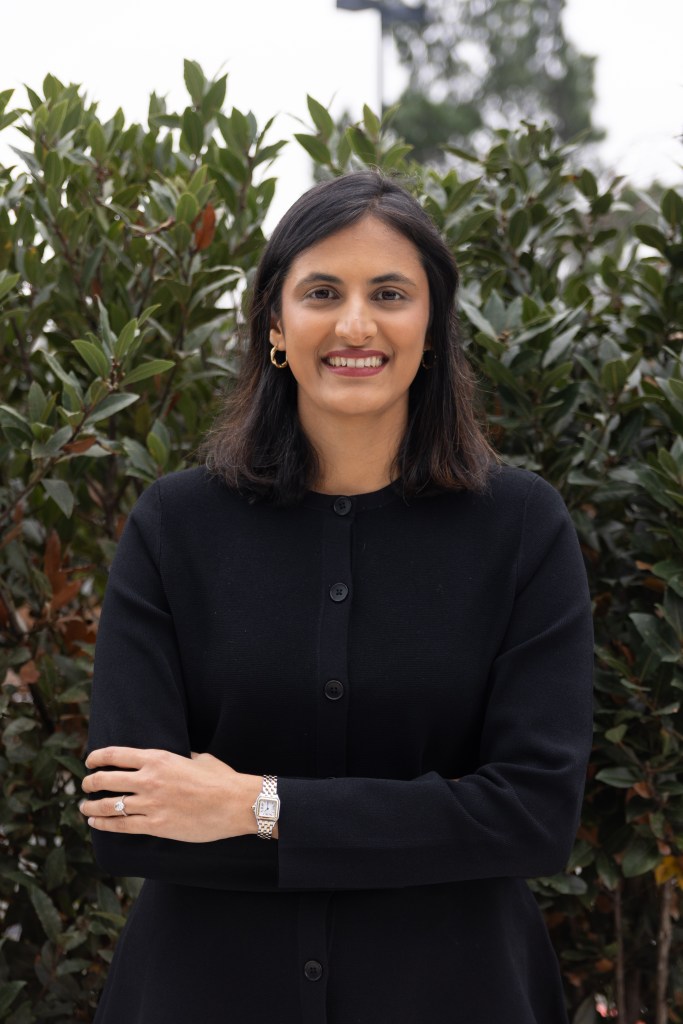
In India’s gemstone hub Jaipur, where Nidhi Singhvi grew up, gold jewelry is a family heirloom passed through generations, and it’s always considered when calculating someone’s net worth, she tells Entrepreneur. 

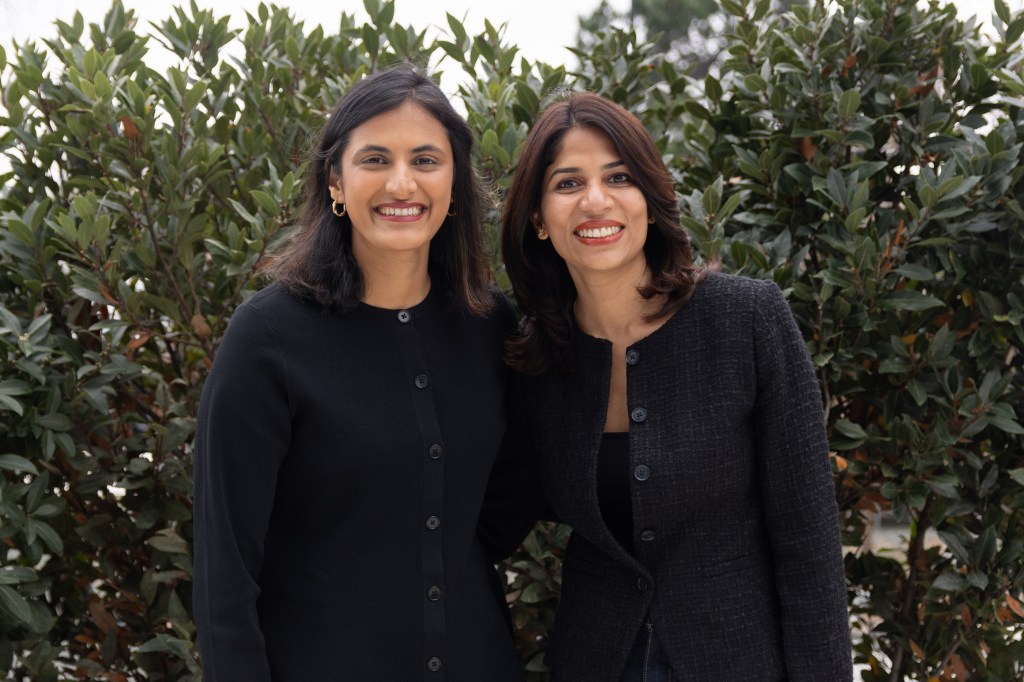
Image Credit: Courtesy of Unvault. Co-founders Nidhi Singhvi, left, and Navya Reddy, right.

However, when Singhvi moved to the U.S. about 14 years ago, she noticed a very different attitude toward the asset. 

“ Jewelry was always done stupidly,” Singhvi says. “It’s so marked up when you buy it, and if you want to sell it, like a broken chain or earring, your infrastructure is a pawn shop or a local jeweler.”

The wheels were turning as Singhvi graduated from The Wharton School with her MBA and launched her career. She focused on currency investing at a hedge fund, then built an options trading desk at a crypto brokerage. 

But Singhvi’s interest in the jewelry business never waned. “Gold is the OG asset class,” she says.

So, in 2024, she co-founded Sonalore, a company offering 18-karat gold jewelry with a lifetime buyback guarantee, with fellow Wharton graduate Navya Reddy. 

But it wasn’t long before Sonalore’s customers came back with a frequent request: They already owned a lot of jewelry, but they didn’t know how much it was worth — could Singhvi and Reddy help with that? 

“The way the customers pushed us was the revelation there,” Singhvi says. “They know it’s an investment. Ask any woman. She treats her jewelry differently than everything else. But what’s the value of it? For an asset to be a true asset, you need to know the value of it.”

Image Credit: Unvault

Co-founding Unvault to unlock $750 billion in assets

Singhvi and Reddy immediately pivoted to meet customer demand. The co-founders launched Unvault, a financial platform for personal gold, the “$750 billion asset class hiding in plain sight,” in Palo Alto, California in June 2025.

By October of that year, Singhvi and Reddy had leveraged AI to build their platform’s first valuation app. 

Not having raised money at the time was a significant advantage, as it motivated them to become AI natives and “use everything that was available on the AI front,” Singhvi notes. 

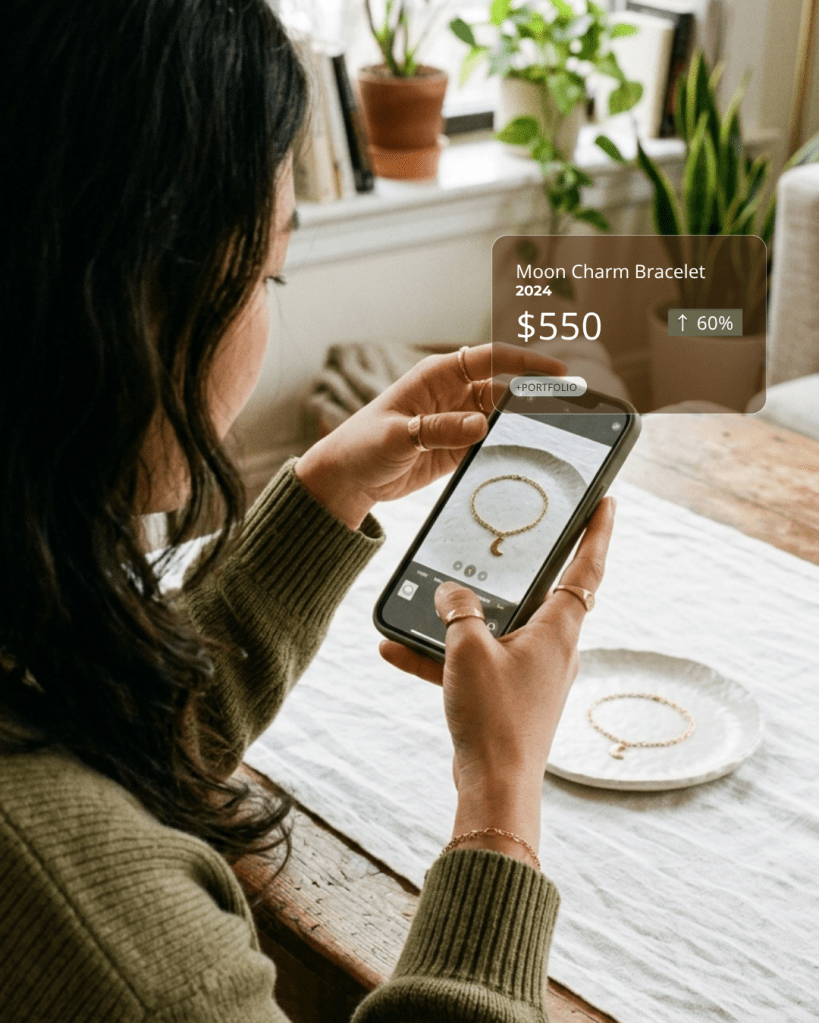
Unvault’s app took photos of customers’ jewelry and used volumetric data to estimate value. 

“We used all our training from being in jewelry for a year already to make that assessment better,” Singhvi explains. “Even though at that time we were using frontier [AI] models, we still used our layer of understanding of jewelry to give better results. And that took off.” 

Customer requests lead to the option to sell jewelery

Customers soon expressed a desire to sell their jewelry on the platform, so Unvault added the option within the same month of launch. The company opened a PO box to receive the items in Palo Alto. “People were shipping thousands of dollars of jewelry to us,” Singhvi recalls. And she would drive there herself to pick the pieces up. 

“We built Unvault for knowing the value and for tracking the value,” Singhvi says. “But the selling was a use case that customers gave it.” 

Fostering transparency has been key within that selling component too, Singhvi notes. Unvault provides video throughout the whole process to keep customers informed at every step, from opening the box of jewelry to testing gold in the X-ray machine. 

“So it will tell you exactly, it’s 17.34-karat gold,” Singhvi says. “Then we will give you a complete breakdown. So it’s not one number for a bunch of your jewelry items. It’ll be a number for every single item, and then the fees are broken down as well.” 

Image Credit: Unvault

Navigating Silicon Valley investors who want $1 trillion

Despite the early customer interest, when it came time to raise money from Silicon Valley investors, the co-founders faced some pushback. 

“ Everyone wants to back a trillion-dollar company,” Singhvi says. “They want to back Anthropic, and I understand it. If I am making that decision, I want to do that as well. So there’s definitely some of that. They’re like, ‘Oh, gold jewelry, can you be $1 trillion?’”

For example, one investor told Singhvi that women don’t wear jewelry. He explained that his wife just wears a few pieces: earrings, a ring and a bracelet. 

“By the way, that’s a few thousand dollars right there,” Singhvi says. “But women do have jewelry. Jewelry predates agriculture. It has taken a lot of different forms, but there is an industry that is working, and you are a participant in it whether you like it or not.” 

The good news, according to Singhvi? As long as there’s a customer to prove the market, it’s only a matter of time before investors respond. Unvault had that customer from the start  — asking the question that led to the company’s very existence.  

“VCs are very good at [smelling] customer traction,” Singhvi says. “Everyone that partnered with us [did so] once we started getting customer traction, once they started seeing that curve go up.”

Image Credit: Unvault

Unvault saw its first $1 million of assets tracked in 27 days, then crossed the $2 million milestone in five. By the time the company began fundraising, it boasted $5 million of assets logged. 

Unvault most recently raised early-stage capital in June 2026. The amount hasn’t yet been disclosed.

To date, the company’s helped users unlock more than $150 million in assets.

The importance of customer feedback at every stage

Singhvi and Reddy have continued to solicit customer feedback wherever possible (they’ve even placed golden eggs in Dolores Park to catch attention and collect opinions), cognizant of just how valuable it’s been at every stage of Unvault’s journey. 

Not only does it boost their confidence in their offering, but it keeps them agile enough to fulfill the next customer request. 

Now, those customers are asking for the option to track inherited assets and expand beyond jewelry to include items like silverware or other collectibles. Older generations will pass down $93 trillion in assets to their heirs in the next two decades, Bloomberg reported.

Singhvi looks forward to building out Unvault’s inheritance feature and continuing to listen to its customers. And she suggests any entrepreneur who wants to be successful do the same.  

“ Whatever way you can get customer feedback, and customer feedback at some scale, is great,” Singhvi says. “That will just help building the product, help you be a better founder, and then also help you raise money eventually.”

Key Takeaways

  • After graduating with her MBA, Singhvi wanted to tap into a $750 billion business opportunity.
  • She co-founded Unvault, which allows users to track the value of their jewelry and sell it, in 2025.
  • Now, she looks forward to listening to her customers and introducing more in-demand features.

In India’s gemstone hub Jaipur, where Nidhi Singhvi grew up, gold jewelry is a family heirloom passed through generations, and it’s always considered when calculating someone’s net worth, she tells Entrepreneur. 

Image Credit: Courtesy of Unvault. Co-founders Nidhi Singhvi, left, and Navya Reddy, right.

However, when Singhvi moved to the U.S. about 14 years ago, she noticed a very different attitude toward the asset. 

“ Jewelry was always done stupidly,” Singhvi says. “It’s so marked up when you buy it, and if you want to sell it, like a broken chain or earring, your infrastructure is a pawn shop or a local jeweler.”


Source link

Company Helps People Find Over $150M Hidden at Home: Unvault Read More »

The Skill Behind Every Successful Career Pivot — and How to Build It

The Skill Behind Every Successful Career Pivot — and How to Build It


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Practice, don’t just read. Certification exams test judgment in realistic scenarios, so work through every practice question you can find and study the ones you get wrong.
  • Put it on your calendar. “No time” is a decision, not a scheduling problem. Block a specific, recurring time to study; even 20 focused minutes a day adds up

If there’s one thing I know how to do, it’s fail. It took me three tries to pass a career-defining certification, and only then did I understand that failing was part of how I’d learn the right way.

The material for my Certified in Planning and Inventory Management credential was right in front of me. The problem wasn’t effort; it was method. The flashcard-to-recall routine that works for so many people simply wasn’t helping my brain hold on to the information. That set me on a path to relearn how to learn, and what I found has shaped everything since, from earning corporate credentials to building Pocket Prep from scratch.

It comes down to a foundation and three habits: a reason to care, repeated exposure, and application.

Start with the foundation

If you want to pivot your career or reskill fast, the tactics matter less than the base they sit on. For me, two “parent skills” made every new subject easier to pick up: organization and communication.

My guiding question is always the same: what’s the 20% of effort that drives 80% of the results? Organization and communication are that 20%. Get them right first, and everything you learn afterward compounds faster.

Find a reason to care

Most of us were taught to learn the same way. We’re all born unique, then shuffled into classrooms and expected to conform: sit still, be quiet, learn what you’re told. I was one of many undiagnosed ADHD kids who would rather stare out the window or crack jokes than follow along in the textbook.

What was missing was a personal layer, something that made the material click. For me, that turned out to be stories: the “why” behind the facts.

In college, I studied a hypothetical case about a factory worker who finds bugs in a vat of ice cream. He’s told the contamination level is legally acceptable and instructed to keep processing the batch. Decades later, I can still picture his guilt as he imagines kids happily eating that ice cream on a summer day.

I don’t remember most of what I memorized that semester. I remember that. Information sticks when you have a reason to care about it, not just a reason to memorize it.

Learn, forget, learn, remember

My aikido instructor used to say, “Learn, forget, learn, forge, learn, remember.” She was consoling me when I couldn’t recall the next move, but she was also describing how memory works. You learn a concept, forget most of it, then rediscover it in an “oh, yeah” moment. Each return makes it easier to recall the next time.

That idea is why mobile became so central to our learning tools. Before smartphones, studying had to be deliberate: pick up the book, mark the chapter, make the flashcards. Now people study in the margins of their day, waiting in line for coffee, riding the bus, sitting in the school pickup line. Five to ten minutes, maybe seven to ten practice questions at a time.

That’s not a compromise. Short, repeated exposure beats a long cramming session, because forgetting and re-encountering material is how the brain strengthens recall. It’s also what makes a flow state possible when the stakes are high and the clock is running.

Prove it by applying it

Here’s the hard truth: passing an exam or finishing a course proves you consumed the right knowledge. It doesn’t change your title. Applying it does.

Even if you pursued a certification to change your professional identity, your boss and your customers won’t care that you passed. A credential sets you up to become a better professional; it doesn’t make you one. What people notice is what you do with it.

So ask yourself: after I learn this, who will notice a difference in how I work? If the answer is no one, you were consuming, not learning.

Have 20 minutes? Start here.

Carving out 20 minutes a day is already a win. Use it to get curious about career paths and skills you didn’t know would interest you.

  • Explore before you commit. Don’t enroll in or buy anything yet. Use small pockets of time to explore, not grind.
  • Understand the destination first. Learn what the new role or skill actually requires, and decide whether it’s worth it to you before committing to the process.
  • Check your foundation. Ask honestly whether your organization and communication skills can support learning fast.
  • Protect “sacred time.” Keep one unscheduled block that’s yours no matter what the calendar says. I wake up at 6:30 every day, weekends included (my body can’t tell the difference), to reflect, prioritize, and read, with plenty of coffee.

Then confront the three stories that stall most mid-career pivots:

  • “I don’t have time.” You have 20 minutes. That’s enough to start.
  • “I don’t know if I can.” That’s what exploring is for. You don’t have to know yet.
  • “I don’t know if it’s worth it.” That’s why you study the destination before committing to the path.

There’s no wrong path. But if you keep telling yourself any of these stories, you’ll prove yourself right.

The real advantage: knowing how you learn

Career pivots used to be a once-a-decade decision. Now they’re a recurring requirement, especially for founders adapting to market shifts every quarter.

The entrepreneurs who move fastest won’t be the ones who know the most. They’ll be the ones who’ve built a system for learning under pressure: a strong foundation of organization and communication, a reason to care about what they’re studying, and the discipline to return to it in short bursts instead of waiting for a free weekend that never comes.

While AI is a factor in this shift, it’s not replacing the need to learn. It’s adding an incredible personalization layer on how to do it, making it easier to find the right pace or entry point into something new. That access won’t stay this cheap or this simple forever – learn how you learn, while the tools to accelerate it still are.

Key Takeaways

  • Practice, don’t just read. Certification exams test judgment in realistic scenarios, so work through every practice question you can find and study the ones you get wrong.
  • Put it on your calendar. “No time” is a decision, not a scheduling problem. Block a specific, recurring time to study; even 20 focused minutes a day adds up

If there’s one thing I know how to do, it’s fail. It took me three tries to pass a career-defining certification, and only then did I understand that failing was part of how I’d learn the right way.

The material for my Certified in Planning and Inventory Management credential was right in front of me. The problem wasn’t effort; it was method. The flashcard-to-recall routine that works for so many people simply wasn’t helping my brain hold on to the information. That set me on a path to relearn how to learn, and what I found has shaped everything since, from earning corporate credentials to building Pocket Prep from scratch.

It comes down to a foundation and three habits: a reason to care, repeated exposure, and application.


Source link

The Skill Behind Every Successful Career Pivot — and How to Build It Read More »

How We Built a .6B Company in an Uncharted Industry

How We Built a $3.6B Company in an Uncharted Industry


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Balance experimentation with the reliability of your core offering, and establish a strong patenting system early on.
  • Build for compliance and perform know-your-customer checks from the get-go, and push the whole industry toward self-regulation.
  • Understand that fiscal discipline beats early funding. Being fiscally responsible allows you to raise funds only when you can do so on your own terms.

A few months ago, Oxylabs landed a $130 million investment from Warburg Pincus, pushing our valuation to $3.6 billion — the highest ever recorded in the public web data sector, and our first outside capital in more than a decade of doing business.

Back in 2015, when Oxylabs was launched, few had heard about automated web data access as a separate industry, and even fewer understood the underlying technology. There was no rulebook to follow, no regulatory framework that clearly applied and no seasoned executives to consult on intractable problems. 

Technology develops fast, and today there are plenty of similar avenues for innovation and companies carving out their own niche. So here are simple but hard-won lessons for everyone trying to build a category-defining company in an emerging, stormy industry.

Balance experimentation with the reliability of the core offering

Succeeding in a new industry requires a two-fold approach — frequent, bold experimentation and a dependable core product. To figure out what works, you need to be willing to try many different things, many of which will fail. But you can only afford some turbulence and freedom to experiment if the value of your core offering is unshakeable.

Customers will understand a few misfires, especially if you are building on top of novel solutions. But competitors can pop up just as quickly as client patience runs out when workflows or data pipelines break and cause significant downtime.

Establish a strong patenting system early

Experimenting and innovating is something you must do to claim your place in an emerging industry. Just as important is setting up a patenting system as early as possible. Next to your ingenious engineers, you need capable lawyers who will make their work worth that much more. Proprietary knowledge that no one cares about today will be priceless when everyone else starts to notice the opportunity in your sector. 

Beyond the legal protection, a proactive approach to patents forces your team to articulate exactly what’s proprietary and defensible about their approach in the first place. That clarity, in turn, helps you build a strategy to pre-empt — or at least soften — any disputes that arise later on.

Build for compliance and KYC before anyone’s checking

It might be tempting to treat the absence of clear regulation as an absence of responsibility. Prioritizing growth, revenue and competitive edge makes sense for an emerging company in an unclaimed industry. But if you are in for the long run, act like it from the get-go. Rigorous know-your-customer checks, use-case vetting and data protection should become part of your company’s culture from day one, even when it means turning away opportunities or moving slower than less scrupulous competitors. 

Trust built this way compounds over time. It gives credibility to attract investors and a solid backbone to pass due diligence. Importantly, if you are in an industry no one understands, and many assume it is shady, audits or regulatory inquiries will come without you doing anything wrong. Prejudice is only overcome by proof of responsible conduct. 

Push the whole industry toward self-regulation

A company can only outrun its industry’s reputation for so long. When shady players shape how regulators, the media and the public view a new category, every honest business in that category ends up paying for it. That’s why it often falls to the more responsible players to work together and lead the way. Joining or starting industry associations that set and promote common standards, and that certify companies willing to be held to them, is something companies can do without waiting for outside regulation.

In the web data industry, no such body existed until a group of companies came together to launch the Ethical Web Data Collection Initiative. It’s hard to build trust in your own business if the entire category is seen as untrustworthy, so investing in your industry’s credibility is one of the most impactful things a leader in the field can do.

Fiscal discipline beats early funding

Growing at a pace your infrastructure and compliance standards can support takes real discipline. Enticing offers might come early on. Capital investment early on gives you a head start, resources and time in the sun. But it can also become a burden.

Being fiscally responsible lets you raise funds only when you can do so on your own terms. Similarly, while acquiring a competitor has the appeal of a power move, it doesn’t necessarily make sense in current market conditions. Don’t buy just to demonstrate growth and attract investor attention. Buy to expand your market presence and product offering, and the investors will come to you.

Summing up

Building without a map is hard — failure lurks around any corner, and success is hard to envision, let alone reach. But being among the first also means you have plenty of room where you can build. And you get to help set the terms for how your industry operates and in what light it is judged. That kind of foundational work pays off down the line.

Key Takeaways

  • Balance experimentation with the reliability of your core offering, and establish a strong patenting system early on.
  • Build for compliance and perform know-your-customer checks from the get-go, and push the whole industry toward self-regulation.
  • Understand that fiscal discipline beats early funding. Being fiscally responsible allows you to raise funds only when you can do so on your own terms.

A few months ago, Oxylabs landed a $130 million investment from Warburg Pincus, pushing our valuation to $3.6 billion — the highest ever recorded in the public web data sector, and our first outside capital in more than a decade of doing business.

Back in 2015, when Oxylabs was launched, few had heard about automated web data access as a separate industry, and even fewer understood the underlying technology. There was no rulebook to follow, no regulatory framework that clearly applied and no seasoned executives to consult on intractable problems. 

Technology develops fast, and today there are plenty of similar avenues for innovation and companies carving out their own niche. So here are simple but hard-won lessons for everyone trying to build a category-defining company in an emerging, stormy industry.


Source link

How We Built a $3.6B Company in an Uncharted Industry Read More »

How Much Money Each Generation Is Spending on Fun, Hobbies

How Much Money Each Generation Is Spending on Fun, Hobbies


Key Takeaways

  • A Bank of America Institute study digs into hobby spending across generations.
  • Older millennials invest the most in hobbies, potentially covering costs for young children.
  • Some people turn their fun hobbies into lucrative business opportunities.

How much does it cost to have fun? That depends on whom you ask — and how old they are. 

Nowadays, more Americans than two decades ago rate their hobbies or recreational activities as “extremely” or “very important” to them, per a recent Gallup poll.

But how much people spend on their preferred hobbies varies significantly across generations. 

A new analysis from Bank of America Institute, which examined credit card data across a three-month moving average to August 2026, explores how Gen Z, millennial, Gen X and Baby Boomer consumers participate in the hobby economy.

Hobby spending rose 7.9% and suggests a rise in “funflation”

Hobby spending rose 7.9% year over year in August, but at more than double the rate of transaction growth, suggesting an uptick of “funflation” hobbies, according to the report.

“Funflation,” a term coined by economists, refers to the rising price of entertainment and experiences that people are willing to pay to make up for lost time during the pandemic. 

On average, Boomers spend more than $200 per person on their hobbies monthly, the study shows. 

Boomers’ hobby spending is right in line with that of Gen X, but notably higher than that of Gen Z and younger millennials, who typically spend about $100 and just over $140 on their hobbies each month, respectively. 

However, older millennials take the top spot for monthly hobby spending, edging past Gen X and Boomers at nearly $220 per person. Researchers believe this may be because older millennials are most likely to be spending on their kids’ hobbies in addition to their own. 

Investing in your hobby could lead to a business opportunity

What’s more, for some people, hobbies evolve from a fun way to pass the time into lucrative business opportunities. 

During the pandemic, nearly 60% of Americans picked up a new hobby, and about half of them turned it into a side hustle to bring in extra cash, according to a survey from LendingTree. 

Earlier this year, Anna Hudick told Entrepreneur about how she turned a jewelry-making hobby into a business at age 58 after retiring from an engineering career. 

Today, Hudick sells her jewelry designs and teaches craft classes, priced between $65 and $75 per person, to introduce the hobby to more people. 

“They’re coming in after work, stressed, and they have two hours where they aren’t tied to their phone or email,” Hudick said. “They just relax. Then by the time they’re done, they’re so happy with what they’ve made. It’s really fulfilling.”

Key Takeaways

  • A Bank of America Institute study digs into hobby spending across generations.
  • Older millennials invest the most in hobbies, potentially covering costs for young children.
  • Some people turn their fun hobbies into lucrative business opportunities.

How much does it cost to have fun? That depends on whom you ask — and how old they are. 

Nowadays, more Americans than two decades ago rate their hobbies or recreational activities as “extremely” or “very important” to them, per a recent Gallup poll.

But how much people spend on their preferred hobbies varies significantly across generations. 


Source link

How Much Money Each Generation Is Spending on Fun, Hobbies Read More »

You Don’t Need a Big Company’s Budget to Borrow Its Best Systems. Here’s How.

You Don’t Need a Big Company’s Budget to Borrow Its Best Systems. Here’s How.


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Instead of studying founders’ habits, study the communication, accountability and process systems that make successful companies’ results repeatable.
  • When you admire a company, ask what behavior it encourages, what system reinforces it and how you could build and measure a smaller version in your own business.

At some point, every business owner has looked at a successful company and thought, “I wish I had thought of that.” Maybe it’s Salesforce. Maybe it’s Costco. Maybe it’s Patagonia. Maybe it’s a competitor that seems to have figured something out before everyone else.

The problem isn’t admiration. The problem is where most entrepreneurs focus their attention. We study founders. We listen to podcasts. We read leadership books. We analyze personalities, habits and morning routines. What we don’t study nearly enough are the systems that made those companies successful in the first place. That’s where the real opportunity is.

Several years ago, one of our larger business partners launched a philanthropy initiative that caught my attention. Community involvement wasn’t an occasional activity. It was built into the company’s culture, and it was reinforced by a measurable process. My first reaction was the same one many small business owners have when they see something impressive: “That’s great, but we’re not them.” They were a much larger organization, with resources, budgets and staff we didn’t have. Replicating their program exactly wasn’t realistic. But then I realized I was asking the wrong question. Instead of asking whether we could copy the program, I started asking why it worked.

The answer was simple: It encouraged employees to engage with their communities and consistently rewarded that behavior. We didn’t need the same structure to accomplish the same goal, so we created our own version. Today, we track volunteer hours and reward team members for community involvement. The program looks different because our business is different, but the principle is the same. It’s also a smart investment. A 2024 Deloitte survey of 1,000 U.S. office professionals found that 87% consider workplace volunteer opportunities a factor in deciding whether to stay with their current employer or pursue a new one.

That experience taught me something many entrepreneurs miss. The companies you admire aren’t valuable because of what they do. They’re valuable because of the systems that make their results repeatable.

Most entrepreneurs study the wrong things

We’ve turned many founders into celebrities. We study Steve Jobs’ black turtleneck. We analyze Elon Musk’s work habits. We obsess over leadership styles and personality traits.

Meanwhile, the things that actually drive performance get far less attention: communication systems, accountability structures, documented processes and performance standards. None of those topics makes for an exciting keynote speech. Yet they’re often the reason one company consistently outperforms another. The next time you admire a business, stop asking what makes the founder special. Ask what allows ordinary people inside that company to perform at a high level, again and again.

That’s usually where the lesson lives.

Steal clear communication

One of the biggest differences between large organizations and small businesses is communication. Large companies can’t afford to keep information inside the owner’s head. They answer to shareholders, boards, investors and thousands of employees. Priorities have to be communicated. Expectations have to be documented. Goals have to be clarified.

Small businesses often work differently. The owner knows where the company is headed and assumes everyone else does too. The result is predictable: Team members fill in the gaps with their own assumptions, work gets misaligned and leaders get frustrated that employees aren’t executing a vision that was never clearly communicated.

Here’s a simple test. Ask your leadership team to write down the company’s top three priorities for the next 12 months. The results may surprise you. In a 2015 study of more than 250 companies published in Harvard Business Review, researchers found that only 55% of the middle managers they surveyed could name even one of their company’s top five priorities. And those were larger organizations with formal communication processes in place.

If everyone on your team gives a different answer, you don’t have a people problem. You have a communication problem. The companies we admire create clarity. Small businesses should do the same.

Steal standards, not personalities

It’s easy to admire leaders who make tough decisions, hold people accountable and maintain high expectations, and to assume their success comes down to personality. What often gets overlooked are the standards guiding those behaviors. The strongest organizations define what success looks like before performance becomes a problem. They set expectations, communicate priorities and coach people toward those standards. Most importantly, they address issues when those standards aren’t being met.

That kind of clarity is rarer than you might think. According to Gallup, just 47% of employees strongly agreed that they know what is expected of them at work as of mid-2025. Small business owners often struggle here because accountability can feel personal. You know your employees’ spouses. You know their children. You know what’s happening in their lives. That makes difficult conversations uncomfortable. But avoiding them creates confusion, not kindness.

You can be direct without being harsh. You can hold people accountable without being militant. The best organizations understand the difference.

Steal process discipline

Large companies create structure because they have to. They document workflows, establish procedures and define ownership. Small businesses often wait until they feel bigger to do those things. But structure is often what allows a company to grow in the first place.

If your team can’t answer these questions, there’s work to do: What are our top priorities? Who owns each one? How do we measure success? What process do we follow when problems arise? When those answers are unclear, people spend more time guessing than executing. The businesses we admire remove that uncertainty.

A simple exercise every entrepreneur should try

The next time you find yourself admiring a company, ask four questions:

  1. What behavior are they trying to encourage?
  2. What system reinforces that behavior?
  3. How could I build a smaller version inside my business?
  4. How would I measure whether it’s working?

Those questions shift your focus from admiration to implementation. You’re not going to become Patagonia or Salesforce, and the goal isn’t to become the next famous founder. The goal is to identify the systems that help great companies succeed and adapt them to fit your business.

The most valuable things to steal from successful companies are usually hidden behind the scenes.

Key Takeaways

  • Instead of studying founders’ habits, study the communication, accountability and process systems that make successful companies’ results repeatable.
  • When you admire a company, ask what behavior it encourages, what system reinforces it and how you could build and measure a smaller version in your own business.

At some point, every business owner has looked at a successful company and thought, “I wish I had thought of that.” Maybe it’s Salesforce. Maybe it’s Costco. Maybe it’s Patagonia. Maybe it’s a competitor that seems to have figured something out before everyone else.

The problem isn’t admiration. The problem is where most entrepreneurs focus their attention. We study founders. We listen to podcasts. We read leadership books. We analyze personalities, habits and morning routines. What we don’t study nearly enough are the systems that made those companies successful in the first place. That’s where the real opportunity is.

Several years ago, one of our larger business partners launched a philanthropy initiative that caught my attention. Community involvement wasn’t an occasional activity. It was built into the company’s culture, and it was reinforced by a measurable process. My first reaction was the same one many small business owners have when they see something impressive: “That’s great, but we’re not them.” They were a much larger organization, with resources, budgets and staff we didn’t have. Replicating their program exactly wasn’t realistic. But then I realized I was asking the wrong question. Instead of asking whether we could copy the program, I started asking why it worked.


Source link

You Don’t Need a Big Company’s Budget to Borrow Its Best Systems. Here’s How. Read More »

Unauthorized Pets in Rentals: What They Cost Landlords

Unauthorized Pets in Rentals: What They Cost Landlords


I want to tell you about a puppy.

It was a mixed-breed puppy, which is the dog version of a mystery box (you don’t know exactly what’s inside, and I’m not convinced the dog does either). It was not house-trained. It was also staying at one of my properties, and nobody told me.

Someone snuck it in, so I found out about the puppy around the same time I found out about everything it had done. Those are two things I typically prefer in reverse order. This one chewed through baseboards, ruined floors, and kept going until the bill hit about $7,000. On a rental cash-flowing $300 a month, that’s almost two years of cash flow eaten by a puppy (in the baseboards’ case, literally).

(Before anybody from the rescue world emails me: I’m building a dog-first hotel, and this is a pro-dog article. It’s also an anti-surprise article).

What bugs me is how avoidable most of it was. If that puppy had been disclosed and screened, we’d have known what was coming and planned for it.

Every landlord eventually meets their own version of this puppy, and $7,000 turned out to be the cheap version. The expensive versions come down to what your paperwork can prove, which, for an animal nobody told you about, isn’t much.

You’re Not the Only One Who Got Surprised

PetScreening surveyed 673 property managers and leasing pros for its 2026 State of Pets in Rental Housing report. Unauthorized pets came out as their top pet problem. 

The same report found that only 43% of renters say they have a pet, compared with 71% of U.S. households, according to the American Pet Products Association. That’s a 28-point gap. Either renters are less into pets than everybody else, or plenty of dogs are living off the books, which is the report’s theory too.

Usually, nobody’s running a con. Someone adopts a puppy in month seven and never thinks to call you. A girlfriend’s dog comes over for a weekend in February and is somehow still there at Easter.

The Bills Come Later

Insurance usually won’t touch pet damage to the unit. Standard renter’s policies exclude it, and no adjuster in America considers a puppy an act of God (except maybe Air Bud). Chewed baseboards and a carpet that smells like a kennel get filed under preventable wear. That leaves your security deposit doing a job plenty of landlords assume insurance is doing.

Bites are the bigger number. Insurers paid $1.86 billion on 28,450 dog-related injury claims in 2025, averaging $65,450 per claim, according to the Insurance Information Institute and State Farm. On that same $300-a-month cash-flowing rental, a single average claim eats up about 18 years of cash flow.

The tenant’s renter’s policy is supposed to pay for a bite first. Plenty exclude certain breeds or any dog with a history of bites, and it gets messier if the tenant never told their insurer either. If you didn’t know the dog existed, you never asked for proof of coverage. Your own landlord policy may have animal exclusions, too, and it’s better to find that now than in a denial letter.

Disputes come down to paperwork

I’ll use Texas as an example because that’s where my properties are. Once a tenant moves out and provides a forwarding address, Property Code 92.103 starts a 30-day clock for the deposit refund. Anything you keep needs a written, itemized list under 92.104, and normal wear and tear doesn’t count. 

If they sue, 92.109 puts the burden on you to prove the deductions were reasonable. Miss the 30 days and the law presumes bad faith. That clock does not care how busy your month was. A bad-faith finding costs $100 plus three times what you wrongly kept, plus the tenant’s attorney’s fees.

Say you keep $600 for floor damage, your list goes out on day 34, and a judge rules against you. Now you owe $1,900, plus a lawyer you never hired.

If the animal were never disclosed, you would have even less to work with. There’s no pet addendum or description of the animal, and nothing signed showing the tenant knew your rules on pet sitting or adopting mid-lease. “I’m pretty sure those scratches weren’t there” won’t carry much weight when the burden of proof is on you.

(Outside Texas? Your state has its own deadlines and penalties. Look them up before a move-out forces the issue.)

That neighbor email is Exhibit A

In Texas, owning the house doesn’t automatically make you responsible for a tenant’s dog. Liability usually turns on what you knew about the dog being dangerous and whether you did anything once you knew.

Now picture the neighbor’s email saying the tenant’s dog charged her kid at the mailbox again. That email is evidence you knew. You can’t unread it. Attorneys in bite cases love a written complaint like that, especially next to a lease rule nobody enforced.

Three Houses, Three Rulebooks

Nobody sets out to run three different pet policies. It happens one house at a time. 

  • House A has the good pet addendum and move-in photos. 
  • House B has a one-line “no pets” clause. 
  • House C is on a lease somebody downloaded in 2019. 

Each one looks fine on its own. Together, they read like a group project where the members never met.

That works until those leases have to back each other up in front of a judge or a fair housing investigator. They notice when similar situations got handled differently.

Assistance animals and ESA’s make this more urgent. HUD withdrew its assistance animal guidance in September 2025. A May 22, 2026, memo narrowed federal enforcement to animals individually trained for disability-related work or tasks. State laws didn’t change; residents can still sue on their own, and attorneys are telling landlords to be careful with denials. 

With the federal approach changing twice in eight months, this is not the place to freestyle. Have an attorney in your state review how you handle these requests.

One Pet Process for Every Door

The fix is boring: Run the same pet process on every property and keep the record. It’s free for housing providers, and more than 28,000 property management firms and communities use it. On a long-term rental, it looks like this:

  1. Everyone Goes Through It: That includes residents with no animals. Their profile is free, takes a few minutes, and has them acknowledge your rules on pet sitting, visiting pets, and getting a pet mid-lease. That’s the signature you’ll want when the weekend dog is still around at Easter.
  2. Every Animal Gets a File: Pet owners upload photos and vaccination records, then attest to your policies and their pet’s history, including bites. You get a FIDO Score, a paw rating of the pet’s housing risk built from more than 35 data points. It won’t make the decision for you, but it helps you make it the same way at every property.
  3. Assistance Animals and ESAs Get Their Own Lane: Requests go to PetScreening’s in-house review team, which verifies the documentation with the healthcare provider. Residents don’t pay a profile fee, and you’re not improvising on a legal question that’s still moving.
  4. Re-Up at Renewal: Have every resident refresh their profile every year. That’s how you meet the new puppy at renewal instead of at move-out.
  5. One Dashboard for Every Door: Every animal and signed policy lives in one place, and it integrates with property management software, including Buildium, Rent Manager, AppFolio, and Yardi. When the neighbor emails, you can pull up that dog’s file instead of guessing.

If a property manager runs your doors, try this: Pick three random units (not the three you know are fine) and ask for the animal record on each. If it takes more than a few minutes, that’s your gap.

Back to That Puppy

None of that $7,000 was the puppy’s fault. A rescue that isn’t house-trained yet is just being a puppy. The problem was that no one on our side knew it was there, so no one had a plan.

So yes, still pro-dog, still anti-surprise. Most residents with pets will do this right if you give them a clear, single process, and that costs way less than the surprise.

Get the animals on paper before you have a puppy that has an appetite for baseboards.


Source link

Unauthorized Pets in Rentals: What They Cost Landlords Read More »

The Reason Your Growth Tactics Probably Aren’t Working

The Reason Your Growth Tactics Probably Aren’t Working


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Growth metrics tell you what is happening, not necessarily why. They tell you where to look. But they don’t necessarily tell you what to fix.
  • The same growth problem can have completely different causes. You need to understand the cause before you can confidently choose the treatment.
  • Analytics can’t always tell you what was happening in a customer’s head when they made a decision. That is where customer interviews can help.
  • Look for the gap between what you expected customers to do and what they actually did. Then try to understand why that gap exists.

When growth slows, there is no shortage of advice about what to do next. Post more on LinkedIn. Invest in SEO. Run paid ads. Rewrite your homepage. Improve onboarding. Change your pricing. Launch a referral program. Hire a salesperson.

But they all have the same problem: They start with a solution before you understand the problem. 

If your company isn’t growing as quickly as you expected, something is preventing potential or existing customers from taking the actions you need them to take. The question is: Why?

Before deciding which growth tactic to try next, I would start there.

Growth metrics tell you what is happening, not necessarily why

Most companies have enough data to identify where their funnel isn’t performing.

You might know that only 2% of website visitors start a trial. You might know that 80% of those trials never become paying customers. Maybe your sales team loses half of its qualified opportunities. Or perhaps customers sign up but never adopt enough of the product to stick around.

Those numbers tell you something important. They tell you where to look. But they don’t necessarily tell you what to fix.

Imagine that 1,000 people visit your website every month, but only 10 request a demo. There are dozens of possible explanations. 

You might be attracting the wrong visitors. Your ideal customers might not immediately recognize that the product is for them. You might be describing a problem they don’t consider important. They might understand the value but not believe your claims. They might think the product is too expensive. They might not want a demo. Or they might simply have unanswered questions preventing them from taking the next step.

The metric is the same in every scenario: 1% visitor-to-demo conversion. But the appropriate solution is completely different. That is why jumping from a disappointing metric directly to a growth tactic can be so inefficient.

The same growth problem can have completely different causes

Consider another common SaaS problem: Lots of people start a free trial, but few become paying customers.

What should you do? A common recommendation might be to improve onboarding. That sounds reasonable. But first, consider some of the reasons people might not be converting.

Maybe your marketing attracts people who were never likely to buy. Maybe users sign up expecting a capability your product doesn’t have. Maybe they can’t figure out how to use the product. Maybe they understand how to use it but never experience enough value during the trial. Maybe they love the product but can’t get their team on board. Maybe they can’t justify the price. Or perhaps they simply aren’t ready to buy yet.

If the problem is usability, improving onboarding could work. If the problem is that you’re attracting the wrong people, it probably won’t. If the problem is missing functionality, a better nurture sequence probably won’t solve it either.

This is why I think of growth problems as discovery problems before they become execution problems.

You need to understand the cause before you can confidently choose the treatment.

Start with the customer behavior you need to change

Instead of beginning with “What should we try next?” start by identifying the behavior that isn’t happening.

For example:

  • Your target buyers see your ads but don’t click.
  • Website visitors don’t start trials.
  • Website visitors don’t book demos.
  • Trial users don’t become paying customers.
  • Demos don’t convert to qualified opportunities.
  • Qualified opportunities don’t close.
  • New customers don’t adopt important features.
  • Existing accounts don’t add more users.
  • Customers cancel.

These are much more useful starting points because they force you to focus on a specific customer behavior. Then ask a simple question: Why aren’t these customers doing what we expected them to do?

That changes the growth conversation. Instead of brainstorming tactics, you start by investigating causes. And one of the most useful ways to investigate those causes is to talk to the people who actually made the decisions.

Ask customers what happened

Analytics are incredibly useful for understanding behavior. They can show you where people drop off, which features they use, how often they return, which campaigns produce signups and how different customer segments behave.

But analytics can’t always tell you what was happening in someone’s head when they made a decision.

That is where customer interviews can help. Suppose you want to understand why trial users aren’t buying. Talk to people who recently completed a trial but didn’t convert.

Ask what originally caused them to look for a solution. Ask what they hoped your product would help them accomplish. Ask what they expected when they signed up. Walk through what happened during their trial. Find out what they liked, what confused them, what disappointed them and what ultimately prevented them from purchasing.

Don’t ask, “Would you have bought if our onboarding were better?” That introduces your hypothesis into their answer.

Instead, reconstruct what actually happened. The same approach works throughout the funnel.

If target buyers aren’t responding to your marketing, talk to people who resemble the audience you’re trying to reach and understand how they think about the problem you’re solving. If qualified prospects aren’t buying, interview lost opportunities and find out how they evaluated the decision.

If customers aren’t expanding, talk to accounts that considered adding users but didn’t. If customers are leaving, talk to people who recently canceled.

You’re looking for the gap between what you expected customers to do and what they actually did. Then you’re trying to understand why that gap exists.

Look for patterns, not individual requests

One customer interview shouldn’t determine your growth strategy.

Customers have individual preferences, circumstances and opinions. Someone might dislike your pricing model. Another might ask for a particular integration. Someone else might want a completely different feature.

The value comes from patterns. If six of eight lost prospects tell you they couldn’t confidently explain the product’s value to the person approving the purchase, you may have discovered a champion enablement problem. If trial users repeatedly tell you they signed up but didn’t know what they were supposed to accomplish first, you may have found an onboarding problem.

If customers who churn consistently tell you they stopped using the product months before canceling, you may have discovered an adoption problem that begins much earlier in the lifecycle. Those findings give you something much more useful than a list of growth ideas.

They give you evidence about which problem deserves to be solved and strong clues into how to solve it.

Then choose the tactic

This is where tactics become valuable. Once you have evidence about what is preventing customers from moving forward, you can decide what intervention is most likely to change their behavior.

  • Maybe the answer really is a new onboarding flow.
  • Maybe it’s different positioning.
  • Maybe you need stronger customer proof.
  • Maybe you need to change who you’re targeting.
  • Maybe sales needs better tools for helping a champion build internal consensus.
  • Maybe customers need more support during their first 30 days.
  • Maybe the product is missing something important.

You still have to make a judgment. Customer interviews won’t hand you a perfect growth plan, and qualitative research should usually be considered alongside funnel data, product analytics and other evidence.

But now your growth ideas are responding to something you have observed rather than something you have assumed. That is a very different way to make growth decisions.

Diagnose before you prescribe

There will always be another growth tactic to try. That’s part of what makes growing a company difficult. There are hundreds of things you could be doing at any moment, and many of them sound plausible.

The challenge is figuring out which problem is actually preventing growth and which action is most likely to address it. So the next time a funnel metric disappoints you, resist the temptation to immediately ask what tactic you should try.

  1. Start with the behavior.
  2. Identify the people who aren’t doing what you expected.
  3. Talk to them.
  4. Understand what happened.
  5. Look for patterns.

Then decide what to change. Because the fastest route to growth may not be trying more things. It may be understanding why the things you need customers to do aren’t happening in the first place.

Key Takeaways

  • Growth metrics tell you what is happening, not necessarily why. They tell you where to look. But they don’t necessarily tell you what to fix.
  • The same growth problem can have completely different causes. You need to understand the cause before you can confidently choose the treatment.
  • Analytics can’t always tell you what was happening in a customer’s head when they made a decision. That is where customer interviews can help.
  • Look for the gap between what you expected customers to do and what they actually did. Then try to understand why that gap exists.

When growth slows, there is no shortage of advice about what to do next. Post more on LinkedIn. Invest in SEO. Run paid ads. Rewrite your homepage. Improve onboarding. Change your pricing. Launch a referral program. Hire a salesperson.

But they all have the same problem: They start with a solution before you understand the problem. 

If your company isn’t growing as quickly as you expected, something is preventing potential or existing customers from taking the actions you need them to take. The question is: Why?


Source link

The Reason Your Growth Tactics Probably Aren’t Working Read More »

CFPB examiner sues bureau over race discrimination claims

CFPB examiner sues bureau over race discrimination claims


CFPB examiner sues bureau over race discrimination claims


What’s New?

Updated 2 minutes ago


Source link

CFPB examiner sues bureau over race discrimination claims Read More »

Your Pitch Opens the Door. These Operating Habits Earn My Investment.

Your Pitch Opens the Door. These Operating Habits Earn My Investment.


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Founders earn investor trust by running a weekly execution meeting, keeping a one-page plan and assigning a clear owner to every metric that matters.
  • Monthly investor updates that honestly share wins, misses and asks build credibility, because bad news rarely ruins a relationship but silence does.

Early-stage founders love to talk about vision. I get it. Vision is exciting, and it is often the reason a company exists in the first place. Still, when I sit across from a founder, I usually learn more from their operating habits than from their headline.

I have heard plenty of polished pitches over the years. The founders who earn my attention are usually the ones who show me a simple system for execution. They know what matters this week, who owns it, how progress gets tracked, and when the team will review it again. That may sound basic, yet basic wins more often than a grand speech.

My father taught me that lesson long before I worked in venture. He came from very little, built from scratch and expected the people around him to care deeply about the details. But one thing he said really stayed with me, and that’s if you expect other people to care about your company, you had better care first.

Founders who gloss over the details usually reveal something larger. They want the title of a founder more than the work of actually building. You can’t expect the investors to care more about your company than you. And that shows up in how you organize the details.

Care shows up in the calendar

One of the clearest signals of discipline is how a team runs its week. I want to see a recurring execution meeting with a fixed rhythm, a short agenda and real owners on every priority. A good weekly meeting does not need fancy software or a consultant. It needs structure. The best teams I meet can answer four questions quickly. What were the top priorities last week? What moved forward? What slipped? What matters most before the next meeting? If a founder cannot answer those questions with clarity, then the team is probably drifting.

I think about punctuality the same way. People love saying they arrived right on time, as if that proves seriousness. To me, arriving exactly on time often says the opposite. Life happens. Traffic happens. Tech issues happen. People who truly care usually build margin into the day. That mindset carries into company building. Great founders prepare before the meeting starts. They do not show up and decide what matters in real time.

Keep the weekly plan painfully simple

Founders often assume better execution means more process. Usually, it means less. Early teams rarely need layers of bureaucracy. They need one page.

I like a one-page weekly plan because it forces clarity. The company mission may be broad, yet the week should feel specific. List the three to five priorities that matter most. Name the owner beside each one. Add a target date or metric. Then review the same sheet at the next meeting.

That simple habit does two things. First, it exposes confusion early. Second, it makes accountability feel normal instead of personal. A missed priority no longer becomes a dramatic confrontation. It becomes a visible item the team can address, learn from and reset.

Too many founders confuse motion with traction. They stay busy, take meetings, answer messages and jump between fires. Then Friday arrives, and nobody can say what actually moved. A one-page plan gives the week a spine.

Metrics need owners, not admirers

Another thing I watch closely is how founders talk about metrics. Vague language tells me very little. I don’t want to hear that revenue is improving or the pipeline looks strong. I want to know who owns revenue, what the customer pipeline looks like, where deals are stalling and what number the team is trying to move next.

A young company does not need 50 dashboards. It needs a handful of numbers that matter and a person responsible for each one. Revenue, pipeline, customer conversations, burn, runway, hiring or product releases can all matter depending on stage. What matters most is ownership.

When no one owns a metric, everyone gets to admire it from a distance. That helps nobody. A founder should be able to say, “Sarah owns the pipeline. James owns product delivery. I own fundraising and key hires.” Clear ownership creates clear conversations.

Investor updates are a discipline tool

Many founders treat investor updates like a favor. I see them as an operating tool. A solid monthly update forces a founder to slow down, look at the business honestly, and decide what belongs in the headline, what belongs in the lowlight, and what support is needed next.

One of the better update formats I have seen is also one of the simplest. Share key metrics, cash in the bank, runway, major wins, major misses, asks and priorities for the next month. That is it.

I have also seen the other side, and it is painful. I have backed founders who chased the investment hard, then went silent after the investor made the deposit. In one case, I learned through LinkedIn that a founder had moved on to a new job while investors were still waiting for a clear update on the company. That kind of behavior kills trust fast. Bad news doesn’t ruin a relationship, but silence does.

Accountability works best when it feels normal

The strongest teams make accountability part of the culture before a crisis arrives. They revisit priorities every week. They schedule standing check-ins. They create a place where asking for help feels responsible rather than weak.

That matters because founders carry a lot. There will be weeks when the plan slips, the hire falls through, or the customer says no. A disciplined operating cadence gives the team a way to recover without panic. It turns execution into a repeatable practice.

If you are building an early company, start here. Set a weekly execution meeting. Build a one-page plan. Assign clear owners to the few metrics that matter most. Send a monthly investor update that tells the truth. Then repeat. Vision opens the door. Discipline keeps it open. Traction usually comes from founders who care enough to do the simple things every single week.

Key Takeaways

  • Founders earn investor trust by running a weekly execution meeting, keeping a one-page plan and assigning a clear owner to every metric that matters.
  • Monthly investor updates that honestly share wins, misses and asks build credibility, because bad news rarely ruins a relationship but silence does.

Early-stage founders love to talk about vision. I get it. Vision is exciting, and it is often the reason a company exists in the first place. Still, when I sit across from a founder, I usually learn more from their operating habits than from their headline.

I have heard plenty of polished pitches over the years. The founders who earn my attention are usually the ones who show me a simple system for execution. They know what matters this week, who owns it, how progress gets tracked, and when the team will review it again. That may sound basic, yet basic wins more often than a grand speech.

My father taught me that lesson long before I worked in venture. He came from very little, built from scratch and expected the people around him to care deeply about the details. But one thing he said really stayed with me, and that’s if you expect other people to care about your company, you had better care first.


Source link

Your Pitch Opens the Door. These Operating Habits Earn My Investment. Read More »