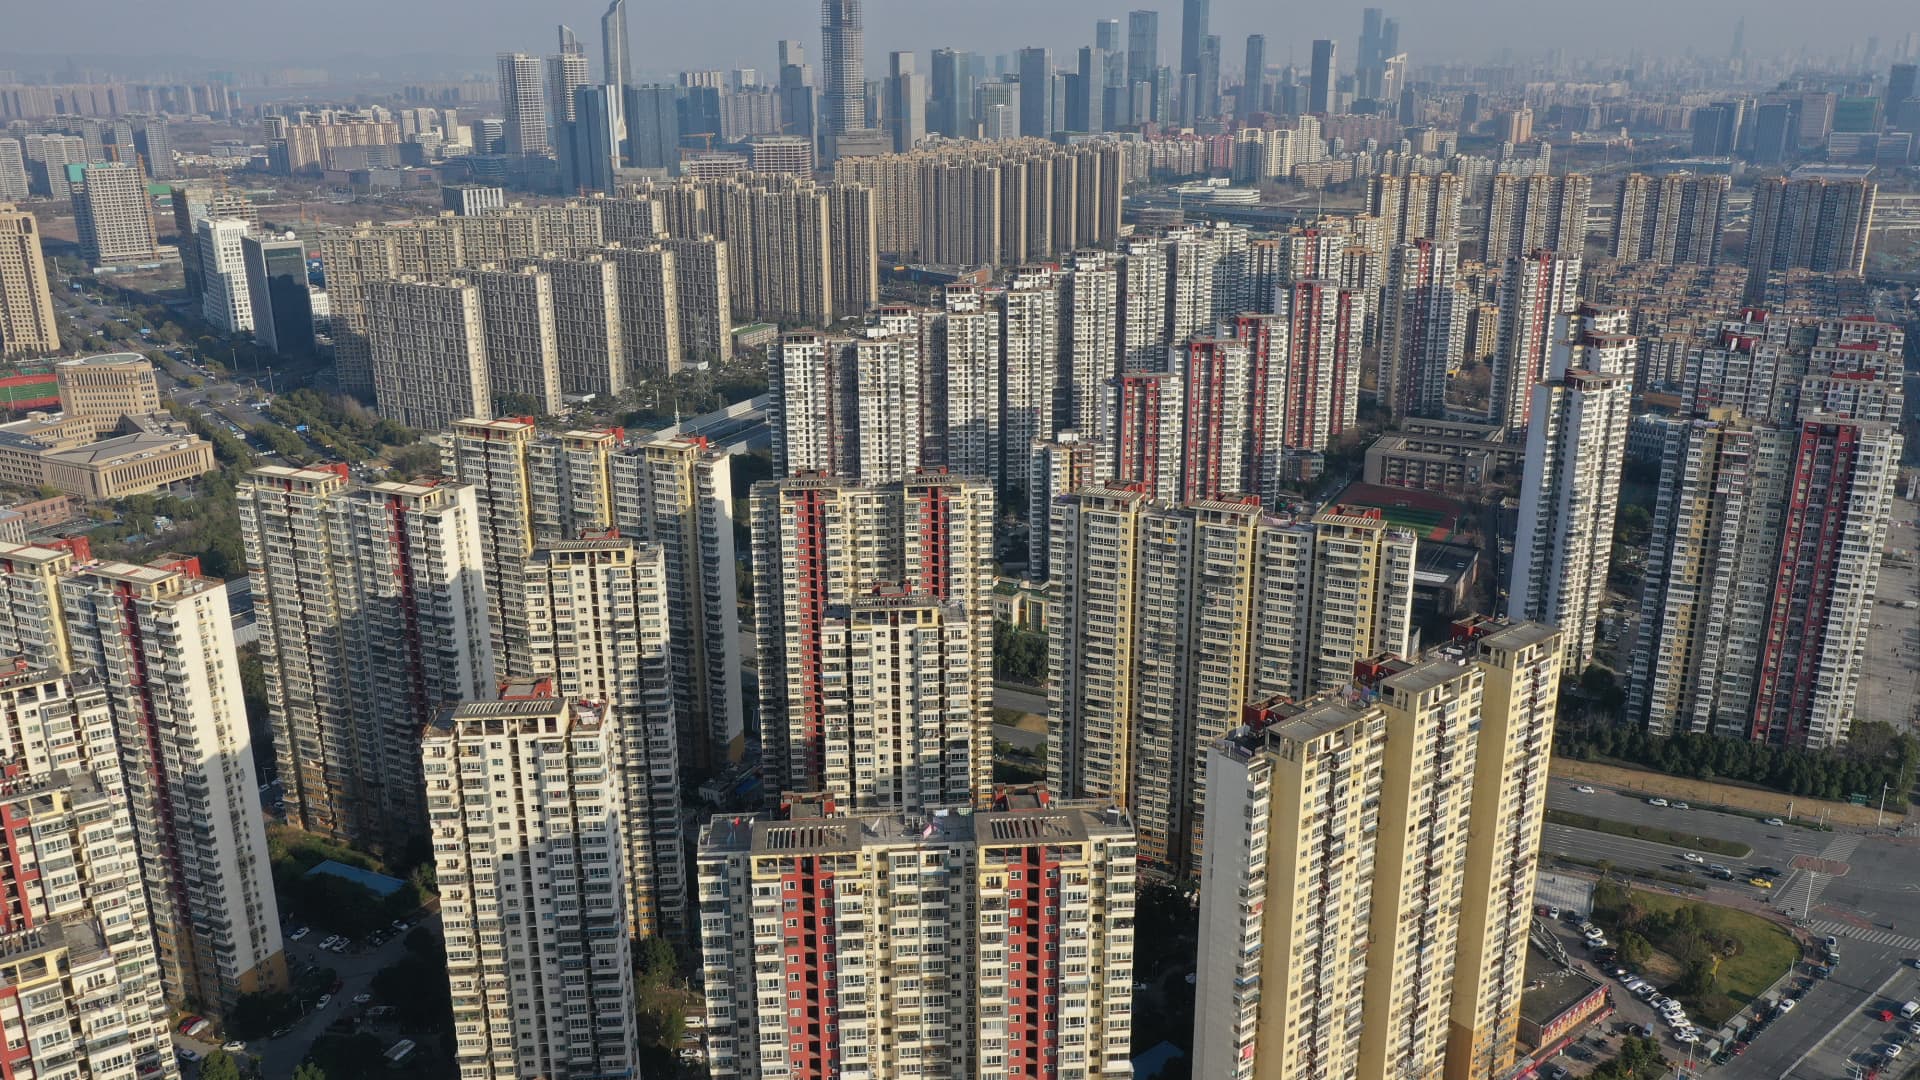
China’s real estate crisis isn’t over yet, IMF says

China’s real estate crisis isn’t over yet, IMF says


China’s real estate market has slumped in the last two years after Beijing cracked down on developers’ high reliance on debt for growth.

Future Publishing | Future Publishing | Getty Images

BEIJING — China needs to do more in order to fix its real estate problems, the International Monetary Fund said Friday.

The property market contributes to about a quarter of China’s GDP and has been a drag on growth, especially since Beijing cracked down on developers’ high reliance on debt in 2020.

Chinese authorities started to ease restrictions on financing for the sector over the last several months.

“Authorities’ recent policy measures are welcome, but in our view additional action will be needed in order to end the real estate crisis,” Thomas Helbling, deputy director in the IMF’s Asia Pacific Department, said in a briefing.

“If you look at the measures, a lot of them address financing issues for the developers that are still in relatively good financial health, so that will help,” he added in an interview with CNBC. “But the problems of the property developers’ facing severe financial difficulties are not yet addressed. The issue of the large stock of unfinished housing more broadly is not yet addressed.”

China is slowly coming back, Dassault Systemes CEO says

Apartments in China are typically sold to homebuyers before completion. Covid and financial difficulties slowed construction so much that some homebuyers halted their mortgage payments last summer in protest.

Chinese authorities subsequently emphasized the need to help developers finish building those pre-sold apartments. Still, residential floor space sold in China dropped by nearly 27% last year, while real estate investment fell by 10%, according to official numbers.

“I think it would be helpful to point to a way out and … how the restructuring could be done and who will absorb losses if there are any losses,” Helbling said. He also called for additional measures to address the large stock of unfinished apartments.

Read more about China from CNBC Pro

“Otherwise the sector will continue to slump and remain a risk and also constrain households that are overexposed to the property sector, and will have cash tied up and their savings tied up which will be a handicap for the broader economic recovery,” he said.

Helbling declined to name a specific timeframe within which authorities needed to act before the situation got much worse.

“The sooner you address downside risks the better.”

China says it’s not a crisis

Chinese property developers such as Country Garden, Longfor and R&F Properties have seen their shares nearly double or more over the last 60 trading days — about three months, according to Wind Information. But trading in shares of one-time giants Evergrande, Shimao and Sunac have been halted since March 2022.

The IMF report pointed out that a significant portion of investors in Chinese developers’ bonds have been affected.

“As of November 2022, developers that have already defaulted or are likely to default — with average bond prices below 40 percent of face value — represented 38 percent of the 2020 market share of firms with available bond pricing,” the report said.

Read more about China from CNBC Pro

“The sector’s contraction is also leading to strains in local governments. Falling land sale revenues have reduced their fiscal capacity at the same time as local government financing vehicles (LGFVs) have also significantly increased land purchases.”

The IMF on Monday raised its global growth expectations for the year due to better-than-expected growth in major countries late last year, softening inflationary pressures and the end of China’s Covid controls.

The new 2.9% forecast for the world is 0.2 percentage points better than anticipated in October. But it’s still a slowdown from 3.4% growth in 2022.

For China, the IMF projects growth of 5.2% this year, faster than the 3% pace in 2022.

— CNBC’s Silvia Amaro contributed to this report.


Source link

China’s real estate crisis isn’t over yet, IMF says Read More »

How To Show Your Business A Little More Love

How To Show Your Business A Little More Love


Entrepreneurship is a long, complicated road, often littered with unforeseen landmines and fires that need to be put out. It’s not a lifestyle for the timid, and its fast-paced nature rarely presents opportunities for contemplative reflection. As 2023 unfolds, however, it’s important to take a step back and look at areas where your business may need more attention in order to achieve your goals.

We interviewed prominent leaders at three companies and asked them why they thinking taking a step back to review company processes is a necessary task. Where should they begin?

“Entrepreneurs start their companies to pursue their dreams,” says Greg Alexander, CEO at Collective 54, the first mastermind community for boutique professional services firms. “Yet, in pursuit of these dreams, life gets in the way. Between emails, Zoom calls, and client meetings, it’s important to step back from time to time to sift through the noise and remember why you’re in business to begin with.”

Harshith Ramesh, co-CEO of Episource, a leading provider of risk adjustment services, software, and solutions for health plans and medical groups, said he tries to look at tasks in terms of the “Eisenhower Matrix,” a 2×2 table grouping tasks by how important and urgent they are.

“When you’re building a business — and especially in the early stages when you’re in high-growth mode — you end up spending all your time in the ‘important and urgent’ bucket,” he says. “In the early days, it’s okay; you’re doing everything you can to get and keep customers. You’re trying to survive and just get it done. However, you have to keep in mind that you start racking up organizational debt while doing so.”

What if ‘what if’ happens?

Larry Clarke, CEO at NanoGuard Technologies, which leverages the power of technology to prevent food and feed waste and aid food recovery efforts, understands the pressures of a startup lifestyle all-too-well. When asked how he’s doing, he answers matter-of-factly that he’s spinning like a top.

“While it is true, it is also seen as a badge of honor. In reality, my answer should be ‘I am quietly reflecting on the long-term business strategy and direction.’ Doesn’t have the same pizzazz, does it?”

While a startup requires that everyone be willing to step up and do a little bit of everything, a CEO needs to be able to look back and evaluate what’s working in order to sow the seeds of future success.

“That means allotting specific time to step back and review the greater marketplace, the long-term goals of the business, and how to articulate these to myself and stakeholders,” Clarke says. “Someone must always be thinking about the ‘what if.’ What if the technology doesn’t work? What if the markets change? What if someone else bring along a better, more disruptive mousetrap? Someone needs to be considering Plan B and C. And even D.”

Startups, by their very nature, run the risk of needing to pivot on a dime. But when they focus to the point of obsession, they can’t accomplish that easily and may miss out on prime opportunities.

“Taking time to let your mind wander is a good thing,” says Clarke.

Going from doer to thinker

The leaders of small companies are scrappy and prefer to get things done, so going from a “doer” to a “thinker” is not an easy transition. To force the issue, Clarke believes that blocking off a set period in the day for “big-picture” thinking is key.

“Making the time is time well-spent because it is the effort, that over time, creates value. I take time out at some point in each day to just think,” said Clarke. That structure—and the right tools—are helpful to get into that contemplative mindset.

“I like a whiteboard,” says Clarke. “Also, thinking out loud helps me. Having someone to listen and question your thoughts in a broad way, not trying to direct you, but creating an open dialogue to help the process along.”

Ramesh said he makes it a point to block off some time on his calendar on a weekly basis to address these “Important & Not Urgent” issues.

“Historically, our company ran pretty lean,” he said. “However, over the last few years, we’ve over-invested in our organization, hiring executives and managers in key positions in which one of their primary responsibilities is to focus on where the business most needs attention. We ask that our executives and managers dedicate around 20-30% of their time to these issues and how they can optimize the business. Thus, it’s important that entrepreneurs and business leaders take some time to step back and address what’s in the bucket of ‘Important & Not Urgent.’”

Asking the right questions

As you think about your business processes and procedures, here are a few guiding questions that you can consider:

● Are we properly investing in all areas of the business (finance, legal, compliance, IT, sales, etc.)?

● Do we have a strong people program and culture? Are we developing leaders? Do we have a strong hiring and training process? Do we have competitive compensation and performance management?

● What does our three-year plan look like?

● What are the biggest risks to the business? Do we have plans in place to mitigate those risks?

● Could we improve our consultants, advisors, and/or board of directors?

In Ramesh’s experience, a business can’t — and shouldn’t — be overly dogmatic about sustainability and scalability.

“In the early stages of growing a business, it’s especially critical to understand your clients, build solutions to solve their needs, and generate revenue,” says Ramesh. “If you consciously make the decision to move fast in the business’s infancy, know that down the line you’ll need to refocus your energies and strike a new balance to create a scalable, long-term business.”

While you’re looking forward, take the time to look backward, too. Twice per year, Alexander reviews the original business plan he wrote before launching his firm in 2019.

“A lot has changed since then. Many of my assumptions were wrong, and some were correct. But, what has not changed is the mission, vision, values, and goals I set forth pre-launch,” Alexander says. “I remind myself of these and screen the current reality against them. If we are not living the mission, vision, values, and goals, we recalibrate. These are the North Star, and they never change. But the business tactics change all the time.

“It takes 15 years to become an overnight success. As much as things change, the truly important items change very little.”


Source link

How To Show Your Business A Little More Love Read More »

How to Find Out Who Owns a Property and Direct Mail 101

How to Find Out Who Owns a Property and Direct Mail 101


You stumble across the perfect rental property, but you don’t know who owns it. So what do you do? Walk up the door and present an offer? Ask the neighbors? Or, is there a better way to do some sneaky searching that could land you the perfect off-market real estate deal? The rookies want to know, and on this Rookie Reply, we’ll get into EXACTLY how to do this, even if you’re starting without much money!

We’re back for one of our last live Rookie Reply episodes! This time, we’re touching on questions about finding off-market property information, what to include in your direct mail letters, and why a home wouldn’t qualify for a mortgage. We’ll also hit on commonly asked title questions and whether or not you can buy real estate while underwater on another mortgage. So, if you’re trying to get your next deal off-market, this is the perfect episode to listen to a few times through!

If you want Ashley and Tony to answer a real estate question, you can post in the Real Estate Rookie Facebook Group! Or, call us at the Rookie Request Line (1-888-5-ROOKIE).

Ashley:
This is Real Estate Rookie episode 258. So one of the first ways that you can look at a property for free and get some information on it is going to your county’s GIS mapping system. So if you know what county this property is that you just drove by, you’re going to Google Erie County GIS mapping system. It’ll take you to the county website where there’s a link to their mapping system where you can put in the address of the property. You can kind of zoom in on a map on the property and it’s going to give you some generic details about the property. My name is Ashley Kehr and I’m here with my co-host, Tony Robinson.

Tony:
And welcome to the Real Estate Rookie Podcast, where every week, twice a week, we bring you the inspiration, motivation, and stories you need to hear to kickstart your investing journey. And today I want to shout out Chad and Emily who left us a five-star review on Apple Podcast. They say, “Longtime VP listener, but I love the way the host keep it simple and actionable. If you’re just beginning and don’t need deeper understanding of the nuances in real estate, this is where to start. Using this podcast and other VP content, we have purchased an investment tri-plus last year, even during these hots market conditions and now have the lot next door in our contract with seller financing. This show really works.”
Chad and Emily, congrats to you guys on all that success, and thank you for that five-star review. And if you’re listening and haven’t yet love to say five-star review, please take just a few minutes out of your day, do that small favorite for us. The more reviews we get, the more folks we can reach, more folks we can reach, more folks we can help. Ashley Kehr, how you doing?

Ashley:
So once again, we are live in Phoenix. This is what, probably the-

Tony:
Episode 333 that we’ve done here.

Ashley:
But they’re all in different orders that we did, but for a while we’re going to be doing some live recordings. So let us know how you guys ended up liking these episodes in person. I feel like it’s a lot more fun to get to talk-

Tony:
Actually sitting here with me.

Ashley:
And actually for this episode, this is the last one we’re recording before we head to the airport. My actually flight just got delayed, so we’ll see if I actually make it home.

Tony:
I don’t know if you guys know this about Ashley, but she probably has the worst travel luck out of anyone I’ve ever, literally ever met. She went to Florida and it hurricaned in Florida when she was there last time. It’s like everywhere you go.

Ashley:
Yeah. And then I went back to New York, so Florida was a state of emergency. I went to New York, they had a big snowstorm state of emergency.

Tony:
And right now she gets a flight saying blizzard warning for her layover in Denver.

Ashley:
And that’s not even the flight that’s delayed. I’m delayed to Denver, so I’m sure if I do make it to Denver then [inaudible 00:02:35]-

Tony:
It’ll be even longer. So anyway, the lesson to take away from this is if you find yourself on a flight with Ashley, get off.

Ashley:
So we decided for our last episode here together for this one, we are actually going to have a drink. I think that probably during the episode we were talking so much we each only took one sip maybe, or two.

Tony:
[inaudible 00:02:59].

Ashley:
So if you’re listening to the show, feel free to have a drink with us.

Tony:
Well, you know it’s bad luck to cheers and not drink.

Ashley:
I’m focused on the cheers.

Tony:
[inaudible 00:03:08].

Ashley:
So Tony, what was your favorite part about being in Phoenix and the meetup?

Tony:
First, if you guys came out to the meet up, we appreciate you guys. If you missed it, please do go to the Real Estate Rookie Facebook group, we’re the BiggerPockets forums. Let us know where you guys want to see us next. We really do want to take the show on the road and meet more people from the rookie audience.
I think my favorite part of being here was hearing the stories. I met so many amazing people. I met a kid who was 19 years old already thinking about investing in real estate. Met another guy that was 20 years old already door knocking, trying to find deals. I met someone who flew all the way from Ohio. I met people who, just so many different stories and so many different achievements and so many different successes. And that’s what makes this role that we have as podcast hosts so incredibly …

Ashley:
Yeah. I mean, I’m on East coast time right now, so I was up pretty early, but I have to see the energy in that room yesterday motivated me to get to work right away this morning.

Tony:
People always tell us, they come up to us and say, “Tony, Ashley, thank you guys so much for everything you do on the podcast.” And I heard a little bit of that last night as well. And what always tell people is that, really, all we do is we answer the …

Ashley:
We facilitate it.

Tony:
Right, we facilitate the conversation, but the people that really bring the value are the guests for sharing their stories. And then really, it’s all the listeners who take those stories and turn them into action. Because we could put out this podcast, people could listen and do nothing with it and no one would really care. But it’s the fact that people are hearing these stories and doing something with it that makes all the difference. So kudos to you guys for taking action.

Ashley:
So if you guys want to find out more about meetups and events that BiggerPockets is doing, you can go to biggerpockets.com/events.

Tony:
All right, so we’ll get into the first question. Today’s question number one comes from Sam Ecmillian, and Sam, I hope I got your last name right there. But Sam’s question is, what is the best way to find the name and the number of a property owner? On the way home, I see this one home that’s been what appears to be abandoned for over a year, and I would like to get in touch with the owners to buy it. Any help is greatly appreciated. So Ashley, as you’re driving through Western New York and you see those houses that you want to buy, what steps are you taking to find those property owners?

Ashley:
This is why I don’t like to drive so that I can take action right away and actually look up the property.

Tony:
You have other people drive you.

Ashley:
Yeah, so-

Tony:
Wait, let me ask a question. Can that be a business write-off then? Say that you hire someone to drive you around-

Ashley:
Oh, definitely.

Tony:
… just so that you can look at deals.

Ashley:
Or even just so that I can do work-

Tony:
Work.

Ashley:
… in the backseat.

Tony:
Man.

Ashley:
Actually, we were talking today about how I put in a reservation for the Ford Lightning, the electric Ford. And part of the features of it was it actually had a desk tabletop that would flip out from the [inaudible 00:05:52] console. That was one of the selling points, like I can actually use it.

Tony:
So a new tax strategies unlocked here on the Rookie podcast.

Ashley:
So one of the first ways that you can look at a property for free and get some information on it is going to your county’s GIS mapping system. So if you know what county this property is that you just drove by, we’re going to Google Erie County GIS mapping system and it’ll take you to the county website where there’s a link to their mapping system where you can put in the address of the property. You can kind of zoom in on a map on the property and it’s going to give you some generic details about the property.
So you’ll have the address, you’ll have the current owner, sometimes it will include the sales history of the property, what the county property taxes are, and then also a mailing address for the owner. So that’s the address that is actually on the tax record where the property taxes are mailed.
So you can get an idea of, if the mailing address shows out-of-state, it’s probably an out-of-state owner. If the property taxes aren’t mailed to that property and appears to be vacant, well then that’s kind of a dead end because if you mail the property, mail to that property, you’re not really going to get anyone if you do know that it’s vacant or maybe it’s just really distressed and it’s really not vacant. So that would be the starting point is going on there.
You could also go to the town website and pull up the property taxes. Almost all municipalities have the property taxes online that you can go and you just put in the address and it’ll pull up the property tax record showing the mailing address and the current property owner. And then there’s paid services like PropStream where you can pay $99 per month to get access to information like that. And then also Invelo is a new partner with BiggerPockets where you can pull information like that too. So if you’re a pro member that is free.

Tony:
Yeah, I’ve used the paid software a lot to source all of our off-market deals and it’s super cool. 30 seconds or less, you find the property, plug the address in, skip trace the owner and you got some contact information.

Ashley:
Do you want to talk more about skip tracing because I touched on the mailing address if you’re mailing them letters.

Tony:
Yeah, so it’s a lot of times, these property softwares, they will give you as part of your initial subscription, the property owner’s name and address. But if you want a phone number, typically you have to skip trace. And skip trace comes from, I don’t know where it comes from, but anyway, the process of skip tracing is, I don’t know what it does in the backend, but it takes this person’s information, their name, their addresses, and it looks for some kind of records online that have phone numbers associated with that person’s information. And then it spits out a phone number for that person.
Typically, you’re going to get several phone numbers and you don’t know which one is the right one. You could get up to 10 phone numbers back for one person and you got to work through each one of those 10 to find the right phone number. And sometimes you’ll call, say you’re calling for Ashley and maybe you find Ashley’s brother and, “This is not Ashley Kehr, this is …” Ashley, what’s your brother’s name?

Ashley:
Chad.

Tony:
“This is Chad Kehr. What are you calling for?”

Ashley:
Malloy.

Tony:
Oh yeah, Malloy. But anyway, sometimes you have to work through some of those dead leads. Some of the other issues that I run into sometimes with some of these paid software is that when you look up the owner, sometimes it’s an LLC, and with an LLC it doesn’t really show what an owner’s name is. Sometimes it’s a PO Box, so it’s hard to figure out where to mail that stuff.
So what I typically do when it’s an LLC or some kind of entity is I look that up on the state, the Secretary of State website. So every state has an SOS website, Secretary of State, and if you plug in that entity’s name, so 123 Main Street LLC, and then it shows who the registered agent is, sometimes a mailing address. And then there’s one step further you can take to try and find that person’s contact information.

Ashley:
And if you remember when you were a toddler and you went to somebody’s house and they didn’t have a booster seat, they give you that big old phone book to sit on as a booster seat. So you can go online these days and go to the whitepages.com and you can even search the person’s name on there too by state. So if you do get their mailing address, you might even be able to get a phone number off of the white pages too.

Tony:
Have you used that with success before, the Whitepages?

Ashley:
Yeah.

Tony:
I know that it’s around, but I’ve never actually used it, but that you’ve actually had success with it.

Ashley:
Yeah. And also another way too is if you have the person’s name, so if it’s a personal name and maybe you have their mailing address so you know that they’re from the Buffalo, New York and you go on to Facebook and search their name on Facebook too and see if anybody comes up, that it shows that Tony Robinson from Buffalo, New York, he has it in his profile, comes up, you can take that risk and message the person, “Hey, are you the owner of this property?”

Tony:
That’s like some next level type sleuthing there. Have you seen You on Netflix?

Ashley:
Yeah.

Tony:
That’s like some Joe type activity. So for all my You fans out there, you know what I’m talking about. Cool. All right, let’s jump into the next question here. So question number two today comes from Will Harrington and Will says, “For those of you who do direct mail, do you list your offer price and terms in the letter or is the goal to get them on the phone first?”
That’s a great question, Will, and I’ll kind of share what steps I take in this. So when you send direct mail, think about it almost like dating. And you like the dating analogy with partnerships, but it works well for this as well. When you date someone, when you first meet them, you don’t say, “I love you and I want to marry you.” You say, “Hi, my name is Tony, what’s your name?”
And when you’re going off market, it’s very much the same process. Two reasons that I would recommend you don’t give the offer up front. First, it could turn that person off if the offer is way too low, they might not even take the time to respond to you and maybe they would’ve taken that offer had you really built some rapport with them first and communicated the value you can provide to them and all those other things. But they just see the number first. If it’s lower than what they want, they may not even take the time to communicate with you.
And on the flip side, if your number’s super high and they respond right away and say, “Yes, take my home,” it’s probably a sign that you could have gotten it for a lower price. So I think the purpose of that direct mail is just to express your interest in purchasing that property and then it’s the phone to phone or the face-to-face or on the phone conversations where you build that relationship and provide the value to get it at the right price.

Ashley:
The person that I want to refer you guys to is Nate Robbins. So on Instagram he’s N8, the number eight, Robins, and I have him onto every bootcamp session I do to talk about direct mail and cold calling.
So what he does is I agree, not putting the terms because you haven’t even seen the inside of the property yet most likely. So you don’t actually know what you can really offer the person, but when he actually sends out the letter and then maybe they call him or he’s just doing a cold call or door knocking, he likes to let the person know. And within the first 30 seconds, the reason for the call is, because there’s that kind of you’re getting a call from somebody unknown or you’re calling someone and letting them know, “I’m interested in purchasing your property.” And then that’s where you kind of lead into, “Let’s discuss more about it.”
And he tries to get as much information as he can and if they ask for an offer, “Well, what do you want me to sell it for? What are you going to pay for it? What’s your purchase price, what’s your offer?” And he goes on to say, “To give you a fair, reasonable price, I would really need to come and see the property. I don’t want to waste your time by giving you some number that I’m throwing out without actually seeing the property itself. I’m available to tomorrow, I can come out to the property, I can take a look at it and I can give you an exact number instead of a ballpark number as to what I would offer for.”
And really explains that it’s to the seller’s benefit that they’re going to take him through the property and show him instead of him just throwing out some random number because he is letting them know it wouldn’t be a number he could commit to without seeing the property anyways. So what would be the point?

Tony:
Yeah, that’s a great point. And there really is a framework you can apply to direct to seller conversations. And Nate Robbins is a great resource. Brit Daniels, he’s got a bunch of free stuff on YouTube where he breaks down his scripts with folks. Another guy by the name of Max Maxwell who’s also been on, I think on one of the BP podcasts before. He’s got a great kind of framework around how he speaks to people. So do a little YouTube university, you guys can find some great resources on how to communicate with those people when you got them on the phone.

Ashley:
Our next question is from Iva Forton. “Newbie here, what are the reasons a house wouldn’t qualify for a mortgage?”

Tony:
That’s a great question. Have you ever applied for a loan and it not gotten approved because of the condition of the home?

Ashley:
No.

Tony:
I haven’t either. But I think it’s because I have purchased homes that I think have been in pretty terrible shape.

Ashley:
You didn’t try to get the loan.

Tony:
I didn’t try to get a traditional loan. We went with private money are hard money. So I don’t know. What would your advice be to Iva?

Ashley:
So part of the reasons is that it’s inhabitable. So especially if you’re going for an FHA loan or maybe even a BA loan where it’s meant to be your primary residence and they want you living in the property pretty quickly after closing. So they will actually go through and FHA does their own inspection. This is separate than you hiring an inspector, they’re mostly going through to making sure that the property is habitable, all the mechanics are functioning, that it’s also up to code.
So I remember when my cousin bought a house with an FHA loan, they had to have handrails installed on the stairway because it wasn’t up to code without those handrails, and they couldn’t close on their FHA loan until that was done on the property. So there’s things like that.
But then if you’re going the conventional route where there is no FHA inspection, it’s more flexible, but also the bank may not go onto the property if it doesn’t have running water, things like that. Bank sometimes will require that you have a well and a septic inspection. So if those are not operating, that needs to be corrected. But that can get pretty expensive too to do.

Tony:
Yeah, and what we talked about so far is the physical nature of the home, but it’s also the nature of the contract you have. So another reason that a home wouldn’t qualify for a mortgage is if the amount that you have it under contract for is higher than what the property’s actually appraised for.
So say you’re trying to buy a house for half a million bucks, but the bank only thinks it’s worth 400,000, they’re not going to give you a loan for that $500,000. They’re going to give you a loan for the $400,000 and now you as a borrower are responsible for that $100,000 difference. So that’s the only other scenario I can really think of outside of the condition.

Ashley:
Actually, that made me think of one more, and it would be if you cannot get title insurance on the property. So a bank will not give you a loan on a property if they can’t get title insurance. And that’s basically saying when the title company went and did the title work to show that yes, the person’s selling it is the owner and you are now the buyer going on title and there’s no liens, there’s no judgments, nobody else owns it, you’re getting title insurance in case they made a mistake so that you’re able to, the insurance will pay out, you can pay off your loan and pay damages from having this corrected or you lose the house to the person was actually the owner, but the bank will not lend on it if you can’t get that title insurance. So I’ve come up with this in two circumstances.
One was a campground where it was actually sold at the county auction for back taxes. The bank actually that had the mortgage on it is the one who bought it from the county at the sales auction. During that time period, there was no title insurance put on the property to show those two transactions. So it going from the owner that defaulted to the county and then the sale from the county to the bank.
So a title insurance would not put title insurance onto that property for so many years, like a time period had to pass. And if nobody claimed ownership or called out an issue in the title, then they would go ahead and reinstate that. But that means that there was no bank that was going to lend on it, and that’s coming up with cash to hold that property in cash until it was bank financing.
The second time I ran into it as a lake property where they had a separate parcel that was included into the sale, but the separate parcel was actually where the driveway was, so it needed to be included with that house. The Lake Association had actually sold that piece of property to the current owners.
Well, it had actually been an abandoned piece of property and we couldn’t get title insurance on it because there was no record of any previous owner. And later on we actually did some digging and the sellers actually found a letter of abandonment. So with that letter then we were able to get title insurance, but if there wasn’t that letter then we wouldn’t be able to get title insurance and the bank wasn’t going to finance at that point.

Tony:
We should probably bring a title insurance expert onto the show.

Ashley:
Yeah, that’d be really cool.

Tony:
Just to talk about the purpose of title insurance, different claims that people have filed because title insurance for a lot of us is just something, like a box we check when we’re closing that your lenders typically make you get, but it’s not something that I think a lot of people understand in detail around what is it actually for? When can I use it? And what are the risks of not having title insurance?

Ashley:
Yeah, I actually did, last spring it was, I did a hard money loan and the closing was actually at the attorney’s office of the hard money lender and there was some issues with the title work there and they actually had a title attorney at the closing who was trying to figure out the situation. But it was a three-hour-long closing and we ended up not even figuring it out.
It was a Friday and we ended up having to wait until Monday to close. But we sat there and we literally just picked this title attorney’s brain going after all these scenarios and things and it was really interesting. I did ask him if he would like to come on the podcast and stuff. He’s like, “I do so many speaking events and things like that.” Here I am thinking here’s an opportunity, come, get some more clients, come to the podcast. He’s like, “Oh, I do so many speaking engagements, I’m really kind of burnt out.” I’m like, “Oh, okay.”

Tony:
You win some, you lose some. All right, so our next question here comes from Nathaniel Munier and Nathaniel’s question is, I have the opportunity to purchase four single family rentals from my wife’s relatives. They’re very upfront and honest about the houses. Would you do a title search on each of these properties or save the $1,000? This will save me some out-of-pocket costs, but it would be the property I’ve purchased without a title search. We kind of just touched on this, right?

Ashley:
Yeah, I would say no because they could not even know of the issue.

Tony:
Just because they think it’s clean doesn’t mean there wasn’t something happened before they owned. So I don’t think we need to spend too much time on this one because …

Ashley:
And usually it’s typically the seller that is paying for the title work because usually they should have the title search already or the abstract of title and give it to the title company and then it gets sent to your attorney and then you’re updating it from there.

Tony:
I think we pay for our title work.

Ashley:
Well, I think it’s split because it goes on both sides of it, but you can usually have the seller cover all of it, but there’s work that needs to be done on both ends. So there was actually a property I was selling that somehow we misplaced the title of abstract, the title search, so we had to pay for a new title search. So I’m thinking at the cost of that, that they probably don’t have the title search anymore, that being that it would cost $1,000 because usually it’s not that much to just update a title.

Tony:
And I was going to say, I’m not even sure what we pay for our title reports because it’s just something that’s rolled into our closing costs. So if you ask me what we pay, I can’t even tell you.

Ashley:
Yeah, my attorney, we usually pay around $1,200 per closing and she fronts the closing costs of doing the title work. So I know that she’s not making only $200 on it. So another thing that goes along with the title insurance is a survey. Sometimes a seller will ask you to accept the survey that they have.
So I actually just closed on a property last year where I accepted a survey from 1986. It was my attorney talked to the surveyors who had done it. The property was still went and staked out where the survey lines were and we accepted it as is. But that is something to also be cautious of if lot lines have changed and the survey has been different.
So there’s also been properties where we went to … the seller went to go have it surveyed and issues came up from the last time they had it surveyed until now, and they had to resolve those issues with the neighboring property owner before we could actually close onto the property. So that’s another thing to not skimp on if you’re not sure of the whole picture of the parcel.

Tony:
Yeah, I mean, I think for me, just the spirit of the question I think is what are some ways I can save money, but I think if you are making this several hundred thousand dollars investment into a property, spending that extra $1,000 to protect yourself is so worth that small investment because imagine if there was an issue with the title or the survey or whatever it was, that’s going to come back and potentially cost you way more headache, more cost and more time than the [inaudible 00:23:48] cost a thousand bucks or so.

Ashley:
And do people actually go and not do the title search? They must be just doing a quick claim deed and then updating the title, not actually going back and doing the title search.

Tony:
I’ve never not had a title report run, so I’m not even sure what the process is if you don’t. I literally couldn’t even tell you.

Ashley:
Yeah, because you’ll still have to pay a fee to have the title updated to show that you are now the deed, hold the deed on the property. Another thing to add on to that too is so within the last couple years, the market’s really hot. People are waiving inspections, everything like that, and you couldn’t have any kind of contingency on a property. But now that is kind of changing and also with this example where it’s your family, so I doubt that you’re competing against a ton of other buyers too.
So I think it would be perfectly acceptable to ask for these things. And even for anyone listening, if you’re putting in offers, now is not the time to skip an inspection. You’re at an advantage now that you can put an inspection into your property and it’s not going to be completely out of the bidding process, I guess.

Tony:
Yeah, I think in the last few years to be competitive, a lot of people were doing that, but for our rookies, I think it is a slippery slope because if you get into a property, there are some things this family, they might not even know that something’s wrong with the property. When’s the last time they scoped the sewer line or they check the HVAC or if there’s a septic tank, did they have the septic tank inspected? There’s so many things that are kind of behind closed doors that you can’t see unless you open up and do an inspection.

Ashley:
Or one thing may be okay to you or be okay to your father-in-law but not be okay to you like, “Oh yeah, every year I got to go in there and jiggle this thing.”

Tony:
It’s fine. It’s no big deal.

Ashley:
Yeah, no worries. The hot water tank, it maybe starts making noise, just give it a couple kicks.

Tony:
Everything’s good.

Ashley:
Because I think it’s way better to just go ahead with the inspection now and just be honest with them too and say, “You know what? I completely understand your honesty, but I would still like to do an inspection on all these things in case there’s things you guys don’t know about the property.” So if they’re rental properties and maybe it’s a septic or a sewer and you want to do a sewer scope is to, one of the tenants could’ve shoved something down there and it’s about to crack the pipe or something like that.

Tony:
Or even sometimes little things change in the code and what’s safe 30 years ago might not be safe today. We have a property where it was something about the wall in between the garage, the wall in between your home and the garage, there wasn’t enough fire protection in that wall. So it’s like there’s certain little things that pop up that you never know unless you actually do that inspection.
All right, so our next question comes from Emily P and Emily’s question is, does anyone know that if the housing market crashes, if you can buy a house for investment purposes if your primary residence is underwater? If I’m still making payments, but suddenly it’s value dropped by $200,000 and I owe more than it’s worth. So this is a great question, Emily, and just to paint a picture for the rookies in case that wasn’t clear.
What Emily’s question is, is say you have a primary residence that you bought for $500,000, that’s the amount of the mortgage that you have on that property. Your loan balance is $500,000, because the market shifts, say your appraised value to what your property would sell for today goes from 500,000 down to 200,000. Some big difference. So now you’re underwater on that property.
Emily’s question is, does the fact that I have negative equity, the loan balance on my house is higher than what the appraised value is, will that stop me from buying an investment property? The short answer is no, it shouldn’t. Typically when you’re going to apply for a new loan, what they are looking at to approve you for that mortgage is your debt to income ratio and your credit score. They want to know what is your profile as a borrower. As long as you are current on your mortgage, and as long as your credit score is still strong, you have the ability to get approved for that new mortgage with your debt to income ratio, typically they’re going to approve you for that loan.
What they won’t look at, and I don’t think you’ve ever had this happen before either, when you apply for a home, typically they are not going to go back and appraise all of the other properties that you own to make sure that they’re underwater or not underwater.

Ashley:
Yeah. The only reason they would do an appraisal on your primary residence is if you’re going to use that house as collateral for the loan. So if you’re getting a line of credit or refinancing your mortgage, or maybe you’re doing a portfolio loan where you’re including a rental property in your primary residence, but if you are not using that property as collateral, they’ll never go and ask.
And if they do ask what the value of that house is, you can tell them, I purchased the property for $500,000 in 2021 or whatever it is, and give them the purchase price of that property. Plus maybe if you did any improvements on it to show the value of the property.

Tony:
Yeah, I’m trying to think if there’s any risks associated with that happening where your primary residence goes underwater and as long as you’re like on long-term fixed debt and you have the ability to keep making those payments, I mean, hopefully eventually your house value’s going to rebound. Maybe the only time you get in trouble is if you’re on some kind of like adjustable rate mortgage or some kind of short term debt where the payment is one number today, but a year from now it’s going to adjust up to some higher number. Now you’ve got a mortgage that was 2,000, now it’s 5,000 or some other crazy high number, and now you don’t have the ability to carry both of those mortgages.

Ashley:
And that could happen even if your property has appreciated value, where that happens, where your payment changes, if you are on a variable, you switch to a variable interest rate. But the problem here is if you are underwater and you can’t afford what that new mortgage payment is, you can’t go and sell that property very easily without probably putting some money into the deal to pay it off or taking a big loss on it too.
Thank you guys so much for listening. I’m Ashley, @wealthfromrentals. And he’s Tony, @TonyJRobinson, and we will see you guys for the next episode.

 

??????????????????????????????????????????????????????????????????????????????????????????

Interested in learning more about today’s sponsors or becoming a BiggerPockets partner yourself? Check out our sponsor page!

Note By BiggerPockets: These are opinions written by the author and do not necessarily represent the opinions of BiggerPockets.


Source link

How to Find Out Who Owns a Property and Direct Mail 101 Read More »

Eight Steps An Entrepreneur Can Take To Start Repairing Their Personal Brand

Eight Steps An Entrepreneur Can Take To Start Repairing Their Personal Brand


Everyone makes mistakes from time to time, and entrepreneurs are no exception. With so many pressures and responsibilities that affect not only themselves, but also their employees and customers, it’s almost inevitable that an entrepreneur will occasionally make a bad decision. However, sometimes big mistakes can lead to big consequences that can tarnish the entrepreneur’s reputation.

But that doesn’t necessarily mean there’s no possibility of redemption. Here, eight Young Entrepreneur Council members discuss what an entrepreneur can do if they’re looking to improve their personal brand after making a mistake and why these methods are so effective at turning things around.

1. Own Your Past

Before you can improve a damaged brand, the first step is to own the choices you made that led to the mistake. While audiences don’t expect you to be perfect, they do expect you to be honest. Being accountable shows that you are responsible, that you have integrity and that you’re relatable. Audiences love when someone takes personal accountability and can get back up. Owning your mistakes makes you a much more powerful entrepreneur in the long run. – Shu Saito, All Filters

2. Highlight The Lessons You Learned

When presenting their personal brands, entrepreneurs often introduce themselves as relentless forces of nature. They are so focused on displaying their past victories and accomplishments that they often forget about the human aspect—something that makes your brand relatable. No human is error-free, as we have all made mistakes in the past and will probably continue making errors in the future. But, that’s how we learn, evolve and grow to be better than we were yesterday. So, if you’ve made some mistakes in the past and are looking to improve your personal brand, highlight those mistakes and the lessons learned. Don’t present yourself as a deity but as someone whom others can relate to and be inspired by. – Jared Atchison, WPForms

3. Ask Your Network For Feedback

One step an entrepreneur can take to improve their personal brand is to reach out to their network and ask for feedback. By asking for feedback from trusted contacts and colleagues, entrepreneurs can gain valuable insight into their strengths and weaknesses, both professionally and personally. This feedback can help entrepreneurs identify areas for improvement and develop a plan for success. Additionally, by demonstrating their initiative and commitment to personal growth, entrepreneurs can show their network that they are serious about their professional development. This can help to strengthen their personal brand and build relationships with potential partners and investors. – Andrew Munro, AffiliateWP

4. Communicate With Your Team And Other Stakeholders

No mistake should be a roadblock for your entrepreneurial journey. Mistakes are temporary. Don’t let them define your future. A mistake is just a detour on the road to success. By reflecting on what went wrong and identifying the lessons learned, you can use that knowledge to develop a plan for the future and take action to move forward. Primarily, you’ll want to communicate with your team and stakeholders. If the mistake affected your team or business partners, it’s important to be transparent and honest about what happened. This can help build trust and strengthen your relationships. Also, develop a plan for moving forward. This might involve making changes to your processes or seeking additional support or resources. – Kelly Richardson, Infobrandz

5. Gather Plenty Of Data

If someone has made mistakes in the past, it’s likely they didn’t accumulate enough information to make informed decisions. So, this time around, the entrepreneur should conduct thorough research to take action. They should carry out a detailed assessment of their brand, current market trends and the competitive landscape to gather relevant information that facilitates an informed decision. This is an effective approach because data never lies. Making decisions by trusting your gut may backfire, but the decisions backed by research often yield promising results. – Chris Klosowski, Easy Digital Downloads

6. Share Your Story And Your Knowledge In A Book

One way for an entrepreneur to improve their personal brand is by writing a book. This can be a memoir, a how-to guide or a fictional novel. Books are the most impressive way of telling your story and sharing your knowledge with the world. It will give you the opportunity to build your credibility as an expert in your industry. – Kristin Kimberly Marquet, Marquet Media, LLC

7. Be The Person You Wish To Be Seen As

It’s about actions over words. When you’re in a place where you’re confident that your mistakes are behind you, then you can announce your new intentions to the world. Don’t be surprised if you are met with cynicism early on. Continue to be the person you wish to be seen as, and eventually, your brand will catch up to where it needs to be. There is no magic pill for sincerity, but the good news is that people love a redemption story, and if mending your personal brand is yours, you’ll get more than enough encouragement to balance out the hate. Focus on the encouragement and try to be the person you want your brand to be as often as possible. – Tyler Bray, TK Trailer Parts

8. Showcase Your New Achievements

One step an entrepreneur can take to improve their personal brand is to create a blog or website that showcases their work and accomplishments. This is effective because it allows them to control the narrative and shape their public image. By creating a website, they can create content that highlights their strengths and accomplishments while downplaying their past mistakes. Additionally, it gives them an online platform to showcase their ideas and projects, which can help to build their reputation as an expert in their field. – Josh Kohlbach, Wholesale Suite


Source link

Eight Steps An Entrepreneur Can Take To Start Repairing Their Personal Brand Read More »

“Catastrophic” Consequences of the US Defaulting on Its Debt

“Catastrophic” Consequences of the US Defaulting on Its Debt


The US debt ceiling has been hit; what happens next could send ripples through the economy. But is now the time to panic? Or is there still time to solve this situation? With the US economy relying so heavily on borrowing, the prospect of being unable to pay back its debts could come with a series of “catastrophic” consequences. Higher mortgage rates, a market crash, and an even harsher recession could be on the horizon. But what’s the likelihood of this happening? And are we really on the cusp of a debt debacle?

We brought on Sarah Ewall-Wice, Washington D.C.-based reporter, to help explain what is happening with the US debt limit. Sarah knows that many Americans are used to these types of debt ceiling congressional debates, but most people don’t know the impact these could have on their wealth, investments, and society as a whole. With COVID spending forcing the government to pay for even more, the debt ceiling has reached an almost unimaginable $31 trillion.

Sarah describes what would happen if the US defaulted on its debt, the programs that would be impacted the most, what republicans and democrats both want in their upcoming debates, and what everyday Americans can expect to happen over the coming months. Dave and Sarah also discuss the “trillion dollar coin” method, which could end the US’s debt quite quickly, while simultaneously acting as the most comical government bailout plan to date!

Dave:
Hey, what’s going on everyone? Welcome to On The Market. I’m Dave Meyer, your host. Today, we have a super cool new format for you. We are going to be bringing in a CBS News reporter to talk about an economic issue that has been making a lot of news recently, and that is that the United States just hit its debt limit. It’s this wonky but fascinating situation that’s playing out in Washington right now and could have potential impacts for real estate investors, all sorts of investors and just ordinary Americans. We wanted to help you all understand this issue in-depth so we’ve brought on Sarah Ewall-Wice, who is a reporter in Washington who covers this sort of thing in Washington DC and is going to teach us about the history of the debt limit, what’s going on in Washington right now, and what some of the implications could be for you and other investors. I really hope you like it.
We would love your feedback on this type of show. You can always go on the BiggerPockets forums and tell us about it. Or you can hit me up on Instagram where I’m @thedatadeli and let me know what you think of this show. With that, we’re going to take a quick break and then we’re going to welcome on Sarah to talk about the debt limit. Sarah Ewall-Wice, thank you for joining us On The Market today.

Sarah:
Hello. Good to be here.

Dave:
All right, Sarah, well, let’s start by having you introduce yourself to our audience and explain why you are here talking to us about this exciting, important, and somewhat nerdy topic.

Sarah:
Sure. I am a reporter for CBS News based in Washington DC. I cover both economic policy and also politics. The debt ceiling conversation is one that both hits on the economy big time depending on how long these talks go and also is a huge political talker for folks here in Washington, lawmakers, policymakers, experts all across the board. But we are back at that point where we’re talking about the debt ceiling again because the United States government hit the debt limit. So this becomes a conversation where members of Congress need to act now to avoid calamity.

Dave:
Okay. Well, that is definitely on my mind and many people’s minds. We’re going to get to that, but let’s just start at the beginning. Can you explain to us what the debt ceiling even is?

Sarah:
Sure. The debt ceiling, also referred to as the debt limit, is how much the United States government is allowed to borrow to pay the bills. This is very important to note. This is not how much the United States government is allowed to spend. This is the spending that’s already gone out the door across the board, across the federal government. It was actually first really saw the debt limit, it was back in 1917. There was a law and then it was expanded to cover all government debt right before World War II. But basically, Congress enacted this law and continually, every few years, they have to come back to it as the national debt grows and up that balance so that the United States government could continue paying the bills without going into default, which has never happened before in US history.

Dave:
Over the last couple of years, we are all hearing more and more about the debt ceiling. Has it always been of public interest?

Sarah:
It feels like it’s becoming more frequently and frequently talked about, and that’s because it’s become more of a political battle in the past couple of decades. Essentially, we’ve obviously always had this national debt and we’ve always really had a deficit depending on a few times where they’ve been able to balance the budget, but it does need to be addressed every so often. With that said, lawmakers have started using the debt limit to really come out as a tool to negotiate spending in Washington. We get to the point now every few years where we are hitting this limit and so that is when they come to the table and some lawmakers say, “Well, we need to cut spending.” Others say, “We just need to raise the national debt.” But the idea is is we get to this crisis point where it really needs to be addressed and then we kick it down, the can down the road rather than addressing the actual issue. And I say we, talking about Congress, rather than addressing the actual issue, which is how much the United States government is spending.
You keep in mind, the United States government has always really been borrowing to pay the bills. It comes down to tying the debt limit to the budget as they go, whereas these are two separate conversations that aren’t happening together. Then we get to this point where there’s a real freak out and a lot of concerns across the economy about what this means if the US stops paying the bills or is unable to pay the bills. So it’s become more frequent. It’s been used more of a tool lately. We saw in 2011, Republicans use this in negotiations with the Obama administration, and now we’re back here with the Biden administration, Republicans in a showdown over the exact same issue over a decade later.

Dave:
I do want to get into current events in just a minute here, but I just want to make clear. From my understanding, the debt limit has been raised dozens of times over the last couple of decades. The fact that it’s getting raised is not actually new. It’s just the political climate about it has changed a bit.

Sarah:
Yes. The debt limit has been raised dozens of times, many times in the past two decades. Just thinking back, we feel like we’ve had this conversation recently. It was raised in 2021, in December 2021. We had to reach a deal. Of course, it was raised or suspended three times under President Trump while he was in office over four years. So it’s an ongoing conversation. It’s raised multiple times in the Obama administration. Every time there’s this larger growing debt, they come back and they look at it and they move forward and they either raise or suspend it. Suspending it means they just kick the can down the road and it kicks back in later with the number at a higher level than it was when they suspended it.

Dave:
Okay. That makes sense. Obviously, we know during COVID, there was a lot of spending, but has the debt increased recently faster than it has historically?

Sarah:
I think it’s tricky really to say whose debt it is specifically. I think you can absolutely say during the coronavirus pandemic, the government, both under President Trump and then under President Biden, put out a lot of spending really to help save the economy from tanking, and that has added to it much more rapidly in the past few years. I would avoid saying, well, who’s added more to the debt, because it really is hard to tell because there’s been this accumulation of debt for so many decades in the United States. It’s tricky, but yes, I would say the coronavirus pandemic definitely did not help in speeding up the rising debt.

Dave:
Okay, great. You mentioned something earlier, which is that we have hit the debt limit. What does that mean?

Sarah:
Treasury Secretary Janet Yellen sent a letter to congressional leaders a little over a week ago, around January 19th. She said, “Hey, we’re starting to use these measures to move around money because we’ve hit the limit,” the limit being $31.4 trillion. That was the decide upon number back when they negotiated this last time in 2021. So they’ve hit that limit and now the Treasury Department is moving around funds to keep paying the bills. They call them extraordinary measures. It’s funny because these are not extraordinary anymore. We’ve used them many times starting in 1985 and onwards. We’ve heard it time and time again, but they’re so-called extraordinary measures still. Essentially, it means moving around money to keep paying the bills. But she did say that essentially, the ability to pay the bills would run out as early as June. There’s a lot of uncertainty because we do have revenue coming in, and as revenue comes in, the Treasury puts it out and pays the bills and is able to move things around. Starting in June, she says that could completely run out.
When it runs out and the United States government is unable to pay the bills, it’s the so-called X date. As we get closer to that timeframe, more policy experts will start to come out with their estimates on exactly what that date is. The Treasury Department will get a better idea of exactly what that date is. But when that date hits, the United States unable to pay its bills, and that is when the United States could go into default for the first time. That is where the real uncertainty happens. We’re in this period of this needs to be addressed and it’s a pressing issue, but we are not really sounding the red flags and the alarms aren’t going off at this stage. But of course, you know that Congress doesn’t do anything quickly, and so that is why it’s a pressing issue now rather than waiting till the last possible minute. Even if they reach a deal at the last possible minute, there could be repercussions.

Dave:
Yeah, absolutely. Let me just summarize that by saying basically, you’re saying that we have technically hit the limit and the implications in the long term are that if we can’t borrow more money, we can’t pay our obligations. As you said, the debt that we are financing is for spending that has already been approved.

Sarah:
Exactly.

Dave:
So that is the concern. But because the Treasury has some accounting tricks up their sleeves, they can continue to pay the debts of the United States even though we have technically hit the limit. Now, I think we were both about to just go to an idea that basically, I think it was 2011 where there was a negotiation over the debt ceiling and the United States did not default, but there were repercussions for it. Is that correct?

Sarah:
That is correct. There was a last-minute deal that was reached, and this was something that was negotiated between the Obama administration and House Republicans, which is a similar makeup to what we have now, where the White House is a Democratic president, but the House is run by Republicans. We have a Democratic senate currently. But they had to reach a deal and it came down to the wire where they were negotiating spending cuts to make this happen. Even though they were able to reach a deal, leading up to it, there was so much uncertainty that the stock market took a plunge and the US credit score or excuse me, credit rating was downgraded by S&P. So that had repercussions. There’s estimates that cost the US economy about $20 billion over a decade, which is one estimate that was done, but the S&P dropped about 6% leading up to that.
They were able to reach that deal, and we avoided a greater financial catastrophe, but that just goes to show that even leading up to this, as the clock ticks down to that so-called X date, or in this case, sometime in June as we’re seeing it, there are challenges and uncertainties that could lead to problems in the economy.

Dave:
That is something I think real estate investors in our audience will understand. Basically, what happened is that the credit worthiness of the United States was downgraded by credit rating agencies. When that happens, the debt, usually the person whose credit is downgraded has to pay more to get loans in the future. It’s a similar to taking out a real estate mortgage. If you have worse credit, you are going to pay a higher interest rate. What happened in 2011 is that the US basically became less creditworthy and had to pay a higher interest rate among other things and economic repercussions. That seems like just the tip of the iceberg. That is the tip of the iceberg of things that could happen if the United States were to actually default on its debt. Can you tell us a little bit more about what the repercussions could be if not just the debt ceiling has reached because we have done that, but the United States is unable to meet its obligations?

Sarah:
Yes. If the United States defaults, we started to get into it, this could be a catastrophe for the stock markets. We could see the stocks plunge across the board, not just the United States, but we’re looking at this from a global scale because the United States really sets the tone for the rest of the world. With that said, when you mentioned it, being able to borrow, this would boost interest rates on borrowing for the United States moving forward and that would cost the United States billions more on top of the trillions it already owes when it goes to pay its bills in the future. So that is one thing. The United States government, they’re supposed to be the most confident. It’s supposed to be risk-free investments. If it’s no longer risk-free and we’re facing all these challenges, what does that mean for everything else?
So that also has further waves or repercussions when it comes to how much Americans are borrowing because that boosts interest rates. When you’re going to get a mortgage, when you’re going to pay a car loan, now you want to buy a car, when you’re paying for credit card bills, your interest will go up across the board and this is on top of the already challenging time power in where we know inflation is high and the Fed is boosting interest rates. We’ve seen record high credit card interest rates already. So those are different things that are happening. At the same time, we have the repercussions that happen in the government itself because the government pays billions of dollars on a monthly basis to different parties across the board. Different groups of Americans receive different things. So for instance, if the United States is unable to meet its debt obligations, it will be unable to pay veterans benefits, for one thing.
Social security payments, one of the most important things for our senior citizens, those could be delayed, not go out in time when many people need those payments and rely on those payments. There’s also the things like the SNAPs program, formerly Stamp, so food benefits for low-income Americans. Different types of benefits that people rely on are going to stop and be delayed should we reach that point. The military would go unpaid, of course. We just hope they just continue working on the job. But that’s the reality and that has repercussions in the economy me because when they are getting the money, guess where that money’s going? It’s going out to businesses when they go and buy things. It’s going out for housing. It’s going out and it has this long ripple effect across other sectors of the United States coming from the government. So that is important to keep in mind. This won’t just impact those who rely on government payments, it’s anyone who’s relied on people who get any kind of government payment. Who knows really where this could go, but all in all, it’d be really, really bad.

Dave:
Yeah. That’s a question no one wants to answer. Yeah, no one wants to know what happens if the United States defaults on its debt. I think people on both sides of the aisle have basically said, we cannot default on our debt. But it does seem that given the importance of paying our debts, that that is basically why it’s being used as leverage for this broader conversation about spending and fiscal policy in the US.

Sarah:
That’s exactly right. It’s funny because it’s being used as a negotiation tool in a way where it’s really something that there should be no conversations about even going there. It’s just too risky to even consider, but it’s been tied into this political battle here in Washington that happens over and over again, when the reality is is lawmakers are setting budgets and paying for things and putting money out the door and borrowing to do it regularly anyway on both sides of the aisle. They have to come up with a budget every year, every couple of months, depending on how they go about it and that spending is happening anyway. So this just becomes one tool that has really brought people to the table, but in a way that could be really brutal and catastrophic for all entities. It’s a poor way of looking at the situation, but it’s the way that it’s come about for multiple scenario or multiple years now in recent decades.

Dave:
Yeah. It seems like basically, Congress has used this as a forcing function to talk about spending, even though it sounds like they’re not necessarily even related. The spending and what the Congress and the government is spending on is done during appropriations. That’s when they are spending money, but this is basically just a check mark to say, yeah, we will actually send you a check, basically for all those things we paid. So that’s interesting, but I think a lot of people feel that this is an important conversation to be had and I guess the debt ceiling somehow has evolved as the time when we talk about this. I’m just curious. You said House Republicans are negotiating with the White House. What is it that they’re hoping for and what are they asking for in exchange for raising the debt limit? That’s basically the conversation. They want reduction of spending in exchange for approving an increased debt limit ceiling.

Sarah:
This is the trick here. I should say the Republicans say they want to negotiate. We aren’t even at the point where they actually are negotiating yet. Just to be clear, there’s been a standoff on the start point of talks. I’ll talk about it in terms of the press office has said, the White House is not going to negotiate. This is not something they can negotiate on. This is a risk that will not be addressed and they need to raise the debt limit point blank. They’ve done it before under Republican presidents, why are they holding this hostage now? That is the White House messaging essentially on this. At the same time in Congress, Republicans are saying they absolutely need to negotiate on this and they also need to negotiate it in terms of spending cuts. They’re not actually saying specifically they want to see cut.
Democrats will point at them. Democrats in Congress point at them and say, “Well, they’re looking at Social Security and they’re looking at Medicare.” Some Republicans are in fact bringing up those two entitlement programs as a part of this conversation, but other Republicans are saying, “Well, no, we need to cut spending across the board.” So there’s really a standoff right now specifically on, well, what’s the plan? Who’s going to decide the plan? Because that’s where you can then go and point fingers depending on who actually comes forward with that plan and say, well, they wanted to cut this or that. So it’s still at the point where both sides haven’t taken a seat at the table and are asking the other side to sit down first and lay out a map of what they want to see. But that is where we’re at, where the White House wants it to raise the debt ceiling, we’ll talk about spending, but we’re not going to do it in this conversation. This is not where we’ll negotiate at this point in time.
And Republicans are saying, “Well, no. We have to negotiate spending at this point in time to address the debt ceiling and the debt limit.” So that’s where it’s at. I think in the coming months, coming weeks, really, we’ll get more information on where there could be places where there is a path to a compromise, but right now, it’s really a lot of posturing and not a lot of sit-down, hard conversations being had. There will be, I’m sure, other proposals about how to go about addressing this so we’re not in this situation again in two years moving forward between now and June, hopefully sooner rather than later.

Dave:
I’m guessing that you, being a reporter in Washington, you can describe a lot of things you cover as posturing.

Sarah:
Oh, most of it is posturing, I will say, and then suddenly something happens usually.

Dave:
Yeah. It just seems like what’s going to happen, is both sides are talking at each other, but there’s not really a conversation going on right now. What do you think happens? You said there’s posturing, but what do you think happens over the next couple of months? Is there going to be progress? Are the people like me who look at this very anxiously going to be worried for the next several months or do you think there’ll be steady progress towards a resolution?

Sarah:
I think people are going to remain anxious for a little bit of time. I will say, I think the White House and Republican congressional leaders are supposed to meet and start these conversations or just start a conversation in general. We are in a new Congress in the coming days and months. So that is a starting point. It’ll go from there. Every time this happens, there’s a standoff and at some point, somebody blinks. We felt that in 2021, where there was a standoff specifically in the Senate because they needed 60 votes in the Senate and that wasn’t happening. Then finally, essentially, Senate minority leader Mitch McConnell blinked, and in that instance, they were able to use just Democrats to raise the debt limit. So that’s going to be one of those situations where one side does have to blink. There are other ideas being floated out there about how this could go about where it doesn’t happen in this way moving forward.
I don’t know if they can reach any meaningful way to address this differently between now and June, but that is something that I think there’ll be another conversation so that we aren’t just kicking the can down the road. There will be a separate group. But the makeup of this Congress is different than it has been in the past and that’s why there’s different uncertainty surrounding this issue. In 2021, they needed to get Republicans in the Senate to step down so that they could pass it, but it was a Democratic-controlled Senate House and White House, so they were able to reach that deal. This time, there’s such a small majority of Republicans in the House that it’s harder to pass anything in the House, and there’s a group of very hard-line Republicans that are simply saying, “We will not vote on this.” So it comes down to they need to reach a compromise.
We’ve spoken to some Democratic congressmen who’ve said it’ll end up being a group of Republicans and a lot of Democrats who come and address this together to pass something in the House. So the makeup of how the House is made up has made this uncertain in a different way. Then of course, it comes down to what will the relationship really be between the White House and Speaker McCarthy and Congressional Republican leaders as they start to have these conversations, because like I said, we had a new Congress that came in in January.

Dave:
Yeah, it’s very interesting. It seems like one of the first tests of the relationship between the new Congress, the White House, and that everything that’s going on happening at a crucial economic period. We’ll have to see what happens, but thank you for explaining this to us. One of the options I’ve heard about, I really don’t understand this, have you heard of the trillion-dollar coin?

Sarah:
Oh, yes. I love this.

Dave:
What is that? I don’t get it.

Sarah:
The idea is there is a law in the books from 1997, which essentially says that the Treasury Department can mint a coin of absolutely any denomination. This has been floated by a former director of the mint. It’s been called for by some lawmakers, I believe more recently from some Democratic lawmakers. The idea is the Treasury could simply mint a trillion-dollar coin. It could be taken and that could be used to address the national debt.

Dave:
Oh, wait, so is that basically just money printing though, but it’s-

Sarah:
Pretty much. Well, the Fed has to step in and accept this.

Dave:
Okay.

Sarah:
So that’s one uncertainty. I can say point blank that Treasury Secretary Janet Yellen has been asked about this and she’s called it a gimmick, so not really onboard. So it can toss this out the window in reality, though it comes up every couple of years when we talk about the debt ceiling. She’s also said this would be one of those things where you’re overriding the independence of the Fed. So that’s part of it where it just comes down to, okay, so we are not going to get the Treasury secretary to say yes to this. Then at the other side of this is, well, if the US can simply mint a coin of any denomination, what does that mean for the markets moving forward and any future situation the United States might be in, period?

Dave:
Yeah, that seems like a terrible idea. Okay.

Sarah:
So if it is something that’s okay, it’s out there, it might be doable. It’s never been tried before.

Dave:
Oh, I get it. So it’s basically saying that normally, the Fed controls monetary policy. Just for everyone listening, when we talk about Congress and spending by the government, that is fiscal policy. When we’re talking about how much money is in circulation, federal funds rate, stuff we talk about a lot on this show, that is called monetary policy. Usually, the Fed controls money printing, that sort of stuff. So what you’re saying though is there’s basically a loophole where the Treasury, which is part of the executive branch, I don’t even know,-

Sarah:
Yes.

Dave:
Executive branch?

Sarah:
It’s the executive branch under, yes.

Dave:
Okay. So it’s part of the executive branch. Could get through a loophole, print a trillion-dollar coin. Glad to hear that’s not going to happen, but man, they would’ve to have a cool design. I feel like a trillion-dollar coin would have to look pretty cool.

Sarah:
That would be fantastic. I should add the specifics on this is that it has to be platinum.

Dave:
Ooh.

Sarah:
That is also a part of this rule,

Dave:
Baller. Okay.

Sarah:
So yes, a coin of any denomination, but it must be platinum and it must be cool-looking, I’m sure.

Dave:
Yes. Wow.

Sarah:
And the Treasury Secretary has been like, not going to happen.

Dave:
What weird law was like, yeah, you could print anything as long as it’s platinum?

Sarah:
I think it had to do with coin collectors and valuation on that front. That’s a really wonky random loophole and a really random law that just materialized as this debate moved on and now we have lawmakers who are like, that sounds like a potential way to address this ongoing crisis that we face every few years. But no one’s tried it. I think the folks, of course, the Treasury secretary also used to be the chair of the Federal Reserves, Secretary Yellen, so she’s gone mm-mm.

Dave:
Okay. All right. Well, we won’t know what happened, but glad to hear that a trillion-dollar coin is not one of the realistic options.

Sarah:
Not yet. We’ll see where we go in a couple of months, but I’m holding off on that for now.

Dave:
Okay. Well, thank you, Sarah. This has been super helpful. Is there anything else you think our listeners should know about the debt ceiling as it pertains to investors or just everyday Americans?

Sarah:
I think right now, it’s one of those conversations where the bigger problem will need to be addressed in how we go about spending moving forward, but that doesn’t seem to be something that is addressed when we get to this debt limit crisis and counting down the clock to the so-called X date. So big picture, I think there will be conversations about this, about how the US is spending money. But the other aspect of this, I think, is people will yawn when they hear about this now because it’s happened so many times, and it shouldn’t be something that people panic about at this moment. I really don’t think it is at the stage where there should be the panic, but it is a pressing issue and it’s one that will continually to become more and more dire as we get into the coming months. So that is where, take a deep breath now. Stay calm. Don’t change up your pattern so much yet in terms of how you’re spending or your investing at this stage.
I don’t think anyone, when we see these warnings coming out of the White House or Treasury secretary’s office specifically, or Congress are like, “Ooh, need to sell off immediately.” That’s not where we’re at right now, but it is something to keep an eye on moving forward. Everyone says we absolutely cannot default on our debt. Let’s see if they hold that up in Congress and keep on playing a game of chicken moving forward.

Dave:
All right. Well, thank you. This has been super helpful. I have learned a lot. I really appreciate your expertise on this. If people want to follow you and your reporting, where can they learn more about you?

Sarah:
Sure. Well, follow our reporting at CBS News at cbsnews.com, your local stations, our national news. We have the morning show and evening news as well. Then of course, you can always find me on social media @ewallwice. It’s my last name, E-W-A-L-L-W-I-C-E, on both Twitter and Instagram.

Dave:
All right. Thanks again, Sarah.

Sarah:
Thank you.

Dave:
Big thanks to Sarah for joining us for this episode. I learned a ton from this. I learned that I don’t need to be anxious about this just yet, and that we have a couple of months. Even though we had hit the debt limit, the US is still paying its obligations and there is time for Congress to figure this out. I would love to know what you all think about this type of episode. We’re trying something new just to help you stay on top of the important things that impact investors and ordinary Americans related to the economy. This is an important issue, and hopefully you learn something. You can always hit me up on Instagram where I’m @thedatadeli. You can find me on BiggerPockets and send that feedback as well.
Thank you all so much for listening. We’ll see you next time for On The Market. On The Market is created by me, Dave Meyer, and Kailyn Bennett, produced by Kailyn Bennett, editing by Joel Esparza and Onyx Media, researched by Pooja Jindal, and a big thanks to the entire BiggerPockets team. The content on the show On The Market are opinions only. All listeners should independently verify data points, opinions, and investment strategies.


Interested in learning more about today’s sponsors or becoming a BiggerPockets partner yourself? Check out our sponsor page!

Note By BiggerPockets: These are opinions written by the author and do not necessarily represent the opinions of BiggerPockets.


Source link

“Catastrophic” Consequences of the US Defaulting on Its Debt Read More »

Swap ‘I’ For ‘We’ In All Of Your Business Communications

Swap ‘I’ For ‘We’ In All Of Your Business Communications


The words you use in all of your work related communications can have a major impact on how others perceive you, as a leader. And as entrepreneurs, it is really easy to put yourself in the middle of it all, on a pedestal, as the person that founded the company. But as you all should know by now, you are not building your business by yourself, and credit needs to be shared with all, to keep everyone feeling respected and motivated in their day-to-day efforts as part of the company. That all starts with removing the word “I” from your vocabulary, effective immediately.

Defining “I” vs. “We”

According to the Merriam-Webster Dictionary, the word “I” is speaking to one’s SELF, possessing a personal INDIVIDUALITY. And the same source, defines the word “We” as “a GROUP that includes me”. Notice the stark difference between the two: using the word “I” makes it sounds like you are building your business by yourself, and using the word “We” clearly tells others that you are part of a team, that is equally invested in building your company’s success.

What Does That Mean For Your Communications?

Unless you are a solopreneur working by yourself, ditch the word “I”. And, even then, you are most likely working with other outside partners (e.g., investors, bankers, accountants, lawyers, contractors, agencies) in some capacity. And they too want to feel like they are doing their part to participate in your success. So, you too need to swap “I” for “We” when working with anyone that is involved with your business.

What Communications Are We Talking About?

ALL communications need to be amended to remove the word “I”. Verbal conversations by phone, written communications by email, corporate materials that describe the efforts of the business . . . basically everything. You should set up a “swear jar”, that every time you communicate with the word “I”, you have to put a dollar in the jar. For some of you, you may have just found your capital source for your next fundraising needs!!

What is the Result?

Making this change will have a lasting impact on your team. No longer will you be at risk of being perceived as an out-of-touch egomaniac. Instead, you will better motivate your team, instill a sense of self-worth into your employees committed to the company’s success, and promote long term loyalty to your business.

Who am I Speaking To?

You need to look in the mirror, as I am speaking to YOU. Take a look at your last few emails written to your team. Do you see the word “I” anywhere in there? You most likely do!! Stop doing that!! Before you send out your next corporate communication, proof-read it first to make sure the word “I” is nowhere to be found.

Closing Thoughts

For entrepreneurs that have been at the center of their worlds for years on end, this will be a really hard bad habit to break. But if you are religious about removing the word “I” from your vocabulary, your team will take notice, appreciate you including them in your COLLECTIVE success (not your INDIVIDUAL success) and want to work hard WITH you (not FOR you), as a leader that knows the importance your team has in building THE company (not YOUR company). As you can hopefully see now, the words you use with your team really matter.

—

George Deeb is a Partner at Red Rocket Ventures and author of 101 Startup Lessons-An Entrepreneur’s Handbook.


Source link

Swap ‘I’ For ‘We’ In All Of Your Business Communications Read More »

Mortgage rates drop to the 5% range for first time since September

Mortgage rates drop to the 5% range for first time since September


Prospective buyers at an open house in Florida.

Mike Stocker | South Florida Sun Sentinel | Tribune News Service | Getty Images

The average rate on the 30-year fixed rate mortgage has fallen to 5.99%, according to Mortgage News Daily.

The housing market hasn’t seen the rate with a five handle since a brief blip in early September. Before that, it was in early August.

The rate started this week at 6.21% and fell sharply Wednesday after Federal Reserve Chairman Jerome Powell said inflation “has eased somewhat but remains elevated,” which was a shift from previous language.

That sent bond yields lower, and mortgage rates loosely follow the yield on the 10-year Treasury.

“Measured steps can continue as long as the economic and inflation data is there to support them. This means rates can make progress down into the 5’s but are unlikely to stampede quickly into the 4’s,” said Matthew Graham, chief operating officer at Mortgage News Daily. “I’m not saying that won’t happen–just that it would take a bit more time than some of the rate rallies we remember from the past.”

Mortgage rates peaked in October with the 30-year fixed at 7.37% and have been sliding since then. For potential homebuyers that means savings. For a consumer purchasing a $400,000 home today with a 20% down payment, the monthly payment is $293 less than it would have been in October.

Lower rates already appear to be juicing buyer interest.

Pending home sales, which measure signed contracts on existing homes, rose in December for the first time in six months. They gained 2% compared with November, according to the National Association of Realtors. 

Stocks of the nation’s homebuilders have been on a tear since rates started to fall back and several are seeing 52-week highs Thursday. The U.S. Home Construction ETF is hitting a new one-year high, up over 3% on the day.

Homebuilder stocks are also reacting positively to earnings beats reported this week from PulteGroup and last week from the nation’s largest homebuilder, D.R. Horton. Both builders reported seeing renewed buyer interest in December, attributing that to lower mortgage rates.


Source link

Mortgage rates drop to the 5% range for first time since September Read More »

Nine Factors To Consider Before Upgrading Or Replacing Your Business Equipment

Nine Factors To Consider Before Upgrading Or Replacing Your Business Equipment


When it comes time to upgrade or replace your business’s equipment—such as computers, vehicles, tools or anything else your team may use to get the job done—it would be quicker and far simpler to merely purchase the newest model or renew your subscription without much thought. However, to truly ensure you’re getting the best return on investment in terms of cost and team productivity, careful research and reflection is necessary.

But what exactly should you consider before making a purchase? Here, nine members of Young Entrepreneur Council discuss just that, each offering up one factor you should consider first before upgrading or replacing your equipment and why it can ultimately help you make a better decision for your business.

1. What Your Team Really Needs

Ask your team what they really need. I can speak from the perspective of a marketing and software company. We used to buy all sorts of digital tools to make our processes more efficient, but we ended up canceling a lot of subscriptions because a tool is just a tool. It’s pretty much useless if people don’t know how to use it or simply find it inconvenient. Always check in with your team before you decide to upgrade or replace something. What might seem like a good idea to you may not necessarily feel like a helpful improvement for everybody else. – Solomon Thimothy, OneIMS

2. Your Time And Energy

We take the stance that if it will make you more productive or less frustrated, buy it. We work with accounting software and it alone can be annoying as you’re stuck watching the spinning wheel while your report is calculating. With upgrades to hardware, and particularly speed, it will improve the performance of your most expensive asset: your people. – Marjorie Adams, Fourlane

3. Support Availability

If you’re thinking about replacing business equipment, one of the first things you need to think about is support availability. In other words, is support readily available to help you or will you have to wait until Monday (if it’s the weekend)? If it’s a big problem and you have to wait for an answer, you could lose out on profits and the trust of your audience. With this example in mind, it’s easy to see why the way a brand offers support should drive many of the decisions you make for your small business. – John Turner, SeedProd LLC

4. The Impact On Your Clients And Customers

What will the impact be on your clients or customers? In some business areas, it is okay if you avoid upgrading your equipment because the impact on customers may be minimal. However, in other areas, such as technology or customer-service-related fields, it is important to consider your customer’s experience. For example, whenever Google makes a core update to its products, it has a powerful and immediate impact on how people interact with search engines and websites. So, you have to get on board and upgrade your processes or workflows or else you risk being left in the dust. Overall, it is important to consider the customer experience when upgrading or replacing business equipment. – Syed Balkhi, WPBeginner

5. The Cost Versus The Benefit

When it comes time to upgrade or replace business equipment, one factor you should consider first is the cost-benefit analysis. This involves weighing the costs of purchasing and maintaining new equipment against the potential benefits it will bring to the business. It includes the upfront purchase price of the equipment, any financing or leasing options available and the expected lifespan of the equipment. It’s also important to consider the potential impact the new equipment could have on the business, including any potential efficiency gains or productivity improvements. By carefully evaluating the costs and benefits of new equipment, you can make informed decisions about whether the investment is worthwhile and whether it aligns with your business goals. – Candice Georgiadis, Digital Day

6. Scalability

One factor worth considering when you need to upgrade or replace business equipment is scalability. In other words, is it possible to continue growing with the new iteration of the tool? Or will you need to upgrade again in a year or two? Understanding how well a new tool or resource scales is one of the most important things to examine when upgrading your business equipment. – Chris Christoff, MonsterInsights

7. Safety

One factor to consider when it comes time to upgrade or replace your business’s equipment is safety. No matter the equipment you use, it’s important to ensure that it’s safe for your employees and your business in general. It is important to ensure that the equipment meets all safety standards and regulations to protect your employees from potential harm or your business from any confidentiality breach. – Andrew Munro, AffiliateWP

8. The Timing Of The Purchase

Consider the timing. Is it the right time to replace your equipment? That’s a huge investment and your finances must be in good shape before you make such a decision. Not only that, but you must also look at the market to see if it is able to support your big investment. This doesn’t mean that you’re never going to replace your equipment—just that you have to wait for the right time. There are also seasonal reasons to wait because there may be a better time to purchase equipment, like when demand is low and supply is high. You also want to look at the loan terms because it would be practical to upgrade when interest rates are low. Moreover, you have to consider if the available equipment is the latest model because if the latest version is available in less than a year, you might as well wait. – Bryce Welker, Crush The GRE Test

9. Payment Options

Before you invest in costly equipment or technology upgrades, consider other options. For some equipment, leasing is worth considering. You have lower upfront costs and you may have certain services such as repairs included. Leasing is also good if you think you may want to upgrade again in the near future. The leasing company can often provide the upgrade and you don’t have outdated equipment to sell or discard. When it comes to digital services such as software, you can also consider a subscription service, also known as software as a service (SaaS). This is another case where you have lower upfront costs and can count on the company for support. In all such agreements, however, read the terms carefully so you know exactly what is and isn’t included. – Kalin Kassabov, ProTexting


Source link

Nine Factors To Consider Before Upgrading Or Replacing Your Business Equipment Read More »