These Are the Leadership Decisions That Actually Build Trust

These Are the Leadership Decisions That Actually Build Trust


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Customer trust isn’t built through slogans or advertising. It’s built through operational decisions that customers experience every day.
  • It’s easy to believe the next advantage will come from a new feature, a lower price or the latest technology, but that’s rarely what customers remember.
  • Your customers will remember whether your company delivered on its promises. They remember whether the process felt fair. Most of all, they remember whether they trusted you.

Every founder wants a moat. We spend countless hours discussing product differentiation, defensibility, AI, proprietary data and network effects. But after spending the last several years building a company in one of America’s least trusted, most opaque industries, I’ve come to believe we’ve been asking the wrong question. The most durable competitive advantage isn’t what you build. It’s whether customers believe you. 

In industries where customers feel confused, skeptical or taken advantage of, trust becomes the moat. But trust isn’t built through slogans or advertising. It’s built through operational decisions that customers experience every day. Unlike most competitive advantages, trust compounds. 

Why opaque industries create the greatest leadership test

Many industries remain opaque, not because they are inherently complicated, but because opacity has historically been profitable. Complexity creates leverage. If customers don’t understand how something works, they can’t easily compare offers, evaluate fairness or recognize hidden costs. Confusion does the heavy lifting. Businesses no longer have to earn trust because complexity protects them from scrutiny. That’s when companies begin optimizing for information asymmetry, margin extraction, low accountability and short-term transactions instead of long-term relationships. 

Gold is one example, but it doesn’t stand alone. Healthcare, car sales, real estate, financial services and online payments also often rely on opacity, leaving customers frustrated and wondering whether they made the right decision. The harder a market is for customers to understand, the easier it becomes for weak leadership to hide behind complexity.

This means rebuilding trust requires leadership, not better marketing.

The leadership decisions that build trust

When I started Alloy, I wasn’t trying to become “the transparent company.” I was trying to answer two questions:

  • Who benefits from opacity?
  • What breaks if we remove it?

The reason Alloy has earned repeat customers and word-of-mouth referrals isn’t that buying gold suddenly became easier. It’s not. It’s because we made leadership decisions that prioritized long-term trust over short-term convenience.

Transparency over margin maximization

Unlike many competitors, we chose to explain our pricing, process and expectations, even when doing so made negotiations more difficult. Conventional wisdom says transparency weakens your position because customers have more information. We found the opposite. When people understand how decisions are made, they’re more likely to trust the outcome, even if it isn’t exactly what they hoped for.

That philosophy led us to build online valuation calculators that allow customers to estimate the value of their items before they ever request a mailer. The calculators aren’t just a convenience. They’re an extension of our belief that uncertainty shouldn’t be part of the buying process.

Transparency often makes individual transactions harder. Customers ask more questions. They negotiate more. Some decide not to sell at all. But over time, transparency makes the business easier because customers stop wondering what you’re hiding. When people trust the process, every conversation starts from a stronger foundation.

Systems over discretion

Instead of leaving evaluations open to individual interpretation, we standardized them so outcomes wouldn’t depend on who happened to answer a customer’s call that day. Every offer is based on the same defined criteria rather than personal discretion. Standardizing the process reflected the kind of company we wanted to build. Customers shouldn’t have to wonder whether they’d receive a different offer if they spoke to someone else.

Consistency gives people confidence that they’re being treated fairly, regardless of who they interact with. The goal wasn’t to eliminate judgment. It was to make sure every decision reflected the same standards. When fairness isn’t left to individual judgment, trust grows.

Operational rigor over speed

Early on, we resisted the temptation to grow faster than our systems could support. Like many startups, we felt pressure to move quickly, expand and scale. But we also knew that every operational weakness would become more visible as the business grew. Scaling inconsistent experiences only magnifies problems.

Instead, we invested time in refining our processes, documenting clear standards and building systems that could deliver the same level of service every time. Those investments weren’t always visible to customers, but they shaped every interaction they had with us.

Growing quickly is exciting. Growing consistently is much harder. We learned early that every shortcut becomes more expensive as a company scales. Investing in strong systems upfront wasn’t always the fastest path, but it meant we could grow without asking customers to absorb the cost of our growing pains.

That isn’t just our experience. Research from PwC similarly argues that trust isn’t owned by marketing. It’s created through leadership decisions, operational discipline and accountability across the organization.

We designed every interaction assuming customers were comparing us to the worst experience they’d ever had, not our closest competitor. That mindset helped to frame everything, from how we communicated expectations to how we handled questions and difficult conversations. Every decision was filtered through a simple question: Does this make the customer feel more informed, more respected and more confident?

It’s simple to optimize a business for transactions. It’s much more difficult to optimize for trust. We believed that creating a better experience wouldn’t just improve a single sale; it would create repeat customers, referrals and a reputation that competitors couldn’t easily replicate.

Visibility over plausible deniability

We quickly learned that leadership should never be insulated from operational mistakes. It was important to us that if customers experience friction, leaders should feel it too. It’s easy to build layers that shield executives from day-to-day problems, but every layer of distance makes it harder to understand what customers are actually experiencing. 

We made it a priority to stay close to customer feedback, because operational blind spots don’t disappear on their own. They grow. When leaders have visibility into what’s working and what isn’t, accountability becomes part of the culture rather than a response to a crisis. 

Transparency leaves leaders with fewer places to hide, and that’s exactly the point.

Trust is the only moat that gets stronger when shared

Technology eventually catches up. Prices get matched. Features become commodities, and even today’s AI advantage will narrow as competitors adopt the same tools. Most competitive advantages have a shelf life.

Trust behaves differently. The more consistently a company earns it, the more valuable it becomes. Competitors can copy products, pricing models and even customer experiences, but they can’t instantly replicate the culture, operational discipline and leadership decisions that created years of credibility.

PayPal is a good example. It didn’t invent online payments. It helped make them mainstream by reducing perceived risk through buyer protection, fraud prevention and greater transparency around digital transactions. The technology mattered, but widespread adoption happened because people trusted the experience.

The same principle applies across industries. Customers don’t simply adopt new products because they’re available. They adopt them when they believe the company behind them has earned their confidence.

By the time trust becomes part of your reputation, it’s already the product of countless decisions your competitors can’t easily see or recreate.

The takeaway

Every founder wants a moat. While most look outward, the strongest ones build inward.

It’s easy to believe the next advantage will come from a new feature, a lower price or the latest technology. Those things matter, but they’re rarely what customers remember. They remember whether your company delivered on its promises. They remember whether the process felt fair. Most of all, they remember whether they believed you.

Leadership isn’t about building systems that maximize advantage over customers. It’s about building organizations that deserve their confidence. Every decision, from how you communicate to how you respond when something goes wrong, either reinforces or erodes trust. That’s the kind of moat no competitor can replicate overnight.

In a world where nearly everything can be copied, trust remains one of the few competitive advantages that still has to be earned.

Key Takeaways

  • Customer trust isn’t built through slogans or advertising. It’s built through operational decisions that customers experience every day.
  • It’s easy to believe the next advantage will come from a new feature, a lower price or the latest technology, but that’s rarely what customers remember.
  • Your customers will remember whether your company delivered on its promises. They remember whether the process felt fair. Most of all, they remember whether they trusted you.

Every founder wants a moat. We spend countless hours discussing product differentiation, defensibility, AI, proprietary data and network effects. But after spending the last several years building a company in one of America’s least trusted, most opaque industries, I’ve come to believe we’ve been asking the wrong question. The most durable competitive advantage isn’t what you build. It’s whether customers believe you. 

In industries where customers feel confused, skeptical or taken advantage of, trust becomes the moat. But trust isn’t built through slogans or advertising. It’s built through operational decisions that customers experience every day. Unlike most competitive advantages, trust compounds. 

Why opaque industries create the greatest leadership test

Many industries remain opaque, not because they are inherently complicated, but because opacity has historically been profitable. Complexity creates leverage. If customers don’t understand how something works, they can’t easily compare offers, evaluate fairness or recognize hidden costs. Confusion does the heavy lifting. Businesses no longer have to earn trust because complexity protects them from scrutiny. That’s when companies begin optimizing for information asymmetry, margin extraction, low accountability and short-term transactions instead of long-term relationships. 


Source link

These Are the Leadership Decisions That Actually Build Trust Read More »
3 Kinds of Deals I Turn Down — Even When Everything in the Room Says Yes

3 Kinds of Deals I Turn Down — Even When Everything in the Room Says Yes


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • The hardest investment decisions aren’t rejecting obvious failures — they’re walking away from opportunities where the product works, the founder is convincing, and the room is leaning forward, but the cost structure, the market, or the founder’s judgment quietly signals the risk is bigger than it looks.
  • Momentum in the pitch room doesn’t translate to durability in the business — and the investors who last are the ones who trust their pattern recognition on the three quiet failure signals (unforgiving cost structure, a founder you want to believe but can’t fully back, and a saturated market with entrenched incumbents) over the excitement of the moment.

Some of the best investment decisions I’ve made never show up anywhere. No press release. No board seat. No update email celebrating traction. Just a quiet “no” on something that, in the moment, felt very close to a “yes.”

That’s the part of investing that doesn’t get talked about enough. The discipline to walk away when everything in the room is leaning forward. When the founder is convincing, the idea is compelling and the momentum starts to build in a way that makes hesitation feel like a mistake.

After years of investing in early-stage companies, sitting through countless pitches and working closely with founders at every stage, one thing becomes clear: Attractive opportunities carry their own kind of risk. Sometimes more.

Here are three kinds of deals I walk away from, and why.

1. A great product with the wrong cost structure

One of the more interesting ideas I came across was a rapid hydration test for athletes. It was clever, easy to understand and had real consumer appeal. You could picture it on shelves. You could imagine the branding. It checked a lot of boxes very quickly. Then you started to peel it back. What did it take to manufacture at scale? What did distribution look like? How much capital was required just to get to a point where the market could even react? The answers weren’t easy (or cheap).

I’ve seen this pattern enough to know how it plays out. The idea gets attention, maybe even early excitement, but the business underneath it demands constant funding just to stay alive long enough to prove anything. That kind of pressure compounds quickly. It narrows your margin for error to almost nothing.

A similar situation came up with a custom furniture concept built around CNC technology. The output was impressive. High-quality, scalable in theory, differentiated from traditional manufacturing. But the financial engine behind it required heavy upfront investment, operational precision, and time. A lot of time.

In both cases, the product worked on paper. The economics created a different story. Risk doesn’t always sit in the idea. Sometimes it’s buried in what it takes to make the idea real.

2. A founder you want to believe, but can’t fully back

You meet a founder who is charismatic, driven and absolutely convinced they are onto something big. They communicate well. They create energy in the room. They sell the vision in a way that makes you want to lean in. And then something feels off. I’ve learned to pay attention to that.

One founder I met was building a business tied to a major social platform. The concept made sense. The timing felt right. The delivery, though confident, came across as “off” to me. He tipped over into abrasiveness; his answers may have been right for all I know, but they had an edge. And when he started asking me for introductions, I wasn’t ready to have my name tied to his. Regardless of the idea, I don’t want to be in business with people like this.

Then there are the one-dimensional founders. The brilliant scientist with a breakthrough idea but no grasp of how to build a company around it. The operator who understands execution but is stepping into a technical space without the depth to navigate it. Both scenarios create gaps that are hard to close under pressure.

In one case, I looked at a healthcare concept involving at-home testing. Interesting model, real potential, completely outside my lane. That alone became a deciding factor. If I can’t understand the underlying risk, I have no business pretending I can manage it.

There are also smaller signals that tend to show up early. A founder hiring a COO before a product even exists. Loose thinking around expenses. A financial plan that feels more like a placeholder than a strategy. Individually, these things might seem manageable. Together, they paint a picture.

First-time founders absolutely can and do succeed. Some build extraordinary companies. But experience leaves marks, and those marks matter. Founders who have been through failure often carry a different level of awareness, a sharper sense of what can go wrong and how quickly things can unravel. In early-stage investing, you are not just backing an idea. You are underwriting a person’s judgment.

3. A strong concept entering an unforgiving market

Some opportunities check every box you expect: a clear product, a capable founder, a clean pitch and early signs of traction. You walk into the meeting expecting to find something wrong, only to find something that holds together. Then you look at the market.

I spent time with several founders in the skincare space who had built thoughtful, well-positioned products with good branding and a clear audience. They had a solid understanding of what they were trying to do. But they were stepping into a category dominated by companies with massive R&D budgets, global distribution and deep customer loyalty. The kind of incumbents that don’t just compete; they absorb. Breaking through in that environment requires more than a good product. It requires a level of differentiation and staying power that can withstand sustained pressure from players who operate at a completely different scale.

That’s where the risk lives. Your product might work; it might be the best skin care product ever conceived, but it might still have no real path to visibility, adoption and longevity once it hits the market. Saturation has a way of compressing outcomes. It turns good ideas into background noise.

The discipline behind the decision

Walking away from these deals wasn’t about finding obvious flaws. Each one had elements that could have worked. That’s what makes these decisions difficult. You’re not rejecting failure. You’re passing on potential, and that’s where discipline comes in.

Founders are wired to sell a vision. Sometimes that vision stretches far beyond what’s realistic in the near term. That’s part of the role. They have to believe. They have to push. The investor’s role is different. You can trust the founder. You can respect the ambition. You can even believe the idea has merit and still decide the risk profile doesn’t align.

Over time, you realize momentum in the room doesn’t translate to durability in the business and excitement has the ability to amplify risk. The longer you stay in this world, the more you understand that saying no is the difference between staying in the game and chasing something that was never going to get there.

Key Takeaways

  • The hardest investment decisions aren’t rejecting obvious failures — they’re walking away from opportunities where the product works, the founder is convincing, and the room is leaning forward, but the cost structure, the market, or the founder’s judgment quietly signals the risk is bigger than it looks.
  • Momentum in the pitch room doesn’t translate to durability in the business — and the investors who last are the ones who trust their pattern recognition on the three quiet failure signals (unforgiving cost structure, a founder you want to believe but can’t fully back, and a saturated market with entrenched incumbents) over the excitement of the moment.

Some of the best investment decisions I’ve made never show up anywhere. No press release. No board seat. No update email celebrating traction. Just a quiet “no” on something that, in the moment, felt very close to a “yes.”

That’s the part of investing that doesn’t get talked about enough. The discipline to walk away when everything in the room is leaning forward. When the founder is convincing, the idea is compelling and the momentum starts to build in a way that makes hesitation feel like a mistake.

After years of investing in early-stage companies, sitting through countless pitches and working closely with founders at every stage, one thing becomes clear: Attractive opportunities carry their own kind of risk. Sometimes more.


Source link

3 Kinds of Deals I Turn Down — Even When Everything in the Room Says Yes Read More »

I Went to a ,000 Retreat for 9-Figure Founders in Italy

I Went to a $14,000 Retreat for 9-Figure Founders in Italy


Key Takeaways

  • The OOAK Mastermind conference took place in late August in Tuscany.
  • In order to attend, founders had to apply and pay $14,000 in conference fees.
  • The event was geared towards founders of seven- to nine-figure founders who want to take their businesses to the next level.

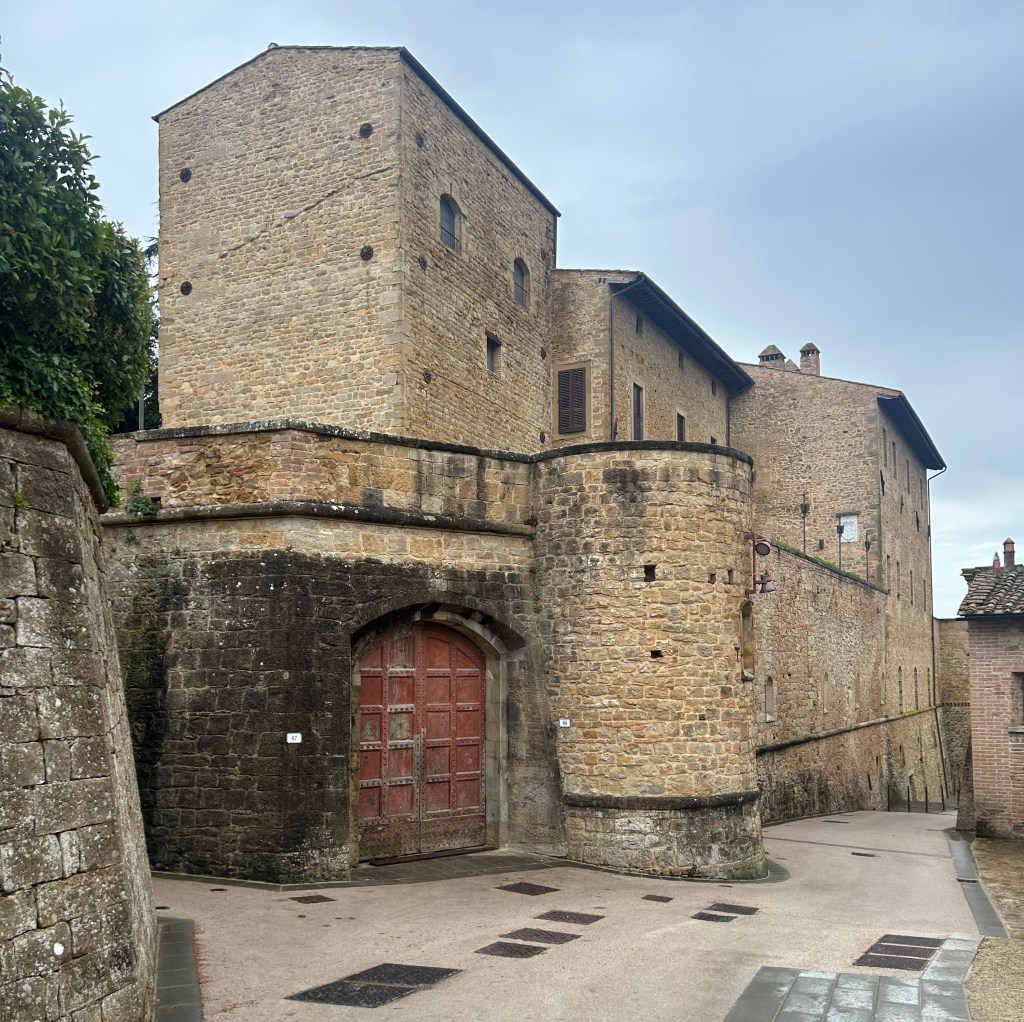
I first saw the hotel Castelfalfi from the back of a cab, its stone exterior rising out of the Tuscan hills. Inside waited founders who collectively generate more in annual revenue than some small countries — and each had paid thousands of dollars for the privilege of being there.

On paper, I had no business being at a $14,000 retreat for seven- to nine‑figure founders in Tuscany. I don’t run a massive consumer goods brand or a unicorn startup, and my net worth is far from impressive. But when I was invited to sit in on three days of keynote sessions and fireside chats at the OOAK Mastermind conference, I couldn’t turn down the chance to see what happens when ultra‑successful founders gather behind closed doors.

OOAK Mastermind was hosted by OOAK, short for One Of a Kind. The global consumer brand-building company creates, scales and acquires brands.

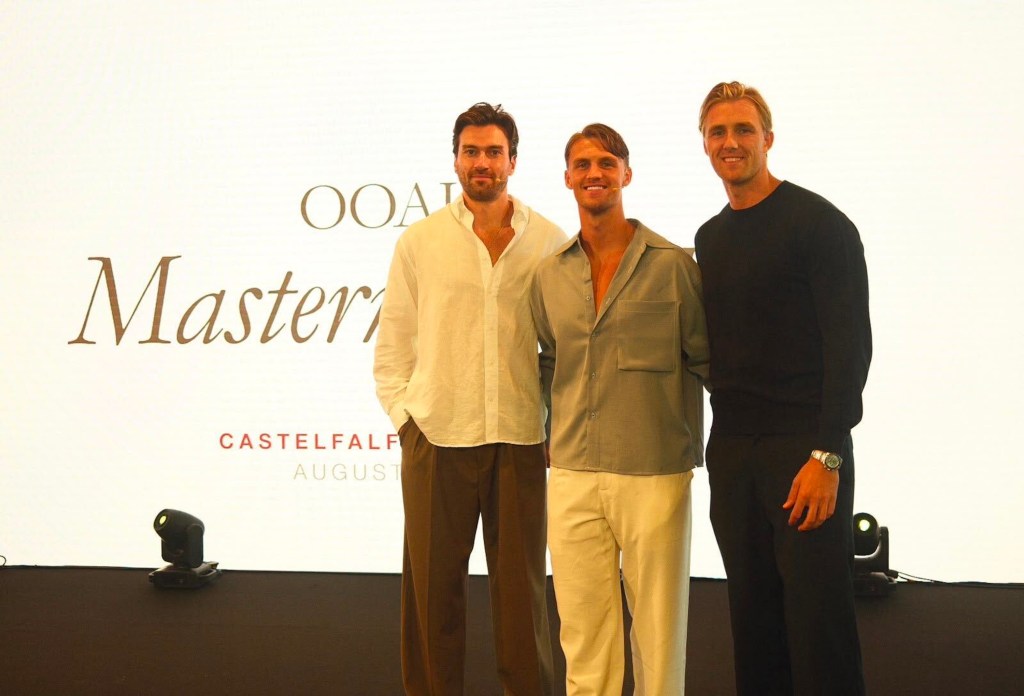
The three co-founders of OOAK were everywhere at this event. Bob Verlaat, Nick Nijhof and Vince Nijhof delivered the keynotes and moderated the fireside chats. The three of them are actually best friends from childhood; Nick and Vince are brothers.

OOAK founders: (left to right) Bob Verlaat, Vince Nijhof and Nick Nijhof.

The three founders came up with the idea for this event after hosting two smaller iterations in Dubai. They originally intended to keep this conference small, with only a few dozen participants, but kept attracting more interest and selling out.

What surprised me most was how young everyone was. Vince, Nick and Verlaat are all under 30 years old, and they were able to attract an audience of about 100 young founders.

The experience 

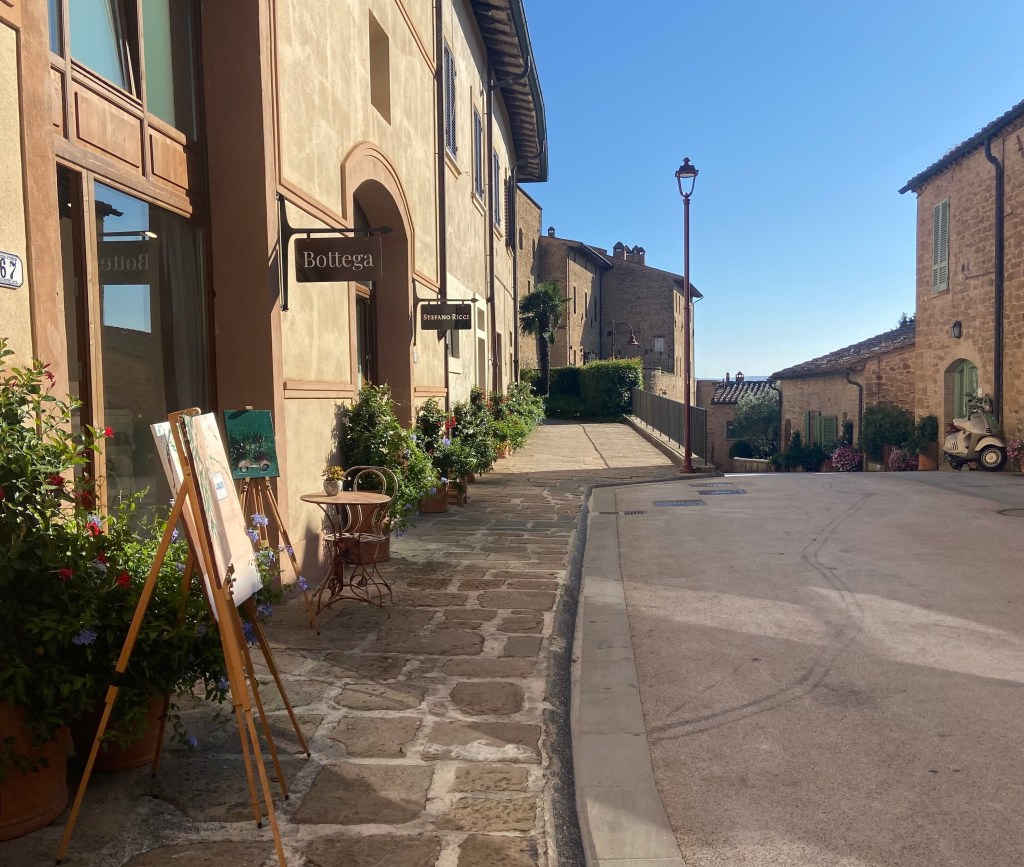
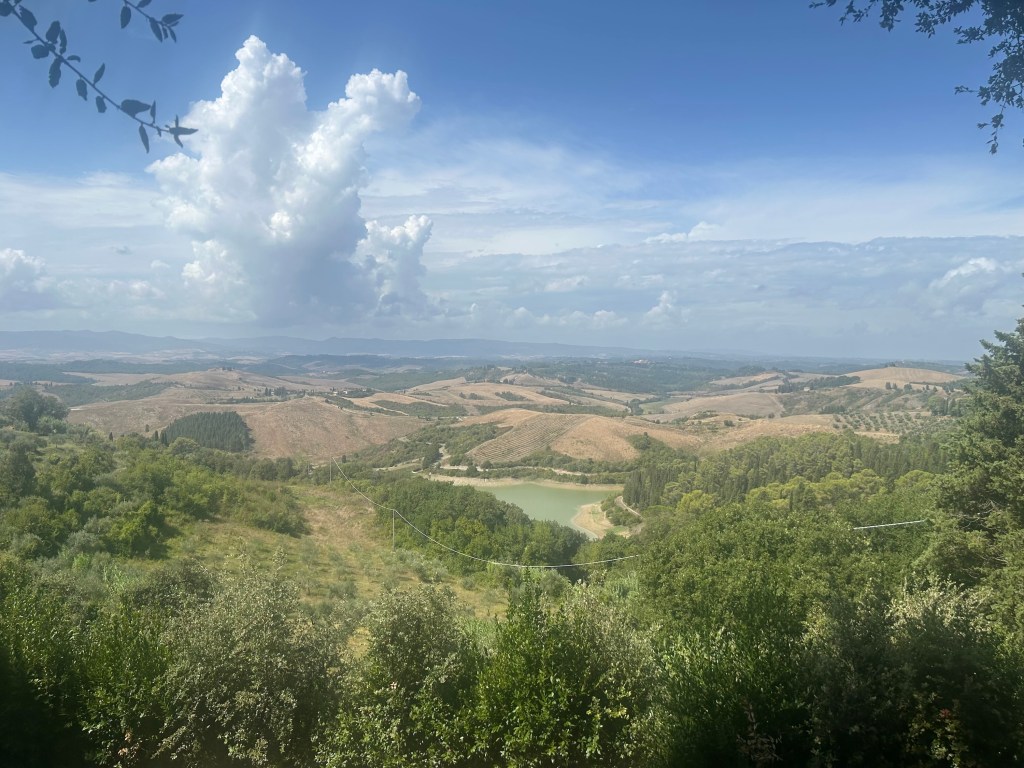
The event was at the Castelfalfi resort in the heart of Tuscany, Italy. The village of Castelfalfi was a five-minute walk from the hotel and featured a row of shops ranging from a clothing store to a gelato shop. Everywhere I looked, there were scenic views. 

Event participants paid $14,000 for five-star accommodations, meals and airport transfers. Attendees had to apply and have a proven track record of leading a seven- to nine-figure brand.

Besides the three OOAK founders, speakers at the event included Jeff Srithongrung, director of creative strategy at TubeScience, and Ray Jang, founder and CEO at AI ad company Atria. Srithongrung spoke about how to run an effective ad campaign and the benefits of changing an ad to appeal to different audiences. Jang spoke about the transformative effect of AI in advertising and said that AI has reduced the cost of testing concepts and trying new things to “close to zero.”

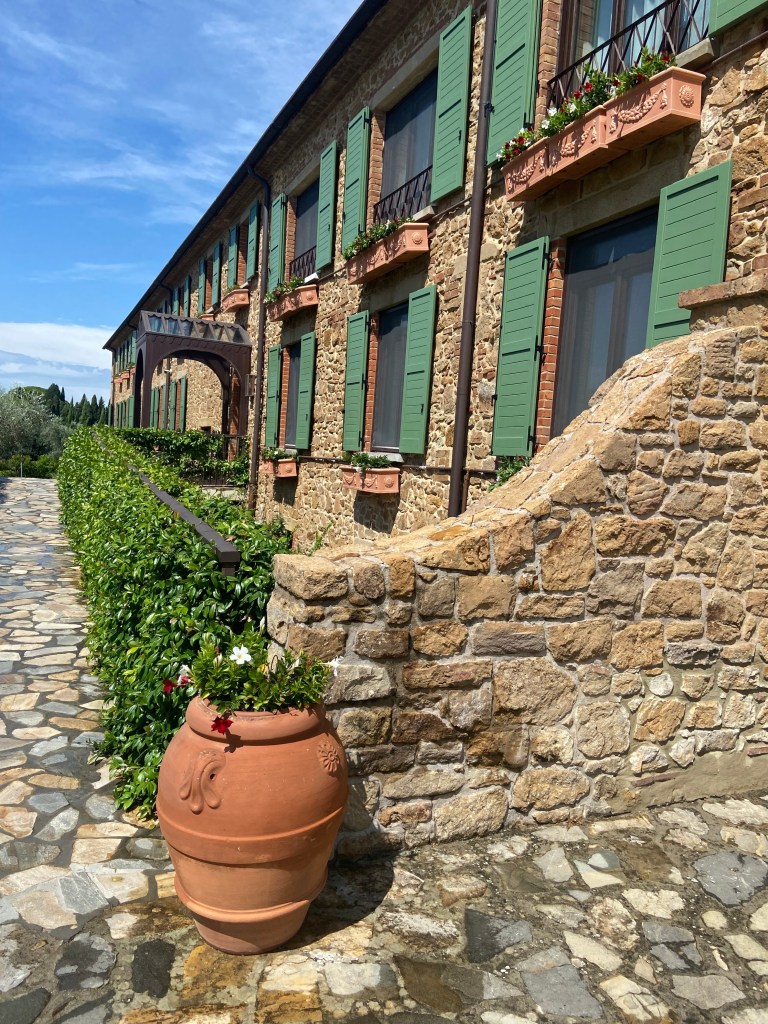
This was where I stayed.
The Castelfalfi resort
A row of shops in the village.

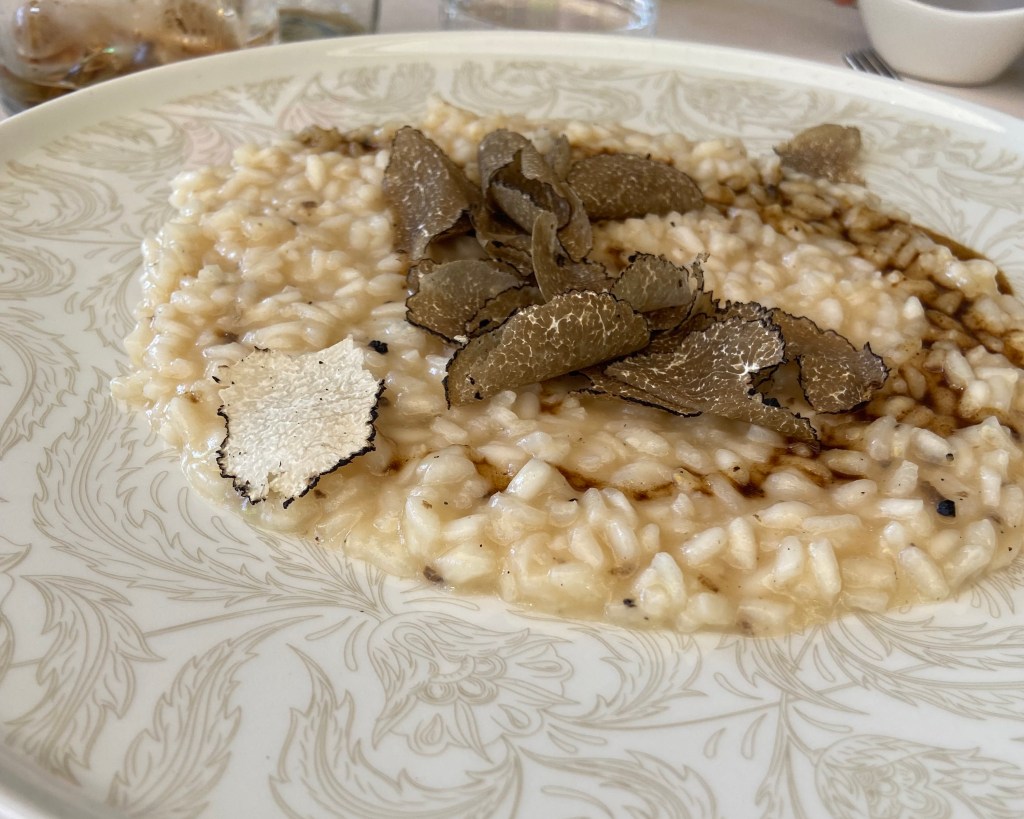
On Saturday afternoon, I joined the conference participants for a truffle-filled lunch: We had beef tartare with truffle as a starter, truffle risotto for the main course and vanilla truffle mousse for dessert. I sat with founders working on selling everything from supplements to gold. 

Truffle risotto.
Truffle risotto.
One part of the Castelfalfi village
One part of the Castelfalfi village.
The view
The view.

One attendee spoke about his success

Most event participants were brand founders. One speaker, 32-year-old Alvaro Gellings, revealed that he built an apparel brand and sold $1.4 million worth of products within the first hour of launch. He then built a sportswear brand called Day One and tapped into a partnership with German creator and endurance athlete Arda Saatçi. Gellings, who was also an attendee at the conference, knew that selling sportswear required more than just having a quality product. 

“Nobody’s looking for the next gym tank to buy,” he says. “Nobody’s in urgent need of the next T-shirt, the next socks, the next shoes. You have to create a story.”

Gellings created a highly publicized story: Saatçi would run 1,960 miles from Berlin to New York. 

He would start in Berlin and run across Europe to Porto, Portugal, then take a flight from Porto to Boston. For the final stretch, he would run from Boston to New York. He would do it all while wearing Day One sportswear, and the company’s official launch would be tied to him completing his run.

It took Saatçi 74 days in 2024 to complete the task. The ad campaign had “everyone posting,” Gellings says. It was a prime example of how companies can leverage partnerships with influencers to make their brands more recognizable and focus on the story, not the product. 

Framing products in new ways

The OOAK co-founders hosted a number of talks at the retreat, and I sat down with the trio before the event started to hear more about their entrepreneurial journeys.

Even if you don’t know OOAK, you may recognize one of their portfolio brands, like earplug company Hears and sleepwear startup Dore & Rose. Verlaat, Nick and Vince founded Dore & Rose in 2022, followed by Hears in 2023 and subsequently grouped the businesses under the holding company OOAK.

Verlaat oversees brand, creative direction and positioning while Nick handles product and people and Vince focuses on growth, paid acquisition and supply chain execution. 

“We all had a very separate skill set [when we started], and we still have [that],” Verlaat says.

He added that his blueprint for launching brands, his core thesis, was to take a “boring” product and frame it differently. For example, the founders position Dore & Rose as a premium sleep-wellness brand rather than a conventional bedding retailer, selling mulberry-silk sleep products infused with silver ions. They emphasize overnight skin recovery and restorative sleep.

The founders took a relatively familiar product, the silk pillowcase, and pushed it toward an emotionally richer category: beauty, wellness and sleep quality. It’s a silk pillowcase brand positioned as beauty, not bedding. 

Hears applies the same playbook to hearing protection: It sells earplugs for music, nightlife and event environments but positions them as a premium lifestyle product rather than a mere accessory. Its public narrative is about enjoying music clearly and confidently while protecting hearing. The founders repositioned the earplugs as a fashion product, not a medical device.

The outcome

So far, the way they market their products is paying off: The founders disclosed that OOAK Brands is making a combined yearly revenue of $100 million. They are targeting $200 million this year. 

In addition, they have sold over one million silk items through Dore & Rose and have placed their silk products in 50 five-star hotels, like Four Seasons, Belmond and Cheval Blanc. Dore & Rose has partnerships with over 150 retailers, including Nordstrom, Mecca and Namshi.

Meanwhile, Hears hit $7 million in revenue in its first year, 2024. Since then, the brand has sold more than 250,000 pairs of earplugs. Hears partnered with the Hearing Health Foundation to donate a portion of revenue and raise awareness for hearing protection. 

Their advice

Verlaat’s advice for potential founders waiting to make the leap is to “just do it.” “What’s the worst thing that could happen, really?” he says. “You don’t die.” 

He says that he knew from the start that he would succeed. “We always believed that we’re going to get to where we are today.”

Vince pursued entrepreneurship because he “wanted to work and make money.”

“I wanted to just go harder,” he says. “For me, I think I figured out really, really soon that working for a boss was not going to cut it for me.”

Nick was candid that founders needed to “wear multiple hats,” especially in the early stages of building a business. He is also an advocate of just getting started, even if a founder doesn’t have everything figured out. “You don’t need to see the finish line. You don’t need to know where it will end,” he says. “As long as you know your next step, eventually you will get there.”

Key Takeaways

  • The OOAK Mastermind conference took place in late August in Tuscany.
  • In order to attend, founders had to apply and pay $14,000 in conference fees.
  • The event was geared towards founders of seven- to nine-figure founders who want to take their businesses to the next level.

I first saw the hotel Castelfalfi from the back of a cab, its stone exterior rising out of the Tuscan hills. Inside waited founders who collectively generate more in annual revenue than some small countries — and each had paid thousands of dollars for the privilege of being there.

On paper, I had no business being at a $14,000 retreat for seven- to nine‑figure founders in Tuscany. I don’t run a massive consumer goods brand or a unicorn startup, and my net worth is far from impressive. But when I was invited to sit in on three days of keynote sessions and fireside chats at the OOAK Mastermind conference, I couldn’t turn down the chance to see what happens when ultra‑successful founders gather behind closed doors.

OOAK Mastermind was hosted by OOAK, short for One Of a Kind. The global consumer brand-building company creates, scales and acquires brands.


Source link

I Went to a $14,000 Retreat for 9-Figure Founders in Italy Read More »

Business Formations Are at Record Highs — and the Fastest-Growing States Aren’t the Ones You’d Guess

Business Formations Are at Record Highs — and the Fastest-Growing States Aren’t the Ones You’d Guess


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • AI and remote work have erased the two biggest reasons founders used to move to Silicon Valley or New York — access to talent and access to tools — leaving affordability, tax climate, and quality of life as the real deciding factors.
  • The fastest-growing states for new business formation aren’t the traditional hubs but places like Wyoming, Oregon, Mississippi and North Dakota, signaling that entrepreneurial wealth creation is being redistributed across America in ways that reward founders willing to look past the coasts.

From movies to novels, we’ve been told that a business sprouts best in the most fertile garden. In The Social Network, Mark Zuckerberg drops out of Harvard and heads west to grow Facebook in the new tech hub of Palo Alto. The Great Gatsby finds rural North Dakota boy James Gatz moving to Long Island to build his business and reinvent himself in the process.

These may be works of fiction, but in real life the startup guide has been the same for decades. If you wanted to launch a successful business, you went where the opportunity was. In this vein, Silicon Valley became synonymous with innovation. New York dominated finance and media. Boston excelled in biotechnology, and so on.

Today, that assumption is extinct. AI, cloud computing and the adoption of remote work have changed the dynamics of starting a business. Founders no longer need to be in a major civic hub to access trained talent, sophisticated business tools or even global markets. Aspiring founders are now choosing where to build companies based on affordability, operating costs and lifestyle.

More than 548,000 new U.S. business formations took place this past June, the strongest June on record, and nearly 3.5 million through the first half of the year. But the interesting trend is where many of those businesses are launching. States like Oregon, Mississippi and North Dakota posted some of the nation’s strongest year-over-year growth, while Wyoming remains a magnet for new business formations, especially LLCs and out-of-state ventures. These hotspots underscore that entrepreneurial momentum is becoming more geographically diverse.

AI changes the economics of company building 

Until just a few years ago in the pre-ChatGPT world, launching a startup usually required hiring employees or outsourcing work. Entrepreneurs needed analysts to conduct market research, programmers to develop websites, designers to create marketing materials, writers to produce content and customer service reps to serve as liaisons. Now AI allows founders, even solo or two-person ventures, to perform many tasks themselves before making their first hires.

Let’s be clear: This doesn’t replace expertise or eliminate the value of seasoned employees, but it does significantly lower the cost and complexity of going to market. This means that one of the strongest advantages of traditional startup ecosystems – access to large pools of talent and cash – is no longer essential to nurture a company through its earliest stages.

Remote work unchains employees from offices

Along with powerful AI tools, post-COVID remote work has altered another enduring business assumption: that employers and employees must share the same offices. Many founders now recruit nationally or globally, customizing their teams based on expertise rather than ZIP codes. Software developers can work in Colorado, designers in North Carolina, accountants in Texas. Meanwhile, a company’s leaders can operate somewhere else, nearly anywhere they’d like.

This flexibility gives entrepreneurs something previous generations rarely had: the freedom to choose where they want to live without impeding access to talent. Instead of asking themselves, “Where do I need to move to build my company?” founders now ask, “Where can my company give me a strategic advantage?” and “Where do I want to operate from?”

Geography still matters for different reasons

As they say in real estate, it’s still about “location, location, location.” Geography continues to matter in many ways, but not because of specialized business hubs.

Lower commercial rents reduce overhead. Business-friendly tax policies improve cash flow. Decreased housing costs benefit founders and staff alike. Shorter commutes and better access to bike lanes and outdoor recreation can improve quality of life and help prevent burnout amid the nascent years of company building.

For entrepreneurs bootstrapping a business, every dollar they can save on overhead is a dollar that can be invested in product/service development, hiring or customer acquisition. Cities don’t have an irresistible magnetic pull anymore because they’re the preeminent hub for tech, finance or anything else. Unless your vision is a location-based business like a restaurant, retail shop or amusement park, more and more founders are unshackled by a “required” location.

Build where you can thrive

Business formation data suggests that the redistribution of entrepreneurship is accelerating. Communities that historically struggled to attract startups now find themselves competing on strengths that matter to today’s entrepreneurs: affordability, broadband connectivity, favorable tax climates and a high quality (and often slower pace) of life.

Wealth creation is becoming increasingly democratized, pushing into previously overlooked parts of America with a surge in LLC formations. Today, successful companies are as likely to emerge from midsize cities, suburban communities or even rural regions as from traditional metropolitan corridors.

Entrepreneurs have always been encouraged to “Think differently.” With a leg up from AI and remote work, that mindset is extending into where they plan.

Key Takeaways

  • AI and remote work have erased the two biggest reasons founders used to move to Silicon Valley or New York — access to talent and access to tools — leaving affordability, tax climate, and quality of life as the real deciding factors.
  • The fastest-growing states for new business formation aren’t the traditional hubs but places like Wyoming, Oregon, Mississippi and North Dakota, signaling that entrepreneurial wealth creation is being redistributed across America in ways that reward founders willing to look past the coasts.

From movies to novels, we’ve been told that a business sprouts best in the most fertile garden. In The Social Network, Mark Zuckerberg drops out of Harvard and heads west to grow Facebook in the new tech hub of Palo Alto. The Great Gatsby finds rural North Dakota boy James Gatz moving to Long Island to build his business and reinvent himself in the process.

These may be works of fiction, but in real life the startup guide has been the same for decades. If you wanted to launch a successful business, you went where the opportunity was. In this vein, Silicon Valley became synonymous with innovation. New York dominated finance and media. Boston excelled in biotechnology, and so on.

Today, that assumption is extinct. AI, cloud computing and the adoption of remote work have changed the dynamics of starting a business. Founders no longer need to be in a major civic hub to access trained talent, sophisticated business tools or even global markets. Aspiring founders are now choosing where to build companies based on affordability, operating costs and lifestyle.


Source link

Business Formations Are at Record Highs — and the Fastest-Growing States Aren’t the Ones You’d Guess Read More »

Ardente: recensione e reputazione tra i giocatori

La domanda di ricerca

Questa analisi esamina che cosa si possa stabilire su Ardente a partire dai documenti di ricerca conservati: quale identità operativa viene attribuita al marchio, quali elementi riguardano il mercato italiano e quanto siano solide le informazioni disponibili sulla sua reputazione tra i giocatori.

L’obiettivo non è formulare un giudizio promozionale né trasformare singole indicazioni in una valutazione definitiva. La domanda centrale è più circoscritta: quali fatti e quali dichiarazioni risultano documentati, quali aspetti rimangono incerti e come dovrebbe interpretarli un lettore alle prime armi?

Ardente: recensione e reputazione tra i giocatori

Metodo e criteri di valutazione

La ricerca utilizza esclusivamente i record conservati nel dossier su Ardente. Il materiale dichiara di avere incrociato il registro ufficiale delle licenze di Curaçao relativo ad Antillephone, un’analisi tecnica dei pacchetti di dati per la sicurezza SSL/TLS e una raccolta di discussioni online: oltre 25 discussioni su Reddit e più di 15 discussioni su forum italiani, osservate negli ultimi sei mesi rispetto alla ricerca registrata.

Questa descrizione del metodo è riportata dal record di verifica della ricerca e non viene qui trattata come una nuova verifica indipendente. Inoltre, il dossier indica come ultimo aggiornamento giugno 2024 e registra, tra le modifiche, la verifica dello stato della licenza Antillephone N.V. Di conseguenza, il risultato va letto come una fotografia documentale riferita a quel perimetro temporale, non come una verifica automatica dello stato attuale.

I criteri adottati sono quattro:

  • identificabilità dell’operatore e della licenza dichiarata;
  • chiarezza della struttura societaria riportata;
  • distinzione tra il contesto internazionale attribuito al marchio e quello italiano;
  • qualità dell’evidenza sulla reputazione dei giocatori e sugli strumenti di tutela descritti.

Che cosa riportano i documenti su Ardente

Licenza e soggetto operativo

Il record dedicato alle autorizzazioni riporta che Ardente Casino opera sotto la giurisdizione di Curaçao e attribuisce al marchio una licenza rilasciata da Antillephone N.V., con numero 8048/JAZ. La formulazione è quella del documento di ricerca: non viene trasformata in una garanzia generale sulla qualità del servizio, sulla protezione del giocatore o sull’accessibilità del marchio nel mercato italiano.

Un secondo record identifica l’entità legale dietro Ardente come Ardente N.V., o come una società di gestione equivalente, con sede legale indicata ad Abraham de Veerstraat 9, Willemstad, Curaçao. Anche questa informazione deve essere mantenuta nel suo corretto livello di certezza: il dossier la presenta come identificazione societaria attribuita, non come un’analisi autonoma degli assetti proprietari. Nel dossier, l’entità legale di https://ardenteit.com e l’entità legale è indicata come Ardente N.V. (o società di gestione equivalente), con sede legale ad Abraham de Veerstraat 9, Willemstad, Curaçao.

Struttura societaria e collegamenti con altri marchi

La struttura del gruppo è uno degli aspetti meno definiti nei materiali conservati. Il dossier riferisce che Ardente viene spesso collegato a siti consorelli che opererebbero sotto la stessa sublicenza Antillephone, ma aggiunge che i legami di governance rimangono opachi.

Per un lettore inesperto, la distinzione è importante. Un collegamento riportato tra marchi non equivale automaticamente a una proprietà comune dimostrata, né permette di ricostruire da solo chi prenda le decisioni operative. Il record stabilisce quindi l’esistenza di una lacuna informativa segnalata dalla ricerca, non una conclusione definitiva sulla titolarità del gruppo.

Il rapporto con il mercato italiano

Un record del dossier descrive Ardente come un operatore globale con un focus aggressivo sul mercato italiano. La frase va attribuita alla ricerca conservata e non deve essere letta come una misurazione indipendente della quota di mercato, della presenza pubblicitaria o del numero di giocatori italiani.

Lo stesso materiale colloca Ardente, nel contesto italiano, in una “zona grigia” e sostiene che la promozione di siti privi di licenza italiana sarebbe vietata secondo il Decreto Dignità e successive circolari ADM. Il record collega questa interpretazione all’assenza del marchio dai media tradizionali e alla dipendenza da canali Telegram e siti di recensioni estere.

Questa è una valutazione giuridica e di mercato contenuta in una nota di ricerca: non viene presentata come una determinazione legale autonoma di questo articolo. Il dossier fornito non include una verifica corrente nell’elenco ADM dei concessionari autorizzati. Pertanto, i materiali disponibili non stabiliscono lo stato attuale di Ardente rispetto alla concessione italiana.

Che cosa si può dire sulla reputazione dei giocatori

La reputazione è il punto in cui il dossier richiede maggiore prudenza. Il record metodologico dichiara di avere monitorato discussioni su Reddit e forum italiani, ma non fornisce nel materiale disponibile una sintesi numerica dei giudizi, una classificazione dei commenti o un risultato aggregato che consenta di definire la reputazione di Ardente come positiva o negativa.

Di conseguenza, la ricerca documenta un’attività di raccolta di conversazioni, ma non stabilisce una reputazione generale tra i giocatori. Le discussioni online possono essere una fonte di segnali e di domande da approfondire; nel dossier, però, non sono riportati contenuti sufficienti per attribuire al pubblico italiano un orientamento univoco.

È altrettanto importante non confondere la popolarità menzionata nella nota sulle lacune informative con una prova di affidabilità o di soddisfazione. Il dossier riferisce una crescente popolarità e, nello stesso tempo, segnala lacune informative significative. Le due affermazioni non producono da sole una valutazione complessiva del marchio.

La conclusione più fedele all’evidenza è quindi limitata: esiste una traccia di monitoraggio di comunità e forum, ma il materiale fornito non contiene abbastanza risultati per misurare la reputazione dei giocatori. Qualunque recensione che trasformasse questi dati metodologici in un voto o in un verdetto generale andrebbe oltre le fonti disponibili.

Strumenti di gioco responsabile riportati

Il dossier descrive una politica di gioco responsabile di Ardente che fornirebbe collegamenti a strumenti di autolimitazione. Secondo il record conservato, gli utenti possono richiedere un periodo di pausa da 24 ore a 30 giorni oppure l’autoesclusione permanente contattando il supporto all’indirizzo support@ardente.com.

La stessa nota afferma che l’implementazione sarebbe meno granulare rispetto a quella dei siti ADM. Anche questo è un giudizio attribuito al record di ricerca, non una misurazione indipendente condotta per questo articolo. Il dossier non permette quindi di convertire tale confronto in una valutazione complessiva della sicurezza del marchio.

Per chi legge una recensione, il significato pratico è soprattutto documentale: la ricerca conservata riporta l’esistenza di opzioni di pausa e autoesclusione, ma non offre una verifica aggiornata del loro funzionamento in ogni situazione. Non è inoltre corretto usare la presenza di uno strumento come prova di un’esperienza uniforme per tutti gli utenti.

Limiti, incertezze e interpretazioni da evitare

Il primo limite riguarda il tempo. L’ultimo aggiornamento indicato è giugno 2024; licenze, domini, politiche e assetti operativi possono richiedere una verifica specifica al momento della consultazione, mentre il dossier non fornisce una verifica successiva.

Il secondo limite riguarda la struttura societaria. Ardente N.V. viene indicata come entità legale o società di gestione equivalente, ma i collegamenti con eventuali siti consorelli sono descritti come opachi. Non è quindi possibile ricavare dal materiale una mappa certa della governance.

Il terzo limite riguarda la distinzione tra licenza e mercato. La licenza Curaçao attribuita ad Antillephone N.V. e il numero 8048/JAZ sono elementi riportati nel dossier; non costituiscono, da soli, una prova della presenza di una concessione ADM o della conformità a ogni requisito applicabile agli utenti italiani.

Il quarto limite riguarda la reputazione. Il monitoraggio di discussioni non equivale alla disponibilità di un campione rappresentativo. Nel materiale conservato non sono riportati un metodo di ponderazione dei commenti, una distribuzione dei giudizi o una verifica indipendente dell’identità degli autori.

Infine, la ricerca dichiara di essere stata condotta indipendentemente da analisti senior del settore del gioco. Questa è una dichiarazione di trasparenza attribuita al dossier; non sostituisce la lettura critica delle singole fonti né amplia ciò che i record permettono di stabilire.

Conclusione: che cosa stabilisce davvero la ricerca

I documenti conservati descrivono Ardente come un marchio associato a una licenza Curaçao attribuita ad Antillephone N.V. e a un’entità indicata come Ardente N.V. Riportano inoltre una presenza orientata al mercato italiano, ma accompagnata da una valutazione sulla sua collocazione normativa e da una lacuna nella chiarezza dei rapporti societari.

Sulla reputazione dei giocatori, il risultato è più ristretto: il dossier riferisce un monitoraggio di Reddit e forum italiani, ma non fornisce dati sufficienti per sostenere un giudizio generale. Anche gli strumenti di gioco responsabile sono descritti attraverso una nota attribuita, senza una verifica aggiornata della loro applicazione.

In sintesi, la ricerca offre elementi identificativi e alcune dichiarazioni operative, ma non stabilisce un verdetto complessivo su Ardente. Per un lettore principiante, la distinzione tra fatto riportato, interpretazione attribuita e informazione non stabilita è il risultato più importante dell’analisi.

Mini-FAQ

Qual è il principale risultato della ricerca su Ardente?

Il dossier riporta una licenza Curaçao attribuita ad Antillephone N.V., numero 8048/JAZ, e identifica Ardente N.V. come entità legale o società di gestione equivalente. Non stabilisce però una reputazione generale tra i giocatori.

Il monitoraggio dei forum dimostra che Ardente ha una buona reputazione?

No. Il record metodologico riferisce il monitoraggio di discussioni su Reddit e forum italiani, ma il materiale fornito non contiene risultati aggregati sufficienti per definire la reputazione come positiva o negativa.

La ricerca chiarisce i rapporti tra Ardente e altri siti?

Solo in parte. Una nota riferisce collegamenti con siti consorelli sotto la stessa sublicenza Antillephone, ma afferma anche che i legami di governance rimangono opachi. La struttura proprietaria completa non è quindi stabilita.

Che cosa viene riportato sul gioco responsabile?

Il dossier descrive strumenti di autolimitazione, un periodo di pausa da 24 ore a 30 giorni e l’autoesclusione permanente tramite supporto. La stessa nota attribuisce alla ricerca un confronto meno favorevole con i siti ADM, senza fornire una verifica aggiornata del funzionamento.

Ardente: recensione e reputazione tra i giocatori Read More »

Queen: sicurezza dei giocatori e gioco responsabile

La domanda di ricerca

Per un giocatore principiante, valutare la sicurezza di Queen significa distinguere ciò che è documentato da ciò che resta da verificare. La domanda affrontata in questa analisi è quindi circoscritta: quali segnali relativi alla tutela del giocatore e al gioco responsabile sono riportati nei documenti disponibili per il mercato italiano, e quali conclusioni non possono essere tratte da tali informazioni?

Il nome “Queen” richiede inoltre una verifica preliminare dell’identità. La nota di ricerca segnala che il brand viene cercato anche come “Queen Casinò” e “Queen Casino online” e che le ricerche rilevate sono soprattutto di tipo navigazionale e transazionale, con riferimento a luglio 2026. La stessa nota invita a non confondere la piattaforma italiana con entità internazionali omonime, tra cui Emerald Queen Casino, situato a Tacoma negli Stati Uniti, o Casino Queen. Questa distinzione è importante: una policy o una licenza associata a un soggetto diverso non sarebbe automaticamente pertinente.

Queen: sicurezza dei giocatori e gioco responsabile

Metodo e criteri di valutazione

La metodologia descritta nella ricerca consiste nell’incrocio di dati ufficiali, indicati come registri ADM e Termini e Condizioni dell’operatore, con le informazioni della comunità. Si tratta della metodologia riportata nella nota di ricerca conservata, non di una nuova verifica svolta per questo articolo.

Per rispondere alla domanda sono stati considerati quattro criteri:

  • la presenza di un riferimento alla regolazione del gioco a distanza in Italia;
  • la disponibilità dichiarata di documenti su condizioni, privacy e trattamento dei dati;
  • la presenza di uno strumento di autoesclusione collegato al sistema italiano;
  • la distinzione tra un segnale documentale e una prova dell’effettivo funzionamento quotidiano dei controlli.

Questi criteri non misurano la qualità complessiva dell’esperienza, la correttezza di ogni singola operazione o l’efficacia concreta dei controlli in ogni circostanza. Servono invece a ordinare le evidenze disponibili e a chiarire il loro peso.

Cosa riportano i documenti sulla regolazione

La ricerca conservata riferisce che Queen Casinò opera in Italia tramite la Concessione ADM numero 15221. La formulazione è attribuita alla nota di ricerca: non viene trasformata qui in una verifica autonoma o in una garanzia generale di sicurezza. La stessa nota descrive il brand come gestito da una società a responsabilità limitata registrata in Italia e colloca la sede legale e operativa principale a Roma.

Questi elementi sono pertinenti perché collegano l’operatore al contesto italiano del gioco a distanza. Tuttavia, un riferimento alla concessione non dimostra da solo ogni aspetto della protezione del giocatore. Nel materiale disponibile non è riportato un audit tecnico indipendente, non sono forniti risultati di test sui sistemi e non sono presentate misurazioni sull’efficacia degli strumenti di gioco responsabile. Perciò il dato sulla concessione va letto come un’informazione regolatoria riportata, non come una conclusione totale sulla sicurezza.

La nota descrive inoltre la piattaforma come strutturata esclusivamente per il mercato italiano e riferisce che non accetta registrazioni da indirizzi IP esteri non autorizzati o da giocatori privi di un Codice Fiscale italiano valido. Anche questo è presentato come una caratteristica dichiarata nella ricerca. Il dossier non stabilisce però come vengano gestiti tutti i casi di accesso, né consente di valutare l’affidabilità operativa dei controlli geografici o anagrafici.

Documenti e trasparenza delle regole

Secondo la nota dedicata alle policy, i Termini e Condizioni generali di Queen Casinò sono redatti in italiano e descritti come conformi alle direttive ADM sulla tutela del consumatore. La stessa nota riferisce che i collegamenti alle policy sono accessibili dal piè di pagina della pagina iniziale. I Termini e Condizioni in italiano di https://queencasinoplay-it.com sono descritti come conformi alle direttive ADM sulla tutela del consumatore.

La disponibilità di condizioni in italiano è un elemento utile per un principiante: rende più semplice consultare le regole applicabili senza dipendere da una traduzione informale. Non equivale, però, a dimostrare che ogni clausola sia stata compresa o che ogni procedura venga applicata in modo uniforme. Il dossier non fornisce una valutazione giuridica indipendente delle condizioni e non riporta l’esito di un controllo sistematico delle singole clausole.

La ricerca riferisce anche che, in conformità al GDPR europeo e alla normativa italiana antiriciclaggio, la piattaforma espone una Privacy Policy e una Cookie Policy. La formulazione resta attribuita alla nota conservata. Da questo elemento si può desumere soltanto che tali documenti sono indicati come presenti; il materiale fornito non stabilisce la qualità della loro attuazione, la rapidità delle risposte o l’esito di eventuali richieste degli utenti.

Gioco responsabile e autoesclusione

Il segnale più direttamente collegato al gioco responsabile è quello relativo al Registro Unico Autoesclusi ADM. La ricerca descrive la presenza, nel piè di pagina, di un collegamento al registro e riferisce che il sistema consente ai giocatori l’autoesclusione temporanea o a tempo indeterminato, con validità trasversale su tutti i concessionari italiani.

Questa informazione è rilevante perché l’autoesclusione trasversale non viene presentata come una funzione limitata al singolo marchio, ma come uno strumento collegato al sistema italiano. La frase precedente mantiene tuttavia il livello di certezza della fonte: è la nota di ricerca a descrivere la presenza del collegamento e la portata dello strumento. Il dossier non documenta prove pratiche dell’attivazione, dei tempi di applicazione o della procedura attuale per revocare o modificare una scelta.

Per un lettore inesperto, è utile non confondere la presenza di un riferimento al Registro Unico Autoesclusi con una valutazione del comportamento di gioco. Il registro è uno strumento istituzionale di autoesclusione; non costituisce una misurazione delle abitudini dei giocatori e non consente di stabilire, sulla base dei dati forniti, quanto spesso venga utilizzato o quale effetto produca nel singolo caso.

Le lacune informative più importanti

La fase iniziale della ricerca ha identificato tre lacune informative nelle query degli utenti: i tempi effettivi di elaborazione dei prelievi tramite PostePay rispetto ai tempi pubblicizzati, la procedura esatta per lo sblocco dei conti durante la verifica KYC e i requisiti reali di scommessa associati ai codici promozionali e ai bonus senza deposito.

Queste lacune sono riportate per spiegare quali domande restano aperte, non per affermare che esista un problema in ciascuna area. Il dossier non fornisce dati sufficienti per stabilire i tempi effettivi dei prelievi, descrivere una procedura di sblocco o determinare i requisiti di scommessa. Di conseguenza, nessuna di queste questioni può essere usata per formulare una valutazione positiva o negativa sull’operatore.

La distinzione è particolarmente importante nell’analisi della sicurezza. Un testo promozionale, una discussione della comunità o una pagina di condizioni possono fornire indicazioni diverse per natura e attendibilità. La metodologia conservata parla di un incrocio tra fonti ufficiali e informazioni della comunità, ma non presenta nel dossier un campione, una distribuzione dei casi o una verifica indipendente delle segnalazioni. Le informazioni della comunità, quindi, non possono essere trasformate in una misura generale delle prestazioni del servizio.

Come leggere correttamente le evidenze

Un primo errore consiste nel trattare la concessione ADM riportata dalla ricerca come una garanzia assoluta. Il dato segnala un collegamento dichiarato con il quadro regolatorio italiano, ma non sostituisce la consultazione delle informazioni ufficiali aggiornate né una verifica dell’identità del dominio al momento della pubblicazione.

Un secondo errore consiste nel considerare la presenza di Privacy Policy, Cookie Policy e Termini e Condizioni come prova dell’efficacia dei controlli. I documenti sono un segnale di trasparenza formale secondo la nota di ricerca; il dossier non esamina la loro applicazione concreta.

Un terzo errore è confondere l’autoesclusione con un sistema di controllo delle decisioni del giocatore. La ricerca descrive uno strumento di autoesclusione collegato al Registro Unico Autoesclusi ADM, ma non fornisce elementi per valutare il comportamento individuale, l’uso dello strumento o l’impatto nel tempo.

Infine, non è corretto trasferire automaticamente informazioni da marchi omonimi esteri a Queen Casinò per il mercato italiano. La disambiguazione geografica è parte del controllo iniziale e deve precedere qualunque valutazione su regolazione, policy o gioco responsabile.

Limiti dell’analisi

Questa analisi utilizza esclusivamente le informazioni presenti nel dossier conservato. L’ultimo aggiornamento indicato nella ricerca è luglio 2026, ma il materiale non contiene una verifica successiva o una consultazione in tempo reale. Le affermazioni relative a concessione, struttura societaria, policy, geolocalizzazione e Registro Unico Autoesclusi sono riportate come esiti della nota di ricerca e non come accertamenti autonomi svolti in questa sede.

Il dossier non stabilisce i tempi di prelievo tramite PostePay, la procedura di sblocco durante il KYC o i requisiti di scommessa dei bonus. Non stabilisce neppure l’efficacia tecnica dei controlli, la frequenza degli episodi problematici o la qualità complessiva dell’assistenza. Questi limiti impediscono di trasformare i segnali disponibili in un punteggio di sicurezza o in un verdetto generale.

Conclusione

Le evidenze conservate descrivono tre livelli distinti. Sul piano regolatorio, la ricerca riporta il riferimento alla Concessione ADM numero 15221 e colloca Queen Casinò nel mercato italiano. Sul piano documentale, riferisce la presenza di Termini e Condizioni in italiano, Privacy Policy e Cookie Policy. Sul piano del gioco responsabile, descrive un collegamento al Registro Unico Autoesclusi ADM, con autoesclusione temporanea o a tempo indeterminato e validità trasversale secondo la fonte.

Questi elementi rispondono in parte alla domanda sulla sicurezza dei giocatori, ma non la esauriscono. Il dossier offre segnali documentali e regolatori attribuiti alla ricerca; non offre una prova indipendente dell’efficacia quotidiana dei controlli né dati sufficienti sulle tre lacune informative individuate. Per un principiante, la conclusione più rigorosa è quindi mantenere separati i fatti riportati, le procedure non documentate e ciò che resta da verificare nelle fonti ufficiali al momento della consultazione.

Mini-FAQ

Qual è il principale criterio usato nell’analisi?

L’analisi confronta i riferimenti regolatori, le policy dichiarate e gli strumenti di gioco responsabile riportati nel dossier, distinguendo questi segnali dalle prove sull’effettiva applicazione quotidiana.

La Concessione ADM numero 15221 è stata verificata autonomamente?

No. La ricerca conservata riferisce il riferimento alla concessione, ma questo articolo non presenta una verifica autonoma o aggiornata del dato.

Che cosa stabilisce il dossier sull’autoesclusione?

La nota di ricerca descrive un collegamento al Registro Unico Autoesclusi ADM e riferisce un’autoesclusione temporanea o a tempo indeterminato con validità trasversale sui concessionari italiani. Non documenta invece prove pratiche sui tempi o sull’attivazione.

Il dossier chiarisce la procedura KYC e i tempi dei prelievi?

No. La ricerca identifica questi temi come lacune informative e non fornisce elementi sufficienti per descrivere la procedura di sblocco o stabilire i tempi effettivi dei prelievi tramite PostePay.

Queen: sicurezza dei giocatori e gioco responsabile Read More »

How I Became a Verified 7-Figure Short-Selling Day Trader

How I Became a Verified 7-Figure Short-Selling Day Trader


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • After being diagnosed with a brain tumor at 25, my life changed completely. I had surgery and took my renewed chance at life to turn it into the exact one I wanted.
  • Success is not an overnight phenomenon. It requires rigorous discipline and sacrifice.

Some of the hallmarks of a successful entrepreneur include the ability to self-actualize through rigorous study, continuous learning, relentless tenacity and the resilience to rebound after setbacks. 

I know this firsthand. At 25, my goals were set in stone. I knew what I wanted: a career in architecture. At the time, I was enrolled in UCLA’s master’s program in architecture, studying and working on projects nonstop, setting the bar as high as I could. The renowned Pritzker Prize-winning architect Thom Mayne was my mentor. I was at the top of my game.  

Then, overnight, I received the blow of a lifetime: I was diagnosed with a brain tumor that required immediate surgical intervention. When I awoke, staring at the cold, clinical hospital ceiling, I had 150 stitches on the side of my head and was unable to move. However, I was able to discern two searing sentences of a conversation between my mother and the surgeon. 

“What have you done to my son?” My mother railed at the doctor. 

“I have given him 50 more years of life,” the doctor replied decisively. 

From that moment on, I knew I had to make that 50-year gift count. After taking half a year off from my studies, I returned to class with renewed zeal — and mounds of debt. Despite the appearance of gradual recovery, I had a long road ahead. 

Still, I was determined to make the most of every moment. But the medical bills kept piling up, and I was forced to make a drastic change — a pivot to a high-income skill. While searching online, I found day trading, which I understood less than nothing — but not for long. I studied the discipline for countless hours, delving into books, podcasts and YouTube videos until my brain hurt. I became so assiduous and single-minded that I knew I had to go further and immerse myself completely in my new focus. 

By sheer force of will and necessity, I absented myself from everything and everyone I knew. My colleagues and friends thought I had taken leave of my senses. My family didn’t know what had become of me. I sold my car, changed my number and ensconced myself in an office in an LA skyscraper for $230/month. 

“What happened to David?” echoed faintly in my ears, carried by the grapevine. But I didn’t care what anyone thought. I had “burned the boats,” as Hernán Cortés told the Conquistadors in the 16th century. There was no turning back. I had survived life-altering surgery; now my future was on the line, and I had to shape and claim it. 

To support my new venture, I took on odd jobs as a tutor and an Uber driver. The landlord kept knocking on my door, and the creditors couldn’t wait. While these practicalities held sway, I worked day and night, sleeping on the floor of my office to ensure wakefulness at the market open.  

In my personal life, I became a minimalist — again, not by choice, but by necessity. For example, when the world went into lockdown during the Covid-19 pandemic, all the gyms were closed, and I had nowhere to shower. So, I resorted to Skid Row. Stoic and poker-faced, I walked through the streets of downtown L.A., intent on reaching my destination undisturbed. I had 10 minutes to shower and then return to monitor my trades. Everything was the trade. 

When I wasn’t trading, I read voraciously and studied into the night, honing my skills, journaling and envisioning. The Law of Attraction was central to my approach. I truly believed — as I still do — that what I projected in my mind’s eye would manifest. And so it did: I became a high-stakes, 7-figure day trader with a 90%-win rate.  

However, success was not an overnight phenomenon. It required rigorous discipline and sacrifice. Some might say my tactics were extreme, but I had no choice. I had to become an autodidact, front-loading all my strategies and literally devising them. The result was a set of proprietary winning strategies that I share in my book, Short Selling Master: Proven Strategies from a High-Stakes Day Trader (Harriman House). 

My objective: to vanquish the 96% failure rate in my industry by providing cogent strategies for success. Today, I have become the mentor I never had, with the opportunity to witness others advance in the field and attain financial freedom.

Some might say that my unique methodology for attaining success — a compelled absence from mainstream society — was extreme. Indeed, that plan took all the fortitude I could muster. In no guise do I advocate such a plan for my students or other aspiring traders. But looking back, I have absolutely no regrets. Hard work and ingenuity led me to where I am today. I hearken back in gratitude while moving forward and lifting others up.  

Key Takeaways

  • After being diagnosed with a brain tumor at 25, my life changed completely. I had surgery and took my renewed chance at life to turn it into the exact one I wanted.
  • Success is not an overnight phenomenon. It requires rigorous discipline and sacrifice.

Some of the hallmarks of a successful entrepreneur include the ability to self-actualize through rigorous study, continuous learning, relentless tenacity and the resilience to rebound after setbacks. 

I know this firsthand. At 25, my goals were set in stone. I knew what I wanted: a career in architecture. At the time, I was enrolled in UCLA’s master’s program in architecture, studying and working on projects nonstop, setting the bar as high as I could. The renowned Pritzker Prize-winning architect Thom Mayne was my mentor. I was at the top of my game.  

Then, overnight, I received the blow of a lifetime: I was diagnosed with a brain tumor that required immediate surgical intervention. When I awoke, staring at the cold, clinical hospital ceiling, I had 150 stitches on the side of my head and was unable to move. However, I was able to discern two searing sentences of a conversation between my mother and the surgeon. 


Source link

How I Became a Verified 7-Figure Short-Selling Day Trader Read More »

Why Formula E Thinks It Can Beat Formula One at Its Own Game

Why Formula E Thinks It Can Beat Formula One at Its Own Game


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • In just 12 years, Formula E has gone from a niche all-electric experiment that needed two cars to finish a race to a global championship with hundreds of millions of fans and cars that top 200 miles per hour.
  • Formula E’s mission is baked into its DNA: it is the world’s first sport to earn B Corp certification and works as a real-time test lab for EV innovation.

The idea of an all-electric racing championship used to sound like science fiction, and in its debut season, Formula E’s cars needed a mid-race swap just to make it to the checkered flag.

“12 years ago, if someone said we’re going to create an all-electric racing championship, people might have thought you were absolutely crazy,” says Jeff Dodds, CEO of Formula E.

At the time, just 300,000 electric vehicles were sold worldwide and, according to Dodds, “they weren’t very good.” 

“In our first season, we needed to have two cars to finish a race, because the battery wouldn’t last long enough,” he recalls.

Today, the technology has improved dramatically. Around 22 million EVs are expected to be sold this year, with BloombergNEF forecasting that figure could reach 35-40 million annually by 2030.

The transition is already accelerating in markets worldwide. And Formula E has spent the past 12 years positioning itself in the driver’s seat.

Altering the Formula 

Before joining Formula E, Dodds spent years in the automotive industry, working for Volvo and later Honda, where he became deeply immersed in motorsport.

“We had our own Formula One team, MotoGP, British Superbikes, touring cars—they had everything,” he recalls.

That background explains why Dodds doesn’t view Formula One as a threat. If anything, he sees it as the benchmark for elite motorsport

“Believe it or not, whilst I was an F1 fan, I also followed Formula E before I came to work here,” Dodds says. “I have a good appreciation for the journey that Formula One’s been on,” he adds. “We’re similar, and then we’re very different.”

F1 and Formula E both use open-wheel, single-seater Formula racing cars. But there are some major distinctions. The main one is obvious from the name: Formula E is an all-electric racing league, while Formula One uses traditional internal combustion to power its cars. 

This doesn’t just reduce Formula E’s carbon footprint — it changes the racing product itself. With limited energy at their disposal,  the world’s best drivers must decide when to conserve and when to push, adding another layer of strategy to wheel-to-wheel racing. Dodds likens it to “a game of chess on the racetrack.”

He believes this appeals to racing fans differently than F1. “F1, for me, is nostalgic,” Dodds explains. “I know the drivers. I know their journeys. I love the locations they race at. Perhaps the bit I like least about it is the actual racing.”

He compares many F1 races to a “procession,” where fans often have a good idea of who will win before the engines start.

Formula E, by contrast, places a premium on parity.

“If you say to me, ‘Who do you think is going to win the London race?’ I legitimately would say it could be anybody.” Dodds says. “Everyone has a chance of winning that race. That’s pretty rare in motorsport.”

Races are designed to last under an hour, with plenty of overtakes and the kind of “thrills and spills” that can hold the attention of viewers accustomed to faster-paced entertainment.

Those differences are reflected in Formula E’s audience. Its fan base skews younger, is split nearly 50-50 between men and women, and has a particular interest in technology, sustainability and innovation. That audience has also attracted the attention of media giants. On August 11, Formula E, Disney+ and ESPN announced a landmark multi-year agreement that will make Disney+ the global streaming home of the ABB FIA Formula E World Championship across 144 territories. In the U.S., races will stream on Disney+ alongside ESPN+ beginning with the 2026/27 season.

“I don’t mean to be disparaging because I watch it and enjoy it,” Dodds says, “but I don’t find F1 anywhere near as exciting as I find us.”

Speed without sacrifice

What sets Formula E apart from many companies now embracing sustainability is that its mission wasn’t created in response to a trend. Sustainability has been at the championship’s core from the beginning.

“If you’re a big business that decides you want to become more sustainable, that’s a very worthy thing,” Dodds says. “But you’re trying to reverse-engineer a more sustainable approach into your processes and the way you work. We’ve only ever had it as a core tenet of our business.”

Formula E was built around three goals: create an elite global racing championship, help accelerate the transition from combustion engines to electric vehicles and become the world’s most sustainable sport.

More than a decade later, Dodds believes the organization has a strong case for achieving that last goal. Formula E is the only sport in the world certified as a B Corp. This designation recognizes companies meeting high standards for social and environmental performance while committing to continuous improvement. 

Sustainability is embedded throughout the race weekend. Events are powered by hydrogenated vegetable oil, single-use plastics are eliminated on-site, and the cars are charged using renewable energy. Formula E says its Gen4 car will also be 100% recyclable or reusable.

“My personal view is when people hear ‘sustainable,’ they often hear compromise,” Dodds says. “They think the product’s going to be more expensive, or not as good, because you’re trying to do it sustainably. And I think we are a brilliant argument against that, because we produce the fastest-selling race cars in the world and the most exciting racing, while being the most sustainable sport.”

World’s most exciting test lab 

The racing is entertaining, but it isn’t what makes Formula E important. Much of the championship’s impact happens off the track, where it works alongside some of the world’s largest automakers to test EV technology that can eventually find its way into consumer vehicles.

Formula E has six manufacturers competing in its championship: Porsche, Jaguar, Nissan, Stellantis, Yamaha and Mahindra.

“One of the reasons they’re in is they treat the racetrack like a laboratory for testing technology that can make its way into their road cars,” Dodds explains. 

“If you look at the latest Porsche Cayenne Turbo, it’s the most powerful production Porsche ever released — and it’s all-electric,” Dodds says. “It’s an incredible piece of machinery, and a lot of the technology in that car has been developed through, or come out of, Porsche’s Formula E program.”

He also mentions Formula E’s work with Jaguar’s I-Pace, where Jaguar discovered a way to install over-the-air software updates to their cars from an iPhone. “This is where we are in terms of the cutting-edge nature of the technology,” Dodds says. “You know, things are being developed and discovered on our racetrack that will find their ways into your cars incredibly quickly.”

Zero to 100

Dodds admits it’s difficult to imagine just how far Formula E could go. After all, the championship’s first 12 years have already produced growth that once seemed unimaginable.

“12 years ago, we had zero fans, zero TV audience, and a car. You needed two cars to do a race. The car finished at 130 miles an hour,” Dodds shares. “Ten years on, you’ve got 420 million fans, over half a billion TV audience, and you’ve got a car that accelerates to 100 kilometers in 1.6 seconds and races well over 200 miles an hour. It’s inconceivable how far we’ve come.”

Because of this, Dodds is reluctant to put hard limits on Formula E’s long-term growth. In an industry moving as quickly as electric vehicles, he believes setting objectives too far into the future can be more constraining than helpful.

“I definitely have an ambition, but I wouldn’t want to constrain that by tethering us to a set of targets that are too low,” he says. They’ve already gone from zero to 100 incredibly quickly. It’s impossible to tell how fast they’ll grow now.

Key Takeaways

  • In just 12 years, Formula E has gone from a niche all-electric experiment that needed two cars to finish a race to a global championship with hundreds of millions of fans and cars that top 200 miles per hour.
  • Formula E’s mission is baked into its DNA: it is the world’s first sport to earn B Corp certification and works as a real-time test lab for EV innovation.

The idea of an all-electric racing championship used to sound like science fiction, and in its debut season, Formula E’s cars needed a mid-race swap just to make it to the checkered flag.

“12 years ago, if someone said we’re going to create an all-electric racing championship, people might have thought you were absolutely crazy,” says Jeff Dodds, CEO of Formula E.

At the time, just 300,000 electric vehicles were sold worldwide and, according to Dodds, “they weren’t very good.” 


Source link

Why Formula E Thinks It Can Beat Formula One at Its Own Game Read More »

Atas Review and Player Reputation

Research question

This review asks what the supplied research records establish about Atas and its player reputation in Malaysia. The focus is not on promotional claims or personal experience. Instead, it examines how the brand is identified, what the retained records say about its regulatory context, how player disputes are described, and whether the available evidence supports a clear reputation assessment.

The name requires some care. The retained research describes Atas Casino as frequently operating under the primary brand alias Atas88 and as being tailored to players in Malaysia using Malaysian Ringgit. This is a description recorded in the research dossier, rather than an independently verified statement about the operator’s corporate identity.

Atas Review and Player Reputation

Method and evaluation criteria

The method was limited to the supplied research dossier. No additional websites, public registers, user-review platforms, or current regulatory databases were consulted for this article. The analysis therefore treats each retained statement according to its status and wording. Where a record makes an assessment, warning, or observation, that point is presented as a claim made by the stored research rather than as an established conclusion.

Four criteria were used:

  • Identity: whether the records provide a clear and consistent basis for identifying Atas.
  • Regulatory context: whether the records distinguish operator assertions from verified regulatory information.
  • Player recourse: what the records describe about handling complaints and disputes.
  • Responsible-play controls: what the records report about account-level tools.

These criteria can describe the quality and boundaries of the available evidence. They cannot establish that every player has had the same experience, that a particular transaction would succeed or fail, or that the operator meets a legal or technical standard not addressed in the dossier.

What the records establish about Atas

Brand identity remains partly unresolved

The retained research identifies Atas Casino, often associated in the records with Atas88, as a grey-market online gambling platform aimed at the Malaysian market. Because this wording is attributed to the research note, it should be read as the dossier’s classification, not as a verified legal status.

The same research records state that the corporate architecture and ownership structure remain entirely anonymous and opaque. This is an important qualification for a reputation review. A brand name and an operating alias do not, by themselves, identify the legal entity responsible for the service. The supplied material does not establish a named owner, corporate registration, or financial backer.

The dossier also records critical information gaps concerning platform ownership, regulatory oversight, and financial backing. These gaps affect how confidently a reader can connect public-facing brand activity with an accountable operator. They do not, on their own, demonstrate misconduct or determine the outcome of an individual player’s dispute.

Regulatory claims need separate verification

The stored licensing research states that evaluating Atas’s legal authority and licensing status requires a distinction between operator marketing assertions and verified regulatory records. This is a methodological point rather than a licensing finding. The supplied records do not provide a verified licence for Atas, and they do not establish that any marketing statement about licensing is accurate.

The dossier describes Malaysia’s federal online-gambling framework as strictly prohibitionist and identifies the Common Gaming Houses Act 1953 (Act 289) and the Betting Act 1953 (Act 495) as the two primary statutes governing remote and online casino operations. This article reports that legal-framework description as retained research context. It does not attempt to apply those statutes to a particular person, website, transaction, or enforcement situation.

For beginners, the key distinction is between three different propositions: a brand may advertise a regulatory association; a research note may record that the association was not verified; and a legal authority may make a formal determination. The supplied dossier contains the first two types of information, but it does not supply a formal determination about Atas.

Player reputation and dispute handling

Player reputation cannot be reduced to the existence of a brand name or to promotional visibility. A useful assessment also asks whether a player has a transparent route for raising a complaint and whether an independent body can review an unresolved dispute.

The retained dispute-resolution record reports that Atas handles player disputes internally through customer-support channels, including 24/7 Live Chat, WhatsApp, and Telegram. The same record states that this process operates without oversight from an accredited, independent Alternative Dispute Resolution body. These are claims recorded in the research dossier and should not be treated as a firsthand assessment of response quality.

This distinction matters. Internal support can show that communication channels are described in the records, but it does not establish that a complaint will be resolved, that a response will be timely in every case, or that an internal decision is independently reviewable. Conversely, the absence of an independently supervised ADR route in the retained record does not prove that every player dispute is mishandled. It limits what can be concluded about external accountability.

The supplied evidence also does not include a systematic sample of verified player reviews, a complaint database, or a measured resolution rate. As a result, the dossier cannot support a general claim about whether players are usually satisfied or dissatisfied. It supports a narrower The recorded dispute pathway is described as internal, and the retained research does not identify accredited independent ADR oversight.

Responsible-play evidence

Independent site evaluations and technical audits retained in the dossier report that Atas lacks built-in automated responsible-gambling tools within its member account control panel. This is an attributed finding from the stored research, not an independently reproduced technical test in this article.

The wording is deliberately specific. It concerns automated tools inside the member account area. It does not establish the absence of every possible responsible-play measure, nor does it describe a player’s personal behaviour or level of control. The dossier does not provide a broader measured assessment of responsible-gambling outcomes.

For a reputation review, this point is relevant because player trust involves more than access and customer contact. It also involves the transparency of account controls. However, the evidence remains narrow: it reports a limitation identified by the retained evaluations, without supplying a complete account of all policies or interventions that might exist outside the control panel.

How to interpret the reputation evidence

The available evidence is fragmented. One group of records concerns identity and ownership, another concerns the distinction between marketing and verification, another describes dispute handling, and another reports on account-level responsible-play tools. These records do not form a statistical reputation survey.

It would therefore be a misreading to treat brand visibility as proof of reliability. The retained research describes a widespread but fragmented digital footprint concentrated in Malaysian metropolitan areas and East Malaysian regions. That observation concerns search and digital presence. It does not measure player satisfaction, verify ownership, or establish regulatory approval.

It would also be a misreading to treat an information gap as proof of wrongdoing. The dossier records uncertainty about ownership, oversight, and financial backing, but it does not provide evidence that resolves those questions negatively. Similarly, an internally managed complaint route may be less externally accountable than an independent ADR process, but the supplied records do not provide enough player-level data to calculate a general outcome.

The most defensible reputation description is consequently limited and evidence-based: the retained research presents Atas as a Malaysia-focused brand whose ownership and regulatory position are not clearly established in the supplied material, whose dispute process is described as internal, and whose account-level responsible-play tools are reported as limited. Each part of that description remains tied to an attributed research record.

Limitations of this review

This article does not independently verify the brand alias, corporate identity, licence status, statutory application, customer-support performance, or technical configuration. It also does not contain a representative player survey or a verified analysis of public complaints. The dossier’s statements are marked as research notes, and several use attributed wording. They should not be upgraded into guarantees, legal conclusions, or a universal account of player experience.

The records also do not establish how individual account cases were decided, whether every listed support channel remains available, or how the reported account-control limitation compares with a separately verified product specification. Those points are outside the supplied evidence boundary. A later review using dated primary records could produce a different picture if the underlying operator, policies, or regulatory information changes.

Conclusion

The supplied evidence supports a cautious, qualified review rather than a simple reputation verdict. Atas is described in the retained research as a Malaysia-oriented brand associated with Atas88, but the same material records unresolved questions about ownership, regulatory oversight, and financial backing. The legal context is described through Malaysia’s federal statutes, while Atas’s own regulatory assertions are distinguished from verified records rather than accepted as proof.

For player reputation, the records describe internal dispute handling without identified accredited independent ADR oversight and report a lack of built-in automated responsible-gambling tools in the member account panel. These findings are attributed to the stored research and do not establish the experience of every player. Overall, the dossier provides identifiable areas for scrutiny but not enough independently verified, player-level evidence for a definitive reputation conclusion.

What method was used for this Atas review?

The review used only the supplied research dossier. It compared records on brand identity, regulatory context, dispute handling, and responsible-play controls, while preserving the records’ attributed wording and stated uncertainty.

Does the supplied research verify Atas’s ownership or licence status?

No. The retained records describe ownership as opaque and state that licensing evaluation requires separating operator marketing assertions from verified regulatory records. The supplied material does not establish a verified Atas licence or named corporate owner.

What does the evidence say about player disputes?

The retained research reports internal handling through Live Chat, WhatsApp, and Telegram and states that it does not identify oversight from an accredited independent ADR body. It does not provide a representative player survey or a general dispute-resolution success rate.

Is the reported responsible-play finding a complete product assessment?

No. Independent site evaluations and technical audits retained in the dossier report a lack of built-in automated responsible-gambling tools in the member account control panel. That narrow finding does not establish the presence or absence of every other policy or measure.

Atas Review and Player Reputation Read More »

The Next Wave of American Innovation Isn’t Being Built in Silicon Valley. Here’s Where It’s Actually Happening.

The Next Wave of American Innovation Isn’t Being Built in Silicon Valley. Here’s Where It’s Actually Happening.


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • The innovation frontier is shifting from software to physical infrastructure — energy transition, supply chain resilience, advanced manufacturing, and climate adaptation — and the Gulf South, with 40%+ of U.S. crude oil production, half of U.S. refining capacity, and major LNG, aerospace, and defense corridors, is one of the few regions structurally positioned to lead it.
  • What makes the Gulf South an investable mispricing isn’t the assets alone — it’s that this level of global connectivity (to Latin America, West Africa, Europe, the Middle East, and Asia) exists at a materially lower cost basis than traditional capital hubs, creating the conditions where patient investors can build lasting positions before consensus arrives.

The most important shift in global capital right now is not about which sector is hot or which market is recovering. It is about how the system itself is being reorganized. While much of the investment world remains fixated on AI and software, the next wave of opportunity lies where technology intersects with physical infrastructure — from energy and logistics to manufacturing and defense. Those industries are being reshaped by innovation, and the Gulf South is emerging as one of the places where that future is being built.

The Gulf South sits at the intersection of American productive capacity and global demand in a way that very few regions in this country can claim, and that positioning is not yet reflected in how institutional capital is allocated here. The gap between what this region represents structurally and how it is currently valued is, in my assessment, one of the most significant mispricings in American economic geography.

An investment thesis in motion

Earlier this year, I attended the 3rd Coast Venture Summit in New Orleans, one of the Southeast’s premier gatherings for founders, investors and startup leaders. What I saw was a thesis in motion: founders building at the intersection of energy, logistics, climate and technology; capital from outside the region engaging seriously, some for the first time; and a community that had been building quietly and was beginning to move with real intention.

That moment reinforced what I had already been working toward as an investor building within the region. The opportunity is to build investment architecture specifically designed to capture this dynamic, connecting the depth of Gulf South industry to the global corridors of demand across Europe, the Middle East and beyond.

If New York is America’s financial brain and Silicon Valley is its technology center, then the Gulf South is its physical infrastructure and its gateway to the rest of the world. And right now, that gateway is dramatically undervalued relative to what it is already producing and what it is positioned to become.

Regional assets, global implications

The Gulf South — Texas, Louisiana, Mississippi, Alabama and Florida — is the load-bearing infrastructure of the American economy. Texas produces over 40% of the nation’s crude oil. Louisiana anchors American LNG exports to Europe and Asia. The Gulf Coast holds roughly half of U.S. refining capacity and is also home to one of the largest concentrations of aerospace production and advanced industrial capacity in the world. The ports of Houston, South Louisiana and Corpus Christi move an enormous share of what this country produces and imports. That alone would make it strategically significant, but the more interesting fact is where those ports point.

The region connects directly, by water, pipeline and long-established trade route, to Latin America, West Africa, Europe and increasingly the Middle East and Asia. These are the corridors where the majority of global GDP growth will originate over the next twenty to thirty years. Emerging markets are not a future consideration for serious investors. They are the primary consideration. The founders building here reflect that same orientation, constructing businesses with operational discipline and capital efficiency that the build-fast-break-things era rarely produced.

The opportunity for investment

What compounds this opportunity is the cost structure. This level of global connectivity exists at a materially lower cost basis than the traditional hubs where capital tends to concentrate. For investors and operators, that changes the calculus entirely. Capital can move into real industries at scale without the saturation or the premium that coastal markets demand.

Some of that mispricing has a foundation. Governance challenges and climate risk in certain metros — New Orleans being the most visible — create perception drag that bleeds into broader regional assessments. These are legitimate factors. They are also exactly what creates the entry point. Complexity and perceived risk, when layered over genuine structural strength, produce the conditions where patient capital can build lasting positions before consensus arrives.

There is also a deeper shift in what innovation actually means that makes this moment particularly important.

Where the innovation curve is heading

The dominant narrative of the last twenty years was software eating the world, and it did so productively. The frontier is now moving. Energy transition, supply chain resilience, advanced manufacturing and climate adaptation are the defining challenges of the next era. The innovation curve is bending toward physical systems and industrial complexity — toward the kind of problems that require more than a laptop and a good API. Those problems are native to the Gulf South. The companies being built to solve them will define a new geography of innovation, one that does not look like the last cycle.

The defense and space layer adds another dimension entirely. NASA infrastructure in Houston, New Orleans and Mississippi; propulsion testing corridors; defense shipbuilding operations across the Gulf — these represent strategic infrastructure in the fullest sense. They make the Gulf South simultaneously economically essential and geopolitically irreplaceable, a combination that attracts long-duration capital and signals something important about where national and institutional priorities are actually pointed.

In a multi-node world, rare combinations of productive capacity and global connectivity are exactly what serious capital should be identifying before the market does. The Gulf South is the connective corridor between what America produces and what the world needs. The opportunity now is not simply to invest in technology, but to invest where technology is transforming energy, logistics, advanced manufacturing and other critical infrastructure sectors the global economy can’t function without.

Key Takeaways

  • The innovation frontier is shifting from software to physical infrastructure — energy transition, supply chain resilience, advanced manufacturing, and climate adaptation — and the Gulf South, with 40%+ of U.S. crude oil production, half of U.S. refining capacity, and major LNG, aerospace, and defense corridors, is one of the few regions structurally positioned to lead it.
  • What makes the Gulf South an investable mispricing isn’t the assets alone — it’s that this level of global connectivity (to Latin America, West Africa, Europe, the Middle East, and Asia) exists at a materially lower cost basis than traditional capital hubs, creating the conditions where patient investors can build lasting positions before consensus arrives.

The most important shift in global capital right now is not about which sector is hot or which market is recovering. It is about how the system itself is being reorganized. While much of the investment world remains fixated on AI and software, the next wave of opportunity lies where technology intersects with physical infrastructure — from energy and logistics to manufacturing and defense. Those industries are being reshaped by innovation, and the Gulf South is emerging as one of the places where that future is being built.

The Gulf South sits at the intersection of American productive capacity and global demand in a way that very few regions in this country can claim, and that positioning is not yet reflected in how institutional capital is allocated here. The gap between what this region represents structurally and how it is currently valued is, in my assessment, one of the most significant mispricings in American economic geography.

An investment thesis in motion

Earlier this year, I attended the 3rd Coast Venture Summit in New Orleans, one of the Southeast’s premier gatherings for founders, investors and startup leaders. What I saw was a thesis in motion: founders building at the intersection of energy, logistics, climate and technology; capital from outside the region engaging seriously, some for the first time; and a community that had been building quietly and was beginning to move with real intention.


Source link

The Next Wave of American Innovation Isn’t Being Built in Silicon Valley. Here’s Where It’s Actually Happening. Read More »