Blog

Falling GDP, High Inflation, & More

Falling GDP, High Inflation, & More


The US economy has seen a couple of recessions over the past two decades. The most brutal one being the great recession, which remains an anomalous event. Fast forward twelve or so years, and we entered into the 2020 recession, one of the fastest recessions ever recorded that resulted in a massive run-up of stock, crypto, and real estate prices. Now, as a recession looms on the horizon, Americans are struggling to figure out whether or not we’re about to hit a short-term speed bump or a long-term depression.

So many different economists, newscasters, and financial bloggers love to debate whether or not we’re truly in a recession. By definition, we should be, but the experts are slowly taking their time, trying to calculate the true impact of this latest economic cycle we’ve entered. But does being in a recession really matter? Yes, recessions affect almost every aspect of financial life. Labor slows down, consumer prices go up while asset prices drop, and it’s harder to make economic progress. But, is that what we’re experiencing in 2022, or is the term “recession” just propping up fabricated fear that matters far less than we think?

In this bonus episode of On The Market, Dave gives his insight into whether or not the US economy has entered a recession, how this affects real estate investors, and why experts can’t agree on a definition. If you’re actively investing, Dave gives some good advice on how to keep your head screwed on straight while every news outlet plays chicken little.

Dave:
What’s going on, everyone? Welcome to On The Market. I’m your host, Dave Meyer. If you haven’t heard already, last week, the BEA also known as the Bureau of Economic Analysis announced that real gross domestic product had dropped 0.2% in Q2 of 2022. Now, this is important and really newsworthy for several reasons. First and foremost, anytime GDP declines, it is noteworthy. That means that the US economy is contracting and as investors or just as everyday Americans, we should be wondering why the economy is declining and trying to understand what happens next.
Now, this news is even more noteworthy because this is actually the second consecutive quarter of real GDP decline. And if you were paying attention back in Q1, real GDP dropped 1.6%. And so now two quarters in a row, the first two quarters of 2022, we have seen real GDP decline. And the reason this is so noteworthy is because two consecutive quarters of GDP declines is the most commonly accepted definition of a recession.
I’m going to get all into this today, but obviously this causes some fear and concern because we are now hearing a lot of people saying that the United States is in a recession. I wanted to make this episode because there are a lot of questions about this. There’s a lot of confusion and honestly, there have been a lot of heated arguments I’ve seen about whether or not we are technically in a recession, what this means that we’re in a recession, what we should do about it. And so I decided to make this episode to dive into all this.
We’re going to talk about what actually got announced this last week. We’re going to talk about whether or not we are officially in a recession and then we are going to talk about the history of recessions and the implications for investors about what the current economic environment means. But before we jump into this super important topic, we’re going to take a quick break.
Okay. First things first, let’s just jump into what actually was announced this last week. On July 28th, the Bureau of Economic Analysis released the Q2 GDP data. Now, if you’re not familiar with the term GDP, that’s fine. It stands for Gross Domestic Product. And what it is basically if you added up all of the value of the goods and services produced in the United States in the second quarter of 2022, if you summed all of that information, all of the value created there, that’s what Gross Domestic Product is.
It is generally how economies all across the world are evaluated at the highest level. Now, there are tons of other economic factors that advanced economies use to evaluate production and output, but GDP is basically the most commonly accepted highest level analysis of an economy. So the US government specifically the Bureau of Economic Analysis puts out GDP data every single quarter.
Now, sometimes this announcement, it just goes by and some stock traders and people who like me just follow the economy closely, pay attention to it, but this particular announcement was watched really closely because real GDP declined back in the first quarter of 2022. And if it declined again, it would meet the classic definition of a recession. So a lot of people were eagerly awaiting this announcement to know whether or not the US now falls under this classic definition of a recession.
And what happened? Well, real GDP did decline for the second consecutive quarter. It was actually down 0.2% in Q2 or that’s 0.9% if you annualize that out to an entire year. So the US now meets that classical definition of a recession. And before we get into what this all means, let me just go into a quick note on some terminology here.
Real GDP. If you’ve been noticing, I keep saying real GDP. Real, “real” means inflation adjusted. And this is really important because you see if you looked at the opposite of that which is known as nominal GDP. So that’s not inflation adjusted, they tell totally different stories. So when you have real GDP, inflation adjusted GDP, it went down in Q2. But nominal GDP, which is not inflation adjusted at all, it actually went up. It went up quite a lot. It went up 7.8%.
And this is a super noticeable difference, right? 7.8% growth in GDP during normal times would be enormous. People would be singing its praises and would be so excited, but inflation is so bad right now that it is more than canceling out all of that growth as reflected in real GDP, right? If there was zero inflation, we could look at that nominal 7.8% and be super excited about it.
But the reason we have to look at real GDP is because inflation is devaluing the dollar and that means that when you account for that, the actual growth in the economy was slightly negative in the second quarter. So this is just something that drives me nuts because a lot of like really big reputable data sources, media sources will publish GDP data and not clarify whether it’s real or nominal.
So just as a note if you are looking into this information, make sure to check which one you’re looking at, because they’re both valuable measurements, but they are very different ones. And for the rest of this episode, I am going to be talking about real GDP. Again, that is inflation adjusted GDP because I think that is probably the most important thing that we can all look at this.
Now, I interpret all this information one way. You might interpret it differently. There are so many different variables in the economy, but overall, I mean, I don’t think anyone can really argue that negative real GDP is not a good thing, right? It means that inflation is overshadowing US productivity, right? As I just said, if there was no inflation right now, the US would’ve grown at nearly 8% which is amazing. But instead, when you adjust for inflation, as you should, it is negative.
So this is a really important difference. And again, I think that this shows weakness in the US economy. The big question now seems to be are we actually in a recession? And if you pay attention to the news or to social media, you probably see people arguing about this a lot right now. And it seems like it should be a simple answer, but unfortunately it’s not.
So I did some research just to figure out what is behind this entire debate. And let me just explain to you why it’s not so clear whether we are technically in a recession right now. So first, most people accept that two consecutive quarters of GDP declines equals a recession. Many people believe this makes it officially a recession, but that’s not actually the case.
So again, people generally accept that, but to get, quote-unquote, officially a recession, there is only one group of people who can do that and it is not as simple as two consecutive quarters of GDP decline. In fact, it is done by a group called the National Bureau of Economic Research. And specifically it is done by this very strangely named group called the business cycle dating committee. They put out dates around business cycles. There is no romantic dating that I know of at least going on, and it is just a bunch of academics basically.
This is a bunch of economists from universities across the country, and they look at an overwhelming amount of data to make their determination of whether or not we are in a recession. And as their very strange name indicates, their job is basically to decide when the recession starts and when the recession ends.
So how do they do that, right? Because most of us are walking around thinking two consecutive quarters of GDP decline, that’s a recession, right? Well, they look at it in a more complicated way. They say according to their website and I quote, “A recession involves a significant decline in economic activity that is spread across the economy and lasts more than a few months.”
That’s obviously not as simple a definition as two consecutive quarters. They go on to say, “In our interpretation of this definition, we treat the three criteria, depth, diffusion and duration as somewhat interchangeable. That is while each criterion needs to be met individually to some degree, extreme conditions revealed by one criterion may particularly offset weaker indications from another. Because a recession must influence the economy broadly and not be confined to one sector, the committee emphasizes economy wide measures of economic activity. The determination of the months of peaks and troughs is based on a range of monthly measures of aggregate real economic activity published by the federal statistical agencies.”
Whoa. Okay. That was a lot of big words and random stuff, but basically what they are saying is that they look at a lot of different stuff across the economy. It has to be across different economic activities, right? That’s something that they said that it doesn’t really come down to one standard definition. They are looking at the depth of economic decline. They’re looking at the duration of economic decline and they’re looking at how broadly it is spread across the economy. And they also said that they are basing it off real economic activity.
So they are saying what we were just talking about, that they base it off inflation adjusted numbers. Okay. So I know that’s pretty wonky and it’s notable that these people, the National Bureau of Economic Research, basically the only people allowed to officially call a recession have a very complicated definition of a recession, right? After I read that, we can all agree on that they are not just saying it’s two quarters of GDP decline.
So that is the important piece. The other important piece that I uncovered when I was researching this is something else they said. So they write and I quote, “The committee’s approach to determining the dates of turning points is retrospective in making its peak and trough announcements. It waits until the sufficient data are available to avoid the need for major revisions to the business cycle chronology.”
I know. Another really wonky, big word sentence, but basically what they’re saying is that the only people who are able to make the official recession designation say that they don’t do it in real time. They are not trying to decide right now today, “Are we in a recession?” They like to look backwards and say, “Okay, let’s look at what happened in 2022 and we’re going to decide when the recession really started and when it really ended.”
They always do it retroactively. Listen, I think it’s annoying and frustrating that it is not in real time, but in some way it does make sense because look at their definition, right? They’re saying they have to look at all this crazy data to make the determination. And if they have to look at that much data, according to them, then I understand it’s going to take some time to look at all this data. Unfortunately for us, the debate about whether we are in a recession is going to go on for some time.
Let me just show you something that I found actually on the Wall Street Journal. And it showed that just some recent examples, the 2001 recession, which was some people call like the dot com boom bubble burst, whatever, started in March 2021. That’s when it officially started, but the NBER only announced that in November of 2021. So eight months later. The great recession, which officially started in December of 2007 wasn’t announced until December of 2008. That is a whole year later.
The COVID recession, which is the most recent one, which started in February of 2020 was announced in June of 2020. So that one was actually relatively quick. Only four months later. But I know people get frustrated about this. They argue about this and they say that it’s all political. And there is obviously politicking going on. This is the United States after all. But there is just precedent. This is always what happens. This isn’t a change based on current economic conditions. The official designation of a recession always comes months after it actually starts.
So I actually didn’t know that. I thought that was really interesting. Something to help you all understand why there is still room for people to debate this and why people are debating this so much is because it’s going to be several months until we actually know for sure. So everyone wants to know are we in a recession? Most people would say yes because we have seen two consecutive quarters of GDP declines. Some people are going to say no, and we don’t know officially for sure.
Now, my personal opinion, and I know this is probably going to be different than what most people think is that it doesn’t really matter. I know that sounds counterintuitive, but my point is that the definition and whether the current time period is labeled as a recession, it doesn’t really matter to me.
Let me just be clear. I’m not saying that a decline in economic growth doesn’t matter. That absolutely matters. The fact that GDP, real GDP is declining, absolutely matters that it’s extremely important. What I’m saying is that whether or not we are officially in a recession, whether a group of people have decided that we are going to call this current time a recession or not, honestly doesn’t matter. It doesn’t change anything, right?
Because the broad macroeconomic trends that are underlying our economy that exist today are not exactly new. And whether or not the NBER decides that we are in a recession right now, or maybe in six months, or maybe not at all. I don’t know, but it doesn’t change the underlying facts, right? So let’s review some of those underlying facts. One inflation is outpacing wage growth. And as we’ve discussed has led to a decline in real GDP.
Economic output in the US on an inflation adjusted basis has been down for all of 2022. Whether you want to call this a recession or not, that remains true, and that remains concerning, right? To me, a decline in real economic output is not a good thing. Number two, the stock market and crypto markets are down considerably year to date. I’ve said this before and I want to make a point that the stock market and crypto market or other asset markets are not the economy, but they are part of the economy and they both have been down this year.
That said they have bounced back in July, but they’re still down from early in 2022. So that is a trend that we have been seeing for most of 2022. Whether we call this a recession or not, that is true. Number three, the housing market remains up year over year but is showing signs of slowing. What’s happening in the housing market, the data lines that we’ve been looking at have remained consistent.
Interest rates are going up. Affordability is declining. Demand is going with it and we are starting to see cooling in the housing market. But housing market is still up a lot year over year, but it is showing signs of cooling.
Four, generally speaking, consumer spending remains high. And yes, a lot of consumer spending increasing is a reflection of raised prices, right? So if people are just buying the same stuff and they’re more expensive, of course, consumer spending looks higher because everything costs more. But it is notable that even despite inflation and people spending power going down, they are still spending. So that is an important thing to note and has buoyed some particular retail businesses.
Some businesses continue to show good profit and strong growth. And lastly, the labor market remains strong. And it is true that the labor market, generally speaking, if there is a recession is a lag indicator. And if there is a protracted decline in real GDP, the labor market will probably take a hit. But as of this recording, I’m just looking at the data that I have today, as of this recording, that has not happened yet. Based on basically all the traditional measures of labor out there, people are highly employed right now.
I know there’s people who are going to point to labor force participation and that has declined. That is true. It is a very small amount. It is declined about 1%. So it’s really not that significant. And honestly, if you look at it by most traditional measurements, unemployment is really low right now.
So all these things, there are many other economic factors we could talk about, but these are the ones I just wanted to point out. And if you look at all of these things, like I said, they are true whether or not we call this a recession.
All these things, they can change. They are going to change. All this economic data is released at least a month ago. As of recording, I’m looking at June data for the most part. But these are the economic factors that we know about. And if we’re going to analyze our investments, if we’re going to analyze the market and try and make wise decisions based off it, we need to use the data that is available. And this is the data that is available to us right now.
So all of this is to say that I would advise you not to get too hung up on the definitions here, right? If you understand the underlying forces that are driving the economy, some of the things that I just talked about, then the label of recession, it matters very little, right? If you understand what’s going on with interest rates, the housing market, the stock market, inflation, the labor market. Then what a couple of people decide whether to call it a recession or not, it doesn’t really matter because you’ll be able to make informed decisions about your own financial life.
The fact remains the US economy is not growing on an inflation adjusted basis. And Americans generally speaking are not feeling very good about the economy. Consumer sentiment is extremely low. People are afraid of inflation, and these are the things, at least to me, that really matter. So that, sorry, is my rant about definitions. I just see so many people… Well, I feel like they’re wasting their time just arguing about whether in a recession or not, when really what you should be looking at, and what really matters is the underlying things that impact a recession like GDP, labor market, asset prices, interest rates.
These are the things that we talk about on the show and that I encourage you to pay more attention to than whether or not we are officially in a recession. Sorry, that’s my rant. So, anyway, as I said at the beginning of that I don’t care too much about the definition. What I care about is that declining real GDP is a concern. I wanted to share some historical data about that because I look at that data and I think that’s an economy and decline. I don’t want anyone to panic because recessions happen. That is part of a normal economic cycle.
I just want to share some information about you about what a normal, “recession” looks like. So I looked at some data since World War II and the average recession lasted about 11 months. Not so long. That was actually shorter than I thought it would be. If you’re someone who thinks we are in a recession right now, you follow the two consecutive quarter rule, we’re already at six months, right? Cause Q1, Q2.
So hopefully that means that it might end towards the end of this year. I don’t know. Just something to think about. Interestingly, I also found out that the most recent two recessions that we’ve had in the United States have been outliers. 2020 was the shortest ever recession lasting just two months. So again, that defies the two consecutive months of GDP rule.
It was just two months long. And then the gray recession was an outlier in the other way. Unfortunately, it was the longest post World War II recession and lasted about 18 months. If you look at the severity of these, they really do very pretty considerably. So if you look at the 2001 recession, which again was like the dot com bubble burst, again, it started in March 2021. Only announced in November 2021. And from the peak, the peak of the economy before the recession to the trough, which is the low of the recession, real GDP declined, but it was less than 1%.
So that’s about what we saw in Q2. And so back then, that was a pretty shallow recession. And the stock market took an absolute beating during that time. But real GDP declined less than 1%. And most notably for people listening to this episode, housing prices actually went up over 6% during that recession. So there you go. Pretty interesting. The great recession started in December 27th, 2007. Wasn’t announced for a year after that. And during that time, GDP went down more than 4%.
So that was much more significant recession, as we all know, by most economists and historians standards. The great recession was the worst economic period since the great depression. During that time, the housing prices dropped almost 20%. And as real estate investors, this is the horrible period that a lot of people remember and are afraid that it’ll happen again.
But just to be clear in four of the last six recessions, housing prices actually grew. And so just on an average basis in recessions, that housing prices typically do not go down 20%. And the reason, in my opinion why housing prices went down so much in the great recession is because housing caused that recession, right? In this economy, in this potential recession, housing is not causing it, right? Inflation is mostly causing this one.
So when housing caused the recession back in 2007, there’s a reason housing prices went down so much. That is why personally, I don’t believe even if we are in a recession that we are going to see housing prices decline anywhere close to 20%. I do think that in certain markets we will see housing prices declines, but I don’t think we are really anywhere close to what we saw in terms of macroeconomic conditions around the great recession.
Lastly, I’ll just talk about it quickly because it was barely a recession, but the COVID recession started in February 2020, was announced a couple months later. Only lasted two months and we all remember what happened there, right? The stock market tanked. I think it went down about 30% and then it bounced back quickly and went on an enormous bull run.
Similarly, housing market. It didn’t go down, but the start of this recession, the COVID recession was actually one of the beginning of one of the most aggressive, fastest periods of housing appreciation in American history. So I’m telling you all this because we call this recession, we want to call it a recession, but every recession looks really different. That is part of the reason why it’s hard to define, but it also is part of the reason why the recession label doesn’t matter as much as the underlying fundamentals, right?
What matters is what’s going on with the housing market? What matters is going on with the stock market, with interest rates, with consumer spending, with wage growth, right? These are the things that actually matter. So I obviously can’t say what’s going to happen next, but I wanted to share this information at least because history can be a useful guide for us. And that’s at least what happened over the last three recessions. If you want to look up more, you can just Google it. There’s tons of information about previous recessions that you can look at as well.
Now, we don’t know what’s going to happen, but there are some things that I think are important to watch. And here are a couple things that I personally am going to be watching over the next couple months to get a sense of my own investing but what is likely to happen in the economy.
So what to watch for first thing is employment. The real thing that’s scary about recessions is the unemployment rate rising. As I said earlier, right now the most recent data we have, unemployment is still super low. I am personally curious to see that if we have a sustained period of real GDP declines will unemployment go up? And the reason why I’m thinking about this is because, one, interest rates are going up, which makes it more expensive for businesses to borrow, which means it costs them more to expand, to build the new factory and to hire the people who are going to build stuff in that factory has become more expensive.
Second, if real GDP is down and corporate profits take a hit, they’re less likely to invest. They’re probably not going to raise salaries at the same rate that they have been. And maybe they’ll stall on a couple of new hires or maybe they’ll freeze hiring altogether. I think whether in a recession or not, it is a little too early to understand what is going to happen to the labor market right now.
Right now, it still looks really good, but we don’t know what’s going to happen over the next couple months. And so that’s why it is my number one thing I am going to be keeping an eye on is unemployment rates. The second thing is of course, inflation.
Now, many forecasters are projecting that inflation has actually peaked. And listen, this is not my area of expertise. I don’t have economic models or statistical models to project inflation, but I do follow a lot of different economists from all different types of backgrounds and beliefs. And if you look at commodity prices, this seems plausible.
You look at food prices, you look at energy prices, they are starting to come down. And a lot of that is because of fear of an inflation, but there is a plausible path that inflation has peaked. Now, that does not mean that prices are going to go down. That is just not going to happen. But what it does mean is that inflation may grow less fast, right? We’ve seen it at high eights, 9%. Maybe it goes down to 8% year over year. And then by the end of the year, maybe it’s 7% year over year.
I don’t know. This is just what people are… The majority of economists believe that it is going to start going down. That doesn’t mean the problem is going away because even if it goes down to 7%, 7% is still bad. But it would be a good sign for the economy if it peaked and started to decline. So that is something to watch for because, I guess, the point is if inflation starts to come down and employment, the other thing I’m looking at remains relatively strong, if those two things do happen, then we’ll probably see real GDP and economic confidence start to improve probably towards the end of this year.
If that doesn’t happen and inflation remains high, and we start to see large scale job losses, then we are at risk for a longer term recession and more economic pain. Maybe not quite at the scale of the great recession. I don’t think we’re really looking at something like that, but there is a scenario where this is a short and shallow recession and there is a scenario where this is more of a protractor recession. Personally, I think it is too early to tell one way or another, but these are the things I’m going to be looking at.
The last thing is of course interest rates. I do think this is honestly maybe the most interesting thing that may come of this GDP data that came out is that the federal reserve has obviously been raising interest rates since March in an effort to combat inflation. They’ve been very clear that they’re going to keep doing that. They’ve raised rates by 75 basis points. Two times in a row right now. That is very significant. But the fed also doesn’t want to crater the economy.
Officially, their job is to secure price stability, basically fight inflation and to pursue maximum employment. And if recession comes… And it’s a long recession, like we just talked about employment could start to go down. And so that will put the fed in a really interesting spot where they can’t just be aggressive against inflation because if employment starts to fall, then they have to decide, right? They have to do this balancing act of how do they fight inflation while keeping employment as high as possible.
So that could mean that the fed reverses course a little bit. Now, I don’t think we’re at the point where they’re going to start cutting rates, but my expectation is that they will probably start raising rates slower. And this is just my opinion. I am just speculating here. I think we’re not going to see any more 75 basis points hikes. I think we’ll probably see a 50, maybe 25 basis points hikes through the rest of the year.
A lot of people believe that the fed could start cutting rates in 2023. I don’t know about that. I am not projecting that, predicting that, but people have been talking about that. A lot of people on Wall Street believe that might be the case. So those are things to look at. My top three are employment rates, inflation and interest rates.
Okay. So quickly before we go, I just have a couple of notes and things to point out for real estate investors based on this announcement. First and foremost, as I said before, housing prices have actually risen in four of the last six recessions. And so don’t just assume that there’s going to be a crash because there is a recession. There is a lot more going on in the housing market than just whether GDP is going up or down.
We try and cover this extensively here on this podcast. And you can listen to a lot of our recent episodes if you want to learn more about that. I’m not going to get super into that right now. But lot of episodes. You can listen to one with Logan Mohtashami, Rick Sharga, one we just did with the whole panel. Just talking about what’s going on in the housing market will help you understand what might happen next.
The second thing is that, although, the fed is raising interest rates. The fed does not control mortgage rates. I say this all the time, but I want to just hammer this home. The fed does not control mortgage rates. Rates are much more closely. Mortgage rates are much more closely tied to the 10-year treasury yield, right? So go look on whatever financial data website you like. Go look at the yield on a 10-year treasury.
It peaked back in June and it is starting to go down. In a historical context, it is still extremely low. Now, why is this happening? And just for the record, the yield on the 10-year treasury is starting to decline and that has moderated mortgage prices very considerably.
Now, why is this happen? Well, it’s because of fear of a recession. When there is fear of a recession, investors, generally speaking flock to safer investments. They don’t take as much risk. You see that reflected in really risky stocks, right? They’re getting hammered more than blue chip stocks, for example. So investors flock to safe investments and treasury bonds like the 10-year yield, the 10-year treasury, excuse me, that I am talking about are extremely safe investments because they’re guaranteed by the US government.
So all these people are looking for these bonds because they’re safe and that raises demand, right? There is demand for bonds and it does with everything else, and it’s supply and demand. When there is more demand, prices go up. And the funny thing about bonds just… I’m not going to get super into this. I will do a full episode soon, but when prices for bonds go up, they’re yields fall. They’re inversely correlated.
So demand is up. That increases the price for bonds that pushes down their yields and that means that mortgage rates have gone steady. They’re down from their peak. I don’t know what’s going to happen, but if you are looking to buy real estate, look at what’s going on right now. And you can see that bond yields are a bit lower. They’re not going back to… We’re not going to get 3% mortgages again. We’re not going to get 4% mortgage again anytime soon, but they have stopped growing so quickly and we are starting to see five and a half, 5.75 be the standard right now.
They’re no longer on this like exponential rise that we saw for the first half of the year in mortgage rates, they’re starting to flatten out. And to me, this is really important because it provides more stability to the housing market, right? Investors, homeowners, can all start to make informed decisions if they have a good idea of where mortgage rates are going to be over the next six months or during at least during their buying period.
So that is something to also keep an eye on is mortgage rates because, again, just to reiterate here, although the fed is raising interest rates, fear of a recession is pushing down bond yield and that constrains mortgage rates.
Okay. So that is what I got for you guys. Just to recap, the US is seeing declining output on an inflation adjusted basis. We now have seen real GDP decline for two consecutive quarters. Most people consider this a recession, but we won’t know if it’s officially a recession for at least a few more months.
My personal advice, don’t get too caught up in the definition of a recession. It is the underlying economic forces that matter. Inflation is far too high. Spending is keeping up. We have not yet seen a large scale job losses, but that is going to be a key thing to watch in the coming months. And the housing market is cooling on a national scale, but still up double digits year over year which in any other year would be absolutely massive.
As an investor, you should be understanding all of these forces. That is my recommendation to you. Again, don’t get too caught up into whether we are in a recession or not, whether we’re calling it a recession or not. Try instead to understand the underlying economic forces. This is what this show is all about. Our aim is to help you understand the important trends and data points that have led to the economic conditions we find ourselves in and not get caught up into what words we use to describe them and into some debate that is ultimately going to be settled by a couple of academics a few months from now.
So hopefully, we’ve done that today and we’re going to keep trying to do that twice a week to help you understand the complex economic situation we find ourselves in. Thank you all so much for listening. We really appreciate it. If you have any feedback for me or thoughts about this episode, please reach out to me on Instagram where I am @thedatadeli. Thank you all. We will see you again on Monday.
On The Market is created by me, Dave Meyer and Kailyn Bennett. Produced by Kailyn Bennett. Editing by Joel Esparza and Onyx Media. Copywriting by Nate Weintraub. And a very special thanks to the entire BiggerPockets team.
The content on the show, On The Market are opinions only. All listeners should independently verify data points, opinions, and investment strategies.


Note By BiggerPockets: These are opinions written by the author and do not necessarily represent the opinions of BiggerPockets.

Source link

Falling GDP, High Inflation, & More Read More »

Don’t expect recovery in housing any time soon, says Piper Sandler’s Kantrowitz

Don’t expect recovery in housing any time soon, says Piper Sandler’s Kantrowitz


Share

Michael Kantrowitz, Piper Sandler chief investment strategist, joins ‘Power Lunch’ to discuss what history tells investors about the Federal Reserve’s prior rate hikes, why initial unemployment claims are so important for Kantrowitz and more.

03:23

Wed, Aug 3 20222:52 PM EDT


Source link

Don’t expect recovery in housing any time soon, says Piper Sandler’s Kantrowitz Read More »

3 Reasons For Why You Should Brand Your Rental Business

3 Reasons For Why You Should Brand Your Rental Business


15% ROI”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2021\/05\/large_Extra_large_logo-1.jpg”,”imageAlt”:””,”title”:”SFR, MF & New Builds!”,”body”:”Invest in the best markets to maximize Cash Flow, Appreciation & Equity with a team of professional investors!”,”linkURL”:”https:\/\/renttoretirement.com\/”,”linkTitle”:”Contact us to learn more!”,”id”:”60b8f8de7b0c5″,”impressionCount”:”198949″,”dailyImpressionCount”:”601″,”impressionLimit”:”350000″,”dailyImpressionLimit”:”1040″},{“sponsor”:”Azibo”,”description”:”Smart landlords use Azibo”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2021\/11\/Logo-512×512-1.png”,”imageAlt”:””,”title”:”One-stop-shop for landlords”,”body”:”Rent collection, banking, bill pay and access to competitive loans and insurance – all free for landlords.”,”linkURL”:”https:\/\/www.azibo.com\/biggerpockets\/?utm_source=biggerpockets&utm_campaign=biggerpock ets&utm_medium=affiliate&utm_content=blog”,”linkTitle”:”Get started, it\u2019s free”,”id”:”618d372984d4f”,”impressionCount”:”266310″,”dailyImpressionCount”:”372″,”impressionLimit”:”300000″,”dailyImpressionLimit”:0},{“sponsor”:”The Entrust Group”,”description”:”Self-Directed IRAs”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2021\/11\/TEG-Logo-512×512-1.png”,”imageAlt”:””,”title”:”Spring Into investing”,”body”:”Using your retirement funds. Get your step-by-step guide and learn how to use an old 401(k) or existing IRA to invest in real estate.\r\n”,”linkURL”:”https:\/\/www.theentrustgroup.com\/real-estate-ira-report-bp-awareness-lp?utm_campaign=5%20Steps%20to%20Investing%20in%20Real%20Estate%20with%20a%20SDIRA%20Report&utm_source=Bigger_Pockets&utm_medium=April_2022_Blog_Ads”,”linkTitle”:”Get Your Free Download”,”id”:”61952968628d5″,”impressionCount”:”401974″,”dailyImpressionCount”:”362″,”impressionLimit”:”600000″,”dailyImpressionLimit”:0},{“sponsor”:”Steadily”,”description”:”Best-Rated Landlord Insurance\r\n”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2021\/11\/STEADILY.png”,”imageAlt”:””,”title”:”Fast, Affordable Landlord Insurance”,”body”:”Affordable insurance for rental properties of all kinds, including fix n\u2019 flip. Multi-property discounts available. \r\n”,”linkURL”:”https:\/\/bit.ly\/3FUfGgE”,”linkTitle”:”Get a free quote today”,”id”:”61a51c5a6182e”,”impressionCount”:”156592″,”dailyImpressionCount”:”414″,”impressionLimit”:”390000″,”dailyImpressionLimit”:”3250″},{“sponsor”:”Guaranteed Rate”,”description”:”One-Stop Mortgage Lender”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/01\/927596_CB_BiggerPockets-January-2022-Assets-512×512-1.png”,”imageAlt”:””,”title”:”$1,440 Mortgage Savings*”,”body”:”Whether you\u2019re buying new or cash-out refinancing to upscale the old \u2013 get started today and we\u2019ll help you save!\r\n\r\n”,”linkURL”:”https:\/\/www.rate.com\/biggerpockets?adtrk=|display|corporatebenefits|biggerpockets|july2022_blog||||||||||&utm_source=corporatebenefits&utm_medium=display&utm_campaign=biggerpockets&utm_content=july2022-blog “,”linkTitle”:”Buy or Cash-Out Refi”,”id”:”61ccd6a886805″,”impressionCount”:”96188″,”dailyImpressionCount”:”318″,”impressionLimit”:”200000″,”dailyImpressionLimit”:”2222″},{“sponsor”:”Roofstock”,”description”:”Real estate investing”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/02\/roofstock1644.jpeg”,”imageAlt”:””,”title”:”SFR Marketplace”,”body”:”Build wealth through single-family rental (SFR) investing. Roofstock makes it radically accessible.\r\n\r\n”,”linkURL”:”https:\/\/www.roofstock.com\/bp”,”linkTitle”:”Visit the Marketplace”,”id”:”6217d101980a8″,”impressionCount”:”139019″,”dailyImpressionCount”:”269″,”impressionLimit”:”490000″,”dailyImpressionLimit”:0},{“sponsor”:”Roofstock One”,”description”:”Meet the SFR asset class”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/02\/MicrosoftTeams-image-2.png”,”imageAlt”:””,”title”:”Expand your portfolio”,”body”:”Accredited investors: Access investments in the single-family rental (SFR) sector\u2014no property management required. “,”linkURL”:”https:\/\/www.roofstock.com\/one?utm_campaign=BiggerPockets-Podcast&utm_source=sponsorships&utm_medium=podcast”,”linkTitle”:”Explore Roofstock One”,”id”:”6217fa9c588dd”,”impressionCount”:”144875″,”dailyImpressionCount”:”317″,”impressionLimit”:”490000″,”dailyImpressionLimit”:0},{“sponsor”:”Stessa, a Roofstock company”,”description”:”Keep your houses in order”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/02\/MicrosoftTeams-image-3.png”,”imageAlt”:””,”title”:”Track properties for free”,”body”:”Manage and report on your investment properties with asset management software purpose-built for real estate investors.”,”linkURL”:”https:\/\/www.stessa.com\/bp”,”linkTitle”:”Claim your free account”,”id”:”6217fa9c6258f”,”impressionCount”:”154128″,”dailyImpressionCount”:”347″,”impressionLimit”:”490000″,”dailyImpressionLimit”:0},{“sponsor”:”BAM Capital”,”description”:”Multifamily Syndicator\r\n\r\n”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/02\/Bigger-Pockets-Forum-Ad-Logo-512×512-2.png”,”imageAlt”:””,”title”:”$100M FUND III NOW OPEN”,”body”:”Earn truly passive income with known assets in an award-winning market. Confidently targeting 2.0x-2.5x MOIC.\r\n\r\n\r\n”,”linkURL”:”https:\/\/capital.thebamcompanies.com\/offerings\/?utm_source=bigger-pockets&utm_medium=paid-ad&utm_campaign=bigger-pockets-blog-feb-2022&utm_content=fund-iii-now-open”,”linkTitle”:”Learn more”,”id”:”621d250b8f6bd”,”impressionCount”:”120583″,”dailyImpressionCount”:”207″,”impressionLimit”:”150000″,”dailyImpressionLimit”:”2500″},{“sponsor”:”Walker & Dunlop”,”description”:” Apartment lending. Simplified.”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/03\/WDStacked512.jpg”,”imageAlt”:””,”title”:”Multifamily Property Financing”,”body”:”Are you leaving money on the table? Get the Insider\u0027s Guide.”,”linkURL”:”https:\/\/explore.walkerdunlop.com\/sbl-financing-guide-bp-blog-ad”,”linkTitle”:”Download Now.”,”id”:”6232000fc6ed3″,”impressionCount”:”120608″,”dailyImpressionCount”:”222″,”impressionLimit”:”200000″,”dailyImpressionLimit”:”6500″},{“sponsor”:”SimpliSafe Home Security”,”description”:”Trusted by 4M+ Americans”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/03\/SS-Logo-.png”,”imageAlt”:””,”title”:”Security that saves you $”,”body”:”24\/7 protection against break-ins, floods, and fires. SimpliSafe users may even save up to 15%\r\non home insurance.”,”linkURL”:”https:\/\/simplisafe.com\/pockets?utm_medium=podcast&utm_source=biggerpockets&utm_campa ign=2022_blogpost”,”linkTitle”:”Protect your asset today!”,”id”:”624347af8d01a”,”impressionCount”:”91079″,”dailyImpressionCount”:”240″,”impressionLimit”:”200000″,”dailyImpressionLimit”:”2222″},{“sponsor”:”Delta Build Services, Inc.”,”description”:”New Construction in SWFL!”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/04\/Image-4-14-22-at-11.59-AM.jpg”,”imageAlt”:””,”title”:”Build To Rent”,”body”:”Tired of the Money Pits and aging \u201cturnkey\u201d properties? Invest with confidence, Build To\r\nRent is the way to go!”,”linkURL”:”https:\/\/deltabuildservicesinc.com\/floor-plans-elevations”,”linkTitle”:”Look at our floor plans!”,”id”:”6258570a45e3e”,”impressionCount”:”82136″,”dailyImpressionCount”:”232″,”impressionLimit”:”160000″,”dailyImpressionLimit”:”2163″},{“sponsor”:”RentRedi”,”description”:”Choose The Right Tenant”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/05\/rentredi-logo-512×512-1.png”,”imageAlt”:””,”title”:”Best App for Rentals”,”body”:”Protect your rental property investment. Find & screen tenants: get full credit, criminal, and eviction reports.”,”linkURL”:”http:\/\/www.rentredi.com\/?utm_source=biggerpockets&utm_medium=paid&utm_campaign=BP_Blog.05.02.22&utm_content=button&utm_term=findtenants”,”linkTitle”:”Get Started Today!”,”id”:”62740e9d48a85″,”impressionCount”:”66405″,”dailyImpressionCount”:”255″,”impressionLimit”:”150000″,”dailyImpressionLimit”:”5556″},{“sponsor”:”Guaranteed Rate”,”description”:”One-Stop Mortgage Lender”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/06\/GR-512×512-1.png”,”imageAlt”:””,”title”:”$1,440 Mortgage Savings”,”body”:”Whether you\u2019re buying new or cash-out refinancing to upscale the old \u2013 get started today and we\u2019ll help you save!”,”linkURL”:”https:\/\/www.rate.com\/biggerpockets?adtrk=|display|corporatebenefits|biggerpockets|july2022_blog||||||||||&utm_source=corporatebenefits&utm_medium=display&utm_campaign=biggerpockets&utm_content=july2022-blog%20%20%20″,”linkTitle”:”Buy or Cash-Out Refi”,”id”:”62ba1bfaae3fd”,”impressionCount”:”22864″,”dailyImpressionCount”:”276″,”impressionLimit”:”70000″,”dailyImpressionLimit”:”761″},{“sponsor”:”Avail”,”description”:”#1 Tool for Landlords”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/06\/512×512-Logo.png”,”imageAlt”:””,”title”:”Hassle-Free Landlording”,”body”:”One tool for all your rental management needs — find & screen tenants, sign leases, collect rent, and more.”,”linkURL”:”https:\/\/www.avail.co\/?ref=biggerpockets&source= biggerpockets&utm_medium=blog+forum+ad&utm _campaign=homepage&utm_channel=sponsorshi p &utm_content=biggerpockets+blog+ad+fy23+1h”,”linkTitle”:”Start for FREE Today”,”id”:”62bc8a7c568d3″,”impressionCount”:”25257″,”dailyImpressionCount”:”289″,”impressionLimit”:”200000″,”dailyImpressionLimit”:”1087″},{“sponsor”:”Steadily”,”description”:”Easy landlord insurance”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/06\/facebook-business-page-picture.png”,”imageAlt”:””,”title”:”Rated 4.8 Out of 5 Stars”,”body”:”Quotes online in minutes. Single-family, fix n\u2019 flips, short-term rentals, and more. Great prices and discounts.”,”linkURL”:”http:\/\/www.steadily.com\/?utm_source=blog&utm_medium=ad&utm_campaign=biggerpockets “,”linkTitle”:”Get a Quote”,”id”:”62bdc3f8a48b4″,”impressionCount”:”26953″,”dailyImpressionCount”:”293″,”impressionLimit”:”200000″,”dailyImpressionLimit”:”1627″},{“sponsor”:”MoFin Lending”,”description”:”Direct Hard Money Lender”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/06\/mf-logo@05x.png”,”imageAlt”:””,”title”:”Flip, Rehab & Rental Loans”,”body”:”Fast funding for your next flip, BRRRR, or rental with MoFin! Close quickly, low rates\/fees,\r\nsimple process!”,”linkURL”:”https:\/\/mofinloans.com\/scenario-builder?utm_source=biggerpockets&utm_medium=cpc&utm_campaign=bp_blog_july2022″,”linkTitle”:”Get a Quote-EASILY!”,”id”:”62be4cadcfe65″,”impressionCount”:”30347″,”dailyImpressionCount”:”303″,”impressionLimit”:”100000″,”dailyImpressionLimit”:”3334″},{“sponsor”:”REI Nation”,”description”:”Premier Turnkey Investing”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/07\/REI-Nation-Updated-Logo.png”,”imageAlt”:””,”title”:”Fearful of Today\u2019s Market?”,”body”:”Don\u2019t be! REI Nation is your experienced partner to weather today\u2019s economic conditions and come out on top.”,”linkURL”:”https:\/\/hubs.ly\/Q01gKqxt0 “,”linkTitle”:”Get to know us”,”id”:”62d04e6b05177″,”impressionCount”:”17403″,”dailyImpressionCount”:”304″,”impressionLimit”:”195000″,”dailyImpressionLimit”:”6360″},{“sponsor”:”Zen Business”,”description”:”Start your own real estate business”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/07\/512×512-1-300×300-1.png”,”imageAlt”:””,”title”:”Form Your Real Estate LLC or Fast Business Formation”,”body”:”Form an LLC with us, then run your real estate business on our platform. BiggerPockets members get a discount. “,”linkURL”:”https:\/\/www.zenbusiness.com\/p\/biggerpockets\/?utm_campaign=partner-paid&utm_source=biggerpockets&utm_medium=partner&utm_content=podcast”,”linkTitle”:”Form your LLC now”,”id”:”62e2b26eee2e2″,”impressionCount”:”2266″,”dailyImpressionCount”:”318″,”impressionLimit”:”80000″,”dailyImpressionLimit”:”2581″}])” class=”sm:grid sm:grid-cols-2 sm:gap-8 lg:block”>


Source link

3 Reasons For Why You Should Brand Your Rental Business Read More »

Mortgage applications inch up for the first time in five weeks

Mortgage applications inch up for the first time in five weeks


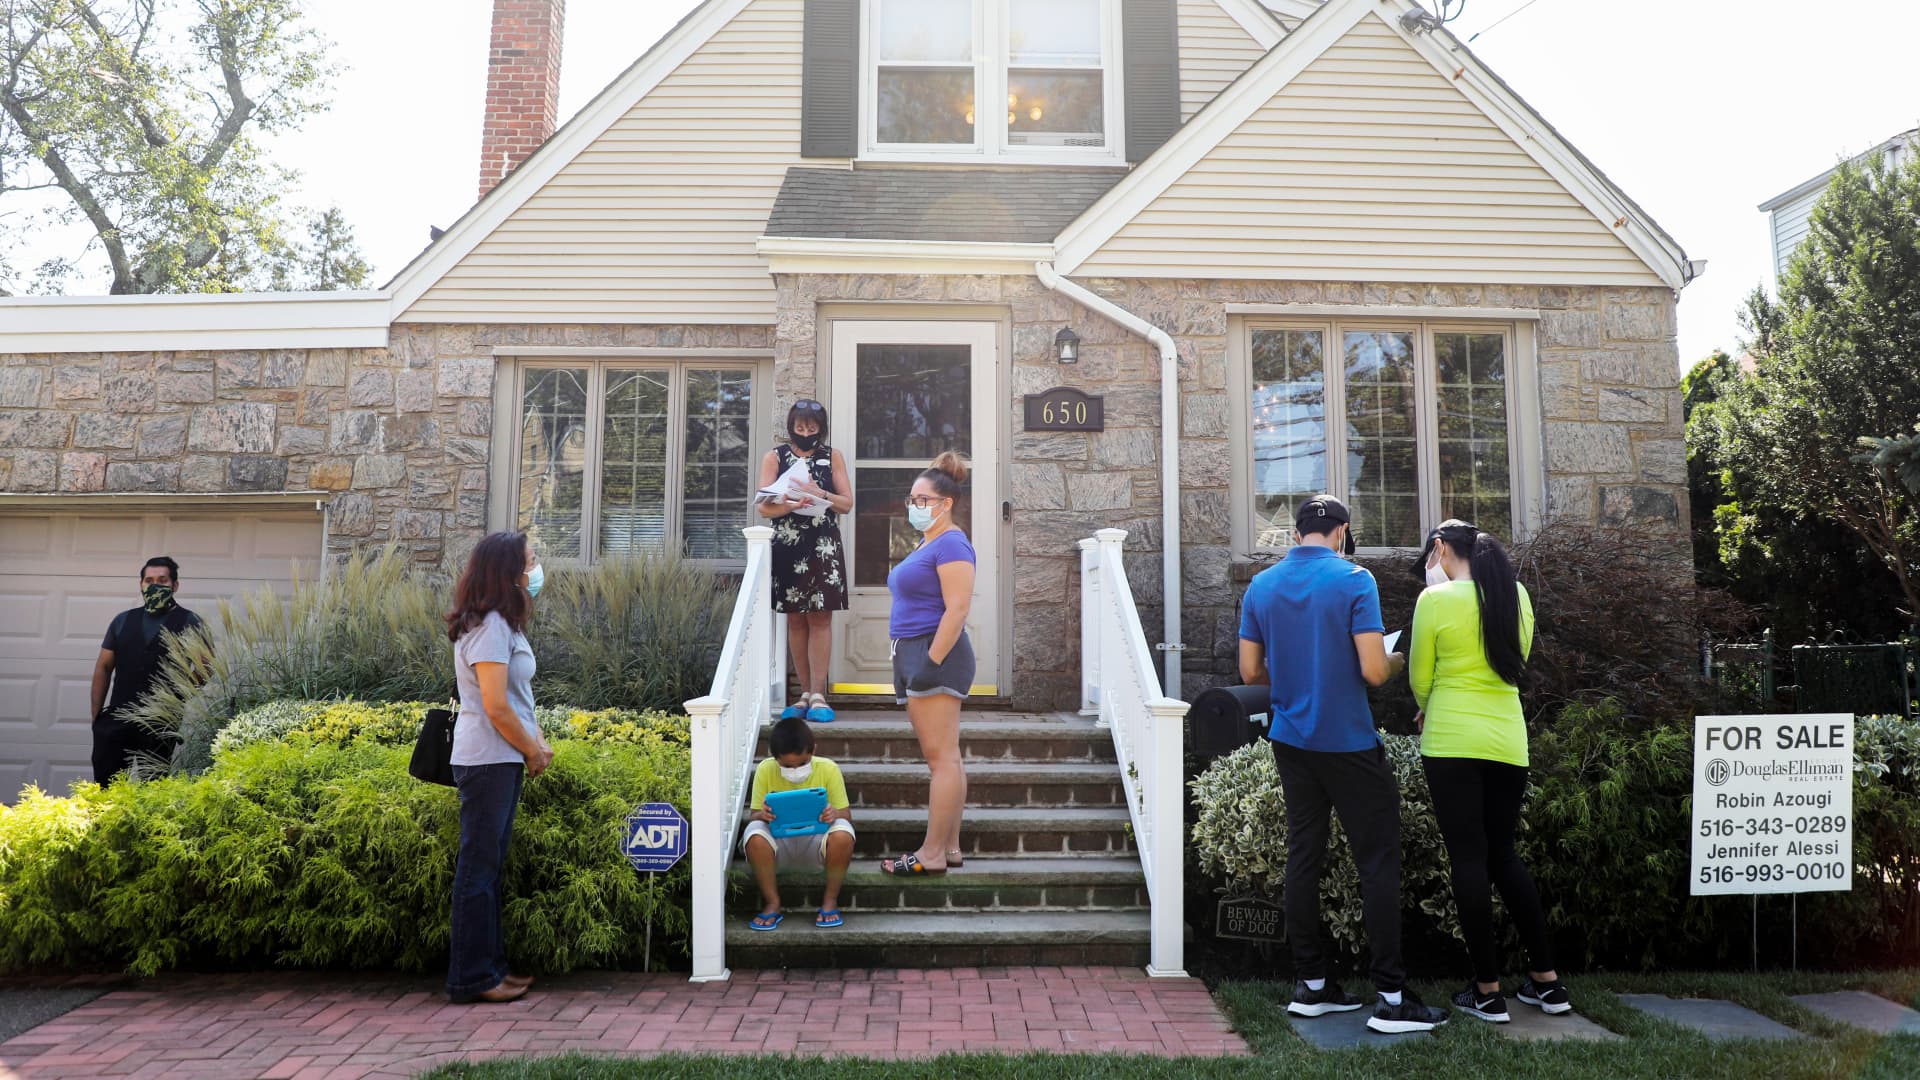
People wait to visit a house for sale in Floral Park, Nassau County, New York, the United States, on Sept. 6, 2020.

Wany Ying | Xinhua News Agency | Getty Images

Mortgage applications inched up last week for the first time since June 24. Total mortgage demand increased 1.2% as the average 30-year fixed mortgage rate made the largest weekly drop since 2020.

Applications to refinance a home rose 2%, according to the Mortgage Bankers Association, but the annual drop was still huge, down 82% since last year.

Applications to purchase a home increased 1% and were down 16% from one year ago.

The slight increases came as mortgage rates dropped 0.31 percentage point from 5.74% to 5.43% following the Federal Reserve announcement of its latest rate hike and the GDP report, which showed the U.S. economy contracted for the second straight quarter.

“Mortgage rates declined last week following another announcement of tighter monetary policy from the Federal Reserve, with the likelihood of more rate hikes to come. Treasury yields dropped as a result, as investors continue to expect a weaker macroeconomic environment in the coming months,” said Joel Kan, MBA’s associate vice president of economic and industry forecasting.  

Kan added that there are some signs of optimism in the housing market. “Lower mortgage rates, combined with signs of more inventory coming to the market, could lead to a rebound in purchase activity,” he said.

The National Association of Home Builders also sees some signs of improvement. According to the NAHB’s Housing Trends Report, after declining for five straight quarters, the share of buyers seeing more homes available for sale rose 5 percentage points to 28% in Q2.

NAHB’s expectations of housing availability also improved. For the first time since 2020, the share of prospective buyers who expect the home search to get easier in the months ahead rose, also increasing 5 percentage points to 22%. Housing availability expectations rose in all regions except the Midwest. In the West, it rose 13 percentage points; in the Northeast, the share climbed 6 percentage points; in the South, it was up 1 percentage point; and in the Midwest, it was down 1 percentage point.


Source link

Mortgage applications inch up for the first time in five weeks Read More »

Rent prices are soaring in these 5 metros. What to know before moving

Rent prices are soaring in these 5 metros. What to know before moving


Los Angeles

Ron_Thomas | Getty Images

As rising interest rates and surging property values prevent more families from buying a home, the demand for rentals has soared, with the highest rent prices in the sunniest states.  

Rent prices for single family homes swelled during the first half of 2022, hitting a national average of $2,495 a month — a 13.4% increase compared to the same period in 2021, according to a new report from national real estate brokerage HouseCanary.

While cities in warmer climes like California and Florida dominated the list of highest median rent prices, midwestern states such as Ohio earned the top spots for most affordable rent, the report found.

More from Personal Finance:
5 markets where home sales are cooling fastest
These 10 U.S. real estate markets are cooling the fastest
Millennials’ net worth more than doubled during pandemic

The findings come as more Americans, including some six-figure earners, are living paycheck to paycheck amid rising costs.

Annual inflation jumped by 9.1% in June, growing at the fastest pace since late 1981, according to the U.S. Department of Labor.

5 U.S. metros with most expensive monthly rents

5 U.S. metros with least expensive monthly rents

Remote work may stunt wage growth 

The pandemic accelerated the trend of leaving expensive coastal cities for more affordable areas as more Americans shifted to remote work.

And a record number of U.S. homebuyers are still eyeing cheaper options from cities like San Francisco, Los Angeles and New York, according to a July report from Redfin. However, remote work may come with a hidden cost.

While many have enjoyed the perks of remote work, research shows it may stunt wage growth over time, according to a working paper published by the National Bureau of Economic Research.

There may be other ‘hidden’ expenses of moving


Source link

Rent prices are soaring in these 5 metros. What to know before moving Read More »

What An Economic Downturn Means for Real Estate Investments

What An Economic Downturn Means for Real Estate Investments


15% ROI”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2021\/05\/large_Extra_large_logo-1.jpg”,”imageAlt”:””,”title”:”SFR, MF & New Builds!”,”body”:”Invest in the best markets to maximize Cash Flow, Appreciation & Equity with a team of professional investors!”,”linkURL”:”https:\/\/renttoretirement.com\/”,”linkTitle”:”Contact us to learn more!”,”id”:”60b8f8de7b0c5″,”impressionCount”:”197839″,”dailyImpressionCount”:”761″,”impressionLimit”:”350000″,”dailyImpressionLimit”:”1040″},{“sponsor”:”Azibo”,”description”:”Smart landlords use Azibo”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2021\/11\/Logo-512×512-1.png”,”imageAlt”:””,”title”:”One-stop-shop for landlords”,”body”:”Rent collection, banking, bill pay and access to competitive loans and insurance – all free for landlords.”,”linkURL”:”https:\/\/www.azibo.com\/biggerpockets\/?utm_source=biggerpockets&utm_campaign=biggerpock ets&utm_medium=affiliate&utm_content=blog”,”linkTitle”:”Get started, it\u2019s free”,”id”:”618d372984d4f”,”impressionCount”:”264372″,”dailyImpressionCount”:”483″,”impressionLimit”:”300000″,”dailyImpressionLimit”:0},{“sponsor”:”The Entrust Group”,”description”:”Self-Directed IRAs”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2021\/11\/TEG-Logo-512×512-1.png”,”imageAlt”:””,”title”:”Spring Into investing”,”body”:”Using your retirement funds. Get your step-by-step guide and learn how to use an old 401(k) or existing IRA to invest in real estate.\r\n”,”linkURL”:”https:\/\/www.theentrustgroup.com\/real-estate-ira-report-bp-awareness-lp?utm_campaign=5%20Steps%20to%20Investing%20in%20Real%20Estate%20with%20a%20SDIRA%20Report&utm_source=Bigger_Pockets&utm_medium=April_2022_Blog_Ads”,”linkTitle”:”Get Your Free Download”,”id”:”61952968628d5″,”impressionCount”:”400315″,”dailyImpressionCount”:”451″,”impressionLimit”:”600000″,”dailyImpressionLimit”:0},{“sponsor”:”Steadily”,”description”:”Best-Rated Landlord Insurance\r\n”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2021\/11\/STEADILY.png”,”imageAlt”:””,”title”:”Fast, Affordable Landlord Insurance”,”body”:”Affordable insurance for rental properties of all kinds, including fix n\u2019 flip. Multi-property discounts available. \r\n”,”linkURL”:”https:\/\/bit.ly\/3FUfGgE”,”linkTitle”:”Get a free quote today”,”id”:”61a51c5a6182e”,”impressionCount”:”155463″,”dailyImpressionCount”:”522″,”impressionLimit”:”390000″,”dailyImpressionLimit”:”3250″},{“sponsor”:”Guaranteed Rate”,”description”:”One-Stop Mortgage Lender”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/01\/927596_CB_BiggerPockets-January-2022-Assets-512×512-1.png”,”imageAlt”:””,”title”:”$1,440 Mortgage Savings*”,”body”:”Whether you\u2019re buying new or cash-out refinancing to upscale the old \u2013 get started today and we\u2019ll help you save!\r\n\r\n”,”linkURL”:”https:\/\/www.rate.com\/biggerpockets?adtrk=|display|corporatebenefits|biggerpockets|july2022_blog||||||||||&utm_source=corporatebenefits&utm_medium=display&utm_campaign=biggerpockets&utm_content=july2022-blog “,”linkTitle”:”Buy or Cash-Out Refi”,”id”:”61ccd6a886805″,”impressionCount”:”95202″,”dailyImpressionCount”:”365″,”impressionLimit”:”200000″,”dailyImpressionLimit”:”2222″},{“sponsor”:”Roofstock”,”description”:”Real estate investing”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/02\/roofstock1644.jpeg”,”imageAlt”:””,”title”:”SFR Marketplace”,”body”:”Build wealth through single-family rental (SFR) investing. Roofstock makes it radically accessible.\r\n\r\n”,”linkURL”:”https:\/\/www.roofstock.com\/bp”,”linkTitle”:”Visit the Marketplace”,”id”:”6217d101980a8″,”impressionCount”:”138290″,”dailyImpressionCount”:”366″,”impressionLimit”:”490000″,”dailyImpressionLimit”:”1633″},{“sponsor”:”Roofstock One”,”description”:”Meet the SFR asset class”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/02\/MicrosoftTeams-image-2.png”,”imageAlt”:””,”title”:”Expand your portfolio”,”body”:”Accredited investors: Access investments in the single-family rental (SFR) sector\u2014no property management required. “,”linkURL”:”https:\/\/www.roofstock.com\/one?utm_campaign=BiggerPockets-Podcast&utm_source=sponsorships&utm_medium=podcast”,”linkTitle”:”Explore Roofstock One”,”id”:”6217fa9c588dd”,”impressionCount”:”144129″,”dailyImpressionCount”:”389″,”impressionLimit”:”490000″,”dailyImpressionLimit”:”1633″},{“sponsor”:”Stessa, a Roofstock company”,”description”:”Keep your houses in order”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/02\/MicrosoftTeams-image-3.png”,”imageAlt”:””,”title”:”Track properties for free”,”body”:”Manage and report on your investment properties with asset management software purpose-built for real estate investors.”,”linkURL”:”https:\/\/www.stessa.com\/bp”,”linkTitle”:”Claim your free account”,”id”:”6217fa9c6258f”,”impressionCount”:”153281″,”dailyImpressionCount”:”419″,”impressionLimit”:”490000″,”dailyImpressionLimit”:”1633″},{“sponsor”:”BAM Capital”,”description”:”Multifamily Syndicator\r\n\r\n”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/02\/Bigger-Pockets-Forum-Ad-Logo-512×512-2.png”,”imageAlt”:””,”title”:”$100M FUND III NOW OPEN”,”body”:”Earn truly passive income with known assets in an award-winning market. Confidently targeting 2.0x-2.5x MOIC.\r\n\r\n\r\n”,”linkURL”:”https:\/\/capital.thebamcompanies.com\/offerings\/?utm_source=bigger-pockets&utm_medium=paid-ad&utm_campaign=bigger-pockets-blog-feb-2022&utm_content=fund-iii-now-open”,”linkTitle”:”Learn more”,”id”:”621d250b8f6bd”,”impressionCount”:”119811″,”dailyImpressionCount”:”282″,”impressionLimit”:”150000″,”dailyImpressionLimit”:”2500″},{“sponsor”:”Walker & Dunlop”,”description”:” Apartment lending. Simplified.”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/03\/WDStacked512.jpg”,”imageAlt”:””,”title”:”Multifamily Property Financing”,”body”:”Are you leaving money on the table? Get the Insider\u0027s Guide.”,”linkURL”:”https:\/\/explore.walkerdunlop.com\/sbl-financing-guide-bp-blog-ad”,”linkTitle”:”Download Now.”,”id”:”6232000fc6ed3″,”impressionCount”:”119967″,”dailyImpressionCount”:”296″,”impressionLimit”:”200000″,”dailyImpressionLimit”:”6500″},{“sponsor”:”SimpliSafe Home Security”,”description”:”Trusted by 4M+ Americans”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/03\/SS-Logo-.png”,”imageAlt”:””,”title”:”Security that saves you $”,”body”:”24\/7 protection against break-ins, floods, and fires. SimpliSafe users may even save up to 15%\r\non home insurance.”,”linkURL”:”https:\/\/simplisafe.com\/pockets?utm_medium=podcast&utm_source=biggerpockets&utm_campa ign=2022_blogpost”,”linkTitle”:”Protect your asset today!”,”id”:”624347af8d01a”,”impressionCount”:”90422″,”dailyImpressionCount”:”282″,”impressionLimit”:”200000″,”dailyImpressionLimit”:”2222″},{“sponsor”:”Delta Build Services, Inc.”,”description”:”New Construction in SWFL!”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/04\/Image-4-14-22-at-11.59-AM.jpg”,”imageAlt”:””,”title”:”Build To Rent”,”body”:”Tired of the Money Pits and aging \u201cturnkey\u201d properties? Invest with confidence, Build To\r\nRent is the way to go!”,”linkURL”:”https:\/\/deltabuildservicesinc.com\/floor-plans-elevations”,”linkTitle”:”Look at our floor plans!”,”id”:”6258570a45e3e”,”impressionCount”:”81446″,”dailyImpressionCount”:”316″,”impressionLimit”:”160000″,”dailyImpressionLimit”:”2163″},{“sponsor”:”RentRedi”,”description”:”Choose The Right Tenant”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/05\/rentredi-logo-512×512-1.png”,”imageAlt”:””,”title”:”Best App for Rentals”,”body”:”Protect your rental property investment. Find & screen tenants: get full credit, criminal, and eviction reports.”,”linkURL”:”http:\/\/www.rentredi.com\/?utm_source=biggerpockets&utm_medium=paid&utm_campaign=BP_Blog.05.02.22&utm_content=button&utm_term=findtenants”,”linkTitle”:”Get Started Today!”,”id”:”62740e9d48a85″,”impressionCount”:”65630″,”dailyImpressionCount”:”325″,”impressionLimit”:”150000″,”dailyImpressionLimit”:”5556″},{“sponsor”:”PadSplit”,”description”:”Co-Living Marketplace”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/05\/Picture1.jpg”,”imageAlt”:””,”title”:”Double your cash flow”,”body”:”Join hundreds of investors on the largest co-living marketplace. Improve your return and help the housing shortage.”,”linkURL”:”http:\/\/www.padsplit.com\/biggerpockets?utm_campaign=H-Host_Content&utm_source=Biggerpockets&utm_medium=referral&utm_content=bp_blog&utm_term=hyperlink-landing_page”,”linkTitle”:”Get a Free Consultation!”,”id”:”628e464abfe5f”,”impressionCount”:”49280″,”dailyImpressionCount”:”316″,”impressionLimit”:”50000″,”dailyImpressionLimit”:”1667″},{“sponsor”:”Guaranteed Rate”,”description”:”One-Stop Mortgage Lender”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/06\/GR-512×512-1.png”,”imageAlt”:””,”title”:”$1,440 Mortgage Savings”,”body”:”Whether you\u2019re buying new or cash-out refinancing to upscale the old \u2013 get started today and we\u2019ll help you save!”,”linkURL”:”https:\/\/www.rate.com\/biggerpockets?adtrk=|display|corporatebenefits|biggerpockets|july2022_blog||||||||||&utm_source=corporatebenefits&utm_medium=display&utm_campaign=biggerpockets&utm_content=july2022-blog%20%20%20″,”linkTitle”:”Buy or Cash-Out Refi”,”id”:”62ba1bfaae3fd”,”impressionCount”:”22068″,”dailyImpressionCount”:”375″,”impressionLimit”:”70000″,”dailyImpressionLimit”:”761″},{“sponsor”:”Avail”,”description”:”#1 Tool for Landlords”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/06\/512×512-Logo.png”,”imageAlt”:””,”title”:”Hassle-Free Landlording”,”body”:”One tool for all your rental management needs — find & screen tenants, sign leases, collect rent, and more.”,”linkURL”:”https:\/\/www.avail.co\/?ref=biggerpockets&source= biggerpockets&utm_medium=blog+forum+ad&utm _campaign=homepage&utm_channel=sponsorshi p &utm_content=biggerpockets+blog+ad+fy23+1h”,”linkTitle”:”Start for FREE Today”,”id”:”62bc8a7c568d3″,”impressionCount”:”24401″,”dailyImpressionCount”:”396″,”impressionLimit”:”200000″,”dailyImpressionLimit”:”1087″},{“sponsor”:”Steadily”,”description”:”Easy landlord insurance”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/06\/facebook-business-page-picture.png”,”imageAlt”:””,”title”:”Rated 4.8 Out of 5 Stars”,”body”:”Quotes online in minutes. Single-family, fix n\u2019 flips, short-term rentals, and more. Great prices and discounts.”,”linkURL”:”http:\/\/www.steadily.com\/?utm_source=blog&utm_medium=ad&utm_campaign=biggerpockets “,”linkTitle”:”Get a Quote”,”id”:”62bdc3f8a48b4″,”impressionCount”:”26052″,”dailyImpressionCount”:”462″,”impressionLimit”:”200000″,”dailyImpressionLimit”:”1627″},{“sponsor”:”MoFin Lending”,”description”:”Direct Hard Money Lender”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/06\/mf-logo@05x.png”,”imageAlt”:””,”title”:”Flip, Rehab & Rental Loans”,”body”:”Fast funding for your next flip, BRRRR, or rental with MoFin! Close quickly, low rates\/fees,\r\nsimple process!”,”linkURL”:”https:\/\/mofinloans.com\/scenario-builder?utm_source=biggerpockets&utm_medium=cpc&utm_campaign=bp_blog_july2022″,”linkTitle”:”Get a Quote-EASILY!”,”id”:”62be4cadcfe65″,”impressionCount”:”29334″,”dailyImpressionCount”:”424″,”impressionLimit”:”100000″,”dailyImpressionLimit”:”3334″},{“sponsor”:”REI Nation”,”description”:”Premier Turnkey Investing”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/07\/REI-Nation-Updated-Logo.png”,”imageAlt”:””,”title”:”Fearful of Today\u2019s Market?”,”body”:”Don\u2019t be! REI Nation is your experienced partner to weather today\u2019s economic conditions and come out on top.”,”linkURL”:”https:\/\/hubs.ly\/Q01gKqxt0 “,”linkTitle”:”Get to know us”,”id”:”62d04e6b05177″,”impressionCount”:”16357″,”dailyImpressionCount”:”438″,”impressionLimit”:”195000″,”dailyImpressionLimit”:”6360″},{“sponsor”:”Zen Business”,”description”:”Start your own real estate business”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/07\/512×512-1-300×300-1.png”,”imageAlt”:””,”title”:”Form Your Real Estate LLC or Fast Business Formation”,”body”:”Form an LLC with us, then run your real estate business on our platform. BiggerPockets members get a discount. “,”linkURL”:”https:\/\/www.zenbusiness.com\/p\/biggerpockets\/?utm_campaign=partner-paid&utm_source=biggerpockets&utm_medium=partner&utm_content=podcast”,”linkTitle”:”Form your LLC now”,”id”:”62e2b26eee2e2″,”impressionCount”:”1017″,”dailyImpressionCount”:”448″,”impressionLimit”:”80000″,”dailyImpressionLimit”:”2581″}])” class=”sm:grid sm:grid-cols-2 sm:gap-8 lg:block”>


Source link

What An Economic Downturn Means for Real Estate Investments Read More »

Rising Interest Rates Challenge Investors — Here’s What Expert Lenders Suggest You Do

Rising Interest Rates Challenge Investors — Here’s What Expert Lenders Suggest You Do


15% ROI”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2021\/05\/large_Extra_large_logo-1.jpg”,”imageAlt”:””,”title”:”SFR, MF & New Builds!”,”body”:”Invest in the best markets to maximize Cash Flow, Appreciation & Equity with a team of professional investors!”,”linkURL”:”https:\/\/renttoretirement.com\/”,”linkTitle”:”Contact us to learn more!”,”id”:”60b8f8de7b0c5″,”impressionCount”:”197029″,”dailyImpressionCount”:”926″,”impressionLimit”:”350000″,”dailyImpressionLimit”:”1040″},{“sponsor”:”Azibo”,”description”:”Smart landlords use Azibo”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2021\/11\/Logo-512×512-1.png”,”imageAlt”:””,”title”:”One-stop-shop for landlords”,”body”:”Rent collection, banking, bill pay and access to competitive loans and insurance – all free for landlords.”,”linkURL”:”https:\/\/www.azibo.com\/biggerpockets\/?utm_source=biggerpockets&utm_campaign=biggerpock ets&utm_medium=affiliate&utm_content=blog”,”linkTitle”:”Get started, it\u2019s free”,”id”:”618d372984d4f”,”impressionCount”:”264372″,”dailyImpressionCount”:”577″,”impressionLimit”:”300000″,”dailyImpressionLimit”:0},{“sponsor”:”The Entrust Group”,”description”:”Self-Directed IRAs”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2021\/11\/TEG-Logo-512×512-1.png”,”imageAlt”:””,”title”:”Spring Into investing”,”body”:”Using your retirement funds. Get your step-by-step guide and learn how to use an old 401(k) or existing IRA to invest in real estate.\r\n”,”linkURL”:”https:\/\/www.theentrustgroup.com\/real-estate-ira-report-bp-awareness-lp?utm_campaign=5%20Steps%20to%20Investing%20in%20Real%20Estate%20with%20a%20SDIRA%20Report&utm_source=Bigger_Pockets&utm_medium=April_2022_Blog_Ads”,”linkTitle”:”Get Your Free Download”,”id”:”61952968628d5″,”impressionCount”:”400315″,”dailyImpressionCount”:”527″,”impressionLimit”:”600000″,”dailyImpressionLimit”:0},{“sponsor”:”Steadily”,”description”:”Best-Rated Landlord Insurance\r\n”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2021\/11\/STEADILY.png”,”imageAlt”:””,”title”:”Fast, Affordable Landlord Insurance”,”body”:”Affordable insurance for rental properties of all kinds, including fix n\u2019 flip. Multi-property discounts available. \r\n”,”linkURL”:”https:\/\/bit.ly\/3FUfGgE”,”linkTitle”:”Get a free quote today”,”id”:”61a51c5a6182e”,”impressionCount”:”154876″,”dailyImpressionCount”:”659″,”impressionLimit”:”390000″,”dailyImpressionLimit”:”3250″},{“sponsor”:”Guaranteed Rate”,”description”:”One-Stop Mortgage Lender”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/01\/927596_CB_BiggerPockets-January-2022-Assets-512×512-1.png”,”imageAlt”:””,”title”:”$1,440 Mortgage Savings*”,”body”:”Whether you\u2019re buying new or cash-out refinancing to upscale the old \u2013 get started today and we\u2019ll help you save!\r\n\r\n”,”linkURL”:”https:\/\/www.rate.com\/biggerpockets?adtrk=|display|corporatebenefits|biggerpockets|july2022_blog||||||||||&utm_source=corporatebenefits&utm_medium=display&utm_campaign=biggerpockets&utm_content=july2022-blog “,”linkTitle”:”Buy or Cash-Out Refi”,”id”:”61ccd6a886805″,”impressionCount”:”94795″,”dailyImpressionCount”:”405″,”impressionLimit”:”200000″,”dailyImpressionLimit”:”2222″},{“sponsor”:”Roofstock”,”description”:”Real estate investing”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/02\/roofstock1644.jpeg”,”imageAlt”:””,”title”:”SFR Marketplace”,”body”:”Build wealth through single-family rental (SFR) investing. Roofstock makes it radically accessible.\r\n\r\n”,”linkURL”:”https:\/\/www.roofstock.com\/bp”,”linkTitle”:”Visit the Marketplace”,”id”:”6217d101980a8″,”impressionCount”:”137869″,”dailyImpressionCount”:”446″,”impressionLimit”:”490000″,”dailyImpressionLimit”:”1633″},{“sponsor”:”Roofstock One”,”description”:”Meet the SFR asset class”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/02\/MicrosoftTeams-image-2.png”,”imageAlt”:””,”title”:”Expand your portfolio”,”body”:”Accredited investors: Access investments in the single-family rental (SFR) sector\u2014no property management required. “,”linkURL”:”https:\/\/www.roofstock.com\/one?utm_campaign=BiggerPockets-Podcast&utm_source=sponsorships&utm_medium=podcast”,”linkTitle”:”Explore Roofstock One”,”id”:”6217fa9c588dd”,”impressionCount”:”143685″,”dailyImpressionCount”:”490″,”impressionLimit”:”490000″,”dailyImpressionLimit”:”1633″},{“sponsor”:”Stessa, a Roofstock company”,”description”:”Keep your houses in order”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/02\/MicrosoftTeams-image-3.png”,”imageAlt”:””,”title”:”Track properties for free”,”body”:”Manage and report on your investment properties with asset management software purpose-built for real estate investors.”,”linkURL”:”https:\/\/www.stessa.com\/bp”,”linkTitle”:”Claim your free account”,”id”:”6217fa9c6258f”,”impressionCount”:”152806″,”dailyImpressionCount”:”526″,”impressionLimit”:”490000″,”dailyImpressionLimit”:”1633″},{“sponsor”:”BAM Capital”,”description”:”Multifamily Syndicator\r\n\r\n”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/02\/Bigger-Pockets-Forum-Ad-Logo-512×512-2.png”,”imageAlt”:””,”title”:”$100M FUND III NOW OPEN”,”body”:”Earn truly passive income with known assets in an award-winning market. Confidently targeting 2.0x-2.5x MOIC.\r\n\r\n\r\n”,”linkURL”:”https:\/\/capital.thebamcompanies.com\/offerings\/?utm_source=bigger-pockets&utm_medium=paid-ad&utm_campaign=bigger-pockets-blog-feb-2022&utm_content=fund-iii-now-open”,”linkTitle”:”Learn more”,”id”:”621d250b8f6bd”,”impressionCount”:”119487″,”dailyImpressionCount”:”306″,”impressionLimit”:”150000″,”dailyImpressionLimit”:”2500″},{“sponsor”:”Walker & Dunlop”,”description”:” Apartment lending. Simplified.”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/03\/WDStacked512.jpg”,”imageAlt”:””,”title”:”Multifamily Property Financing”,”body”:”Are you leaving money on the table? Get the Insider\u0027s Guide.”,”linkURL”:”https:\/\/explore.walkerdunlop.com\/sbl-financing-guide-bp-blog-ad”,”linkTitle”:”Download Now.”,”id”:”6232000fc6ed3″,”impressionCount”:”119630″,”dailyImpressionCount”:”357″,”impressionLimit”:”200000″,”dailyImpressionLimit”:”6500″},{“sponsor”:”SimpliSafe Home Security”,”description”:”Trusted by 4M+ Americans”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/03\/SS-Logo-.png”,”imageAlt”:””,”title”:”Security that saves you $”,”body”:”24\/7 protection against break-ins, floods, and fires. SimpliSafe users may even save up to 15%\r\non home insurance.”,”linkURL”:”https:\/\/simplisafe.com\/pockets?utm_medium=podcast&utm_source=biggerpockets&utm_campa ign=2022_blogpost”,”linkTitle”:”Protect your asset today!”,”id”:”624347af8d01a”,”impressionCount”:”90092″,”dailyImpressionCount”:”367″,”impressionLimit”:”200000″,”dailyImpressionLimit”:”2222″},{“sponsor”:”Delta Build Services, Inc.”,”description”:”New Construction in SWFL!”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/04\/Image-4-14-22-at-11.59-AM.jpg”,”imageAlt”:””,”title”:”Build To Rent”,”body”:”Tired of the Money Pits and aging \u201cturnkey\u201d properties? Invest with confidence, Build To\r\nRent is the way to go!”,”linkURL”:”https:\/\/deltabuildservicesinc.com\/floor-plans-elevations”,”linkTitle”:”Look at our floor plans!”,”id”:”6258570a45e3e”,”impressionCount”:”81096″,”dailyImpressionCount”:”400″,”impressionLimit”:”160000″,”dailyImpressionLimit”:”2163″},{“sponsor”:”RentRedi”,”description”:”Choose The Right Tenant”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/05\/rentredi-logo-512×512-1.png”,”imageAlt”:””,”title”:”Best App for Rentals”,”body”:”Protect your rental property investment. Find & screen tenants: get full credit, criminal, and eviction reports.”,”linkURL”:”http:\/\/www.rentredi.com\/?utm_source=biggerpockets&utm_medium=paid&utm_campaign=BP_Blog.05.02.22&utm_content=button&utm_term=findtenants”,”linkTitle”:”Get Started Today!”,”id”:”62740e9d48a85″,”impressionCount”:”65266″,”dailyImpressionCount”:”390″,”impressionLimit”:”150000″,”dailyImpressionLimit”:”5556″},{“sponsor”:”PadSplit”,”description”:”Co-Living Marketplace”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/05\/Picture1.jpg”,”imageAlt”:””,”title”:”Double your cash flow”,”body”:”Join hundreds of investors on the largest co-living marketplace. Improve your return and help the housing shortage.”,”linkURL”:”http:\/\/www.padsplit.com\/biggerpockets?utm_campaign=H-Host_Content&utm_source=Biggerpockets&utm_medium=referral&utm_content=bp_blog&utm_term=hyperlink-landing_page”,”linkTitle”:”Get a Free Consultation!”,”id”:”628e464abfe5f”,”impressionCount”:”48916″,”dailyImpressionCount”:”418″,”impressionLimit”:”50000″,”dailyImpressionLimit”:”1667″},{“sponsor”:”Guaranteed Rate”,”description”:”One-Stop Mortgage Lender”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/06\/GR-512×512-1.png”,”imageAlt”:””,”title”:”$1,440 Mortgage Savings”,”body”:”Whether you\u2019re buying new or cash-out refinancing to upscale the old \u2013 get started today and we\u2019ll help you save!”,”linkURL”:”https:\/\/www.rate.com\/biggerpockets?adtrk=|display|corporatebenefits|biggerpockets|july2022_blog||||||||||&utm_source=corporatebenefits&utm_medium=display&utm_campaign=biggerpockets&utm_content=july2022-blog%20%20%20″,”linkTitle”:”Buy or Cash-Out Refi”,”id”:”62ba1bfaae3fd”,”impressionCount”:”21635″,”dailyImpressionCount”:”437″,”impressionLimit”:”70000″,”dailyImpressionLimit”:”761″},{“sponsor”:”Avail”,”description”:”#1 Tool for Landlords”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/06\/512×512-Logo.png”,”imageAlt”:””,”title”:”Hassle-Free Landlording”,”body”:”One tool for all your rental management needs — find & screen tenants, sign leases, collect rent, and more.”,”linkURL”:”https:\/\/www.avail.co\/?ref=biggerpockets&source= biggerpockets&utm_medium=blog+forum+ad&utm _campaign=homepage&utm_channel=sponsorshi p &utm_content=biggerpockets+blog+ad+fy23+1h”,”linkTitle”:”Start for FREE Today”,”id”:”62bc8a7c568d3″,”impressionCount”:”23947″,”dailyImpressionCount”:”420″,”impressionLimit”:”200000″,”dailyImpressionLimit”:”1087″},{“sponsor”:”Steadily”,”description”:”Easy landlord insurance”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/06\/facebook-business-page-picture.png”,”imageAlt”:””,”title”:”Rated 4.8 Out of 5 Stars”,”body”:”Quotes online in minutes. Single-family, fix n\u2019 flips, short-term rentals, and more. Great prices and discounts.”,”linkURL”:”http:\/\/www.steadily.com\/?utm_source=blog&utm_medium=ad&utm_campaign=biggerpockets “,”linkTitle”:”Get a Quote”,”id”:”62bdc3f8a48b4″,”impressionCount”:”25529″,”dailyImpressionCount”:”477″,”impressionLimit”:”200000″,”dailyImpressionLimit”:”1627″},{“sponsor”:”MoFin Lending”,”description”:”Direct Hard Money Lender”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/06\/mf-logo@05x.png”,”imageAlt”:””,”title”:”Flip, Rehab & Rental Loans”,”body”:”Fast funding for your next flip, BRRRR, or rental with MoFin! Close quickly, low rates\/fees,\r\nsimple process!”,”linkURL”:”https:\/\/mofinloans.com\/scenario-builder?utm_source=biggerpockets&utm_medium=cpc&utm_campaign=bp_blog_july2022″,”linkTitle”:”Get a Quote-EASILY!”,”id”:”62be4cadcfe65″,”impressionCount”:”28809″,”dailyImpressionCount”:”473″,”impressionLimit”:”100000″,”dailyImpressionLimit”:”3334″},{“sponsor”:”REI Nation”,”description”:”Premier Turnkey Investing”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/07\/REI-Nation-Updated-Logo.png”,”imageAlt”:””,”title”:”Fearful of Today\u2019s Market?”,”body”:”Don\u2019t be! REI Nation is your experienced partner to weather today\u2019s economic conditions and come out on top.”,”linkURL”:”https:\/\/hubs.ly\/Q01gKqxt0 “,”linkTitle”:”Get to know us”,”id”:”62d04e6b05177″,”impressionCount”:”15806″,”dailyImpressionCount”:”499″,”impressionLimit”:”195000″,”dailyImpressionLimit”:”6360″},{“sponsor”:”Zen Business”,”description”:”Start your own real estate business”,”imageURL”:”https:\/\/www.biggerpockets.com\/blog\/wp-content\/uploads\/2022\/07\/512×512-1-300×300-1.png”,”imageAlt”:””,”title”:”Form Your Real Estate LLC or Fast Business Formation”,”body”:”Form an LLC with us, then run your real estate business on our platform. BiggerPockets members get a discount. “,”linkURL”:”https:\/\/www.zenbusiness.com\/p\/biggerpockets\/?utm_campaign=partner-paid&utm_source=biggerpockets&utm_medium=partner&utm_content=podcast”,”linkTitle”:”Form your LLC now”,”id”:”62e2b26eee2e2″,”impressionCount”:”446″,”dailyImpressionCount”:”501″,”impressionLimit”:”80000″,”dailyImpressionLimit”:”2581″}])” class=”sm:grid sm:grid-cols-2 sm:gap-8 lg:block”>


Source link

Rising Interest Rates Challenge Investors — Here’s What Expert Lenders Suggest You Do Read More »

The Calculated Way to Retire Early WITHOUT Giving Up What You Love w/Jessica from The Fioneers


Coast FI is an interesting concept. Unfortunately, to much of Mindy’s surprise, “coast FI” doesn’t mean having enough money to live by the coast. But, just like living down by the beach, the coast FI lifestyle is far more enjoyable than most. We constantly hear from online personal finance bloggers about how you need to save as much as you can, eat at home every night, and never take a vacation. While this does allow you to hit financial independence faster, it makes the journey a highly stressful one at worst and a barely bearable one at best.

What about a different way to reach financial independence? What about still eating out and taking trips, all while working to retire early? This is the path that Jessica from The Fioneers has chosen to take. She and her husband learned about the financial independence movement while they were making just $30,000 per year combined. As their income grew, so did their savings rate. But, Jessica realized that the stress of climbing the corporate ladder wasn’t worth it when she ended up taking a six-month mental health break from her work.

Jessica never ended up going back to work, but she did start working for herself. Now, she’s on the path to coast FI, or as she also likes to call it, “slow FI.” She still takes trips and lives comfortably, but she does so with full autonomy of her time and a plan to retire in her early 50s. She is living proof that you don’t need to burn yourself out to hit financial freedom, and you definitely don’t need to do so just to reach retirement.

mindy:
Welcome to the BiggerPockets Money Podcast show number 323, where we interview Jess from the Fioneers and talk about Coast FI and designing not only your post-financial independence life, but also your life along the journey.

Jessica:
You don’t need to stay in your toxic job for another 10 years just to get to this point of eternal bliss. Because it’s not actually going to turn out that way. And so I needed to hear those messages to say, “Okay, I can do this, but I can take a different path that focuses on both getting to financial independence and financial freedom in the long term and designing my life.

mindy:
Hello. Hello. Hello. My name is Mindy Jensen. And with me as always is my stunningly bearded cohost, David Pere.

David:
It’s coming in nice, isn’t?

mindy:
It is. It’s really filling out, almost as good as mine.

David:
I don’t like the little gray patches in here like I’m old.

mindy:
David and I are here to make financial independence less scary, less just for somebody else to introduce you to every money story, because we truly believe financial independence is attainable for everyone, no matter when or where you are starting.

David:
Whether you want to retire early and travel the world, go on to make big-time investments in assets like real estate or start your own business, we’ll help you reach your financial goals and get money out of the way, so that you can launch yourself towards your dreams.

mindy:
David, I am so excited to talk to Jess today, because she has a different perspective. We’ve never really featured Coast FI on our show. And I really what she has to say about it. The Coast FI ideal is not this just hard and fast furious, “How do I get to financial independence as fast as possible?” It’s more enjoying the journey along the way. And I think that I wish I would’ve heard about this before we started our path to financial independence, my husband and I.

David:
I think it’s a good way to try to find some balance throughout a financial journey. Because a lot of people try to either compress it as quickly as humanly possible and they hate themselves for all the years they’re doing it or they don’t do it at all and they get to retirement and go, “Oh crap. Hopefully my kids have money to support me.” So I like the middle ground there. I think it’s good. I think a little balance is good in life.

mindy:
I do like the balance. It’s a balanced approach to financial independence. That’s a great way to phrase it. Joining us today is Jess from the Fioneers. Jess lives in a van down by the river, hoping someday to be unemployed.

Jessica:
Well, Mindy, that’s not exactly true, because I do hope to do work that I love forever. So I don’t ever actually plan to retire early. And I don’t quite live in a van down by the river. I do have a van that lives in my driveway that I take out for short and long trips over the course of the year.

mindy:
Okay. So I’m super excited to talk to Jess today, because we are going to hit a lot of things. We’re going to talk about Coast FI versus Slow FI and camper van life. And we’re going to talk about the journey to financial independence, not just the end. And we’re going to do all of these things today with Jess from the Fioneers. So Jess, welcome to the BiggerPockets Money Podcast.

Jessica:
Thanks so much for having me.

mindy:
So let’s jump right into it. Let’s start with Coast FI versus Slow FI. What’s the difference?

Jessica:
So Coast FI is a specific number where based on your age and your spending here is the amount of money that you need saved and invested so that you can not add any more money to your retirement accounts, but it will grow to provide you with a comfortable, traditional retirement at the age that you choose, 60, 65 or earlier. So basically once you reach Coast financial independence, this means you could scale back and only cover your actual costs of living with active income. So that gives people a lot of freedom and flexibility to be able to do work that they enjoy more and to do less of it.

David:
So it’s like instead of… A lot of people, their FIRE, right? so their number, let’s say their number’s $40,000 a year and at the 4% safe withdrawal rate, they’re like, “Hey, I need to have a million dollars saved by the time I’m 30, so that I can retire.” And you are saying, “Well, if the million dollars is your goal, then maybe by the time you’re 30 or by the time you’re 25, if you had 250 saved, you could look at the math and go, “By the time I hit retirement, that’ll be a million. So now I can enjoy life.””

Jessica:
So I actually have a Coast FI calculator that I just pulled up. And so for someone who spends $40,000 a year, their larger FI number eventually is 1 million. At the age of 30, they would only need $181,000 invested toward their retirement, which is still a lot of money, but nowhere near the 1 million that they would eventually need to have. And so giving it time to grow in the market really can benefit people.

mindy:
And that’s assuming you’re not putting any more money into the accounts. I would… oh, the frugal investor saver in me would to encourage you to continue to put money in those accounts, although maybe not at quite the same pace that you were before. I love a good 401(k) match and I love a Roth IRA max. And listen to the nerds that we are here. I love HSA maxing for all the things that life can throw at you. But I like this idea too, where if you’re just learning about financial independence… I say this all the time and people make fun of me and that’s okay, because it’s my show. I can say what I want, but personal finance is personal and you don’t have to do it my way. You can do it Jess’ way or David’s way. Or you can combine all of our ways and do it your own way.

mindy:
If your name’s Bob and you’re listening, you can do it Bob’s way. It can be your own choose your own adventure. Remember those books? You can choose your own adventure and as long as you get there, it’s really just getting people thinking about their money, because we’ve all seen those studies where 40% of Americans can’t pay for a new tire on their car. They can’t float a $400 emergency or a $1,000 emergency. And that’s just sad. That gives me breathing problems when I hear about that.

Jessica:
I definitely agree with you on the Coast FI front that many people would benefit from continuing to save at least some. I just think once you get to that point of Coast FI, you have so many more options. So I think of it as there’s three main options. One is you can continue to save at a high rate and now you know that every dollar you save and invest is going toward an early retirement. It’s no longer going toward a traditional retirement. The second option is scale back completely and only cover your actual costs. So if you only spend 40 to $50,000 a year, you could only generate 40 to $50,000 a year. And if you come from a higher income earning profession, you could do that doing consulting work or doing contract work for your former employer or working part-time, that kind of thing.

Jessica:
Or, and this is what I’m doing, the third option is saying, “I’ve reached Coast FI and I’m going to use that to give me a feeling of freedom to start making significant life changes.” So for me, that gave me the feeling of freedom to take a six-month career break in 2018 to deal with a mental health challenge. It gave me the feeling of freedom that when I went back to work, I decided to go back to work three days a week. And when I had an opportunity to increase my hours, I decided not to, because I loved the super chill schedule that I had. And then it gave me an opportunity to start a business. And then that business then allowed me to be able to quit that part-time job.

Jessica:
And so it enabled me to do all of these things and we’re still saving. We’re not saving at the same rate that we were previously, around the 50 to 60% mark. But It also enabled us to say, “We’re going to only save 20% this year, because we’re buying and building out this camper van.” And so we got to choose also to spend quite a bit more money for a short period of time as well.

mindy:
You just gave me a whole bunch of things I want to unpack. So let’s rewind to 2010, 2012, 2013 and talk about where you were saving at… well, actually let’s let’s you decide where we start. When did you discover financial independence?

Jessica:
So I actually didn’t discover financial independence until about 2017, but my husband knew all about financial independence from 2010 onward. And every year we would sit down with our anti-budget and he would say, “Let’s just say 5% more every year.” But it wasn’t until 2017 that he gave me Your Money or Your Life in a book swap. We each gave each other a book to read. Just he was saying, “I just want you to understand my perspective.” And then from there I was in it.

mindy:
That’s a great book. That’s a wonderful book. And it’s not even about financial independence. It’s just about trading your time for money. So your husband knew about this. So you were savers?

Jessica:
We were savers. Yeah. So if we go back to the early 2010s to 2015. So we had just graduated from college in the middle of the recession and started out with extremely low incomes. So he worked part-time at university. I did a year of AmeriCorps where I made $11,000 a year before taxes. And we lived in Northern New Jersey, so right outside New York City. So we had a combined income of less than $30,000. And we had to have our finances on point, because it was out of necessity. And we had a commitment, and I think it came from our upbringing, that we were going to do everything we could not to go into debt. That wasn’t a thing that seemed an option for us. And so that was our introduction to finances generally.

Jessica:
And so when my husband learned about financial independence, he was like, “Oh, well, this isn’t really, for us. We make too low of incomes. We work in nonprofits,” but some of the ideas resonated. And so when we did start to grow our careers and make a little bit more money, he was like, “Okay, now we can save a little bit. We can save, now that we’re past subsistence, we’re able to…” It’s funny, I have a budget back from 2011 or 2012 or something where he earmarked the entire raise to go towards savings and investments. And I was like, “No. No, we’re not doing that. We do we do nothing. We spend no money right now. We are going to get a better apartment and not have to go to the laundromat. Something that has a washer and dryer. And we’re going to go out to dinner once a month.

Jessica:
And so we definitely had that push and pull of “I want to spend more and have a better life,” and him wanting to just save every, every penny of it. But then over time, our income did increase, but we had a really solid foundation and not a ton of lifestyle inflation, because in those early years we had to really cut those expenses quite a bit.

David:
So obviously there’s a benefit to the fact that in 2010, the market’s seen a great run up. So even if you’d only contributed a little bit to investing, you’ve done pretty well with it. But everybody listening right now is going, “How in the world did they save any money on $30,000 a year in one of the more expensive places in the nation?” That’s bonkers to me. So I’m curious.

Jessica:
We didn’t. So to be clear, that year, we didn’t.

David:
Okay. Okay. I was like, “Man, what percentage where you guys…” Even 5%, at that point, would be impressive.

Jessica:
No. We, at that point, we were just trying to be in the black. That was our goal at that point in time was just not going to debt with the income that we had. It took us increasing our income to be able to start saving and investing. But then that’s when my husband then would see, “Oh.” We’d take a pay increase and he would make the new budget and earmark all of it towards saving and investing. And so that was the situation. So two to three years in when we were starting to make a little bit more.

David:
I would definitely be on your side, like, “No, man. We are going to go eat a cheeseburger this month. So 75% is going to the budget,” to you savings.

Jessica:
And we did eventually get to a good place where we were spending more and improving our quality of life and saving more. But at that time we were saving 10% and then maybe it increased to 15% and then 20% and then by 2016, I don’t remember the numbers exactly, we have a chart of it on our website, but by 2015, 2016, we were saving maybe 33% of our income. Then 45, then 50. And so we were able to continually increase that over time as we increased our income.

David:
Anything over 10% is impressive. Anybody listening to this, who’s thinking, “Oh, I can’t save 50, 60%.” Okay, first off, they built into that. And second, if you’re saving more than 10%, most people don’t do that. Most people don’t even do 10% tithe. They’re like, “I’m super religious and I don’t do that, because I can’t afford to.” I hear that. And so saving 10%, we’re just men in Babylon or whatever, that’s enough. If you’re consistent with that, that can be enough. But definitely the more you crank that up, the faster things go.

mindy:
So what sort of income are we talking about in 2015, 2016. And where are you living? Are you still in Northern New Jersey?

Jessica:
We actually moved to Boston, Massachusetts in late 2013.

mindy:
A cheaper place?

Jessica:
It was actually more expensive. And I’m trying to think. Around that time, neither of us was making six figures salaries, but combined we were in the six figures at that point.

mindy:
Okay. So there’s much more room here to breathe.

Jessica:
Yes, yes.

mindy:
Okay. And then saving… I don’t want to belittle what you’re doing, but saving 33% when you’re making $30,000 living in New Jersey is like, okay, we got to get tips on that. So where were you investing this money when you were saving 33% and 50%. And I agree with David, I think that we don’t do enough of celebrating. Yay, Jess, that’s amazing saving. Honestly, I’m going to go further than David and say saving anything is fantastic, because so many people in America are like, “oh, I’ll do that next year. I’ll do that next year.” And next year never comes. Next year always comes, but the I’ll do it next year part never comes. So saving 33% is fantastic when this isn’t really what people are talking about and saving 50% is even better than saving 33%.

Jessica:
So we were saving it and investing it mainly in our employer retirement plans. So our 403(b)s or 401(k)s, depending on where we were at any given time and into Roth IRAs at the time. We worked up to being able to max those plans out, but it took years to be able to get to that point, especially since we started and spent most of our careers, both of us, my husband and I, in nonprofit organizations.

David:
That’s kind of what I was talking with Mindy before we recorded. She mentioned Coast FI and I was like, “Never heard of that. What’s that?” And she gave me the super quick rundown and I was like, “Oh, okay. I tell service members a very similar thing. It’s like look, when you first join the military, if you can max out your TSP. And that’s not an easy thing, but that’s our 401(k). But even if you can’t max it out, if you can just contribute the most you possibly can. And if you do that for three or four years and not to say that means when you’re 65, you’ll never have to work again because it’ll be enough. And you should continue to invest at least the matching contribution.

David:
But if you do that for those first three or four years, I’m a big real estate guy, you can’t really invest in real estate your first few years for various reasons. Not having a housing allowance, probably stationed overseas, whatever. Well, then you’ve done that for three or four years. Now you’ve got a safety net that allows you to take a few larger risks, because you know that you’re not going to fall flat out on your face. And so that’s what I about this is the matching employer, tax advantage, matching contributions, people, to use the hipster word, the cool kid word, people sleep on matching contributions, because they’re like, “Oh, well, yeah, it’s only 5%.” But if you put 5% in and you get a 5% match, that is a instant, guaranteed, 100% return on investment and essentially a pay raise that you’re missing out on if you don’t take it. And I love the whole tax advantage thing. So I like it.

mindy:
Let’s move to 2017 where you got Vicki Robins, Your Money or Your Life. And what book did you give your husband? Do you remember?

Jessica:
Oh, goodness. I am ashamed to say this, but I was in my super, “I’m going to climb the corporate ladder,” period of my life. And so I gave him Lean In and now I’m like, “I hate that book. That book ruined my mental health.” But luckily he gave me Your Money or Your Life, which helped me get out of that brain space.

David:
I was waiting on you to be like, “I gave him the book, do yourself a favor and love your wife” or something like that. Like “Babe, our marriage is terrible,” and he’s like, “Our finances.” But that’s equally as funny.

mindy:
I almost guessed Lean In.

Jessica:
Why?

mindy:
I don’t know, because it’s the opposite of Vicki.

David:
Mindy’s telepathic.

mindy:
And I’m telepathic. Did you read the book right away?

Jessica:
I did. Yeah. I read it right away and when I first read it, I was like, “This is funny. I don’t know about this.” And then I got further into it and I was like, “Wait, people actually do this? There’s math behind the fact that you could get to a point where you don’t need to work anymore?” I think I had just always assumed you find a job that you hopefully don’t hate and you do it for 40 years and maybe, just maybe you’ll have enough that you can retire someday. And I never really knew that there was a number and there was math behind it. And so I started to see that and understand that. And then when it got to the point in the book where she was talking about, “Well, what would you do if you didn’t need to work for a living?” And that question was really tough for me, because I had invested so much time and energy and brain space into my career up to that point that I couldn’t answer it.

Jessica:
I didn’t even know what I liked to do anymore. I didn’t know who I was. And so from there I went through, I don’t know, this period of self discovery to say, “Well, what would I do? What do I actually enjoy? What would I want to do if this whole work thing didn’t have to be part of my life?”

mindy:
And what did you come up with?

Jessica:
So it was interesting. I came up with that I would want to have some creative outlet. So I thought maybe that would be writing. So I ended up starting my blog later. I thought about doing some career coaching since my career had been in human resources up to that point and thought that it would be fun to help people in that way. I thought about volunteering on political campaigns, traveling the world, taking photographs. There was a bunch of different ideas that came up for me over the course of a six-month period of time before I felt I was ready to say, “Okay, I can commit and I want to move forward with this FI thing.” And a lot of those things are coming to reality in my life now long before FI, which is really exciting to see.

mindy:
You just said something that I think is really important to highlight. You said, “This came up over the course of about a six-month time.” I think that when people discover financial independence, they’re like, “Okay, I win it now.” Well, yeah, don’t we all. I want to win the lottery too.” Or, “I’m unhappy with my life. I want to change now.” Well, that’s when you are going to jump from the frying pan into the FIRE. Don’t expect instant change. You didn’t get into the position that you’re in right now, most likely you didn’t get there overnight. Your corporate unhappiness, let’s call it, didn’t happen overnight. You graduated from high school or from college, you started your job like, I’m sure, full of excitement and “Oh, this is going to be great. And I’m going to change the world,” because you were in nonprofit. So I’m assuming that you were like, “I’m going to change the world,”

mindy:
And then you get there. You’re like, “Oh, that’s how it is.” And then you’re, “I’m going to do something different and I’m going to… And I’m going to…” And all of a sudden you’re like, “Wow, this life is really not as exciting as I thought it was going to be. I was really expecting, “You can do anything you want and you can be anything and it’s going to be great.” And adulthood isn’t the best thing ever. It’s better than the alternative. I would love to continue to get older and older and older, but your life is what you make of it. And working for the man is, how do I say this? Not really making the most of it. So let’s get this stuff figured out ahead of time, but you are not going to figure it all out in one day.

mindy:
We just talked to Doc G about his new book. He made me cry when I was talking to him, because I’m like, “You’re asking these questions that I can’t answer right now. And I need to answer them, because I’ve been thinking about a lot of things lately and what am I going to do 10 years down the road? How am I going to set myself up now to be there? And this is really heavy, Doc G.” He’s like, “Yeah, it wasn’t supposed to be the light fair.” I’m like, “Well, you need a disclaimer on the front of the book.” But over the course of a six-month time, you got there. I love that. It’s not an instant.

Jessica:
And I would also say that the process is ongoing too. It took me six months to figure out here some of the things that maybe I would want to do and try out. And then it took another year to actually get out of the toxic job, start actually trying things out, get into a job that was much better, that gave me more freedom and flexibility to do some more of the things that I wanted. And then it continued to evolve over time. And I think there’s this big vision and there’s the… I have a set of things that “These are the things that I… Like the pillars. These are the things in my life that are the most important to me,” but those things look different in different phases of life as I get closer and closer to figuring out what ideal really looks and feels like in this moment.

David:
I like that. It’s easy to get lost in the journey to building wealth and then look up one day and go, “Oh crap.” A lot of times and a lot of people seem to let things suffer. So what’s it all for? If you hit 45 and you’re like, “Woohoo, I can retire. But my relationship’s trash, my health is gone and I have no friends.” So that’s not the retirement you envisioned.

mindy:
My husband wrote an article for his blog called Death March to FI and I’ve mentioned it a few times on the show before, but we had this epiphany just like you, “Wait, I don’t have to work till I’m 65? I could become financially independent and quit my job? Great. I’m going to do that and just focus.” We focused on that and we stomped down that path and we got there and then he didn’t quit, because he wasn’t sure. Because even though it’s just a math number and the 4% rule says you can do it. We got to our FI number and I was like, Yeah, you can quit now.” And he said, “Well, maybe one more year.” He did one more year and he’s now been retired for five years. And the day after he quit, he’s like, “Oh, I should have done this years ago.”

Jessica:
And actually his article that he wrote about that was one of the things that inspired us to take a different path. So I think we were getting into the FIRE movement. Let’s say if it’s been five years, that’s probably right around the time that he wrote that article. I think it was 2016 or something, 2016, 2017 that he wrote that. And when I first learned about FI I then was starting to see all of the OG FIRE bloggers and content creators start talking about how they went too fast and they went too hard and the death march to FI and Mad Fientist was talking about that. And JD Roth was talking about how reaching FI didn’t fix all of his problems and all of that. And so I actually needed to hear those messages from people to say like, “You don’t need to go all in on this. You don’t need to stay in your toxic job for another 10 years just to get to this point of eternal bliss. Because it’s not actually going to turn out that way.”

Jessica:
And so I needed to hear those messages to say, “Okay, I can do this, but I can take a different path that focuses on both getting to financial independence and financial freedom in the long term and designing my life along the way, so that it matters less whether I reach FI really quickly.”

mindy:
I think that our journey could have been significantly better without being significantly longer. We had this goal and because when we started this, nobody was talking about the journey. It was always the end result. So I love that you took that… I want to tell him, did you tell him that his…

Jessica:
Mm-hmm.

mindy:
Okay. I want to make sure that he knows that article helped shape your path, because that article is not fun to read. It’s kind of depressing to read. I’ll link to it in the show notes, so everybody can read this horrible… he’s lamenting this journey and he was really sad about it when he stopped to think about it and it’s not a happy, lighthearted article.

David:
You know what’s funny about that. So I mentioned that this is something like… Well, Mindy, you’ve heard me and Alex talk about it. “Well I achieved whatever. And now what?” I was talking to someone just yesterday about this, because I had Mike McCarthy on my podcast and we talked similar. Once you get to a point and you’re like, “Holy crap, I let all these other things go.” I always said it’s akin to when service members get stationed on Hawaii, they get stationed there for two years, three years. And a lot of them don’t it because they’re essentially trapped on this island and things are expensive. And if they’re not a big beach person, what else? And I was like, “Yeah.” Every time I heard someone complain about that, it’s like, “Dude, just shh.” There is not a single person stuck in Missouri or Arkansas or Utah who cares to hear you be like, “Oh, I got stationed in Hawaii. This is terrible.”

David:
And it’s like this unspoken thing, because it’s like, “I achieved complete and total financial freedom. I’m a millionaire. All these buzzwords, whatever. And it’s not as great as I thought.” Everybody who hasn’t achieved that yet is just going to be like, “Oh, that sounds so terrible that you don’t have to work anymore.” And so it’s cool to hear that he, he went through with that, because it doesn’t get talked about enough and it’s a very real problem where people reach financial independence and go, “I don’t have a hobby. I’m whatever.” Whatever that thing is. Somewhere along the way, they stopped enjoying life. And then it’s not like this light switch where you’re like, “Now I can enjoy life again.” It’s a lot harder than you think to… Once the money problem solved, you realize there’s a lot bigger problems out there. And it’s an interesting conundrum that’s hard to say publicly because nobody cares.

Jessica:
Mindy, you said something a second ago that I want to follow up on. You said, “I think we could have made a bunch of changes on our journey to make it better that wouldn’t have increased the timeline.” And I think that’s something that I have experienced and that I see so often among people who are taking a slower, happier path to FI. So for example, for me, so I took that six-month career break and then I went back to work part-time and we assumed, so I have an article on the website that I wrote, that the assumption was this was going to add two to three years to our FI timeline to make this decision. But it was worth it, because I’m buying some of my time back now. And one year later come to find out our savings rate was exactly the same, because it had actually just reduced the stress and anxiety that was causing us to overspend in the first place on things like convenience, escape. We were able to make more of our own food at home.

Jessica:
We didn’t get takeout as much. We didn’t have to buy the super expensive, pre-made stuff at the grocery store. Or we didn’t feel like, “Oh, I’m going to take this expensive vacation, because I deserve it. I’m going to check for the travel deals, because now I have an extra 20 minutes to sign up for a new credit card,” or something like that. And so we started, when we looked back at it, we realized we were saving $1,500 a month or not spending $1,500 a month on things that would fall into the buckets of convenience and escape. And so our FI number didn’t change at all. So it was like, “Okay, well I guess we can just keep going on the path and making the changes.” And so once we realized that, it was like, “Okay, so there’s no need for me to try to work more and increase my hours at my job.”

Jessica:
And then I started thinking about, “Okay, people who reach financial independence, they often still do work. They often do work that they and they often still get paid for it.” Somehow, some way. And it seems the majority of people, especially if they’re people who are ambitious enough to reach financial independence, maybe they need a period of time to de-stress and get through the burnout and all of that. But after a while it’s like, “Okay, great. Now I’m ready to do something, some sort of creative thing.” And so I saw that amongst people who had reached FI, And so I was asking myself, “How can I figure out what is the work that I would love to do after reaching financial independence, like all of these people are doing. But can I figure out if there’s a way to generate income doing that work so that I could just transition to doing that long before FI, so that I don’t have to wait the 10 years just to make more money and then over-save for retirement.

Jessica:
And so it was the lessons that learned from Carl and from so many other folks in the space that made me say, “Okay, let me then use this extra time and energy I have now to figure out the business that I would want to start,” even if I didn’t need to generate any money doing it.

mindy:
So what was your financial position before you took your let’s call it a six-month sabbatical. Before you took your six-month sabbatical, what was your financial position in terms of your Coast FI number?

Jessica:
So I didn’t know about Coast FI at that time, I don’t think we were quite there yet. I think we were close. But definitely had a good amount of emergency savings that allowed me to be able to say, “Okay, I’m just not doing this anymore.”

mindy:
And in terms of your husband’s income, what percentage of that were you spending?

Jessica:
So collectively our incomes were at that time about the same and we were saving about 50% and so total of combined. And so we then during that period were spending close to 100% of his income. And then I did receive a short-term disability insurance, because it was a mental health crisis issue. Yeah, so I received 60% of my salary, so we were actually able to save that portion once it actually came in, because it took months and months for them to actually approve it and payment it.

David:
Wait. Insurance wasn’t immediate?

mindy:
Shocking. And did that insurance… was that for an entire six months when it eventually came in or was it for a shorter period?

Jessica:
It was for five of the six months.

mindy:
For five. Okay. Okay. I don’t know how that insurance works. So that’s good. There was a bit of a cushion, but even if there wasn’t, you could have quit that job, taken… Now I called it a sabbatical. Did you ever go back to them or did you completely cease employment with them?

Jessica:
I completely ceased employment with them. Yep.

mindy:
When you took your sabbatical, did you have a plan to take six months off or were you just going to stop working until you had recovered?

Jessica:
So actually I did not have a plan at all. So I actually talk a lot about mental health on my blog, but I actually just started having severe anxiety and panic attacks and just could not go to work and assumed it would be a couple days, then a couple weeks. And then it turned into about six-month period of time and then decided to not return to that employer afterward.

mindy:
But you started off with the idea that you would go back?

Jessica:
Mm-hmm. Yes.

David:
I also like that you mentioned the piece about being able to start a business that you would like to and enjoy without it having to make money right away. I just want to hone in on that, because there’s this I always jokingly call it the BMW phase, below minimum wage. And everybody I know who started a business, for the most part, hasn’t made money in the first little while. People assume… And don’t get me wrong. There are ways you can franchise, you can buy into a business, you can do whatever. But if you’re building something from scratch, especially something like a blog where there’s a content piece, you’re going to be paying to build that for the first little bit. I don’t think I saw a month out of red for the first 18 months. And then it was mediocre for the next six.

David:
It wasn’t until two years, two and a half years in that I was like, “Hey, I’m getting paid to do this and I enjoy it.” And so I think that’s the best time. When you can say, “Hey, I can afford to do this from a time perspective and a money standpoint, it’s not going to break the bank for me to put some work into this thing. And if it works great and if it doesn’t work, it’s not going to put me on my butt.” We grazed over it, but I was like, “Man, there’s a lot of business or entrepreneur or side-hustle minded people on here who probably should at least hear, “This is why that cushion’s nice, because you can afford to take a little bit of risk without it being the risk of ruin.”

Jessica:
And I actually really loved and would highly recommend, if it’s possible for people, to start a business while they’re working part-time and have a stable income, because I did feel that allowed me to make decisions in the business that were long-term strategic. “Is this what I really want to be doing?” kind of decisions, rather than the short-term “What’s going to make me money immediately” kind of choices. And so for me, I think that actually helped me to grow the business more quickly to a point that I was able to become an entrepreneur and quit the part-time job, because I had that long-term perspective and was able to say, Am I this business in a way that feels like how I would want it to feel if I was FI?” And I would not have been able to approach it in that way, and I don’t think I would be enjoying it as much as I currently do, if I did not have the cushion to be able to approach it that way.

mindy:
So you started your digital marketing business while working part-time for another business, not competing businesses, correct?

Jessica:
No, I was working part-time for a nonprofit organization.

mindy:
Okay. I just want to throw that out there. If you are already a digital marketer, don’t start a digital marketing side business. Your boss may find out, your boss will find out and then will get very angry with you. So what did that look like, starting your own business?

Jessica:
So actually I worked with a nonprofit organization and I actually started my blog in 2018. And so my work has historically, my career background has been in human resources and organizational development and training and adult learning and that sort of thing. And so when I transitioned my blog into a business, I decided to do lifestyle and career coaching. So using all of those skills that I had built to run group programs focused on helping people design lives that they truly love, that they wouldn’t want to retire from. So all of these things that we’ve been talking about on the podcast, so bringing people, in a group context with a supportive community, through a lifestyle design process to figure out “What is it that I want? How can I then dream even bigger and then start to experiment and take steps toward those things that I want and continue that cycle?”

mindy:
How long did it take you to get your business up and running before you felt comfortable quitting your job completely?

Jessica:
So it was about nine months. So it happened actually a lot more quickly than I expected. When I started the business, I was like, “Well, maybe this’ll generate me a little bit of income that’ll let me semi-retire in three to five years or something.” So that was my initial plan with it. And then realized, “Oh, no, I can make real money doing this.” And so I was to a place where I was replacing my income from my part-time job. But although I wanted it to be like it could cover our full expenses before quitting. It didn’t get there, but there were a few frustrations at work. And I was like, “It’s replacing my income. I don’t need to put up with the BS at work anymore.” And so it definitely gave me the freedom to leave. And I would say several months earlier than I was even expecting to after I had figured out, “Wow, this is a viable career option now.”

mindy:
And how many hours were you working at the job versus how many hours are you working now at your own company?

Jessica:
So at the time, I was working 24 hours a week and commuting. So I was on site with a half hour commute each way. So I was working three days a week and then I was working on my business the other days a week, sometimes in the evening, sometimes the weekends. I would imagine I was putting in like 20 hours a week into it. And now I work 25 to 30 hours a week total just on my business. So I have a lot of free time, which I absolutely love. That’s part of building a business that I would want to… that is the vision of what it would be, even if I didn’t need to work for income, and I think that’s the question that I’m asking myself is “Can I run this business as if I’m financially independent and still generate the income that I need?”

Jessica:
And I think that’s what I’m talking about…. going back to your comment, Mindy, about how people could make changes and still work toward financial independence in a similar timeframe. I see people making changes like this, transitioning to self-employment or going freelance or going part-time or different options. And oftentimes it doesn’t change their timelines all that much, because they make a little bit more money than they expected, or they spend less money than expected. And so I think people can make shifts a lot earlier in their path to FI and I think that’s what I want to use my experience to help more people understand, because it seems like in the FI movement, sometimes we don’t realize that we can use our freedom along the way.

mindy:
Absolutely. I think there’s not enough people talking about the journey can be enjoyable. And I love the tip to start a business if that’s something that you want to do post-FI start it pre-FI. And start it while you’re still working and generating income, because then you’re not relying on just this one thing. You could, I don’t know if you know this, you were working 40 hours a week, 45 hours a week. You could work 45 hours a week now and make even more money. You said you have all this free time.

Jessica:
I could, if I wanted to.

mindy:
If you wanted to. So what your future look like? And in terms of your Coast FI number, where are you right now?

Jessica:
So we have reached Coast financial independence. If we were to scale back completely and not add another dollar to our retirement accounts, we would be on track to retire early in our fifties. So we are a little bit past that Coast FI milestone. And to full financial independence, we’re 42% of the way there.

mindy:
Oh, nice. Okay.

Jessica:
So then in the future… So I think that’s a great question, because we’re still in some ways figuring that out. So my husband is still working in his full-time job. He actually really enjoys it and I’m getting ready for him to be done. So it’s good right now that he’s doing that, because we just had a couple high-spending years, where we bought our camper van and we paid to build it out and do all of those things. So because of those things, our savings rate for last year and this year are going to be around 20%, which was down from the 50 to 60% the few years before. And so for us, the path that we’re thinking of now is though, if we can scale back the work that we’re doing to cover our costs and save 10 to 20% a year, that would allow us still to retire sometime in our mid-forties.

Jessica:
And so that’s the plan. So we could, There could be certain years where we only cover our actual costs or where we use some of the money from our emergency funds, depending on if we want to do less work that year and that kind thing. But I do expect that, we enjoy saving. We get a rush from being able to save, like I imagine most people who are pursuing FI do. It’s kind of like a little addiction. And so it’s hard to completely scale back. And I don’t expect that we will scale back completely, that we’ll likely continue. And then my husband will quit his job, hopefully within the next couple of years. He knows right now that he’s doing it because he wants to not because he has to. So I think it changes the perspective too for him. And he’ll join me doing some entrepreneurial-type work and will be fully location independent, traveling around the country in our camper band.

David:
The crazy part about all this, you mentioned that if you guys just scaled back and stopped right now, you’d probably be able to retire at 50. And people joke about compound interest being the eighth wonder of the world, but to put in perspective, what you’re actually saying is that you’ve doubled your FI number if you stayed until 60, because over that from 50 to 60 compounding, even at just a normal 7% interest, whatever you’ve got in that account would’ve doubled. So to be able to say, “Well, if we keep going a little bit, 10 or 20%, we’ll reach it by 40.” Okay, well now you’re talking four times what you need at retirement.

David:
So the math is there that says, “If you wanted to, you could never save another dollar and 50” but if you save 10 or 20% going forward, that’s still a hefty amount of savings and you don’t necessarily need it, which is a great spot to be in financially, because it gives you peace. Which ultimately financial independence, if you ask me my definition is to do what I want, when I want, how I want. Nobody else can dictate whatever that is. And so congratulations. You guys have done awesome.

mindy:
I have one last question before we get to the famous four.

David:
Famous four.

mindy:
That’s the other show. We don’t have a song for this one. We should make one up.

David:
Yeah, it should be… Anyway.

mindy:
In terms of annual spending, what amount of income does your business generate right now?

Jessica:
I would say it close to covers it. So I would say my business income could cover about 75% of our annual spending right now. However, if my husband quits, we will have much higher costs, because of health insurance.

mindy:
Oh, good point.

Jessica:
And so am accounting for that in needing to generate a higher amount for future spending.

David:
But that’s 75% on, I know you mentioned you’ve designed it around five. How many hours a week do you think you’re putting in on that?

Jessica:
Oh, it’s like 25.

David:
See, that’s awesome. That’s a great spot to be.

Jessica:
Okay, Jess, this has been such a fun episode. I really appreciate your time, but we are not done. We still have our famous four.

Speaker 4:
Famous four.

mindy:
What is your favorite finance book?

Jessica:
So I actually recently read Cashing Out by Julien and Kiersten from rich & REGULAR.

mindy:
I love [inaudible 00:53:59] and Kirsten.

Jessica:
It was the absolute best argument for FIRE that I have ever read. And I’m not even for the retire early piece of it. It was an incredible book. It was incredibly inspiring and I think is going to reach a lot of new people that FIRE hasn’t reached previously.

mindy:
That is awesome. I have a copy. It is next on my list of books to read. I’m super excited.

David:
All right. What was your biggest money mistake?

Jessica:
Let’s see. I would say the biggest money mistake that I made was not being involved in my finances with my spouse in my twenties. So I had no interest in being involved. I didn’t want to think about money. I had some limiting beliefs about how having money makes you a bad person, that kind of thing to work through. And so as a result, I didn’t realize how much money we had or what it meant. And so got to a place that my job ruined my mental health, even though I probably could have quit or scaled back and used the cushion that I had built earlier, but didn’t realize that was an option.

mindy:
What is your best piece of advice for people who are just starting out?

Jessica:
So my advice for people just starting out would be to save as much as you can early within reason. So you don’t need to get an increase in salary above $30,000 a year and put 100% of it into your 401(k). You can do 75. You can inflate your lifestyle a little bit, just focus on inflating your lifestyle on the things that really will add significant value to your life. And then bank the rest of that raise. Because if you can reach Coast financial independence by 30 by saving maybe less than 200,000, that’s going to give you so much more freedom and flexibility for the next 70 years of your life.

David:
What’s your favorite joke to tell at parties?

Jessica:
So I actually recently burst into my husband’s home office earlier today to tell him that I saw a video with Jennifer Lopez that she did on TikTok that said adulthood is the worst hood to live in. I agree.

David:
Adulting.

mindy:
Whoa. She’s right.

David:
That’s the second jab at adulthood we’ve made down this show. We’re all Peter Pan at heart.

mindy:
Oh, I had a van life joke ready? I’m going to tell it anyway. What are van lifer’s favorite music bands. Van Halen and Camper van Beethoven. Okay, Jess, where can people find out more about you?

Jessica:
People can find me on my website. It’s the fioneers.com. And then I’m on the socials. So Twitter and Instagram, @thefioneers. And then for people who are interested in lifestyle design and living a intentional and designing your life along the path to financial independence, I run a Facebook group called Slow FI Enthusiasts and you can find that at thefioneers.com/FB for Facebook.

mindy:
Awesome. And I assume, because you invented the word Fioneers, you are the Fioneers everywhere, which is awesome. Just the Mad Fientist. He’s like, “I made this word up, so nobody else has it.”

Jessica:
Yes, we did make that word up.

mindy:
That’s a great word. We were sitting around trying to come up with a name for our blog and all these clever people and we’re like, “Oh, 1,500 days.” Okay. Jess, thank you so much for your time today. And we’ll talk to you soon.

Jessica:
Thanks so much for having me.

mindy:
All That was Jess from the Fioneers. David, what’d you think of the show?

David:
That was a great show. I think Coast FI is everything that we thought it would be, wanted it to be. And I think she’s got a good head on her shoulders. And I the fact that they’re already living a much more relaxed lifestyle than a lot of people their age. They’re already able to take the foot off the gas a little bit, knowing that their future is secure and be able to stop and smell the roses along the way. And I think that’s a very beneficial way to live life.

mindy:
I really wish that I had heard about Coast FI many, many years ago. I have peripherally heard about Coast FI. We have reached financial independence about five years ago before they started throwing all of these different FI terms around. And Coast FI seems like something that is beneficial. It’s the best of all worlds. You’re still reaching financial independence. You’re still enjoying your life while you’re doing it. You’re setting your future self up for success, but your current self is also still having a good time. When I first heard the term Coast FI, I thought it was having enough money to live on the coast. So super fat FIRE.

David:
Like, “Oh…” No.

mindy:
No. It’s you’re coasting to financial independence and the concept that you are going to just stop contributing after you’ve hit a certain number is, honestly, I think is kind of false. I think if you have the ambition enough to contribute to your 401(k) and contribute to your retirement accounts and your post tax investment accounts, once you get to this Coast FIRE number, I really don’t see a lot of people stopping completely and then just be like, “I’m just going to spend every dime I have now.” I think they’ll continue to, at the very least, get the match, do the Roth IRA contributions and maxing that out. Do the HSAs, if that’s something that’s available to them. They’ll just continue on with that part of it, because that’s just what you do. And if you’re already used to it, it doesn’t really make a big dent a lot of times to just continue on.

David:
Yeah. At that point, you’re really only contributing to either shorten the timeline to retirement or to live a more luxurious lifestyle in retirement or I guess ultimately to pass more on when you depart the earth. But it makes it really easy to scale back significantly and enjoy your present life. But every little bit that you help is just a bonus, because you already got the numbers down.

mindy:
Get money out of the way, so you can lead your best life.

David:
Yeah. Absolutely.

mindy:
Okay. Should we get out of here?

David:
We should.

mindy:
From episode 323 of the BiggerPockets Money Podcast, he is David Pere and I am Mindy Jensen saying catch you on the rebound. (silence)


Help us reach new listeners on iTunes by leaving us a rating and review! It takes just 30 seconds. Thanks! We really appreciate it!

Interested in learning more about today’s sponsors or becoming a BiggerPockets partner yourself? Check out our sponsor page!

Note By BiggerPockets: These are opinions written by the author and do not necessarily represent the opinions of BiggerPockets.


Source link

The Calculated Way to Retire Early WITHOUT Giving Up What You Love w/Jessica from The Fioneers Read More »