Blog

This Is the Hidden Cost of Being Too Agreeable at Work

This Is the Hidden Cost of Being Too Agreeable at Work


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Agreeableness comes with a cost. When you’re the one dissenting voice, all eyes turn to you. Suddenly, you have to justify your thinking and defend your reasoning. That’s a whole lot harder than simply saying, “yep, looks good!” 
  • In order to hear dissent, you need to create a culture that makes space for differing opinions.

Picture this: It’s a scorching hot afternoon in Texas. Luckily, you’ve got a shady porch, a pitcher of ice-cold lemonade and a very effective fan. You’re enjoying passing the afternoon playing dominoes with your family when suddenly, out-of-the-blue, your father-in-law comes up with a terrible idea: why not drive to Abilene for dinner, more than 50 miles away?

Why not? Here’s why not, you think. The car doesn’t have air conditioning. It will be a cramped, sweltering and miserable road trip, hours in each direction. Before you can say anything, your wife says the trip sounds fun. Your mother-in-law says the same. You hate to be disagreeable, so you say the only thing you think is allowed: Sounds great. 

The trip is just as bad as you imagined, and, adding insult to injury, your meal is bad, too. After all that, you have to pile back into the car and make the reverse journey home. 

At long last, you get back to the porch and the fan. Everyone is silent for a long time. Lying through your teeth, you say to the group, “Well, that was fun!” 

No one agrees. One by one, every family member confesses they thought it was an awful plan before leaving — but felt pressured to go by everyone else. Even your father-in-law said he’d have preferred to stay home — he was just worried everyone else was bored. 

This was an actual experience lived by the management professor Jerry Harvey, who published the story in 1974, calling it “the Abilene Paradox.” Ultimately, his point wasn’t really about road trips; it was about the perils of phony consensus. Here’s why being too agreeable is a genuine risk that can hurt your team. 

The cost of false alignment

Everyone loves consensus. We assume that if agreement is unanimous, we must be doing something right. 

Unfortunately, agreeableness comes with a cost. I’m reminded of the show Silicon Valley, one of the best depictions of startup culture I’ve seen. A beta version of the fictional startup Pied Piper’s platform is released to almost universal adoration — except for a board member named Monica, who hates it. As the only non-engineer to try it, she assumes she’s in the wrong, so she keeps her feedback quiet. Turns out, she’s spot on — the product is a huge flop with the general public. 

This is what false consensus looks like in practice. Monica was the odd one out, and it seemed like the failure was with her for not understanding the platform’s value. She felt pressure to fall in step with its many fans, because frankly, it was easier. When you’re the one dissenting voice, all eyes turn to you. Suddenly, you have to justify your thinking and defend your reasoning. That’s a whole lot harder than simply saying, “yep, looks good!” 

In The Five Dysfunctions of a Team, the consultant and speaker Patrick Lencioni concludes that smart teams make bad decisions thanks to a preference for keeping things pleasant at the expense of keeping them honest. When people don’t feel safe to disagree openly, it’s not that they don’t stop disagreeing; they just move the conversation to the sidelines. “It’s as simple as this,” Lencioni writes. “When people don’t unload their opinions and feel like they’ve been listened to, they won’t really get on board.”

The alternative to consensus (hint: it’s not dictatorship) 

If false consensus is the problem, the obvious fix sounds like this: the leader decides, everyone else falls in line. But that’s not the answer, either.

As leaders, I believe it’s our job to gather information, weigh options, analyze data and yes, hear opinions. Jeff Bezos uses a principle he calls “disagree and commit,” in which teams are encouraged to voice their opinions and argue in favor of what they actually believe. But once a decision has been made, everyone gets on board, including people who voted the other way. 

Bezos has applied this rule to himself: when he’s deferred to a direct report’s judgment over his own, he’s been explicit about what that means. “I’m not going to be second-guessing it, I’m not going to be sniping at it, I’m not going to be saying ‘I told you so.’ I’m going to try actively to help make sure it works,” he said. 

When you’re the head of a company, the buck stops with you, but that doesn’t mean you’re always right. There have been times at Jotform where I’ve learned this the hard way — I’ve wasted time and energy seeking a consensus that was never going to materialize. Now, I follow a version of Bezos’s principle: I listen, I consult, I gather data. When I make a decision — even if that decision is at odds with my original thinking — I own it. 

In order to hear dissent, you need to create a culture that makes space for differing opinions. Harvey’s sweltering Texas family and Silicon Valley’s Monica had one important thing in common, which was that they didn’t feel comfortable sharing what they actually thought. Leaders have to make sure they’re fostering an environment where raising an objection won’t come with negative consequences. 

Artificial consensus might be peaceful and efficient. But it’s also built on a fundamental lie. Good leaders will aspire to something deeper, messier and ultimately, better for everyone. 

Key Takeaways

  • Agreeableness comes with a cost. When you’re the one dissenting voice, all eyes turn to you. Suddenly, you have to justify your thinking and defend your reasoning. That’s a whole lot harder than simply saying, “yep, looks good!” 
  • In order to hear dissent, you need to create a culture that makes space for differing opinions.

Picture this: It’s a scorching hot afternoon in Texas. Luckily, you’ve got a shady porch, a pitcher of ice-cold lemonade and a very effective fan. You’re enjoying passing the afternoon playing dominoes with your family when suddenly, out-of-the-blue, your father-in-law comes up with a terrible idea: why not drive to Abilene for dinner, more than 50 miles away?

Why not? Here’s why not, you think. The car doesn’t have air conditioning. It will be a cramped, sweltering and miserable road trip, hours in each direction. Before you can say anything, your wife says the trip sounds fun. Your mother-in-law says the same. You hate to be disagreeable, so you say the only thing you think is allowed: Sounds great. 

The trip is just as bad as you imagined, and, adding insult to injury, your meal is bad, too. After all that, you have to pile back into the car and make the reverse journey home. 


Source link

This Is the Hidden Cost of Being Too Agreeable at Work Read More »

The 4 Blind Spots That Quietly Cost Entrepreneurs the Most

The 4 Blind Spots That Quietly Cost Entrepreneurs the Most


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Owners know their companies better than anyone, and that familiarity can create blind spots when it comes to capital, people, earnings and succession planning.
  • Weakness in one of these areas typically creates problems in the others, so they should be examined together and early to preserve the owner’s freedom to decide what comes next.
  • Capital, talent, earnings and succession deserve attention before a crisis or transaction forces the issue. Treat them as ongoing responsibilities to preserve more choices and build a stronger company.

The most expensive problems in a business rarely appear overnight. They develop gradually while the owner is focused on growth and the daily pressure to keep moving. That is one of the paradoxes of entrepreneurship: The closer you are to your business, the harder it can be to see it clearly.

Owners know their companies better than anyone, but that familiarity can create blind spots. Decisions become habits. Risks feel manageable because they are familiar. Questions without urgent deadlines keep getting pushed aside.

My new colleague Tom Matthesen, who leads business advisory at Balentine, has spent decades helping owners navigate growth, capital decisions and business transitions. He has identified four areas where capable leaders can lose significant value: capital, people, earnings and succession planning.

These issues are connected. A weakness in one often creates problems in the others. Examining them early can strengthen the business and preserve an owner’s freedom to decide what comes next.

Capital: Are you funding the business you’re becoming?

Many owners think about capital only when they need it for an acquisition, expansion, equipment purchase or unexpected shortfall. By then, circumstances may be dictating the available choices.

A capital strategy should evolve with the business. The funding that helped a company launch may not suit its next stage of growth. Bank debt, private credit and minority investment come with different costs, restrictions and implications for control.

The blind spot is assuming that capital is interchangeable or that the lowest apparent cost is always the best choice. The right funding depends on what you are trying to accomplish, how quickly the company is growing, how predictable its earnings are and how much flexibility you want to preserve.

Capital decisions can also affect a future sale. Restrictive debt, a complicated ownership structure or poorly timed financing can narrow your options when flexibility matters most.

Ask, “What kind of company are we building, and what capital structure will help us get there without creating unnecessary constraints?”

People: Is the team built for the next chapter?

Loyalty matters, especially in closely held and family businesses. Many companies succeed because a small group of people has worked together for years, wearing multiple hats and solving problems through trust and persistence.

But growth changes what a company needs from its people.

That does not mean replacing loyal employees each time the company reaches a new stage. It means assessing whether roles, responsibilities and capabilities are keeping pace. A longtime employee may grow into a larger role with support. The company may also need expertise it has never required before. Often, it needs both.

Owners can become part of the problem without recognizing it. If every important relationship, decision or piece of institutional knowledge runs through you, the company remains dependent on one person. That dependence limits growth, increases risk and can reduce the company’s value to a future buyer.

Ask, “Do we have the leadership, accountability and depth to operate successfully without everything flowing through me?”

Earnings: Are you building profit that is worth something?

Revenue growth is gratifying, but earnings have a greater influence on what a company is worth. The quality of those earnings matters as much as the amount.

Two companies can report the same profit and command very different valuations. Buyers, lenders and investors look at whether margins are durable, profits are predictable and the business converts revenue into profit efficiently. They also examine how much of that performance depends on the owner.

A growing company can still be financially shallow. Its top line may be strong while rising overhead and weakening margins leave little room to invest or withstand a disruption. Because margins tend to erode gradually, the change can be difficult to see from inside the business.

Comparing current results only with your company’s history may not be enough. Outside benchmarks can show how your margins and operating efficiency compare with peers and with what the business could reasonably achieve.

If you have a target value in mind for the company, work backward from it. What level and quality of earnings would support that value? What stands in the way? The answer may involve pricing, operating efficiency, overhead or margins that have slipped over time.

Earnings quality affects more than a future transaction. It determines how much room you have to invest, absorb setbacks and make thoughtful decisions instead of reactive ones.

Succession and exit: Are you preparing before you have to?

Succession planning is easy to postpone when you are busy running the company and do not know when, or whether, you want to sell.

Exit planning covers more than a sale. It prepares the business to keep creating value without depending on its owner.

Starting early preserves more choices. You might sell to a third party, transfer the company to family members, create an opportunity for management or retain ownership while stepping away from daily operations.

Each path requires different preparation. A family successor may need years to develop. A management team may need new incentives or financing. An outside buyer will examine earnings, customer relationships, leadership depth, operating processes and dependence on the founder.

Those weaknesses are difficult to repair during a transaction, health crisis or family change. By the time you decide to exit, many of the factors that determine value have already been established.

Ask, “What needs to be true for this business, and for me, to be ready?”

Seeing the business clearly

Blind spots are a natural consequence of building something complex while standing at its center. Addressing them requires disciplined financial analysis, candid conversations and trusted advisors who will challenge your assumptions.

Capital, talent, earnings and succession deserve attention before a crisis or transaction forces the issue. Owners who treat them as ongoing leadership responsibilities build stronger companies and preserve more choices. When circumstances change, they are better prepared to choose their next move instead of having it chosen for them.

Key Takeaways

  • Owners know their companies better than anyone, and that familiarity can create blind spots when it comes to capital, people, earnings and succession planning.
  • Weakness in one of these areas typically creates problems in the others, so they should be examined together and early to preserve the owner’s freedom to decide what comes next.
  • Capital, talent, earnings and succession deserve attention before a crisis or transaction forces the issue. Treat them as ongoing responsibilities to preserve more choices and build a stronger company.

The most expensive problems in a business rarely appear overnight. They develop gradually while the owner is focused on growth and the daily pressure to keep moving. That is one of the paradoxes of entrepreneurship: The closer you are to your business, the harder it can be to see it clearly.

Owners know their companies better than anyone, but that familiarity can create blind spots. Decisions become habits. Risks feel manageable because they are familiar. Questions without urgent deadlines keep getting pushed aside.

My new colleague Tom Matthesen, who leads business advisory at Balentine, has spent decades helping owners navigate growth, capital decisions and business transitions. He has identified four areas where capable leaders can lose significant value: capital, people, earnings and succession planning.


Source link

The 4 Blind Spots That Quietly Cost Entrepreneurs the Most Read More »

Her Mom Made This Toast Every Day. Now Customers Line Up for It.

Her Mom Made This Toast Every Day. Now Customers Line Up for It.


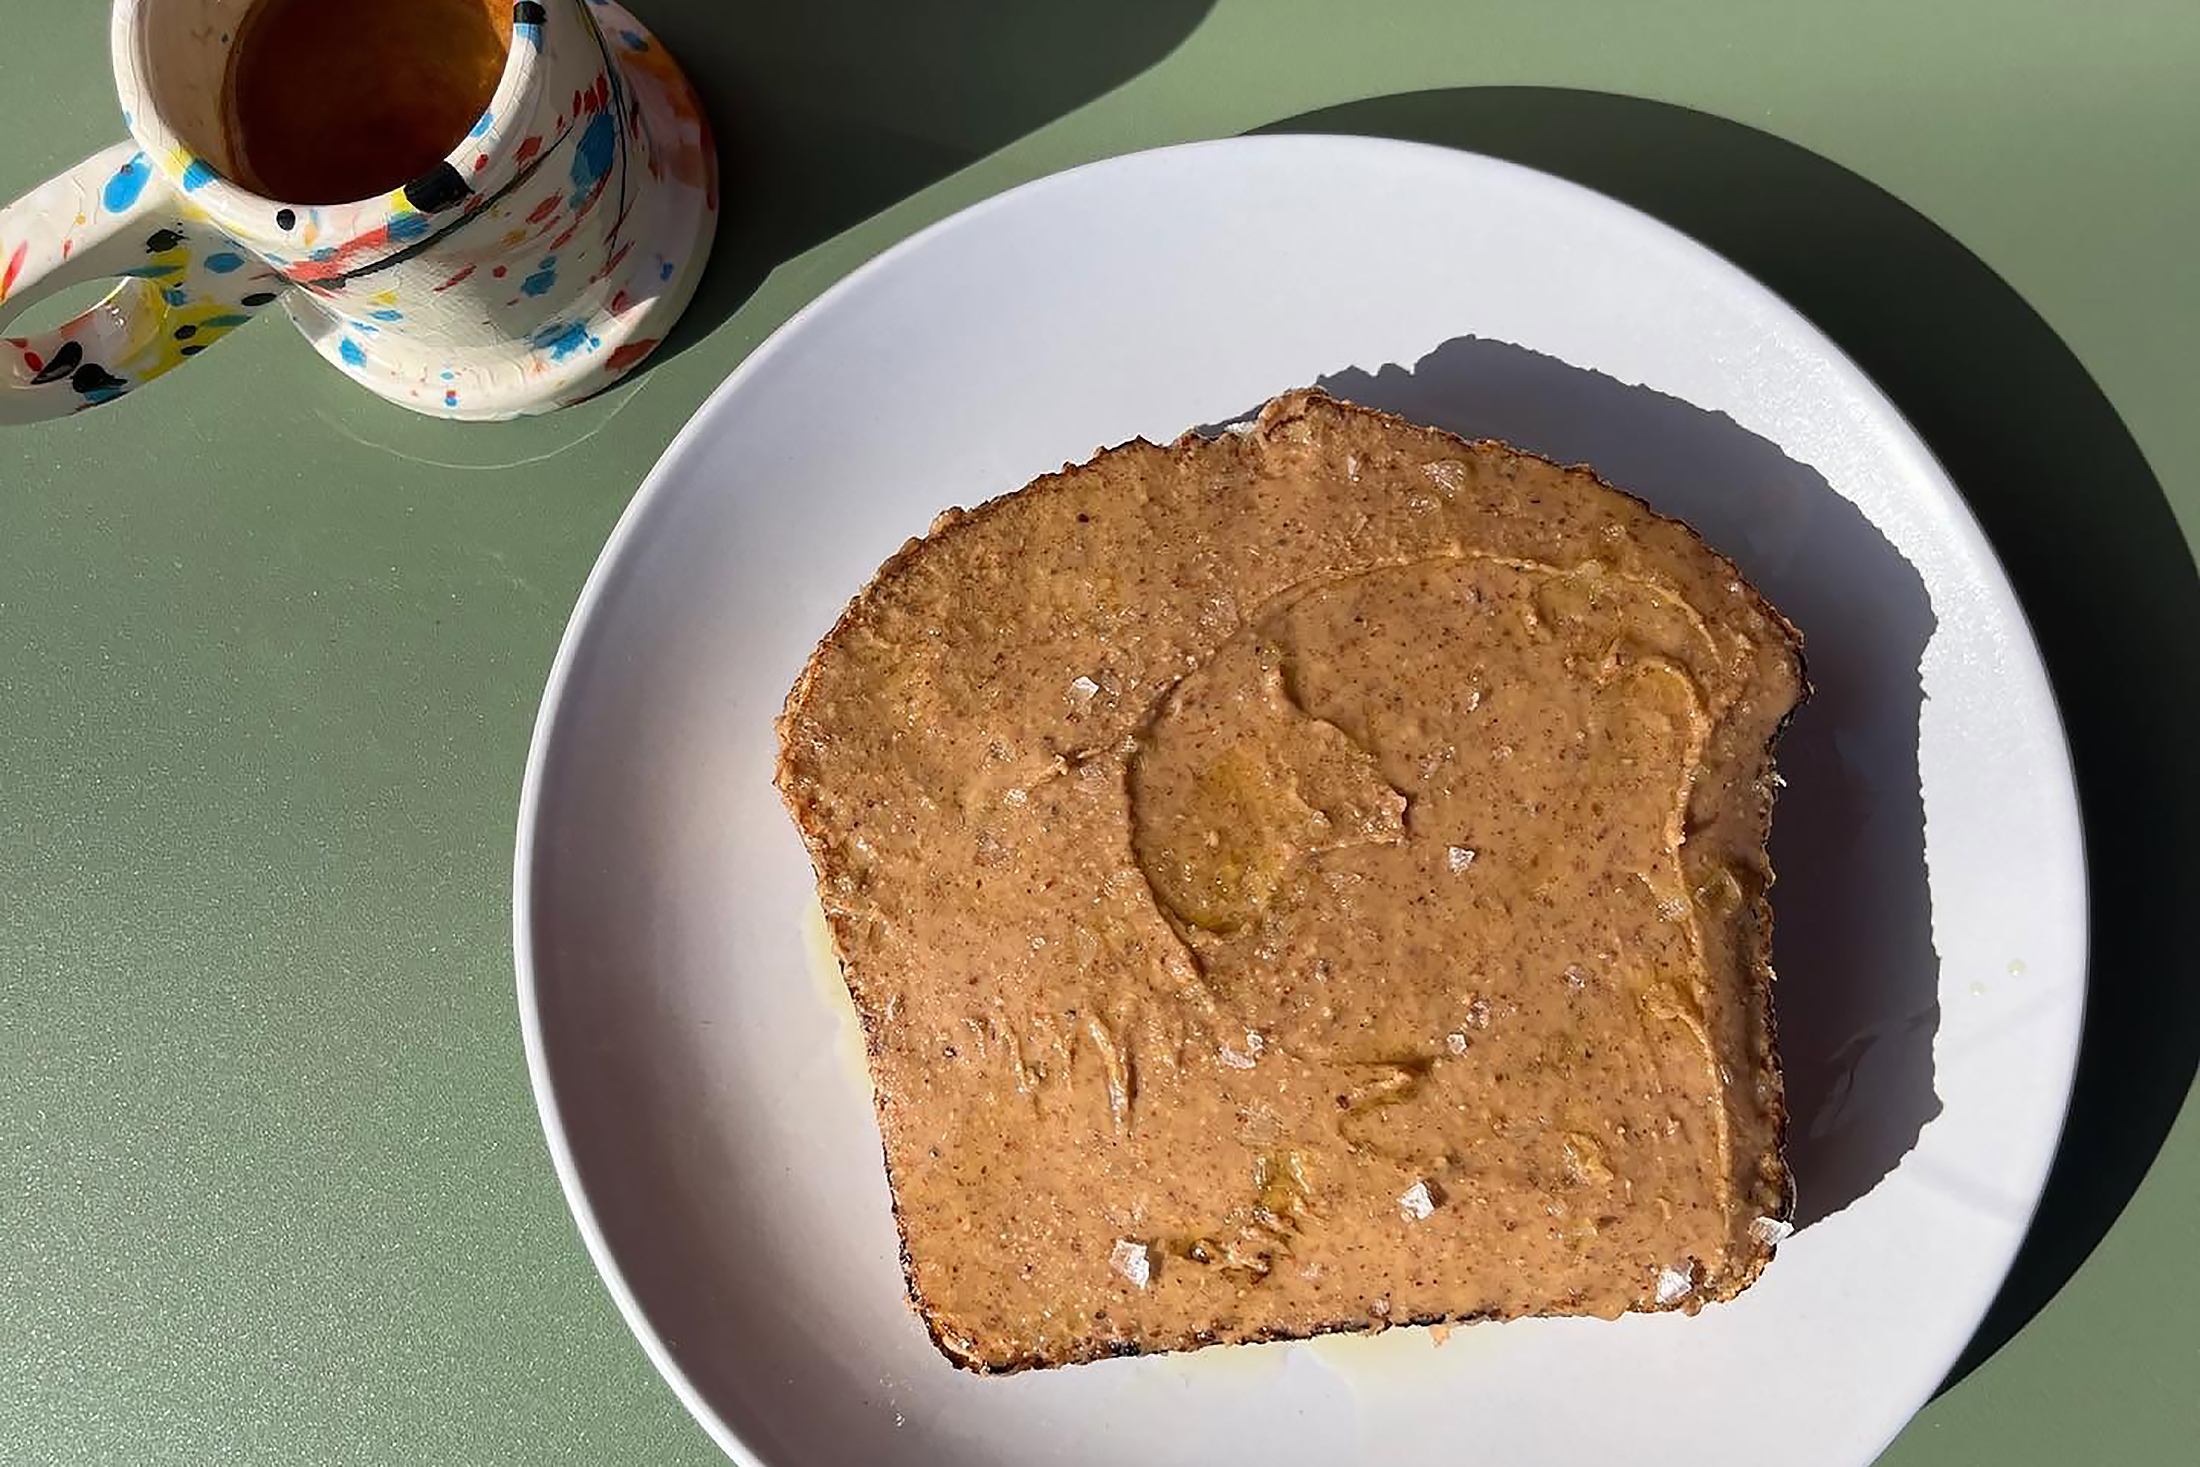
Ally Walsh eats the same snack every day. Thick bread, almond butter, a pinch of salt and a drizzle of olive oil. Her mom used to make it for her. Now it’s one of the items customers line up for at Canyon Coffee, the roaster and cafe business she co-founded with Casey Wojtalewicz in 2016.

Getting here wasn’t easy. Walsh and her son evacuated their Altadena home in January 2025 as the Eaton fire swept the region, The Wall Street Journal reports. Her mother died of ovarian cancer soon after, and the two bounced between more than a dozen places that year.

Walsh kept the coffee business running through all of it. Canyon has cafes in trendy Echo Park and Brooklyn’s Prospect Heights, where she says the shop handles roughly one order per minute. A new El Sereno location opens this month.

She finally landed in a Mount Washington house last October. “It was a whole new start, and that’s what it felt like I needed,” she tells the Journal.


Source link

Her Mom Made This Toast Every Day. Now Customers Line Up for It. Read More »

The 4 Questions That Helped Me Stop Making Blind Decisions as a Founder

The 4 Questions That Helped Me Stop Making Blind Decisions as a Founder


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Asking questions is a leadership advantage, not a weakness. Pausing to get input from your team surfaces risks and gaps you can’t see on your own.
  • Four types of questions sharpen decisions. Foundation, practical, perspective and alignment questions bring clarity, expose problems early, widen your view and build commitment.

Early in building my venture fund, I made a mistake many founders make: I worked alone and rushed decisions.

Even after I built a team, I would walk into a meeting, feel like I understood the opportunity and start connecting the dots out loud. I thought I was being decisive. In reality, I had blinders on. I was seeing what I expected to see and missing what I should have been asking. The turning point came when I forced myself to do something different. Instead of talking, I paused and asked a few simple questions. Then I went around the room and got input from the team. What I heard changed the direction of the decision.

My team raised issues I had completely missed. Risks, gaps and constraints that were obvious to them were invisible to me in the moment. In a few cases, they talked me out of decisions I was ready to make. In others, they strengthened the case in ways I hadn’t considered. Either way, the outcome was better because I stepped back and listened.

That shift made something clear: Asking questions isn’t a leadership weakness. It’s a leadership advantage. It makes you sharper, makes your team better and protects your business from blind spots you can’t see on your own. The best entrepreneurs understand this. They don’t try to have all the answers. They learn to ask better questions and actually listen to what comes back. Here are the four types of questions I rely on most.

1. Foundation questions: Get back to what matters

Every decision benefits from clarity at the starting line. Foundation questions cut through the noise and force focus.

Ask: What problem are we solving? What are you excited about?

I often start conversations with founders this way. It sounds basic, but it quickly reveals whether an idea is grounded or drifting. When founders can clearly explain the problem and why it matters, the rest of the discussion sharpens. When they can’t, there’s work to do before anything else moves forward.

In one conversation with a group of student founders who had just won a design competition, the room was full of excitement. They were energized and eager to talk. Starting with these simple questions brought the conversation back to first principles and gave it structure where there had only been momentum.

2. Practical questions: Surface the gaps early

Vision matters, but execution lives in the details. Simple, practical questions bring those details into focus.

Ask: Where are you in the build? Do you have a minimum viable product? What does your market actually look like? Have you talked to any potential customers yet?

With those same student founders, a few targeted follow-ups revealed big gaps that wouldn’t have surfaced otherwise. They hadn’t built a minimum viable product, let alone talked to prospective customers. Without those questions, it would have been easy to move forward on enthusiasm alone. With them, the next steps became clear and grounded in reality.

I’ve seen this play out again and again. Teams move faster when constraints are visible early. Practical questions reduce rework by exposing what needs attention before resources are committed.

3. Perspective questions: Open the door to better thinking

In my experience, blind spots usually come from a limited perspective. You can widen that perspective by tapping into your team.

Ask: What are we missing? What else should we be thinking about?

This has become one of the most valuable questions I ask. It creates space for ideas that would otherwise go unspoken.

In one team meeting, I closed with a simple version of it. A team member pointed out that our investors would soon expect a performance dashboard with key metrics, something I hadn’t considered. It was the right call at the right time. That moment turned into action. Our analysts and interns built the dashboard, which strengthened how we communicated progress and added value for our investors. The idea didn’t come from the person leading the meeting. It came from making room for others to think out loud.

4. Alignment questions: Turn input into ownership

Great decisions require more than input. They require commitment.

Ask: Where are you on this decision: yes, no or hold? Why?

When we began making investment decisions as a team, I made a point of hearing from everyone, from experienced professionals to student interns. I went person by person and asked where they stood and why.

The impact was immediate. Sometimes the team talked me out of deals I initially favored. Other times, strong alignment gave us the confidence to move forward. Those early investments turned out well, but the process built something more important than any single outcome: shared ownership. People support what they help shape, and alignment questions make that possible. Over time, this became part of our culture. Everyone knew they would be asked, so everyone came prepared, which improved both our decisions and our execution.

Make it a daily habit

You don’t need a formal system to use this approach. You need consistency.

In meetings, one-on-ones and major decisions, build the habit of asking instead of telling. Start with these four questions:

  • What problem are we solving?
  • Where are we really on this?
  • What are we missing?
  • Where are you on this decision, and why?

Used consistently, these questions reshape how teams think. They move conversations from assumptions to clarity and replace resistance with ownership.

The real advantage

Entrepreneurial leadership is often framed around decisiveness and speed. Those matter. But leaders who consistently outperform understand something deeper.

They know when to pause, and that a well-timed question can do more than a well-crafted answer. By slowing down at the right moment, they give their teams the chance to move faster where it counts.

Key Takeaways

  • Asking questions is a leadership advantage, not a weakness. Pausing to get input from your team surfaces risks and gaps you can’t see on your own.
  • Four types of questions sharpen decisions. Foundation, practical, perspective and alignment questions bring clarity, expose problems early, widen your view and build commitment.

Early in building my venture fund, I made a mistake many founders make: I worked alone and rushed decisions.

Even after I built a team, I would walk into a meeting, feel like I understood the opportunity and start connecting the dots out loud. I thought I was being decisive. In reality, I had blinders on. I was seeing what I expected to see and missing what I should have been asking. The turning point came when I forced myself to do something different. Instead of talking, I paused and asked a few simple questions. Then I went around the room and got input from the team. What I heard changed the direction of the decision.

My team raised issues I had completely missed. Risks, gaps and constraints that were obvious to them were invisible to me in the moment. In a few cases, they talked me out of decisions I was ready to make. In others, they strengthened the case in ways I hadn’t considered. Either way, the outcome was better because I stepped back and listened.


Source link

The 4 Questions That Helped Me Stop Making Blind Decisions as a Founder Read More »

This CEO Cut Ties With Subway, Grew to M a Year: Hero Bread

This CEO Cut Ties With Subway, Grew to $54M a Year: Hero Bread


Key Takeaways

  • After exiting the Subway partnership, Hero Bread focused on five SKUs.
  • The brand pivoted to DTC, then explored different retail channels.
  • Now, it’s navigating what the CEO calls the third chapter in its DTC playbook.

In 2022, when YuChiang Cheng invested in Hero Bread on behalf of 444 Capital and stepped in as the company’s interim chief marketing officer, the low-carb, zero-sugar brand was at a critical crossroads. 

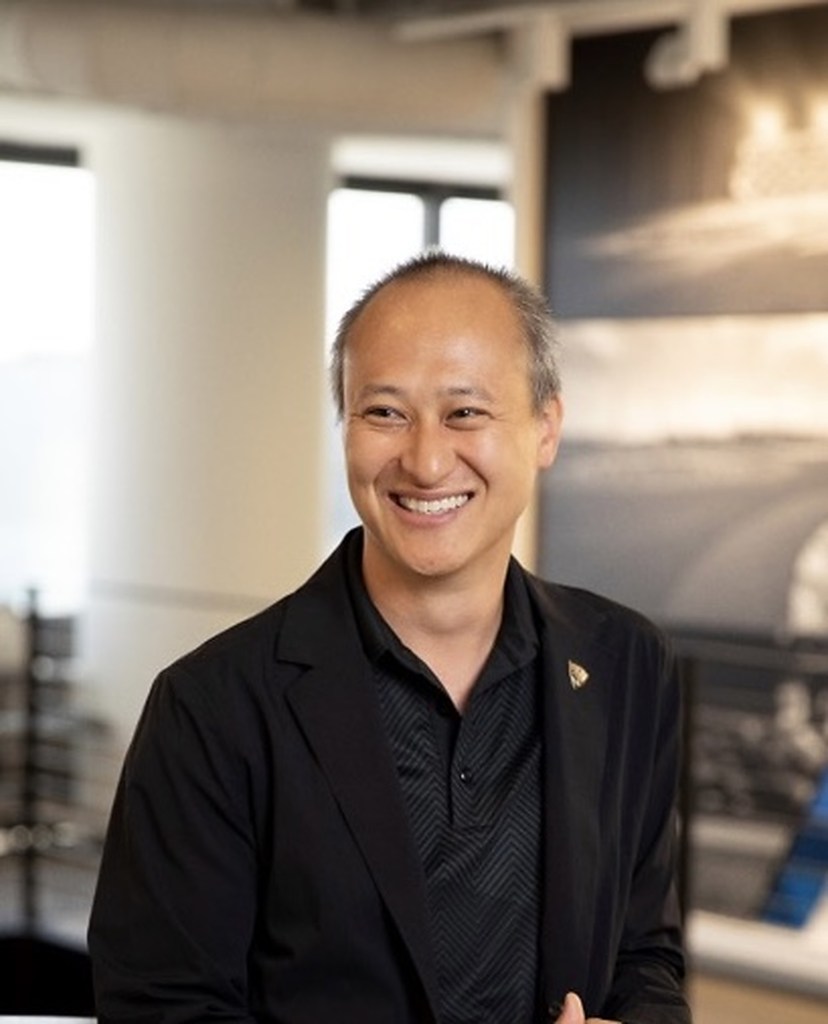
Image Credit: Courtesy of Hero Bread. YuChiang Cheng.

Cole Glass had founded the company in 2019 to address his severe food allergies related to pollen. By October 2021, a partnership with Subway seemed like an exciting path forward. The idea was to get the macro-friendly bread products into as many hands as possible so people could taste it for themselves. 

However, around the time Cheng joined the company, it was clear the unit economics didn’t make sense. The Subway deal wasn’t profitable; Hero Bread was running out of money. 

“ We were just too small at the time and couldn’t service it, didn’t have the resources and all the infrastructure put in place to effectively deliver that,” Cheng says. “So we backed out of it.”

Hero Bread brought in $54 million in revenue last year

Cheng pivoted to a direct-to-consumer (DTC) strategy, allowing the brand to receive feedback from consumers more quickly and drive word-of-mouth sales, he says. 

Cheng assumed the role of CEO in November 2023 and has continued to grow the company.

In a funding round announced in June 2024, Hero Bread raised $21 million in under 90 days. The round, co-led by Cleveland Avenue, DNS Capital and Composite Ventures, brought the company’s total funding to date to more than $68.5 million. 

Hero Bread brought in $54 million in annual revenue last year. Additionally, the company more than doubled its retail presence in two years, expanding from about 4,000 to 10,000 doors, which includes a recent Target launch. 

But Hero Bread’s successful push into retail — a feat many CPG brands that launch DTC hope to achieve — doesn’t mean the company plans to put the brakes on its DTC strategy anytime soon.

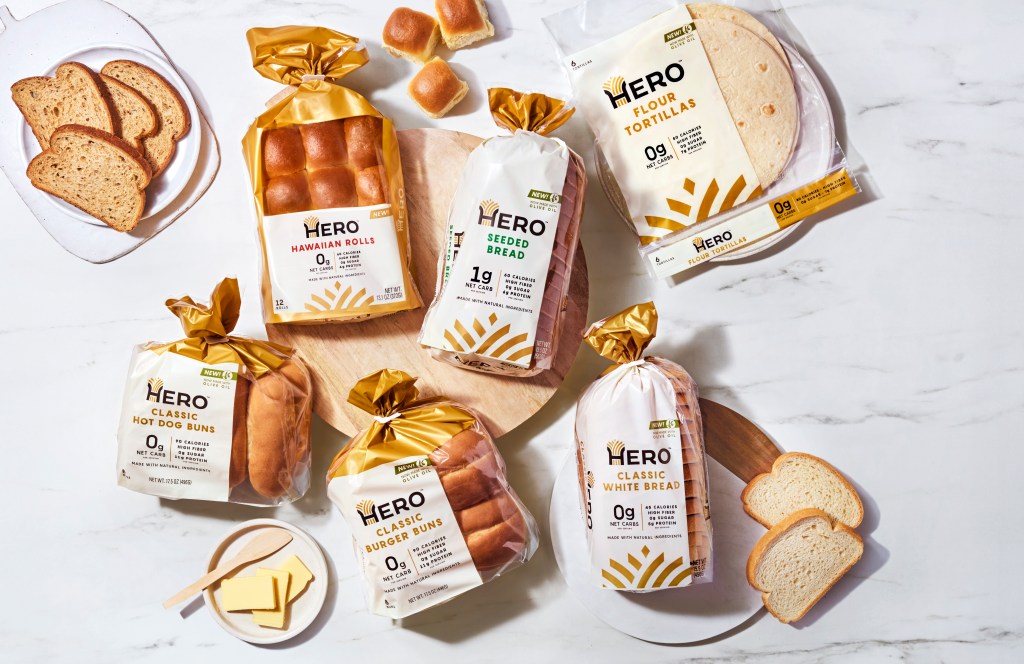
Image Credit: Courtesy of Hero Bread

Entrepreneur sat down with Cheng to learn more about what he calls the “third chapter” of Hero Bread’s DTC playbook, and how it’s continuing to unlock growth for the company. 

Hero Bread experimented with different retail channels

After walking away from the Subway partnership and prioritizing DTC sales, Hero Bread focused on five SKUs: white bread, seeded bread, burger buns, hot dog buns and flour tortillas. 

The line-up also made sense as the company entered retailers: The goal was to offer everyday staples that would drive repeat purchases on a weekly basis. 

Initially, though, Cheng and the team weren’t quite sure which retailers would be the right fit. 

“It’s a very mainstream taste profile,” Cheng explains. “So there was a lot of debate, if this is going to be more of a Publix, Target type product, or is this going to be more of a natural Whole Foods, Sprouts, type of product.”

So Hero Bread opted to experiment with different types of retailers. The company launched in Market District, Publix and Sprouts and planned to lean into whichever channel performed best. But six months later, the company’s products had an impressive track record at all three. 

“We were very, very fortunate in that,” Cheng says. “So instead of picking [retail] channels, we decided to pick retailers that were more enthusiastic regardless of what channel they were in.” 

It’s a different tactic than many CPG brands use; they tend to zero in on one retail channel and go regional, the CEO notes. 

Striking the balance between affordability and convenience

Of course, CPG brands that expand into retail have the advantage of economies of scale. 

“You can move tons of pallets on a truck much more affordably than you can send individual packages through ecommerce,” Cheng says. 

As a result, retail typically gives consumers a more affordable way to buy. DTC, on the other hand, serves as a more concierge path to purchase not only Hero Bread’s staple products, but also other offerings that might not be able to hit retail shelves as seamlessly. 

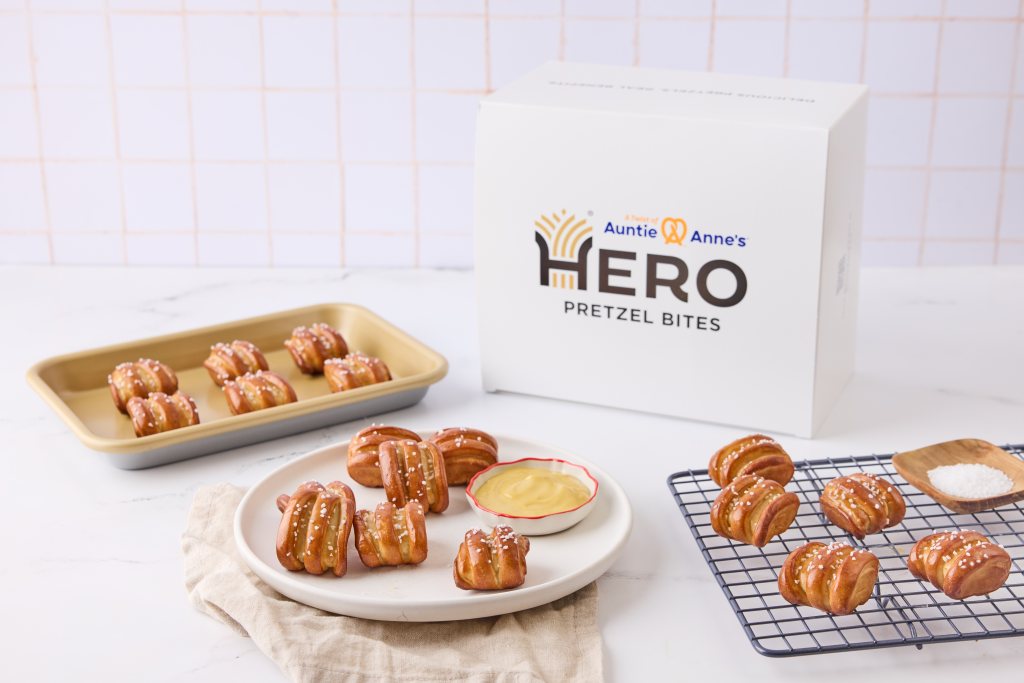
Hero Bread’s Crafted Collection, which includes items like croissants, lemon poppy seed scones, shortbread biscuits (hand-baked in Sonoma with brown butter made by a Michelin chef), lends itself well to the model. The company’s recent collaboration on pretzel bites with Auntie Anne’s does too. 

“ [These are] small-batch, largely handmade products that are exclusive to hero.co, where it just wouldn’t make economic sense for us to hand-roll 300,000 to 400,000 croissants,” Cheng explains. 

Image Credit: Courtesy of Hero Bread

What’s more, DTC can act as an invaluable testing ground for products with the potential to sell effectively in a brick-and-mortar setting. 

That’s exactly what the company did with its bagels, unveiling a limited-edition launch online in December 2024. 

“ We weren’t sure if people would want to buy bagels from us,” Cheng says, “so we initially made them in smaller batches, sold them at hero.co, and they quickly became one of our best-selling items.” 

Hero Bread’s bagels landed on retail shelves within six months. 

Meeting Hero Bread’s consumers wherever they may be

Cheng doesn’t believe a successful entrepreneur or business leader is defined by how many times they win. 

“It’s how many times you can try again, regardless of how many times you’ve fallen down or how much blood you get on your face,” the CEO says. “There is a level of courage that is really necessary.” 

It’s a tendency toward resilience that’s helped Cheng lead Hero Bread through some crucial years that required an enthusiastic willingness to adapt to every challenge — and the CEO looks forward to what comes next. 

“We’re always trying to meet the consumer where they are,” Cheng says. “There’s a specific Hero fan, and then there’s the overarching bread fan. We believe that the more people who try us, the more people who will believe [in us].”

Key Takeaways

  • After exiting the Subway partnership, Hero Bread focused on five SKUs.
  • The brand pivoted to DTC, then explored different retail channels.
  • Now, it’s navigating what the CEO calls the third chapter in its DTC playbook.

In 2022, when YuChiang Cheng invested in Hero Bread on behalf of 444 Capital and stepped in as the company’s interim chief marketing officer, the low-carb, zero-sugar brand was at a critical crossroads. 

Image Credit: Courtesy of Hero Bread. YuChiang Cheng.

Cole Glass had founded the company in 2019 to address his severe food allergies related to pollen. By October 2021, a partnership with Subway seemed like an exciting path forward. The idea was to get the macro-friendly bread products into as many hands as possible so people could taste it for themselves. 

However, around the time Cheng joined the company, it was clear the unit economics didn’t make sense. The Subway deal wasn’t profitable; Hero Bread was running out of money. 


Source link

This CEO Cut Ties With Subway, Grew to $54M a Year: Hero Bread Read More »

This Doctor Made a List of Everything Patients Hate. Then Did the Opposite

This Doctor Made a List of Everything Patients Hate. Then Did the Opposite


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Dr. Darshan Shah’s own health problems inspired him to rethink how doctors approach preventive healthcare
  • He founded Next Health to create a medical experience that people would actually want to return to.
  • Will patients visit physical clinics at a time when much of healthcare is moving online?

When Dr. Darshan Shah, a board-certified surgeon, set out to create a different kind of medical clinic, he took out a whiteboard and made a list of everything people hate about going to the doctor. Bad parking. Old furniture. A grumpy person at the front desk. Long waits. Old magazines.

Then he set about doing the opposite. “This needs to be a beautiful space that inspires you to want to be there,” Shah says. The result was Next Health, a longevity clinic that Shah says has been described as “the Apple Store of health and wellness.”

Next Health now has more than 25 locations around the world, offering everything from advanced health testing to hormone optimization and IV therapy. But Shah’s path to becoming a longevity entrepreneur started long before wellness clinics became a booming business. On a recent episode of the One Day with Jon Bier podcast, he explained how his own health crisis while working as a surgeon forced him to reconsider what he’d been taught about keeping people healthy, and why he thinks the doctor’s office should be as focused on keeping people healthy as it is on treating them when they’re sick.

The surgeon becomes the patient

Shah was a bit of a child prodigy. He entered a combined medical program at the University of Missouri-Kansas City at 15 and graduated as a physician at 21. He went into surgery, eventually becoming chief resident and pursuing further surgical training at the Mayo Clinic.

But caring for others meant he seldom cared for himself. Shah was spending 12 to 14 hours a day in surgery, sometimes six days a week. “I was at my unhealthiest myself,” he says. “I was diabetic, 50 pounds overweight, hypertensive, on 10 different prescription medications.”

He eventually developed an autoimmune disease and was prescribed methotrexate, an immunosuppressant. He says the medication made him feel worse. 

At the same time, Shah was seeing many of the same problems in his patients. Before elective surgery, patients had to be medically cleared by their primary care doctors. Many had high blood pressure, diabetes, obesity, and other conditions that prevented them from being cleared. 

“I was witnessing the problem that needed to be solved, and I was also experiencing it myself. I decided that I needed to learn the science of health because all I was getting was the science of disease management,” he says.

That decision led to a deep dive into the burgeoning practice of functional medicine, which focuses on identifying the underlying causes of health problems rather than simply treating their symptoms.

He began applying what he learned to himself and his patients. “I was getting my patients so healthy they even canceled their surgery, so they didn’t need it anymore,” Shah says. “I was like, ‘This is what we need to be doing in medicine.’”

A clinic people actually want to visit

As Shah sees it, one of the biggest problems with traditional healthcare is that people don’t want to be there. For many patients, he says, visiting a doctor evokes feelings of “number one, fear, number two, of annoyance.”

That presented a business problem. He could offer all the health testing and longevity treatments he wanted, but if people dreaded coming through the door, they weren’t likely to come back. “I knew I had all these tools to get people healthy,” he says. “But I was like, people aren’t going to want to do this unless we change the experience.”

Next Health combines medical consultations and testing with services ranging from IV therapy and hormone optimization to red-light therapy and other wellness treatments. “We spend 45 minutes to an hour with our patients every time they come in,” Shah says.

That kind of healthcare comes at a price. Some testing and treatments cost considerably more. Its Executive Physical, for example, is currently listed at $14,500.

Shah acknowledges the criticism that longevity medicine can seem like healthcare for the wealthy, but says, “Next Health has been very mindful in creating programs that almost anyone can afford.” Memberships start at $99 a month, an amount Shah says is low enough to be covered through a health savings account. “Of course, we have concierge-level memberships as well, but we have equal numbers of members across all the different levels,” he says. “As we continue to scale, our goal is to drive down costs and make this affordable longevity care for everyone.”

Why brick and mortar still matters

The concept started with a single West Hollywood location in 2016. By the end of 2024, Next Health had five locations. Then the company began expanding through franchising, with now more than 25 clinics. 

That growth has required Shah to double down on something many healthcare companies have tried to move away from: brick and mortar. “People still think we’re crazy to be opening all these four walls,” he says. “Because they’re expensive, there’s employees you have to hire, there’s so much you have to do.” 

But Shah believes the physical space is an essential part of the product. “Every corner of your brick-and-mortar location inspires a feeling that you want the person to have,” he says. “It’s not just the location, it’s also the people in the location and what experience they are providing.”

The whiteboard may be long gone, but the idea behind it remains. Patients shouldn’t need so much patience to get healthy.

Key Takeaways

  • Dr. Darshan Shah’s own health problems inspired him to rethink how doctors approach preventive healthcare
  • He founded Next Health to create a medical experience that people would actually want to return to.
  • Will patients visit physical clinics at a time when much of healthcare is moving online?

When Dr. Darshan Shah, a board-certified surgeon, set out to create a different kind of medical clinic, he took out a whiteboard and made a list of everything people hate about going to the doctor. Bad parking. Old furniture. A grumpy person at the front desk. Long waits. Old magazines.

Then he set about doing the opposite. “This needs to be a beautiful space that inspires you to want to be there,” Shah says. The result was Next Health, a longevity clinic that Shah says has been described as “the Apple Store of health and wellness.”

Next Health now has more than 25 locations around the world, offering everything from advanced health testing to hormone optimization and IV therapy. But Shah’s path to becoming a longevity entrepreneur started long before wellness clinics became a booming business. On a recent episode of the One Day with Jon Bier podcast, he explained how his own health crisis while working as a surgeon forced him to reconsider what he’d been taught about keeping people healthy, and why he thinks the doctor’s office should be as focused on keeping people healthy as it is on treating them when they’re sick.


Source link

This Doctor Made a List of Everything Patients Hate. Then Did the Opposite Read More »

You Don’t Need Dozens of Rentals to Reach Financial Freedom (He Tried It)

You Don’t Need Dozens of Rentals to Reach Financial Freedom (He Tried It)


For over a decade, John Crutchfield was in full-on acquisition mode. Despite starting with very little money, he scaled to over 600 units across multiple states and tens of millions of dollars’ worth of real estate. He even quit his job to focus on his portfolio full-time!

But then the market changed. Interest rates spiked, debt became more expensive, and John’s expenses ballooned. He had overleveraged his real estate portfolio, and suddenly, owning more properties wasn’t really making him wealthier. So he did something he had spent years trying to avoid: he started selling. And in the process, John learned a painful lesson about building wealth: sometimes, having less can actually give you more.

In today’s episode, John shares some of the highs and lows from his own real estate investing journey, how he went about pruning his portfolio, and why the number of doors you own doesn’t matter nearly as much as the cash flow, value, and freedom each property provides.

Henry Washington:
You don’t need dozens of rentals to reach financial freedom. And if you ask today’s guest, less is usually more. For over a decade, John Crutchfield was in full acquisition mode. Despite starting with very little money, he scaled to over 600 units across multiple states and tens of millions of dollars worth of real estate. He even quit his job so he could focus on his portfolio full time, but then the market changed. Interest rates spiked, debt became more expensive, and John’s expenses bloomed. Suddenly, owning more properties wasn’t making him any wealthier, so he started selling. And in the process, John learned a crucial lesson about building wealth. Sometimes having less can actually give you more, more cash flow, more flexibility, more peace of mind. In today’s episode, John shares the highs and the lows of his real estate investing journey, how he turned a smaller portfolio into a more profitable business, and why door count matters far less than the freedom each property provides.
What’s going on, everybody? I’m Henry Washington, co-host of the BiggerPockets Podcast. And today we’re bringing you an investor story with Dr. John Crutchfield who invests in Tupelo, Mississippi. So let’s bring him on. All right, Dr. John Crutchfield, welcome to the BiggerPockets Podcast, my friend.

John Crutchfield:
Man, too cool, too cool. How you doing? Henry Washington, the Henry Washington.

Henry Washington:
Why don’t you give us some background? Start a little bit before real estate and then kind of talk us up to where you are now.

John Crutchfield:
I’m John Crutchfield. Grew up in Tallahassee, Florida. I’m a Florida boy. Time came to go to college. It was like, okay, where are you going? Well, I don’t want to go too far. So Florida State was right down the street. Fast forward a little bit, got my first job as a teacher because teachers get summers off, they get all the holidays. Somebody said, “Well, if you go back to school, you’re such a good teacher. I bet you could be a good principal.” And I was like, “Yeah, you know what? That’s right.” So I went back and got a master’s degree, became a principal, realized that as a principal, you do get paid a little bit more, but you have to be there all the time. So somebody then said, “Hey, you’d like to talk and you seem kind of smart. Maybe you want to be a college professor.
That’s the next level. All of these, by the way, you got to go back to school, pay more money so that you can get a better job.” And so I just kind of followed that track, ended up as a professor at Ole Miss, that probably was my dream job, got to help people who wanted to become teachers become teachers. So very fulfilling work. But every time I got these increased roles, I ended up seeing lifestyle creep happen. So more money coming in the personal account meant, okay, better furniture or a bigger house, more spending because hey, you got to have a better car because you’re making more money. That’s the thought. And so ended up at the end of the month, no matter what job I had, not having enough money or having to wait till the next month. So then I started Googling stuff like passive income and stumbled on real estate investing.
There was this podcast at the time called the BiggerPockets Podcast. So it’s funny. Never heard

Henry Washington:
Of it.

John Crutchfield:
Yeah. And I stumbled on their forums, getting tons of quality answers from the community, but just started kind of feeding that bug of getting financial education.

Henry Washington:
How old were you at the time when you found this real estate bug?

John Crutchfield:
Oh, probably 26. 25, 26.

Henry Washington:
How long did it take you to go from that learning to doing and what were those steps?

John Crutchfield:
I ended up meeting a guy at church who had about 30 properties, and this was his retirement plan. And he, as we’re having the conversation says, “You should sit with me so I can show you what I’m doing.” And that mentorship became very valuable to me because we struck up a relationship, started having multiple conversations. He sat down with me and he told me, “Just look at your life in your W2 world. If you can run a school, you can run a business.” That was kind of my moment because before he said that, I had never in my life considered actually owning a business. That’s how ingrained it was for me that you go to school, you get good grades, you go to college, you get a good job. I was that guy. So what I ended up doing is going online like some people do and looking for sale by owners because I had a big problem.
I didn’t have any money. So I remember my strategy, very concrete, it actually still works in 2026. It’s a lot harder, but it still works. To go on Zillow, filter for sale by owners, and you get their phone number right there. And I will text them, “I’m interested in buying your house, but I don’t have any money. Will you owner finance it to me?” That was the text that I sent hundreds of times and one guy said yes. He said, “Actually, I will.”

Henry Washington:
It does still work. You can actually do that. But most people won’t commit to sending the amount of text messages that you would need to send in order for somebody to get a yes. Where people screw up, it’s not that you can’t get into real estate with limited funds, it’s that most people aren’t willing to put in the level of effort it’s going to take to find that deal and to get that deal closed when you don’t have money as a resource. You’re going to have to spend way more time and put a lot more effort in. You got to be more creative.

John Crutchfield:
Absolutely.

Henry Washington:
Well, I know it was a while ago, but the principles remain the same. Would you mind sharing with us kind of what that ended up looking like, what that deal structure was? What’d you pay for the house? How’d you structure the financing? What’d you give him? What’d you not give him?

John Crutchfield:
I bought the house for $80,000. It was a three bedroom, two bath in the market that I’m in, Tupelo, Mississippi. The monthly payment was $528 a month. And then I was responsible for the taxes and insurance. The house did need about $20,000 in work. So he had just had a tenant move and that’s why he was interested in this because he didn’t want to do the renovations. Ended up spending that 20,000, a lot of it was sweat equity, but getting the house presentable where we could rent the house out and ended up renting the house out for $1,200 a month.

Henry Washington:
So that’s a screaming deal.

John Crutchfield:
Look, I owned that house for maybe 10 years before we sold it and we sold it recently for like $220,000.

Henry Washington:
Sounds like a deal to me, buddy.

John Crutchfield:
Yeah. And I ended up having an investor relationship, kind of a guy that we ended up doing more business together because of this. So that first deal went pretty well.

Henry Washington:
This absolutely can still work. Almost all of my owner finance deals have been from landlords because landlords understand the value of cash flow. That’s why they were landlords in the first place. And a lot of people would love to get out of the business of being a landlord, but still maintain cash flow. And the way to do that is owner finance because then you get paid every month, but you’re doing got to deal with tenants and toilets. So if you want to try this, I would say try it, except just do it a little different now. Help yourself pull a list of people who own property free and clear, absentee owners and landlords. Call them all or text them all and ask them. And I bet you won’t have to send as many thousands, but it’ll still be a lot and you’ll get a lot of rejection, but this can absolutely still work.
So I’m very curious how that deal sparked your growth and how long it took you to scale, but I want to ask you those questions right after the break. All right. Welcome back to the BiggerPockets Podcast. I am here with investor Dr. John Crutchfield, who just told us the story of his first deal. And it’s so interesting that our stories are so similar in how we got started in our upbringings even into leading into that first deal. So you did a first deal, pure hustle, sent hundreds of text messages asking somebody if they’d owner finance you a house. And lo and behold, somebody says yes, you end up buying a screaming deal. How did that spark the rest of your real estate investment journey?

John Crutchfield:
When I had the mentor that I mentioned come over to look at the house after we were done, he was like, “I think you need to get this appraised.” That was the eureka moment. When I got the appraisal and I had $100,000 on this property, but it was worth 160, and at the time I was a professor at a college making $60,000 in a whole year. I was like, “Wait a minute, this is possible to do over and over and over again?” And he was like, “Yes.” And so that is how the first deal really kind of sparks the push into, “Well, if I could do this five times a year, I’d be making five times as much as I make on a job. And this is a no-brainer.” At the time, I never thought about quitting my job. I just said, “I could do my job and do this on the side.” So ended up doing my next deal.
Similar type situation. I would say you asked me how long. It was probably a year or two. There was some space, but ended up buying a property, again, very limited funds, using sweat equity. I have pictures with my wife and kids helping me paint and fix up countertops, but ended up doing a similar thing. $15,000 purchase. This is a Mississippi property.

Henry Washington:
$15,000 for the whole house or the down payment?

John Crutchfield:
For the whole house. There was an evolution that happened here. Once I saw that appraisal and the whole value add situation, my mind switched from, “Well, I need to get the properties for as low as possible.” My strategy improved, and this is a strategy I used probably for my first 30 units. You have all these people on the MLS that are trying to sell their property, and some of those properties are sitting there for months and months and months. So I found a realtor who would do what I asked, because some of them wouldn’t. I just want to offer $15,000 on everything on the market. And that’s what I started doing, just offering as low as possible on everything on the market. Some of them wouldn’t respond. Some of them would say, “Heck no,” all that stuff. But then somebody would counter a lot lower than their asking price.
Or in this case, the guy just said, “Have you even looked at the house? Yes, I’ll take 15K.”

Henry Washington:
That doesn’t sound like a good answer. Oh

John Crutchfield:
My goodness. If I asked a third grader to describe what they think a $15,000 house looks like, that’s what this house looked like.

Henry Washington:
The house needed a whole new house?

John Crutchfield:
It needed everything. It needed everything. Everything. Holes everywhere, stuff everywhere, vacant for a long time. But the numbers made sense. I ended up buying that house for 15K. My wife and I spent about 35. Again, a lot of that sweat equity in there, went to the bank and they said it was worth 100K. So this whole concept of adding value and making something worth more because you did the work, it really provoked an addiction. And so that’s kind of what I did. I started doing as many of these as I could.

Henry Washington:
I actually teach people how to offer on the MLS in a very similar fashion. You want to find a deal on the MLS? Do these steps. Define your buy box. Your buy box is just what you want to buy and where you want to buy it, right? Give that buy box to an agent who’s willing to submit offers for you. John said not everybody was willing to do this for him. That’s still true to this day. You got to find an agent who’s going to be willing to do this dirty work. And so I pull every house on the MLS that is in my buy box and has been listed for 90 days or more. Average days on market here is about 60 days. So I do 30 days beyond average days on market. That’s my assumption that they may be motivated for a lower offer.
And then I just have my agent offer 40% off of the price it’s listed for. So we take the list price, we subtract 40%, that is our offer. And we don’t write up official offers for everyone. My agent has a canned text message that he sends to the other agent that basically paints me as the bad guy so he doesn’t have to damage his reputation for making lower offers. He says, “Hey, I’ve got an investor client. He’s only making offers based on the numbers. It’s not personal at all. I’m sorry the offer’s not what you’re hoping it is, but would you consider an offer of X?” And he sends that to every one of these listings. We are not looking for someone to say yes. Matter of fact, I don’t want somebody to say yes. Like your guy said yes, that ended up being a doozy.
If somebody takes that and says yes, I’m probably pretty skittish, but absolutely want people to counter because if you counter or if you say, “Hey, we’d consider it, great. Now we can have a conversation. I can go see the house. I can analyze it thoroughly and I can make an offer.” This is the exact same strategy you just talked about, maybe refined a little different for the times. You guys, this stuff still works if you’re willing to put in the hustle.

John Crutchfield:
That idea of making offers and starting conversations is something that I still have to remind myself of all the time. When I want to build my pipeline, it’s like how many conversations have I had? How many offers have I made?

Henry Washington:
People get so overwhelmed with the concept of how do I find a good deal? Simplify the process. That’s what John just did. If you simplify the process down, it becomes a lot easier. So what if instead of worrying about what kind of marketing you’re going to do or if you’re going to make MLS offers, what if you just said, “What if I talk to three to five people a day who can sell me a house?” Just get on the phone with three to five people a day who can sell you a house. If you make it a point to have a conversation with three to five people a day who could sell you a house, I bet you’d buy a house pretty quickly, 30, 60, 90 days if you do that consistently. So what does that mean? You can either call direct sellers and see if they’re willing to talk to you about selling a house, real estate agent.
You can call real estate agents and see if they have anything that would fit your buy box, or you can call a wholesaler. Those are three different types of people who can all help you buy a house. So talk to one of each a day. What if you just talk to a wholesaler, a seller and a real estate agent every day? That’s very easy to do. And if you did that consistently for 30 days, I bet you’d be pretty close to getting a deal.

John Crutchfield:
And also what you’re doing is you’re leveraging other people to help you reach your goal. So now it’s not just the deal you’re looking at that you might have started the conversation with, but it’s all the other deals that they may be aware of that they may present and say, “Hey, this is something you should consider.” So you’re exponentially growing your reach by having these conversations.

Henry Washington:
Would you mind sharing with us kind of how big your business got over the course of the next several years and what that timeframe looked like for you to get there?

John Crutchfield:
So I actually don’t know how many I had at the peak. I really don’t. I would go to these conferences and people would be like, “How many doors?” And I was using a CRM, so I know I remember 585. I remember that number being in the CRM. Problem was I was focused on acquisition and growing, so not all the units ever made it into the CRM. We were picking up deals in Iowa. I was picking up deals in Arkansas, picking up deals we started buying in Texas.

Henry Washington:
And you were keeping these. These weren’t like wholesale deals.

John Crutchfield:
Never sold a property till the market turned and I realized I should have been selling some sometimes. It probably ended up being 600 plus.

Henry Washington:
That’s a lot of real estate across multiple states. Were you building teams in all these states to help you operate all this real estate and were you buying it all creative? That’s a lot, man.

John Crutchfield:
Yeah. So out of state means you got to leverage other people. And so a lot of times we were partnering with property management in those areas because I didn’t have a team there. And then you’re absolutely correct. You probably are not going to buy 500 plus units with it just being one house at a time, one property at a time. And so somewhere in 2017, 2018, it kind of clicked for me that a lot of property owners, a lot of landlords had more than one property that they would want to sell at one time.
And so I remember buying a package of 50 doors. I remember buying a package of 30. I would go on the property tax records and I would look for LLCs or people that had multiple properties under their name and they would get a text or an email from me. And at that point, my goal was growth. So if they asked me what I wanted to buy, it was like, how much are you willing to sell? And so I started being that leader, that visionary that was thinking, how fast can I grow the door count? Since I’ve realized that that actually doesn’t matter at all. So what I loved doing was making an offer on a property, figuring out what my renovations were going to be, figuring out what that ARV was going to be and putting that in a spreadsheet, figuring out what the rent was going to be, what the expenses I thought would be, and putting that in a spreadsheet.
And so what I would do is every time I was acquiring, I would just add to my spreadsheet and it starts to add up really fast. I mean, when I say I got addicted to this, I got addicted to every 30 days updating my personal financial statement and seeing my net worth just going up like crazy or every single month seeing the deposits in the bank account keep going up. And so if you’re somebody who grew up like I did or who was a school teacher and you’re making $3,000 net after your pay, seeing $100,000 hit a bank account or $200,000 start to hit a bank account every single month, you’re just looking at that top number saying, “This is beautiful. I’m doing something right.” But when you as the owner are focused on just growing, you are kind of at the mercy of your property management, you’re at the mercy of your team.
And then most importantly, you’re at mercy of the expenses staying the same as what was in your proforma, and that will not stay the same.

Henry Washington:
Were you still working your day job when you were this big?

John Crutchfield:
I quit my day job once I realized the possibilities, right? In fact, I just became a horrible employee, right? They would ask me to do something extra or give me an extra assignment and I was like, “Do I want to do this instead of trying to be a good team player?” So I remember, and this was in the peak of good times, I remember doing a deal where I added $300,000 into my net worth on one deal. I remember my boss saying, “Hey, we need you to teach an extra class or something and we’re not going to pay you for it because we think you can fit it in your schedule.” And I was like, “I got to talk to my wife, but I think I’m done.” And I ended up quitting, but I went full-time into this business somewhere around 2019. And so that meant every day I was giving 100% of my effort to growing the business.
I’m an entrepreneur now. I’m a full-time business owner. I probably work too much, but I don’t clock in or clock out. So it feels like I’m doing what I like to do.

Henry Washington:
And that’s specifically what I’d like to talk to you about right after the break is what were some of the lessons you learned as a technically small business operating a large portfolio. So let’s jump into that after we come back. All right, we’re back on the BiggerPockets podcast. I’m talking with investor Dr. John Crutchfield, who took growing and scaling to a whole new level and did it during a market transition. You said you quit your job in around 2019. The market got real good between 2019 and 2022, and then it’s been not as great from 2022, 2023 until now. So I’m very curious about what lessons you learned while you were in that growth mode and operating mode and how that’s shaped where your business is today.

John Crutchfield:
I learned that more doors does not necessarily mean more success. Once you get into it, you realize, okay, I’m actually now managing employees, I’m managing contractors, I’m managing inventory and materials that I don’t want to just walk off. All of the little issues that you might have on one project, I want you to start multiplying those by hundreds of doors. You know the stories, right? Contractor walks off with this material or you got a water leak or some kind of plumbing issue or AC out, and this is going to create wear and tear on your properties, but also ultimately affect your bottom line, which is what matters, not door count, your bottom line, what’s left over at the end of the month. And so people ask me, well, what’s it like? Were you really making 50, $100,000 a month? Henry, I remember celebrating at one point I was paying off a house every single month.
In Mississippi, a good house was 60, 70K. I was paying down 50, 60, 70K a month in debt pay down and looking at that like, man, I got a house paid off and I’m doing that every single month. So beautiful. But then you’d have some seasons of the year where we were giving that back in CapEx because when their AC goes off, it has to be fixed. You can’t say, well, I’m just a little landlord and I only have a property or two and I need you to understand or you’re going to be in a newspaper. You got to get those units fixed and get those people back up so that they’re operating, they can have a safe, affordable place to live. A key principle here is that it’s like a living, breathing organism as you grow that has so many lessons that you can’t find in a book.

Henry Washington:
Yes.

John Crutchfield:
And that’s what I learned.

Henry Washington:
So how did that change your business? Did you start to sell property? Did you stay in growth mode? What changed and when did it start to change?

John Crutchfield:
So big change started in late 2022, 2023. A lot of us are aware that the Fed started increasing interest rates. And if you have $30 million borrowed and your interest rate average is 4%, that’s like free money. It’s beautiful. You’re making payments and you got money left over to do stuff. But when that same $30 million, and a lot of my loans were these local community bank loans that reset every five years, ask me how they time this, okay? When they reset and then your average interest rate goes to eight, that literally is a huge increase in your expenses and it changes your lifestyle. So if I had one property where the mortgage payment went from 12,000 to 21,000, that changes the salaries that I can pay off that property. It changes the salary I can pay myself. And then you multiply that across the whole portfolio and you’re really in a tight trying to figure out, okay, how am I going to adjust?
The first adjustment we made is like, okay, let’s double down on the strategy that was working for me. I grew the business by burrowing, buying and fixing up the property and renting it out and refinancing. So let’s go borrow some more money so that we can have cash to keep operating. That was the first thing I did. The problem is we weren’t borrowing that cheap money anymore. We were borrowing more expensive money. And it got volatile, Henry. It got kind of volatile for a little bit as those rates were going up. Some of the lenders started squeezing in some 10% rates in there. So we had the cash to operate today, but not the cash to operate in the future if we were depending on cashflow. And so realized looking at the spreadsheets that this was not going to work. Eventually we were going to run out of cash and we were going to run out of the ability to keep borrowing.
And so this is when I started saying, okay, we got to sell some stuff. I wish I had took some chips off the table sooner. I will tell you something, this is probably put this on a bumper sticker. It’s actually very easy to buy real estate. It is a totally different game to sell real estate.

Henry Washington:
That’s true.

John Crutchfield:
And it’s a new skill that we’re still having to learn because we’re still selling some properties. Fortunately, I met some awesome realtors who have been helping dispose some of the portfolio, and I’m also now a licensed realtor, so I’ve learned a little bit more about selling properties as well. I told you I quit my job, but I thought that I quit my job to live off the rental properties. That was a misunderstanding. And so when you start pulling your lifestyle off of the rental properties, that makes the things tighter as well. And so what I learned as we started selling properties is like, oh, I actually still need an active income from something to make sure that I’m not pulling money off of these very limited tight margin rental properties and cash flows. So that’s probably a whole nother thing. But if I could save one person, I’m like, “Hey, quitting your job is beautiful in this business once you’re ready, but it’s not always the right thing for everybody.”

Henry Washington:
The realization I had was I’m running a business, the business makes money, and then if I take all the money it makes out of the business every month, it’s hard for the business to grow. If I suck every ounce of profit out and I don’t reallocate some of that to improving the business, the business doesn’t grow. Any business that isn’t real estate, they don’t do that. They don’t suck all the profits out and then hope the business grows. There’s a plan for reallocating profits to continue to grow the business. Two, most investors realize, okay, if I’m going to quit my job, it’s not going to be the cash flow that gets me there. It’s a hard realization because most of us get sold into real estate investing on the concept of properties paying for life’s expenses. That was the thing that got me. Oh, you want to buy a new car, get a house.
The house produces cash flow, cashflow pays for the car. In practice, it doesn’t always work like that because maintenance is unpredictable because even if you are predicting the maintenance, if you haven’t owned the property that long, you haven’t saved up enough cash to cover said maintenance item that comes from somewhere out of your pocket, which means you have less to go pay for this new car or this thing you have in your lifestyle. And so you realize the same thing I realized and the same thing that a lot of investors listening to this are going to realize that if I want to quit my job and use real estate, I can’t just do it on cash flow. I have to find another active income stream within the real estate space to do that. And there’s nothing wrong with that. And so I tell people, yeah, I retired from corporate, but I didn’t retire from working.
I flip houses. That’s a job. It’s a construction business. That’s what I do. And on its surface, I flip houses. So I run a construction business that renovates properties that produces cash. I use that cash and I live off that cash so I don’t have to touch my cash flow. I can use that cash to also pay down the assets and then at some point I won’t have to flip houses anymore. And so for those of you that are listening, if you want to quit your job, you can get there, but think of it in two phases. Phase one is if I want to get out of my corporate gig, what job within the real estate space can I replace my corporate gig with? Phase two is to work yourself out of having to have that active income stream over the course of the next several years.
So my goal is to take the flip proceeds, pay off more rentals. More paid off rentals is unleveraged cash flow, unleveraged cash flow is substantially higher than leverage cash flow, and at some point I don’t have to flip houses anymore. So that’s the way that I think people need to think about leaving their job.

John Crutchfield:
And you don’t need hundreds of doors if you’re looking at it like paid off rental property. So the 500 number, totally unnecessary. What you just said there is like gold for anybody that’s like, okay, if I want to fast track my knowledge five, 10 years in the business, just listen to what Henry just said about active cash flow, paying off your eventual retirement income.

Henry Washington:
Let’s put some actual numbers to this, if you don’t mind. Where does your portfolio stand today and where are you trying to get it to?

John Crutchfield:
I mean, at the peak, we probably were close to 30 to 35 million in assets and today we’re down to about 10 million.

Henry Washington:
Wow. So you sold two thirds of your portfolio?

John Crutchfield:
Yes. And selling and selling. So what that means is we’ve had capital to be able to reinvest in other things, but also it means we’ve taken some chips off the table. Unfortunately, we are not selling at a time where you can get those max values. And so that means that in some cases I’ve had to be a motivated seller. We wanted to get out of certain debt. Just to be clear, if I’m at a 10% interest rate right now, that property is not making money, not in the market that I’m in. So being out of them in certain cases was better than holding onto them. I don’t actually have a target anymore for the size of the portfolio because what I realized is that I already have more than I’ll ever need if it’s paid off.
I’ll give you an example. A lot of my properties are five, 10 property packages. Well, if I sell six of them, I’ve got four free and clear. And that’s been happening over and over for the last three years. So I’m starting to fall in love with the ones that we own that don’t have any payment, whereas the ones that are kind of in these packages and still in debt, especially if they’re not cash flowing, they got to go. Of course, I have a proforma and I have a spreadsheet, but when you go to sell, you don’t know what’s going to sell first or what’s going to sell for what.

Henry Washington:
There

John Crutchfield:
You go. And you’re kind of adjusting the plan every 30 days as it goes.

Henry Washington:
This is the realest real estate talk I’ve had in a while. All right, John, you shared a lot with us and I’m sure there are people who would love to learn more about you and the choices you’ve made in your business. And so if somebody wants to reach out, how can they find you?

John Crutchfield:
You can find me all over social handle is @grabthemap, or you can just search my name on Facebook. I’d probably hang out there where the old folks are. That’s what my kids tell me is where the old folks are.

Henry Washington:
All right, John. And if you are listening to this episode and you are thinking, “Man, I’ve got a pretty cool story I’d like to share with the listeners of the BiggerPockets Podcast,” well, you may have a chance. Why don’t you head on over to biggerpockets.com/guest and fill out the form. You may find yourself right here in a conversation with myself or Dave sharing your story for the betterment of our community. Once again, thank you so much for listening to the BiggerPockets Podcast. We’ll see you on the next episode.


Help us reach new listeners on iTunes by leaving us a rating and review! It takes just 30 seconds and instructions can be found here. Thanks! We really appreciate it!

Interested in learning more about today’s sponsors or becoming a BiggerPockets partner yourself? Email [email protected].


Source link

You Don’t Need Dozens of Rentals to Reach Financial Freedom (He Tried It) Read More »

AI Governance Needs Instrumentation, Not Insurance

AI Governance Needs Instrumentation, Not Insurance


AI Governance Needs Instrumentation, Not Insurance


What’s New?

Updated 2 hours ago


Source link

AI Governance Needs Instrumentation, Not Insurance Read More »

What LEGO’s Near-Collapse Taught Me About Saying ‘No’

What LEGO’s Near-Collapse Taught Me About Saying ‘No’


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Growth and ownership aren’t the same thing, and trying to personally run everything your business touches can bankrupt the parts that actually matter, one distraction at a time.
  • The instinct to build and operate everything in-house often masks a business that’s spreading its best people too thin across things they don’t actually do best.
  • A simple audit of what you own versus what you personally operate usually reveals one or two things you should hand off, long before the numbers would ever force the decision.

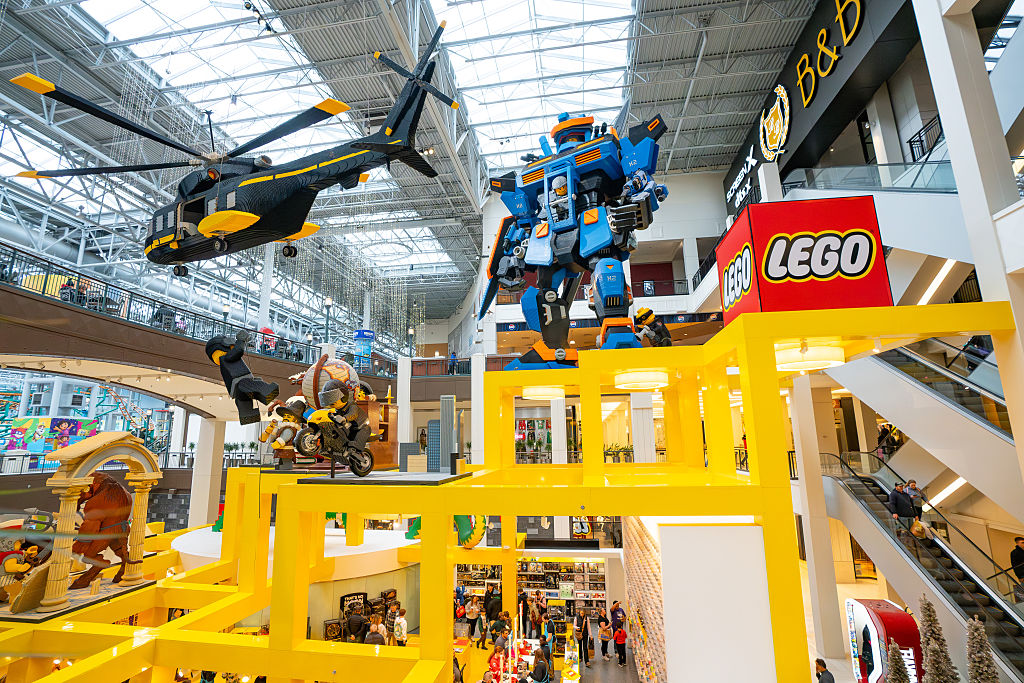
By the early 2000s, LEGO had expanded well beyond the plastic brick that built its name. The company was operating its own Legoland theme parks, running an in-house video game development studio and producing its own clothing line and television content. This looked like smart diversification: A toy company was evolving into a full entertainment brand.

But in practice, LEGO was trying to be an amusement park operator, a game studio and a clothing brand all at once, none of which it had ever actually been good at, while the core product — the brick sets that built its identity in the first place — lost focus and market share as attention scattered across everything else. By 2003, the company had lost close to a third of its revenue in a single year. It was reportedly within about 18 months of running out of cash entirely.

When Jørgen Vig Knudstorp became CEO in 2004, he did something a little unexpected: He didn’t abandon the games, parks or films. Instead, LEGO sold majority ownership of its theme parks to Merlin Entertainments, while keeping the licensing rights, so the brand stayed in the parks without LEGO having to run them. The in-house game studio was shut down, and LEGO began licensing its brand to specialist developers instead, which is how Lego Star Wars and Lego Batman came to exist (parents: ask your kids).

A decade later, The Lego Movie came to be the same way, as a licensed partnership with a film studio, not an internal production arm. LEGO kept every one of those businesses. It stopped being the one operating them.

This paved the way for one of the most legendary comebacks in business history.

The difference between owning something and running it yourself

Nobody at LEGO decided theme parks or video games were bad ideas. They were good ideas. The mistake was assuming that having a good idea for a business meant LEGO had to be the one personally running it.

Operating a theme park requires an entirely different set of skills than designing a toy. Building a video game engine requires an entirely different discipline than manufacturing plastic bricks. LEGO’s leadership had correctly identified where the opportunities were and incorrectly assumed that capturing the opportunity meant doing the operational work themselves.

The fix meant recognizing which parts of the opportunity they should own and license out, and which single thing, the brick system, they needed to run themselves better than anyone else could.

I’ve seen this pattern in the business owners I work with, and I also relate.

The year I had to decide

A few years ago, when my father passed away, I found myself responsible for running the family businesses on my own — work we had previously split between us. On top of that, I had my own growing venture: the coaching that has become an integral part of what I do today.

The logical move was obvious: The coaching business was the smallest revenue generator by far, and it was also demanding on my time because it was my newest venture. Every efficiency argument pointed toward shutting it down and focusing entirely on the established, profitable businesses.

I couldn’t do it.

That work was something that fulfilled me, and giving it up to save time felt like solving the wrong problem. So instead of cutting the newest business, I went back into one of the established ones and looked at every part of it individually: what each piece actually generated and how much of my direct, personal attention it needed to keep running.

Here’s what I found: It was, in fact, possible that someone else could run them well without my direct hand in it every day. So I handed them off, because keeping myself personally attached to them meant I never had the space to do the coaching work that mattered to me, or to lead the rest of the business properly.

The audit that actually makes a difference

The audits that business owners see regularly say nothing about which parts of your business are consuming your personal attention in a way the revenue number never shows. LEGO’s theme parks and game studio weren’t obvious disasters … for a while. They were slow leaks on leadership’s focus, long before the financial damage became impossible to ignore.

But that’s not to say any of those were bad decisions, because every business owner adds things for good reasons. There are opportunities too promising to pass up, natural extensions of what customers already love, which give you a chance to be involved in something exciting.

The mistake is assuming that chasing a good opportunity means you personally have to operate every part of it.

An exercise to run this month

Take the different parts of your business, whether that’s product lines, services, client segments or side ventures, and lay them out individually. For each one, ask two separate questions: “What does this actually generate?” and “Does it need my direct, personal involvement to keep running, or could someone else — a hire, a partner, a licensing arrangement — run it perfectly well without me in the middle of it?”

You’re looking for the mismatch: the thing that deserves to exist in your business, but doesn’t actually need you personally running it day to day.

When you find it, you have the same decision LEGO made when it sold the theme parks and shut down the game studio while keeping both in the business through licensing. Own the thing that made you valuable in the first place. Let people who are more suited to operating the rest actually operate it.

The real goal was always creating something built to last. Sometimes, the fastest way back to that starts with being honest about which parts you actually need to be doing yourself.

Here’s to building a business, and a life, with zero regrets.

Key Takeaways

  • Growth and ownership aren’t the same thing, and trying to personally run everything your business touches can bankrupt the parts that actually matter, one distraction at a time.
  • The instinct to build and operate everything in-house often masks a business that’s spreading its best people too thin across things they don’t actually do best.
  • A simple audit of what you own versus what you personally operate usually reveals one or two things you should hand off, long before the numbers would ever force the decision.

By the early 2000s, LEGO had expanded well beyond the plastic brick that built its name. The company was operating its own Legoland theme parks, running an in-house video game development studio and producing its own clothing line and television content. This looked like smart diversification: A toy company was evolving into a full entertainment brand.

But in practice, LEGO was trying to be an amusement park operator, a game studio and a clothing brand all at once, none of which it had ever actually been good at, while the core product — the brick sets that built its identity in the first place — lost focus and market share as attention scattered across everything else. By 2003, the company had lost close to a third of its revenue in a single year. It was reportedly within about 18 months of running out of cash entirely.

When Jørgen Vig Knudstorp became CEO in 2004, he did something a little unexpected: He didn’t abandon the games, parks or films. Instead, LEGO sold majority ownership of its theme parks to Merlin Entertainments, while keeping the licensing rights, so the brand stayed in the parks without LEGO having to run them. The in-house game studio was shut down, and LEGO began licensing its brand to specialist developers instead, which is how Lego Star Wars and Lego Batman came to exist (parents: ask your kids).


Source link

What LEGO’s Near-Collapse Taught Me About Saying ‘No’ Read More »

Why Better Branding Makes More Money Than Better Marketing

Why Better Branding Makes More Money Than Better Marketing


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • The first conversation with a customer is not the beginning of the sales process. It’s often closer to the end of it. Your first impression actually starts with whatever exists on the internet about you and your business.
  • People don’t hire the first company they find. They hire the first one they truly believe in.

For a long time, winning in real estate meant being easier to find. Get your name in front of more people, show up on more searches, run more ads and post more content. The industry built its entire marketing philosophy around the assumption that the agent who reached the most people would get the most business.

That assumption is quietly breaking down.

Consumers today are not starved for options. They’re overwhelmed by them. A buyer in any major market can find dozens of qualified agents before lunch without trying particularly hard. Search, referrals, social media, AI tools, Zillow profiles. Discovery is essentially solved. What hasn’t been solved — and what actually determines who gets hired — is something different and considerably harder to manufacture.

Who do they believe?

Discovery is no longer the hard part

The marketing problem most brokerages are still trying to solve was genuinely difficult 15 years ago. Getting found required real effort, real investment and real strategy. The playing field rewarded whoever could achieve the most visibility. That era produced an entire industry built around lead generation, impression counts and reach.

Lead generation has been commoditized. Practically every brokerage has access to the same digital tools, the same ad platforms, the same syndication networks. Being findable is table stakes now, not a competitive advantage. The brokerages still treating it as their primary strategic focus are optimizing for a problem that largely solved itself.

The harder problem, the one most of the industry is underinvesting in, is what happens after someone finds you. A consumer has now discovered three or four qualified agents. They look at each one for a few minutes. They read some reviews. They scroll through some content. They may ask an AI tool who the most respected agents in the area are. At the end of that research session, one of them feels like the obvious choice and the others feel like options.

What made one feel obvious? That’s the question that matters.

Consumers are buying confidence, not information

Here’s the thing most marketing misses about what people actually need when they’re making a high-stakes decision. They’re not looking for more informatio — they already have more information than they know what to do with. What they’re looking for is a reason to stop being uncertain.

Confidence is the real product in real estate. Not MLS access. Not showing schedules. Not transaction coordination. The thing a buyer or seller is actually purchasing when they hire an agent is the feeling that they’ve put this complicated, financially enormous, emotionally loaded process into hands they can trust. When that confidence exists, the conversation is easy. When it doesn’t, no amount of follow-up calls or drip emails can manufacture it.

Trust reduces perceived risk. That’s what it’s doing functionally in the consumer’s brain. When someone trusts you, they stop running through worst-case scenarios. They stop second-guessing. They stop hedging. They commit. And the brokerages that understand trust as a business asset, not a soft skill, are building toward a completely different competitive position than the ones still chasing clicks.

The sales process starts long before the first call

Here’s where strategy needs to shift. Every public signal surrounding a brokerage or agent is doing trust-building work before any conversation happens. Reviews. Media coverage. The quality of published market insights. Whether the agent has been quoted somewhere credible. Whether their educational content suggests they actually understand the nuances of the local market or just know how to use Canva.

Consumers increasingly arrive having already researched you. The first conversation is not the beginning of the sales process. It’s often closer to the end of it. And the agent who walks into that conversation with a trail of credible third-party signals behind them is starting from a fundamentally different position than one who showed up with a nice headshot and some listing stats.

Most brokerages are obsessed with generating more leads. Very few ask seriously why they lose the leads they already have. A significant portion of those losses happen before the first meeting, during the research phase, when a consumer is quietly deciding whether this particular brokerage feels like the obvious choice or just another option. No amount of lead generation investment fixes that problem. The fix lives upstream.

Think like a reputation architect, not a marketer

The mental model shift here is specific. Marketing asks: How do we get more people to find us? Reputation architecture asks: What does someone find when they look, and does it make us easier to believe?

Those are different questions with different answers. Marketing produces content. Reputation architecture produces signals. Content fills time. Signals accumulate into something that changes how a brokerage is perceived before anyone has spoken to them.

Every published market analysis that demonstrates real knowledge of a neighborhood. Every media mention that positions an agent as a credible voice in the local housing conversation. Every client review that describes something specific rather than just saying it was a great experience. Every piece of original thinking that makes someone pause and consider a perspective they hadn’t encountered before. These things aren’t separate marketing activities. They’re deposits into something that eventually becomes the most valuable asset a brokerage has: the default assumption that they’re the right choice.

The first agent they believe

Pull together everything that shapes who wins a high-stakes service decision. Discovery matters, but discovery is nearly even across the field now. Price matters at the margins. Referrals matter, but referrals still require a research phase where someone decides whether the recommendation makes sense. What ultimately determines selection, consistently, is uncertainty reduction. The option that makes someone feel most confident tends to win even when other options are objectively comparable.

People don’t hire the first agent they find. They hire the first agent they believe.

If someone spent 20 minutes researching your brokerage today, what story would they find? Media coverage that signals expertise? Reviews that describe specific moments of value? Published thinking that demonstrates real understanding of what’s happening in the local market? A clear sense of who you are and what you actually stand for? Or would they just find listings?

The brokerages that answer that question honestly and don’t like what they find have identified the actual strategic problem. It’s not a lead generation problem. It’s a belief gap. And closing it requires investing in something most real estate marketing budgets still treat as secondary: becoming genuinely easy to trust before anyone has asked you to earn it.

Key Takeaways

  • The first conversation with a customer is not the beginning of the sales process. It’s often closer to the end of it. Your first impression actually starts with whatever exists on the internet about you and your business.
  • People don’t hire the first company they find. They hire the first one they truly believe in.

For a long time, winning in real estate meant being easier to find. Get your name in front of more people, show up on more searches, run more ads and post more content. The industry built its entire marketing philosophy around the assumption that the agent who reached the most people would get the most business.

That assumption is quietly breaking down.

Consumers today are not starved for options. They’re overwhelmed by them. A buyer in any major market can find dozens of qualified agents before lunch without trying particularly hard. Search, referrals, social media, AI tools, Zillow profiles. Discovery is essentially solved. What hasn’t been solved — and what actually determines who gets hired — is something different and considerably harder to manufacture.


Source link

Why Better Branding Makes More Money Than Better Marketing Read More »