Blog

The Networking Mistake That Feels Productive but Quietly Stalls Your Business

The Networking Mistake That Feels Productive but Quietly Stalls Your Business


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Motion isn’t progress. Networking can feel productive, but no introduction will make up for a weak product, poor service or a lack of customer trust.
  • Build first, and the right relationships follow. Doing great work, collaborating well and following through on specific outreach earn the trust that turns contacts into lasting relationships.

Most entrepreneurs spend a lot of time thinking about networking, and it makes sense. Industry events, conferences, panels, coffee meetings and dinners can lead to customers, partners, hires and investors that would never come through a cold channel.

But I think many founders misunderstand what kind of networking actually pays off.

In my view, the best networking is a byproduct of doing excellent work, serving customers well and becoming known for something specific. When that happens, the right relationships tend to find you. Investors reach out because the company is working. Customers refer you because the experience was great. Other operators want to meet you because you’ve built something worth understanding. The strongest networks rarely come from handing out the most business cards. They come from trust earned again and again over time.

The problem with networking before you have traction

Networking can become a distraction, especially early on. It can look like spending time at panels and conferences hoping one meeting will fix the underlying challenge of building the business, while the fundamentals, such as the product, customer experience and follow-up, aren’t where they need to be.

The uncomfortable truth is that no amount of networking will make up for a weak product, inconsistent service or a lack of customer trust. If the product isn’t working, more introductions usually won’t fix it. If customers don’t feel taken care of, more surface-level relationships won’t create a lasting business.

I’ve been there myself. A coffee meeting can feel productive because it creates motion. You had a conversation, made a new contact and maybe got some advice. But motion isn’t progress, and it’s easy to confuse the two when the real work is harder to face.

For a founder, the real work might be talking to customers, improving the product, tightening the business model or making a hard hiring decision. These tasks may not feel as exciting as meeting new people, but they’re usually what make networking work later.

Why founder friendships are different

I don’t want to dismiss relationships altogether. I’ve benefited enormously from a core group of founder friends, and that’s very different from general networking.

These are people who know me, understand my business and have lived through enough of the founder journey that I can be honest with them in ways that are harder with employees, investors or board members. They understand the pressure of making decisions with incomplete information, being responsible for other people’s livelihoods and pushing forward when the answer isn’t obvious. Peers like that challenge your thinking and share what they’ve learned, which is incredibly valuable.

What makes these relationships work is depth, trust and shared context. They aren’t random contacts collected at events. They’re people who have seen how you work, understand what you’re building and have a reason to stay invested in your progress.

How to build the network that actually matters

For some people, that network already exists through school, past companies, former colleagues or years in the same industry. Others have to build it more intentionally.

If you’re an early founder without a real network, I recommend spending time in a high-talent environment before starting your own company. Work at a great startup. Join a team with excellent engineers, operators, salespeople and product thinkers. Learn how strong people work, build trust with them and form relationships based on doing hard things together.

The same principle applies in any industry: the best relationships come from real collaboration and follow-through. Take real estate. The agents with the strongest referral networks usually aren’t the ones at every event. They’re the ones who make the lender’s job easier, communicate well with attorneys and vendors, and protect the client experience when a deal gets stressful. Over time, people remember who made the work smoother and who handled pressure well.

Targeted outreach can work

Targeted outreach still has value when it’s done well. If you reach out to someone a few years ahead of you, in a relevant market, with a specific reason for wanting their perspective, many people will respond. Most founders had help along the way, and there’s a natural instinct to pay it forward when a request feels genuine.

A thoughtful, specific question will usually get a better response than a vague request to “pick your brain.” Someone who studies how another founder built their business and asks about one relevant decision is far more likely to make a real connection than someone sending the same message to 50 people.

Follow-through is what turns that first conversation into something meaningful. When someone asks for advice, acts on it, reports back on what happened and keeps the other person updated, the relationship changes. That’s the kind of networking that works: specific, earned and grounded in action.

The best network is usually a byproduct of doing the work so well that people want to be close to it. Build something strong, serve people well, follow through and become known for a clear standard. The relationships that matter will follow.

Key Takeaways

  • Motion isn’t progress. Networking can feel productive, but no introduction will make up for a weak product, poor service or a lack of customer trust.
  • Build first, and the right relationships follow. Doing great work, collaborating well and following through on specific outreach earn the trust that turns contacts into lasting relationships.

Most entrepreneurs spend a lot of time thinking about networking, and it makes sense. Industry events, conferences, panels, coffee meetings and dinners can lead to customers, partners, hires and investors that would never come through a cold channel.

But I think many founders misunderstand what kind of networking actually pays off.

In my view, the best networking is a byproduct of doing excellent work, serving customers well and becoming known for something specific. When that happens, the right relationships tend to find you. Investors reach out because the company is working. Customers refer you because the experience was great. Other operators want to meet you because you’ve built something worth understanding. The strongest networks rarely come from handing out the most business cards. They come from trust earned again and again over time.


Source link

The Networking Mistake That Feels Productive but Quietly Stalls Your Business Read More »
Workers Are Becoming AI Managers, Without Pay Raise, Promotion

Workers Are Becoming AI Managers, Without Pay Raise, Promotion


Key Takeaways

  • AI is changing the way people work without giving them a pay raise or promotion.
  • Employees spend more time managing AI bots that do tasks humans were initially hired to do.
  • They spend less time on work responsibilities related to their professions.

AI promises to make employees more productive. It may also turn them into managers of AI bots — without a promotion or pay increase. 

According to a recent Business Insider report, AI is changing the workday for many employees. Employees face pressure to use the technology and consequently spend more time managing AI bots that do tasks humans were initially hired to do, like teaching, coding, writing or designing. They now spend less time on work responsibilities related to their professions and more time managing bots that do work for them. 

For many workers, AI now comes with management responsibilities. They must tell agents what to do, review their output, ask for changes and step in when something goes wrong. Other employees spend much of their time checking AI-generated work and remain accountable for everything that gets published or sold. 

The idea that AI could turn every worker into a manager has been around for years. Now, companies are putting it into practice.

Salesforce recently introduced “job-ready agents” for sales, customer service, ecommerce and internal operations. The company is also giving employees tools to train those agents and improve their results.

At the same time, IT service provider Wipro has seen massive productivity improvements due to AI. The company’s chief technology officer, Sandhya Arun, said in an interview with Business Insider that AI has added the productivity equivalent of 20,000 workers. She imagines a future in which one engineer can manage a group of agents.

Meanwhile, at Daytona, a 30-person AI startup, CEO Ivan Burazin recently told Business Insider that each of its 16 engineers oversees about five AI agents on average. He said employees there no longer write code themselves.

The pros and cons of managing AI

Sinda Khenine became a software engineer because she wanted to build things. But today, much of her job involves overseeing the AI systems that do much of that building for her, she told Business Insider.

Khenine, a software and AI engineer at Electrolux who is also starting her own AI business, says that on the pro side, agents have helped her write more code and build a company on her own. That’s something that would have been “10 times harder” before, she acknowledged.

However, the trade-off is that she spends less time on the hands-on engineering work she originally loved. Instead, she picks the models, gives them context and rules, checks their work and pieces together output from several agents into a finished product.

“The effort is more focused on the coordination itself rather than the engineering problem that we are solving in the first place,” Khenine told Business Insider. 

Khenine also manages people at Electrolux, but she said overseeing AI agents can be even more demanding. Agents need extensive setup, and they require continued attention after they start working.

“It’s like a loop,” she says. “You need to monitor the results, you need to see the progress. You need to decide if you need to rerun or finish the job.”

Key Takeaways

  • AI is changing the way people work without giving them a pay raise or promotion.
  • Employees spend more time managing AI bots that do tasks humans were initially hired to do.
  • They spend less time on work responsibilities related to their professions.

AI promises to make employees more productive. It may also turn them into managers of AI bots — without a promotion or pay increase. 

According to a recent Business Insider report, AI is changing the workday for many employees. Employees face pressure to use the technology and consequently spend more time managing AI bots that do tasks humans were initially hired to do, like teaching, coding, writing or designing. They now spend less time on work responsibilities related to their professions and more time managing bots that do work for them. 

For many workers, AI now comes with management responsibilities. They must tell agents what to do, review their output, ask for changes and step in when something goes wrong. Other employees spend much of their time checking AI-generated work and remain accountable for everything that gets published or sold. 


Source link

Workers Are Becoming AI Managers, Without Pay Raise, Promotion Read More »

She Spent  Million on 6 Tutoring Franchises, Then Lost Them All

She Spent $3 Million on 6 Tutoring Franchises, Then Lost Them All


Key Takeaways

  • Danielle Scott bought six tutoring centers in Central Florida right before the Great Recession and had to close them all.
  • Tutoring was among the first expenses many customers cut when they needed to tighten their budgets.
  • Scott eventually recovered and returned to the franchise industry; she now serves as chief development officer at Alliance Franchise Brands.

Danielle Scott had spent years working in franchise development when she got an opportunity that appeared too good to be true and almost impossible to pass up: buying six tutoring centers in Central Florida.

She was successful, ambitious and, by her own description, “pretty arrogant.” The chance to become a franchise operator felt like the next logical move. So Scott assembled funding, drawing from her own savings and money from her family and friends, and bought the portfolio for more than $3 million in the early 2000s.

“Everybody could get money back then,” Scott says in a new interview with Entrepreneur. “Money was very easy and very cheap, and that was the problem.”

Danielle Scott. Credit: Alliance Franchise Brands

In hindsight, Scott saw warning signs she didn’t fully investigate. She says she should have asked why the tutoring company was selling off corporate-owned locations. At the time, however, she interpreted it as an extraordinary opportunity rather than a possible indication of risk.

“I got very excited,” she says. “I was very young, and I was very successful, and I pretty much had the world in the palm of my hand at that moment.”

Then the Great Recession happened

The 2008 Great Recession hit Scott’s businesses hard. When the economy worsened, many households began cutting discretionary spending. Tutoring, music lessons and extracurricular activities were often among the first expenses to go.

The business suffered an immediate exodus of customers. Scott says one child’s program could cost nearly $5,000 per year, and as parents withdrew their children, the revenue loss piled up rapidly.

“Everybody was pulling out their kids,” Scott says. “We lost $180,000 in one week. We didn’t have enough money to keep things afloat; we had to start closing the centers.” 

The centers were in Central Florida, a market Scott says was hit especially hard by the downturn. Her recollection of the period is defined by incomplete housing developments, closed businesses, empty malls and a swift increase in crime.

“There were roads that were being built into neighborhoods that would just stop,” she says. “You would see a road going up a hill with street lamps, no houses, just a road, and it just stopped.”

The conditions were devastating not only because of the macroeconomic collapse, but also because Scott had built a business model that depended on customer spending that could be postponed or eliminated. In a downturn, many families didn’t view tutoring as a necessity, even if Scott believed in the service and the company’s mission.

Closing the centers

As the centers’ finances deteriorated, Scott began closing them. She ultimately lost all six businesses.

The loss was financial, professional and personal. Scott employed more than 100 people, some of whom had spent a decade or more with the tutoring centers. Some blamed Scott for their lost jobs. She received death threats. And for a time, she believed the collapse had ended her career in franchising.

Eventually, she realized that “this situation would have happened whether I was standing there or not,” she says. “There was nothing that anybody could do.”

Before the collapse, Scott believed that she had reached the top of her professional game. She had corporate experience, operational knowledge, a growing portfolio and the confidence that comes with early success. Losing the businesses forced her to reassess her identity as a leader. 

“It humbled me completely,” Scott says. “I mean, beyond humbled me.”

Reflecting on that time, Scott now believes she should have paid closer attention to the broader business environment and demanded answers about why the franchisor was divesting corporate-owned units. She had been senior enough to recognize that the decision warranted scrutiny, but she did not pause long enough to conduct the level of due diligence she now considers necessary.

“If I had, I probably wouldn’t have bought them at all,” she says. 

The emotional toll was equally severe. Scott feared that the loss had permanently damaged her standing in franchising.

“It made me feel like I had ruined my career,” she says. “It made me feel as though I would never work in franchising again because who does something like this at the top of their career and then fails so massively?”

Returning to the franchise industry

Her return was not immediate. Scott says it took about three years after the collapse for her to feel that she had truly come back to the franchise industry. 

“It took a lot of people telling me that it wasn’t my fault and that they still wanted to work with me and that I was still amazing and that I still had a lot to offer to the industry,” she says.

Scott dipped her toe back into the franchise industry by helping a franchise owner pursue growth and secure an equity partner. She was initially hesitant, but the relationship became a successful experience.

Today, as chief development officer of Alliance Franchise Brands, Scott helps guide franchise growth, legacy ownership transitions, business sales and acquisitions across brands including graphics and signage franchises Allegra and Image360.

Her advice to entrepreneurs is not to minimize hardship or pretend that failure is painless. Her story makes it clear that when a business collapses, it can carry economic consequences, damaged relationships, public embarrassment and grief. But she believes that leaders cannot afford to remain trapped. 

“Don’t sit in it too long,” Scott says. “Let it be what it is, because the failures and the hits, they’re just going to keep coming — and all it does is make you better.”

For Scott, that perspective was hard-won. The crisis had made her feel exposed and ashamed, especially when employees blamed her for the closures. But over time, she came to see the difference between a flawed decision and a permanent personal failure.

“Just because you failed at something doesn’t mean you fail at everything,” she says. “And just because this happened doesn’t mean that it’s a reflection upon you.”


Source link

She Spent $3 Million on 6 Tutoring Franchises, Then Lost Them All Read More »

How to Use AI to Rethink Workflows, Not Just Speed Them Up

How to Use AI to Rethink Workflows, Not Just Speed Them Up


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • AI-assisted isn’t AI-native. Adding AI to an existing workflow creates incremental gains, but redesigning the workflow from scratch is where the bigger advantage lies.
  • Give AI the grunt work, and keep humans where judgment matters. Let AI handle research, data and first drafts, and design the product so people stay in control of the moments that depend on their judgment and relationships.

There’s a lot of noise around AI right now, and most of it describes a familiar pattern: a chatbot layered on top of existing software, an automation added to a workflow or a feature that helps someone finish a task a little faster.

Some of those features are genuinely valuable. If AI can reduce manual work, make information easier to find or help someone move through a task more efficiently, that’s real utility. But useful and AI-native aren’t the same thing.

Much of what gets called AI-native today is really AI-assisted. The old workflow is still there, the same person handles the same sequence of steps and the same assumptions shape the product. The AI simply sits on top and speeds up parts of it.

That creates incremental value, but it has a ceiling. When you assume the existing workflow is fixed, you limit yourself to improving the work as it is instead of asking whether it should be redesigned altogether. The companies that build truly AI-native products will think very differently.

AI-native design starts with the work, not the feature

The most important question isn’t “How can we add AI to this product?” It’s “If we were designing this workflow from scratch, knowing what AI can and can’t do, what would the best version look like?”

Those questions lead to very different products. Start with the existing workflow, and you’ll likely end up with a better tool: a few faster steps, some automated tasks, easier access to data. The product improves, but the user’s day-to-day work looks largely the same.

Start with the work itself, and you’re forced to ask more fundamental questions. What outcome is the user trying to achieve? Which parts of the work require human judgment, taste, context or relationship-building? Which parts are repetitive, research-heavy or data-driven, and better suited to AI? Where should the human stay in control, and where are they doing work software can now handle better?

The best AI-native products may even feel surprisingly quiet, because the value comes from redesigning the workflow beneath the surface rather than adding something flashy on top.

How we applied this to our CRM

At Luxury Presence, we recently went through this exercise while building our new customer relationship management (CRM) product.

Our customers are professionals whose businesses run on personal relationships. The best of them stay in touch with their contacts, follow up at the right moments, remember client preferences, track life events, maintain referral relationships and make clients feel cared for long after a deal closes.

That work is valuable, but it’s time-consuming. Most of our customers know they should reach out to past clients and prospects more consistently, but doing it well takes research, context, timing, writing, personalization and follow-through. When they’re also serving clients, closing deals and running a business, relationship-building is often the first thing to slip.

We could have asked how to make the existing CRM experience better by adding AI-generated email copy, a chatbot or a feature that made the current workflow slightly faster. Instead, we asked what relationship management should look like now that AI can already handle parts of the process extremely well. Three areas stood out:

  • Researching contacts. AI can pull together relevant signals, identify useful context and surface timely reasons to reach out faster and more consistently than a person manually combing through a database.
  • Filling in missing information. AI can find third-party data, fill gaps and organize information around each contact, making the whole system more useful.
  • Drafting personalized messages. With enough context, AI can produce a strong first draft, especially when the alternative is that the message never gets written.

Where the human still matters

For our customers, the personal relationship is the business. They know things about their clients that no system may capture: the nuance of a relationship, the right tone, the history that matters and context that never makes it into a database.

That’s why we chose a human-in-the-loop model. AI does the research, fills in the contact record, flags the opportunity and drafts the message, but the user reviews it, customizes it if needed and decides when to send it.

The goal isn’t to replace the relationship. It’s to remove enough manual work that people can show up more consistently and thoughtfully in the relationships that already drive their business. A fully automated message may be technically possible, but possible doesn’t always mean valuable. In a relationship business, the user’s judgment is part of what clients are paying for.

How to apply this to your business

The same exercise works for almost any product or team. Before adding AI to anything, try this:

  1. Define the outcome. Ignore the current process and name what the user or employee is ultimately trying to achieve.
  2. Break the work into parts. List every task involved, including the ones that tend to get skipped because they take too long.
  3. Sort each task. Decide which parts depend on human judgment, taste or relationships, and which are repetitive, research-heavy or data-driven.
  4. Assign the work. Give AI the tasks it handles well, and design the product so people stay in control of the moments where their judgment creates the most value.

Most companies are still in the AI-feature stage, adding useful tools to existing systems and calling it transformation. Some of those tools will help, but the bigger advantage will go to companies willing to redesign their workflows from the ground up.

The most valuable AI products won’t just make yesterday’s work faster. They’ll help people do the right work better.

Key Takeaways

  • AI-assisted isn’t AI-native. Adding AI to an existing workflow creates incremental gains, but redesigning the workflow from scratch is where the bigger advantage lies.
  • Give AI the grunt work, and keep humans where judgment matters. Let AI handle research, data and first drafts, and design the product so people stay in control of the moments that depend on their judgment and relationships.

There’s a lot of noise around AI right now, and most of it describes a familiar pattern: a chatbot layered on top of existing software, an automation added to a workflow or a feature that helps someone finish a task a little faster.

Some of those features are genuinely valuable. If AI can reduce manual work, make information easier to find or help someone move through a task more efficiently, that’s real utility. But useful and AI-native aren’t the same thing.

Much of what gets called AI-native today is really AI-assisted. The old workflow is still there, the same person handles the same sequence of steps and the same assumptions shape the product. The AI simply sits on top and speeds up parts of it.


Source link

How to Use AI to Rethink Workflows, Not Just Speed Them Up Read More »

Your Instinct Might Be to Cut Brand Marketing in a Downturn. Our Sales Pipeline Told a Different Story.

Your Instinct Might Be to Cut Brand Marketing in a Downturn. Our Sales Pipeline Told a Different Story.


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Cutting brand to fund lead generation backfires over time. Leads get harder to close, and competitors who stay visible win more business when demand returns.
  • Prove brand’s value with deal speed, not direct attribution. Tracking how quickly prospects move through the pipeline when brand campaigns are running gives leadership evidence they can trust.

When budgets get tight, most companies make the same move: they cut brand marketing and put every dollar into lead generation. It’s easy to see why. A paid search campaign that brought in 200 demo requests last month has a clear return you can show your CFO. A podcast sponsorship that makes future buyers recognize your name doesn’t. But cut brand long enough, and those leads get harder to close, more expensive to win and slower to come back when the market recovers.

When performance marketing eats the entire budget, a company stops creating demand and starts harvesting only what already exists in the market. On a spreadsheet, cutting upper-funnel spend looks like prudent governance: pause expensive media campaigns, put every dollar toward immediate conversions and present a clean return to leadership. Repeat that decision cycle after cycle, though, and you’re trading long-term market share for short-term efficiency.

The cost of harvesting without planting

Over my years leading marketing through shifting market cycles and economic headwinds, I’ve watched this tension play out again and again. During extended downturns, the instinct is to pull spending deeper into lead capture. For a public company under pressure to show profitability, the urge to cut anything without immediate, line-item attribution is almost irresistible.

The risk comes when a company over-indexes on demand capture for too long: it hits a wall of diminishing returns. Inbound form fills might hold steady for a quarter or two, but lead quality drops sharply. Prospects arrive without context or familiarity, so sales teams spend twice the effort explaining who you are and why you matter, burning valuable capacity on cold prospects who don’t yet trust the company.

Worse, pulling back on brand during a downturn costs you your place at the starting line when demand rebounds. Brand awareness isn’t a light switch you can flip back on when the economy loosens. If you go dark while conditions are tough, competitors who maintained their presence capture most of the recovering demand, and you’re left rebuilding recognition from scratch at a much higher cost.

Build a return case your CFO will accept

Breaking this cycle requires marketing leaders to change how they frame brand value in the boardroom. Asking a CFO to trust intuition or fuzzy ROI will fail every time. Brand investment can’t be presented as a leap of faith; it has to be tied to concrete proxy metrics that reflect real pipeline acceleration.

When my team set out to rebalance our marketing portfolio at Ryder, we stopped trying to prove direct attribution for broad awareness, which is nearly impossible. Instead, we focused on localized correlation and deal velocity, establishing a clear link between upper-funnel presence and bottom-of-funnel conversion.

We worked with partners to tag digital touchpoints during active brand campaigns, tracking regional website traffic jumps of more than 20% within a five-second window of campaign airtime. Then we mapped how that heightened visibility affected active deal cycles.

The data revealed a pattern even the most numbers-focused executive team could respect: when brand messaging is active in a market, prospects move through the sales pipeline significantly faster. Visibility validates your story before the first sales call, reducing friction and shortening sales cycles. Pairing those traffic spikes with annual brand perception studies gave our executive team clear evidence that brand spending isn’t a discretionary luxury. It’s the infrastructure that makes lead generation efficient.

Rebalance without breaking the budget

Rebalancing doesn’t require a multimillion-dollar broadcast buy in the middle of a lean cycle. If budget pressure rules out major broadcast channels, marketing leaders can shift a portion of performance dollars into targeted digital brand presence. Placing story-driven content on the specific channels where key decision-makers spend time keeps your brand visible without an outsized budget line.

Maintaining steady brand investment also keeps a company from yanking spending up and down with every quarterly shift. Expecting bottom-of-funnel tactics to drive sustainable revenue without brand equity is like asking someone to sign a marriage certificate before you’ve taken them to dinner.

Sustainable growth belongs to leaders who treat brand building and lead generation as two halves of the same engine. Lead generation captures today’s business; brand investment ensures tomorrow’s pipeline exists at all. Winning the budget argument isn’t about abandoning financial accountability. It’s about making sure your company stays top of mind long after the current quarter ends.

Key Takeaways

  • Cutting brand to fund lead generation backfires over time. Leads get harder to close, and competitors who stay visible win more business when demand returns.
  • Prove brand’s value with deal speed, not direct attribution. Tracking how quickly prospects move through the pipeline when brand campaigns are running gives leadership evidence they can trust.

When budgets get tight, most companies make the same move: they cut brand marketing and put every dollar into lead generation. It’s easy to see why. A paid search campaign that brought in 200 demo requests last month has a clear return you can show your CFO. A podcast sponsorship that makes future buyers recognize your name doesn’t. But cut brand long enough, and those leads get harder to close, more expensive to win and slower to come back when the market recovers.

When performance marketing eats the entire budget, a company stops creating demand and starts harvesting only what already exists in the market. On a spreadsheet, cutting upper-funnel spend looks like prudent governance: pause expensive media campaigns, put every dollar toward immediate conversions and present a clean return to leadership. Repeat that decision cycle after cycle, though, and you’re trading long-term market share for short-term efficiency.

The cost of harvesting without planting

Over my years leading marketing through shifting market cycles and economic headwinds, I’ve watched this tension play out again and again. During extended downturns, the instinct is to pull spending deeper into lead capture. For a public company under pressure to show profitability, the urge to cut anything without immediate, line-item attribution is almost irresistible.


Source link

Your Instinct Might Be to Cut Brand Marketing in a Downturn. Our Sales Pipeline Told a Different Story. Read More »

3 Ways to Protect Your Margins When Growth Slows

3 Ways to Protect Your Margins When Growth Slows


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • When growth becomes harder to predict, the answer is not always blunt cost-cutting.
  • Founders can improve the economics of growth by reducing variation, removing integration friction and turning customer success into a source of recurring value.

When revenue growth becomes harder to predict, cost discipline matters more. But as the founder of ButterflyMX, I’ve learned that the most durable opportunities do not always come from cutting headcount or delaying investments. They often come from reducing the cost and complexity of growth itself.

I see this clearly in proptech, where scaling can involve hardware, software, onsite deployments, integrations and ongoing customer support. But the underlying lesson applies to many businesses: Growth gets expensive when every new customer requires you to reinvent how the company operates.

Here are three ways founders can make growth more repeatable and protect margins in the process.

1. Turn successful pilots into repeatable playbooks

A successful pilot proves that a customer wants what you are selling. It does not prove that you can deliver it profitably at scale.

The problem often becomes visible after the first few wins. Each new customer requires a slightly different onboarding process, configuration, implementation workflow or support model. Individually, those exceptions may seem manageable. Across dozens or hundreds of customers, they create more labor, longer deployments and higher costs.

The lesson I’ve learned is to treat scaling like product development. Examine what worked, identify what truly needs to be customized, and standardize everything else.

Start with the customer profile. Define which types of customers are most likely to see value, what problems they are trying to solve and what conditions make implementation successful. Then build a repeatable sales process around the business case rather than the product alone.

Apply the same discipline to delivery. Standardize configurations, implementation requirements, documentation and handoffs between sales, implementation and customer success. A customer may have unique needs, but the internal process for serving that customer should not be entirely unique.

The goal is not to eliminate flexibility. It is to eliminate unnecessary variation. Every custom workflow and manual handoff adds cost, and those costs compound as the business grows.

2. Remove integration friction before it becomes a scaling tax

The second problem is fragmentation.

Most businesses eventually accumulate technology from different vendors, departments and stages of growth. When those systems cannot communicate easily, every new implementation can create another integration project.

I see this frequently in real estate. A single property might have access control, energy management, maintenance software, sensors, resident applications and other systems operating alongside one another. The same challenge exists in other industries wherever companies rely on a growing collection of specialized technology.

Founders should think about interoperability before fragmentation becomes expensive. That starts with consistent data. Information should use common definitions and structures so it can move between systems without requiring teams to repeatedly clean, translate or reconcile it.

Open interfaces matter, too. Application programming interfaces and other common standards make it easier to connect new systems without rebuilding the technology environment around them.

In real estate, that principle can extend from access control and energy management to in-unit thermostats. The point is not to connect technology simply because it can be connected. It is to make sure adding another system does not create another isolated source of data and another layer of operational work.

This is ultimately a margin issue, not just a technology issue. When integrations are repeatable, implementations require less custom work and customers can expand without forcing the company to solve the same technical problems again.

3. Turn customer success into a revenue engine

Customer success is often viewed primarily as a retention function. I think founders should also ask a different question: What expertise is the company already providing after the sale that customers would value as an ongoing service?

Customer-facing teams have a particularly useful vantage point. They see where customers struggle, which workflows consume the most time and which problems continue after implementation. Those insights can reveal opportunities for new services, product improvements and expansion.

The first step is to identify recurring work that produces a clear customer outcome. Depending on the business, that might include monitoring, optimization, reviews, training or proactive support.

Then make the offering repeatable. Define what customers receive, how frequently the service is delivered and how success will be measured. Avoid vague promises or outcomes you cannot substantiate. Build measurement into the service so customers can evaluate the value themselves.

Customer success teams can also help expansion happen more naturally. When customers have simple ways to understand and communicate the results they are seeing, it becomes easier for them to make the case for expanding the relationship internally.

The broader lesson is that customer success should not only solve problems after the sale. Done thoughtfully, it can help identify what customers value enough to keep buying.

The bottom line

When growth slows, protecting margins does not have to mean indiscriminate cost cutting. One of the most valuable things founders can do is examine the cost of growth itself.

Make successful processes repeatable. Remove technical friction before it multiplies. Look for recurring value in the work your teams are already doing for customers.

The companies that do this well do not simply spend less. They build businesses in which each new customer becomes easier to serve than the last.

Key Takeaways

  • When growth becomes harder to predict, the answer is not always blunt cost-cutting.
  • Founders can improve the economics of growth by reducing variation, removing integration friction and turning customer success into a source of recurring value.

When revenue growth becomes harder to predict, cost discipline matters more. But as the founder of ButterflyMX, I’ve learned that the most durable opportunities do not always come from cutting headcount or delaying investments. They often come from reducing the cost and complexity of growth itself.

I see this clearly in proptech, where scaling can involve hardware, software, onsite deployments, integrations and ongoing customer support. But the underlying lesson applies to many businesses: Growth gets expensive when every new customer requires you to reinvent how the company operates.

Here are three ways founders can make growth more repeatable and protect margins in the process.


Source link

3 Ways to Protect Your Margins When Growth Slows Read More »

Larry Ellison Quietly Spent  Million on Homes for His Staff

Larry Ellison Quietly Spent $10 Million on Homes for His Staff


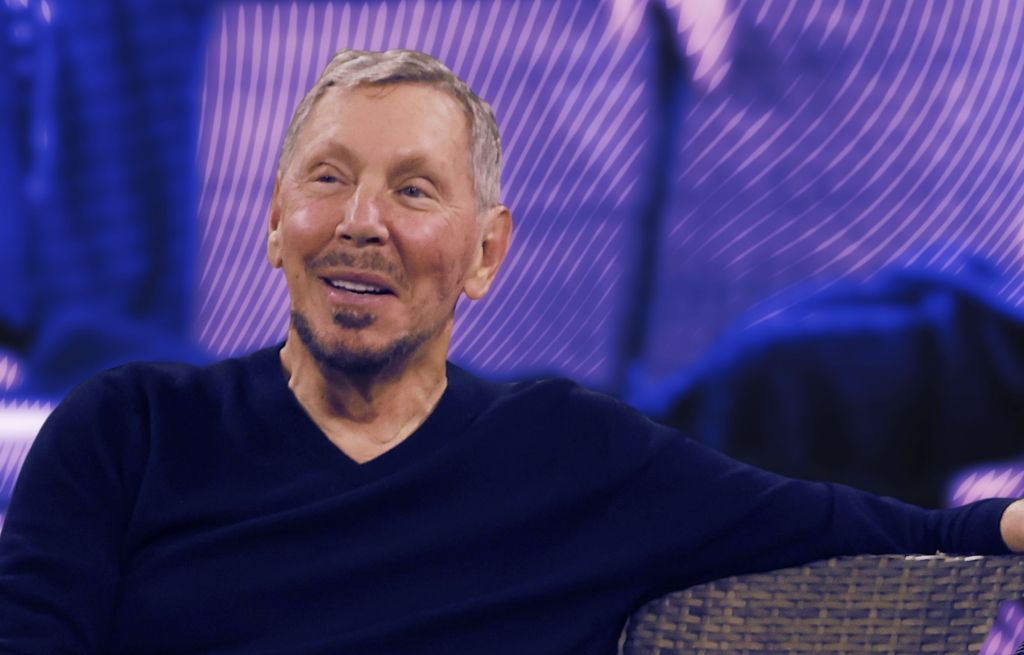
Billionaire Larry Ellison, 82, has a $173 million oceanfront compound in Manalapan, Florida. About 30 minutes away, he owns eight more homes. They’re all for his family’s staff, including tutors for some of the five young children he shares with his wife, Jolin.

The purchase was shrouded in secrecy. In 2023, an LLC bought the houses in Palm Meadows Estates, a gated community in Boynton Beach, for almost $10 million, The Wall Street Journal reports. Nosy neighbors guessed it was Mark Zuckerberg or Elon Musk. Even the local agent who helped line up the deals didn’t know who the mystery buyer was until Ellison arrived to tour the homes, flanked by bodyguards.

The real estate grab is part of a larger trend among the ultrarich to buy up housing for their employees. It helps them recruit top talent in pricey markets while keeping staff close enough to help, far enough to stay out of the way. “Investing in lodging can be a very smart decision,” said Peter Mahler of Mahler Private Staffing.


Source link

Larry Ellison Quietly Spent $10 Million on Homes for His Staff Read More »

Company Helps People Find Over 0M Hidden at Home: Unvault

Company Helps People Find Over $150M Hidden at Home: Unvault


Key Takeaways

  • After graduating with her MBA, Singhvi wanted to tap into a $750 billion business opportunity.
  • She co-founded Unvault, which allows users to track the value of their jewelry and sell it, in 2025.
  • Now, she looks forward to listening to her customers and introducing more in-demand features.

In India’s gemstone hub Jaipur, where Nidhi Singhvi grew up, gold jewelry is a family heirloom passed through generations, and it’s always considered when calculating someone’s net worth, she tells Entrepreneur. 

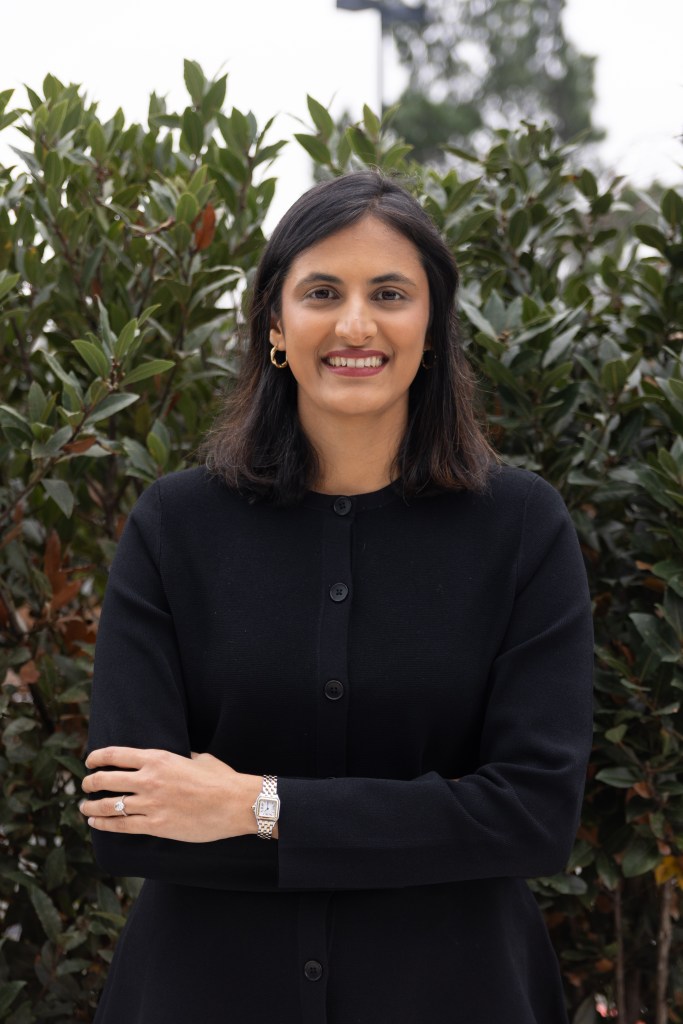
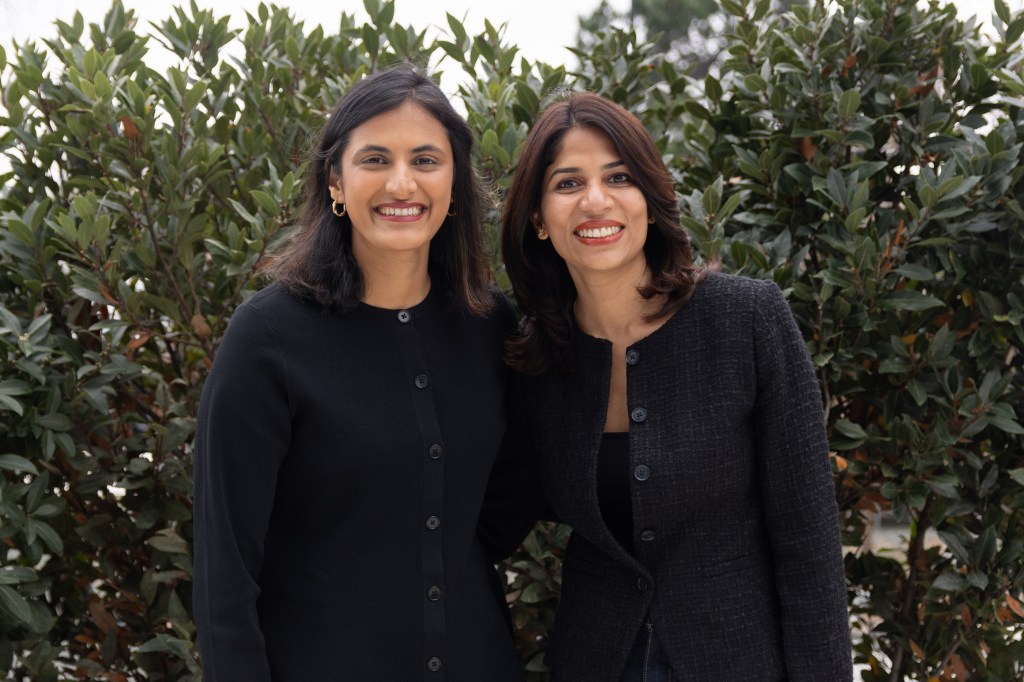
Image Credit: Courtesy of Unvault. Co-founders Nidhi Singhvi, left, and Navya Reddy, right.

However, when Singhvi moved to the U.S. about 14 years ago, she noticed a very different attitude toward the asset. 

“ Jewelry was always done stupidly,” Singhvi says. “It’s so marked up when you buy it, and if you want to sell it, like a broken chain or earring, your infrastructure is a pawn shop or a local jeweler.”

The wheels were turning as Singhvi graduated from The Wharton School with her MBA and launched her career. She focused on currency investing at a hedge fund, then built an options trading desk at a crypto brokerage. 

But Singhvi’s interest in the jewelry business never waned. “Gold is the OG asset class,” she says.

So, in 2024, she co-founded Sonalore, a company offering 18-karat gold jewelry with a lifetime buyback guarantee, with fellow Wharton graduate Navya Reddy. 

But it wasn’t long before Sonalore’s customers came back with a frequent request: They already owned a lot of jewelry, but they didn’t know how much it was worth — could Singhvi and Reddy help with that? 

“The way the customers pushed us was the revelation there,” Singhvi says. “They know it’s an investment. Ask any woman. She treats her jewelry differently than everything else. But what’s the value of it? For an asset to be a true asset, you need to know the value of it.”

Image Credit: Unvault

Co-founding Unvault to unlock $750 billion in assets

Singhvi and Reddy immediately pivoted to meet customer demand. The co-founders launched Unvault, a financial platform for personal gold, the “$750 billion asset class hiding in plain sight,” in Palo Alto, California in June 2025.

By October of that year, Singhvi and Reddy had leveraged AI to build their platform’s first valuation app. 

Not having raised money at the time was a significant advantage, as it motivated them to become AI natives and “use everything that was available on the AI front,” Singhvi notes. 

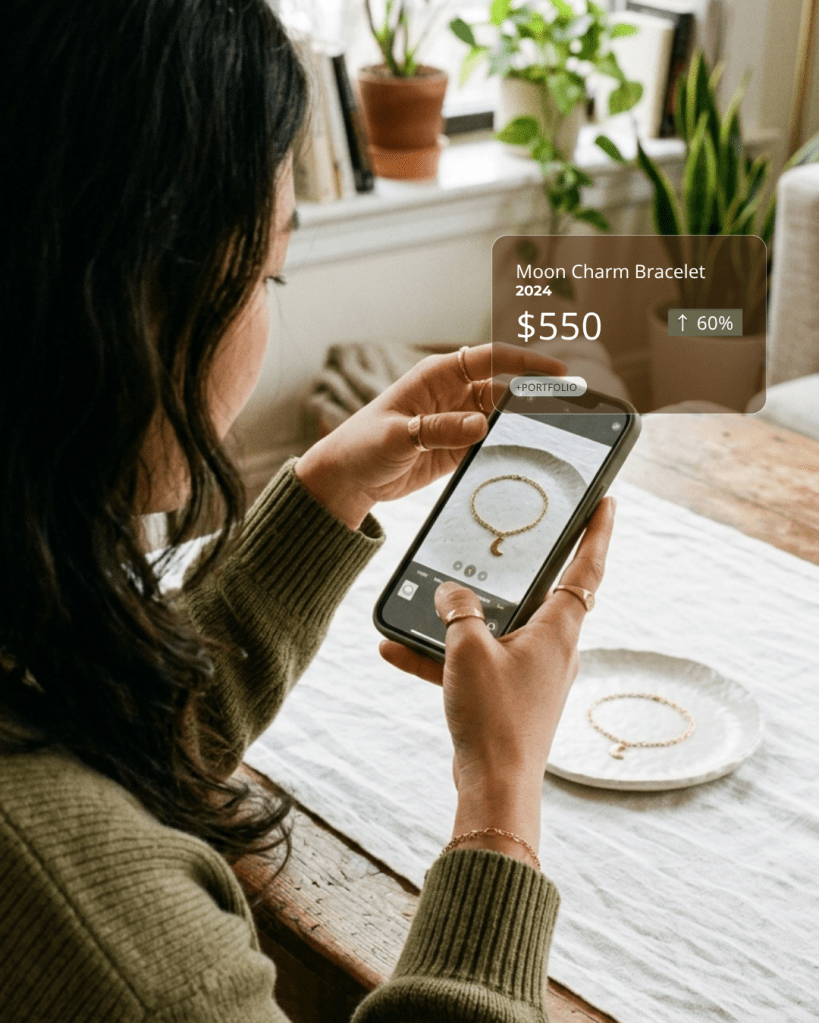
Unvault’s app took photos of customers’ jewelry and used volumetric data to estimate value. 

“We used all our training from being in jewelry for a year already to make that assessment better,” Singhvi explains. “Even though at that time we were using frontier [AI] models, we still used our layer of understanding of jewelry to give better results. And that took off.” 

Customer requests lead to the option to sell jewelery

Customers soon expressed a desire to sell their jewelry on the platform, so Unvault added the option within the same month of launch. The company opened a PO box to receive the items in Palo Alto. “People were shipping thousands of dollars of jewelry to us,” Singhvi recalls. And she would drive there herself to pick the pieces up. 

“We built Unvault for knowing the value and for tracking the value,” Singhvi says. “But the selling was a use case that customers gave it.” 

Fostering transparency has been key within that selling component too, Singhvi notes. Unvault provides video throughout the whole process to keep customers informed at every step, from opening the box of jewelry to testing gold in the X-ray machine. 

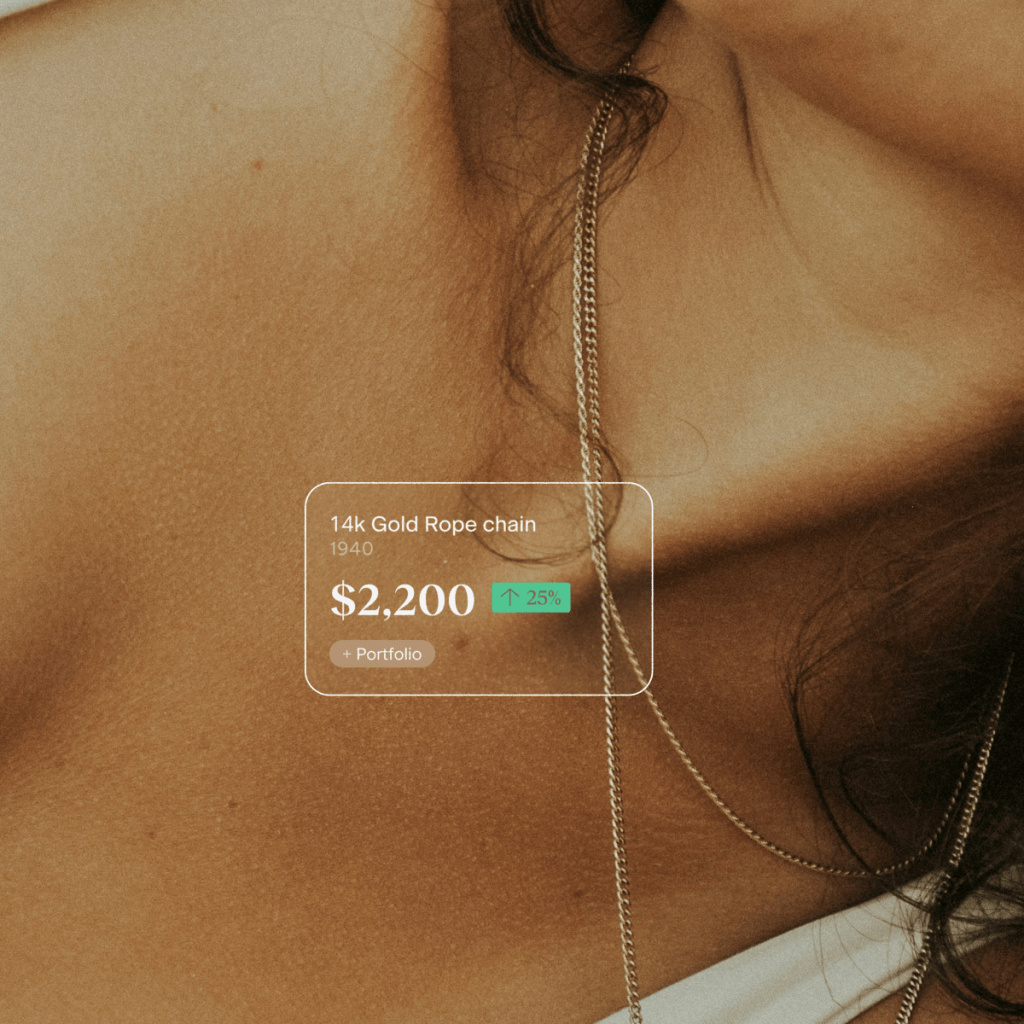
“So it will tell you exactly, it’s 17.34-karat gold,” Singhvi says. “Then we will give you a complete breakdown. So it’s not one number for a bunch of your jewelry items. It’ll be a number for every single item, and then the fees are broken down as well.” 

Image Credit: Unvault

Navigating Silicon Valley investors who want $1 trillion

Despite the early customer interest, when it came time to raise money from Silicon Valley investors, the co-founders faced some pushback. 

“ Everyone wants to back a trillion-dollar company,” Singhvi says. “They want to back Anthropic, and I understand it. If I am making that decision, I want to do that as well. So there’s definitely some of that. They’re like, ‘Oh, gold jewelry, can you be $1 trillion?’”

For example, one investor told Singhvi that women don’t wear jewelry. He explained that his wife just wears a few pieces: earrings, a ring and a bracelet. 

“By the way, that’s a few thousand dollars right there,” Singhvi says. “But women do have jewelry. Jewelry predates agriculture. It has taken a lot of different forms, but there is an industry that is working, and you are a participant in it whether you like it or not.” 

The good news, according to Singhvi? As long as there’s a customer to prove the market, it’s only a matter of time before investors respond. Unvault had that customer from the start  — asking the question that led to the company’s very existence.  

“VCs are very good at [smelling] customer traction,” Singhvi says. “Everyone that partnered with us [did so] once we started getting customer traction, once they started seeing that curve go up.”

Image Credit: Unvault

Unvault saw its first $1 million of assets tracked in 27 days, then crossed the $2 million milestone in five. By the time the company began fundraising, it boasted $5 million of assets logged. 

Unvault most recently raised early-stage capital in June 2026. The amount hasn’t yet been disclosed.

To date, the company’s helped users unlock more than $150 million in assets.

The importance of customer feedback at every stage

Singhvi and Reddy have continued to solicit customer feedback wherever possible (they’ve even placed golden eggs in Dolores Park to catch attention and collect opinions), cognizant of just how valuable it’s been at every stage of Unvault’s journey. 

Not only does it boost their confidence in their offering, but it keeps them agile enough to fulfill the next customer request. 

Now, those customers are asking for the option to track inherited assets and expand beyond jewelry to include items like silverware or other collectibles. Older generations will pass down $93 trillion in assets to their heirs in the next two decades, Bloomberg reported.

Singhvi looks forward to building out Unvault’s inheritance feature and continuing to listen to its customers. And she suggests any entrepreneur who wants to be successful do the same.  

“ Whatever way you can get customer feedback, and customer feedback at some scale, is great,” Singhvi says. “That will just help building the product, help you be a better founder, and then also help you raise money eventually.”

Key Takeaways

  • After graduating with her MBA, Singhvi wanted to tap into a $750 billion business opportunity.
  • She co-founded Unvault, which allows users to track the value of their jewelry and sell it, in 2025.
  • Now, she looks forward to listening to her customers and introducing more in-demand features.

In India’s gemstone hub Jaipur, where Nidhi Singhvi grew up, gold jewelry is a family heirloom passed through generations, and it’s always considered when calculating someone’s net worth, she tells Entrepreneur. 

Image Credit: Courtesy of Unvault. Co-founders Nidhi Singhvi, left, and Navya Reddy, right.

However, when Singhvi moved to the U.S. about 14 years ago, she noticed a very different attitude toward the asset. 

“ Jewelry was always done stupidly,” Singhvi says. “It’s so marked up when you buy it, and if you want to sell it, like a broken chain or earring, your infrastructure is a pawn shop or a local jeweler.”


Source link

Company Helps People Find Over $150M Hidden at Home: Unvault Read More »

The Skill Behind Every Successful Career Pivot — and How to Build It

The Skill Behind Every Successful Career Pivot — and How to Build It


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Practice, don’t just read. Certification exams test judgment in realistic scenarios, so work through every practice question you can find and study the ones you get wrong.
  • Put it on your calendar. “No time” is a decision, not a scheduling problem. Block a specific, recurring time to study; even 20 focused minutes a day adds up

If there’s one thing I know how to do, it’s fail. It took me three tries to pass a career-defining certification, and only then did I understand that failing was part of how I’d learn the right way.

The material for my Certified in Planning and Inventory Management credential was right in front of me. The problem wasn’t effort; it was method. The flashcard-to-recall routine that works for so many people simply wasn’t helping my brain hold on to the information. That set me on a path to relearn how to learn, and what I found has shaped everything since, from earning corporate credentials to building Pocket Prep from scratch.

It comes down to a foundation and three habits: a reason to care, repeated exposure, and application.

Start with the foundation

If you want to pivot your career or reskill fast, the tactics matter less than the base they sit on. For me, two “parent skills” made every new subject easier to pick up: organization and communication.

My guiding question is always the same: what’s the 20% of effort that drives 80% of the results? Organization and communication are that 20%. Get them right first, and everything you learn afterward compounds faster.

Find a reason to care

Most of us were taught to learn the same way. We’re all born unique, then shuffled into classrooms and expected to conform: sit still, be quiet, learn what you’re told. I was one of many undiagnosed ADHD kids who would rather stare out the window or crack jokes than follow along in the textbook.

What was missing was a personal layer, something that made the material click. For me, that turned out to be stories: the “why” behind the facts.

In college, I studied a hypothetical case about a factory worker who finds bugs in a vat of ice cream. He’s told the contamination level is legally acceptable and instructed to keep processing the batch. Decades later, I can still picture his guilt as he imagines kids happily eating that ice cream on a summer day.

I don’t remember most of what I memorized that semester. I remember that. Information sticks when you have a reason to care about it, not just a reason to memorize it.

Learn, forget, learn, remember

My aikido instructor used to say, “Learn, forget, learn, forge, learn, remember.” She was consoling me when I couldn’t recall the next move, but she was also describing how memory works. You learn a concept, forget most of it, then rediscover it in an “oh, yeah” moment. Each return makes it easier to recall the next time.

That idea is why mobile became so central to our learning tools. Before smartphones, studying had to be deliberate: pick up the book, mark the chapter, make the flashcards. Now people study in the margins of their day, waiting in line for coffee, riding the bus, sitting in the school pickup line. Five to ten minutes, maybe seven to ten practice questions at a time.

That’s not a compromise. Short, repeated exposure beats a long cramming session, because forgetting and re-encountering material is how the brain strengthens recall. It’s also what makes a flow state possible when the stakes are high and the clock is running.

Prove it by applying it

Here’s the hard truth: passing an exam or finishing a course proves you consumed the right knowledge. It doesn’t change your title. Applying it does.

Even if you pursued a certification to change your professional identity, your boss and your customers won’t care that you passed. A credential sets you up to become a better professional; it doesn’t make you one. What people notice is what you do with it.

So ask yourself: after I learn this, who will notice a difference in how I work? If the answer is no one, you were consuming, not learning.

Have 20 minutes? Start here.

Carving out 20 minutes a day is already a win. Use it to get curious about career paths and skills you didn’t know would interest you.

  • Explore before you commit. Don’t enroll in or buy anything yet. Use small pockets of time to explore, not grind.
  • Understand the destination first. Learn what the new role or skill actually requires, and decide whether it’s worth it to you before committing to the process.
  • Check your foundation. Ask honestly whether your organization and communication skills can support learning fast.
  • Protect “sacred time.” Keep one unscheduled block that’s yours no matter what the calendar says. I wake up at 6:30 every day, weekends included (my body can’t tell the difference), to reflect, prioritize, and read, with plenty of coffee.

Then confront the three stories that stall most mid-career pivots:

  • “I don’t have time.” You have 20 minutes. That’s enough to start.
  • “I don’t know if I can.” That’s what exploring is for. You don’t have to know yet.
  • “I don’t know if it’s worth it.” That’s why you study the destination before committing to the path.

There’s no wrong path. But if you keep telling yourself any of these stories, you’ll prove yourself right.

The real advantage: knowing how you learn

Career pivots used to be a once-a-decade decision. Now they’re a recurring requirement, especially for founders adapting to market shifts every quarter.

The entrepreneurs who move fastest won’t be the ones who know the most. They’ll be the ones who’ve built a system for learning under pressure: a strong foundation of organization and communication, a reason to care about what they’re studying, and the discipline to return to it in short bursts instead of waiting for a free weekend that never comes.

While AI is a factor in this shift, it’s not replacing the need to learn. It’s adding an incredible personalization layer on how to do it, making it easier to find the right pace or entry point into something new. That access won’t stay this cheap or this simple forever – learn how you learn, while the tools to accelerate it still are.

Key Takeaways

  • Practice, don’t just read. Certification exams test judgment in realistic scenarios, so work through every practice question you can find and study the ones you get wrong.
  • Put it on your calendar. “No time” is a decision, not a scheduling problem. Block a specific, recurring time to study; even 20 focused minutes a day adds up

If there’s one thing I know how to do, it’s fail. It took me three tries to pass a career-defining certification, and only then did I understand that failing was part of how I’d learn the right way.

The material for my Certified in Planning and Inventory Management credential was right in front of me. The problem wasn’t effort; it was method. The flashcard-to-recall routine that works for so many people simply wasn’t helping my brain hold on to the information. That set me on a path to relearn how to learn, and what I found has shaped everything since, from earning corporate credentials to building Pocket Prep from scratch.

It comes down to a foundation and three habits: a reason to care, repeated exposure, and application.


Source link

The Skill Behind Every Successful Career Pivot — and How to Build It Read More »

How We Built a .6B Company in an Uncharted Industry

How We Built a $3.6B Company in an Uncharted Industry


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Balance experimentation with the reliability of your core offering, and establish a strong patenting system early on.
  • Build for compliance and perform know-your-customer checks from the get-go, and push the whole industry toward self-regulation.
  • Understand that fiscal discipline beats early funding. Being fiscally responsible allows you to raise funds only when you can do so on your own terms.

A few months ago, Oxylabs landed a $130 million investment from Warburg Pincus, pushing our valuation to $3.6 billion — the highest ever recorded in the public web data sector, and our first outside capital in more than a decade of doing business.

Back in 2015, when Oxylabs was launched, few had heard about automated web data access as a separate industry, and even fewer understood the underlying technology. There was no rulebook to follow, no regulatory framework that clearly applied and no seasoned executives to consult on intractable problems. 

Technology develops fast, and today there are plenty of similar avenues for innovation and companies carving out their own niche. So here are simple but hard-won lessons for everyone trying to build a category-defining company in an emerging, stormy industry.

Balance experimentation with the reliability of the core offering

Succeeding in a new industry requires a two-fold approach — frequent, bold experimentation and a dependable core product. To figure out what works, you need to be willing to try many different things, many of which will fail. But you can only afford some turbulence and freedom to experiment if the value of your core offering is unshakeable.

Customers will understand a few misfires, especially if you are building on top of novel solutions. But competitors can pop up just as quickly as client patience runs out when workflows or data pipelines break and cause significant downtime.

Establish a strong patenting system early

Experimenting and innovating is something you must do to claim your place in an emerging industry. Just as important is setting up a patenting system as early as possible. Next to your ingenious engineers, you need capable lawyers who will make their work worth that much more. Proprietary knowledge that no one cares about today will be priceless when everyone else starts to notice the opportunity in your sector. 

Beyond the legal protection, a proactive approach to patents forces your team to articulate exactly what’s proprietary and defensible about their approach in the first place. That clarity, in turn, helps you build a strategy to pre-empt — or at least soften — any disputes that arise later on.

Build for compliance and KYC before anyone’s checking

It might be tempting to treat the absence of clear regulation as an absence of responsibility. Prioritizing growth, revenue and competitive edge makes sense for an emerging company in an unclaimed industry. But if you are in for the long run, act like it from the get-go. Rigorous know-your-customer checks, use-case vetting and data protection should become part of your company’s culture from day one, even when it means turning away opportunities or moving slower than less scrupulous competitors. 

Trust built this way compounds over time. It gives credibility to attract investors and a solid backbone to pass due diligence. Importantly, if you are in an industry no one understands, and many assume it is shady, audits or regulatory inquiries will come without you doing anything wrong. Prejudice is only overcome by proof of responsible conduct. 

Push the whole industry toward self-regulation

A company can only outrun its industry’s reputation for so long. When shady players shape how regulators, the media and the public view a new category, every honest business in that category ends up paying for it. That’s why it often falls to the more responsible players to work together and lead the way. Joining or starting industry associations that set and promote common standards, and that certify companies willing to be held to them, is something companies can do without waiting for outside regulation.

In the web data industry, no such body existed until a group of companies came together to launch the Ethical Web Data Collection Initiative. It’s hard to build trust in your own business if the entire category is seen as untrustworthy, so investing in your industry’s credibility is one of the most impactful things a leader in the field can do.

Fiscal discipline beats early funding

Growing at a pace your infrastructure and compliance standards can support takes real discipline. Enticing offers might come early on. Capital investment early on gives you a head start, resources and time in the sun. But it can also become a burden.

Being fiscally responsible lets you raise funds only when you can do so on your own terms. Similarly, while acquiring a competitor has the appeal of a power move, it doesn’t necessarily make sense in current market conditions. Don’t buy just to demonstrate growth and attract investor attention. Buy to expand your market presence and product offering, and the investors will come to you.

Summing up

Building without a map is hard — failure lurks around any corner, and success is hard to envision, let alone reach. But being among the first also means you have plenty of room where you can build. And you get to help set the terms for how your industry operates and in what light it is judged. That kind of foundational work pays off down the line.

Key Takeaways

  • Balance experimentation with the reliability of your core offering, and establish a strong patenting system early on.
  • Build for compliance and perform know-your-customer checks from the get-go, and push the whole industry toward self-regulation.
  • Understand that fiscal discipline beats early funding. Being fiscally responsible allows you to raise funds only when you can do so on your own terms.

A few months ago, Oxylabs landed a $130 million investment from Warburg Pincus, pushing our valuation to $3.6 billion — the highest ever recorded in the public web data sector, and our first outside capital in more than a decade of doing business.

Back in 2015, when Oxylabs was launched, few had heard about automated web data access as a separate industry, and even fewer understood the underlying technology. There was no rulebook to follow, no regulatory framework that clearly applied and no seasoned executives to consult on intractable problems. 

Technology develops fast, and today there are plenty of similar avenues for innovation and companies carving out their own niche. So here are simple but hard-won lessons for everyone trying to build a category-defining company in an emerging, stormy industry.


Source link

How We Built a $3.6B Company in an Uncharted Industry Read More »