October 2026

3 Paid-Off Rentals: The “Boring” (But Proven) Path to Financial Freedom

3 Paid-Off Rentals: The “Boring” (But Proven) Path to Financial Freedom


Financial freedom with three rental properties? It almost sounds too easy, but it’s reality for today’s guest, who went from making roughly $11 an hour to having more than enough cash flow to live on.

With a little hard work and discipline, Lucas Teague saved $10,000 to buy his very first rental property. He made several offers and heard plenty of “nos.” But he only needed one “yes.” And that first yes changed everything.

Lucas repeated the process: buy a “cheap” property, live in it, fix it up, and make tens of thousands of dollars. But instead of racing to build a massive real estate portfolio, Lucas settled on three rentals and started paying them off.

Now he’s almost completely debt-free and earns enough rental income to cover his family’s expenses and then some. Lucas has all that he needs. Now, he’s focused on a new objective: giving back. In this episode, he’s sharing an unconventional but proven path to financial freedom so YOU can do the same.

Henry:
Financial freedom with just three rental properties? It almost sounds too easy, but it’s reality for today’s guest who went from making roughly $11 an hour to having more than enough cashflow to live on. With a little hard work and discipline, Lucas Teague saved $10,000 to buy his very first rental property. He made several offers and heard several nos, but he only needed that one yes. And that first yes changed everything. Lucas repeated this process, buy a cheap property, live in it, fix it up, and make tens of thousands of dollars. But instead of racing to build some massive portfolio, Lucas settled on just three rentals and started paying them off. Now, he’s almost completely debt-free, living in his dream home, and he earns enough rental income to cover his family’s expenses and then some. Lucas has all that he needs. Now he’s focused on a new objective, giving back.
In this episode, he’s sharing his unconventional but proven path to financial freedom so you can do the same. What’s going on everybody? I am Henry Washington, co-host of the BiggerPockets Podcast. And today we have an investor story with Lucas Teague from Indiana, so let’s bring him on. Lucas Teague, welcome to the BiggerPockets Podcast, my friend.

Lucas:
Yeah, thanks Anneria. I’ve been watching this show for probably 10 years now and it’s an honor to be here.

Henry:
Why don’t you give us a little bit of background. What got you into real estate in the first place and when did you get started?

Lucas:
I’m in my early 30s now. I’ve been investing in real estate for about 14 years. And really, I think it boils down to financial freedom. As a kid, I had a parent who lost their job after working for a place for about 30 years and just all of a sudden they came home one day and didn’t have a job. I was probably 15 or 16 and after that I made the decision I’ve got to prevent that if at all possible.

Henry:
How did that turn into real estate being the source for that extra income?

Lucas:
Yeah, so I’ve always had the mathematical lens. And so I looked at, “Hey, can I buy a business?” And this is at 18 years old, so it’s zero capital at the time. Well, with no money, it’s a little bit difficult to buy a business. So then I turned to, okay, what if I invest in some stocks? Well, once I get to $2 million in stocks, maybe I can make 60 to $80,000 a year, but it’s going to take me about a hundred years to get to two million at the money I was making at 18. So I moved on to the next thing, which was real estate. And in my area at the time, there were houses selling for 20 or $30,000 and you could rent those out for three or $400 a month. And I’m crunching the numbers and man, I could do something within a decade probably or five to 10 years and get the tax benefits and all of the other benefits that come with real estate investing.
And it seemed like a no-brainer.

Henry:
So what year was this when you’ve had this epiphany?

Lucas:
Yeah, this was probably 2012. So I graduated high school in May of 2012, and I worked in the pharmaceutical industry at the time, and I still do today. I work for Eli Lilly, the largest pharmaceutical company in the world. So I do that. And then I’m also a real estate agent, but at the time I made about 11.95 an hour. And so my first year was essentially just saving up $10,000 for that either down payment or that first house that I purchased later in 2013.

Henry:
Okay. Well, that’s some good bit of background. You bought that first property in 2013. What’d that deal look like?

Lucas:
Yeah, so this was a HUD foreclosure and it was listed on hud.gov on an auction website for about $50,000. And my poor realtor friend, we spent probably a month, we’d submit our offer on the auction website, we’d wait a week, it would get declined. And so it was listed at 50,000. We started at 6,000, then 7,000, then 8,000. And after about a month of doing that, the bank or whoever owned the house on the auction website, they finally accepted the offer of $8,000. So at the time I had about $10,000 in cash and I went for it. So I figured, hey, for $8,000, what could go wrong?

Henry:
That’s an uncomfortable offer. They’re asking 50, you’re offering a couple grand to start out. What helped you just start making uncomfortable offers? Because that’s a big hill to climb for a lot of investors.

Lucas:
I try to look at it with a non-emotional lens. In this instance, it was a bank that owned the property. I’m probably not going to hurt anybody’s feelings if I submit a low offer. Even if it’s a person who owns the property, really, you shouldn’t hurt their feelings if you’re offering something low. We deal with this, especially now being a real estate agent, an offer is better than no offer at all. They can say no and then move along and that’s better than not hearing anything.

Henry:
If you’re listening to this and you’re like, “I don’t know what to do to get my next deal,” go open the MLS and find a bunch of houses that are for sale that are in your buy box. Who cares what they’re listed for? And make an offer that makes sense to you. Worst case scenario is they say no. Best case scenario is they say, “I don’t want that offer, but let’s talk about it.” That’s why an offer is better than no offer, no matter what it is, because you’re basically saying, “Hey, I’m willing to have a conversation about this.” So you did that first deal in 2013, you bought a house for $8,000. That sounds to me like you didn’t buy much house, so tell us about it. What’d you do with it? Do you still have it? How did it work out?

Lucas:
No, so I sold that after about a year of owning it. I put about $2,600 into that house, did all of the work myself, watching YouTube videos and the bones of the house were good. It was really cosmetic. It needed paint, it needed some flooring, some kitchen stuff. And so I worked on that for about a year and sold that in early 2014 for about 60,000. So I had about a $50,000 profit on that place.

Henry:
What goes through your mind after that? Because I think a lot of investors get to this point where it’s like, “All right, I did a deal, but what do I do now?”

Lucas:
Well, I think I said earlier at the time I made 11.95 an hour, which I thought was a ton of money and I was hourly. And within a year I had just made 50,000. And if I worked on that full-time for a year, that’s $25 an hour, which was double what I was making for my W-2 job at the time. And my mind was completely blown that you could do this and make… It was essentially part-time, a few hours a week. I worked on that property for a year and I could make double what I made at my W-2 job. So thankfully I had a good experience on the first property and yeah, I think that I got the bug after that and I kept looking and quickly transacted again shortly after that.

Henry:
So what did the next one look like? How’d you find that one?

Lucas:
The next one was probably 30 minutes northwest of where I live, and it was a triplex that was for sale for about $45,000. I had enough work experience at the time to actually apply for financing and get financing on this place. Unfortunately, this is where I learned a lot of lessons. The house was about 150 years old. It had two vacant units in it. It had one unit where somebody was living there, but they weren’t paying any rent in there. So I had to go through an eviction and get those folks out of that apartment. Essentially, I just moved into each one of the apartments. I’d lived there for three to four months. I would renovate everything. I’d move into the next unit that’s available, get that previous unit rented out and did that for about a year as well and sold that in 2015.

Henry:
Okay. So you paid about $45,000. How much money do you think you spent fixing up the entire property?

Lucas:
I would say between five and 6,000. Structurally, the house was in good shape. It was more of a cosmetic rehab, flooring, paint, that kind of stuff. So probably 5,500, I would say.

Henry:
Okay. And what were you renting the units out for?

Lucas:
Previously, they were rented for probably 400 before I had to do the eviction. Once I remodeled everything, I moved those up to about 700. So once it was completely turned over, the property brought in about 2,100 a month.

Henry:
2,100 a month on a note of where you’re only paying 45,000. That’s a crap ton of cash flow. That’s amazing. But then you said you sold it, so why sell instead of keep the cash flow? I

Lucas:
Was still 19 or 20 at the time, and it was not in the best location. So the area had some extracurricular activities kind of going on in the area and not the type of tenants that I wanted to have long term. And so it was quite a bit of headache and stuff, but I was doing the math. So I listed the property for 100,000. I got a full price offer on it. And so at the time, having the capital at 19 or 20 years old meant a lot more to me than making the $2,100 a month.

Henry:
I know people are listening to this and going, “This was so long ago. The numbers don’t work like that anymore.” Now you can’t pay the same price points you were paying then, but there are deals that you can still get at a discount and you can still rent and get current cash flow. And what I want people to focus on is not necessarily what the dollars were for the purchase price, but look at the spreads and understand the concepts of what Lucas was doing. This stuff still works. You can absolutely still go buy a single family home, live in it while you renovate it, and then sell it for a profit when you’re done and not have to pay capital gains taxes because you lived in the property, especially if you lived there for two years. If you lived there less than two years, you’re going to pay some capital gains, right?
You can absolutely go and find yourself a triplex and live in a unit, renovate it while you’re living in it, move to the next one, renovate it while you’re living in it, rent it out and then sell it when you’re done or keep it as a rental when you’re done. Those strategies worked then. They still work now. The dollar signs are bigger now, yes. But also the purchase prices are bigger, but so are the rents and so are the sale prices, right? So these strategies still work and the way you use to find these deals still works. There are bank-owned properties again, guys. That died off for a while, but a lot of them are back. People are getting foreclosed on and banks are sitting on some properties. You can absolutely go bid on foreclosures. There are opportunities on the market if you’re willing to make offers that make sense to you.
You’ll have to make a lot of them, but conceptually what Lucas did is very much still possible in today’s environment. Is it going to be a little more challenging? Yes. Will it be more expensive? Yes. But it can also be more profitable if you do it properly. So thank you so much for sharing some of those lessons and being transparent with it. I want to learn more about what you continued to do after that second deal, because now you’ve done a live-in flip as a single, you’ve done a live-in flip technically as a triplex. You’ve gotten a taste of that. I’m curious, did you continue down the same path or did you transition to something different? But we’ll get into that right after the break.

Speaker 3:
Before we go to break, if you’re someone who’s bought a couple of deals and you’re looking to scale up your portfolio into something bigger, I have a really exciting announcement for you. BiggerPockets is hosting its first ever conference focused just on scaling up. It’s this December. It’s coming up soon, this December, 5th through 7th in Phoenix, Arizona. We’re going to have a full day of programming with speakers like myself, James Daynard, Kathy Fecke, and Devon Kinard talking about how to scale up and build a sustainable business. Tickets are on sale now, but there are only 100 tickets, so go to biggerpockets.com/conferences now and get your ticket today.

Henry:
Welcome back to the BiggerPockets Podcast. I am here with investor Lucas Teague, and he has been sharing his real estate investment journey. He started back in 2013, bought a single family, lived in it, renovated it, sold it, moved on to a triplex, and the concepts for the way he did this are absolutely still possible today. So I’m curious, Lucas, what did you transition to after that? Did you stay the course on what you were doing, live in flips, or is there some other strategy you tried?

Lucas:
Now to some extent, yes. I took a two-pronged approach at this point. So I needed a place to live, obviously. I had sold the place that I was living. So I bought a primary residence for myself and same pattern as the first two. The house had good bones. It was a cosmetic flip where I didn’t want my family to come over for Christmas, but it was very livable. And so I did that on nights and weekends as I was working my W-2 job. And at the same time, I started looking for… I wanted to be in the long-term rental business, which is what I’m in today. So in my area, I’m shooting for a 15% cash on cash return. So I’m starting to look for these properties, and maybe that’s once a year, maybe that’s one property every three years. And so probably around 2017, 2018, I began to buy these 15% cash-on-cash return long-term rentals and simultaneously working on the house that I was living in, shooting for that two-year turnaround time, that way I could avoid capital gains taxes and do both simultaneously.

Henry:
What I like about your strategy is what makes it possible is you said you had a goal of 15% cash on cash return. That was the goal. So that was the thing that was important. Not volume of deals, but deals that meet your very specific criteria. And whether that meant one deal a year or one deal every three years, that wasn’t what was important. What was important was that the deal met your criteria. That discipline is exactly what makes investors successful in a down market like we’re in now. And what makes that kind of strategy possible is because you had a day job, right? You had active income from going to work every day. And so I know a lot of people are listening to this podcast because they want to retire from their day job. There’s absolutely a path to do that. It takes longer now than it used to, but yes, you can do that.
But there’s also still a path that builds wealth. If you have a job you like or a job that you enjoy, you don’t have to focus on quitting your job, but the benefit of not having to quit your job allows you to have the discipline to have a strategy like this, to be able to say, “Hey, I want 15% cash on cash return. Maybe that sounds wild, but the deals are out there and if I got to buy one deal every three years to get it, then that’s what I’ll do because I have a job that’s bringing in the income.” So you were looking for this 15% cash on cash return type deals. How long did it take you to find one?

Lucas:
Really not long. Again, I’m a mathematical focused person, and so I found ways to export the entire MLS into an Excel spreadsheet, use Excel to calculate cash on cash return for thousands of properties simultaneously. That’s still something today that I do as a real estate agent, just make analyzing properties so much faster. And so maybe took me a year and the first one was a house listed at 150. I offered 110 thinking we would negotiate and hey, they accepted 110. We still have that property today and it’s way under rented. It’s 1350 a month, but still off 110,000, it’s well above the 1% rule.

Henry:
That’s super cool too. So you basically made a spreadsheet that told you what price to offer for all these properties in order for it to hit your number. Did you just go down the list, pick your favorites and start making offers?

Lucas:
Yeah. I would just sort the column by, “Hey, what’s the highest cash on cash return that’s on the market currently?” And of course some are going to come up 20, 25% cash on cash return. You look at the pictures and it needs a complete gut. But it gives you a list to look at where you’re not looking at thousands of properties, you’re looking at five or 10 and spending your time focusing on the ones that are most likely to work for

Henry:
You.This strategy’s so much easier now with AI. Literally anyone can do this now. You can scrape the MLS or have your agent send you a bunch of listings and then you can just have AI put it into a spreadsheet, use some basic rental knowledge on what you think the rents would be and calculate cash on cash return for all the deals that are on the market and have it literally tell you this is the price you would need to pay for this to work and you could just start submitting offers. You can do this today.

Lucas:
Yeah. So speaking of AI, I’ve built a tool as well that will analyze the micro environment of your specific town and neighborhood. I live in a city with 5,000 people and you can even specifically target neighborhoods and everything like that now with AI.

Henry:
Okay. Tell me what that means though for normal people talk. What does the tool do?

Lucas:
That means now you can analyze news articles, anything that would affect the market value in your specific town, and then maybe there’s specific news where something, a new business is going to go in close to a specific neighborhood. And so you know over the next five years it’s going to increase 15% or 20% in that neighborhood. Now you can find those 15% cash on cash returns in that neighborhood and get the appreciation simultaneously.

Henry:
That’s really cool. Let’s put a pin in it because I want to get back to the story, but that’s super cool. And of course you did something like that because why wouldn’t you? All right, so you did that first 15% cash on cash return deal. What year was that?

Lucas:
That was 2019.

Henry:
That wasn’t that long ago. And so did you just ramp up continuing to do that or how did you go from there to where you’re at today?

Lucas:
So I attempted to. This was in rates were under 3%. So I found another one in 2020. I bought that property for 120,000. It rents out for 1,525 per month per day. I continued to look through 2021 until about 2026 earlier this year and just honestly could not find anything that was worth my time to look at. I asked myself, what else can I do if I’m building up this cash pile to buy these 15% cash on cash returns, but there’s none out there, what can I do to hit financial freedom faster so I can pay down debt and deleverage myself? And so for the past four years, I would have a cash pile enough to purchase a house, but if that started to grow and grow, I would use the additional to pay down leverage.

Henry:
I love this conversation. If you are a real estate investor, buying a new property isn’t the only way to help yourself achieve financial freedom. You have a couple of options and I love that you explored this option. You can look inwardly at your portfolio and say, “Yes, I have this property. It cash flows great leveraged if I pay it off. So if I take this $50,000 and I pay off my loan on this asset, what kind of cash on cash return do I get now? What kind of return do I get? And is it better than going and buying a new one?” Because if you’ve got cash flow of, let’s call it $300 a month and you can pay that asset off and now you’ve got unleveraged cash flow of $1,200 a month, that’s a substantial increase. And is that return higher than if you just go buy another leveraged house and add it to your portfolio?
That’s the math you get to do. Another option is maybe you can pivot a strategy, take a long term and make it a short term if it makes sense. I guess the point I’m trying to make is you don’t have to go buy another property, consider your current portfolio. Can you pay for something either paying down the asset, remodeling a kitchen, adding a bedroom? Can you add money to your current asset to increase the rents and will that produce a higher cash on cash return than buying a new asset or just paying something down? Because paying something down not only gives you more cashflow, but it gives you less stress. So that’s my favorite part about it. So then what do you do? Are you just going to focus on paying off deals now or is there something else you’re working on?

Lucas:
No. So probably three years ago, my poor wife was so patient with me for the past 10 years, moving her into a different place, having half the house under construction. And so I told her, “Hey, at some point we’re going to have to buy the house that we want to live in for a longer period of time.” And this is your seasoning as you go through your investor life cycle, right? In the beginning, you’re looking for anything that you can do. You’re willing to live right next to tenants. And once you’ve done that five or six times, you’ve got to be making some progress within yourself and within your family as well. So we found 66 acres out in the country where we live here and we decided, hey, we were going to clear a small section and build our dream house on there. So it took me about a year to clear about four acres, get all my permits and stuff, and that’s where I’m here now.

Henry:
Oh, wow. So you found wooded acreage.

Lucas:
Exactly.

Henry:
What did 66 acres cost?

Lucas:
378.

Henry:
378. How long ago did you start that purchase?

Lucas:
So that was in 2022 is when I purchased that property. And throughout 2022, I cleared the… It was about four acres of smaller trees that I had to clear for the house and continued to save up to have enough for a down payment to actually build the house that we wanted to live in for the rest of our life.

Henry:
I’ve got tons of questions because I’m doing something very similar, and I’m going to ask you some of those questions right after this break. All right, we’re back on the BiggerPockets podcast. I am with investor Lucas Teague, and he has been sharing his investor journey starting at a young age back in 2013, and now he has told us he purchased 66 acres, cleared out about four to five acres, and has built a home on that land. I have lots of questions because this is kind of a popular concept right now. I just bought 20 acres. I’m going to build a house on it. I’m excited about it. So how did you purchase this land? Because there’s several ways to do this. I know some people buy the land and get a loan for the land and building the house all as one, but you had to buy land, clear land, there’s site work, there’s utility work.
What did you have to research, and then how long did the process take between finding the property and then being able to start a build?

Lucas:
So it probably took us two or three years to actually find the property. And the reason we signed up for this one was it was right next to where my parents lived at the time. And my father was sick at the time and didn’t have much time left, and so I wanted to be close to family when that time were to come. And so my parents owned 68 acres to the north, and this property came up just to the south of that at 66 acres. I mean, it came up for sale. I did a little bit of research. Thankfully, it’s not overly difficult to get permits in our area. It’s not easy, but we’re probably right there in the middle. So there’s some utility work that you’ve got to do. There’s some elevation profile. There’s floodplains you’ve got to look at. Mistake that I made, there’s no internet access out where I live, there’s no fiber.
So I’m calling in from Starlink here, which saved me. So there’s a little bit of homework that you need to do before you purchase something like that.

Henry:
And did you use one loan for all of it or did you have to do this all separately?

Lucas:
No. I stayed pretty conservative. I put probably 50% down payments on the land. I did a specific land loan on a 15-year fixed at 3.7%, and that was back in 2022. And then I waited about another year. I got a construction loan to build the primary residence, which we finished construction of that in June of 2023. Since then, I’ve spent three years of just paying that property off. So now essentially, we’re debt free with our primary residence and our land, and so our monthly basis of what we need to make is fairly low.

Henry:
That’s really cool, because there’s a lot of different ways to A, purchase land and to B, build on that land. Not only are there combined loans like I talked about, so for those that are listening, you can get one loan that will allow you to purchase the land and build the house. Now you have to have done a lot of research on the front side because you need to know who your builder are. You got to have your plans, right? But a bank can loan you everything to do this, or you can go the route like I went and like Lucas went, which is to go buy the land first, and then a lot of banks will let you leverage the land once you own it as your down payment so you don’t have to put money down for the construction loan. So talk to the banks and find out what products they have that can help you do something like this.
I also hear that there’s all kinds of grants and programs to help people take raw land and develop something on that land. It just depends on what it is that you want to develop on what programs that are available to you. Did you look into anything like that?

Lucas:
I did, and that’s something that I’ve hardly ever heard discussed anywhere on any real estate podcast. So if you own raw land in most of the United States, we have an issue where invasive species like bush honeysuckle, espediza, automolive, those invasive species seeds are coming in from, it could be China or Russia or Australia, things that are not native here to the United States. So our government has funding where they create a pool of funds to give to landowners to eradicate those invasive species on the property,
Which was something I have never heard anywhere. And so I’m doing some research, “Hey, I’ve got these 66 acres. Do I want to timber this? No, not really. I don’t want them destroying the forest. Well, what else can I do?” And so I stumbled across this. It’s United States Department of Agriculture and then the subdivision Natural Resource Conservation Service, and they will essentially come out and look at your land, see the level of invasive species that you have on the property, and then assign a budget for your property to get those invasive species removed. It’s a one-time grant that you’ll get usually over three to five years, depending on how invasive the species are at your property. In my specific case, they gave us about a thousand dollars an acre over the course of three years, so about 66,000. We just finished that contract about three months ago or so, and yeah, super, super easy.

Henry:
So they just gave you a thousand dollars an acre. Now, you had to go do the work to eradicate the invasive species of plant. What does it cost you to do that versus what they’re giving you?

Lucas:
In my specific situation, the levels were so high where I subcontracted it out to a group of folks, they would come out here, do the work for me, and so we basically split the money fifty fifty. I paid them, and then I kept the rest as well.

Henry:
That’s so cool. I am absolutely researching this the second we got off this podcast. That’s really cool. So how did you even stumble across that?

Lucas:
Just researching. I mean, I have the 66 acres and I wanted it to produce some cash flow just like a rental property would. And really, am I going to raise farm animals? Probably not. That’s not my skillset. I could do a timber harvest. Can I let somebody else use the land maybe for hunting? I wasn’t really comfortable with any of those things. So I just kept researching, “Hey, you can use AI now too. Hey, I’ve got 66 acres. What kind of ideas do you have for me to make money from this where it’s not too disruptive to my lifestyle?” I mean, sure enough, there it was. And honestly, it’s a great program. Three years later, our forest is so much healthier. We have 99% native species out here. The birds, the turkeys, all of the deer, the wildlife are happier because there’s more calorically dense food out there, and so it’s really a good program.

Henry:
Well, Lucas, this has been really fun. What a cool story of how to use real estate to supplement your lifestyle, right? Not everybody needs to start investing and retire in a few years, but you can still build a pretty cool life and a pretty cool lifestyle using real estate and keeping your job. I love that you’ve kind of talked us through how you did that. So before we get out of here, a couple of things. Can you tell us a little bit about where you stand today as an investor, what’s your portfolio look like?

Lucas:
So today we have three rental properties and we’ve got our primary residence on the 66 acres, which is paid off. And so complexity started to enter my life at some point, and I decided to simplify. And so we have a very simple portfolio that covers all of our family’s basic needs. I still continue to work my W-2 job for different reasons than what I did 12 years ago, but now I’ve shifted into a different phase of it’s not as much about me and my family. It’s about what I can give back to my community, what I can give back to other families. So I’ve been able to donate very large sums of money to local charities and families and things like that. I’m giving a house away to a family member that needs it as well, and so I’m moving into an all new chapter of life here.

Henry:
I love that. I love that more than anything. I’m just truly a believer in that. We are chosen to be stewards of wealth. When I hear stories all the time of people who’ve amassed wealth and lost it, I always see people who were selfish with it, but people who have philanthropic ambitions or who are using it in good ways always seem to continue to find more, and I don’t think that that’s a coincidence. So that’s really cool that you’re doing that, and it’s really cool that you’re able to do that all through buying a couple of properties back in 2013. That’s really, really fun. All right. So earlier in the show, you were talking about this tool you built with AI to help you analyze neighborhoods. Can you give us a little more detail on that?

Lucas:
We’re now in the generation of AI, and it is such a powerful tool. Hey, 10 years ago, prices were significantly lower than what they are now, but there was not tools like this that existed and made it so easy for the average person, and you don’t even have to be an expert. You can type into ChatGPT or Claude or Grok or whichever app that you’re using, and you can ask any series of questions and will make your life so much easier. But one specific thing that I do for my real estate clients and from an investing lens is in my specific market, there’s maybe 100,000 people, and there’s businesses going in, there’s new neighborhoods going in, there’s so much stuff that’s going on just in my micro economic circle and something you can use AI for, you can have it analyze all of the local news that’s going on in your specific area, have it overlay those news articles with a specific map of your area, and then chart out what’s the next five years going to look like?
What’s the next 10 years going to look like? If a new business goes in that’s hires 5,000 people, what that’s going to do to the property values? There’s some news that happens to neighborhoods where the prices are probably going to go down 10%, maybe a new neighborhood’s going in and prices are going to raise Based off that new neighborhood or shrink. If a business is going in, there’s going to be more jobs most likely. And so probably property values in that area are going to increase. And you can use AI to analyze that massive data set, overlay it with the map of your area. And now you can even target specific neighborhoods that have a higher probability of having more appreciation than what the normal house would in your town.

Henry:
That’s pretty cool. How long have you been using this tool?

Lucas:
Probably a year now. And I just purchased my first property almost using exclusively AI. I trended the neighborhood. I found a specific area that’s probably going to appreciate 20% in value over the next five years. Then I overlaid that with my 15% cash on cash return AI tool. And sure enough, hey, a property came up. I went and looked at it in pretty good shape. So yeah, we’re already seeing results in roughly six months.

Henry:
Have you seen results that match the research?

Lucas:
Probably not on the appreciation side yet. I would say on the cash on cash return side, yes, but I’d say too soon to tell on the appreciation aspect.

Henry:
It is rare to find great cashflow and great appreciation. And you’re using technology to help you be more strategic to where you have a higher probability of getting both, which is super smart. Thank you for sharing that. All right, Lucas, thank you so much for joining us on the BiggerPockets Podcast. Is there a place where people can find out more about you or find you?

Lucas:
Yeah, you can find me on biggerpockets.com or you can find me on Facebook, Lucas T.

Henry:
Awesome. And thank you everyone for listening to this episode of the BiggerPockets Podcast. This was super cool. I’ve got some homework I’m going to go do based on what I learned from Lucas. Hopefully you do too. As always, we’ll see everybody on the next episode.


Help us reach new listeners on iTunes by leaving us a rating and review! It takes just 30 seconds and instructions can be found here. Thanks! We really appreciate it!

Interested in learning more about today’s sponsors or becoming a BiggerPockets partner yourself? Email [email protected].


Source link

3 Paid-Off Rentals: The “Boring” (But Proven) Path to Financial Freedom Read More »
Why the Smartest Franchise AI Strategy Keeps Humans Central

Why the Smartest Franchise AI Strategy Keeps Humans Central


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • AI mimics expertise but can’t replace it.
  • A brand-wide AI strategy with approved private platforms and data-privacy training protects proprietary assets and prevents leaks.
  • Over-reliance on AI erodes both talent and brand.

Artificial intelligence is reshaping the global business landscape, and franchising is no exception. While the adoption of AI presents growth opportunities, it has also introduced widespread uncertainty. To navigate this shift, franchise leaders must look past the initial buzz, evaluate associated risks and strategically implement AI models.

AI should be used to increase operational efficiency — not as a replacement for human judgment, as improper allocation of these tools may leave your business open to serious operational risks. 

The illusion of expertise

AI platforms provide lightning-fast access to unprecedented volumes of information, which can mimic expertise, but that is a dangerous illusion. Because these models lack lived human experience and rely entirely on data, they cannot offer a genuine first-person perspective, draw from real-world practice or evaluate situational nuance. Often, these chatbots don’t have accurate, up-to-date information because it may not be publicly available or may not even exist yet. 

In franchise development, growth depends on more than simply signing franchise agreements. Success requires identifying the right locations, securing favorable deals and keeping the real estate pipeline moving. While an algorithm can process useful real estate information, like public square footage and location data, it cannot replicate the real-time, high-stakes market intelligence that seasoned brokers — who help with site selection, landlord negotiations and securing high-value locations — build through interpersonal relationships.

An algorithm lacks the foresight into local market dynamics, such as upcoming developments, emerging brand synergies that boost foot traffic or tenant shifts that pose major risks. Crucially, a broker’s local network identifies seller motivations that may not appear in public filings, whether a landlord is racing against a 1031 exchange timeline or seeking a quick exit from an off-portfolio asset. This off-market insight and trust provide a strategic edge that data alone cannot match.

When leaders rely on AI, they may ask fewer critical questions, leading to greater confidence in recommendations that have not been fully vetted. AI should serve as a starting point for research and ideation, encouraging strategic thinking and refining ideas, rather than replacing human judgment. 

Targeted training improves effectiveness  

Deploying AI without structured employee training is a fast track to ROI loss. Unlike traditional software rollouts, successful AI integration requires a clear business rationale, defined operational guardrails, ongoing support and a workforce trained to use AI safely and effectively. Organizations should establish clear guidelines around approved platforms and train employees on data privacy, including the risks associated with using open-source models. Without proper training, employees risk leaking proprietary information to a model that trains on user inputs. 

This impact is not theoretical; in 2023, engineers at Samsung’s semiconductor division accidentally leaked proprietary source code and confidential meeting notes by pasting them into ChatGPT to optimize the code and draft meeting summaries, forcing the company to ban public AI tools and build internal alternatives. 

To maintain consistency and protect brand integrity, franchise systems should implement a brand-wide AI strategy rather than allowing individual locations to adopt ad hoc solutions. Establishing standardized AI platforms and clear usage guidelines ensures that site operations and training remain uniform across all franchisee locations. Systems should enforce strict data security protocols to safeguard proprietary assets — such as brand manuals and specialized curriculum — by utilizing private AI models that restrict data training and prevent confidential information from entering public platforms.

While AI speeds up execution, it cannot replace strategic vision or human oversight. Real transformation occurs only when organizations empower their teams through training to turn model capability into measurable business outcomes.

Balancing efficiency with human insight 

Across many industries, leaders have attempted to replace entire teams with AI to reduce operational costs. While this is attractive from a budgeting standpoint, over-reliance on these models can have severe long-term consequences. For example, Klarna, the digital bank and global payment service provider, had to roll back its AI-driven workforce cuts when customer satisfaction fell, as the system struggled with complex, multi-step issues that required a human touch.

AI must remain an aid, not an answer. Replacing employees with AI eliminates expertise from your staff that may be required for complex, situational issues. There’s institutional knowledge you acquire on the job that can’t be replicated by artificial intelligence — things you intuitively know about corporate culture and internal processes that aren’t necessarily written down anywhere, much less available in the public domain on which LLMs rely. Your employees possess unique real-world experiences, critical thinking skills and relationships built on trust that inform real-time decision-making, as well as the ability to shift and adapt in the moment. 

Avoiding brand homogeneity 

Furthermore, using generic AI tools can dilute brand identity in an increasingly similar marketplace. Because these models operate with past data — often from the same set — they lack adaptability, individuality and a unique human voice required to differentiate your brand. 

While AI streamlines content creation, it also makes it easier for brands to blend together with generic marketing material. Rather than focusing on generating content at scale, companies should protect their unique brand voice by leaning on recognizable intellectual property their audience associates with the brand. 

This challenge is especially pronounced in franchising. Effective franchisors must establish clear guidelines that maintain a consistent voice while empowering franchisees to create locally relevant content. As a franchisor, we invest heavily in crafting intentional mission and value statements, distinct messaging and visuals, as well as brand-level campaigns. However, the moment these are fed into AI models, the investment is diluted, rendering the system’s intentionally crafted messaging unremarkable. 

Unrivaled performance through cautious adoption 

A cautious approach to AI does not mean avoiding it completely. When implemented with strict guardrails, AI enables long-term integration while mitigating risk, driving measurable efficiency and cost-effectiveness across a franchise system.

These guardrails must start with clear leadership. Without explicit guidance and transparent strategy from executive leadership, AI adoption across channels may become inconsistent. Leaders who set proactive expectations for acceptable AI use ensure their teams understand how to leverage these tools effectively.

At Kiddie Academy, we use AI to help franchisees operate better and make data-informed decisions. From communication guidance and operational insights to identifying opportunities for improvement, AI helps Academy leaders access relevant information more quickly so they can focus their time on serving families, supporting educators and growing their business. Human judgment remains at the center of every decision.

For prospective franchise owners, AI is a powerful tool for aggregating competitive market data and identifying top industries. However, this data is not the end. You should first focus on self-reflection. Evaluate your own background, interests and operational preferences before turning to a language model. AI can serve as a source of information, but not a source of truth. Its interaction biases tend to tailor responses to what it thinks the user wants to hear, serving as an echo chamber rather than a sounding board.

AI is essential to the future of franchising, acting as a franchise accelerator that enables franchisees to scale their business, analyze industry trends and make data-driven decisions faster than before. From scheduling to competitive market research, AI empowers franchisees to streamline daily activities. However, overreliance poses risks, including a lack of human insight and potential degradation of brand identity. Successful AI integration requires a balance between human experience, brand voice and operational automation. 

Because real organizational intelligence requires more than tools; it needs the irreplaceable value of human experience and knowledge.


Source link

Why the Smartest Franchise AI Strategy Keeps Humans Central Read More »

How AI Companies Are Making Normal Growth Look Like Failure

How AI Companies Are Making Normal Growth Look Like Failure


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Don’t benchmark against AI’s growth curve. AI companies often benefit from unusually short sales cycles, little regulation and instant product adoption — conditions that don’t apply to most industries.
  • Study companies in your own category to map realistic timelines, then set investor expectations and internal plans against that curve.
  • Track short-term metrics your team can influence weekly, while identifying the specific milestone — such as a license, partnership or cost threshold — that could accelerate growth.

Every few weeks, another AI company posts a revenue chart that goes almost straight up. Lovable crossed a $600 million revenue run rate in September 2026, up from $500 million in June. Cursor passed $4 billion in annualized revenue in early June 2026, double where it stood in February. Three years ago, those numbers would have sounded made up.

Founders outside AI feel these charts. A fintech team waiting on a license starts to feel slow. A payments company growing 6% a month starts calling it a plateau. Plans get reset around a tempo that was never theirs.

The decisions that follow are usually bad ones. They hire ahead of demand, raise on terms they can’t grow into or walk away from a market right before it turns.

AI’s speed has specific causes

The AI coding tools grew fast for reasons that don’t transfer. The product lives in a browser tab. A user pays with a credit card, so there’s no procurement cycle. No regulator signs off. The buyer already understands the job, which is building software, and sees a result in minutes. Every new model release makes the product better before the startup ships anything.

Remove those conditions, and the curve flattens. Most sectors carry at least two brakes: a long sales cycle, a regulator, a customer who needs educating or a physical supply chain. Copy the pace of a company with none of those brakes, and you’ll burn 18 months of runway in nine.

Other categories, other clocks

Fintech runs on regulatory time. Revolut, founded in 2015, spent close to two years in the UK on a restricted banking license with a cap on deposits. It only launched as a full UK bank in March 2026, with 13 million UK customers already on the app. One of the fastest-growing companies in Europe still had to wait for a regulator to say yes.

Singapore’s digital banks show the same pattern closer to home. Trust Bank recorded its first profitable month in March 2026, just over three years after launch. GXS Bank, backed by Grab and Singtel, lost S$132 million in FY2025, the largest loss among the city’s digital banks. Same market, very different curves, and both still early.

A bank has to win deposits, build a loan book and prove credit quality across a full cycle before the economics work. None of that compresses because a competitor in another sector shipped faster. Speed shows up later, once trust and the balance sheet are in place.

Trust Bank’s CEO described the March result as the outcome of years of disciplined execution. That’s what the right clock looks like from the inside: long stretches of unglamorous work, then a month where the numbers turn.

Map your category’s curve

Founders tend to benchmark against whoever is loudest that quarter. A better benchmark is the companies that went through your category before you. Pick three. Find out how many years each took to reach its first $1 million in revenue, its first institutional round and its first profitable year. Most of this is public in IPO filings, funding announcements and founder interviews.

Then look at what controls speed in your market. How long between first meeting and signed contract? Who else has to say yes: a regulator, a compliance team, a bank partner? How often does the buyer make this decision? A company selling into annual budgets gets one real shot per customer per year. That’s your clock, and your plan should run on it.

This changes the investor conversation, too. If a fintech board expects AI-style growth, someone will be disappointed around month 14. Put the category curve in front of them early, with the comparables, so you’re measured against the right line.

Staying motivated on a long curve

Long curves are hard on morale. The visible milestones sit far apart. When your feed is full of eight-month success stories, the gap between your effort and your progress starts to feel personal.

The fix is to shorten the feedback loop without pretending the curve is shorter. Pick two or three numbers your team controls and can move inside a week: discovery calls booked, day-30 cohort retention, time from signup to first value. Review them every Monday. When those move, you’re making real progress, even if revenue moves at the speed of your category.

It also helps to name the bend. Every long curve has a point where it steepens: a license granted, a distribution deal signed, a cost threshold crossed. Write down what yours is and how you’d know you’re getting close. A team that knows what it’s waiting for can wait a long time. A team that’s just waiting tends to quit.

The next time an AI revenue chart crosses your feed, count how many of its conditions you share before you let it touch your plan. If the answer is zero, close the tab and get back to your own curve.

Key Takeaways

  • Don’t benchmark against AI’s growth curve. AI companies often benefit from unusually short sales cycles, little regulation and instant product adoption — conditions that don’t apply to most industries.
  • Study companies in your own category to map realistic timelines, then set investor expectations and internal plans against that curve.
  • Track short-term metrics your team can influence weekly, while identifying the specific milestone — such as a license, partnership or cost threshold — that could accelerate growth.

Every few weeks, another AI company posts a revenue chart that goes almost straight up. Lovable crossed a $600 million revenue run rate in September 2026, up from $500 million in June. Cursor passed $4 billion in annualized revenue in early June 2026, double where it stood in February. Three years ago, those numbers would have sounded made up.

Founders outside AI feel these charts. A fintech team waiting on a license starts to feel slow. A payments company growing 6% a month starts calling it a plateau. Plans get reset around a tempo that was never theirs.

The decisions that follow are usually bad ones. They hire ahead of demand, raise on terms they can’t grow into or walk away from a market right before it turns.


Source link

How AI Companies Are Making Normal Growth Look Like Failure Read More »

Your Payments Got Faster. So Why Didn’t Your Finance Team?


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • The goal is not maximum payment speed. It is knowing what happened after the money moved.
  • A company has not meaningfully improved its payment operation if it shortens the payment clock while making the close clock harder to manage.

The payment went through in seconds. The books were still wrong three days later.

Money can move quickly while invoice data, approval history, remittance details and accounting records remain scattered across different systems. Faster settlement does not automatically create a faster finance operation. It can move the bottleneck downstream, from the payment desk to the reconciliation queue.

I think about this in terms of two clocks. The payment clock measures how quickly money moves. The close clock measures how quickly the business can explain and reconcile that movement.

A company has not meaningfully improved its payment operation if it shortens the payment clock while making the close clock harder to manage.

Separate the payment from the record

A payment has two journeys: the movement of funds and the movement of information through approval, accounting and reconciliation.

The Federal Reserve distinguishes clearing from settlement. Clearing involves payment information and related activities. Settlement is the debiting and crediting of accounts. They are connected, but they are not the same step.

That difference became clear to me while running Tyler Petroleum. We were using different payment providers for different vendors, which created cost and time burdens. The problem was not just how long money took to move. Every additional system created another place where payment information had to be tracked, matched and understood.

The question is not simply, “How quickly can we send this?” It is, “What will finance need to know after we send it?”

The issue is becoming more relevant as businesses add payment methods. A 2025 Federal Reserve Financial Services survey summary reported that 92% of businesses use some form of faster payments, including Same Day ACH and digital wallets. The same summary reported that businesses still identified cost, security concerns and lack of timeliness as leading payment challenges.

Measure both clocks before changing the rail

Before changing a payment method or adding payment automation, map the workflow from invoice approval through payment initiation, settlement, remittance delivery, accounting entry, reconciliation and exception resolution.

Measure both clocks: how long the payment takes to settle and how long finance takes to identify it, match it to the right invoice and resolve an exception. If settlement falls from a day to a few seconds while an unmatched transaction still takes three days to resolve, the company has improved payment speed, not visibility.

Assign an owner to every stage, especially the break. That is one of the most important payment controls. If the answer to an unmatched payment is “accounts payable will find it later,” the workflow is not ready.

Choose the payment method by the business need

Not every payment requires the same timing or data. A payroll correction late on Friday may justify a faster method. A routine invoice due next week may not.

Before changing the method, ask three questions:

  1. Does this payment actually need speed? If the answer is no, faster settlement may add cost or process complexity without improving the business outcome.
  2. What information must travel with the money? A payment that arrives without a usable invoice number, vendor identifier or remittance detail creates work for someone else.
  3. What happens when something goes wrong? Decide who handles a duplicate, changed instructions, returned payment or unmatched remittance before the first transaction is sent.

The right payment method fits the urgency, approval process, accounting workflow, cash forecast and exception plan.

Run the five-payment test before you scale

Before expanding a new method, test five cases:

  1. A normal payment. Can the team trace it from approval to the accounting record?
  2. A duplicate attempt. Does the workflow identify the risk before two payments leave the business?
  3. A payment with changed instructions. Is there a review step before the new details are used?
  4. A failed or returned payment. Who receives the exception, and how quickly is the vendor or recipient informed?
  5. An unmatched remittance. Can finance identify the payment’s purpose and resolve it without searching across several systems?

If the team cannot explain all five cases, the process is not ready to scale. Real finance work is defined by payment exceptions, not by the one payment that works as planned.

Design reconciliation before launch

Reconciliation should be designed before a payment project goes live.

Require one usable identifier to follow the transaction from approval through settlement and into the accounting system. Define a daily exception queue. Set a deadline for resolving unmatched items. Keep an audit trail that connects the original approval, the actual payment and any correction.

Nacha has noted that many payment back offices still rely on manual intervention for exception handling, returns and reconciliation. Automation can reduce repetitive work, but it does not remove the need for judgment. A system that can send a payment in seconds but cannot explain it is only partially controlled.

Before approving the project, ask whether the business can identify every payment’s purpose, assign responsibility for unmatched transactions and distinguish timing differences from actual errors at close. If the answer is no, slow down the rollout. The goal is not maximum payment speed. It is knowing what happened after the money moved.

Faster payments are useful. Faster confusion is not.

Key Takeaways

  • The goal is not maximum payment speed. It is knowing what happened after the money moved.
  • A company has not meaningfully improved its payment operation if it shortens the payment clock while making the close clock harder to manage.

The payment went through in seconds. The books were still wrong three days later.

Money can move quickly while invoice data, approval history, remittance details and accounting records remain scattered across different systems. Faster settlement does not automatically create a faster finance operation. It can move the bottleneck downstream, from the payment desk to the reconciliation queue.

I think about this in terms of two clocks. The payment clock measures how quickly money moves. The close clock measures how quickly the business can explain and reconcile that movement.


Source link

Your Payments Got Faster. So Why Didn’t Your Finance Team? Read More »

Former UPS Employee’s ‘Flavorful’ Side Hustle Hit K a Month

Former UPS Employee’s ‘Flavorful’ Side Hustle Hit $30K a Month


Key Takeaways

  • Ramlal and his wife, Yuvika Wadhwa, launched side hustle Protein Chefs in 2015.
  • Two years in, Ramlal left his UPS role and continued to build the business.
  • Protein Chefs saw consistent revenue immediately; now, it surpasses seven figures annually.

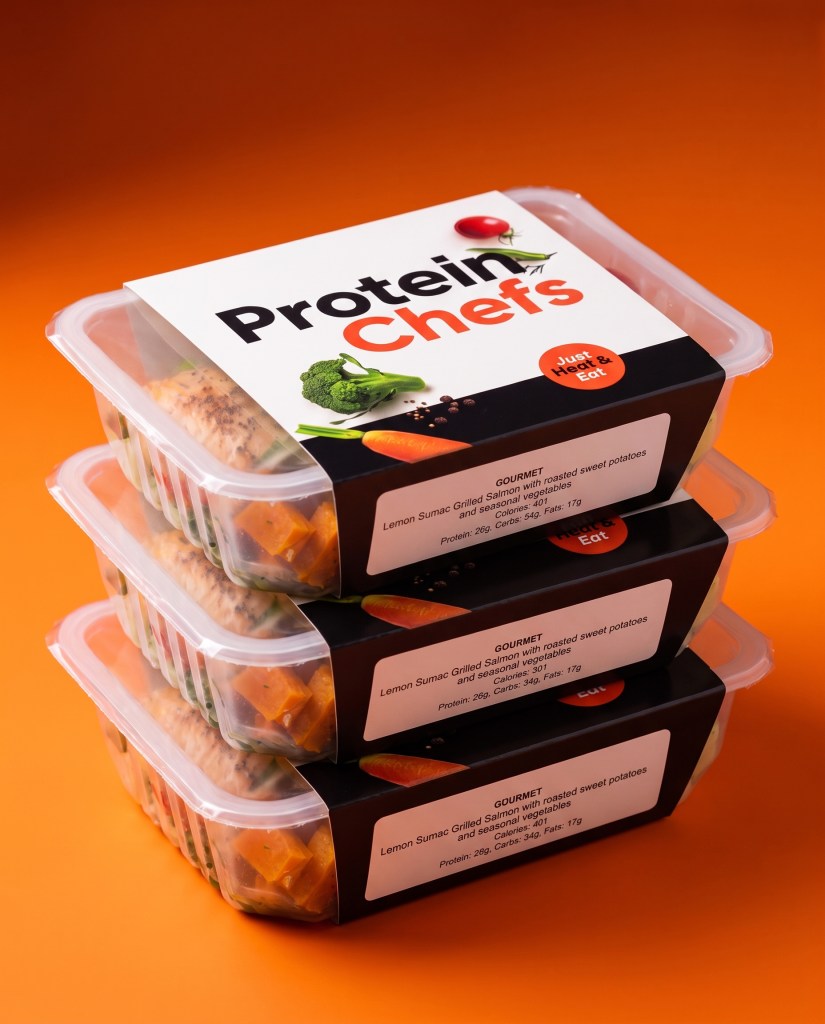
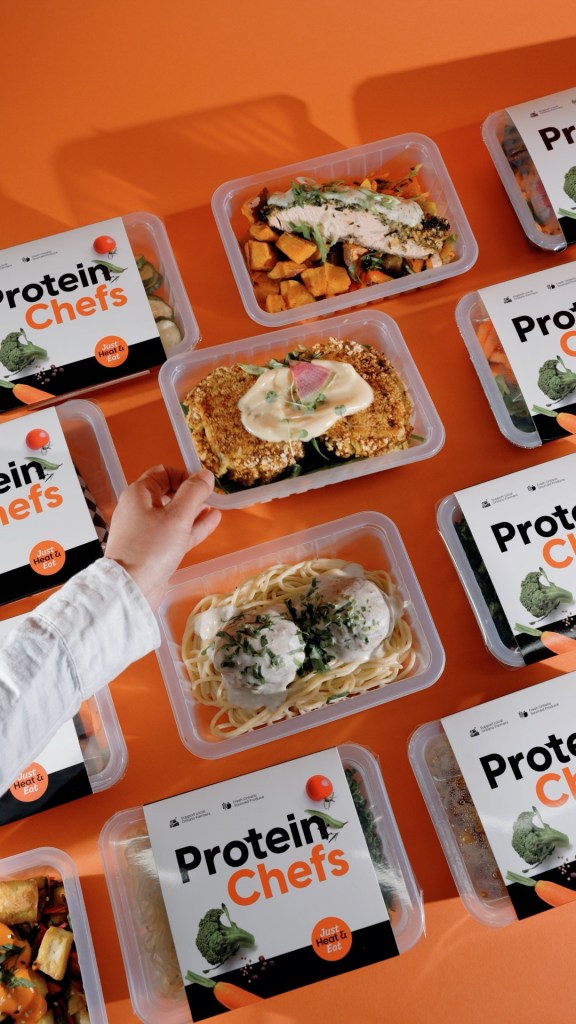
This Side Hustle Spotlight Q&A features Ronneil Ramlal, a 38-year-old entrepreneur based in Ontario, Canada. Ramlal is the founder and CEO of Protein Chefs, a gourmet and health-focused meal delivery service. He started Protein Chefs as a side hustle while working as a supervisor at United Parcel Service (UPS), then left that role to focus on the business in 2017. 

Image Credit: Protein Chefs. Ronneil Ramlal.

When did you start your side hustle, and where did you find the inspiration for it?
I started Protein Chefs in 2015 with my wife, Yuvika Wadhwa. I was always passionate about starting a business because I grew up watching my father, who is an entrepreneur. My wife was a pastry chef, and we met at the gym. Since we both are serious about our fitness, and with our respective backgrounds in business and hospitality, the food industry was naturally appealing to us. We specifically chose the prepared meal delivery business because in 2015, with our busy corporate jobs, we struggled to meal prep every week and couldn’t find healthful meal delivery options. We wanted to eat balanced, nutritious food that was also flavorful. 

Bootstrapping the side hustle with $2,500

What were some of the first steps you took to get your side hustle off the ground? How much money did it take to launch?
I didn’t want to borrow money, so we completely bootstrapped the business. I used $2,500 from my savings to get a website developed, hire a chef on an hourly basis and rent a kitchen space. Then, we set up an Instagram account and started posting about the business and gradually getting followers. Next, we reached out to fitness influencers because initially we struggled to get orders. We cold-messaged people on Instagram who might want free meals in exchange for a review of our service. That’s how we got our first few customers.

Are there any free or paid resources that have been especially helpful for you in starting and running this business?
The only “resource” I turned to when I needed help to brainstorm ideas or discuss challenges was my dad. The first person I turned to was my wife because we made all decisions about the business together.

Image Credit: Protein Chefs

Invest early on in marketing, a website and SEO

If you could go back in your business journey and change one process or approach, and how do you wish you’d done it differently?
I would invest early on in marketing, especially in building a better website and SEO. At the time, we were so focused on running kitchen operations that we could barely afford to peep outside. This led to slow growth for the first few years. I wish I had invested more in automating some manual tasks such as customer database management and sending them email reminders to order meals, so I could free up more time for myself. I would have definitely spent more on marketing because that allowed us to hone in on our target audience of busy professionals who want to eat healthfully and update our messaging accordingly.       

The value in customer service and transparency

When it comes to this specific business, what is something you’ve found particularly challenging and/or surprising that people who get into this type of work should be prepared for, but likely aren’t?
The food industry has multiple moving parts such as kitchen operations, packaging, delivery, customer service, partnerships, supplier management, marketing, website and so on. People in this business should be prepared to handle all these areas in unison and simultaneously for the business to be successful.

If your food is great, but no one knows about you, and your customer service doesn’t support your customers, it doesn’t matter how much time and effort you’re spending in the kitchen. If your website is avant garde, and your branding is on point but your meals aren’t what you promised they would be, you won’t get customers to stay. In today’s market, it’s easy to believe that a product can ride on a great social media or personal brand, but that’s a short-sighted strategy. For everything to work, you must be willing to get involved in everything.

Image Credit: Protein Chefs

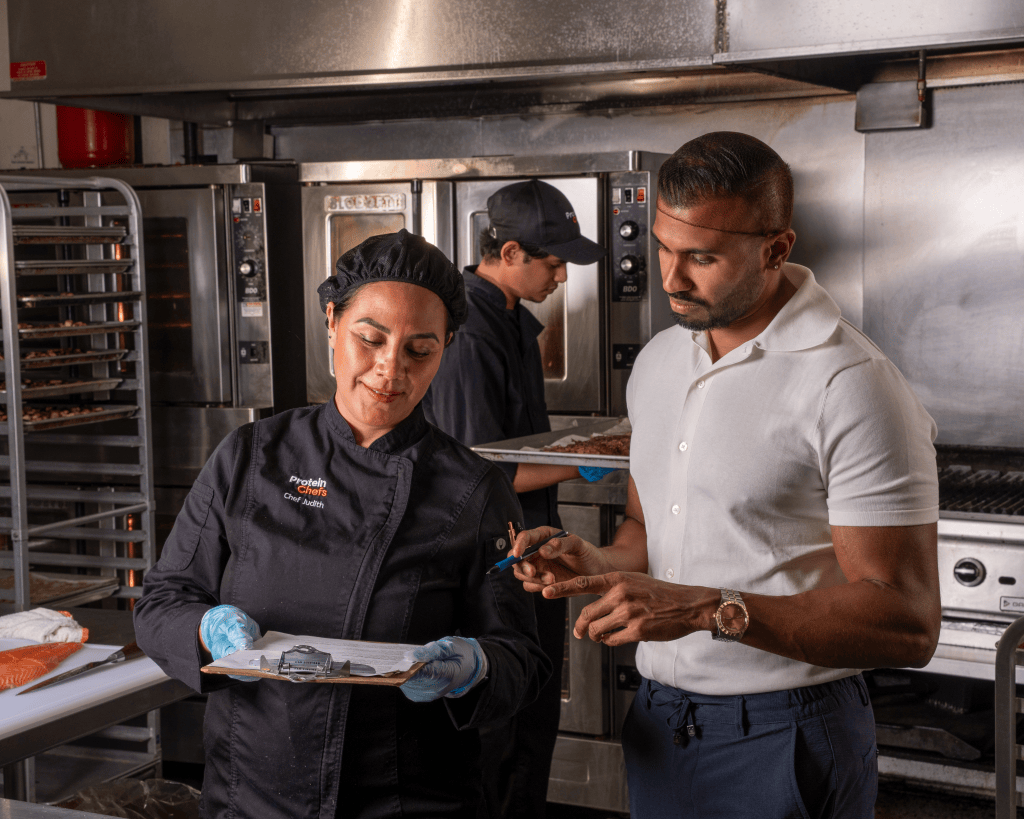
Second, when it comes to food, people are especially cautious about how their food is prepared, so if you can show complete transparency about your behind-the-scenes operations, that can help build credibility. For example, when we started showing our chef creating meals from scratch on our social media and the standards that we adhere to, our customers’ trust grew. So, before entering this industry, you must be prepared not to cut corners.

Another challenge in the food industry is that margins are thin when you only have a few customers. Profits expand once you reach high-volume production and build credibility, which can take a few years. You need a lot of patience.

The importance of hiring the right people

Can you recall a specific instance when something went very wrong — how did you fix it?
The biggest mistake we made was early on hiring a chef who didn’t fully comprehend the role. He was a really skilled cook but not a chef. He made very flavorful food, but he couldn’t do costing, standardize the menu, manage inventory or oversee a team. When we grew our customer base and added more employees into the kitchen, he couldn’t delegate or train. That fell to me and Yuvika, and it held us back for a few years. But that’s what we could afford at the time, and his flexible schedule worked for us. 

After about three or four years, we realized we weren’t growing, so we had to let him go and find someone more advanced. The next chef was a big step up. He standardized the menu, which let us add more dishes and meal plans. We had a few more chefs after that. Now we have a chef who is adept at everything: cooking, team management, menu innovation and development, paperwork and supplier management. It took some years to get here, but we learned how important it is to hire the right people for the job.

Image Credit: Protein Chefs

From $4,000 to $30,000 in monthly revenue — then 7 figures a year

How long did it take you to see consistent monthly revenue? How much did the side hustle earn?
We struggled to get clients for the first weeks, but once that picked up, we had consistent revenue even initially, just not very high. At the beginning, it was around $4,000 monthly, which grew to $20,000 to $30,000 per month in the next few years.

What does growth and revenue look like now?
We plateaued for the first three to four years. After we invested more heavily in marketing and identified our main target audience as busy professionals and not only bodybuilders or fitness enthusiasts, our revenue doubled. Last year, we had 21% revenue growth, and this year, we’re at 30% growth, including our corporate partnerships. We reached seven-figure revenue in 2022 and have continued to maintain that. 

Take risks to see what’s possible

What do you enjoy most about running this business?
For me, it’s the unknown. I like not knowing what the next day could look like because that challenge gets me excited and allows me to push my own limits. There are no caps on what you could achieve, which can be good and bad because the success or failure of the business depends on you. I choose to see it as a vehicle for growth.

What is your best piece of specific, actionable business advice?
When things get tough, know that it’s your job to vouch for yourself because no one else is going to do it for you. Stop comparing yourself to others, and continue to believe in yourself no matter how long it takes to see the result you were hoping for. Also, take measured risks. 

So, my advice is to be abundant when it comes to believing in yourself and calculated when it comes to taking a risk, but nonetheless, take risks, because that’s the only way to know what’s possible.

Key Takeaways

  • Ramlal and his wife, Yuvika Wadhwa, launched side hustle Protein Chefs in 2015.
  • Two years in, Ramlal left his UPS role and continued to build the business.
  • Protein Chefs saw consistent revenue immediately; now, it surpasses seven figures annually.

This Side Hustle Spotlight Q&A features Ronneil Ramlal, a 38-year-old entrepreneur based in Ontario, Canada. Ramlal is the founder and CEO of Protein Chefs, a gourmet and health-focused meal delivery service. He started Protein Chefs as a side hustle while working as a supervisor at United Parcel Service (UPS), then left that role to focus on the business in 2017. 

Image Credit: Protein Chefs. Ronneil Ramlal.

When did you start your side hustle, and where did you find the inspiration for it?
I started Protein Chefs in 2015 with my wife, Yuvika Wadhwa. I was always passionate about starting a business because I grew up watching my father, who is an entrepreneur. My wife was a pastry chef, and we met at the gym. Since we both are serious about our fitness, and with our respective backgrounds in business and hospitality, the food industry was naturally appealing to us. We specifically chose the prepared meal delivery business because in 2015, with our busy corporate jobs, we struggled to meal prep every week and couldn’t find healthful meal delivery options. We wanted to eat balanced, nutritious food that was also flavorful. 

Bootstrapping the side hustle with $2,500

What were some of the first steps you took to get your side hustle off the ground? How much money did it take to launch?
I didn’t want to borrow money, so we completely bootstrapped the business. I used $2,500 from my savings to get a website developed, hire a chef on an hourly basis and rent a kitchen space. Then, we set up an Instagram account and started posting about the business and gradually getting followers. Next, we reached out to fitness influencers because initially we struggled to get orders. We cold-messaged people on Instagram who might want free meals in exchange for a review of our service. That’s how we got our first few customers.


Source link

Former UPS Employee’s ‘Flavorful’ Side Hustle Hit $30K a Month Read More »

How Monopoly Taught Me the Business Mistakes That Keep Entrepreneurs From Building Real Wealth

How Monopoly Taught Me the Business Mistakes That Keep Entrepreneurs From Building Real Wealth


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Track how every dollar of revenue is allocated against target percentages for labor, inventory and facilities, so you can spot problems before they become a cash crisis.
  • Focus your resources on the opportunities where you have the strongest advantage, and judge success by whether the business is becoming a more valuable asset, not just by how much revenue it brings in.

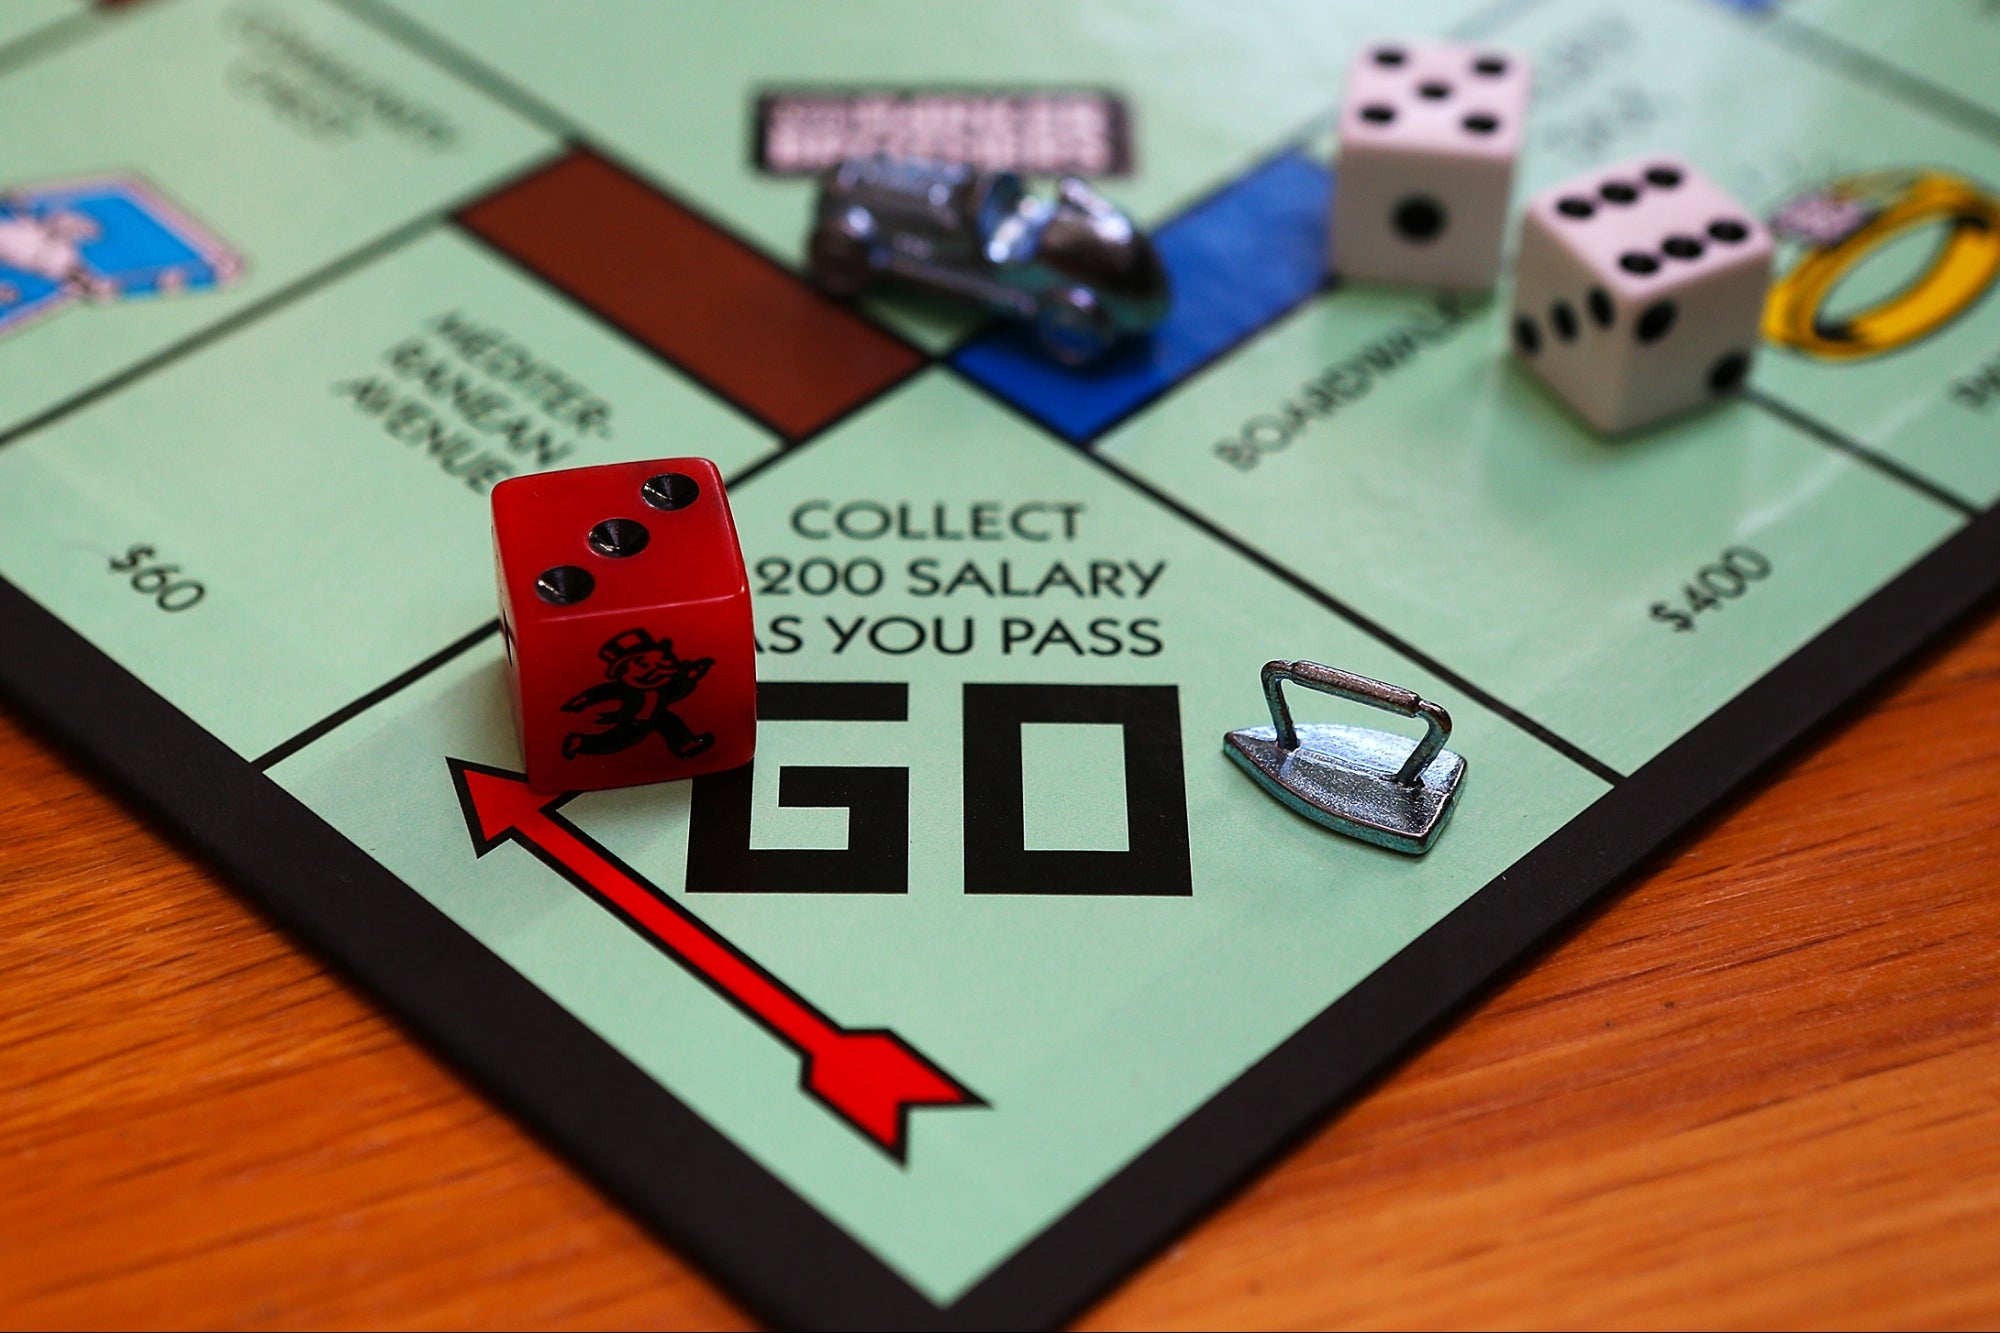
You never forget your first big win in business. Mine came in the form of my first victory over my older brother in Monopoly. The game turned 90 last year, and it remains one of the greatest, most ubiquitous and supremely frustrating games of all time. For nearly a century, Monopoly has taught all of us ages 8 and up how to think about money.

Buy properties. Collect rent. Build houses. Accumulate wealth. Bankrupt your competitors. It’s one of the most successful board games ever created because its rules are simple and its objective is clear: Own the most, and you win. The problem is that many entrepreneurs carry those same rules into business.

Real business doesn’t reward the person who acquires the most assets. It rewards the leader who consistently makes better decisions. Success isn’t determined by a single big move. It’s shaped by thousands of small decisions that compound over time. Ironically, Monopoly hints at this from the start. Every player rolls the same dice, and no one controls the outcome. What separates players isn’t the roll. It’s what they do next.

Business works the same way. Markets shift. Customers leave. New competitors emerge. Economic conditions change. You don’t control those events, but you do control your response. After working with thousands of business owners, I’ve found that the entrepreneurs who consistently outperform their peers share three habits.

1. Know the board before you roll

My first sweet Monopoly victory over my brother came after I learned two invaluable lessons: Whoever controls the bank controls the game, and my brother cheats at board games. Everyone remembers the anticipation of rolling the dice. A lucky roll lands you on an unowned property. An unlucky one checks you into a competitor’s luxury hotel.

But the game was designed long before you picked up the dice. The spaces have different values. Some properties are easier to build on. Some cost more to own. The odds of landing on each space can be calculated. Luck matters, but statistics shape the game before your turn begins.

In business, one of your biggest decisions happens before you open the doors: choosing which game to play. Every industry comes with a built-in financial structure. A hospitality business may carry significant facilities, labor and inventory costs before the first customer walks in. A professional services firm can start with far less overhead. Both can become great businesses, but they start from very different places on the board.

That’s why controlling the bank, or knowing exactly where every dollar goes, matters so much. With clients, I build a financial scorecard using what I call TAPs, or target allocation percentages. Instead of looking only at whether revenue went up or down, I want to know how every dollar is being allocated:

  • What percentage of revenue goes to labor?
  • How much is tied up in inventory?
  • What are you spending on facilities?
  • What should those percentages be for a healthy company in your industry?

Those targets give you something better than a gut feeling. They tell you whether the business is behaving the way you expected. If labor is supposed to consume 35% of revenue and you’re consistently running at 50%, that’s a signal. If facility costs eat up a larger share of revenue every quarter, you have reason to investigate before the problem becomes a cash crisis.

The economy will still shift. A key employee may resign. A competitor may enter your market. New technology may change what customers expect. Those are the dice rolls you can’t control. The founders who outperform their peers don’t make decisions based on hope or instinct. They make them based on data. Before your next major investment, ask:

  • What does the data say?
  • Which assumptions are facts, and which are opinions?
  • If I removed emotion from this decision, would I make the same choice?

Every entrepreneur gets lucky. Sustainable businesses are built by leaders who know what to do after the dice stop rolling.

2. Don’t buy every property

One of the first lessons Monopoly seems to teach is simple: If you land on an available property, buy it. In business, that strategy gets expensive.

You don’t need to offer the market every product or service it might buy from you. You need to understand your core competencies and become exceptionally good where you have the strongest advantage.

I learned a version of this playing Monopoly with my family. I noticed that people kept landing on the orange properties: St. James Place, Tennessee Avenue and New York Avenue. So I started targeting them every game. Instead of trying to own everything on the board, I focused my attention and cash on getting those properties. I started winning a lot more.

Years later, when I discovered game theory, I understood why. The orange properties sit just beyond Jail, and Monopoly has several ways of sending players there. When they leave, the odds created by two dice make certain rolls more likely than others. The board’s design makes those orange spaces especially valuable. I hadn’t stumbled onto a trick. I had identified where the opportunity was concentrated.

Entrepreneurs need the same discipline. Every new customer segment, service, location or acquisition competes for your attention, your team’s capacity and your cash. Just because you can sell something doesn’t mean your company should. Growth adds complexity, and complexity is where many businesses hit a breaking point. The goal is to know which opportunities deserve your resources and which ones pull you away from the business you’re best equipped to build.

Before you buy the next “property,” ask:

  • Does this strengthen our core business, and do we have a real advantage here?
  • Are our systems ready for this level of growth?
  • What will we stop doing to make room for it?

The best Monopoly players don’t need every property on the board. They need the right ones.

3. Passing GO isn’t the same as winning

Everyone loves collecting $200. It’s a reward, but it’s temporary.

In business, revenue feels like passing GO. It’s exciting. It builds momentum. It validates your hard work. But if all you measure is how much the business brings in each month or how much you take home at year’s end, you’re missing a much bigger part of the game. Business isn’t just an income game. It’s an asset game.

You didn’t take the risk of becoming an entrepreneur to build yourself another job. You’re building something that should grow more valuable over time. A healthy business produces income today while becoming an asset that can operate beyond its founder, generate cash flow and hold value for someone other than the person who started it.

That’s why revenue alone can mislead. I’ve met entrepreneurs running multimillion-dollar companies who still have to show up every day for the business to function. If they stop working, decisions stop getting made, customers stop getting served and revenue starts disappearing. They’ve created a great income, but they haven’t finished building the asset.

The shift happens when you focus on what the business does with the money after it passes GO. Healthy businesses convert revenue into cash flow, invest that cash wisely, strengthen their systems and build value that compounds over time.

At the end of every month, ask:

  • Where did our cash actually go?
  • Which customers and investments produced the best returns?
  • What did we build this month that made the company more valuable?

Collecting revenue is satisfying. Building an asset is how entrepreneurship creates lasting wealth.

The die is cast

Monopoly ends when one player accumulates enough assets to bankrupt everyone else. Your goal in business shouldn’t be to eliminate competitors. It should be to build a company that creates value year after year, adapts as conditions change and makes better decisions than it did the year before.

Monopoly has lasted 90 years because it’s a brilliant game. Just remember that building a business requires a different set of rules. Everyone loves a good roll, but you’ll be remembered for the decisions you make when the dice don’t fall your way.

Key Takeaways

  • Track how every dollar of revenue is allocated against target percentages for labor, inventory and facilities, so you can spot problems before they become a cash crisis.
  • Focus your resources on the opportunities where you have the strongest advantage, and judge success by whether the business is becoming a more valuable asset, not just by how much revenue it brings in.

You never forget your first big win in business. Mine came in the form of my first victory over my older brother in Monopoly. The game turned 90 last year, and it remains one of the greatest, most ubiquitous and supremely frustrating games of all time. For nearly a century, Monopoly has taught all of us ages 8 and up how to think about money.

Buy properties. Collect rent. Build houses. Accumulate wealth. Bankrupt your competitors. It’s one of the most successful board games ever created because its rules are simple and its objective is clear: Own the most, and you win. The problem is that many entrepreneurs carry those same rules into business.

Real business doesn’t reward the person who acquires the most assets. It rewards the leader who consistently makes better decisions. Success isn’t determined by a single big move. It’s shaped by thousands of small decisions that compound over time. Ironically, Monopoly hints at this from the start. Every player rolls the same dice, and no one controls the outcome. What separates players isn’t the roll. It’s what they do next.


Source link

How Monopoly Taught Me the Business Mistakes That Keep Entrepreneurs From Building Real Wealth Read More »

This Husband-Wife Duo Made 0,000 in Revenue in a Minute

This Husband-Wife Duo Made $500,000 in Revenue in a Minute


Key Takeaways

  • Allie and Hunter Taylor launched baby carrier brand Mabē in November 2023.
  • The husband-wife founders funded their first product order with their own savings rather than raising outside capital.
  • Mabē framed its product around helping parents feel confident, hands-free and able to keep pursuing their routines and ambitions.

For Hunter Taylor, the story of Mabē goes back “to the very beginning of time.” In other words, it starts in fourth grade when he met Allie Taylor for the first time. 

“I was always in love with Allie,” he tells Entrepreneur. “I just knew that she was my soulmate, that we could do anything together that we put our minds to — I felt like we could tackle the world together.”

The childhood sweethearts got married and, in 2022, became first-time parents. They quickly found a glaring gap in the market for baby carriers. 

Allie and Hunter Taylor. Credit: Mabē
Allie (left) and Hunter Taylor (right). Credit: Mabē

Allie was the first to notice the problem. She had trouble finding a carrier that was both functional and fashionable at an accessible price point. 

She mentioned it to Hunter several times, and he finally went looking for baby carriers himself. He quickly found that there was a gap in the market in terms of price point, aesthetics and messaging components. He also couldn’t find a product that checked all three boxes.

“I just remember in that moment feeling so convicted that we were the right people to do this,” Hunter says.

They were set on writing a different story for new moms

By early 2023, the two agreed that they wanted to create a premium baby carrier. Allie also saw an opportunity to reshape the conversation around what it meant to be a new mom. They decided to call their brand Mabē (pronounced maybe), and their brand name and logo are inspired by the monarch butterfly. 

“Our mission is simple: Provide a baby carrier that looks and feels incredible,” Allie wrote in a September 2023 Instagram post. “One that empowers you to continue doing everything you love, so you can keep chasing your dreams (whatever they mabē) with your hands free, and your baby in tow.”

Her desire to start the brand was also personal: She tells Entrepreneur she remembers feeling “really overwhelmed” as a new mom.

“I felt like everyone was just telling me that I’m gonna lose myself now that I’m a mom,” Allie says. “I was determined to write a different story, and I wanted to continue being who I was as a person in addition to being a mom.”

Carrying her baby changed the game

Allie says that carrying her baby in a carrier was “the ticket” or the “unlock” for her to have the confidence to do the things she used to do. Instead of having to worry about carrying around a car seat or a stroller, she could simply carry her baby on her chest. 

“The confidence that I had from wearing my baby on my chest was just unmatched,” she says. “However, the carrier that I had was just not the cutest thing. As a new mom, you already are not always feeling your very best. Then you layer on ugly baby gear, and it doesn’t help you feel better about yourself.”

Creating the product

The Taylors believed in the product — enough so that they invested hundreds of thousands in personal savings to bootstrap the brand.

To start, they identified manufacturers already experienced in making baby carriers. From there, they went through a months-long sampling process, testing fabrics, adjusting design details and rejecting early versions.

“The first one we got was terrible,” Hunter says.

They continued working with manufacturers until they felt they had a version worth taking to market. The process moved relatively quickly: They came up with the idea in March 2023 and launched in November of that same year. The brand’s signature Monarch Carrier is designed to look more like a stylish accessory than utilitarian baby gear and is priced at around $129.

The Monarch Carrier. Credit: Mabē

Talking to the mom

The product was central, but Mabē’s growth strategy also depended heavily on Allie’s ability to create a brand voice that stood apart from traditional baby-product marketing. She focused on a customer’s identity and aspirations. 

“I acted like a big brand from the very beginning, even though it was just me behind my phone doing all of the posting,” she says.

In the early days, she tapped people in her hometown and small-business circle for help. A friend helped build the website. Another took the brand’s initial photography. She also built an Instagram account and an email list before launch.

Its marketing message was crafted to speak to mothers as individuals rather than as extensions of their babies. Allie says she regularly asks if a piece of content will resonate, help a customer see herself in it and make her feel something.

“Instead of saying something along the lines of, ‘Our carrier has three carry positions and is safety certified, and this is the fabric and this is all the different features of it,’” she says, “I’m talking to the mom and saying, ‘Look what you can do when you put this carrier on.’”

That could mean a stay-at-home parent moving more easily through the day or an entrepreneur building a side hustle with a baby on her chest. The product benefits still matter, but Allie sees them as secondary to the messaging.

“It’s like selling them who they can become and what’s possible if they believe in themselves and if they feel confident,” she says.

The messaging gained momentum. At the time of the interview, Mabē had 176,000 Instagram followers. The founders say social media and word-of-mouth drove initial demand. 

Selling out in a minute

Today, Mabē has grown into an eight-figure business in under three years, and its products recently landed at 1,700 Target stores. In 2026, the company is on pace to grow its revenue by more than 40% year-over-year. 

Mabē’s early rise with customers was also unusually fast. The founders disclosed that their first launch sold out within two hours. Later, shoppers kept asking for preorders, so they decided to test it for their third launch. 

Hunter remembers thousands of people waiting on Mabē’s website before the preorder began.

“Once we opened the preorder, orders started to roll in, and we sold out,” he says. 

The result was startling: Mabē sold thousands of carriers in under one minute, generating about $500,000 in revenue.

“We took all of that and put it back into production,” Hunter says. “That solved a lot of our cash flow problems without having to take outside funding.”

They chose to maintain quality — even at a loss

Fast growth also tested the company’s commitment to quality. During Mabē’s first Black Friday sale in 2024, the founders discovered that a batch of fabric did not have the texture and feel they wanted. The issue was not a safety concern, they say, but it fell short of the brand’s quality standards.

The company could have waited for customers to complain and replaced only the units connected to those complaints. Instead, it contacted affected customers proactively and sent replacement carriers to everyone at no cost.

The company replaced a few thousand products, a decision the founders estimate cost around $250,000.

For a young company coming off its biggest sales period, it was a difficult financial and logistical decision. But the Taylors viewed it as an investment in a long-term brand relationship rather than a short-term expense.

“The customer first,” Allie says. “It was always about the customer; it’s always about their satisfaction and making sure that we gave them the experience that they deserve.”

Hunter added that he never intended Mabē to be “a short-term sort of cash grab.”

“We want to build a dedicated business to make people feel empowered with the product and the brand that we’re building,” he says.

Key Takeaways

  • Allie and Hunter Taylor launched baby carrier brand Mabē in November 2023.
  • The husband-wife founders funded their first product order with their own savings rather than raising outside capital.
  • Mabē framed its product around helping parents feel confident, hands-free and able to keep pursuing their routines and ambitions.

For Hunter Taylor, the story of Mabē goes back “to the very beginning of time.” In other words, it starts in fourth grade when he met Allie Taylor for the first time. 

“I was always in love with Allie,” he tells Entrepreneur. “I just knew that she was my soulmate, that we could do anything together that we put our minds to — I felt like we could tackle the world together.”

The childhood sweethearts got married and, in 2022, became first-time parents. They quickly found a glaring gap in the market for baby carriers. 


Source link

This Husband-Wife Duo Made $500,000 in Revenue in a Minute Read More »

Scaling a Company Forces Founders to Make 3 Key Shifts

Scaling a Company Forces Founders to Make 3 Key Shifts


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Early-stage companies often rely on the founder’s judgment, and for good reason. But as you grow, you have to learn to delegate to give your team the confidence to make decisions without you.
  • Don’t just hire people to execute — hire people who genuinely want to learn.
  • Give your employees enough trust to surprise you with the way they step up to the plate.

When I started Infragistics, I was used to solving problems myself. That was partly because I had to. We were a small company with limited resources and few people to hand things off to. If a task needed to get done, I did it. If a decision needed to be made, I made it. If something went wrong, I jumped in and fixed it.

Those instincts served me well and helped me build a company from a 10-person startup into a global organization with hundreds of employees across six countries. But eventually, they stopped serving me.

The bigger Infragistics became, the more I realized that being the person with all the answers was actually becoming a limitation. I couldn’t be in every meeting, make every decision or personally solve every problem. More importantly, if I kept doing those things, I was preventing other people from developing the judgment and confidence to do it themselves.

That was one of the hardest transitions of my career. I realized that the skills I had relied on to build the company were not necessarily the skills I needed to lead it. Over 35 years, I’ve had to rethink how I manage, how I develop people and how much control I’m willing to give up. I’ve learned that scaling a company requires a founder to make three fundamental shifts.

1. Stop being the only person with all the answers

Early-stage companies often revolve around the founder’s judgment, and there’s good reason for that. Founders are deeply involved in the product, the customers and the day-to-day business. Decisions get made quickly because they don’t have to travel through layers of approval, and that speed is often a real advantage when trying to get ahead of the competition.

But most founders are also, without realizing it, running a command-and-control organization. The leader sets the direction, makes the decisions and expects the team to execute. It works when the company is small enough to manage directly, but as the company grows, people stop bringing problems forward because they expect to be told what to do anyway. The organization becomes dependent on one person’s judgment at the exact moment it needs to be building more of it. And the founder who was once the engine of the company becomes the bottleneck. 

Eventually, a founder’s job is no longer to have the best answer, but to help other people develop the ability to find the best answer. That shift requires moving from command-and-control to coaching. Coaching isn’t about telling people what to do, but about helping people understand why a decision needs to be made and giving them the tools to make better decisions themselves. It builds judgment over time rather than substituting someone else’s. Done consistently, it creates a team that can operate, adapt and lead without the founder in the room.

2. Stop hiring people to execute and start hiring people who want to learn

Most hiring decisions focus on what someone can do right now. Can they handle the role? Do they have the relevant experience? Those are reasonable questions, but as a company grows, the answers become less obvious. Everything from markets and technology to customers can change drastically in the course of a year, and the skills that once made someone an excellent hire may not be the skills the company needs from them down the line. A team built entirely around execution, and around people who are very good at doing what they are told, will struggle to adapt when the ground shifts.

That’s why curiosity matters as much as capability. Leaders who build learning cultures start at the hiring stage. The questions worth asking in an interview are not just about what someone has done, but about how they think and whether they are actively invested in their own growth. 

Once those individuals are hired, the other half of the equation is investing in their curiosity. That means giving people a real budget for learning — conferences, courses, advanced degrees — and building development plans that take their growth seriously. 

A company cannot stay competitive by relying only on the knowledge it already has, and the founders who scale are the ones who hire for who someone can become, not just what they can do on day one. 

3. Give people enough trust to surprise you

Control feels safe, especially when the stakes are high. But a company can’t scale what only one person can manage, and at some point, the need for speed and the need for control become incompatible. 

Real delegation requires trust, and trust requires accepting that people will sometimes do things differently than you would. And while different can feel intimidating, it doesn’t mean the approach is worse. Founders who can’t tolerate change or a different way of thinking tend to pull decisions back toward themselves, which trains their teams to stop taking initiative and wait for direction. 

Building trust means giving people responsibility before it feels completely comfortable, letting them make decisions and resisting the urge to step in every time the approach differs from your own. At the end of the day it’s not about the path to a goal. What’s most important is that the goal is met. 

Trust is also cultivated when leaders model the behavior they want to see. If a leader can’t be challenged, no one else will feel comfortable challenging bad ideas. If a leader cannot admit mistakes, employees will learn to hide theirs. And if people do not feel safe disagreeing, the organization loses some of its best thinking.

The strange paradox of building a company is that the instincts that make a great founder are eventually the same ones that have to be unlearned. The founders who scale aren’t the ones who hold on to control the longest, but are the ones who build people who can think for themselves, create a culture that rewards curiosity and establish enough trust that the organization can make good decisions even when the founder isn’t in the room.

Key Takeaways

  • Early-stage companies often rely on the founder’s judgment, and for good reason. But as you grow, you have to learn to delegate to give your team the confidence to make decisions without you.
  • Don’t just hire people to execute — hire people who genuinely want to learn.
  • Give your employees enough trust to surprise you with the way they step up to the plate.

When I started Infragistics, I was used to solving problems myself. That was partly because I had to. We were a small company with limited resources and few people to hand things off to. If a task needed to get done, I did it. If a decision needed to be made, I made it. If something went wrong, I jumped in and fixed it.

Those instincts served me well and helped me build a company from a 10-person startup into a global organization with hundreds of employees across six countries. But eventually, they stopped serving me.

The bigger Infragistics became, the more I realized that being the person with all the answers was actually becoming a limitation. I couldn’t be in every meeting, make every decision or personally solve every problem. More importantly, if I kept doing those things, I was preventing other people from developing the judgment and confidence to do it themselves.


Source link

Scaling a Company Forces Founders to Make 3 Key Shifts Read More »

How Small Teams Can Beat Big Competitors With the Right AI Use

How Small Teams Can Beat Big Competitors With the Right AI Use


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • AI can help small teams punch above their weight, but this doesn’t mean using AI for its own sake.
  • The best AI-native playbook involves validating AI performance data, holding AI accountable and using it in ways that don’t bury your human employees in time-consuming new review tasks.

You know the competitor with three times your people and three times your budget. Sooner or later, that gap makes you wonder, “Do I have to hire the way they hire to keep up?”

Most of the time, you don’t.

Y Combinator CEO Garry Tan told CNBC that companies are reaching as much as $10 million in revenue with teams of fewer than ten people. “You don’t need a team of 50 or 100 engineers,” he said. Base44, a bootstrapped app builder with eight employees, sold to Wix for $80 million six months after launch.

Small teams can win with an AI-first playbook

As the founder of a 20-person AI company with much bigger competitors, I believe AI can help small teams punch above their weight. But this doesn’t mean using AI for its own sake.

Instead, the best AI-native playbook involves validating AI performance data, holding AI accountable and using AI in ways that don’t bury humans in time-consuming new review tasks.

The strategies below require discipline rather than large teams or big budgets, and you can start them today.

Verify AI-reported performance data

Every AI tool gives you a dashboard of hours saved and output produced. I ignore those numbers because they measure volume. A rising volume line can mean progress or a growing pile of busywork.

When the code analytics firm GitClear studied 211 million changed lines of code, it found copy-pasted code exceeding refactored code for the first time in 2024 and tied the shift to AI coding assistants. More lines shipped, and more of them were duplicates someone will have to maintain.

Tracking how quickly you hit roadmap goals is a better way to assess AI’s impact. A feature slated for late in the third quarter that ships in mid-April has pulled you roughly 170 days forward. Log planned versus actual dates for your next three roadmap items, and keep ignoring the dashboard.

Build prototypes instead of lengthy feature documents

In my experience, the fastest agent-era teams spend more time deciding and less time documenting.

At my company, we used AI to eliminate lengthy proposal documents. When someone has a new idea, they use AI to prototype it fast. Then the team plays with it and makes a go/no-go decision in an hour. You can do this, too.

Write a one-page contract before an agent writes code

Once a feature is approved, we give the coding agent a lean, one-page document naming what the feature does, the data it touches, the interfaces it exposes and the ways it can fail.

A specific, well-written contract dramatically increases code quality and reduces your time-to-ship. A poorly written or missing contract slows you down: Auditing and fixing bad code costs more than the agent saved.

A 2025 Faros AI study of 10,000-plus developers found teams with high AI adoption completing 21% more tasks while code review time rose 91% and bug rates rose 9%.

Require the one-page contract this week for any agent-generated work.

Let automated gates and agents do preliminary reviews

The top frustration with AI tools in the 2025 Stack Overflow Developer Survey, named by 66 percent of developers, was solutions that are “almost right, but not quite.”

Most teams counter these buggy solutions by adding more human review at every stage. I think that instinct can be counterproductive.

Consistent automated testing, built as a series of deterministic gates, frees humans from the first line of review. That can mean requiring a compiler, type checker, linter and a full test suite in front of every merge, then letting agents attack each change like an adversary.

We do this at my company, and the result is cleaner code. My development team spends more time architecting tests and defining outcomes than combing through code. Make one gate non-negotiable, starting with your next merge.

Rank work by what it changed for users

AI made output cheap, and cheap output breaks scoreboards. Commits, tickets, drafts and decks inflate overnight while nothing changes for your customers.

I call this comfort work. It looks and feels productive but doesn’t advance any goal, and AI multiplies it because iterations are nearly free.

Attach a verifiable test to every goal that a stranger could check. “Checkout conversion crossed 4% and held for 30 days” is verifiable. Anyone can look it up. “Improved the funnel” is vague and can’t be validated.

Rank each project against these tests instead of by number of artifacts, and your team learns fast that shipping only counts when it affects a goal.

Use AI for your hardest decisions

The widest gap between a small team and a big one is how quickly they can make good decisions. Big teams have more data and expertise, so they more often choose the right path. Small teams can close the gap by using AI for decision support.

To get an unbiased answer and catch AI fabrications, ask several models the same question. Each has its own map of the world, so the places where they agree suggest a consensus.

Then have one model, or a skeptical teammate, try to discredit that consensus. Consensus tells you what’s popular. Verification tells you what’s true.

At my company, questions that once took a senior researcher a week now come back that morning. Run your next category bet or pricing call through this before the meeting that decides it. It is the throughline of what we’re building: as more buyers and their AI assistants ask whether they can trust a recommendation, the advantage goes to whoever can verify what the model only guesses at.

Discipline is the moat

A competitor with three times your people carries roughly nine times the coordination cost. Fred Brooks named the law a half-century ago in The Mythical Man-Month. “Adding manpower to a late software project makes it later.”

Every new hire coordinates with everyone already there, so working relationships multiply faster than headcount. Five people have 10 of them. A hundred have nearly 5,000.

Shopify runs hiring on this math. CEO Tobi Lütke told his teams to demonstrate why AI cannot do a job before asking for more headcount.

The teams that rebuild around these six shifts win the decade. The ones that wait will spend it catching up to teams a third their size.

Key Takeaways

  • AI can help small teams punch above their weight, but this doesn’t mean using AI for its own sake.
  • The best AI-native playbook involves validating AI performance data, holding AI accountable and using it in ways that don’t bury your human employees in time-consuming new review tasks.

You know the competitor with three times your people and three times your budget. Sooner or later, that gap makes you wonder, “Do I have to hire the way they hire to keep up?”

Most of the time, you don’t.

Y Combinator CEO Garry Tan told CNBC that companies are reaching as much as $10 million in revenue with teams of fewer than ten people. “You don’t need a team of 50 or 100 engineers,” he said. Base44, a bootstrapped app builder with eight employees, sold to Wix for $80 million six months after launch.


Source link

How Small Teams Can Beat Big Competitors With the Right AI Use Read More »