November 2026

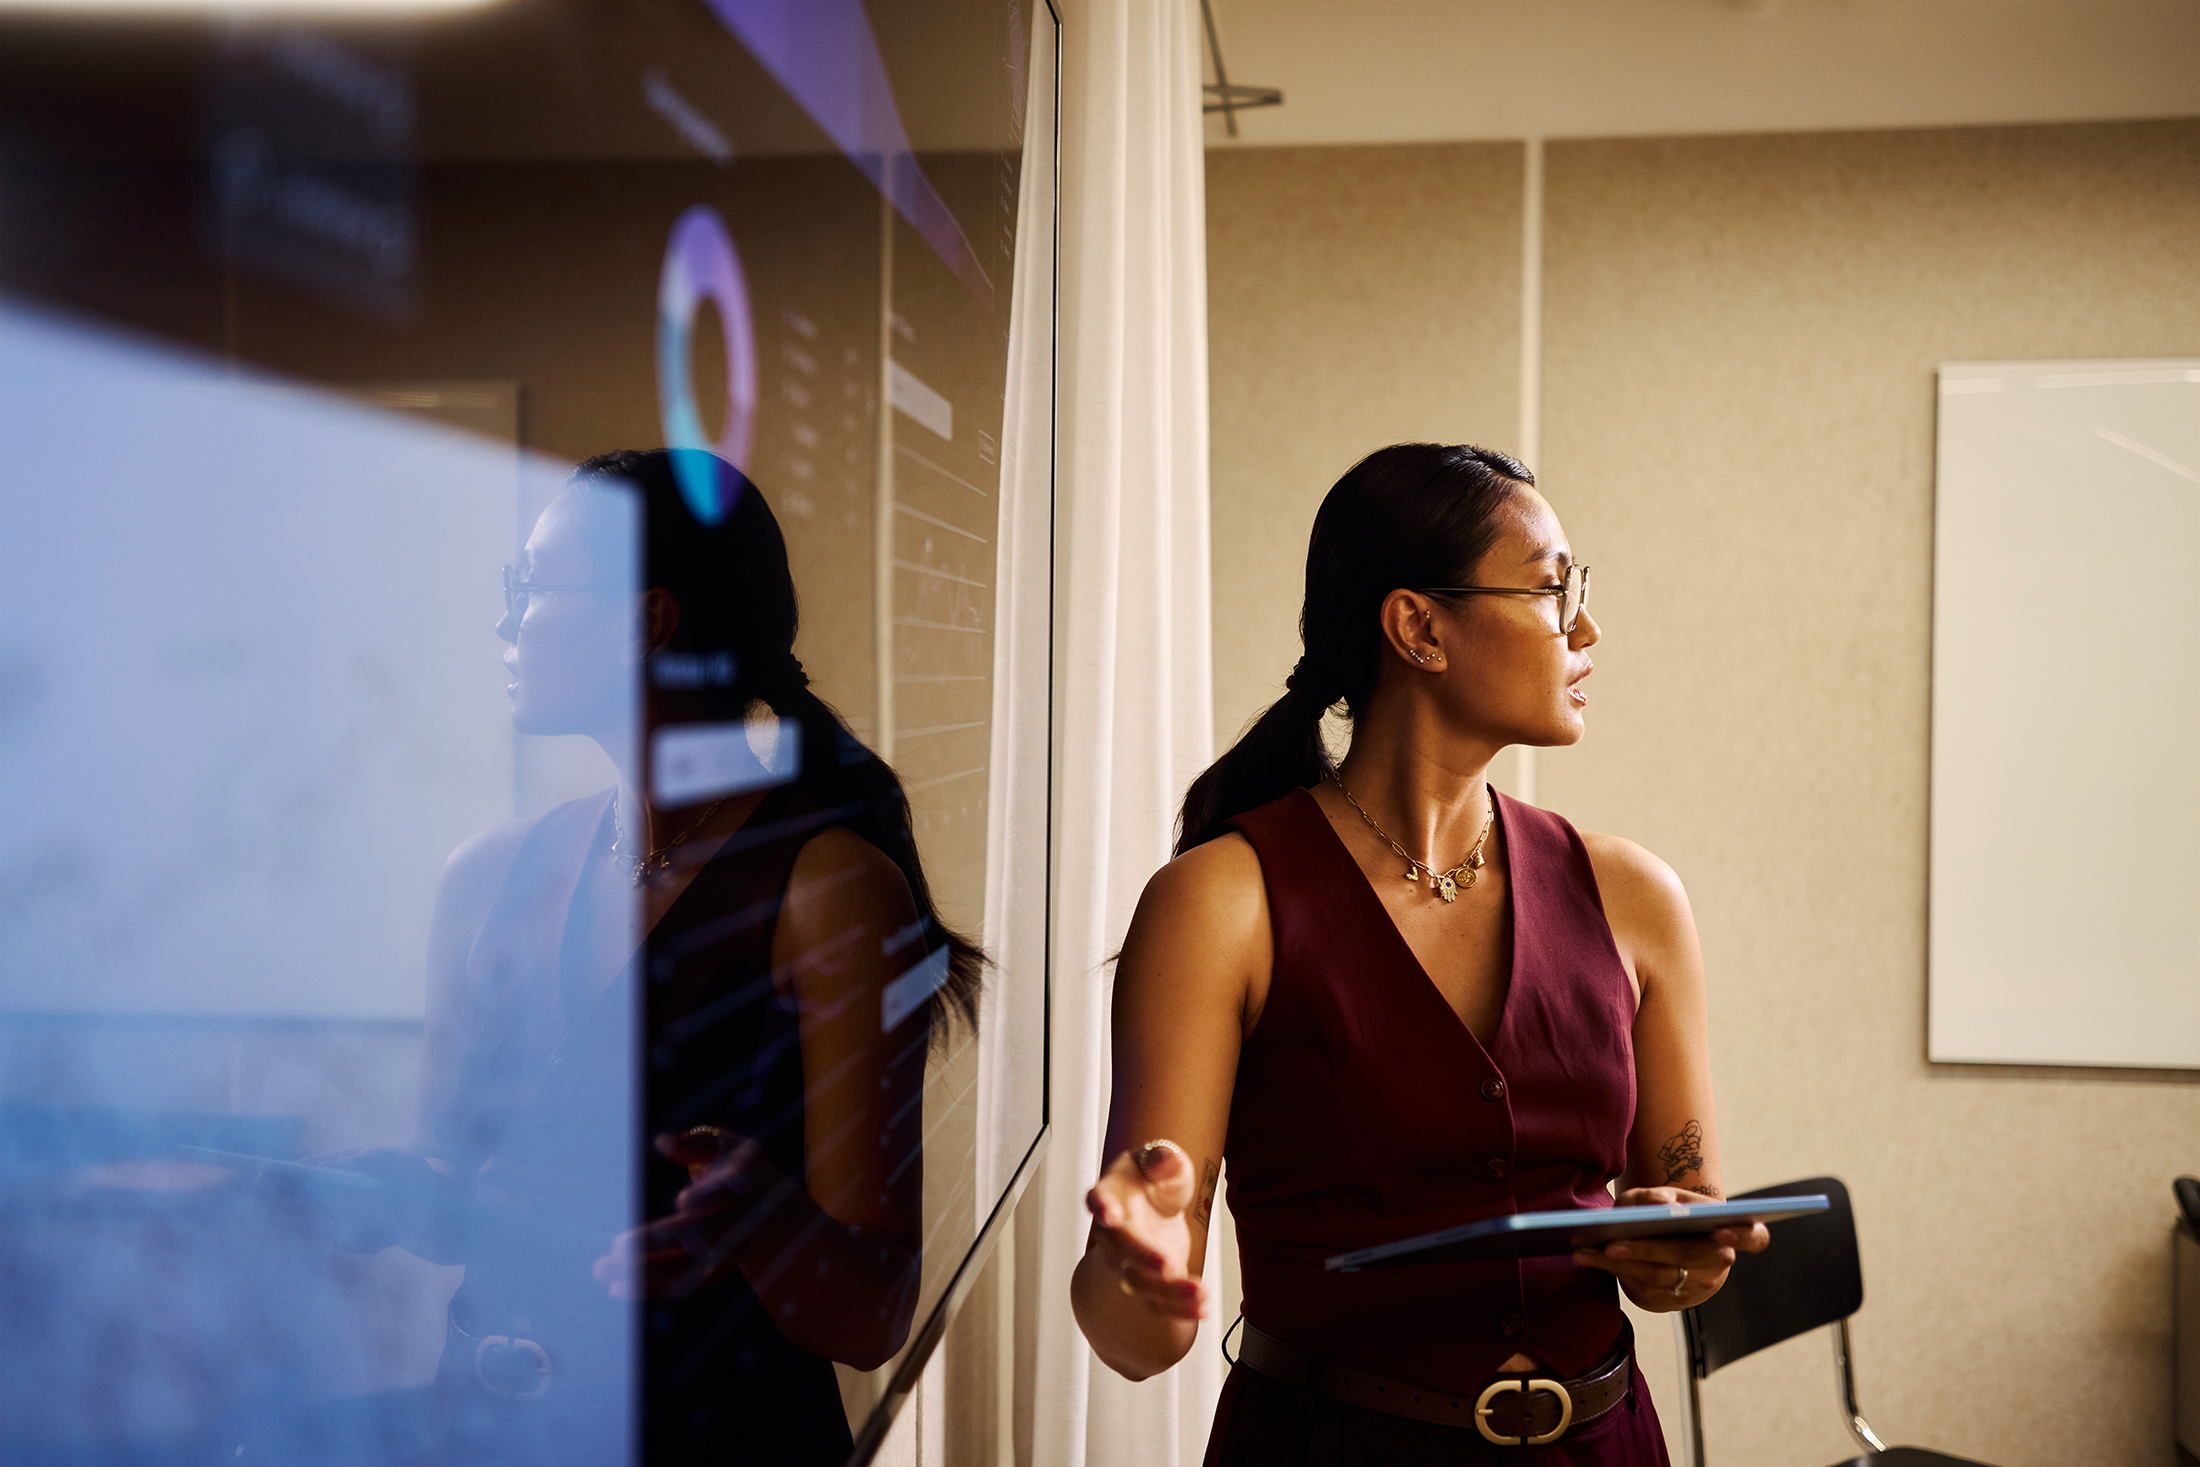
EBONY CEO Eden Bridgeman Tackles What’s Next in Media

EBONY CEO Eden Bridgeman Tackles What’s Next in Media


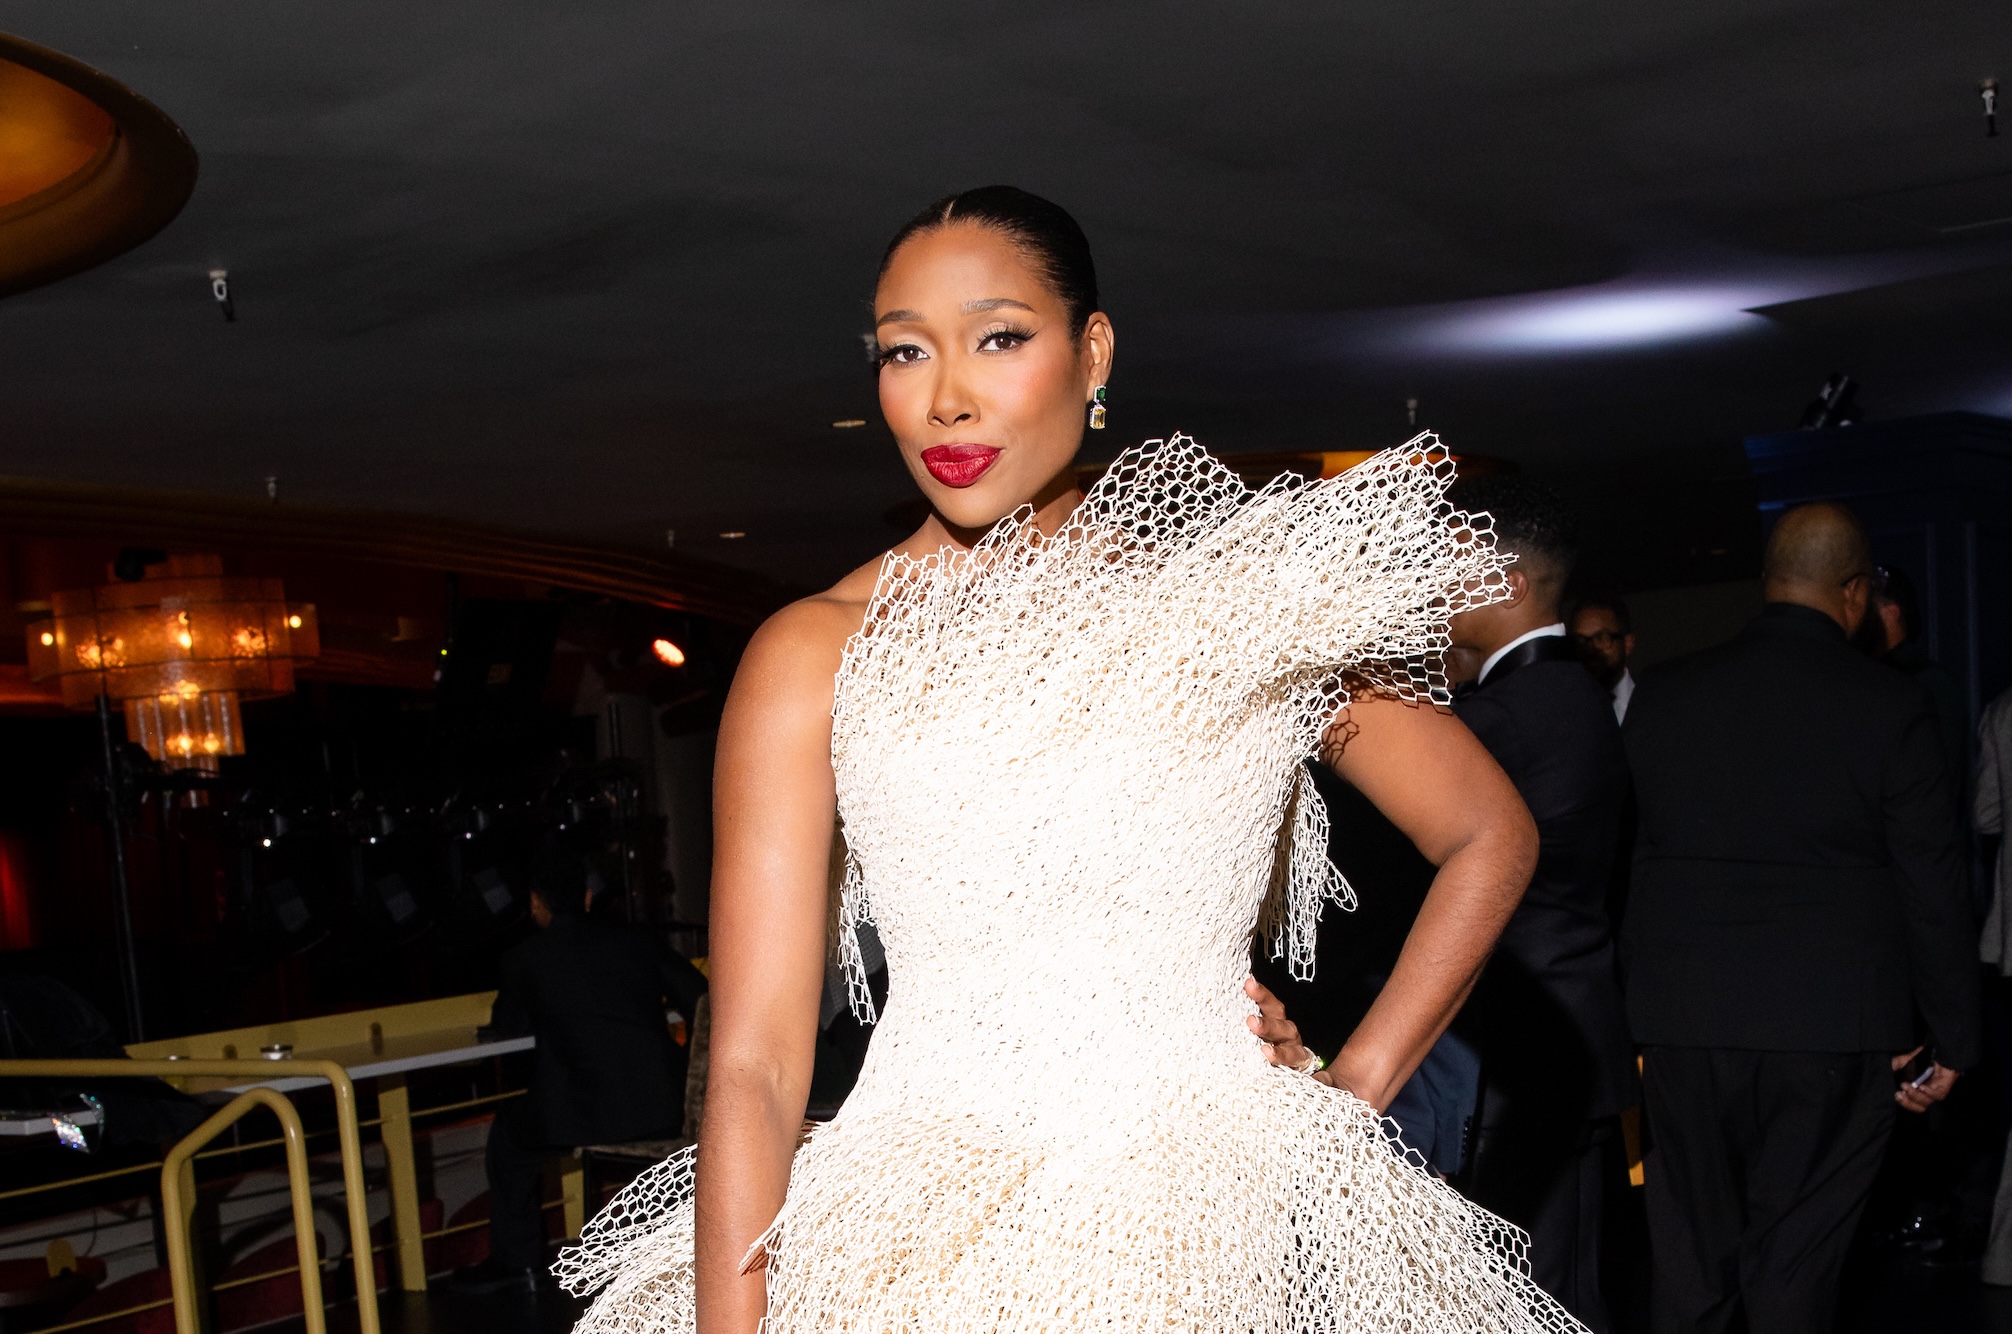
Eden Bridgeman began her working life with shifts at Wendy’s and Chili’s—jobs that taught her key lessons on a career path that put her in the driver’s seat of one of the most iconic brands in media history.

Bridgeman went on from working behind the counter to becoming the CMO of Manna, Inc., a restaurant franchise operator. And in 2021, after her father, the late Ulysses “Junior” Bridgeman, bought EBONY and JET at a bankruptcy auction in 2020, she took the reins of EBONY.

This fall, EBONY unveiled its 2026 Power 100 list, a class that stretches from Jay-Z and Byron Allen to iShowSpeed and a STEM kid creator, all celebrated at a gala at the Hollywood Palladium under the theme “The Stories We Shape.” One of the categories, the Junior Bridgeman Business Vanguard, is named in her father’s honor.

Following the event, Bridgeman shared her thoughts on leadership that serves your team, finding success in the attention economy and defining power that truly makes an impact.

As a teenager, you worked at Wendy’s and Chili’s. What is one specific habit or rule from those shifts that you still use as a CEO? 
One thing I learned very early is that the customer experiences the whole business, not your department. If something was wrong with an order, the customer did not care whether the mistake happened at the register, in the kitchen, or somewhere else. They simply knew the experience did not meet their expectations. Working in restaurants teaches you very quickly that everyone has some responsibility for the final outcome. Restaurants also taught me the importance of staying close to the business. You learn things from the front line that you cannot always see in a report.

You were CMO of a restaurant franchise operator, and then took over an 80-year old media brand. What surprised you most about the media business? 
Honestly, how many businesses exist inside of the media business. Coming from restaurants, there were certainly complexities, but the economic model was relatively clear. Media has a very different ecosystem. You have the audience consuming the product, advertisers funding parts of the business, platforms influencing distribution, creators and talent shaping relevance, technology affecting discovery, and increasingly commerce and experiences creating additional revenue opportunities. All of those constituencies matter, but they do not always want the same thing. 

That requires a different kind of discipline. One of the biggest lessons for me has been that attention and revenue are not the same thing. A piece of content can perform extremely well culturally and still not create meaningful business value unless you have built the right infrastructure around that attention. 
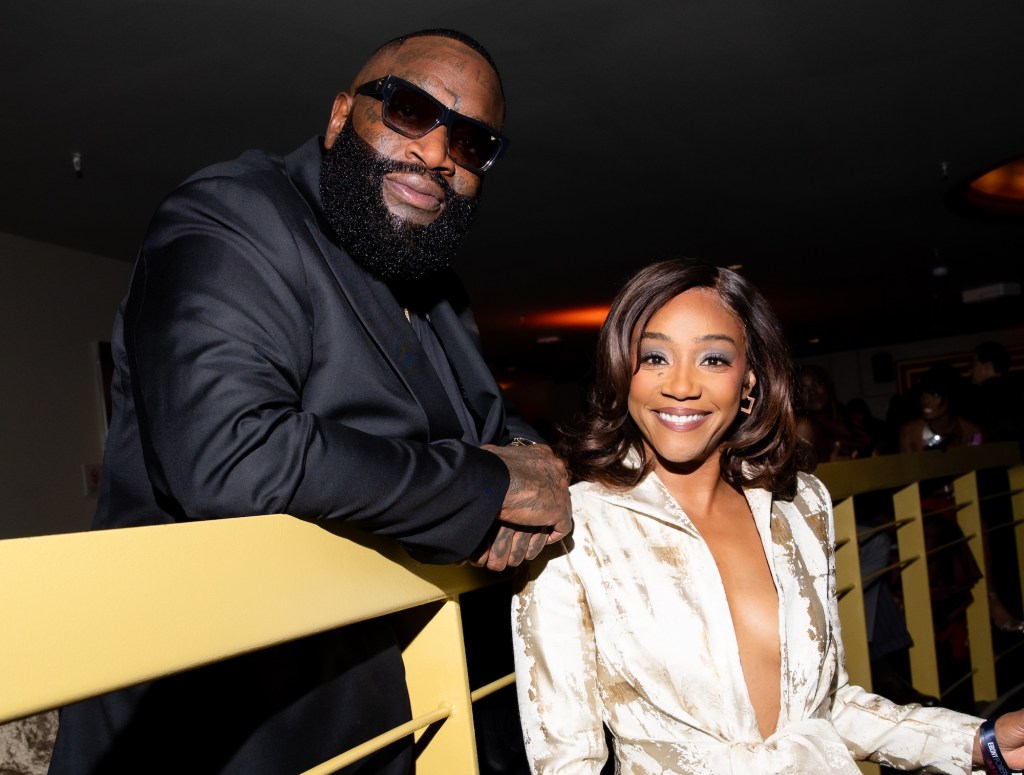
Rick Ross and Tiffany Haddish at the Power 100, photo credit: Jason Sean Weiss, BFA

What practices from the restaurant world do you think can apply to success in media? 
There are actually quite a few. The first is frequency. Restaurants understand that growth is not just about convincing somebody to visit once. The second is consistency. In restaurants, brand standards exist because people expect a certain experience every time they walk through the door. Media brands need that same clarity. And then there is measurement. Restaurant businesses are incredibly disciplined about understanding performance at a granular level. You know what is selling, when it is selling and where there are operational problems. I bring that mindset to EBONY because I believe creativity becomes more powerful when you understand its impact. 

Your father bought EBONY and JET at a bankruptcy auction in 2020. When you took over in 2021, what were the first things you fixed or rebuilt? 
I tend to be careful with the word “fixed,” because it can suggest that everything before you was wrong. That is not how I view EBONY. We inherited an extraordinary brand with generations of cultural equity, but the business around that brand had to operate in a fundamentally different media environment. So much of my focus has been on rebuilding the infrastructure necessary for EBONY to compete as a modern media company. That means strengthening how we operate, how we sell, how we develop partnerships, how we think about content and distribution, and how we measure whether the work is producing the outcomes we intended. 

But there was also a more philosophical question that had to be answered: What does it mean to modernize EBONY without disconnecting it from what made it important in the first place? There are generations of people who have a personal relationship with this brand. Then there is a younger generation whose relationship with media, culture and identity is completely different. My responsibility is not to choose between those audiences. It is to understand the fundamental truth that made EBONY matter historically and translate that truth into products, experiences and storytelling that feel relevant now. Legacy gives you permission to enter the conversation. Relevance determines whether people continue listening. 

Are there any leadership lessons or words of encouragement from your father that you think about regularly? 
I would describe it less as one particular quote and more as a leadership philosophy I learned from my father: the inverted pyramid. 

The idea is that leadership is not about positioning yourself at the top with everyone working up toward you. You turn the pyramid upside down. As a leader, your responsibility is to support the people doing the work and make sure they have what they need to be successful. 

That has stayed with me because it changes the way you think about leadership. A title may give you authority, but leadership is really about service, accountability and creating the conditions for other people to succeed. 

As CEO, I try to remember that my role is not to have every answer or to be the center of every decision. My responsibility is to provide clarity around where we are going, remove obstacles where I can, make the difficult decisions when necessary, and give the team the support and accountability they need to do their best work. 

I think that philosophy takes on another layer at EBONY. There is a responsibility to the people working to move the business forward, but also to the audience and community that have trusted this brand for generations. 

The higher you move in an organization, the more people you are responsible for serving, not the more people who are responsible for serving you. 

My father led humbly, as a servant leader, and that is the lesson from him I carry most directly into how I try to lead today. 
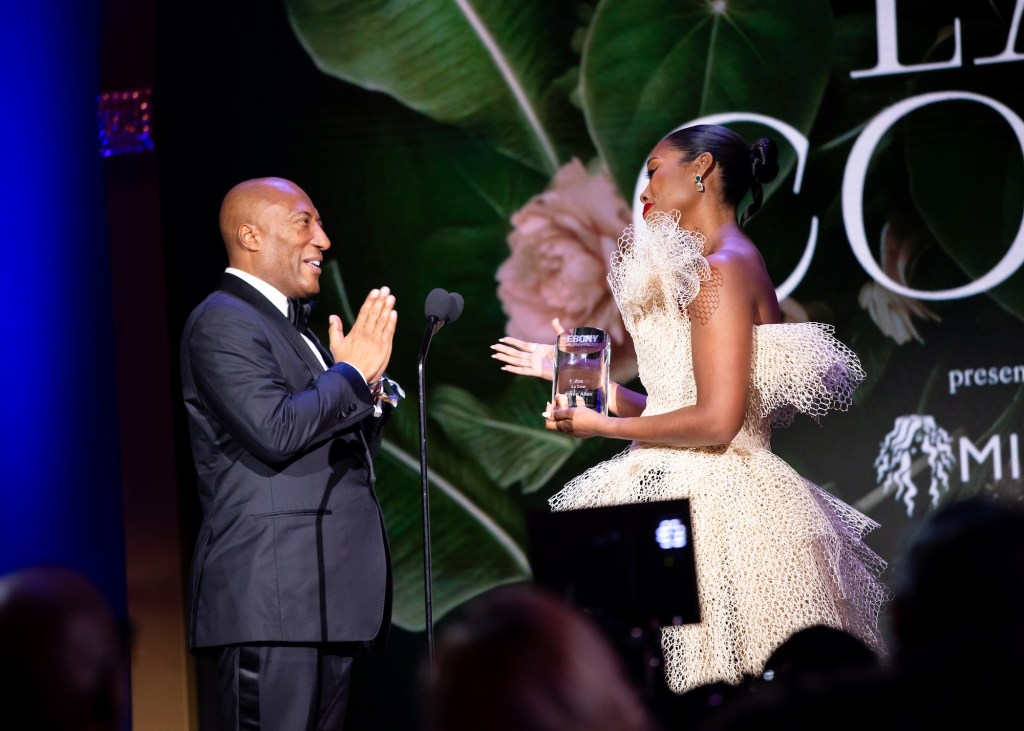
Byron Allen and Eden Bridgeman, photo credit: Jason Sean Weiss, BFA

Where do you think are the biggest opportunities for EBONY and other legacy media brands in today’s media landscape? 
I think the biggest opportunity is to stop defining a media company primarily by the content it publishes. Content will always be essential, but it can extend into original intellectual property, experiences, commerce, recommendations, partnerships and new forms of distribution. It can create opportunities for brands that want genuine cultural credibility. And it gives us the ability to convene communities both digitally and physically. 

I also believe there is significant opportunity in understanding audiences more deeply. Our history is an enormous competitive advantage, but history cannot become an excuse for standing still. Younger consumers are not obligated to love EBONY because their parents or grandparents did. We have to earn their relationship with the brand on their terms. 

If we can combine the trust and cultural authority built over generations with the technology, formats, distribution and business models available today, I think the opportunity is much larger than traditional publishing. 

The Power 100 honorees range from Jay-Z and Byron Allen to iShowSpeed and a STEM kid creator. How do you define “power”? 

I think power has become much more distributed. Traditionally, we tended to associate power with institutions: the person running the company, controlling capital, holding political office or deciding who gained access. Those forms of power still matter enormously. But technology and social platforms have created entirely different ways for people to build influence. 

A young person can create something from their bedroom and develop an audience larger than many traditional media outlets. A creator can introduce millions of people to an idea, product or cause almost instantly. An entrepreneur can build a community without first receiving permission from a traditional gatekeeper. 

That changes the way we should think about power. For EBONY, I think power is ultimately about the ability to create meaningful impact. Can you shift a conversation? Can you open a door that was previously closed? Can you build something that creates opportunity for other people? Can you influence how people see themselves or what they believe is possible? When I think about power today, I am interested not only in who has it, but what they are doing with it. 

Eden Bridgeman began her working life with shifts at Wendy’s and Chili’s—jobs that taught her key lessons on a career path that put her in the driver’s seat of one of the most iconic brands in media history.

Bridgeman went on from working behind the counter to becoming the CMO of Manna, Inc., a restaurant franchise operator. And in 2021, after her father, the late Ulysses “Junior” Bridgeman, bought EBONY and JET at a bankruptcy auction in 2020, she took the reins of EBONY.

This fall, EBONY unveiled its 2026 Power 100 list, a class that stretches from Jay-Z and Byron Allen to iShowSpeed and a STEM kid creator, all celebrated at a gala at the Hollywood Palladium under the theme “The Stories We Shape.” One of the categories, the Junior Bridgeman Business Vanguard, is named in her father’s honor.


Source link

EBONY CEO Eden Bridgeman Tackles What’s Next in Media Read More »
Your Reputation Audit Has a Blind Spot. Here’s How to Check It.

Your Reputation Audit Has a Blind Spot. Here’s How to Check It.


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Ask AI the questions your customers might ask.
  • Check whether AI recommends your company in your category.
  • Audit the CEO separately from the company, and separate criticism from factual problems. Find the source before trying to fix the answer.
  • Keep Google in the audit — and make sure you audit how your company generates reviews. Then track what changes.

Your customers can now investigate your company without visiting your website or clicking a traditional search result.

They can ask an AI platform to compare your company with competitors, summarize customer complaints, research your leadership and identify potential reasons not to do business with you. The resulting answer can shape an opinion before the customer reaches your website.

That changes what CEOs need to monitor. Google results, news coverage, reviews and social media still matter, but an online reputation audit in 2026 should also examine what AI platforms say about your business, which sources support those answers and whether inaccurate or outdated information keeps appearing.

Google reported this year that AI Overviews had more than 2.5 billion monthly active users and AI Mode had surpassed 1 billion monthly users. CEOs should account for this behavior in the same way they learned to pay attention to Google results and online reviews.

I work in online reputation management, and at my company Reputation Pros, we recommend treating a reputation audit as a recurring business process. You do not need sophisticated software to start. You just need the right questions and a system for recording what you find. Here is an audit I recommend.

1. Ask AI the questions your customers might ask

Typing your company name into an AI platform will not tell you enough. Instead, put yourself in the position of a prospective customer conducting due diligence. Ask questions that require the platform to explain what it knows about your company.

Start by copying and customizing this prompt: “I’m considering doing business with [COMPANY NAME]. Research its online reputation as a prospective customer would. Summarize what the company is known for, common positive themes, recurring complaints or criticisms, significant controversies and information that could reasonably affect a customer’s decision. Separate verified facts from allegations or opinions. Where possible, identify the sources supporting each important claim and flag information that may be outdated or uncertain.”

Run the same prompt through several major AI platforms. Do not focus solely on whether the answers sound positive or negative. Look for patterns.

Does the same complaint appear several times? Does one platform emphasize an old controversy? Does another describe your company incorrectly? Which publications, review sites or other sources appear repeatedly?

Record the results. One response does not define your reputation. Differences between platforms can show you where additional investigation is necessary.

2. Check whether AI recommends your company in your category

CEOs naturally focus on branded searches, but customers do not always begin there. Someone looking for a financial adviser, attorney, software company or home services provider may start by asking for reputable companies in a particular market. The customer may then compare two or three businesses before searching any company individually.

Test that part of the journey too. Use questions such as:

  • “What are reputable [CATEGORY] companies in [MARKET]?”
  • “Which [CATEGORY] companies should I consider for [SPECIFIC NEED]?”
  • “Compare [COMPANY] and [COMPETITOR] based on customer feedback, experience, reputation and publicly available information.”
  • “What should I investigate before hiring a [CATEGORY] company?”

Pay attention to how your company appears in those answers. Do not assume that an omission means something is wrong. Instead, investigate whether credible online sources clearly establish the expertise, history and services your company claims.

This exercise can reveal a problem that a branded Google search will miss: The information people find about your company may look fine, while the broader information environment barely associates your company with the category you want to lead.

3. Audit the CEO separately from the company

Customers are not the only people conducting online research. Potential employees, investors, vendors and business partners can investigate company leadership before making decisions. A CEO’s online reputation deserves its own audit.

Try this: “Research [CEO’S NAME] as if you were a potential business partner conducting due diligence. Summarize their professional background, current business affiliations, documented accomplishments, controversies, lawsuits or regulatory matters and recurring criticism. Distinguish verified facts from allegations and opinions. Identify the sources supporting significant claims and flag information that appears outdated, conflicting or uncertain.”

Check the basic facts first. Is the current position correct? Are former positions described as current? Are business affiliations accurate? Does the answer confuse the CEO with someone who has a similar name?

Do not ignore an error because it happens to make the CEO look good. An inaccurate award, inflated job title or incorrect company affiliation can create credibility problems just as easily as negative misinformation.

4. Separate criticism from factual problems

Executives sometimes see an unfavorable result and immediately ask how to remove it. Ask whether it is accurate first.

I use five simple classifications when examining reputation issues:

  • Accurate
  • Inaccurate
  • Outdated
  • Incomplete
  • Unverified

Those categories force you to distinguish between information that damages your reputation and information that you simply dislike.

A legitimate negative customer review requires a different response from a false claim about your company. An accurate article from six years ago requires a different approach from a biography that incorrectly lists an executive’s former employer.

AI can help organize this part of the audit. Copy a concerning response and ask: “Extract every factual claim in the following response that can be independently verified. Organize the claims by Claim, Source Cited, Verification Needed and Potential Business Impact. Do not assume a claim is accurate because it appears in the response.”

Then verify the important claims yourself using reliable sources. Do not use one AI system to declare another AI system correct. Use AI to identify what needs checking. Use primary and authoritative sources to determine what is true.

5. Find the source before trying to fix the answer

An unfavorable AI answer is often the symptom rather than the underlying problem. Investigate the sources behind it.

You may discover an outdated executive biography, an old news article, incorrect directory information, inconsistent company descriptions or customer complaints appearing across multiple sites. Ask the AI platform to show its work when the product supports citations.

You can also use this prompt: “Based only on the sources available in your answer, identify the sources that support the major claims about [COMPANY]. For each source, list the claim it supports, its publication date if available and whether newer authoritative information appears to conflict with it. Do not infer a source if you cannot identify one.”

Then open the sources. I consider this one of the most important steps in a modern reputation audit. Asking “How do we change this AI answer?” too early can send a company in the wrong direction.

Ask a better question: “Why does this information exist?” A factual problem at the source gives you something concrete to investigate.

6. Keep Google in the audit

AI has expanded reputation management, but it has not completely replaced traditional search yet.

Search your company name, executive names and relevant combinations such as your company plus “reviews,” “complaints,” “lawsuit” and other terms a prospective customer might reasonably use.

Look beyond position. A negative article does not become significant simply because it ranks highly. Determine its date, source, context and accuracy. Find out whether multiple independent sources support the underlying claim or whether dozens of pages repeat information originating from a single source.

The same principle applies to positive coverage. Ten websites repeating the same press release do not provide the same independent validation as 10 separate authoritative sources.

Your audit should measure the quality of the information surrounding your company, not simply count positive and negative links.

7. Audit how your company generates reviews

Review management creates another risk CEOs should examine. The Federal Trade Commission’s Consumer Reviews and Testimonials Rule took effect in October 2024. It addresses practices including fake or false reviews and incentives conditioned on a review expressing a particular positive or negative sentiment.

The FTC sent warning letters to 10 companies in December 2025 over potential violations of the rule and noted that violations can result in substantial civil penalties. Ask your marketing and customer service teams how they request reviews.

Are incentives involved? Does anyone ask specifically for a five-star review? Do employees write reviews? Does an outside vendor manage the process? Does anyone discourage dissatisfied customers from leaving legitimate feedback?

CEOs should understand the answers. I recommend one simple test: Could you comfortably explain your review-generation process to a regulator? If you hesitate, investigate it.

8. Track what changes

Finish the audit by creating a basic spreadsheet. You only need seven columns:

  1. Question
  2. Platform
  3. Key claims
  4. Sources
  5. Accuracy
  6. Risk
  7. Action

Run the same core questions every quarter and compare the findings.

Label accurate information and isolated criticism as issues to monitor. Investigate recurring inconsistencies, outdated information and unsupported claims. Prioritize consequential factual errors, impersonation and rapidly spreading false information for action.

Consistency matters more than complexity. The first audit tells you what your reputation looks like today. Repeating the process shows you where it is moving.

A company preparing for an acquisition, leadership change, product launch or other major event may need to run the audit more frequently. Most CEOs can start with a quarterly review and adjust based on the risks they uncover.

Your goal is not to make every search result positive or force every AI platform to praise your company. Neither goal is realistic. Your goal is to know what customers can discover about you, understand where that information comes from and correct factual problems where you legitimately can.

In 2026, people increasingly ask machines to help them evaluate businesses and the people running them. CEOs should know what those machines are finding before an important customer, employee or business partner asks.

Key Takeaways

  • Ask AI the questions your customers might ask.
  • Check whether AI recommends your company in your category.
  • Audit the CEO separately from the company, and separate criticism from factual problems. Find the source before trying to fix the answer.
  • Keep Google in the audit — and make sure you audit how your company generates reviews. Then track what changes.

Your customers can now investigate your company without visiting your website or clicking a traditional search result.

They can ask an AI platform to compare your company with competitors, summarize customer complaints, research your leadership and identify potential reasons not to do business with you. The resulting answer can shape an opinion before the customer reaches your website.

That changes what CEOs need to monitor. Google results, news coverage, reviews and social media still matter, but an online reputation audit in 2026 should also examine what AI platforms say about your business, which sources support those answers and whether inaccurate or outdated information keeps appearing.


Source link

Your Reputation Audit Has a Blind Spot. Here’s How to Check It. Read More »

Small Business Owners Have More AI Insight Than Ever — But It’s Stuck in Dashboards. Here’s How to Put It to Work.

Small Business Owners Have More AI Insight Than Ever — But It’s Stuck in Dashboards. Here’s How to Put It to Work.


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Most small businesses don’t lack workforce data; the problem is that insights live in separate dashboards instead of the tools where decisions get made.
  • AI is most valuable when it surfaces insights inside everyday workflows like payroll and scheduling, supporting human judgment instead of replacing it.

Small business owners have access to more workforce data than ever, and that data may hold insights hiding in plain sight. Most business leaders can track turnover, overtime, engagement, cost per hire and more on real-time dashboards. What they really need is the ability to turn that data into a decision before the moment that matters has passed.

That gap was highlighted in Paychex’s 2026 Business Leaders Priorities Report, which found that AI adoption and usage rank among the top challenges keeping businesses tied to slower, costlier processes. Many people assume the barrier is a lack of information. In reality, most small businesses already have plenty of workforce data and plenty of tools telling them what it means. The real barrier is speed and, increasingly, proof.

More data, same delay

HR leaders are now expected to justify workforce decisions to the C-suite as they happen, not just at the end of a quarter. Decisions are often made before a meeting ends. Leaders need a clear view of their workforce, including why a staffing or scheduling decision was made, before the change shows up on a P&L.

This is becoming a major pressure point for many small businesses, and it’s exposing a design flaw that has existed in workforce technology for years: Insight and action live in different places.

A dashboard can tell a business leader that something needs attention, but acting on it often means switching to another system. Every extra step gives the moment a chance to pass. By the time a decision is made, it’s reactive instead of strategic, and the leader defending it has to reconstruct the reasoning after the fact instead of pointing to it in the moment.

Consider a restaurant owner whose overtime costs are trending above budget. A dashboard might flag the issue, but if that insight only appears in a report reviewed days later, the costs may already be locked in. When the same insight surfaces in the scheduling system the owner or manager uses every day, they can review staffing levels and adjust sooner, before the trend becomes a bigger problem that takes longer to fix.

Where the insight lives changes what it’s worth

When workforce insight sits in a separate report or standalone dashboard, it competes with everything else on a leader’s plate that day. It’s one more tab, one more login, one more thing to remember to check. If a busy owner or manager doesn’t have time to act on an insight, it might as well not exist, and decisions that affect business outcomes get delayed or missed.

The businesses making faster, more defensible workforce decisions aren’t necessarily the ones with the most sophisticated analytics. They’re the ones that understand insight only matters if it shows up inside the systems people already use, like payroll, scheduling and time tracking.

When a scheduling conflict or compliance risk appears in a tool a manager uses every day, they can act on it immediately. When it appears somewhere else, they have to go looking for it, and most small business leaders don’t have that time.

This is where AI has the potential to change the equation. The most effective AI tools do more than generate reports or highlight trends. They proactively surface relevant insights, offer recommendations and deliver guidance within the workflows where managers already spend their time. AI is most valuable when it shortens the distance between knowing and doing, while giving people the context they need to apply their own judgment.

What acting on it actually requires

Small business leaders aren’t struggling because they lack workforce data. They’re struggling because valuable insights are often separated from the systems where workforce decisions actually happen. Closing that gap means being more deliberate about which data matters, where it needs to appear and who has the authority to act on it. It doesn’t mean simply adding another AI tool to the tech stack.

Start by auditing where your team’s data lives compared with where decisions actually get made. If those are two different places, that’s the first gap to close. Then look at how much of your workforce data requires a separate login or report to access. Every extra step is another chance for useful information to lose its relevance before it can inform a good decision.

Next, decide where AI can provide meaningful support without removing human judgment from the process. The goal isn’t to automate every workforce decision. It’s to give the right person the right information, in the right context, at the moment it’s most useful.

What separates the businesses that get this right has less to do with how much they invest in AI and more to do with whether workforce insight is built into the flow of daily work. As small business leaders face growing pressure to explain decisions in real time, speed, context and accountability are becoming real competitive advantages.

The next chapter of AI won’t be defined by how much information it can generate. It will be defined by how well it helps leaders make smarter, more timely decisions. Businesses that can move from insight to action faster, without sacrificing human judgment, will be better positioned to adapt to change, support their workforce and compete in an increasingly complex environment.

Key Takeaways

  • Most small businesses don’t lack workforce data; the problem is that insights live in separate dashboards instead of the tools where decisions get made.
  • AI is most valuable when it surfaces insights inside everyday workflows like payroll and scheduling, supporting human judgment instead of replacing it.

Small business owners have access to more workforce data than ever, and that data may hold insights hiding in plain sight. Most business leaders can track turnover, overtime, engagement, cost per hire and more on real-time dashboards. What they really need is the ability to turn that data into a decision before the moment that matters has passed.

That gap was highlighted in Paychex’s 2026 Business Leaders Priorities Report, which found that AI adoption and usage rank among the top challenges keeping businesses tied to slower, costlier processes. Many people assume the barrier is a lack of information. In reality, most small businesses already have plenty of workforce data and plenty of tools telling them what it means. The real barrier is speed and, increasingly, proof.

More data, same delay

HR leaders are now expected to justify workforce decisions to the C-suite as they happen, not just at the end of a quarter. Decisions are often made before a meeting ends. Leaders need a clear view of their workforce, including why a staffing or scheduling decision was made, before the change shows up on a P&L.


Source link

Small Business Owners Have More AI Insight Than Ever — But It’s Stuck in Dashboards. Here’s How to Put It to Work. Read More »

She Started a Small Gathering to Celebrate Women in Sports. Eight Years Later, The Sports Power Awards Are Sponsored by ESPN Films 

She Started a Small Gathering to Celebrate Women in Sports. Eight Years Later, The Sports Power Awards Are Sponsored by ESPN Films 


Opinions expressed by Entrepreneur contributors are their own.

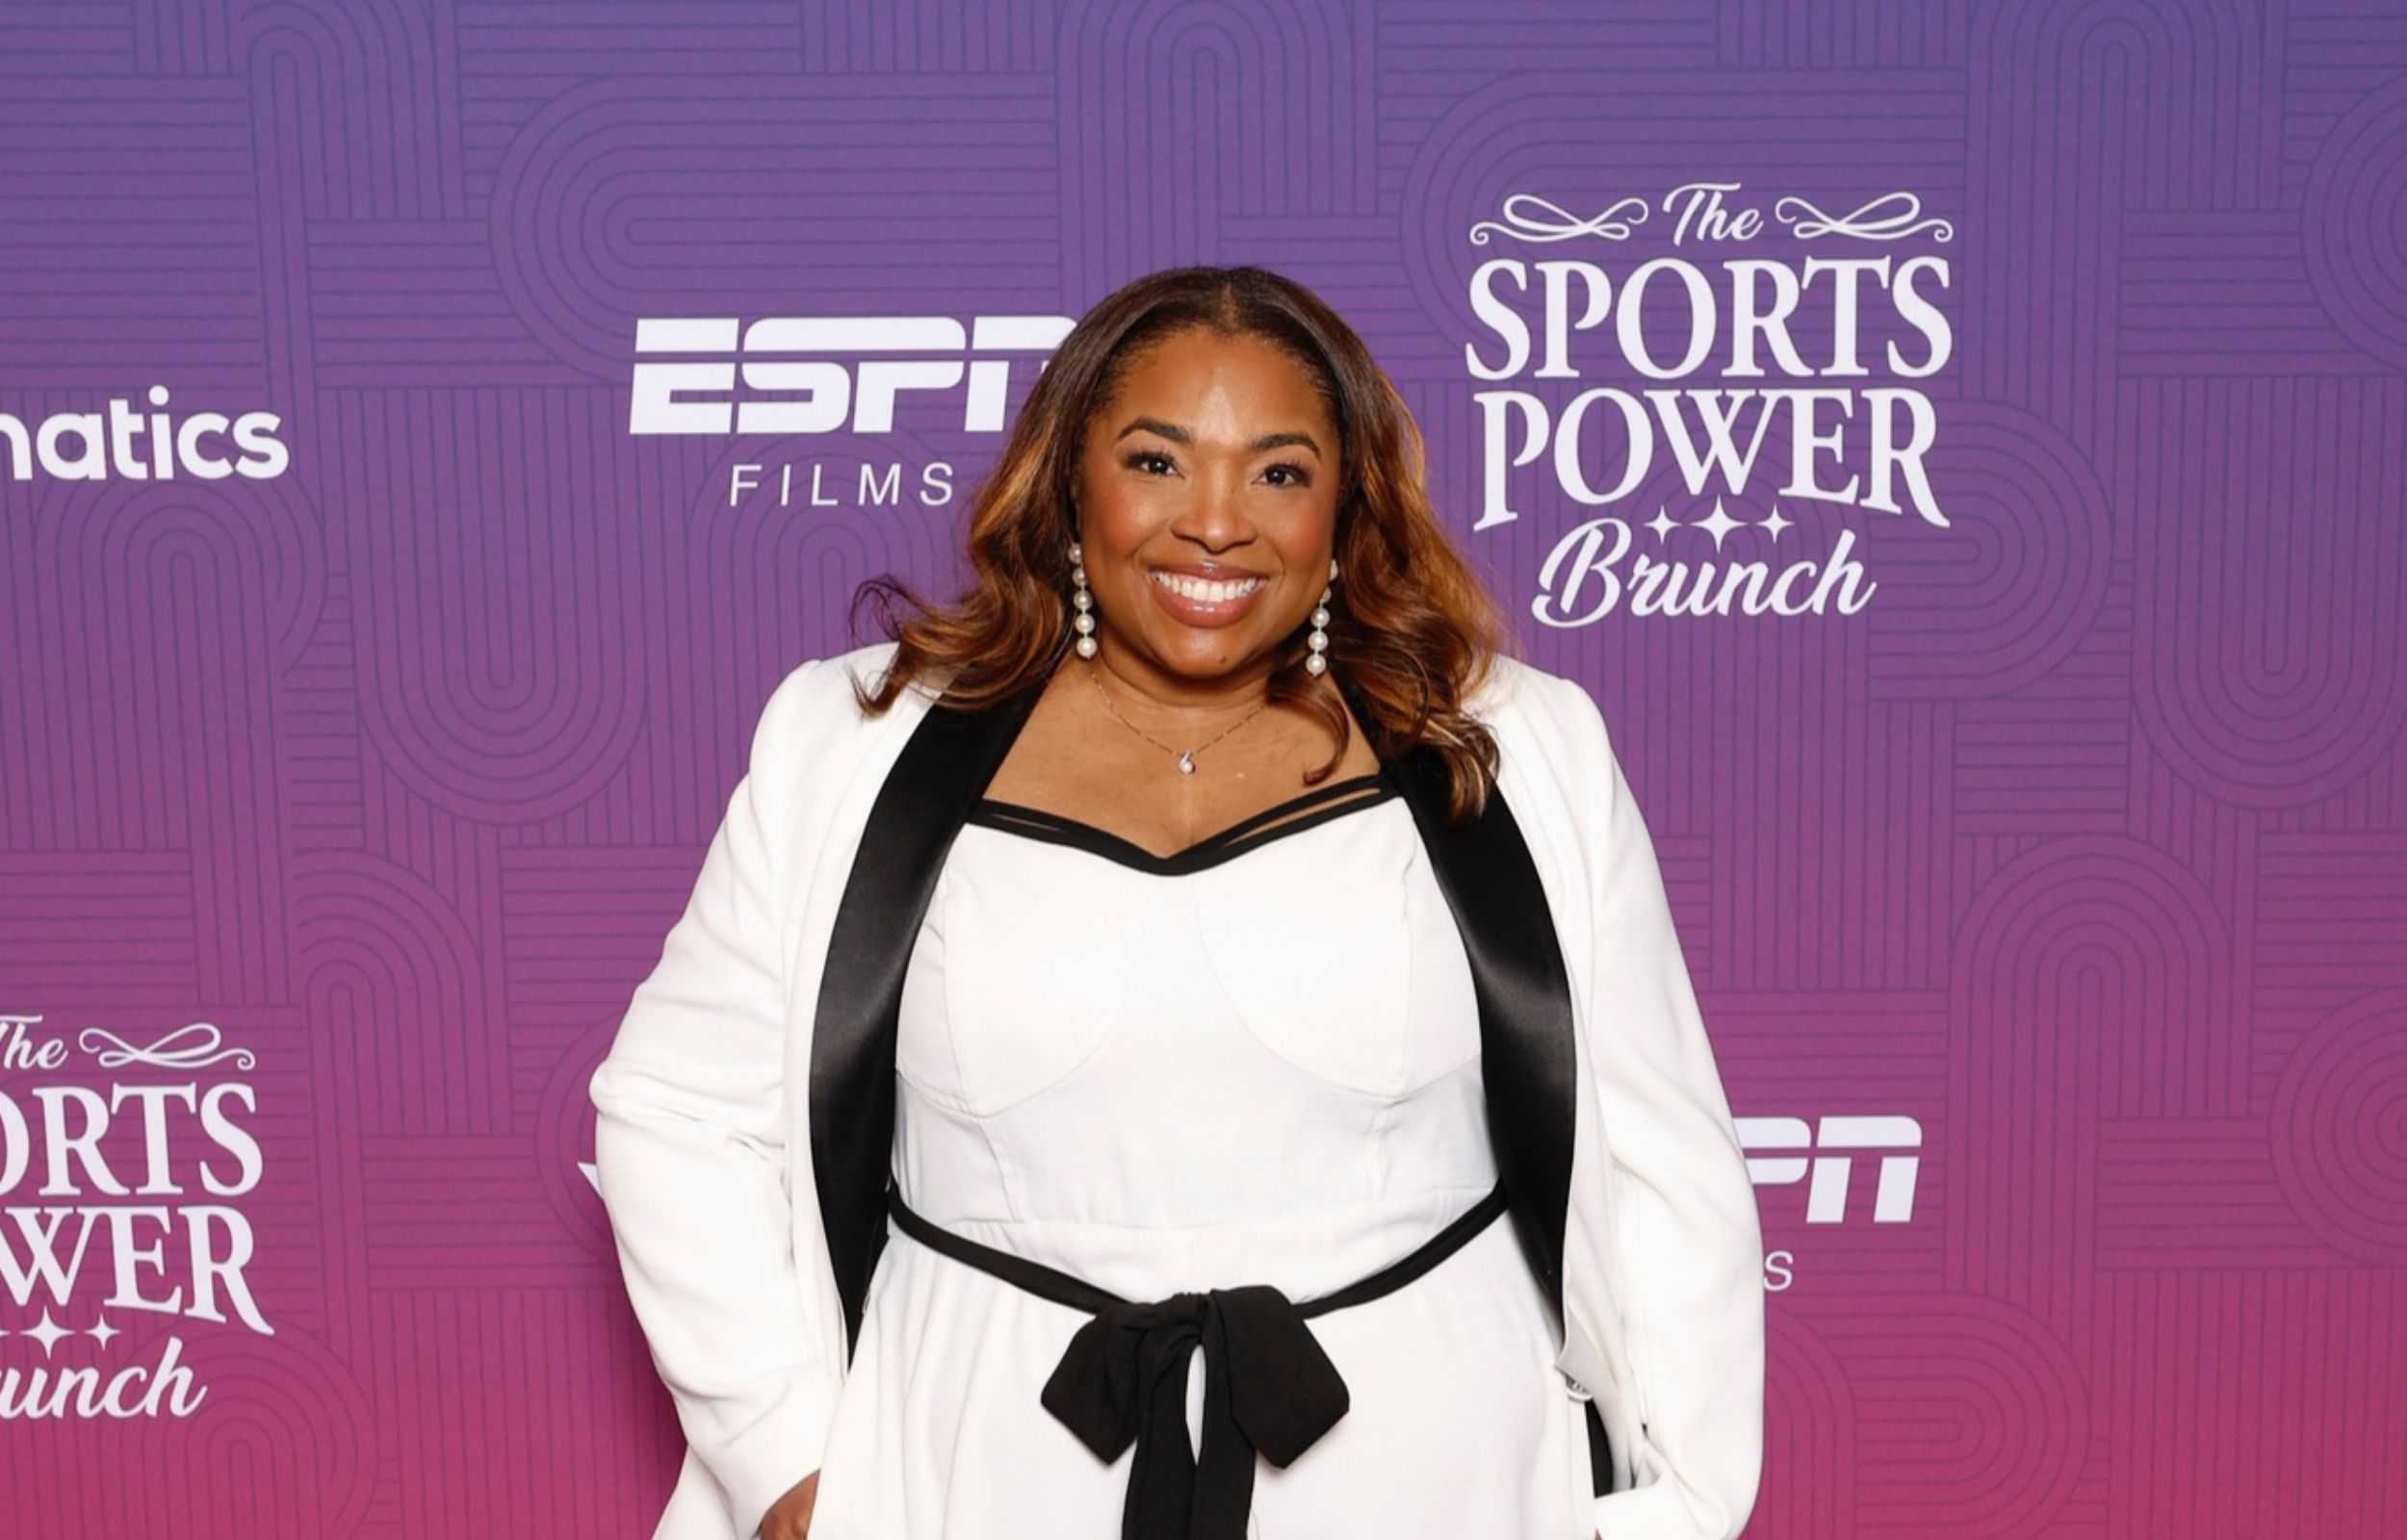
Ironically, the more connected we become online, the more valuable in-person experiences are. It’s classic scarcity theory, and sports publicist and entrepreneur LaTonya Story understands it as well as anyone. That insight helped inspire her to launch the Sports Power Brunch, an event celebrating the most influential women in sports.

Now, after seven years as The Sports Power Brunch: Celebrating the Most Powerful Women in Sports®, the event is entering a new era as The Sports Power Awards™. The rebrand will debut at the eighth annual celebration on Feb. 10, 2027, at The Beverly Hills Hotel during Super Bowl LXI Week in Los Angeles.

Story spoke with Entrepreneur about building the event from the ground up, the thinking behind the rebrand, and the keys to its enduring success.

Start small, think big 

The Sports Power Brunch wasn’t Story’s first foray into event planning. It grew out of something she was already doing in Atlanta: Ladies Pigskin Sundays, weekly gatherings for women who love football.

Through her connections in the sports industry, Story grew the events to include DJs, giveaways, and even NFL-provided swag bags. So when the Super Bowl came to Atlanta in 2019, she was already well positioned to host a bigger celebration.

“I wanted to do an event that honored and celebrated women in sports who I personally admired,” she says. Guided by the belief that “a closed mouth don’t get fed” and “if you have not, because you ask not,” 

Story took the initiative to reach out to women she admired, many of whom she had never met, and launched the inaugural Sports Power Brunch in her hometown.

“I live by the philosophy: ‘If you build it, they will come,’” she says. “Ultimately, my end goal is to have an actual sports awards show for either streaming or linear television.”

Build for the long game 

Of course, bringing influential people together doesn’t automatically make for a great event. Story is conscious of that, which is part of the reason behind this year’s format changes.

“One thing I noticed with our previous format, which included panel discussions, is that people were so excited to meet, greet, and talk to one another,” Story says. “Sometimes you lose that excitement when you transition from the awards into a panel discussion.”

Not wanting to lose that momentum, Story decided to have guests go straight from the awards show into the post-event networking mixer, with panel discussions moved to the second day.

“The true value of a live event isn’t measured solely by bringing people together in a room, although I love doing that,” Story says. “For me, it’s really about longevity and impact, giving sponsors a memorable experience that keeps them coming back, and building a brand that invests in the real success of people.”

Story estimates that roughly 90% of the brunch’s revenue comes from sponsors, with the remaining 10% generated by ticket sales. Her emphasis on relationship building has helped keep sponsors coming back year after year. The NFL has been a legacy sponsor since 2019, Prime Video has supported the event for four to five years, and Delta Air Lines is returning for its third year.

Still, Story is always looking to bring on new sponsors, often through connections made at the events themselves. This year, Visa joins the lineup, thanks in part to a relationship Story built with a former Moët Hennessy executive who previously sponsored one of her events in Las Vegas.

“She remembered me and spoke my name behind closed doors at her new company,” Story says. “That’s a testament to what we’ve created and continue to build.”

Celebrate others to strengthen your brand

Equally important to the networking is the women being honored, something Story takes immense pride in. “About 95% of the women we honor are really behind the scenes,” she explains. “They’re senior executives in sports. Some are front-facing, and some are not.”

Story points to Clutch Sports Group COO Farah Leah and Detroit Pistons President Melanie Harris as examples. “They may not be household names, but they’re doing the true work in the industry,” she says.

For more recognizable figures, Story presents the Trailblazer Award, which will go to WNBA legend Nneka Ogwumike this year.

The selection process also involves strategic considerations. Story makes a point of honoring someone from the Super Bowl host city, which this year will be Rams EVP Molly Higgins. She also selects someone from the NFL office to recognize the league’s role as a partner. This year, that honor goes to SVP Tracy Pearlman.

On the surface, a curated awards show might seem like a superficial way to bring people together. But the business logic is sound: It gives invitees, especially honorees, a compelling reason to attend while reinforcing Story’s authority as a connector and tastemaker in the industry.

“You know, I’ve never had someone say they couldn’t come,” Story laughs. “So that is a great point.”

Make connections count

Ultimately, a host can only control so much. Guests’ experience is up to them, but Story does what she can to make everyone feel welcome.

“I’ve had people email me who came solo and said, ‘I’m an introvert, but I just really felt I needed to be in that room,’” Story shares. “They tend to open up once they get in the room.”

Part of that secret sauce is thoughtful table curation. While sponsors can choose their own seating, Story strategically places ticketed guests near people who could be valuable connections.

“I try to make sure that I’m putting people at tables where they can get to know each other and where there could be some synergy,” she says. “One woman who was attending told me, ‘Oh, no! I already know them. Place me somewhere with someone I don’t know, where I can do business.’ Things like that are really important.”

Story also makes a point of giving guests time to connect, allowing an hour and a half for networking after the awards.

“What’s so funny about the event is that people may not see each other every day or may only know each other through social media,” she says. “It’s so fun to see people running across the room, hugging and catching up. Business deals are being made in that room, too. People are looking at the tables to see which sponsors are represented or which executives are there, and then taking that next step to forge relationships that last long after my event.”

Turn pain into purpose 

The same year Story hosted the inaugural Sports Power Brunch, her 30-year-old son, Sterling, passed away from cancer just two days before Christmas after being misdiagnosed. Rather than letting the tragedy derail her work, Story turned her grief into a mission, establishing the Sterling Legacy Fund to support health-related causes and organizations such as the American Cancer Society.

Still, Story wanted the foundation to feel more personally connected to her son. Sterling was a devoted basketball fan who still had an Allen Iverson Fathead on his wall when he died.

“My day job is as a sports publicist, and my first opportunity to work in sports was volunteering for the Allen Iverson Celebrity Summer Classic in Hampton, Virginia,” Story says.

Sterling’s love of basketball inspired the fund’s signature initiative, Sterling Courts, which renovates basketball courts in his memory. The initiative has brought lasting improvements to communities hosting the Sports Power Brunch, including an outdoor half court at the Downtown Boys & Girls Club in Las Vegas and a full-size indoor court in New Orleans during Super Bowl LIX in 2025. Both projects were completed in partnership with Prime Video, while Microsoft helped renovate computer labs, teen centers, and gaming centers at both locations.

“You never really get through grieving,” Story shares. “But as I processed my grief, I just knew there was something I could do with the platform I have, even if my son wasn’t a household name.”

Bloom where you’re planted 

Story’s, well, story, is proof that you don’t need to reinvent the wheel to find success. By making the most of the resources and relationships you already have, you can simplify the process.

“I always tell people to bloom where they are planted,” Story says. “My very first event was at Davio’s restaurant in Atlanta. I just reached out to people in my network at the time. Most people ask, ‘How do I reach this big organization or that company?’ But you can start by working with people in your immediate circle.”

That approach may simplify the process, but it doesn’t make building an event easy. Securing sponsorships is difficult, and retaining them can be even harder.

“Start small, and then you can grow from there,” Story says. “If you build it, they will come, but sometimes you have to hit the pavement. Never stop pitching, never stop selling, and find people who believe in you.”

She knows firsthand how much that support matters. “At my first event, I couldn’t even pay the entire bill, so my friends put their credit cards down to help cover it. To see where I am now is such a blessing. I believed in myself first, and the people around me believed in me, too. They poured into me and helped grow what is now the event you see today.”

Ironically, the more connected we become online, the more valuable in-person experiences are. It’s classic scarcity theory, and sports publicist and entrepreneur LaTonya Story understands it as well as anyone. That insight helped inspire her to launch the Sports Power Brunch, an event celebrating the most influential women in sports.

Now, after seven years as The Sports Power Brunch: Celebrating the Most Powerful Women in Sports®, the event is entering a new era as The Sports Power Awards™. The rebrand will debut at the eighth annual celebration on Feb. 10, 2027, at The Beverly Hills Hotel during Super Bowl LXI Week in Los Angeles.

Story spoke with Entrepreneur about building the event from the ground up, the thinking behind the rebrand, and the keys to its enduring success.


Source link

She Started a Small Gathering to Celebrate Women in Sports. Eight Years Later, The Sports Power Awards Are Sponsored by ESPN Films  Read More »

28-Year-Old’s Side Hustle Hit $125K in Year 1: More Than Matcha

28-Year-Old’s Side Hustle Hit $125K in Year 1: More Than Matcha


Key Takeaways

  • Goldwasser leveraged her marketing and consulting experience to build More Than Matcha.
  • After steady growth, she quit corporate to focus on the business full-time in March of this year.
  • Now, More Than Matcha is on track to see between $400,000 and $500,000 in revenue in 2026.

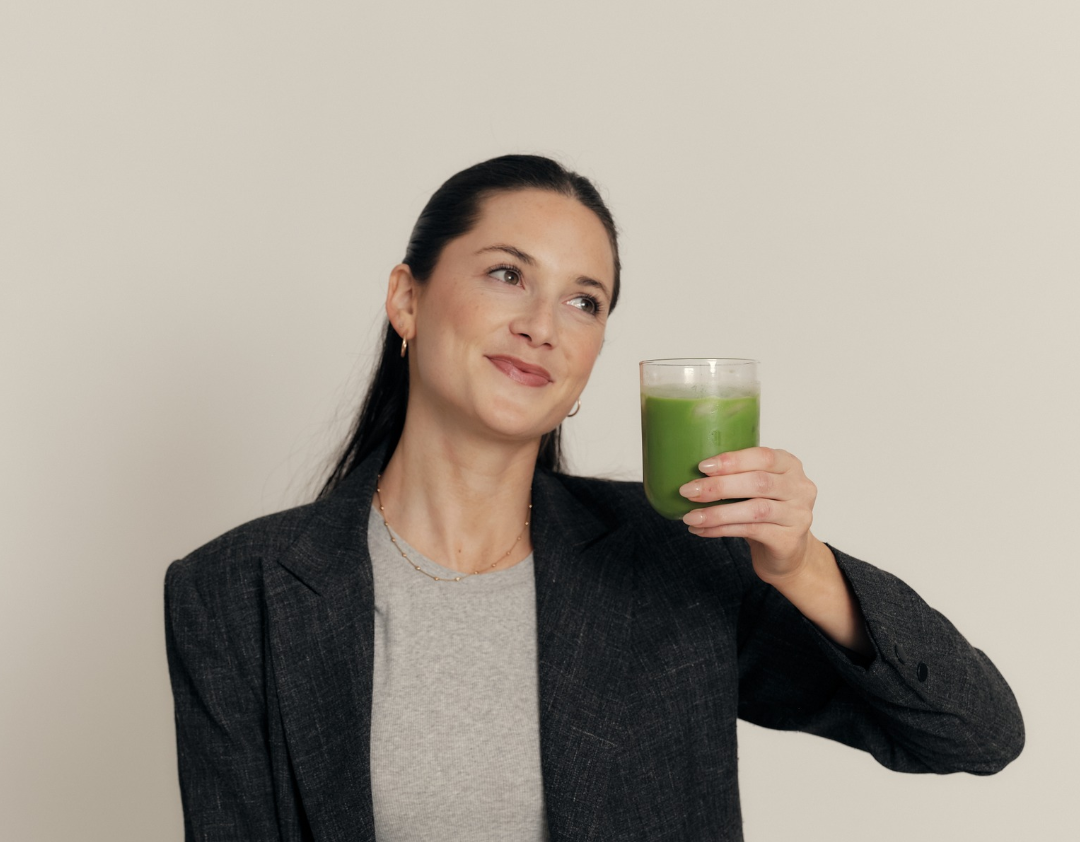
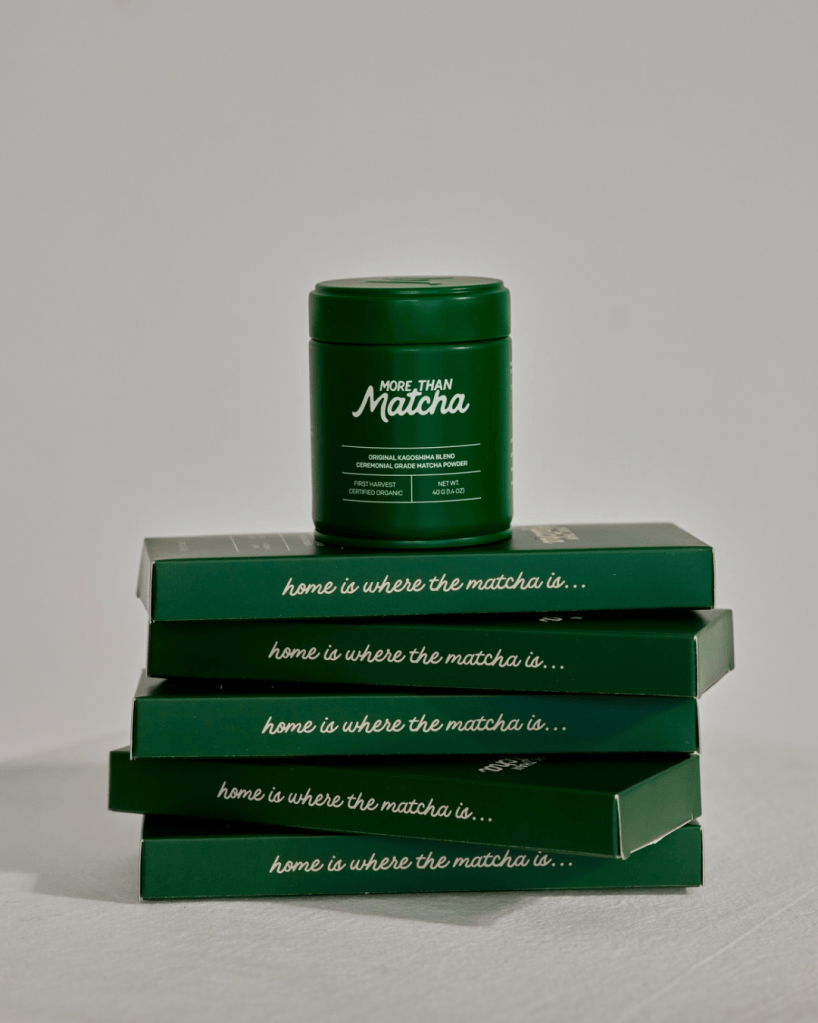
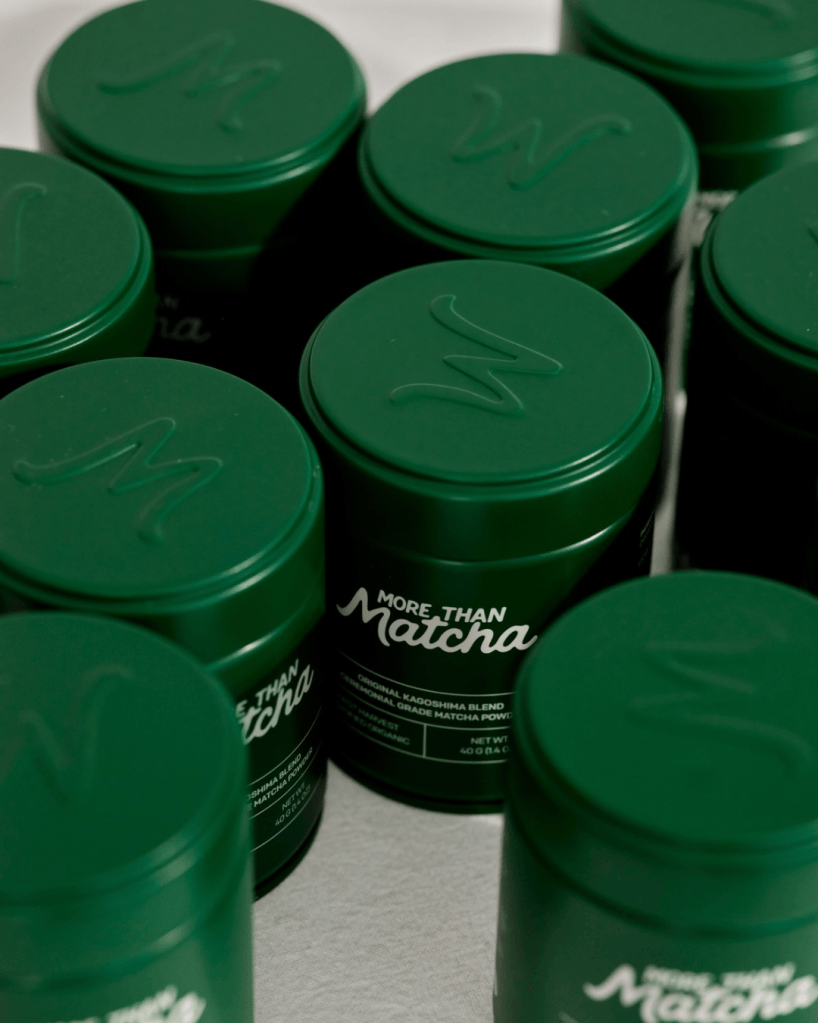
This Side Hustle Spotlight Q&A features Rosie Goldwasser, 28, of Santa Monica, California. Goldwasser was working full-time as a customer experience strategist at PwC (PricewaterhouseCoopers) when she started her side hustle: More Than Matcha, a premium matcha and lifestyle brand.

More Than Matcha. Rosie Goldwasser.

The business hit $125,000 in revenue without spending a single dollar on advertising in its first year and doubled revenue in its second. Goldwasser left her corporate role in March 2026 to focus on More Than Match full-time. The brand is on track for between $400,000 and $500,000 in revenue this year. Responses have been edited for length and clarity. 

Starting a side hustle: More Than Matcha

When did you start your side hustle, and where did you find the inspiration for it?
I started building More Than Matcha in 2023 and officially launched in March 2024. The idea actually came from a personal frustration. For years, I was either too tired to function or too wired, jittery and anxious from coffee to sleep. There was no in-between until I discovered matcha. It was love at first sip. It gave me a calm, focused energy that actually lasted.

But finding high-quality matcha was challenging. Cafés charged $10 for drinks that consistently left me disappointed. At-home options lacked quality, consistency and a brand I could genuinely connect with. 

Having spent four years in marketing and six years in customer experience consulting, I’ve always been fascinated by what makes consumers fall in love with brands and how to create experiences that exceed their expectations. As a daily matcha consumer myself, I saw a gap I couldn’t ignore. 

More Than Matcha

Finding the perfect matcha powder for the market

What were some of the first steps you took to get your side hustle off the ground? How much money did it take to launch? 
I was never going to launch a matcha brand unless I found a matcha powder so good that I felt I’d be doing the world a disservice by not bringing it to market.

So I spent months researching, sourcing, sampling and learning everything I could about what makes exceptional matcha, from growing regions and cultivars to harvesting methods and sustainable farming practices. I finally discovered the four-cultivar blend we use. To this day, it’s the best matcha I’ve ever tasted. I’ve since had the opportunity to visit our supplier in Japan, meet some of the farmers behind our matcha and see firsthand the care that goes into producing it. 

After finding the right product, I invested $25,000 of my own savings into building the matcha brand, without any outside funding. Over the next several months, I brought every detail to life: branding, packaging, website development, product photography — and all the little things that go into creating a brand from scratch. 

More Than Matcha

Outsourcing fulfillment was a turning point

Are there any free or paid resources that have been especially helpful for you in starting and running this business? 
For the first year of More Than Matcha, I packed and shipped every single order myself, spending nights and weekends fulfilling orders. I’d recruit friends and family to help pack during busy periods, turning my 700 square-foot apartment into a makeshift fulfillment center. 

At first, doing everything myself felt like the smartest way to save money. But eventually, I realized I was spending so much time keeping the business running that I had almost no time left to actually grow it. 

Making the decision to outsource fulfillment was a turning point. Yes, it was an added expense, but it gave me back something far more valuable: my time. Suddenly, I could focus on product development, marketing, partnerships and all the things that would actually move the business forward. 

More Than Matcha

Focus on the hero product before a line’s expansion

If you could go back in your business journey and change one process or approach, what would it be, and how do you wish you’d done it differently? 
I would have been much more disciplined about focusing on our hero product before expanding into other categories. When we first launched More Than Matcha, we introduced our matcha powder alongside four different hats. I loved the idea of building a lifestyle brand and imagined people wearing our merchandise everywhere. 

But the problem was that nobody knew who we were yet. We spent so much time and money sampling, designing and producing merchandise before we had built a community of people who actually wanted to represent our brand.

If I could do it again, I would put that money and energy into making our core product even more successful, building customer loyalty and understanding what our audience wanted next. 

The CPG space comes with constant decisions

When it comes to this specific business, what is something you’ve found particularly challenging and/or surprising that people who get into this type of work should be prepared for, but likely aren’t?
Especially in the CPG space, you’re constantly making decisions that could change the trajectory of your business. From the products you develop and the manufacturers you trust, to your branding, pricing, hiring, retail partners and which sales channels to pursue. And when you’re a bootstrapped, solo founder, there’s no team of executives to turn to for the final call. 

I’ve learned to start the decision-making process long before I actually need to make the decision. I’ll start interviewing candidates months before I’m ready to hire and begin conversations with manufacturers long before I need to make the switch. I’ll ask other founders about challenges they’ve faced before I’ve even encountered those challenges myself. 

In a business where one decision can impact your product, customers and cash flow for months to come, that preparation can make all the difference. 

More Than Matcha

Transparency wins customer trust during a crisis

Can you recall a specific instance when something went very wrong — how did you fix it? 
Just a few weeks ago, we were gearing up to launch our new matcha travel collection. After months of development, I had approved the final sample of our single-serve matcha sticks and moved forward with producing 25,000 units.

But the manufacturer kept delaying production. It wasn’t until the night before launch that the first four boxes finally arrived. I had a gut feeling something was wrong, so I drove to our fulfillment center to inspect them myself. Unfortunately, I was right. 

The product was nothing like what I had approved. Matcha powder was leaking out of both ends of the sticks, covering the other products in the boxes. They were completely unsellable. 

We had spent weeks teasing the collection, built an entire marketing campaign, redesigned our website and generated so much excitement. And just like that, on launch day, I had to cancel everything. 

Rather than trying to hide what happened, I picked up my phone, filmed a video in one take and told our community exactly what went wrong. The response was beyond anything I could have imagined. Instead of being disappointed, our customers rallied around us. The comments and DMs poured in, thanking me for being transparent and refusing to compromise on quality. 

We’re now working with a new manufacturer to bring these sticks to market the right way, and somehow our community is even more excited for their eventual launch. 

More Than Matcha

Making $125k in year one, on track for $400k to $500k

How long did it take you to see consistent monthly revenue? How much did the side hustle earn? 
It took about four months to start seeing consistent monthly revenue. In our first year, we generated $125,000 in revenue without spending a single dollar on advertising. In our second year, we more than doubled that revenue, continuing to grow organically and reinvest what we earned back into the business. 

What does growth and revenue look like now? 
2026 has been a major reinvestment year for More Than Matcha. Rather than focusing solely on short-term revenue growth, we made the intentional decision to invest in the long-term future of the brand. 

We completely rebranded, upgraded everything from our packaging to our website and spent much of the year developing our new matcha travel collection, our biggest product launch yet, now scheduled for early 2027. 

Even with so much of our time and resources focused on building for the future, we’re still on track to generate between $400,000 and $500,000 in revenue this year, all while remaining completely bootstrapped. 

More Than Matcha

Let real customers determine where you go next

What is your best piece of specific, actionable business advice? 
Done is better than perfect. When I first started More Than Matcha, I didn’t have a three-year, five-year or 10-year business plan. My goal was simply to get my idea out into the world to see if others believed in it too. 

Looking back, I actually think that was one of the best things I could have done. Had I tried to map out everything I wanted this business to become before I even launched, I might have gotten so overwhelmed that I never would have started in the first place. Instead, I focused on getting a product I was proud of into customers’ hands, letting them validate the idea, and learning, iterating and adjusting along the way. About a year into the business, after seeing how customers responded and what opportunities were opening up, my long-term vision became so much clearer.

So figure out the smallest version of your idea that you’re genuinely proud to put into the world and launch it. Don’t wait until you have the perfect website, the perfect packaging or a five-year roadmap. Let real customers help you figure out what comes next.

Key Takeaways

  • Goldwasser leveraged her marketing and consulting experience to build More Than Matcha.
  • After steady growth, she quit corporate to focus on the business full-time in March of this year.
  • Now, More Than Matcha is on track to see between $400,000 and $500,000 in revenue in 2026.

This Side Hustle Spotlight Q&A features Rosie Goldwasser, 28, of Santa Monica, California. Goldwasser was working full-time as a customer experience strategist at PwC (PricewaterhouseCoopers) when she started her side hustle: More Than Matcha, a premium matcha and lifestyle brand.

More Than Matcha. Rosie Goldwasser.

The business hit $125,000 in revenue without spending a single dollar on advertising in its first year and doubled revenue in its second. Goldwasser left her corporate role in March 2026 to focus on More Than Match full-time. The brand is on track for between $400,000 and $500,000 in revenue this year. Responses have been edited for length and clarity. 

Starting a side hustle: More Than Matcha

When did you start your side hustle, and where did you find the inspiration for it?
I started building More Than Matcha in 2023 and officially launched in March 2024. The idea actually came from a personal frustration. For years, I was either too tired to function or too wired, jittery and anxious from coffee to sleep. There was no in-between until I discovered matcha. It was love at first sip. It gave me a calm, focused energy that actually lasted.


Source link

28-Year-Old’s Side Hustle Hit $125K in Year 1: More Than Matcha Read More »

Silicon Valley Doesn’t Have a Monopoly on Startup Wisdom

Silicon Valley Doesn’t Have a Monopoly on Startup Wisdom


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Founders in small ecosystems design for international markets from day one, planning for localization, payments and regulation before they need to.
  • Scarcity forces discipline as founders who learn to operate lean and treat relationships as infrastructure are better prepared for market corrections and fundraising delays.
  • Local knowledge is a competitive advantage.

Silicon Valley teaches founders to think big. Smaller startup markets teach them how to build when almost nothing is guaranteed.

Over the past year, I have met founders and investors across the Baltics, Georgia and Guatemala through Baltic Fintech Days, a 500 Global Eurasia Demo Day in Tbilisi and Volcano Summit. These ecosystems differ in language, history and access to capital, but the strongest founders shared a common advantage: They could not rely on a large domestic market, abundant venture funding or proximity to the world’s most powerful networks.

That constraint shaped how they built. They thought internationally earlier, stretched resources further and cultivated relationships across borders. As capital becomes more selective and growth at all costs continues to fall out of favor, founders everywhere can learn from companies built in markets that have never had the luxury of excess.

Here are five lessons from some of the world’s smallest startup ecosystems.

1. Build for the world from day one

A founder in the United States can build a large company without ever leaving the domestic market. Founders in Latvia, Lithuania, Estonia, Georgia or Guatemala rarely have that option.

The entire population of Lithuania is smaller than that of Los Angeles. Latvia has fewer than 2 million residents, while Georgia has fewer than 4 million. Even Guatemala, the largest of the markets I visited, represents only a fraction of the purchasing power available in the United States.

As a result, international expansion is not a distant ambition for many of these founders. It is part of the original business model.

At Baltic Fintech Days, I met entrepreneurs who were thinking about cross-border payments, compliance and market entry well before reaching the scale at which an American startup might begin considering international growth. Their home markets gave them useful places to test, but not enough room to stop there.

This forces founders to ask important questions early: Can the product travel? Can it serve customers across languages, currencies and regulatory systems? Does the problem exist beyond the founder’s immediate network?

Building globally does not mean launching in 10 countries at once. It means avoiding assumptions that make international expansion unnecessarily difficult later. Founders should consider localization, payment infrastructure, regulation and cross-border distribution while the company is still young enough to adapt.

2. Treat constraints as a design advantage

Founders love to talk about resourcefulness, but the concept takes on a different meaning in ecosystems where capital, talent and customers are all more difficult to access.

At 500 Global’s Eurasia Demo Day in Tbilisi, I saw companies working to gain attention far beyond their immediate geography. They could not assume that investors would already understand their markets, recognize their universities or trust their local references. They had to communicate the problem, the opportunity and their credibility with unusual precision.

That constraint can produce better companies.

When capital is scarce, founders have less room for performative hiring, unnecessary tools or growth that cannot be tied to customer demand. They learn to test assumptions quickly, sell before everything is perfect and use partnerships to extend their reach.

Founders in major technology hubs should apply the same discipline even when more resources are available. Ask what the company would prioritize if it had half the budget, half the team and half the time. The answer often reveals which initiatives are truly essential.

Scarcity is painful, but it can also create focus. A company that learns to operate efficiently before raising significant capital may be better prepared to survive market corrections, fundraising delays and unexpected competition.

3. Make your ecosystem part of your competitive advantage

Smaller markets are often discussed only in terms of what they lack. That framing overlooks what they can offer.

The Baltics have developed deep expertise in fintech, digital infrastructure and cross-border business. Georgia sits at the intersection of Europe and Asia and is developing a generation of founders accustomed to navigating multiple markets. Guatemala offers access to Central America, proximity to the United States and entrepreneurs with firsthand knowledge of industries and consumers that remain poorly understood by many global investors.

At Volcano Summit in Guatemala, the value of the ecosystem was not simply that it brought international investors into the country. It created a place where local and regional founders could build relationships without first relocating to San Francisco, Miami or New York.

Founders should resist the urge to erase where they come from in an attempt to appear more investable. Geography can be a source of differentiated insight.

A founder who understands regional payment behavior, informal commerce, remittances or local regulation may see an opportunity long before an outsider does. The goal is not to build a business that only works locally. It is to turn local knowledge into an advantage that can travel.

The most compelling question is not, “Why would a major company come from this market?” It is, “What can a founder see from this market that others cannot?”

4. Relationships are infrastructure

In mature startup hubs, founders can mistake proximity for access. They may attend dozens of events, collect hundreds of contacts and still fail to build relationships that materially help the company.

In smaller ecosystems, relationships often function as infrastructure.

One trusted introduction can connect a founder to a customer, investor or market that would otherwise be difficult to reach. Government agencies, accelerators, diaspora networks and local operators frequently play an outsized role in helping companies cross borders.

I saw versions of this at Baltic Fintech Days, through 500 Global’s network in Georgia and at Volcano Summit. These gatherings mattered because they connected local credibility with international reach. They reduced the distance between founders and people who could help them enter new markets.

Founders should approach relationship-building with the same discipline they apply to product development. Instead of asking how many people they met, they should ask whether they are building trust with the right customers, partners and advocates.

That also means becoming useful before asking for something. Founders can share market intelligence, make introductions and offer thoughtful feedback. In smaller ecosystems, reputations travel quickly. Generosity and reliability compound.

5. Learn to tell the market why it should care

A founder in a well-known ecosystem benefits from familiar signals. Investors recognize the schools, employers, accelerators and other funds around the table. Founders from less visible markets must often establish credibility without those shortcuts.

That makes storytelling a core business capability.

The strongest founders I encountered did not simply explain what their products did. They connected a local problem to a much larger shift. A payments challenge became a story about global commerce. A compliance product became infrastructure for the international workforce. A regional marketplace became evidence of changing consumer behavior across emerging economies.

Founders should not expect investors or customers to do this translation themselves.

A strong pitch should answer four questions: Why does this problem matter? Why is the opportunity larger than it first appears? Why is this team uniquely equipped to solve it? And why is now the right moment?

This is especially important for founders building outside established technology centers. Investors may incorrectly interpret an unfamiliar market as a small opportunity. The founder’s job is to distinguish the company’s starting point from its potential destination.

Great companies are not limited to great startup hubs

Talent is distributed far more evenly than capital, attention or access. Some of the world’s most ambitious founders are building in places that receive only a fraction of global venture investment.

The Baltics, Georgia and Guatemala are not interchangeable, nor should they be reduced to a single category of “emerging markets.” Each has its own strengths, challenges and history. What connects them is the resourcefulness required to build beyond the limits of a small domestic ecosystem.

Founders everywhere can learn from that mindset.

Start globally. Use constraints to sharpen your decisions. Turn local knowledge into an advantage. Treat relationships as infrastructure. And make the scale of your ambition impossible to misunderstand.

The next category-defining company may not come from the place investors visit most often. It may come from the market whose founders learned to build without waiting for the world to notice.

Key Takeaways

  • Founders in small ecosystems design for international markets from day one, planning for localization, payments and regulation before they need to.
  • Scarcity forces discipline as founders who learn to operate lean and treat relationships as infrastructure are better prepared for market corrections and fundraising delays.
  • Local knowledge is a competitive advantage.

Silicon Valley teaches founders to think big. Smaller startup markets teach them how to build when almost nothing is guaranteed.

Over the past year, I have met founders and investors across the Baltics, Georgia and Guatemala through Baltic Fintech Days, a 500 Global Eurasia Demo Day in Tbilisi and Volcano Summit. These ecosystems differ in language, history and access to capital, but the strongest founders shared a common advantage: They could not rely on a large domestic market, abundant venture funding or proximity to the world’s most powerful networks.

That constraint shaped how they built. They thought internationally earlier, stretched resources further and cultivated relationships across borders. As capital becomes more selective and growth at all costs continues to fall out of favor, founders everywhere can learn from companies built in markets that have never had the luxury of excess.


Source link

Silicon Valley Doesn’t Have a Monopoly on Startup Wisdom Read More »

How to Speak Honestly at Work Without Derailing Your Career

How to Speak Honestly at Work Without Derailing Your Career


Key Takeaways

  • There’s such a thing as being too honest in the workplace.
  • Social psychologist Vanessa Bohns recently said in an interview that “honesty is not the best policy if whatever we say is going to be honest without any instrumental value.”
  • She advised asking three questions before giving honest feedback.

Saying exactly what you think isn’t always the best career move. 

Social psychologist Vanessa Bohns recently said in an interview with NPR that knowing when to speak up and when to stay quiet can be more challenging than figuring out how to phrase your thoughts.

“There are times when honesty is the best policy,” Bohns said. “On the other hand, honesty is not the best policy if whatever we say is going to be honest without any instrumental value.” 

In her book Should I Say Something? The Science of What to Share—and What to Keep to Yourself, published in October, Bohns draws on research to explore which thoughts and feelings are worth voicing, and which are better left unsaid. Her guidance spans everything from offering an honest opinion to celebrating a win, apologizing or opening up.

People can find it hard to deliver criticism, even comments meant to help. “It pains us to embarrass or hurt other people,” Bohns said. Researchers call it the MUM effect, or minimizing unpleasant messages. It’s a marker of a general human tendency to hold back bad news more than good news. 

Bohns advised workers to ask themselves three questions before sharing their honest opinion or feedback. First, is this information helpful? Second, would I want to hear this? And finally, do they want my feedback? 

First, is your feedback actionable?

Speaking up tells the other person that you noticed something and felt it mattered enough to mention, according to Bohns. 

The question, then, isn’t simply whether your opinion is honest, but if it serves the person hearing it. Will it help them improve or offer insight into themselves?

If your opinion is unkind or about something they can’t change, it might be the better route to keep it to yourself. 

Second, is this something I would want to know about?

If a new colleague repeatedly mispronounces the CEO’s name, gently correcting them now could spare them embarrassment later. 

Pointing it out could feel uncomfortable in the moment, but it could end up helping your colleague make a good impression on senior management. 

Before holding back with honesty or feedback, consider whose feelings you are protecting. As Bohns writes in her book: “Are you being kind, or are you avoiding your own discomfort?”

Finally, are they asking for feedback?

Bohns advises against giving advice to someone who hasn’t asked for it. You may end up explaining something they already understand better than you do, she said.

Even with good intentions, deciding what someone needs to hear or how much honesty they can handle can come across as condescending, Bohns writes in her book.

Instead of making that decision for them, ask if they’d welcome your feedback. “Give them the autonomy, then respect their decision, whatever it might be,” she said. 

Key Takeaways

  • There’s such a thing as being too honest in the workplace.
  • Social psychologist Vanessa Bohns recently said in an interview that “honesty is not the best policy if whatever we say is going to be honest without any instrumental value.”
  • She advised asking three questions before giving honest feedback.

Saying exactly what you think isn’t always the best career move. 

Social psychologist Vanessa Bohns recently said in an interview with NPR that knowing when to speak up and when to stay quiet can be more challenging than figuring out how to phrase your thoughts.

“There are times when honesty is the best policy,” Bohns said. “On the other hand, honesty is not the best policy if whatever we say is going to be honest without any instrumental value.” 


Source link

How to Speak Honestly at Work Without Derailing Your Career Read More »

Shake Shack’s One Strict Rule That’s Paying Off for Growth

Shake Shack’s One Strict Rule That’s Paying Off for Growth


If a Shake Shack opens in your neighborhood, don’t expect another one nearby. Unlike some brands that flood the zone with locations (we’re talking to you, Starbucks), the burger chain doesn’t build a new store within 10 miles of an existing one, at least outside Manhattan, according to CEO Rob Lynch.

That doesn’t mean Shake Shack is growing. It opened a record 21 Shacks last quarter and 54 so far this year, with as many as 65 expected by year’s end. Lynch believes the U.S. has room for at least 1,500, Restaurant Business reports.

The biggest risk of opening stores this fast is cannibalization, where a new location steals sales from an existing one. That’s what the 10-mile rule is designed to prevent. Lynch says the only overlap comes from delivery, since a typical delivery radius is about 7 miles.

So far, the 10-mile strategy seems to be working. Same-store sales rose 2.5% in the third quarter, the fifth straight quarter of growth, even though new shacks open with lower sales than the chain’s $4 million average. Revenue climbed 15.2% to $423.3 million, and the stock jumped nearly 9% on Monday.


Source link

Shake Shack’s One Strict Rule That’s Paying Off for Growth Read More »

How ‘Boring’ Businesses Can Win on Black Friday

How ‘Boring’ Businesses Can Win on Black Friday


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Send handwritten Black Friday offers to existing customers, make your Black Friday offers easier to discover by AI, and create engaging videos to make a “boring” service impossible to ignore.
  • Make your Black Friday deals impossible to miss on Google, use automation to turn abandoned carts into sales, and run short, frequent radio ads with a clear offer and promo code.
  • Offer something free to win a higher-value customer. Giving away a small service can be a smart Black Friday strategy when it helps customers take the first step toward a much larger purchase.

Black Friday isn’t just for big retailers. It’s also an opportunity for the hardworking small businesses we see every day, from bakeries and hair salons to cleaning companies and accounting firms.

I affectionately call them “boring” businesses, but there’s nothing boring about the people behind them. They’re the familiar neighborhood businesses we rely on every day, run by hardworking people who often wear several hats to keep things going.

And these traditional industries continue to attract new entrepreneurs. According to internal Tailor Brands business formation data, cleaning and home service businesses saw growth ranging from 60% to more than 300% in 2026, depending on the subcategory. But whether you’re just starting out or have been serving your community for years, the challenge is the same: finding ways to attract customers and keep them coming back.

Black Friday gives small businesses an opportunity to do both. A record 202.9 million Americans shopped between Thanksgiving and Cyber Monday in 2025, up from 197 million in 2024, as reported by inBeat. While much of the attention goes to major retailers, local businesses can use the shopping season to reconnect with existing customers and give new ones a reason to try their services.

Having worked with many small businesses, I’ve learned that successful Black Friday campaigns don’t always require big budgets or massive discounts. Sometimes, a personal gesture or a clever offer can make all the difference.

Here are a few practical strategies, including examples from my own experience, to help everyday businesses make the most of Black Friday.

1. Send handwritten Black Friday offers to existing customers

Whether you run a hair salon, accounting firm or neighborhood bakery, Black Friday can be an opportunity to generate sales from customers who already know and trust your business. Instead of competing for attention with another promotional email, try sending a handwritten offer.

Handwrytten’s Consumer Survey found that only 11% of consumers had recently received a handwritten note from a brand, and just 4% found them annoying. That makes handwritten outreach an interesting way to stand out during a season dominated by digital promotions.

I’ve seen this work firsthand. I once worked with a client whose cake business was on the verge of bankruptcy. With bills and taxes piling up, we asked the owner’s 10-year-old daughter to handwrite thank-you letters to existing customers, offering them a special Black Friday deal: buy cake credits now and redeem them anytime over the next 12 months.

We sold credits for 271 cakes at an average of almost €60 each, generating nearly €16,000 in Black Friday sales. That cash injection gave the business much-needed breathing room. Customers also loved the letters, and the heartwarming gesture helped turn them into even more loyal supporters.

The same idea can work for almost any local business. Hair salons can sell prepaid appointments, cleaning companies can offer service credits, and accountants can create annual packages. The trick is to combine a personal touch with an offer that brings in revenue today while giving customers something valuable tomorrow.

2. Make your Black Friday offers easier to discover by AI

For hotels, Black Friday is an opportunity to sell discounted spa weekends, romantic getaways and prepaid stays during the quieter winter months. But travelers need to discover these offers before they can book them.

AI-powered travel planning creates another opportunity to reach potential guests. According to Wanderboat, 56% of active U.S. travelers used AI for some aspect of their travel experience in the previous year.

Yet ranking highly on Google doesn’t guarantee visibility in AI-generated answers. Heroic Rankings reports that Google’s AI overlooks approximately 62% of pages ranking in the top 10 traditional search results.

To improve their chances of appearing in AI-generated recommendations, hotels should make their Black Friday offers as specific as possible. Instead of simply advertising “40% off winter stays,” imagine a small hotel offering a “Two-night spa getaway for two in Asheville for $299, including breakfast and spa access, valid December 12–14.”

I’d create a dedicated page for that offer, clearly listing the price, dates, amenities, cancellation policy and booking conditions. I’d also add guest reviews and answer questions travelers might ask, such as whether parking is included or if the spa requires advance booking. Make sure the details match what’s listed on booking platforms and add appropriate structured data to help search engines understand the package.

The easier it is for AI to find and understand your offer, the better your chances of reaching travelers looking for exactly that kind of getaway.

But optimizing your own website is only part of the equation. I’d also try to get my Black Friday offer featured in local media, relevant industry websites and articles rounding up the best Black Friday deals. In its GEO research, CSP analyzed more than 70,000 AI answers across three industries in 2026 and found that 85 earned-media placements generated 5,697 AI citations. This shows why getting your offer mentioned on relevant third-party websites can be just as important as making it easy to find on your own.

3. Make a “boring” service impossible to ignore with video

Video can make even the most ordinary services more appealing. In fact, 85% of consumers say they’ve been convinced to buy a product or service after watching a video, as reported by Flova. Even less flashy businesses like accounting firms, plumbers and cleaning companies can use humor to make their Black Friday campaigns stand out.

Last year, while managing a marketing campaign for a cleaning company, I wanted to create a funny video, but the employees weren’t comfortable on camera. We used AI animation instead, creating a humorous clip about the mess after a holiday party. The video converted particularly well in paid campaigns, driving plenty of sales while also generating strong organic engagement.

What makes this approach even more attractive today is how affordable it has become to experiment. As GPTProto reports, short AI video clips can cost between $0.04 and $0.50 per generation. That doesn’t mean producing an entire campaign costs a few cents, but it does mean small businesses can test different concepts, jokes and visual styles without spending heavily on every attempt.

I’ve since started incorporating AI video into the marketing services I offer clients. For a small business with someone comfortable using AI tools, the opportunity isn’t simply to produce cheaper videos. It’s to experiment with more ideas, discover what resonates with customers and put the strongest creative into a Black Friday campaign.

Small businesses can try the same approach. Show a relatable problem, add some humor, and finish with a clear Black Friday offer. You don’t need a big budget to make an ordinary service memorable.

4. Make your Black Friday deals impossible to miss on Google

Organic search traffic is declining across many industries, partly because Google’s AI Overviews now answer informational queries directly. According to Get Stuff Digital, organic traffic declined by 20% to 35% in its analysis following the introduction of AI-powered search features.

But I don’t see this as a reason to panic. Small businesses don’t necessarily need more informational traffic. They need visitors who are ready to book or buy. That’s why I’d focus Black Friday SEO efforts on high-intent searches rather than trying to recover every lost click.

For example, a cleaning company could create a dedicated page targeting searches like “Black Friday cleaning deals in Chicago” or “holiday deep cleaning discounts in Chicago,” with a specific package, price and clear booking option. I’d publish that page in September, or early October at the latest, to give Google time to discover and index it before Black Friday. I’d also add a few relevant internal links from existing service pages and blog posts to help search engines find it.

The goal isn’t to attract the most traffic. It’s to make sure that when someone searches for a Black Friday deal on a service you provide, your business is there with an offer they can act on.

5. Turn abandoned carts into Black Friday sales

Black Friday isn’t just about attracting new customers. It’s also a chance to bring back shoppers who never completed their purchases.

The average cart abandonment rate is 70.22%, as reported by Knowcrunch. These shoppers have already shown interest, making them a valuable audience for Black Friday offers.

For my clients, I already use automated emails year-round to remind customers about products they’ve left in their carts. During Black Friday, I take this a step further by targeting shoppers who abandoned their carts in the past 30 to 60 days and sending them personalized emails with a limited-time discount.

AI agents can make this process even easier by helping generate messages based on the products each customer considered. Scalably reports that sales professionals expect AI agents to reduce email-drafting time by 36% once fully implemented. In my experience, automating these repetitive follow-ups can save even more time, especially when you’re managing campaigns for multiple clients.

For example, a furniture store could automatically email someone who abandoned a sofa in their cart, remind them of the exact product and offer a Black Friday discount with a direct link to checkout. The system should also exclude customers who’ve already completed their purchases, so they don’t receive unnecessary reminders.

Instead of spending your entire Black Friday budget attracting new visitors, use automated emails and timely discounts to bring interested shoppers back and turn abandoned carts into sales.

6. Reach customers where they spend their day — in the car

One of the first rules of marketing is to be where your customers are. And sometimes, that’s behind the wheel. Munley Law highlights that Americans spend an average of 60.2 minutes driving each day. For local businesses, that creates an opportunity to reach customers during the busy Black Friday weekend.

Run short, frequent local radio ads with one clear offer and a promo code. Leave flyers with a time-limited deal on parked cars in busy shopping areas, where local rules allow.

Extend your opening hours over the holiday weekend and add them as special hours in your Google Business Profile. Drivers searching “near me” early in the morning or late in the evening may be looking for businesses they can visit immediately, so longer hours give you more opportunities to attract them. Add your offers to the profile too, and if your business allows it, offer curbside pickup.

Plan for parking, too. Reserve a few spots near the entrance for pickups. If you need more, offer to rent a few spaces from a neighbor just for the holiday weekend. Many will say no, but a small business only needs a handful of spots, and some neighbors will gladly take a few extra dollars for them. Then tell customers where to park in your emails and Google Business Profile.

On Cyber Monday, extend the deal online for anyone who heard the ad but didn’t make it in.

7. Offer something free to win a higher-value customer

Giving away a small service can be a smart Black Friday strategy when it helps customers take the first step toward a much larger purchase. A limited-time offer gives them a reason to act now rather than keep postponing their decision.

Dental practices are a good example. According to Myra, 23% of adults have delayed dental treatment because of its cost. Offering a free initial consultation during Black Friday can remove that first financial barrier and encourage patients to explore treatments they might otherwise put off.

For example, a dental practice could invite patients considering implants, veneers or orthodontic treatment to book a complimentary examination and personalized treatment plan, with clinically appropriate imaging where needed. The dentist can explain the options, discuss installment payments if available and help patients understand the costs before committing.

And it’s not always just about money. Some patients feel anxious about visiting the dentist or discovering they need extensive treatment. A free, no-obligation first appointment can make that step feel less intimidating while giving the practice an opportunity to build trust.

The appointment can take place after Black Friday, as long as it’s booked during the promotion. For treatments involving a significant financial commitment, even a few new patients could make the offer worthwhile.

If there’s one thing I’ve learned from working with small businesses, it’s that a successful Black Friday campaign doesn’t have to be complicated or expensive. Sometimes, understanding your customers and coming up with a creative offer is enough to stand out.

My advice is to pick one or two strategies that make sense for your business, test them, and learn from the results. You might be surprised by what works.


Source link

How ‘Boring’ Businesses Can Win on Black Friday Read More »

Millions of People’s Wealth Isn’t in a Bank Account — It’s in Jewelry

Millions of People’s Wealth Isn’t in a Bank Account — It’s in Jewelry


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • When people inherit jewelry, emotional value and real financial worth collide. What they rarely understand is the asset itself.
  • This generational hand-off is occurring alongside a seismic shift in consumer behavior: the mainstream adoption of secondhand commerce.
  • The companies that win this transition won’t simply be those offering to buy these assets. They will be the trusted institutions that help heirs understand what they have and empower them to decide what happens next.

When economists and financial advisors talk about the Great Wealth Transfer, the conversation almost always centers on traditional financial assets: brokerage accounts, primary residences, retirement accounts and family businesses.

These numbers are massive, to be sure. Cerulli Associates estimates that $124 trillion will transfer through 2048, with $105 trillion passing directly to heirs. Nearly $100 trillion of that sum will originate with baby boomers and older generations.  

Yet wealth does not sit exclusively on a balance sheet. It lives inside our homes, stored in safes, tucked into back drawers and resting quietly in velvet jewelry boxes.

It’s estimated that half of the gold ever mined in human history exists today as jewelry. Millions of families are about to inherit gold jewelry, luxury watches, diamonds, heirloom rings, coins and precious metals alongside standard investment portfolios.

We are not just approaching a Great Wealth Transfer. We are on the precipice of the Great Jewelry Transfer. Unlike a stock portfolio or checking account, heirloom pieces rarely arrive with a neat financial statement telling heirs what they own, leaving many unprepared when it’s time to evaluate, keep or sell inherited jewelry.

Why jewelry creates a fundamentally different inheritance problem

When people inherit jewelry, emotional value and real financial worth collide.

Most heirs can tell you the backstory without missing a beat:

  • “This was my grandmother’s engagement ring.”
  • “My father gave this bracelet to my mother for their 25th anniversary.”
  • “I remember her wearing this necklace to every holiday dinner.”

What they rarely understand is the asset itself.

They’re left asking basic financial questions: Is this real? Is it worth $200 or $20,000? Does the value come from the gold, the quality of the stones, the brand or the item’s vintage status? And ultimately, what’s the right move: keep it, insure it, divide it among siblings or sell it?

Without clear answers on metal purity or stone quality, deciding whether to keep, divide or sell inherited jewelry becomes an educated guess made during an already stressful time. 

Furthermore, younger generations often don’t want to inherit physical clutter. Modern estate research indicates that millennials and Gen Z heirs prefer a small, curated selection of meaningful possessions over taking custody of an entire household’s worth of heirlooms.

Inheriting an asset and understanding an asset are two completely different things.

A collision course with the resale revolution

This generational hand-off is occurring alongside a seismic shift in consumer behavior: the mainstream adoption of secondhand commerce.

Buying secondhand used to carry a subtle stigma; today it’s a mainstream consumer movement driven by younger consumers who actively prioritize circularity, sustainability and the unique appeal of vintage items. According to data from Deloitte, the broader U.S. resale market is projected to reach $73 billion by 2028, while the number of U.S. fashion brands hosting resale platforms on their own sites increased 325% between 2021 and 2025.

For the jewelry market, this shift changes everything.

A piece one generation no longer wants to wear doesn’t suddenly lose its intrinsic value. Its lifecycle can seamlessly evolve: Kept → Valued → Sold → Recycled → Worn by someone new.

This expands the concept of a circular economy beyond traditional “cash for gold” operations. The next generation doesn’t have to choose between keeping Grandma’s jewelry in a drawer forever or shipping it off to a refinery to be melted down.

What we learned building Alloy

When I founded Alloy, our initial premise was straightforward: The traditional process to sell gold jewelry, or any other high-value estate piece, was unnecessarily opaque and fundamentally built to favor the buyer over the consumer.

After working with thousands of consumers, one thing became clear quickly: Many customers acquired their pieces through inheritance, estate management or a major life transition. We quickly realized our main job wasn’t just facilitating a sale; it was helping people understand what they actually owned.  

Solving that problem requires three foundational pillars:

  1. Transparency: What is the piece made of? What does it weigh? Where does its true financial value come from?
  2. Trust: Is the party evaluating this item financially incentivized to be dishonest about its value?
  3. Optionality: Does this piece actually belong in a refinery, or could someone else want to wear it?

That third pillar, optionality, is where the market’s future lies.

Alloy’s role: Building infrastructure for jewelry’s next life

Historically, the secondary jewelry market has been deeply fragmented. A consumer sells a piece to a local business. That business flips it to another intermediary. Some pieces get resold; others are melted. Throughout the entire process, the original owner has zero insight into the asset’s true destination or value.

At The Alloy Market, we are building the infrastructure to connect these fragmented lifecycles.

By providing upfront valuation tools, real-time calculators and educational resources, we empower consumers to understand the exact value of their items before deciding. When an item is sold, our ecosystem evaluates whether to reintroduce it to the consumer market as a wearable piece, returning a portion of that resale upside to the original seller or whether to return its metals responsibly to the industrial supply chain.

We’re not merely building a better way to sell inherited jewelry; we’re building the underlying digital infrastructure that lets high-value physical assets transition smoothly from one generation to the next.  

The ‘Great Jewelry Transfer’

Leaving things behind isn’t new. But we’ve never seen a handoff like this, where trillions of dollars in physical items land with a generation that thinks very differently about what’s worth keeping, selling or passing along.

Some inherited jewelry will remain in families for another century. Some will be sold for financial liquidity. Some will be melted for reuse. And a growing percentage will find a second life with a new owner who appreciates its history.

The companies that win this transition won’t simply be those offering to buy these assets. They will be the trusted institutions that help heirs understand what they have and empower them to decide what happens next.

While standard wealth management focuses on paper assets and balance sheets, the Great Jewelry Transfer is about what happens to the physical history families leave behind. Trillions are at stake, but the real value is in the objects themselves.

Key Takeaways

  • When people inherit jewelry, emotional value and real financial worth collide. What they rarely understand is the asset itself.
  • This generational hand-off is occurring alongside a seismic shift in consumer behavior: the mainstream adoption of secondhand commerce.
  • The companies that win this transition won’t simply be those offering to buy these assets. They will be the trusted institutions that help heirs understand what they have and empower them to decide what happens next.

When economists and financial advisors talk about the Great Wealth Transfer, the conversation almost always centers on traditional financial assets: brokerage accounts, primary residences, retirement accounts and family businesses.

These numbers are massive, to be sure. Cerulli Associates estimates that $124 trillion will transfer through 2048, with $105 trillion passing directly to heirs. Nearly $100 trillion of that sum will originate with baby boomers and older generations.  

Yet wealth does not sit exclusively on a balance sheet. It lives inside our homes, stored in safes, tucked into back drawers and resting quietly in velvet jewelry boxes.


Source link

Millions of People’s Wealth Isn’t in a Bank Account — It’s in Jewelry Read More »