How “Vibe” Investing Made Me $57,000 in Real Estate


When Obi Johns was a teenager, he saw his parents do something remarkable: they sold their home and made $150,000 from market appreciation alone. But then, months later, the investor who bought his childhood home sold it AGAIN for nearly $400,000 profit. Obi looked at his family and thought, “That should have been us.”

So, after graduating college with a degree he had little interest in, he quickly decided to get into the real estate game—but as an agent. As he grew, he saw his clients flipping houses and knew he wanted to do it, too, not just to make money, but to understand the buyer and seller in the transaction. Obi had zero experience, but he documented his first house flip on Instagram, which went viral overnight and led to 26 showings in a single day.

The best part? Obi didn’t use the copy-and-paste flipper finishes most buyers are tired of; he let his audience decide the design—and it worked. Obi walked away from that flip with a $40,000+ profit, and the next one was even bigger. Obi details his entire “vibe flipping” model to get over-asking offers in a matter of days, and how you can test as you invest in your first deals, too.

Henry:
When Obie Johns was a teenager, he saw his parents do something remarkable. They sold their home and made $150,000 just from appreciation. But then the same investor who bought his childhood home sold it again for nearly $400,000 more. Obi looked at his family and though, “That should have been us.” As soon as he graduated college, he knew what he wanted to do, real estate. And at just 21 years old, Obi became an agent. He bought his first duplex with 5% down and he house hacked it. But after that, he went in a very different direction. Obi saw his clients flipping and though, “I can do that too.” Zoe bought his first flip for $153,000 with zero experience, and he documented every step of the journey on his Instagram. And from that, he went viral and got 26 showings in a single day. And the best part, he let his followers decide the finishes and the design for the house.
He calls it vibe flipping. He made over $40,000 on his first vibe flip and even more on more recent ones. So how did someone starting at 21 with zero experience beat out all the experienced investors in the market? Today, Obi is showing you how.
What’s going on everybody? I’m Henry Washington. I am the co-host of the BiggerPockets Podcast and my co-host Dave Meyer is here as well. And we’ve got an investor story today with Obie Johns from Columbus, Ohio. So let’s bring on Obi. Mr. Obi Johns, welcome to the BiggerPockets Podcast. I hear congratulations are in order, man.

Obi:
Congrats to you.

Dave:
Yeah. Expectant father.

Obi:
We are excited. Yeah, we’re about 12 weeks in.

Dave:
That’s awesome.

Obi:
So we should be finding out if it’s a boy or girl pretty soon. We’re pumped either way. I’m feeling like it’s a boy, so we’ll have to come back and see.

Henry:
All right. We got a couple girl dads here though.

Obi:
Okay. All right. I’ll be reaching out for some real estate advice and maybe some fathering advice.

Henry:
Awesome. Well, now we can get started. Why don’t you tell us about how you got into real estate and give us a little bit of your background.

Obi:
Yeah. My name’s Obi Johns. I am a realtor of five going on six years now. I went to Ohio State. I was majoring in political science and it took me about four years and a college degree to realize that I didn’t love politics and a little bit of money as well that I gave them to figure that out. And so I graduated into COVID, real estate was booming, 3% rates. Everyone’s talking about investment properties and I was looking at a career pivot. And so I figured, you know what? Now’s the time to figure out if this real estate thing works for me. I hear stuff about passive income, financial freedom from pages like BiggerPockets. So I started getting my real estate license. While I was getting licensed, I dabbled in a little bit of wholesaling, got licensed, bought my first rental property, did a house hack, dabbled in flipping.
I tried everything that I learned from podcasts and books. I wanted to make sure that I knew what the full extent of real estate investing looked like. And so I’ve basically tried every way to real estate invest. I’m actually sitting in what is going to be our first short-term rental. I think that was maybe the last box that I needed to check. And it’s been a good five years.

Henry:
And I’ve heard you say a few times that you knew you wanted to be an investor. I knew I wanted to be an investor. Where did that seed get planted? Because that sounds like more than just I watched a podcast.

Obi:
Yeah. Well, right before I went to college, my parents sold our childhood home. They bought it for $80,000 in the late ’90s. And we ended up selling it as a fixer-upper about 20 years later for, I want to say like $230,000. And to me, I just though that was crazy that we got to live in that house for 20 years and my dad got paid to live there. We didn’t really do a whole lot of improvements to it. It was just a good location that appreciated. But what surprised me even more and what got me really intrigued in real estate is when the investor who bought it from us put it back on the market three months later for $600,000 and he got it. He sold it pretty quickly.

Dave:
Wow.

Obi:
And I just couldn’t help but think, why couldn’t that have been us? Why couldn’t we have taken it to $80,000 purchase, $600,000 sale? Him doing it so quickly just made me think this is something I need to figure out.

Dave:
So you were an agent before you did your first deal?

Obi:
That’s correct. My first deal was helping someone sell their first house actually. I did retail and investor business for about a year or two until I bought my first property, which is a duplex. Everyone’s saying house hacking, great way to get into real estate. I was able to buy a house and spend half what other people are spending to live in a home. And I got to ride appreciation on a property that someone else is paying half the payment for.

Dave:
You’re an agent, so did you just find this deal on the MLS? What was your buy box like when you went out to buy this house hack?

Obi:
So I actually found it, I want to say somewhat off market. I was going to real estate meetups in my city and I met an investor who flips 50, 60 houses a year. He keeps a lot his rentals. So we met, I followed him on social media and I see on his story one day that he is taking a video of a duplex that he’s almost done renovating and he was going to rent it out. And it was at a very small buy box when I was looking for our first house. I was actually looking in my childhood neighborhood that we sold our first home. And so there’s not a lot of inventory. There’s probably 100 duplexes in the entire area that I was looking. Most are rented out. They’ve been rented for 15 years and they don’t hit the market very often. So I saw his story.
I asked him where that duplex was. He gave me the address. It was three blocks from my childhood home.

Henry:
That’s crazy.

Dave:
Awesome.

Obi:
Perfect. And I said, “Can I please come see it? I will be there in 20 minutes.” And so I went over, I looked at it. It was 90% done. He was just doing the finishing touches. I loved it right away. My wife and I, we had been renting a one bedroom apartment and we had been thinking about –

Henry:
Oh, you would’ve loved anything you saw then is what I meant.

Obi:
Well, yeah. So we just needed space. We needed out of the bedroom/office that we were working out of.

Dave:
This is exactly how you convince people to house hack. Henry and I talk about this all the time. Everyone’s like, “Oh, house hacking, it’s so inconvenient.” But if you’re coming from a studio apartment that you’re sharing –

Obi:
Yeah, you’re in a one bedroom, anything is more convenient.

Henry:
It’s a Taj Mahal.

Dave:
Everything’s better.

Obi:
So we toured the house. I needed to get my wife on board. She lived in newer homes mostly growing up. And in Columbus, our zoning code is a bit strict. So most of the duplexes are going to be a hundred years old because in the 50s, 60s, I kind of stopped zoning for multifamily. So a hundred-year-old duplex was our only option. And this one was fully renovated. It had an open layout kitchen, everything that my wife was expecting in her first home. And so we ended up making our compromises. I don’t think that she thought our first home would also inherit renters or we would rent out half of it. And I didn’t necessarily need to have the flashy open layout and everything.

Dave:
So

Obi:
It

Dave:
Just

Obi:
Really worked out for us.

Dave:
That’s perfect. And how’d you finance this deal?

Obi:
We went conventional. I want to say it was a low down payment, maybe 5% down just with a lender that I worked with a lot on referring to my clients as a realtor. So it was pretty smooth.

Dave:
Were you able to cash flow right away?

Obi:
So I want to say that we were probably about breaking even when we first moved in. It was a lot cheaper than other rentals would be. I think we were looking at 2,200 for a two bedroom apartment at the time.

Dave:
Oh, Columbus got expensive,

Henry:
Right?

Obi:
Columbus got pretty pricey and post – COVID, and we’re not far from OSU campus. There’s just a lot of people moving here for college, and so there’s a lot of demand. I’d say between 2000 and 2200 would get you an updated two bedroom apartment. Our mortgage on the duplex was about 3,400 and we rented one side out for 18, so that left us with maybe 1,600 that we were paying ourselves. So we looked at it as a win that we were getting an extra bedroom for $600 less than the market would’ve allowed us.

Dave:
Huge win.

Obi:
And once we move out of here and get both sides rented, we should cash flow, I want to say about $500.

Henry:
We’ve got to take a pause, but we’ll be right back with more from agent and investor Obi John’s right after the break.

Dave:
Before we go to break, if you’re someone who’s bought a couple of deals and you’re looking to scale up your portfolio into something bigger, I have a really exciting announcement for you. BiggerPockets is hosting its first ever conference focused just on scaling up. It’s this December, it’s coming up soon, this December, 5th through 7th in Phoenix, Arizona. We’re going to have a full day of programming with speakers like myself, James Daynard, Kathy Fecke, and Devon Kinard talking about how to scale up and build a sustainable business. Tickets are on sale now, but there are only 100 tickets. So go to biggerpockets.com/conferences now and get your ticket today.

Henry:
What’s going on everybody? We are back on the BiggerPockets podcast. We’re talking with agent and investor Obi Johns. Let’s dive back in. You did a house hack and you were like, “This is pretty cool.” Then you said you were looking at doing a flip. So I’m very curious, were you trying to do a flip in that same childhood neighborhood too, like you were trying to get back what you lost on the first house?

Obi:
Somewhat. So I worked with a lot of flippers and I knew the process from underwriting the deals to what people want in a finished product when it’s time to sell the house. I knew the full beginning and I knew the full ending, and I wanted to know everything that my clients go through when they’re flipping a house, like working with contractors and financing the project. And so I figured this would be great experience to flip a house that way when I speak, it’s from personal experience and not just I’ve seen this work, this is what worked for me. And I think it made me a lot more confident as an agent because there just wasn’t any question anymore on what you had to do to successfully flip a house. So I decided I’m going to give this a shot. Part of the inspiration was when we bought this duplex, and we loved the house, we’re so happy how it worked out, but a couple months into closing, our sewer line collapsed.

Henry:
Been there, buddy.

Obi:
And so you know what that situation looks like and smells like. It’s not a pleasant position to be in. And it cost us about $7,000 to get it excavated.

Henry:
Oh, you got off light.

Obi:
We’re right next to the city line, so they didn’t have to dig very far and they didn’t have to put in a whole lot more. But seven grand was a lot for us when we just put down our down payment and we’re furnishing two extra bedrooms that we didn’t have. And we had, I want to say a month or two of vacancy just as we did all the final touches to the property. So it definitely hurt a little bit. And so I said, “You know what? I’m going all in on real estate. I’m not going to let this deter me.” And so I wanted to buy another property and I figured if I make a profit on this flip, I can pay myself back for what we just had to spend on our sewer line, all that money we just buried in the ground and I would get my confidence back to keep pushing in real estate.
We actually found it off market for, I want to say $153,000. It was about 10 minutes away from where we lived, so not quite the same neighborhood, but I was familiar with the area. It didn’t need a whole lot of work. It was mostly cosmetics. We finished the basement, painted, did some roof work, gutters, not a whole lot. It was a pretty simple project. We put in, let’s say around $40,000. I documented the whole flip day by day on Instagram. This is actually how I kind of started doing social media a bit more. I made a series about flipping my first house. Episode one, I went in there and they left a bunch of stuff behind. They weren’t supposed to leave it, and so we had to clear out the house.

Dave:
In there, yeah.

Obi:
And then we find things that we didn’t see on our initial walkthrough. And so it was just day by day, problem by problem, ended up going very viral on social media. I want to say the series got over seven million views. Whoa. A lot of offers from the videos that I was posting because we started posting it on the day that we started. That’s great. And so I was getting comments halfway through of people saying, “Where’s this house? It looks like it’s something that my clients are into.” And so when we listed it, we actually set a record in the zip code for most single day showings. What? We had, I want to say 26 showings in that first day, which this is 2024. This isn’t COVID like 2020. It was the most in the whole zip code. We ended up getting 10 offers on the first day.
I want to say three or four came from agents who either their clients were following the series online or they were following it and they recommended it to their clients. We ended up going 25,000 over the list price and ended up making 44 grand on that first flip.

Dave:
Unbelievable. That’s amazing. Congratulations.

Henry:
That’s awesome.

Dave:
And so why aren’t you doing it again?

Obi:
I mean, it was stressful. It was awesome and it was a great experience, but I’ve learned to tolerate the stress of being an agent and flipping a house is just a different kind of stress. Once you go through it, you kind of figure it out, but it just wasn’t the stress that I chose. I didn’t feel the reward. I mean, it was very profitable and I loved that about it, but it wasn’t as rewarding as helping my clients get their wins or helping people into their first homes. And so it didn’t feel like the stress was outweighed by all the benefit of the project.

Dave:
Obi, I am so glad you just said that. I think this is the most overlooked part of being a real estate investor because there’s so many things that you can do, but the only way you make money in real estate is if you could stay in it for the long game. That’s how you do it. And if you don’t like doing something, it doesn’t matter how profitable it is. You’re going to burn out at some point. That’s why I don’t flip. I’ve passively invested in flips, made some good money, but it’s just not for me. And I think the way you described it is perfect because every job has stress, everything has stress, but you can tolerate the stress of being an agent. It’s such a perfect way to say it. That’s something you can live with and that you feel like that stress is balanced with the reward that you personally feel from helping people get into a home or to sell their home.
And that just the flipping doesn’t do it for you. Henry, you’re probably just the opposite, right? You’ve never wanted to be an agent and you love flipping homes.

Henry:
Absolutely.

Dave:
And that’s why you’ve been able to sustain your business for 10 years.

Henry:
Wholeheartedly agree with you. I loved everything about that answer and the previous answer in saying, “Hey, I had to make a choice. Do I want to flip houses or do I want to be a good agent?” Because when people ask me, should I get my license, my response to them is, “I don’t know. Do you want to be a really good real estate agent and help people buy and sell homes?” And if the answer’s yeah, then heck yeah, go get your license. But if it’s not, then I would probably wait, do a couple of deals and then figure out if your license makes sense for the kind of investor you want to be. Dave, you’re absolutely right. Being an agent sounds like my nightmare. I don’t want anything to do with that at all, but I understand the warm fuzzies of helping someone. I get mine a different way.
I get mine through flipping houses and providing good rental properties and teaching people how to do this business. But it’s all hard, y’all. It’s all hard. Yeah, exactly. Not doing real estate and just working a day job until you retire is hard too. You got to pick the hard that makes sense for you and it’s going to be different for each person. What a great answer.

Dave:
So Obi, I wanted to ask you, you brought up social media because you have a great social media account. Did you expect your series to catch on in the way it did?

Obi:
I thought it was interesting. I would’ve been interested in following it. The quantity of views and interactions and everything surprised me. I didn’t know that it would be that crazy, but I did know that it was a cool story. I framed it as me buying my first house and us running into a huge repair that made me wonder if real estate was even the right thing to do. And flipping this house was supposed to be the hero story of like, yeah, we made it back. We got a big win. But the scary part was I started filming and posting before I had sold the flip. We were still working on it. And I sat down with my wife after the first video went viral, millions of views. I got a hundred thousand followers in a span of maybe a few days. And I told her, “What happens if we don’t profit?
What happens if we lose it on this house too? And what happens as my reputation as an agent if I just put myself out there and it doesn’t work?” And we talked about it and the conclusion we came to was I think that people will feel inspired that you tried and this isn’t going to be your last try. You’re not going to stop if this doesn’t work out well. And so I started off a little bit nervous and then I just felt really comforted by the support that I was getting online. People saying, “I don’t know you. I just met you, but I believe in you. You got this.” And I needed that. It was good to hear at the moment. So it did a lot for my career. It did a lot for my confidence as well.

Henry:
This is really cool, man. There’s tons of people who want to share their story on social media. What advice do you have to those people and what experience? We talked a little bit about the positives, how it’s impacted you. Has there been any downside to you having a social media presence in your business or personal life?

Obi:
For me, coming from the angle of I’m just going to give things a go and document it, I think that’s what works really well right now on social media. There’s a lot of people who have all the answers, but –

Henry:
They think they do.

Obi:
A lot of people who say that they’ve got all the answers and there’s less people who admit that they don’t and are willing to be vulnerable and take you through the experience with you.

Dave:
That’s what people resonate with is it’s hard to connect with someone who pretends they know all the answers. No one does. And so you’re actually connecting with how other people really feel.

Obi:
I agree with that. You asked have there been any downsides? It takes a lot of time to do social media. And right now I’m a one-man team. Hopefully by the time this airs, I’ve got some assistance because it’s something that I’ve been looking to do, but I love making the videos. I love telling the stories, and so it’s been hard for me to hand some of that over. And I would say it took about a few years before I really started getting a great return on that time spent. This year, about 80% of my business came from social media, and I’m probably three years into doing social media. Even when I did that series and I got a bunch of followers, it didn’t immediately turn into a bunch of deals. It turned into a lot of support and it turned into my name being out there.
But then people are like, “Hey, you’re the guy who flipped your first house. My cousin wants to do their first flip.” And it just kind of started to… We pushed the snowball and it took a little while before things really picked up, but now I’m spending less time in content and getting more results from social media than I was a couple years ago.

Henry:
All right. We’ve got to take a quick break, but we’ll be right back right after the break. All right, we are back on the BiggerPockets podcast. Let’s jump back in. So what happened? Did you do more flips? Have you pivoted into rentals?What came next and how would you define yourself as an investor?

Obi:
Yeah, so after that first flip, I took a pause on buying properties for a little bit. Part of me almost thought maybe I got lucky with how everything turned out, and I didn’t want to prove to myself that maybe it was luck. So I just focused on helping other people buy their properties and I got a little antsy. I did purchase another property. I got into partnering with some other investors. Don’t know if I’m the one to coin this term, but I got into what I like to call vibe flipping. Have you heard of vibe coding?

Dave:
Yes.

Obi:
So I think that a lot of flippers, they have a list of all the finishes that they’ll do. They’ll do Greek villa or agreeable gray on all the walls, and you’ve got the same white shaker cabinets. And through my first flip, I actually put a lot of the design choices on my Instagram as polls and let people pick what we should do. And it turned into a really unique product on the market that stood out from other properties. And if I’m posting an option that gets 80% of the vote, I’m going to assume that buyers will also agree that 80% of buyers would prefer that over something else. And so it actually was a weight lifted off of me having to figure out what design choices I had to make, and I let my audience do that, and it turned out really well. We had a unique property that we put on the market, unique colors that we put in different rooms.
We flipped the mid-century modern house earlier this year.

Dave:
They’re the best.

Obi:
And that one was really fun to design. We left a lot of the design up to our audience, and we ended up getting a buyer from Oregon who found it on Zillow, and they just though it was the coolest house that they’ve ever seen and they wanted to move to Ohio. And so maybe my advice to people who want to get into flipping is use your own creative taste on your project because I think that your product will stand out. And across the flips that we’ve done, I’ve averaged five days on market when Columbus’s average days on market is maybe 30 or 40.

Dave:
Wow. Dude, it’s so good because so much of the advice about real estate investing is build a system. And you do need some systems, but taste and design is hard to systematize when you’re trying to apply them to homes that are inherently different. And if you took those gray colors you named and the luxury vinyl plank and put that in a mid-century home, that’s a travesty. You shouldn’t do that. And everyone would hate it. And I look at Zillow, everyone knows when you walk into a flipped house, especially in your neighborhood or in your market, because they all copy each other too. And so you’re like, “Okay, I know these exact floors. I know these pendant lights, and I’m already skeptical of the quality of this home because it was probably someone who was mailing it in and didn’t spend the time to actually think about how to make this house great.” And I think a lot of that, just rinse and repeating, gives flipped homes a bad name and people don’t want to buy them.
And if you actually demonstrate that you care about the finished product and that the people are going to enjoy living there, lo and behold, you find people who actually want to live there. It makes so much sense to me.

Henry:
When I first got into flipping, our first few flips just sold so fast, and it was because we cared about the design and each one of them were different. And I wanted them to cater to who that buyer is in that specific neighborhood for that specific house. And that isn’t a copy paste on finishes per house. So I just love giving people something that they aren’t expecting in a home and that helps them to sell faster. Now, is that harder to systematize? Absolutely. But can you create systems around that? Yeah, you can do that as well. And especially now in a market where eyeballs are limited, the better your design, the more eyeballs you’re going to get. And in every single market, there’s a number of how many eyeballs it takes to get an offer. So the more eyeballs you can get into your property because your design is unique and amazing and shows you care, the more offers that you’re going to get.
So it’s vibe flipping, but it’s also profitable.

Obi:
Definitely. The most recent flip that I did, it made $57,000 and it followed that same process of how do I make this feel like it’s going to be someone’s home, not just how do I turn this from an ugly house into something that is inhabitable, but how do I make it feel cozy? Totally. And I think that’s what leads to properties increasing your margin on a flip is yes, someone can live here now, but why will someone want to live here?

Dave:
That makes you feel good when you sell a home too. It’s like it’s profitable, but because you created something of value, not just because you were able to pawn it off to the next person. I also just want to shout out and say, because Henry and I talk about this all the time, this also matters for rental property investing.

Henry:
Absolutely.

Dave:
People love to just turn their rental properties with the same crappy cabinets and countertops and luxury vinyl plank floors, and no one wants to live there or they will, but they’re going to leave at the soonest opportunity that they can because you don’t make it feel like a comfortable place to live. It’s not valuable. You’re not making something that is a great place for your tenants to live. It’s not a good customer experience. And so vibe flipping, Obi, you got to brand this one for us. I’m terrible at this, but something where you also create a vibe also applies for rental property investing as well.

Henry:
Well, this has been really cool, Obi. I appreciate you coming on the show, being super transparent about your journey. And I think it’s such a practical episode because of your age. There’s a lot of people who are your age who are right now trying to navigate all of these same decisions, and you kind of did it all. You became the agent, you listed houses, you house hagged, did some flips. You said you’re sitting in a short-term rental right now. And so for the investors who are listening, who are curious and cautiously considering jumping in right now, given the state of the market, what path would you recommend somebody in a very similar position take?

Obi:
For me, at the end of the day, I wanted to do something that I enjoyed, and so I didn’t want to leave any options on the table. I wanted to experiment with each of these different ways to invest in real estate to see what really felt good because if you don’t like it, you’re not going to want to wake up and do it first thing in the morning. And so I think it’s obviously in real estate there’s risk, but if you’re an intelligent person, you can navigate that risk and you can attempt any of these approaches relatively new without much experience. My most recent flip, it was 100% financed. I didn’t use any of my own money to flip that house that we made $57,000 on. You don’t need to use your own money. There’s first time home buyer loans, like our duplex, we only had to put 5% down.
There’s a lot of ways to get started. I think you just have to give it a go and don’t convince yourself that you’ve got to get it right the first time when you pick maybe the first way that you want to get into real estate. It’s the experience that you’ll get from that can transfer into other forms of real estate investing. And so that’s something I learned pretty early on when I dabbled in wholesaling and then I got my license and became a realtor. I was having the same conversations on the phone with sellers who needed to put their house on the market. I was just able to offer them different ways to get the job done. So I would say there’s really no barrier. All the information is online. It’s on podcasts like this. There’s so many resources out there and money is not a barrier.
You don’t need a lot of money to get started and you don’t have to pick the best way to start. You just have to give it a go. And from there, the momentum will take you into wherever you really want to end up being.

Henry:
I like that because if you’re going to start with a single family home, the risk is a whole lot lower, right? A house very rarely goes from worth something to worth nothing. So even if you’re not as profitable as you want to be, or maybe you don’t even make a profit on your first deal, if you start with the smaller single family home, what you’re doing is exactly what you said. You were like, “I am learning what I want to be as an investor. I don’t know yet.” And I think a lot of people want to decide what kind of investor they want to be before they’ve ever done a deal, and you will learn so much through your first real estate You’re going to learn what you want to do again. You’re going to absolutely learn what you never want to do again. You might learn you never even want to do real estate again.

Dave:
Also fine, if you’ve tried it.

Henry:
Yes, if you’ve tried it. There’s a difference between getting the bug and then actually defining yourself as a real estate investor, and it takes some experience before you can actually do that. And so I like the concept of let’s put some skin in the game, let’s get started with something lower risk, and let’s learn about who we want to be, what we want to buy, where we want to buy, how we want to buy. There’s too many things to learn on the front side and be able to apply without never having done it. Now, can you leave us just with a little bit on where are you now as an investor? And then knowing what you know now about the market, you just left BP Con, what are your future goals for real estate?

Obi:
So right now it’s still just the duplex that we house hacked. I mean, with rates being higher, I am seeing a lot of my clients pivot towards flipping homes and having a lot of success in flips. Properties that will cash flow a couple hundred dollars might make you 40,000 on a flip, 45,000 on a flip. In my market, Columbus, there’s still a lot of buyer demand even in other places in Ohio. I hear Cincinnati is a really great market. Even the smaller cities like Dayton are performing really well. So I am hoping to guide more clients through their flips, changing their life off of their first flip is something I did myself and it’s something that I think other people should do as well. I like being an investor friendly agent. I love also just helping people get into their first home. So I’d say from here, it’s spending 90% of my time being a realtor and helping people accomplish their real estate goals.
I might flip a house a year just to make sure I keep up with the trends and what the market looks like. I’ve already had my fun in it and now I like to share some of those good deals with the clients that reach out to me looking to get into flipping. So hopefully level up my transactions. We hit, I want to say top 5% and the brokerage last year. I don’t know how far I am from top 1%, but that’s something that I got to keep pushing until we see that number. So it’s just scaling my agent business, doing more transactions and helping people let real estate change their lives.

Henry:
This is cool. You’re wise beyond your years, my man. You’ve learned a lot of lessons that a lot of people in their 40s haven’t learned yet.

Dave:
That’s true. How old are you? Can I ask that?

Obi:
I’m 28. I’m 28.

Dave:
Oh, wow. Yeah, you are wise beyond your years. Well, congrats on all your success, Obi. It’s awesome to hear your story, to hear all the things you’re doing in real estate. Congrats on the social media and most importantly on your growing family. It’s super exciting.

Obi:
I appreciate it. Thanks, Dave. Thanks Henry for letting me share.

Henry:
Well, you can’t get out of here just yet. You got to let people know where they can find you or follow you or learn more about what you do.

Obi:
I’m probably the only guy named Obi that will come up when you do a Google search. So you can search me online, Obie Johns. I’m on Instagram @soldby. Obi, and I’m sure my email or something will be in the description. You can reach out to me directly if you’re looking to invest in Ohio, Central Ohio.

Henry:
Boom.

Dave:
Thanks again.

Henry:
All right everybody. Thank you so much for listening to this episode of the BiggerPockets Podcast. As always, we’ll see you on the next episode.


Help us reach new listeners on iTunes by leaving us a rating and review! It takes just 30 seconds and instructions can be found here. Thanks! We really appreciate it!

Interested in learning more about today’s sponsors or becoming a BiggerPockets partner yourself? Email [email protected].


Source link

How “Vibe” Investing Made Me $57,000 in Real Estate Read More »
A Country Club Built Around a Private Racetrack? Why Exclusive Experiences are the Biggest Trend Among The Wealthy

A Country Club Built Around a Private Racetrack? Why Exclusive Experiences are the Biggest Trend Among The Wealthy


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • APEX Motor Club, a 280-acre facility in Maricopa, Arizona, swaps golf courses for race tracks and offers 240+ track days a year.
  • Members, including business leaders, value being “motorsports people” rather than celebrities.

Country clubs are an American tradition among those wealthy enough to afford them. But as unique experiences become increasingly coveted, many members are looking for more exciting alternatives to a golf course and some fancy hors d’oeuvres. Enter Apex Motor Club.

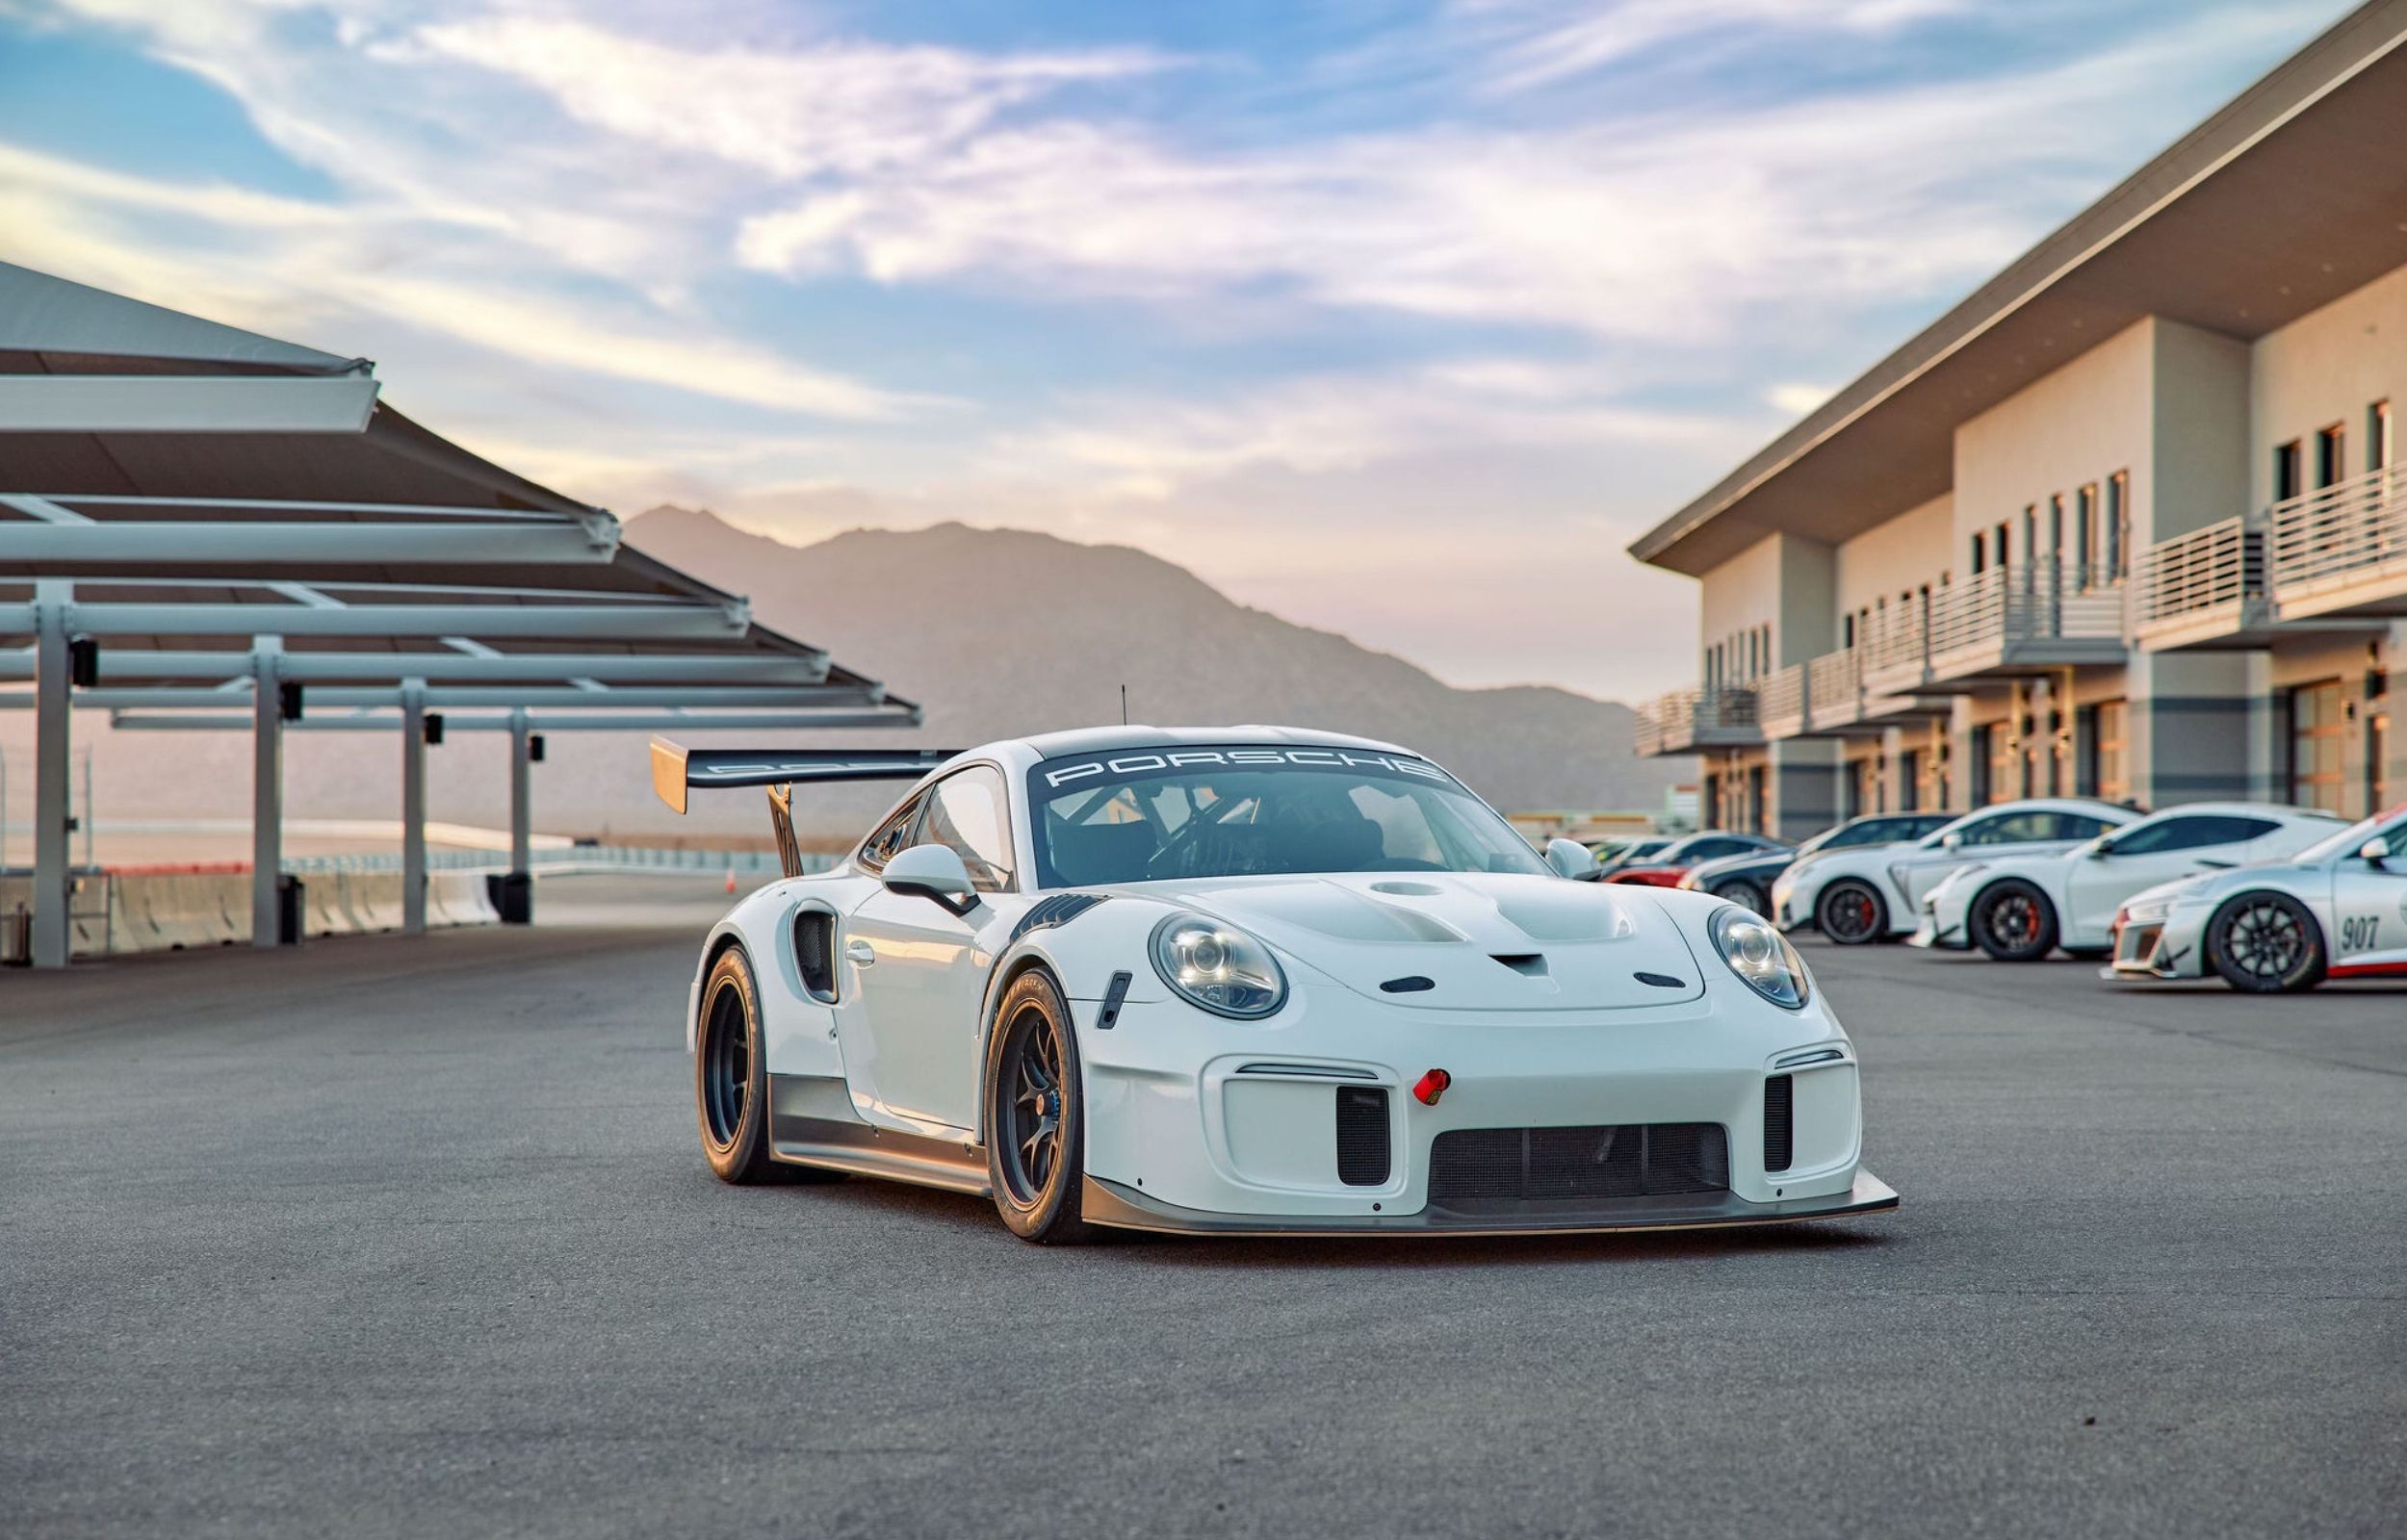
APEX Motor Club is a private motorsports club in Maricopa, Arizona, built around cars, community and competition.

As COO, Bill Barba puts it, “We’re similar to a country club, but instead of golf courses, we have race tracks.” 

Costs and culture 

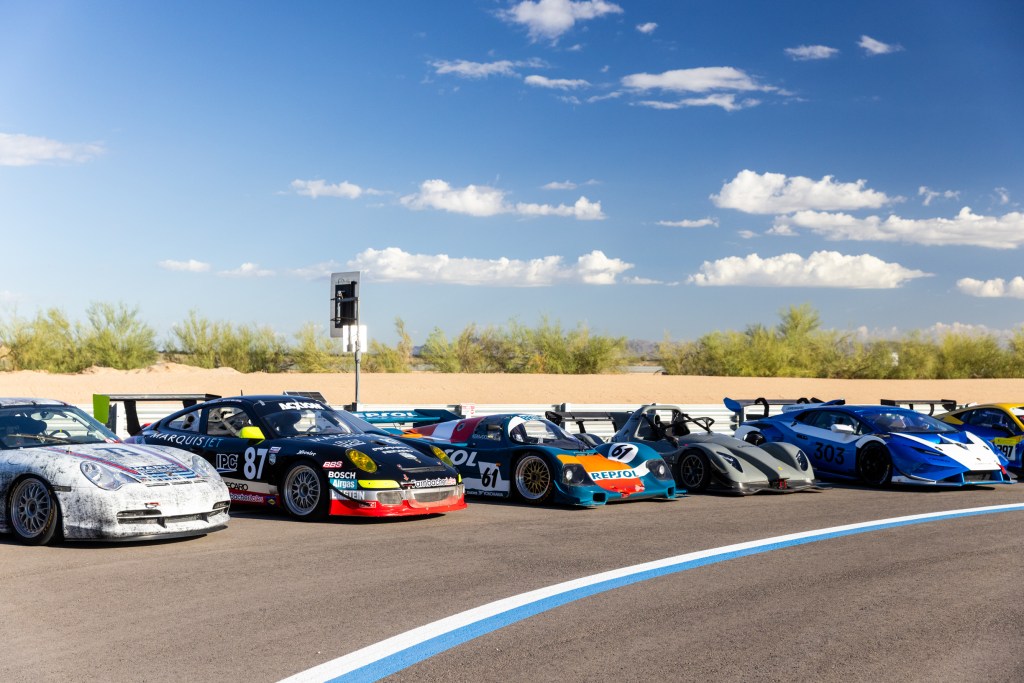
The Club is a 280-acre facility featuring 2 race tracks, a six-acre skid pad, 96 trackside garage condos, a drivers’ lounge and a clubhouse. 

The goal is to give motorsports enthusiasts a place to share that passion with others, including their family members. At the same time, the exclusive luxury landscape offers an escape from the pressure of running a billion-dollar company, as some of its members do. 

“We’ve got members whose names are known,” Barba says. “They run global companies, plus some local entrepreneurs that built great businesses. Motorsports are interesting because they all share the joy, rather than expecting to be Mr. or Mrs. So and So when they’re out here. That’s part of the culture we’ve created.”

There are two primary membership types: Gold, a $70,000 initiation fee plus an annual $8,000 fee and Platinum, a $90,000 initiation fee plus an annual $15,000 fee. The two are similar, offering 240+ annual track days, transferable membership and family access, with Platinum offering event host days. They also recently introduced a one-year membership for $35,000 and an under-35 membership with a $25,000 initiation fee plus $4,500 annually. 

“Motorsports is not a cheap endeavor,” Barba explains. “To run a car for a weekend out here, you go through tires, brakes and maintenance. Depending on the type of car, that cost can go up quite a bit.” 

While APEX provides the location and platform, members must maintain their own cars. Some have small teams doing only the necessary maintenance, while others come to the track with five people analyzing the data behind each lap. Some look to shave milliseconds off their cornering, while others just want a place to let the fancy ride they just bought rip. 

Image credit: APEX Motor Club

Driven to drive 

APEX’s business model includes partnerships with luxury car companies. They have a deal with Lexus, which brought out cars to join the APEX fleet. They also have a relationship with Aston Martin, which has an on-site presence in their garage condos. The local McLaren Scottsdale, one of the country’s highest-volume McLaren dealers, is a corporate member of the club. 

Companies will also rent the tracks for events, including Ferrari, Mercedes and Porsche.

“It gives them a chance to put people who aren’t necessarily enthusiastic enough to join a club on a track to understand what the car can do,” Barba explains. According to him, 85% of the engineering in performance cars never shows up on the street. At APEX, someone might own their fourth Porsche 911 but never experience its full power until they get on the course with an instructor. 

“The guy who buys or leases a Lamborghini to park at the valet is not a member of a motorsports club,” Barba says. “Our members tend to have more enthusiasm for the vehicles. Then there’s a whole different area of what level of racing they may want.” 

While most members are interested in track time, Barba estimates about 20% take wheel-to-wheel racing seriously. For them, APEX runs an 11-race series with 10 to 25 people per race, depending on the car. “Some people love it and thrive on the competition and pushing the car. Others want to enjoy the tracking and their times, but not race,” Babra says. 

A family affair 

What sets APEX apart from the competition is its family policy.

“If you join APEX, your spouse and kids are a part of it, and we don’t age them out,” Barba shares. “What we saw historically was that a lot of clubs would age kids out, and then they’d have to buy a membership. We want kids to stay as long as possible because it keeps parents, grandparents and everyone else engaged. So it’s a family membership because we want it to be a family experience.” 

This plays into a larger theme among the wealthy: finding the “new inheritance.” Rather than passing down expensive paintings and big houses, rich parents want to give their kids something more meaningful and personal.

One option is their passions. “Members will talk about the first race car they had, the first time they reached a certain speed, or the first time they watched their child drive a car,” Barba says. “It’s a passion that passes down, and it connects back to what I believe is most potent about motorsports: the emotions.” 

One example is the Bacon family. Seth Bacon had built a successful logistics business focused on organ donations and sold it. Looking for a way to spend more time with his teenage son Jace as he approached adulthood, he found an unexpected solution: racing.

“He was about to turn 16 and get his driver’s license. He’s getting a job. He was busy in school. He’s about to go off to college, and I thought this is that period where he’s beginning to separate himself from the nest,” Seth says. “I wanted an opportunity for us to still do something tight together.”

The two visited APEX to watch a few races. Before long, they bought a pair of Radical race cars and hit the track themselves.

“Instead of the son ignoring him at 16, they’re working together on racing,” Barba says with a laugh.

At Jace’s first race at another club in Nevada, father and son competed together, with Jace winning. 

“It made a real impact on the dad that out there, his son is an equal with guys who are running billion-dollar companies,” Barba says.

The Bacons could take their cars to any track, but few offer the built-in community they’ve found at APEX. 

“There’s a lot of senior drivers, a lot of retired professional drivers who are members there, and everywhere we go, they’re always checking in on him, asking about his career,” Seth says of Jace. “It really is more of a community of people who are willing to support one another, not only on track, but also, how did that business of yours go? Did you get that acquisition you were looking for? What do you need next?”

Business connections are great, but at the end of the day, APEX is about cars, community and competition. A hole-in-one is unforgettable, but the average day on the golf course doesn’t necessarily make the lifetime highlight reel. Driving a luxury race car at breakneck speeds on an open track? That’s an experience that’s not only incredible, but repeatable.

Key Takeaways

  • APEX Motor Club, a 280-acre facility in Maricopa, Arizona, swaps golf courses for race tracks and offers 240+ track days a year.
  • Members, including business leaders, value being “motorsports people” rather than celebrities.

Country clubs are an American tradition among those wealthy enough to afford them. But as unique experiences become increasingly coveted, many members are looking for more exciting alternatives to a golf course and some fancy hors d’oeuvres. Enter Apex Motor Club.

APEX Motor Club is a private motorsports club in Maricopa, Arizona, built around cars, community and competition.

As COO, Bill Barba puts it, “We’re similar to a country club, but instead of golf courses, we have race tracks.” 


Source link

A Country Club Built Around a Private Racetrack? Why Exclusive Experiences are the Biggest Trend Among The Wealthy Read More »

9 Hidden Technology Challenges That Can Slow Business Growth

9 Hidden Technology Challenges That Can Slow Business Growth


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Business growth depends on more than increasing revenue and attracting customers.
  • The technology decisions companies make behind the scenes can determine whether they scale successfully or struggle with rising costs, operational inefficiencies and missed opportunities.
  • Outdated systems, inefficient technology infrastructure, poor data management and cybersecurity risks can quietly limit scalability and profitability.

For most entrepreneurs, growth is the ultimate measure of success. Expanding into new markets, acquiring customers, increasing revenue and building stronger teams are often the priorities that dominate strategic discussions.

However, one critical factor frequently receives less attention: the technology infrastructure supporting everyday business operations.

A company might have an excellent product, a growing customer base and an ambitious expansion strategy, yet still struggle to scale because its internal systems cannot keep up with increasing demand.

Technology challenges rarely appear overnight. They develop gradually through outdated software, disconnected applications, inefficient databases, inadequate security measures and technology investments made without a long-term strategy.

These issues may seem manageable during the early stages of business development. But as organizations grow, even minor inefficiencies can become expensive obstacles.

Understanding these hidden challenges is essential for entrepreneurs who want to build businesses capable of sustaining long-term growth.

1. Outdated technology can create unexpected operational costs

One of the biggest challenges growing businesses face is their dependence on outdated technology.

Many organizations continue using software and infrastructure implemented years earlier. These systems may still perform their original functions, making replacement or modernization appear unnecessary.

However, maintaining older technology can become increasingly expensive. Outdated systems may require specialized technical support, frequent maintenance, manual workarounds and additional resources to remain compatible with newer applications.

The financial impact extends beyond direct maintenance expenses. Employees may spend additional hours completing routine tasks, departments may struggle to exchange information, and customers may experience slower service.

These inefficiencies reduce productivity and make it harder for companies to respond quickly to changing market conditions.

For business leaders, the important question is not simply whether existing technology still works. It is whether that technology continues to support the organization’s future requirements.

Regular infrastructure assessments can help identify systems that are becoming expensive to maintain or increasingly difficult to integrate with modern business applications.

2. Disconnected business systems reduce productivity

As businesses expand, they frequently introduce new software to address specific operational requirements.

A sales department might adopt a customer relationship management platform, while the finance team uses separate accounting software. Marketing teams may rely on analytics platforms, and operations departments might introduce project management applications.

Each tool can provide individual benefits. However, problems arise when these systems cannot communicate effectively. Employees may need to enter identical information into multiple applications. Managers might receive conflicting reports, while customer-facing teams struggle to access accurate information.

Consider a growing service company where sales, billing and customer support operate through separate systems. When a customer purchases a service, employees may need to manually transfer details between departments. This increases the possibility of errors and delays.

As transaction volumes increase, these problems become more difficult to manage.

The solution is not necessarily purchasing additional software. Instead, companies should evaluate how existing applications exchange information and whether integration or workflow improvements can eliminate unnecessary manual tasks.

Entrepreneur’s discussion of why businesses can have access to powerful tools and still struggle to make progress highlights the importance of turning technology availability into practical business capabilities.

Entrepreneurs should prioritize connected systems that provide reliable information across departments and simplify daily operations.

3. Poor database decisions can limit business scalability

Behind most business applications is a database responsible for storing, organizing and retrieving critical information. Customer records, financial transactions, inventory details, employee information and operational reports often depend on database infrastructure.

When businesses are relatively small, database performance may receive little attention. However, as customer activity increases and applications become more complex, limitations in database architecture can begin affecting operations.

Slow queries, inefficient data processing, limited integration capabilities and inadequate capacity planning can create performance bottlenecks. These issues may result in delayed reports, slower applications and additional infrastructure expenses.

Database selection also involves important architectural considerations.

For example, organizations maintaining applications built around SAP SQL Anywhere or SAP Adaptive Server Enterprise may need to evaluate differences in their deployment requirements, workload characteristics, administrative complexity and scalability.

Understanding how different database systems compare can help technical teams assess the suitability of existing platforms before making decisions about application upgrades or infrastructure modernization.

Importantly, replacing a database is not always the best solution. In some cases, performance improvements can be achieved through query optimization, indexing, infrastructure upgrades or improved database administration.

In other situations, changing business requirements may justify a more substantial modernization initiative.

Entrepreneurs do not need to become database specialists. However, they should understand how database reliability, performance and maintenance requirements affect customer experience and business continuity.

Treating data infrastructure as a strategic business asset rather than an isolated technical concern can help organizations avoid costly decisions as they expand.

4. Technology investments without clear business goals can waste resources

Businesses are constantly introduced to new technologies promising greater efficiency, improved customer experiences and increased profitability. Artificial intelligence, automation, cloud platforms and advanced analytics all offer meaningful opportunities.

However, adopting technology without clearly defined objectives can create additional complexity instead of delivering measurable improvements.

A company might invest in an expensive automation platform without first examining whether its underlying processes are efficient. Another business might purchase sophisticated analytics software without having employees who can interpret and act on the information.

In both situations, the problem is not necessarily the technology itself. It is the absence of a clear implementation strategy.

Before introducing a new system, business leaders should identify the operational challenge they want to solve. They should also establish measurable success indicators, such as reduced processing time, improved customer response rates, lower operational expenses or increased employee productivity.

A practical approach involves testing new technology within a limited business function before expanding its use across the organization. This allows teams to evaluate effectiveness, identify implementation challenges and determine whether the investment provides sufficient value.

Technology should support business strategy rather than become a substitute for it.

5. Weak cybersecurity can threaten business continuity

Cybersecurity is frequently viewed as a technical responsibility assigned to an IT department or external service provider. However, its implications extend directly to business growth, financial stability and customer trust.

As organizations expand, they typically collect more customer information, process larger transaction volumes and provide system access to additional employees and partners. Each expansion can introduce new security considerations.

Weak access controls, outdated applications, inadequate backup procedures and insufficient employee training may increase exposure to cyber threats.

A serious security incident can interrupt operations, damage customer relationships and create substantial recovery expenses. For smaller businesses, the financial and operational consequences can be particularly difficult to absorb.

Effective cybersecurity requires more than installing security software. Organizations should implement appropriate access controls, maintain reliable backups, regularly update systems and establish procedures for responding to incidents.

Employee awareness is equally important because human mistakes can undermine otherwise effective technical safeguards.

Business leaders should consider cybersecurity investments part of their overall risk-management strategy. Protecting systems and information helps maintain the operational stability necessary for sustainable expansion.

6. Lack of reliable data can lead to poor business decisions

Modern businesses generate significant amounts of information through sales transactions, marketing campaigns, customer interactions and internal operations. Yet collecting data does not automatically translate into better decisions.

Many organizations struggle with inconsistent reporting, duplicated records, outdated information and fragmented data sources.

For example, a company might report strong revenue growth while overlooking increasing customer acquisition costs or declining profitability. Similarly, managers may make inventory decisions using incomplete information because different departments maintain separate records.

These challenges can become more serious as organizations expand into additional markets or introduce new products.

A reliable data strategy begins with establishing consistent definitions for important business metrics. Teams should agree on how revenue, customer retention, operational efficiency and other key indicators are measured. Organizations should also identify the systems responsible for maintaining authoritative records.

Automated reporting can reduce manual errors, while regular data-quality reviews help identify inconsistencies before they affect important decisions.

Ultimately, entrepreneurs need information that is accurate, accessible and relevant to their strategic priorities. The goal is not to collect as much data as possible but to turn reliable information into timely business decisions.

7. Scaling too quickly can expose technology weaknesses

Rapid growth creates exciting opportunities, but it also places additional pressure on existing business systems.

A technology setup designed for a company with 10 employees may not adequately support an organization with hundreds of employees operating across multiple locations.

Increased transaction volumes, additional users, more complex reporting requirements and greater customer expectations can expose previously unnoticed limitations.

Businesses may experience application slowdowns, service interruptions, inconsistent processes or rising infrastructure expenses. These problems often emerge when organizations expand faster than their technology planning. Scalability should therefore be considered before major expansion initiatives.

Business leaders can begin by evaluating whether existing systems can accommodate increased workloads and additional users. They should also examine whether infrastructure can be upgraded without requiring expensive or disruptive changes.

Cloud services, modular software architecture and well-documented operational processes may provide greater flexibility, depending on the organization’s requirements. However, scalability involves people and processes as much as technology.

Planning ahead can help companies avoid reactive technology investments made under pressure.

8. Overlooking employee training reduces the value of technology

Even the most advanced technology cannot deliver its full potential if employees do not understand how to use it effectively.

Businesses sometimes invest substantial resources in software implementation while allocating limited time or budget to training.

This can lead to inconsistent adoption, employee frustration and continued dependence on inefficient manual processes. In some cases, employees may avoid using new systems altogether because they find familiar workflows easier.

Successful technology adoption requires clear communication about why changes are being introduced and how they will benefit daily operations. Employees should receive practical training relevant to their responsibilities.

Organizations can also identify internal technology champions who help colleagues understand new processes and provide feedback during implementation. Regular evaluations can reveal whether systems are being used as intended and whether additional training is required.

By treating employee development as part of technology investment, businesses can improve adoption rates and achieve more consistent operational benefits.

9. The absence of a long-term technology roadmap creates unnecessary risk

One of the most common strategic mistakes is approaching technology decisions individually rather than as part of a coordinated plan.

A business might replace an application when it fails, upgrade infrastructure when performance deteriorates or introduce new software when a department requests additional capabilities. While these decisions may solve immediate problems, they can create a fragmented technology environment over time.

A long-term technology roadmap provides a more structured approach.

It should identify current infrastructure limitations, anticipated business requirements, implementation priorities and realistic investment timelines. Business leaders should collaborate with technical specialists to evaluate which systems require immediate attention and which can be improved gradually.

The roadmap should also account for potential changes in customer demand, staffing, regulatory requirements and market conditions. Regular reviews are important because business priorities and technology capabilities continue to evolve.

A useful roadmap does not need to predict every future requirement. Instead, it should provide a flexible framework for making informed decisions while minimizing unnecessary disruption.

Turning technology challenges into growth opportunities

Technology problems often remain hidden until they begin affecting revenue, productivity or customer satisfaction. By that stage, addressing them may require urgent investments and operational changes that could have been avoided through earlier planning.

Entrepreneurs can take a more proactive approach by reviewing their technology environment regularly and identifying potential weaknesses before they become significant obstacles. This includes evaluating outdated systems, improving application integration, monitoring database performance, strengthening cybersecurity and investing in employee training.

Equally important is connecting every major technology decision to a measurable business objective. Not every company needs the newest software, the most sophisticated infrastructure or an immediate migration to emerging technologies. In many cases, improving existing systems and simplifying workflows can produce meaningful results without unnecessary spending.

The businesses best positioned for sustainable growth are not necessarily those investing the most in technology. They are those making thoughtful decisions about where technology can deliver lasting operational and strategic value.

Ultimately, business growth depends on more than ambitious goals and market opportunities. It also requires a reliable foundation capable of supporting those ambitions.

By recognizing and addressing hidden technology challenges early, entrepreneurs can reduce operational friction, make better decisions and create organizations that are better prepared for the next stage of growth.


Source link

9 Hidden Technology Challenges That Can Slow Business Growth Read More »

AI Can Draft in Seconds. Can You Afford to Check Its Work?

AI Can Draft in Seconds. Can You Afford to Check Its Work?


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Before you automate a deliverable, write down who will check it, how long that check should take and what happens when the check fails.
  • The economic value of generated output depends on how cheaply and reliably a competent person can verify it in the real decision.

The first time I watched a machine draft something that looked finished, I almost signed off. The language was clean. The structure made sense. Then I tried to check three claims against the source material and burned more time reconstructing the case than the draft had saved. Speed had moved. The cost had not gone away. It had just changed rooms.

I remember the annoyance more than the draft. The tool had done its job. The review path had not.

Here’s my situation, so you know where I’m coming from. I founded Main & Machine, an AI implementation firm for small and mid-size businesses, and I also sit in the buyer seat when technology lands in a real operating company. (Disclosure for the editor: I have a financial relationship with Main & Machine.) I teach management and entrepreneurship at Arizona State University’s W.P. Carey School of Business. Across those chairs I keep seeing the same pattern: owners celebrate generation and underbuild verification.

Most shops treat “human in the loop” as a checkbox on a vendor slide. That move fails in practice. The economic value of generated output depends on how cheaply and reliably a competent person can verify it in the real decision. U.S. Census Bureau data from late 2025 through early 2026 put overall business AI use in the 17% to 20% range, with more firms still planning to join them. The next wave will not stall because models got worse. It will stall where checking stays slow, opaque or socially expensive.

I used to treat a second click as proof of judgment. Wrong. A second click can still leave you with one judgment if the reviewer never saw the underlying case on independent terms.

Price the review path before the draft

Before you automate a deliverable, write down who will check it, how long that check should take and what happens when the check fails. Generation reduces first-draft cost. Uncertain output creates a checking obligation. When verification is fast and error is reversible, the gain survives. When checking requires scarce expertise, reconstructing evidence or absorbing liability, the apparent speed just moves cost downstream.

The principle fits in one line: Cheap output with expensive verification is still expensive work.

Try the same pricing this week. Pick one workflow you want the machine to touch. Estimate minutes to generate and minutes to verify on a hard case. Skip the polished demo. A restaurant owner might let a tool draft the weekly schedule and still need a manager who can read labor rules and walk the floor. A clinic owner might let a tool summarize intake notes and still need a clinician who can open the raw chart. If the hard-case check cannot fit the day, the automation is not ready.

Give reviewers a route the machine did not frame

A reviewer cannot meaningfully check an automated recommendation when the system is also the only account of the underlying case. When evidence, framing and conclusion arrive through one interface, disagreement requires reconstructing information the reviewer never independently saw. Time pressure then makes rubber-stamping rational.

The principle: Review needs an independent path to the facts.

Build that path on purpose. For high-stakes work, keep a sampled set of raw inputs available beside the machine’s summary. Ask the reviewer to name the decisive evidence and the uncertainty before the recommendation appears, then compare reasons. A franchisee can do this on customer-complaint drafts. A contractor can do it on estimate language. A professional-services owner can do it on client memos. Agreement alone proves little. Shared framing can produce shared error. What matters is whether disagreement can change the action and survive in the record.

Rehearse the override under pressure

An override that exists only as a policy or a button is not a reliable safeguard. Automation reduces exposure to normal system dynamics, while the ugly cases compress time and raise uncertainty. People need practice recognizing, deciding and acting without the automated system when the answer feels wrong.

The principle: Practice the no until it is usable.

Run a short drill this month. Take three recent outputs the team almost shipped. Hide the machine’s confidence language. Ask a named owner to reject one of them with a written reason and an alternate next step. Then watch whether the rejection sticks or gets smoothed over because the draft sounded finished. Automation leaves a harder residue: The exceptions that remain are ambiguous, rare and consequential. If your team only ever sees clean demos, they will not keep the skill they need when the residue shows up on a Tuesday afternoon.

Here’s where I’d start this week: Pick one AI-assisted workflow, write the review minutes and the independent evidence route on a single page, and run one override drill with the person who actually owns the outcome. Say it to the team before you expand the tool’s reach.

The draft that looked finished still sits in my mind. The checking cost was the real product. Build that first, and the machine earns its keep.

Key Takeaways

  • Before you automate a deliverable, write down who will check it, how long that check should take and what happens when the check fails.
  • The economic value of generated output depends on how cheaply and reliably a competent person can verify it in the real decision.

The first time I watched a machine draft something that looked finished, I almost signed off. The language was clean. The structure made sense. Then I tried to check three claims against the source material and burned more time reconstructing the case than the draft had saved. Speed had moved. The cost had not gone away. It had just changed rooms.

I remember the annoyance more than the draft. The tool had done its job. The review path had not.

Here’s my situation, so you know where I’m coming from. I founded Main & Machine, an AI implementation firm for small and mid-size businesses, and I also sit in the buyer seat when technology lands in a real operating company. (Disclosure for the editor: I have a financial relationship with Main & Machine.) I teach management and entrepreneurship at Arizona State University’s W.P. Carey School of Business. Across those chairs I keep seeing the same pattern: owners celebrate generation and underbuild verification.


Source link

AI Can Draft in Seconds. Can You Afford to Check Its Work? Read More »

Build an AI-Native Business in 90 Days, Without a Budget

Build an AI-Native Business in 90 Days, Without a Budget


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • The first 30 days: Write down how the work actually happens. Choose one process that touches revenue directly, and identify which tasks AI can handle versus those requiring human judgment.
  • Days 31 to 60: Take ownership of your data before it owns you. Organize business data, assign clear ownership, standardize definitions, and ensure data can be easily exported.
  • Days 61 to 90: Redesign who decides and what gets measured. Clarify human accountability, and track improvements in cycle time, service costs and customer turnaround.

When I wrote about the difference between using AI and being AI-native, the most frequent response from executives was a polite objection: the distinction is real, but redesigning how work happens is a luxury reserved for companies with transformation budgets.

I spend my working life inside those budgets, and most of what they buy is the expensive undoing of habits that formed when the company was small. A founder has nothing to undo yet, which is why the quarter ahead is worth more than the three-year program a large enterprise will fund.

Here is the plan I would run if I were building a company today with no budget beyond my own calendar. In 90 days, with no new software and no outside help, you can do the three things that separate an AI-native business from one that merely uses AI: Write down how the work actually happens, take ownership of your data, and redesign who decides and what gets measured.

Why the big companies are paying for your quarter

In June, Genpact and HFS Research published a survey of more than 2,000 senior executives, and 85% of them said that accumulated enterprise debt — meaning undocumented processes, unusable data, aging systems and unprepared people — is limiting the value they get from AI. The researchers put the trapped value across the Global 2000 at roughly $18 trillion, found that only 33% of enterprise data is AI-ready and estimated that inefficient or manual processes consume about 40% of a typical employee’s week. More than half of those enterprises have no funded initiative to fix any of it.

Every item on that list is a habit before it is a legacy. Nobody decides to have undocumented processes; they go unwritten while the company grows, and the McKinsey Global Survey published this year found that nearly three-quarters of AI high performers have fundamentally redesigned their workflows, against roughly one-quarter of the rest, while the share of smaller organizations scaling AI agents sat flat at 22%. The gap between the two groups is not spend, and it is not model access. It is redesign, and redesign is cheapest before the habits set.

The first 30 days: Write down how the work actually happens

Choose one process that touches revenue directly, such as quote to cash, customer onboarding or returns, and resist the urge to choose three at once. Sit with the people who run it and have them narrate the real path, including the spreadsheet nobody admits to, the approval stuck in one inbox and the exception handled from memory, because the documented process and the one that actually runs are rarely the same document.

Then mark every step as either production or judgment. Production is the drafting, gathering, comparing and summarizing that a model can increasingly perform; judgment is the deciding, prioritizing and taking of responsibility that a human must own. By day 30, you should hold a one-page map a new hire could follow on their first morning, and if a new hire can follow it, so can a model. A process nobody can describe is a process no model can run and no auditor can defend.

Days 31 to 60: Take ownership of your data before it owns you

With the map in hand, trace where the information for each step lives, and expect to find it scattered across three tools, several inboxes and one personal drive. For every field that matters — meaning customer, product, price, status and date — name a single owner and agree on a single definition, because enterprises I work with across the Americas, Europe, Australasia and Japan are spending fortunes to rediscover what counts as an active customer, a question you can settle in a single afternoon.

Then check the exits. Open every tool you pay for and confirm that your data can leave it, in full, in a usable format, on your schedule — and if it cannot, that is the first renewal to renegotiate. Data you cannot export is data you are renting, and a company that rents its own context is not AI-native, however many models it subscribes to.

Days 61 to 90: Redesign who decides and what gets measured

Return to the judgment steps on your map and give each one a name, a definition of what a good outcome looks like and a clear rule for when a human reviews before anything reaches a customer. Then look hard at the approvals that remain, because most approval chains are information poverty in disguise, and once last month’s data is visible to everyone, many of them survive only out of habit.

Finally, retire the metrics that measure the tool and install the ones that measure the business. Baseline the cycle time, cost to serve and customer turnaround of your chosen process on day 61, measure again on day 90, and let the difference, rather than the number of licenses, tell you whether anything changed. In my experience, the first fully redesigned process returns more than the first 10 pilots combined, because a pilot proves that a model works, and a redesign proves that the company does.

What to do on day 91

Three moves follow. First, run the same quarter on the next process, because the method compounds and the second map takes half the time. Second, only now buy tools, since you can finally specify what a tool must do and measure what it did. Third, make the habit a condition of growth, so every new hire inherits a map, and every new vendor passes the export test before a contract is signed.

In August, I offered a test: If every model disappeared on Monday morning, would your business notice? Here is the companion test once you have run this quarter: If you hired 10 people on Monday morning, would they know by Tuesday how the work happens? The companies spending billions are buying back the quarter you still have, and the only transformation budget it requires is the discipline to spend it.

Key Takeaways

  • The first 30 days: Write down how the work actually happens. Choose one process that touches revenue directly, and identify which tasks AI can handle versus those requiring human judgment.
  • Days 31 to 60: Take ownership of your data before it owns you. Organize business data, assign clear ownership, standardize definitions, and ensure data can be easily exported.
  • Days 61 to 90: Redesign who decides and what gets measured. Clarify human accountability, and track improvements in cycle time, service costs and customer turnaround.

When I wrote about the difference between using AI and being AI-native, the most frequent response from executives was a polite objection: the distinction is real, but redesigning how work happens is a luxury reserved for companies with transformation budgets.

I spend my working life inside those budgets, and most of what they buy is the expensive undoing of habits that formed when the company was small. A founder has nothing to undo yet, which is why the quarter ahead is worth more than the three-year program a large enterprise will fund.

Here is the plan I would run if I were building a company today with no budget beyond my own calendar. In 90 days, with no new software and no outside help, you can do the three things that separate an AI-native business from one that merely uses AI: Write down how the work actually happens, take ownership of your data, and redesign who decides and what gets measured.


Source link

Build an AI-Native Business in 90 Days, Without a Budget Read More »

7 Downsides of Hiring Independent Contractors

7 Downsides of Hiring Independent Contractors


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Contractors can reduce overhead and provide flexibility, but higher rates, turnover and compliance risks can offset the savings.
  • Use contractors for specialized, project-based work and employees when your business needs continuity, accountability and long-term commitment.

After more than two decades of working with independent contractors, I still believe they’re one of the best ways to run a flexible small business. But I’ve also learned that they’re not nearly as cheap, simple or risk-free as many business owners assume.

There are plenty of advantages. I can hire contractors for specific projects without making a long-term employment commitment. I don’t have to provide employee benefits, paid vacation or other traditional employment perks. I can negotiate project rates, define deliverables and avoid worrying about keeping someone busy when the work dries up. Contractors generally manage their own schedules, tools and methods.

It can be a flexible and cost-effective model. But it’s not all rosy.

Here are seven things I’ve learned about working with independent contractors — and what every business owner should consider before building a business around them.

1. Weigh the savings against the costs

When you hire a contractor instead of an employee, you may save money on payroll taxes, benefits and other employment-related expenses. But contractors have their own business expenses, and those costs have to be covered somehow. That’s why their hourly rates are often higher than what you’d pay an employee doing comparable work.

Their rates can also change as market conditions shift, making long-term costs less predictable.

This may still be a financially sound decision for your company, but I recommend projecting the total cost of hiring a contractor versus an employee for every position you consider. Don’t assume you’re saving money just because you’re not running payroll.

2. Invest in compliance

Independent contractors are independent business owners, freelancers and professionals who provide services to other businesses. When you work with them, you need to understand and comply with federal, state and local tax and labor laws.

The distinction between an employee and an independent contractor generally comes down to the nature of the working relationship, including how much control the company exercises over the worker. Factors can include how the work is performed, who provides the tools and equipment, how the worker is paid and whether they operate an independent business.

I generally don’t have the same payroll tax, benefit and wage-and-hour obligations associated with employees — assuming the worker is properly classified as an independent contractor.

I have written agreements with all my contractors. These agreements document the scope of work, payment terms, deliverables and expectations. But a contract alone doesn’t determine someone’s legal classification. Government agencies look at the actual working relationship, not just what the agreement says.

Tax reporting requirements also apply. Depending on the circumstances, you may need to issue Form 1099-NEC to report payments to contractors.

Run these relationships by your accountant and attorney to make sure you’re compliant. Misclassifying an employee as an independent contractor can result in penalties, back taxes and liability for unpaid benefits and wages.

3. Prepare for a changing regulatory landscape

The rules governing independent contractors aren’t necessarily permanent. Federal and state governments have different approaches to worker classification, and regulations can change with new administrations, court decisions and legislative priorities.

Some regulatory changes make it harder for businesses to classify workers as independent contractors, while others give employers more flexibility. These debates often center on worker protections, benefits and the degree of independence a worker actually has.

The takeaway for business owners is simple: Don’t assume today’s rules will remain unchanged. Pay attention to developments in the jurisdictions where you operate, and periodically review your contractor relationships with your legal and accounting advisers.

4. Always have backups

Because independent contractors are independent, they’re free to follow the money wherever it takes them. They can take on other clients, accept new projects or move on when a better opportunity comes along.

Many of my contractors serve multiple clients, which I actually encourage. It reinforces the independent nature of the relationship and allows them to maintain their own businesses.

But contractors come and go. Some are more entrepreneurial, restless or focused on short-term opportunities than others. That’s why I’ve built relationships with multiple contractors, including some who compete with one another.

This gives me options when someone becomes unavailable, misses a deadline or doesn’t deliver. It also means I’m not dependent on one person to keep an important part of my business running.

Just remember: Finding good people isn’t easy. Building a reliable network of contractors takes time, and you need to invest in those relationships before you need them.

5. Don’t confuse ‘independent’ with ‘expert’

I’ve also learned that hiring an independent contractor who presents themselves as an expert doesn’t guarantee that they actually have the experience or skills you need.

Anyone can hang out a shingle and call themselves an expert. I’ve worked with so-called professionals who were hired to perform specific jobs but misrepresented their experience and capabilities.

When you hire an employee, there’s often a formal vetting process. You review resumes, conduct interviews, check references and involve other people in the decision.

Hiring a capable contractor requires the same level of due diligence. Ask for work samples, speak with previous clients, check references and clearly define expectations before signing an agreement.

Don’t assume someone knows what they’re doing just because they have a website, a business name or an impressive title. You still need to do your homework.

6. Your customers may not be thrilled

There’s a difference between the relationship a manager has with an employee and the relationship with an outside contractor. Employees generally work within your organization, while contractors maintain their own businesses and client relationships.

My customers understand this, but sometimes I have to explain that the people I’m sending to their projects aren’t my employees. That can raise an eyebrow.

There’s a perception that employees are more dedicated, accountable and easier to manage than outside contractors. Customers may reasonably believe I have less influence over a contractor servicing them than someone on my payroll. They’re not necessarily wrong.

You can’t hide the relationship, and you shouldn’t try to. Customers aren’t necessarily bothered by contractors. They’re bothered by uncertainty over who’s accountable when something goes wrong.

You need to be prepared to explain how you manage quality, communicate expectations and remain responsible for the work being delivered. The customer is hiring your business, and you need to stand behind the results.

7. Your employees may not be thrilled

Using too many independent contractors can also affect internal relationships and company culture.

Employees may resent the flexibility contractors enjoy or question why certain responsibilities are outsourced instead of handled internally. They may also wonder whether their own contributions are valued if the company regularly turns to outside professionals.

Contractors can become part of a team, but they aren’t employees. How you manage those relationships matters. There are also practical considerations involving confidential information, company data and access to internal systems. Make sure contractors have appropriate agreements and access controls in place to protect your business.

Hiring a contractor for a short-term project is one thing. Relying on contractors for essential, ongoing responsibilities is another. Think carefully about how those decisions affect morale, accountability and the culture you’re trying to build.

Independent contractors can be a great business model — with the right expectations

I don’t want to discourage business owners from using independent contractors. After more than two decades, I still rely on them, which should tell you something.

But it’s important to understand the trade-offs. Contractors can offer specialized expertise, flexibility and defined deliverables without the long-term commitment of traditional employment. They can also introduce uncertainty around availability, costs, compliance and continuity.

My advice is to use contractors when you need specialized skills, project-based support and flexibility. Hire employees when you need consistency, direct oversight, institutional knowledge and long-term commitment. The right mix can help you build a more flexible and efficient business. Just don’t assume that outsourcing the work means outsourcing the responsibility.

Key Takeaways

  • Contractors can reduce overhead and provide flexibility, but higher rates, turnover and compliance risks can offset the savings.
  • Use contractors for specialized, project-based work and employees when your business needs continuity, accountability and long-term commitment.

After more than two decades of working with independent contractors, I still believe they’re one of the best ways to run a flexible small business. But I’ve also learned that they’re not nearly as cheap, simple or risk-free as many business owners assume.

There are plenty of advantages. I can hire contractors for specific projects without making a long-term employment commitment. I don’t have to provide employee benefits, paid vacation or other traditional employment perks. I can negotiate project rates, define deliverables and avoid worrying about keeping someone busy when the work dries up. Contractors generally manage their own schedules, tools and methods.

It can be a flexible and cost-effective model. But it’s not all rosy.


Source link

7 Downsides of Hiring Independent Contractors Read More »

5 Ways to Grow Your Business Without Doing It All


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Use AI to reclaim time for strategic work. Automate routine tasks and build systems that let you focus on the decisions and challenges that require your expertise.
  • Build a business that can grow without your constant involvement. Develop your team’s problem-solving skills, invest in lasting relationships and share credit to create a stronger, more independent organization.

Throughout my career as a business leader, entrepreneur and executive coach, I’ve learned to focus on the work that matters most — the decisions, challenges and relationships where my experience and judgment make the biggest difference. That means building better systems, developing new skills, strengthening relationships and empowering my team. These investments compound over time, helping my businesses grow without requiring me to weigh in on every decision.

If you want to do the same, here are five practical changes you can make today.

1. Stop doing everything. Start building your AI stack.

Doing less yourself doesn’t mean working less. Your value isn’t measured by how much you personally execute. Administrative tasks can quickly consume your day without moving your business forward.

I divide my workload into two categories: below-the-line and above-the-line work. Below-the-line tasks include email, scheduling and project tracking. Above-the-line work is where your judgment matters most: setting strategy, making critical decisions, solving problems and building relationships.

AI creates opportunities to move more work below the line. Start by listing what consumes your time, then determine what you can automate, delegate or eliminate. Build a focused ecosystem of AI agents that can research your industry, track competitors, monitor key performance indicators (KPIs) and prepare meeting notes.

This approach helps me protect 90-minute blocks for deep work, giving me more time to focus on challenges that genuinely require my expertise. After spending too many years on below-the-line tasks, my advice is simple: Let AI handle more of the administrative work so you can focus your best skills on what matters most.

2. Stop thinking you know it all. Start updating your skills.

The moment you think you know everything may be the moment a competitor passes you by. Maintaining a humble, curious mindset has helped me recognize new opportunities, grow as a leader and strengthen my businesses. Learning doesn’t end with a degree. Keep developing new skills, pursuing relevant credentials and embracing a learner’s mindset throughout your career.

AI is a good place to start. Go beyond basic chatbot prompts and learn how AI agents, automation and interconnected systems can work together to improve your business. One agent might research competitors, another monitor regulatory changes and a third identify potential investors or financing opportunities. AI can also surface emerging industry topics, creating opportunities to contribute thought leadership before a conversation gains momentum.

I recommend programs from Vanderbilt Executive Education and MIT Professional Education. Both offer focused learning opportunities centered on executive strategy without getting lost in the technical details.

3. Stop taking over every project. Start coaching your team.

Entrepreneurs are often wired to jump in and solve problems immediately. Eventually, that instinct can become counterproductive. You’ve built a team for a reason, and neither you nor your employees need you involved in everything.

I learned this firsthand as an executive at Intel. During a period when I was pushing myself too hard, the pressure spilled over onto my team. Instead of delegating thoughtfully, I sent early-morning emails and created unnecessary work. When team members told me they were stressed, it was a wake-up call. I realized my team needed me to operate at my best and help them do the same.

I started with a simple coaching principle: Stop offering answers and solutions too quickly. When someone brings you a problem, ask them to recommend a solution, too.

Try asking questions such as:

  • What do you think we should do?
  • What are the primary risks?
  • What does success look like?

If you want your team to think strategically, give them opportunities to contribute to important decisions. Challenge their thinking, encourage them to evaluate trade-offs and let them own the solutions.

You’ll gain a better understanding of their strengths while developing decisive leaders who can exercise sound judgment without relying on you for every answer.

4. Stop networking. Start building lasting relationships.

Networking in the digital age can mean little more than accepting an invitation or adding a connection. But a connection is only the beginning. Would that person invest in you or your business? Could you call each other for advice, an introduction or a potential partnership?

The strongest relationships become more valuable over time. Alpine Investors founder Graham Weaver calls these “lifetime relationships.”When Weaver started his company at 28, he struggled to raise funds. Two investors with whom he had built relationships eventually backed him, helping get the business off the ground. He has said the company wouldn’t exist without their belief in him.

Building lasting relationships requires more than accepting another LinkedIn request. Someone you meet today could eventually become a strategic partner, join your board or help you raise capital. One day, you may be the person they turn to.

Prioritize meaningful relationships over simply accumulating social media connections. Invest time in being authentic. Send the card. Check in when you don’t need anything. Pick up the phone when someone calls for advice.

These small gestures build trust over time and create a network of people who will be there when it matters most.

5. Stop chasing recognition. Start sharing the spotlight with your team.

At a certain point in your career, success becomes less about what you accomplish personally and more about the leaders you develop.

Sharing credit is also a performance strategy. It recognizes strong contributions, reinforces positive behaviors and builds a team capable of achieving more without routing every decision through you.

Give talented employees opportunities to take ownership. Include them when recognition is given, let them lead presentations, put them in front of clients and trust them to make important decisions.

Research from Gallup found that 61% of employees who received both feedback and recognition from their manager at least weekly were engaged, compared with 38% of employees who received weekly feedback but less frequent recognition.

When your people deliver results, make sure they receive the credit. Recognizing their contributions reinforces a culture in which people feel valued and motivated to do their best work.

Build your own playbook

Think of these five shifts as a starting point, not a rigid formula. Put them into practice, pay attention to what works and adjust what doesn’t.

Through experimentation, you’ll develop an approach that fits your leadership style, your business and your team. Keep investing in the systems, skills and relationships that help you operate at your best.

And never stop looking for that edge.

Key Takeaways

  • Use AI to reclaim time for strategic work. Automate routine tasks and build systems that let you focus on the decisions and challenges that require your expertise.
  • Build a business that can grow without your constant involvement. Develop your team’s problem-solving skills, invest in lasting relationships and share credit to create a stronger, more independent organization.

Throughout my career as a business leader, entrepreneur and executive coach, I’ve learned to focus on the work that matters most — the decisions, challenges and relationships where my experience and judgment make the biggest difference. That means building better systems, developing new skills, strengthening relationships and empowering my team. These investments compound over time, helping my businesses grow without requiring me to weigh in on every decision.

If you want to do the same, here are five practical changes you can make today.

1. Stop doing everything. Start building your AI stack.

Doing less yourself doesn’t mean working less. Your value isn’t measured by how much you personally execute. Administrative tasks can quickly consume your day without moving your business forward.


Source link

5 Ways to Grow Your Business Without Doing It All Read More »

Why Playing It Safe Is the Riskiest Marketing Decision You’ll Make

Why Playing It Safe Is the Riskiest Marketing Decision You’ll Make


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • By the time a tactic is safe enough to carry that label, it is crowded and drained of any edge it once held. The same trap shows up in how you measure success.
  • The highest-return version refuses to fight inside a crowded category at all. Instead of scrapping for a sliver of space the leader already defined, you reframe the problem so you become the obvious answer to a question nobody else is asking.
  • AI systems are becoming the layer between your customer and the answer, and the brands that appear inside those answers are the ones deciding today to be there.

The safest-looking marketing plan in the room is usually the one most likely to keep you invisible. When you copy the channels, the messaging and the metrics that already work for the category leader, you compete on terms that favor whoever has the bigger budget and the longer head start. That feels like prudence. It is actually the slowest and most expensive way to stay a follower.

Safe feels responsible because failure is easy to defend when you followed the same plan as everyone else. Nobody gets second-guessed for matching the industry norm. That comfort is exactly the problem, because a plan built to avoid blame is not built to win, and the market rewards the brands willing to be wrong in public before they are proven right.

I learned this early. In 2013, I argued that mobile apps needed a strategy of their own rather than a shrunken version of web marketing, back when that sounded like a distraction. The people who moved before the consensus did not have better tools than everyone else. They simply refused to wait for permission and had already taken ownership of the space by the time the cautious crowd arrived.

The safe playbook keeps you invisible

Best practices earn their name because everyone already uses them. By the time a tactic is safe enough to carry that label, it is crowded and drained of any edge it once held. You can run it flawlessly and still finish exactly where you started, one more voice repeating the same message in the same place as your competitors.

The same trap shows up in how you measure success. Chasing the impressions, followers and engagement numbers every rival reports is the most crowded play in marketing, because those figures are easy to hit and easy to ignore. They make a quarter look healthy while the business underneath them sits still.

That ground is moving faster than the safe playbook admits. A Pew Research Center study of nearly 69,000 searches found that when an AI summary sits atop Google results, users click a traditional link in only 8% of visits, down from 15% when no summary appears. Ranking a page and waiting for the click is losing its footing, and most brands are still optimizing for rules that have already changed.

The calculated move rewards discipline

Bold does not mean reckless. What builds leaders is an asymmetric wager, where the downside is small and survivable, and the upside is owning territory no rival has claimed. You are not gambling the company. You are spending a measured slice of budget and attention on a shift you can already see forming, and planting yourself where it lands before the crowd arrives.

The highest-return version refuses to fight inside a crowded category at all. Instead of scrapping for a sliver of space the leader already defined, you reframe the problem so you become the obvious answer to a question nobody else is asking. Think of the companies that stopped selling a slightly better version of an existing product and instead named a new category they could own outright. They looked risky right up until they looked inevitable.

You can pressure-test the move in a single meeting. Ask what happens if it fails and whether the honest answer is a bruise or a catastrophe. Then ask what happens if it works and whether the payoff is a marginal gain or a foothold nobody can take from you. When failure is survivable and success is defining, hesitation becomes the expensive choice.

AI answers reward the brands that move first

The clearest version of this decision sits in front of every marketer right now. AI systems are becoming the layer between your customer and the answer, and the brands that appear inside those answers are the ones deciding today to be there. Waiting until the behavior is undeniable means arriving after the winners are already chosen.

Winning that visibility depends less on budget than on being the clearest and most credible source on the questions you want to own. When an AI system builds an answer, it pulls from information it can trust and quote, so the work is making your expertise easy to find and hard to leave out. That legwork is fundamentals executed better than the competition, aimed at a channel most of your rivals are still ignoring.

In practice, that means publishing direct answers to the questions your customers actually ask, in language a machine can lift without guessing at your meaning. It means keeping your pages clean enough that the facts are easy to extract and quote. It means earning mentions on the outside sources these systems already trust, so when they build an answer, yours is the evidence within reach. That is unglamorous work, and it is exactly why most of your competitors will skip it until the advantage is gone.

Playing it safe shields you from the danger you can see and hands you the one you cannot, the slow erosion of being easy to overlook. The move that feels too bold today is often the only thing that keeps you relevant tomorrow. The real threat was never the leap. It was standing still while the ground moved.

Key Takeaways

  • By the time a tactic is safe enough to carry that label, it is crowded and drained of any edge it once held. The same trap shows up in how you measure success.
  • The highest-return version refuses to fight inside a crowded category at all. Instead of scrapping for a sliver of space the leader already defined, you reframe the problem so you become the obvious answer to a question nobody else is asking.
  • AI systems are becoming the layer between your customer and the answer, and the brands that appear inside those answers are the ones deciding today to be there.

The safest-looking marketing plan in the room is usually the one most likely to keep you invisible. When you copy the channels, the messaging and the metrics that already work for the category leader, you compete on terms that favor whoever has the bigger budget and the longer head start. That feels like prudence. It is actually the slowest and most expensive way to stay a follower.

Safe feels responsible because failure is easy to defend when you followed the same plan as everyone else. Nobody gets second-guessed for matching the industry norm. That comfort is exactly the problem, because a plan built to avoid blame is not built to win, and the market rewards the brands willing to be wrong in public before they are proven right.

I learned this early. In 2013, I argued that mobile apps needed a strategy of their own rather than a shrunken version of web marketing, back when that sounded like a distraction. The people who moved before the consensus did not have better tools than everyone else. They simply refused to wait for permission and had already taken ownership of the space by the time the cautious crowd arrived.


Source link

Why Playing It Safe Is the Riskiest Marketing Decision You’ll Make Read More »

Why Everyone’s Marketing Tactics Are Starting to Look the Same

Why Everyone’s Marketing Tactics Are Starting to Look the Same


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Here’s the problem with a rising floor: When everyone’s production quality improves simultaneously, production quality stops differentiating anything.
  • The vocabulary of disruption has become so widespread that it now signals nothing about actual disruption. Every company claims to be solving the same friction, but almost none of them tell you what, specifically, they understand about human behavior that nobody else has figured out yet.
  • AI is accelerating in ways that will make the current volume of mediocre content look modest by comparison. What hasn’t been automated is having something genuinely worth saying: a perspective that comes from actual experience rather than market research.

Real estate might produce more marketing per transaction than almost any other professional services industry on earth. Professional photography, drone footage, property films, social reels, brochures, digital advertising, portal listings, email campaigns. A single home sale can generate more content than some companies produce in a quarter. And somehow, most of it sounds exactly the same.

That contradiction is worth sitting with. Because the instinct when marketing isn’t working is almost always to produce more of it. Better cameras. Bigger budgets. More platforms. Higher production value. Real estate has been running that experiment for years, and the result is a market where everything looks increasingly polished and increasingly identical.

Production became a commodity

Not long ago, professional photography was a genuine differentiator in real estate marketing. Most agents were shooting listings on a phone or hiring whoever was cheapest. The agent who showed up with a real photographer was doing something visibly different. That gap closed fast.

Now AI is closing the remaining gaps even faster. Listing descriptions that once took time to write get generated in seconds. Virtual staging that required a designer now takes minutes. Video editing tools that demanded technical skill are increasingly automated. The production floor for every agent, every brokerage, every proptech startup keeps rising.

Here’s the problem with a rising floor. When everyone’s production quality improves simultaneously, production quality stops differentiating anything. Better cameras didn’t solve real estate marketing. They created better-looking sameness. And AI is about to make mediocre content infinitely easier to produce at scale, which means the volume of indistinguishable marketing is going to increase dramatically before anyone figures out that more isn’t the answer.

This isn’t just a real estate problem. It’s happening across every industry that produces content. Design tools democratized. Video became accessible. Writing assistance arrived. The production barrier dropped everywhere. What used to be scarce, the ability to make something that looked and sounded professional, became abundant. The scarcity moved somewhere else entirely.

Better-looking sameness is still sameness

Walk through luxury real estate marketing for an hour and a specific vocabulary emerges. Stunning. Exclusive. One-of-a-kind. White-glove. Market leader. Exceptional. Timeless. These words appear so consistently across so many properties, agents and brokerages that they’ve stopped communicating anything. They’re filler. Placeholder language that signals luxury without describing it, claims distinction without demonstrating it and tells the audience essentially nothing about why this particular property or this particular professional is worth paying attention to.

Agent marketing has its own version. Top producer. Local expert. Client first. Results driven. These phrases are so universal that a consumer could copy and paste them between dozens of competing agent websites without anyone noticing. They describe an aspiration, not a reality. They make no claim that a competitor couldn’t make with identical credibility the same afternoon.

Proptech marketing runs the same pattern. Seamless. Transparent. Frictionless. Innovative. Reimagining. Disrupting. The vocabulary of disruption has become so widespread that it now signals nothing about actual disruption. Every company claims to be solving the same friction. Almost none of them tell you what specifically they understand about human behavior that nobody else has figured out yet.

If your story only gets interesting after someone learns the price, you probably don’t have much of a story.

Finding what’s actually worth saying

The question most marketers ask is: What should we post? The question that actually matters is: What do we have that’s genuinely worth saying? Those questions produce different answers, and the gap between them is where most marketing fails.

At the property level, stories rarely live in the obvious places. Price is not a story. Square footage is not a story. Photographs of a great kitchen are not a story. Stories live in the things that made a property what it is. An architect who designed a home around how morning light moves through a specific valley at a specific time of year. A restoration that brought back materials the original builder sourced from a place that no longer exists. A working ranch that has passed through the same family for three generations and carries a particular relationship to the land that no newly built property can replicate. These things are specific. Specific is the opposite of forgettable.

At the professional level, the story underneath the obvious claims is almost always more interesting than the claims themselves. Not a top producer, but the agent who noticed a decade ago that a specific type of buyer was quietly moving into a region nobody was paying attention to and spent years learning that market before it became obvious. Not a local expert, but the broker who walked away from a larger firm to focus exclusively on a property type most of her competitors couldn’t competently sell. That kind of specificity is earned. Competitors can claim to be local experts tomorrow. They can’t claim ten years of transactions in a niche they didn’t bother to understand.

At the company level, the story worth telling is almost never about features. It’s about the assumption that turned out to be wrong, the behavior that changed, the customer experience that should have worked differently and didn’t. Why does this company need to exist right now rather than five years ago? What did the founders see that others were explaining away? Those are interesting questions. Feature lists are not.

The scarcity shifted

For most of business history, the ability to produce something polished was itself a competitive advantage. Small companies couldn’t afford it. Individual professionals couldn’t access it. The production barrier kept a lot of people out.

That barrier is gone. Anyone can produce something that looks and sounds professional. The tools exist, the cost has collapsed and AI is accelerating the trend in ways that will make the current volume of mediocre content look modest by comparison.

What hasn’t been automated is having something genuinely worth saying. A perspective that comes from actual experience rather than market research. A story that could only be told by this company, this agent, this property. A claim specific enough that a competitor couldn’t make it without lying.

Real estate doesn’t have a content shortage. It has a story shortage. And the response most of the industry is reaching for, more content, better production, more platforms, more posting, is solving a problem that stopped being the real problem a while ago.

The companies that figure that out will stop asking how to make more marketing and start asking whether they have anything worth marketing in the first place. That’s an uncomfortable question. It’s also the right one.

Key Takeaways

  • Here’s the problem with a rising floor: When everyone’s production quality improves simultaneously, production quality stops differentiating anything.
  • The vocabulary of disruption has become so widespread that it now signals nothing about actual disruption. Every company claims to be solving the same friction, but almost none of them tell you what, specifically, they understand about human behavior that nobody else has figured out yet.
  • AI is accelerating in ways that will make the current volume of mediocre content look modest by comparison. What hasn’t been automated is having something genuinely worth saying: a perspective that comes from actual experience rather than market research.

Real estate might produce more marketing per transaction than almost any other professional services industry on earth. Professional photography, drone footage, property films, social reels, brochures, digital advertising, portal listings, email campaigns. A single home sale can generate more content than some companies produce in a quarter. And somehow, most of it sounds exactly the same.

That contradiction is worth sitting with. Because the instinct when marketing isn’t working is almost always to produce more of it. Better cameras. Bigger budgets. More platforms. Higher production value. Real estate has been running that experiment for years, and the result is a market where everything looks increasingly polished and increasingly identical.

Production became a commodity

Not long ago, professional photography was a genuine differentiator in real estate marketing. Most agents were shooting listings on a phone or hiring whoever was cheapest. The agent who showed up with a real photographer was doing something visibly different. That gap closed fast.


Source link

Why Everyone’s Marketing Tactics Are Starting to Look the Same Read More »