You Don’t Need Dozens of Rentals to Reach Financial Freedom (He Tried It)

You Don’t Need Dozens of Rentals to Reach Financial Freedom (He Tried It)


For over a decade, John Crutchfield was in full-on acquisition mode. Despite starting with very little money, he scaled to over 600 units across multiple states and tens of millions of dollars’ worth of real estate. He even quit his job to focus on his portfolio full-time!

But then the market changed. Interest rates spiked, debt became more expensive, and John’s expenses ballooned. He had overleveraged his real estate portfolio, and suddenly, owning more properties wasn’t really making him wealthier. So he did something he had spent years trying to avoid: he started selling. And in the process, John learned a painful lesson about building wealth: sometimes, having less can actually give you more.

In today’s episode, John shares some of the highs and lows from his own real estate investing journey, how he went about pruning his portfolio, and why the number of doors you own doesn’t matter nearly as much as the cash flow, value, and freedom each property provides.

Henry Washington:
You don’t need dozens of rentals to reach financial freedom. And if you ask today’s guest, less is usually more. For over a decade, John Crutchfield was in full acquisition mode. Despite starting with very little money, he scaled to over 600 units across multiple states and tens of millions of dollars worth of real estate. He even quit his job so he could focus on his portfolio full time, but then the market changed. Interest rates spiked, debt became more expensive, and John’s expenses bloomed. Suddenly, owning more properties wasn’t making him any wealthier, so he started selling. And in the process, John learned a crucial lesson about building wealth. Sometimes having less can actually give you more, more cash flow, more flexibility, more peace of mind. In today’s episode, John shares the highs and the lows of his real estate investing journey, how he turned a smaller portfolio into a more profitable business, and why door count matters far less than the freedom each property provides.
What’s going on, everybody? I’m Henry Washington, co-host of the BiggerPockets Podcast. And today we’re bringing you an investor story with Dr. John Crutchfield who invests in Tupelo, Mississippi. So let’s bring him on. All right, Dr. John Crutchfield, welcome to the BiggerPockets Podcast, my friend.

John Crutchfield:
Man, too cool, too cool. How you doing? Henry Washington, the Henry Washington.

Henry Washington:
Why don’t you give us some background? Start a little bit before real estate and then kind of talk us up to where you are now.

John Crutchfield:
I’m John Crutchfield. Grew up in Tallahassee, Florida. I’m a Florida boy. Time came to go to college. It was like, okay, where are you going? Well, I don’t want to go too far. So Florida State was right down the street. Fast forward a little bit, got my first job as a teacher because teachers get summers off, they get all the holidays. Somebody said, “Well, if you go back to school, you’re such a good teacher. I bet you could be a good principal.” And I was like, “Yeah, you know what? That’s right.” So I went back and got a master’s degree, became a principal, realized that as a principal, you do get paid a little bit more, but you have to be there all the time. So somebody then said, “Hey, you’d like to talk and you seem kind of smart. Maybe you want to be a college professor.
That’s the next level. All of these, by the way, you got to go back to school, pay more money so that you can get a better job.” And so I just kind of followed that track, ended up as a professor at Ole Miss, that probably was my dream job, got to help people who wanted to become teachers become teachers. So very fulfilling work. But every time I got these increased roles, I ended up seeing lifestyle creep happen. So more money coming in the personal account meant, okay, better furniture or a bigger house, more spending because hey, you got to have a better car because you’re making more money. That’s the thought. And so ended up at the end of the month, no matter what job I had, not having enough money or having to wait till the next month. So then I started Googling stuff like passive income and stumbled on real estate investing.
There was this podcast at the time called the BiggerPockets Podcast. So it’s funny. Never heard

Henry Washington:
Of it.

John Crutchfield:
Yeah. And I stumbled on their forums, getting tons of quality answers from the community, but just started kind of feeding that bug of getting financial education.

Henry Washington:
How old were you at the time when you found this real estate bug?

John Crutchfield:
Oh, probably 26. 25, 26.

Henry Washington:
How long did it take you to go from that learning to doing and what were those steps?

John Crutchfield:
I ended up meeting a guy at church who had about 30 properties, and this was his retirement plan. And he, as we’re having the conversation says, “You should sit with me so I can show you what I’m doing.” And that mentorship became very valuable to me because we struck up a relationship, started having multiple conversations. He sat down with me and he told me, “Just look at your life in your W2 world. If you can run a school, you can run a business.” That was kind of my moment because before he said that, I had never in my life considered actually owning a business. That’s how ingrained it was for me that you go to school, you get good grades, you go to college, you get a good job. I was that guy. So what I ended up doing is going online like some people do and looking for sale by owners because I had a big problem.
I didn’t have any money. So I remember my strategy, very concrete, it actually still works in 2026. It’s a lot harder, but it still works. To go on Zillow, filter for sale by owners, and you get their phone number right there. And I will text them, “I’m interested in buying your house, but I don’t have any money. Will you owner finance it to me?” That was the text that I sent hundreds of times and one guy said yes. He said, “Actually, I will.”

Henry Washington:
It does still work. You can actually do that. But most people won’t commit to sending the amount of text messages that you would need to send in order for somebody to get a yes. Where people screw up, it’s not that you can’t get into real estate with limited funds, it’s that most people aren’t willing to put in the level of effort it’s going to take to find that deal and to get that deal closed when you don’t have money as a resource. You’re going to have to spend way more time and put a lot more effort in. You got to be more creative.

John Crutchfield:
Absolutely.

Henry Washington:
Well, I know it was a while ago, but the principles remain the same. Would you mind sharing with us kind of what that ended up looking like, what that deal structure was? What’d you pay for the house? How’d you structure the financing? What’d you give him? What’d you not give him?

John Crutchfield:
I bought the house for $80,000. It was a three bedroom, two bath in the market that I’m in, Tupelo, Mississippi. The monthly payment was $528 a month. And then I was responsible for the taxes and insurance. The house did need about $20,000 in work. So he had just had a tenant move and that’s why he was interested in this because he didn’t want to do the renovations. Ended up spending that 20,000, a lot of it was sweat equity, but getting the house presentable where we could rent the house out and ended up renting the house out for $1,200 a month.

Henry Washington:
So that’s a screaming deal.

John Crutchfield:
Look, I owned that house for maybe 10 years before we sold it and we sold it recently for like $220,000.

Henry Washington:
Sounds like a deal to me, buddy.

John Crutchfield:
Yeah. And I ended up having an investor relationship, kind of a guy that we ended up doing more business together because of this. So that first deal went pretty well.

Henry Washington:
This absolutely can still work. Almost all of my owner finance deals have been from landlords because landlords understand the value of cash flow. That’s why they were landlords in the first place. And a lot of people would love to get out of the business of being a landlord, but still maintain cash flow. And the way to do that is owner finance because then you get paid every month, but you’re doing got to deal with tenants and toilets. So if you want to try this, I would say try it, except just do it a little different now. Help yourself pull a list of people who own property free and clear, absentee owners and landlords. Call them all or text them all and ask them. And I bet you won’t have to send as many thousands, but it’ll still be a lot and you’ll get a lot of rejection, but this can absolutely still work.
So I’m very curious how that deal sparked your growth and how long it took you to scale, but I want to ask you those questions right after the break. All right. Welcome back to the BiggerPockets Podcast. I am here with investor Dr. John Crutchfield, who just told us the story of his first deal. And it’s so interesting that our stories are so similar in how we got started in our upbringings even into leading into that first deal. So you did a first deal, pure hustle, sent hundreds of text messages asking somebody if they’d owner finance you a house. And lo and behold, somebody says yes, you end up buying a screaming deal. How did that spark the rest of your real estate investment journey?

John Crutchfield:
When I had the mentor that I mentioned come over to look at the house after we were done, he was like, “I think you need to get this appraised.” That was the eureka moment. When I got the appraisal and I had $100,000 on this property, but it was worth 160, and at the time I was a professor at a college making $60,000 in a whole year. I was like, “Wait a minute, this is possible to do over and over and over again?” And he was like, “Yes.” And so that is how the first deal really kind of sparks the push into, “Well, if I could do this five times a year, I’d be making five times as much as I make on a job. And this is a no-brainer.” At the time, I never thought about quitting my job. I just said, “I could do my job and do this on the side.” So ended up doing my next deal.
Similar type situation. I would say you asked me how long. It was probably a year or two. There was some space, but ended up buying a property, again, very limited funds, using sweat equity. I have pictures with my wife and kids helping me paint and fix up countertops, but ended up doing a similar thing. $15,000 purchase. This is a Mississippi property.

Henry Washington:
$15,000 for the whole house or the down payment?

John Crutchfield:
For the whole house. There was an evolution that happened here. Once I saw that appraisal and the whole value add situation, my mind switched from, “Well, I need to get the properties for as low as possible.” My strategy improved, and this is a strategy I used probably for my first 30 units. You have all these people on the MLS that are trying to sell their property, and some of those properties are sitting there for months and months and months. So I found a realtor who would do what I asked, because some of them wouldn’t. I just want to offer $15,000 on everything on the market. And that’s what I started doing, just offering as low as possible on everything on the market. Some of them wouldn’t respond. Some of them would say, “Heck no,” all that stuff. But then somebody would counter a lot lower than their asking price.
Or in this case, the guy just said, “Have you even looked at the house? Yes, I’ll take 15K.”

Henry Washington:
That doesn’t sound like a good answer. Oh

John Crutchfield:
My goodness. If I asked a third grader to describe what they think a $15,000 house looks like, that’s what this house looked like.

Henry Washington:
The house needed a whole new house?

John Crutchfield:
It needed everything. It needed everything. Everything. Holes everywhere, stuff everywhere, vacant for a long time. But the numbers made sense. I ended up buying that house for 15K. My wife and I spent about 35. Again, a lot of that sweat equity in there, went to the bank and they said it was worth 100K. So this whole concept of adding value and making something worth more because you did the work, it really provoked an addiction. And so that’s kind of what I did. I started doing as many of these as I could.

Henry Washington:
I actually teach people how to offer on the MLS in a very similar fashion. You want to find a deal on the MLS? Do these steps. Define your buy box. Your buy box is just what you want to buy and where you want to buy it, right? Give that buy box to an agent who’s willing to submit offers for you. John said not everybody was willing to do this for him. That’s still true to this day. You got to find an agent who’s going to be willing to do this dirty work. And so I pull every house on the MLS that is in my buy box and has been listed for 90 days or more. Average days on market here is about 60 days. So I do 30 days beyond average days on market. That’s my assumption that they may be motivated for a lower offer.
And then I just have my agent offer 40% off of the price it’s listed for. So we take the list price, we subtract 40%, that is our offer. And we don’t write up official offers for everyone. My agent has a canned text message that he sends to the other agent that basically paints me as the bad guy so he doesn’t have to damage his reputation for making lower offers. He says, “Hey, I’ve got an investor client. He’s only making offers based on the numbers. It’s not personal at all. I’m sorry the offer’s not what you’re hoping it is, but would you consider an offer of X?” And he sends that to every one of these listings. We are not looking for someone to say yes. Matter of fact, I don’t want somebody to say yes. Like your guy said yes, that ended up being a doozy.
If somebody takes that and says yes, I’m probably pretty skittish, but absolutely want people to counter because if you counter or if you say, “Hey, we’d consider it, great. Now we can have a conversation. I can go see the house. I can analyze it thoroughly and I can make an offer.” This is the exact same strategy you just talked about, maybe refined a little different for the times. You guys, this stuff still works if you’re willing to put in the hustle.

John Crutchfield:
That idea of making offers and starting conversations is something that I still have to remind myself of all the time. When I want to build my pipeline, it’s like how many conversations have I had? How many offers have I made?

Henry Washington:
People get so overwhelmed with the concept of how do I find a good deal? Simplify the process. That’s what John just did. If you simplify the process down, it becomes a lot easier. So what if instead of worrying about what kind of marketing you’re going to do or if you’re going to make MLS offers, what if you just said, “What if I talk to three to five people a day who can sell me a house?” Just get on the phone with three to five people a day who can sell you a house. If you make it a point to have a conversation with three to five people a day who could sell you a house, I bet you’d buy a house pretty quickly, 30, 60, 90 days if you do that consistently. So what does that mean? You can either call direct sellers and see if they’re willing to talk to you about selling a house, real estate agent.
You can call real estate agents and see if they have anything that would fit your buy box, or you can call a wholesaler. Those are three different types of people who can all help you buy a house. So talk to one of each a day. What if you just talk to a wholesaler, a seller and a real estate agent every day? That’s very easy to do. And if you did that consistently for 30 days, I bet you’d be pretty close to getting a deal.

John Crutchfield:
And also what you’re doing is you’re leveraging other people to help you reach your goal. So now it’s not just the deal you’re looking at that you might have started the conversation with, but it’s all the other deals that they may be aware of that they may present and say, “Hey, this is something you should consider.” So you’re exponentially growing your reach by having these conversations.

Henry Washington:
Would you mind sharing with us kind of how big your business got over the course of the next several years and what that timeframe looked like for you to get there?

John Crutchfield:
So I actually don’t know how many I had at the peak. I really don’t. I would go to these conferences and people would be like, “How many doors?” And I was using a CRM, so I know I remember 585. I remember that number being in the CRM. Problem was I was focused on acquisition and growing, so not all the units ever made it into the CRM. We were picking up deals in Iowa. I was picking up deals in Arkansas, picking up deals we started buying in Texas.

Henry Washington:
And you were keeping these. These weren’t like wholesale deals.

John Crutchfield:
Never sold a property till the market turned and I realized I should have been selling some sometimes. It probably ended up being 600 plus.

Henry Washington:
That’s a lot of real estate across multiple states. Were you building teams in all these states to help you operate all this real estate and were you buying it all creative? That’s a lot, man.

John Crutchfield:
Yeah. So out of state means you got to leverage other people. And so a lot of times we were partnering with property management in those areas because I didn’t have a team there. And then you’re absolutely correct. You probably are not going to buy 500 plus units with it just being one house at a time, one property at a time. And so somewhere in 2017, 2018, it kind of clicked for me that a lot of property owners, a lot of landlords had more than one property that they would want to sell at one time.
And so I remember buying a package of 50 doors. I remember buying a package of 30. I would go on the property tax records and I would look for LLCs or people that had multiple properties under their name and they would get a text or an email from me. And at that point, my goal was growth. So if they asked me what I wanted to buy, it was like, how much are you willing to sell? And so I started being that leader, that visionary that was thinking, how fast can I grow the door count? Since I’ve realized that that actually doesn’t matter at all. So what I loved doing was making an offer on a property, figuring out what my renovations were going to be, figuring out what that ARV was going to be and putting that in a spreadsheet, figuring out what the rent was going to be, what the expenses I thought would be, and putting that in a spreadsheet.
And so what I would do is every time I was acquiring, I would just add to my spreadsheet and it starts to add up really fast. I mean, when I say I got addicted to this, I got addicted to every 30 days updating my personal financial statement and seeing my net worth just going up like crazy or every single month seeing the deposits in the bank account keep going up. And so if you’re somebody who grew up like I did or who was a school teacher and you’re making $3,000 net after your pay, seeing $100,000 hit a bank account or $200,000 start to hit a bank account every single month, you’re just looking at that top number saying, “This is beautiful. I’m doing something right.” But when you as the owner are focused on just growing, you are kind of at the mercy of your property management, you’re at the mercy of your team.
And then most importantly, you’re at mercy of the expenses staying the same as what was in your proforma, and that will not stay the same.

Henry Washington:
Were you still working your day job when you were this big?

John Crutchfield:
I quit my day job once I realized the possibilities, right? In fact, I just became a horrible employee, right? They would ask me to do something extra or give me an extra assignment and I was like, “Do I want to do this instead of trying to be a good team player?” So I remember, and this was in the peak of good times, I remember doing a deal where I added $300,000 into my net worth on one deal. I remember my boss saying, “Hey, we need you to teach an extra class or something and we’re not going to pay you for it because we think you can fit it in your schedule.” And I was like, “I got to talk to my wife, but I think I’m done.” And I ended up quitting, but I went full-time into this business somewhere around 2019. And so that meant every day I was giving 100% of my effort to growing the business.
I’m an entrepreneur now. I’m a full-time business owner. I probably work too much, but I don’t clock in or clock out. So it feels like I’m doing what I like to do.

Henry Washington:
And that’s specifically what I’d like to talk to you about right after the break is what were some of the lessons you learned as a technically small business operating a large portfolio. So let’s jump into that after we come back. All right, we’re back on the BiggerPockets podcast. I’m talking with investor Dr. John Crutchfield, who took growing and scaling to a whole new level and did it during a market transition. You said you quit your job in around 2019. The market got real good between 2019 and 2022, and then it’s been not as great from 2022, 2023 until now. So I’m very curious about what lessons you learned while you were in that growth mode and operating mode and how that’s shaped where your business is today.

John Crutchfield:
I learned that more doors does not necessarily mean more success. Once you get into it, you realize, okay, I’m actually now managing employees, I’m managing contractors, I’m managing inventory and materials that I don’t want to just walk off. All of the little issues that you might have on one project, I want you to start multiplying those by hundreds of doors. You know the stories, right? Contractor walks off with this material or you got a water leak or some kind of plumbing issue or AC out, and this is going to create wear and tear on your properties, but also ultimately affect your bottom line, which is what matters, not door count, your bottom line, what’s left over at the end of the month. And so people ask me, well, what’s it like? Were you really making 50, $100,000 a month? Henry, I remember celebrating at one point I was paying off a house every single month.
In Mississippi, a good house was 60, 70K. I was paying down 50, 60, 70K a month in debt pay down and looking at that like, man, I got a house paid off and I’m doing that every single month. So beautiful. But then you’d have some seasons of the year where we were giving that back in CapEx because when their AC goes off, it has to be fixed. You can’t say, well, I’m just a little landlord and I only have a property or two and I need you to understand or you’re going to be in a newspaper. You got to get those units fixed and get those people back up so that they’re operating, they can have a safe, affordable place to live. A key principle here is that it’s like a living, breathing organism as you grow that has so many lessons that you can’t find in a book.

Henry Washington:
Yes.

John Crutchfield:
And that’s what I learned.

Henry Washington:
So how did that change your business? Did you start to sell property? Did you stay in growth mode? What changed and when did it start to change?

John Crutchfield:
So big change started in late 2022, 2023. A lot of us are aware that the Fed started increasing interest rates. And if you have $30 million borrowed and your interest rate average is 4%, that’s like free money. It’s beautiful. You’re making payments and you got money left over to do stuff. But when that same $30 million, and a lot of my loans were these local community bank loans that reset every five years, ask me how they time this, okay? When they reset and then your average interest rate goes to eight, that literally is a huge increase in your expenses and it changes your lifestyle. So if I had one property where the mortgage payment went from 12,000 to 21,000, that changes the salaries that I can pay off that property. It changes the salary I can pay myself. And then you multiply that across the whole portfolio and you’re really in a tight trying to figure out, okay, how am I going to adjust?
The first adjustment we made is like, okay, let’s double down on the strategy that was working for me. I grew the business by burrowing, buying and fixing up the property and renting it out and refinancing. So let’s go borrow some more money so that we can have cash to keep operating. That was the first thing I did. The problem is we weren’t borrowing that cheap money anymore. We were borrowing more expensive money. And it got volatile, Henry. It got kind of volatile for a little bit as those rates were going up. Some of the lenders started squeezing in some 10% rates in there. So we had the cash to operate today, but not the cash to operate in the future if we were depending on cashflow. And so realized looking at the spreadsheets that this was not going to work. Eventually we were going to run out of cash and we were going to run out of the ability to keep borrowing.
And so this is when I started saying, okay, we got to sell some stuff. I wish I had took some chips off the table sooner. I will tell you something, this is probably put this on a bumper sticker. It’s actually very easy to buy real estate. It is a totally different game to sell real estate.

Henry Washington:
That’s true.

John Crutchfield:
And it’s a new skill that we’re still having to learn because we’re still selling some properties. Fortunately, I met some awesome realtors who have been helping dispose some of the portfolio, and I’m also now a licensed realtor, so I’ve learned a little bit more about selling properties as well. I told you I quit my job, but I thought that I quit my job to live off the rental properties. That was a misunderstanding. And so when you start pulling your lifestyle off of the rental properties, that makes the things tighter as well. And so what I learned as we started selling properties is like, oh, I actually still need an active income from something to make sure that I’m not pulling money off of these very limited tight margin rental properties and cash flows. So that’s probably a whole nother thing. But if I could save one person, I’m like, “Hey, quitting your job is beautiful in this business once you’re ready, but it’s not always the right thing for everybody.”

Henry Washington:
The realization I had was I’m running a business, the business makes money, and then if I take all the money it makes out of the business every month, it’s hard for the business to grow. If I suck every ounce of profit out and I don’t reallocate some of that to improving the business, the business doesn’t grow. Any business that isn’t real estate, they don’t do that. They don’t suck all the profits out and then hope the business grows. There’s a plan for reallocating profits to continue to grow the business. Two, most investors realize, okay, if I’m going to quit my job, it’s not going to be the cash flow that gets me there. It’s a hard realization because most of us get sold into real estate investing on the concept of properties paying for life’s expenses. That was the thing that got me. Oh, you want to buy a new car, get a house.
The house produces cash flow, cashflow pays for the car. In practice, it doesn’t always work like that because maintenance is unpredictable because even if you are predicting the maintenance, if you haven’t owned the property that long, you haven’t saved up enough cash to cover said maintenance item that comes from somewhere out of your pocket, which means you have less to go pay for this new car or this thing you have in your lifestyle. And so you realize the same thing I realized and the same thing that a lot of investors listening to this are going to realize that if I want to quit my job and use real estate, I can’t just do it on cash flow. I have to find another active income stream within the real estate space to do that. And there’s nothing wrong with that. And so I tell people, yeah, I retired from corporate, but I didn’t retire from working.
I flip houses. That’s a job. It’s a construction business. That’s what I do. And on its surface, I flip houses. So I run a construction business that renovates properties that produces cash. I use that cash and I live off that cash so I don’t have to touch my cash flow. I can use that cash to also pay down the assets and then at some point I won’t have to flip houses anymore. And so for those of you that are listening, if you want to quit your job, you can get there, but think of it in two phases. Phase one is if I want to get out of my corporate gig, what job within the real estate space can I replace my corporate gig with? Phase two is to work yourself out of having to have that active income stream over the course of the next several years.
So my goal is to take the flip proceeds, pay off more rentals. More paid off rentals is unleveraged cash flow, unleveraged cash flow is substantially higher than leverage cash flow, and at some point I don’t have to flip houses anymore. So that’s the way that I think people need to think about leaving their job.

John Crutchfield:
And you don’t need hundreds of doors if you’re looking at it like paid off rental property. So the 500 number, totally unnecessary. What you just said there is like gold for anybody that’s like, okay, if I want to fast track my knowledge five, 10 years in the business, just listen to what Henry just said about active cash flow, paying off your eventual retirement income.

Henry Washington:
Let’s put some actual numbers to this, if you don’t mind. Where does your portfolio stand today and where are you trying to get it to?

John Crutchfield:
I mean, at the peak, we probably were close to 30 to 35 million in assets and today we’re down to about 10 million.

Henry Washington:
Wow. So you sold two thirds of your portfolio?

John Crutchfield:
Yes. And selling and selling. So what that means is we’ve had capital to be able to reinvest in other things, but also it means we’ve taken some chips off the table. Unfortunately, we are not selling at a time where you can get those max values. And so that means that in some cases I’ve had to be a motivated seller. We wanted to get out of certain debt. Just to be clear, if I’m at a 10% interest rate right now, that property is not making money, not in the market that I’m in. So being out of them in certain cases was better than holding onto them. I don’t actually have a target anymore for the size of the portfolio because what I realized is that I already have more than I’ll ever need if it’s paid off.
I’ll give you an example. A lot of my properties are five, 10 property packages. Well, if I sell six of them, I’ve got four free and clear. And that’s been happening over and over for the last three years. So I’m starting to fall in love with the ones that we own that don’t have any payment, whereas the ones that are kind of in these packages and still in debt, especially if they’re not cash flowing, they got to go. Of course, I have a proforma and I have a spreadsheet, but when you go to sell, you don’t know what’s going to sell first or what’s going to sell for what.

Henry Washington:
There

John Crutchfield:
You go. And you’re kind of adjusting the plan every 30 days as it goes.

Henry Washington:
This is the realest real estate talk I’ve had in a while. All right, John, you shared a lot with us and I’m sure there are people who would love to learn more about you and the choices you’ve made in your business. And so if somebody wants to reach out, how can they find you?

John Crutchfield:
You can find me all over social handle is @grabthemap, or you can just search my name on Facebook. I’d probably hang out there where the old folks are. That’s what my kids tell me is where the old folks are.

Henry Washington:
All right, John. And if you are listening to this episode and you are thinking, “Man, I’ve got a pretty cool story I’d like to share with the listeners of the BiggerPockets Podcast,” well, you may have a chance. Why don’t you head on over to biggerpockets.com/guest and fill out the form. You may find yourself right here in a conversation with myself or Dave sharing your story for the betterment of our community. Once again, thank you so much for listening to the BiggerPockets Podcast. We’ll see you on the next episode.


Help us reach new listeners on iTunes by leaving us a rating and review! It takes just 30 seconds and instructions can be found here. Thanks! We really appreciate it!

Interested in learning more about today’s sponsors or becoming a BiggerPockets partner yourself? Email [email protected].


Source link

You Don’t Need Dozens of Rentals to Reach Financial Freedom (He Tried It) Read More »

AI Governance Needs Instrumentation, Not Insurance

AI Governance Needs Instrumentation, Not Insurance


AI Governance Needs Instrumentation, Not Insurance


What’s New?

Updated 2 hours ago


Source link

AI Governance Needs Instrumentation, Not Insurance Read More »

What LEGO’s Near-Collapse Taught Me About Saying ‘No’

What LEGO’s Near-Collapse Taught Me About Saying ‘No’


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Growth and ownership aren’t the same thing, and trying to personally run everything your business touches can bankrupt the parts that actually matter, one distraction at a time.
  • The instinct to build and operate everything in-house often masks a business that’s spreading its best people too thin across things they don’t actually do best.
  • A simple audit of what you own versus what you personally operate usually reveals one or two things you should hand off, long before the numbers would ever force the decision.

By the early 2000s, LEGO had expanded well beyond the plastic brick that built its name. The company was operating its own Legoland theme parks, running an in-house video game development studio and producing its own clothing line and television content. This looked like smart diversification: A toy company was evolving into a full entertainment brand.

But in practice, LEGO was trying to be an amusement park operator, a game studio and a clothing brand all at once, none of which it had ever actually been good at, while the core product — the brick sets that built its identity in the first place — lost focus and market share as attention scattered across everything else. By 2003, the company had lost close to a third of its revenue in a single year. It was reportedly within about 18 months of running out of cash entirely.

When Jørgen Vig Knudstorp became CEO in 2004, he did something a little unexpected: He didn’t abandon the games, parks or films. Instead, LEGO sold majority ownership of its theme parks to Merlin Entertainments, while keeping the licensing rights, so the brand stayed in the parks without LEGO having to run them. The in-house game studio was shut down, and LEGO began licensing its brand to specialist developers instead, which is how Lego Star Wars and Lego Batman came to exist (parents: ask your kids).

A decade later, The Lego Movie came to be the same way, as a licensed partnership with a film studio, not an internal production arm. LEGO kept every one of those businesses. It stopped being the one operating them.

This paved the way for one of the most legendary comebacks in business history.

The difference between owning something and running it yourself

Nobody at LEGO decided theme parks or video games were bad ideas. They were good ideas. The mistake was assuming that having a good idea for a business meant LEGO had to be the one personally running it.

Operating a theme park requires an entirely different set of skills than designing a toy. Building a video game engine requires an entirely different discipline than manufacturing plastic bricks. LEGO’s leadership had correctly identified where the opportunities were and incorrectly assumed that capturing the opportunity meant doing the operational work themselves.

The fix meant recognizing which parts of the opportunity they should own and license out, and which single thing, the brick system, they needed to run themselves better than anyone else could.

I’ve seen this pattern in the business owners I work with, and I also relate.

The year I had to decide

A few years ago, when my father passed away, I found myself responsible for running the family businesses on my own — work we had previously split between us. On top of that, I had my own growing venture: the coaching that has become an integral part of what I do today.

The logical move was obvious: The coaching business was the smallest revenue generator by far, and it was also demanding on my time because it was my newest venture. Every efficiency argument pointed toward shutting it down and focusing entirely on the established, profitable businesses.

I couldn’t do it.

That work was something that fulfilled me, and giving it up to save time felt like solving the wrong problem. So instead of cutting the newest business, I went back into one of the established ones and looked at every part of it individually: what each piece actually generated and how much of my direct, personal attention it needed to keep running.

Here’s what I found: It was, in fact, possible that someone else could run them well without my direct hand in it every day. So I handed them off, because keeping myself personally attached to them meant I never had the space to do the coaching work that mattered to me, or to lead the rest of the business properly.

The audit that actually makes a difference

The audits that business owners see regularly say nothing about which parts of your business are consuming your personal attention in a way the revenue number never shows. LEGO’s theme parks and game studio weren’t obvious disasters … for a while. They were slow leaks on leadership’s focus, long before the financial damage became impossible to ignore.

But that’s not to say any of those were bad decisions, because every business owner adds things for good reasons. There are opportunities too promising to pass up, natural extensions of what customers already love, which give you a chance to be involved in something exciting.

The mistake is assuming that chasing a good opportunity means you personally have to operate every part of it.

An exercise to run this month

Take the different parts of your business, whether that’s product lines, services, client segments or side ventures, and lay them out individually. For each one, ask two separate questions: “What does this actually generate?” and “Does it need my direct, personal involvement to keep running, or could someone else — a hire, a partner, a licensing arrangement — run it perfectly well without me in the middle of it?”

You’re looking for the mismatch: the thing that deserves to exist in your business, but doesn’t actually need you personally running it day to day.

When you find it, you have the same decision LEGO made when it sold the theme parks and shut down the game studio while keeping both in the business through licensing. Own the thing that made you valuable in the first place. Let people who are more suited to operating the rest actually operate it.

The real goal was always creating something built to last. Sometimes, the fastest way back to that starts with being honest about which parts you actually need to be doing yourself.

Here’s to building a business, and a life, with zero regrets.

Key Takeaways

  • Growth and ownership aren’t the same thing, and trying to personally run everything your business touches can bankrupt the parts that actually matter, one distraction at a time.
  • The instinct to build and operate everything in-house often masks a business that’s spreading its best people too thin across things they don’t actually do best.
  • A simple audit of what you own versus what you personally operate usually reveals one or two things you should hand off, long before the numbers would ever force the decision.

By the early 2000s, LEGO had expanded well beyond the plastic brick that built its name. The company was operating its own Legoland theme parks, running an in-house video game development studio and producing its own clothing line and television content. This looked like smart diversification: A toy company was evolving into a full entertainment brand.

But in practice, LEGO was trying to be an amusement park operator, a game studio and a clothing brand all at once, none of which it had ever actually been good at, while the core product — the brick sets that built its identity in the first place — lost focus and market share as attention scattered across everything else. By 2003, the company had lost close to a third of its revenue in a single year. It was reportedly within about 18 months of running out of cash entirely.

When Jørgen Vig Knudstorp became CEO in 2004, he did something a little unexpected: He didn’t abandon the games, parks or films. Instead, LEGO sold majority ownership of its theme parks to Merlin Entertainments, while keeping the licensing rights, so the brand stayed in the parks without LEGO having to run them. The in-house game studio was shut down, and LEGO began licensing its brand to specialist developers instead, which is how Lego Star Wars and Lego Batman came to exist (parents: ask your kids).


Source link

What LEGO’s Near-Collapse Taught Me About Saying ‘No’ Read More »

Why Better Branding Makes More Money Than Better Marketing

Why Better Branding Makes More Money Than Better Marketing


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • The first conversation with a customer is not the beginning of the sales process. It’s often closer to the end of it. Your first impression actually starts with whatever exists on the internet about you and your business.
  • People don’t hire the first company they find. They hire the first one they truly believe in.

For a long time, winning in real estate meant being easier to find. Get your name in front of more people, show up on more searches, run more ads and post more content. The industry built its entire marketing philosophy around the assumption that the agent who reached the most people would get the most business.

That assumption is quietly breaking down.

Consumers today are not starved for options. They’re overwhelmed by them. A buyer in any major market can find dozens of qualified agents before lunch without trying particularly hard. Search, referrals, social media, AI tools, Zillow profiles. Discovery is essentially solved. What hasn’t been solved — and what actually determines who gets hired — is something different and considerably harder to manufacture.

Who do they believe?

Discovery is no longer the hard part

The marketing problem most brokerages are still trying to solve was genuinely difficult 15 years ago. Getting found required real effort, real investment and real strategy. The playing field rewarded whoever could achieve the most visibility. That era produced an entire industry built around lead generation, impression counts and reach.

Lead generation has been commoditized. Practically every brokerage has access to the same digital tools, the same ad platforms, the same syndication networks. Being findable is table stakes now, not a competitive advantage. The brokerages still treating it as their primary strategic focus are optimizing for a problem that largely solved itself.

The harder problem, the one most of the industry is underinvesting in, is what happens after someone finds you. A consumer has now discovered three or four qualified agents. They look at each one for a few minutes. They read some reviews. They scroll through some content. They may ask an AI tool who the most respected agents in the area are. At the end of that research session, one of them feels like the obvious choice and the others feel like options.

What made one feel obvious? That’s the question that matters.

Consumers are buying confidence, not information

Here’s the thing most marketing misses about what people actually need when they’re making a high-stakes decision. They’re not looking for more informatio — they already have more information than they know what to do with. What they’re looking for is a reason to stop being uncertain.

Confidence is the real product in real estate. Not MLS access. Not showing schedules. Not transaction coordination. The thing a buyer or seller is actually purchasing when they hire an agent is the feeling that they’ve put this complicated, financially enormous, emotionally loaded process into hands they can trust. When that confidence exists, the conversation is easy. When it doesn’t, no amount of follow-up calls or drip emails can manufacture it.

Trust reduces perceived risk. That’s what it’s doing functionally in the consumer’s brain. When someone trusts you, they stop running through worst-case scenarios. They stop second-guessing. They stop hedging. They commit. And the brokerages that understand trust as a business asset, not a soft skill, are building toward a completely different competitive position than the ones still chasing clicks.

The sales process starts long before the first call

Here’s where strategy needs to shift. Every public signal surrounding a brokerage or agent is doing trust-building work before any conversation happens. Reviews. Media coverage. The quality of published market insights. Whether the agent has been quoted somewhere credible. Whether their educational content suggests they actually understand the nuances of the local market or just know how to use Canva.

Consumers increasingly arrive having already researched you. The first conversation is not the beginning of the sales process. It’s often closer to the end of it. And the agent who walks into that conversation with a trail of credible third-party signals behind them is starting from a fundamentally different position than one who showed up with a nice headshot and some listing stats.

Most brokerages are obsessed with generating more leads. Very few ask seriously why they lose the leads they already have. A significant portion of those losses happen before the first meeting, during the research phase, when a consumer is quietly deciding whether this particular brokerage feels like the obvious choice or just another option. No amount of lead generation investment fixes that problem. The fix lives upstream.

Think like a reputation architect, not a marketer

The mental model shift here is specific. Marketing asks: How do we get more people to find us? Reputation architecture asks: What does someone find when they look, and does it make us easier to believe?

Those are different questions with different answers. Marketing produces content. Reputation architecture produces signals. Content fills time. Signals accumulate into something that changes how a brokerage is perceived before anyone has spoken to them.

Every published market analysis that demonstrates real knowledge of a neighborhood. Every media mention that positions an agent as a credible voice in the local housing conversation. Every client review that describes something specific rather than just saying it was a great experience. Every piece of original thinking that makes someone pause and consider a perspective they hadn’t encountered before. These things aren’t separate marketing activities. They’re deposits into something that eventually becomes the most valuable asset a brokerage has: the default assumption that they’re the right choice.

The first agent they believe

Pull together everything that shapes who wins a high-stakes service decision. Discovery matters, but discovery is nearly even across the field now. Price matters at the margins. Referrals matter, but referrals still require a research phase where someone decides whether the recommendation makes sense. What ultimately determines selection, consistently, is uncertainty reduction. The option that makes someone feel most confident tends to win even when other options are objectively comparable.

People don’t hire the first agent they find. They hire the first agent they believe.

If someone spent 20 minutes researching your brokerage today, what story would they find? Media coverage that signals expertise? Reviews that describe specific moments of value? Published thinking that demonstrates real understanding of what’s happening in the local market? A clear sense of who you are and what you actually stand for? Or would they just find listings?

The brokerages that answer that question honestly and don’t like what they find have identified the actual strategic problem. It’s not a lead generation problem. It’s a belief gap. And closing it requires investing in something most real estate marketing budgets still treat as secondary: becoming genuinely easy to trust before anyone has asked you to earn it.

Key Takeaways

  • The first conversation with a customer is not the beginning of the sales process. It’s often closer to the end of it. Your first impression actually starts with whatever exists on the internet about you and your business.
  • People don’t hire the first company they find. They hire the first one they truly believe in.

For a long time, winning in real estate meant being easier to find. Get your name in front of more people, show up on more searches, run more ads and post more content. The industry built its entire marketing philosophy around the assumption that the agent who reached the most people would get the most business.

That assumption is quietly breaking down.

Consumers today are not starved for options. They’re overwhelmed by them. A buyer in any major market can find dozens of qualified agents before lunch without trying particularly hard. Search, referrals, social media, AI tools, Zillow profiles. Discovery is essentially solved. What hasn’t been solved — and what actually determines who gets hired — is something different and considerably harder to manufacture.


Source link

Why Better Branding Makes More Money Than Better Marketing Read More »

She Created a Swim Brand With Just 0, Sold It for 7 Figures

She Created a Swim Brand With Just $300, Sold It for 7 Figures


Key Takeaways

  • Jessica Liao Mayers launched Slate Swim in 2015 with $300, a sewing machine and made-to-order products.
  • Slate’s minimalist, seamless swimwear stood out because Mayers resisted chasing trends.
  • Mayers bootstrapped the company, putting revenue back into production, inventory, branding and operations rather than taking outside capital.

She created a product that filled a gap in an industry — and scaled it to a seven-figure business. 

That’s the trajectory Jessica Liao Mayers took over the course of 11 years. Mayers grew up outside Dallas in a family of medical professionals. Fashion was not an obvious career choice. Still, a high school fashion class, one she initially took because she thought it would be easy, changed her path. 

“I ended up really, really loving it,” Mayers says. She competed in state and national fashion design and construction competitions, then moved to Los Angeles to attend the Fashion Institute of Design & Merchandising, where she studied product development.

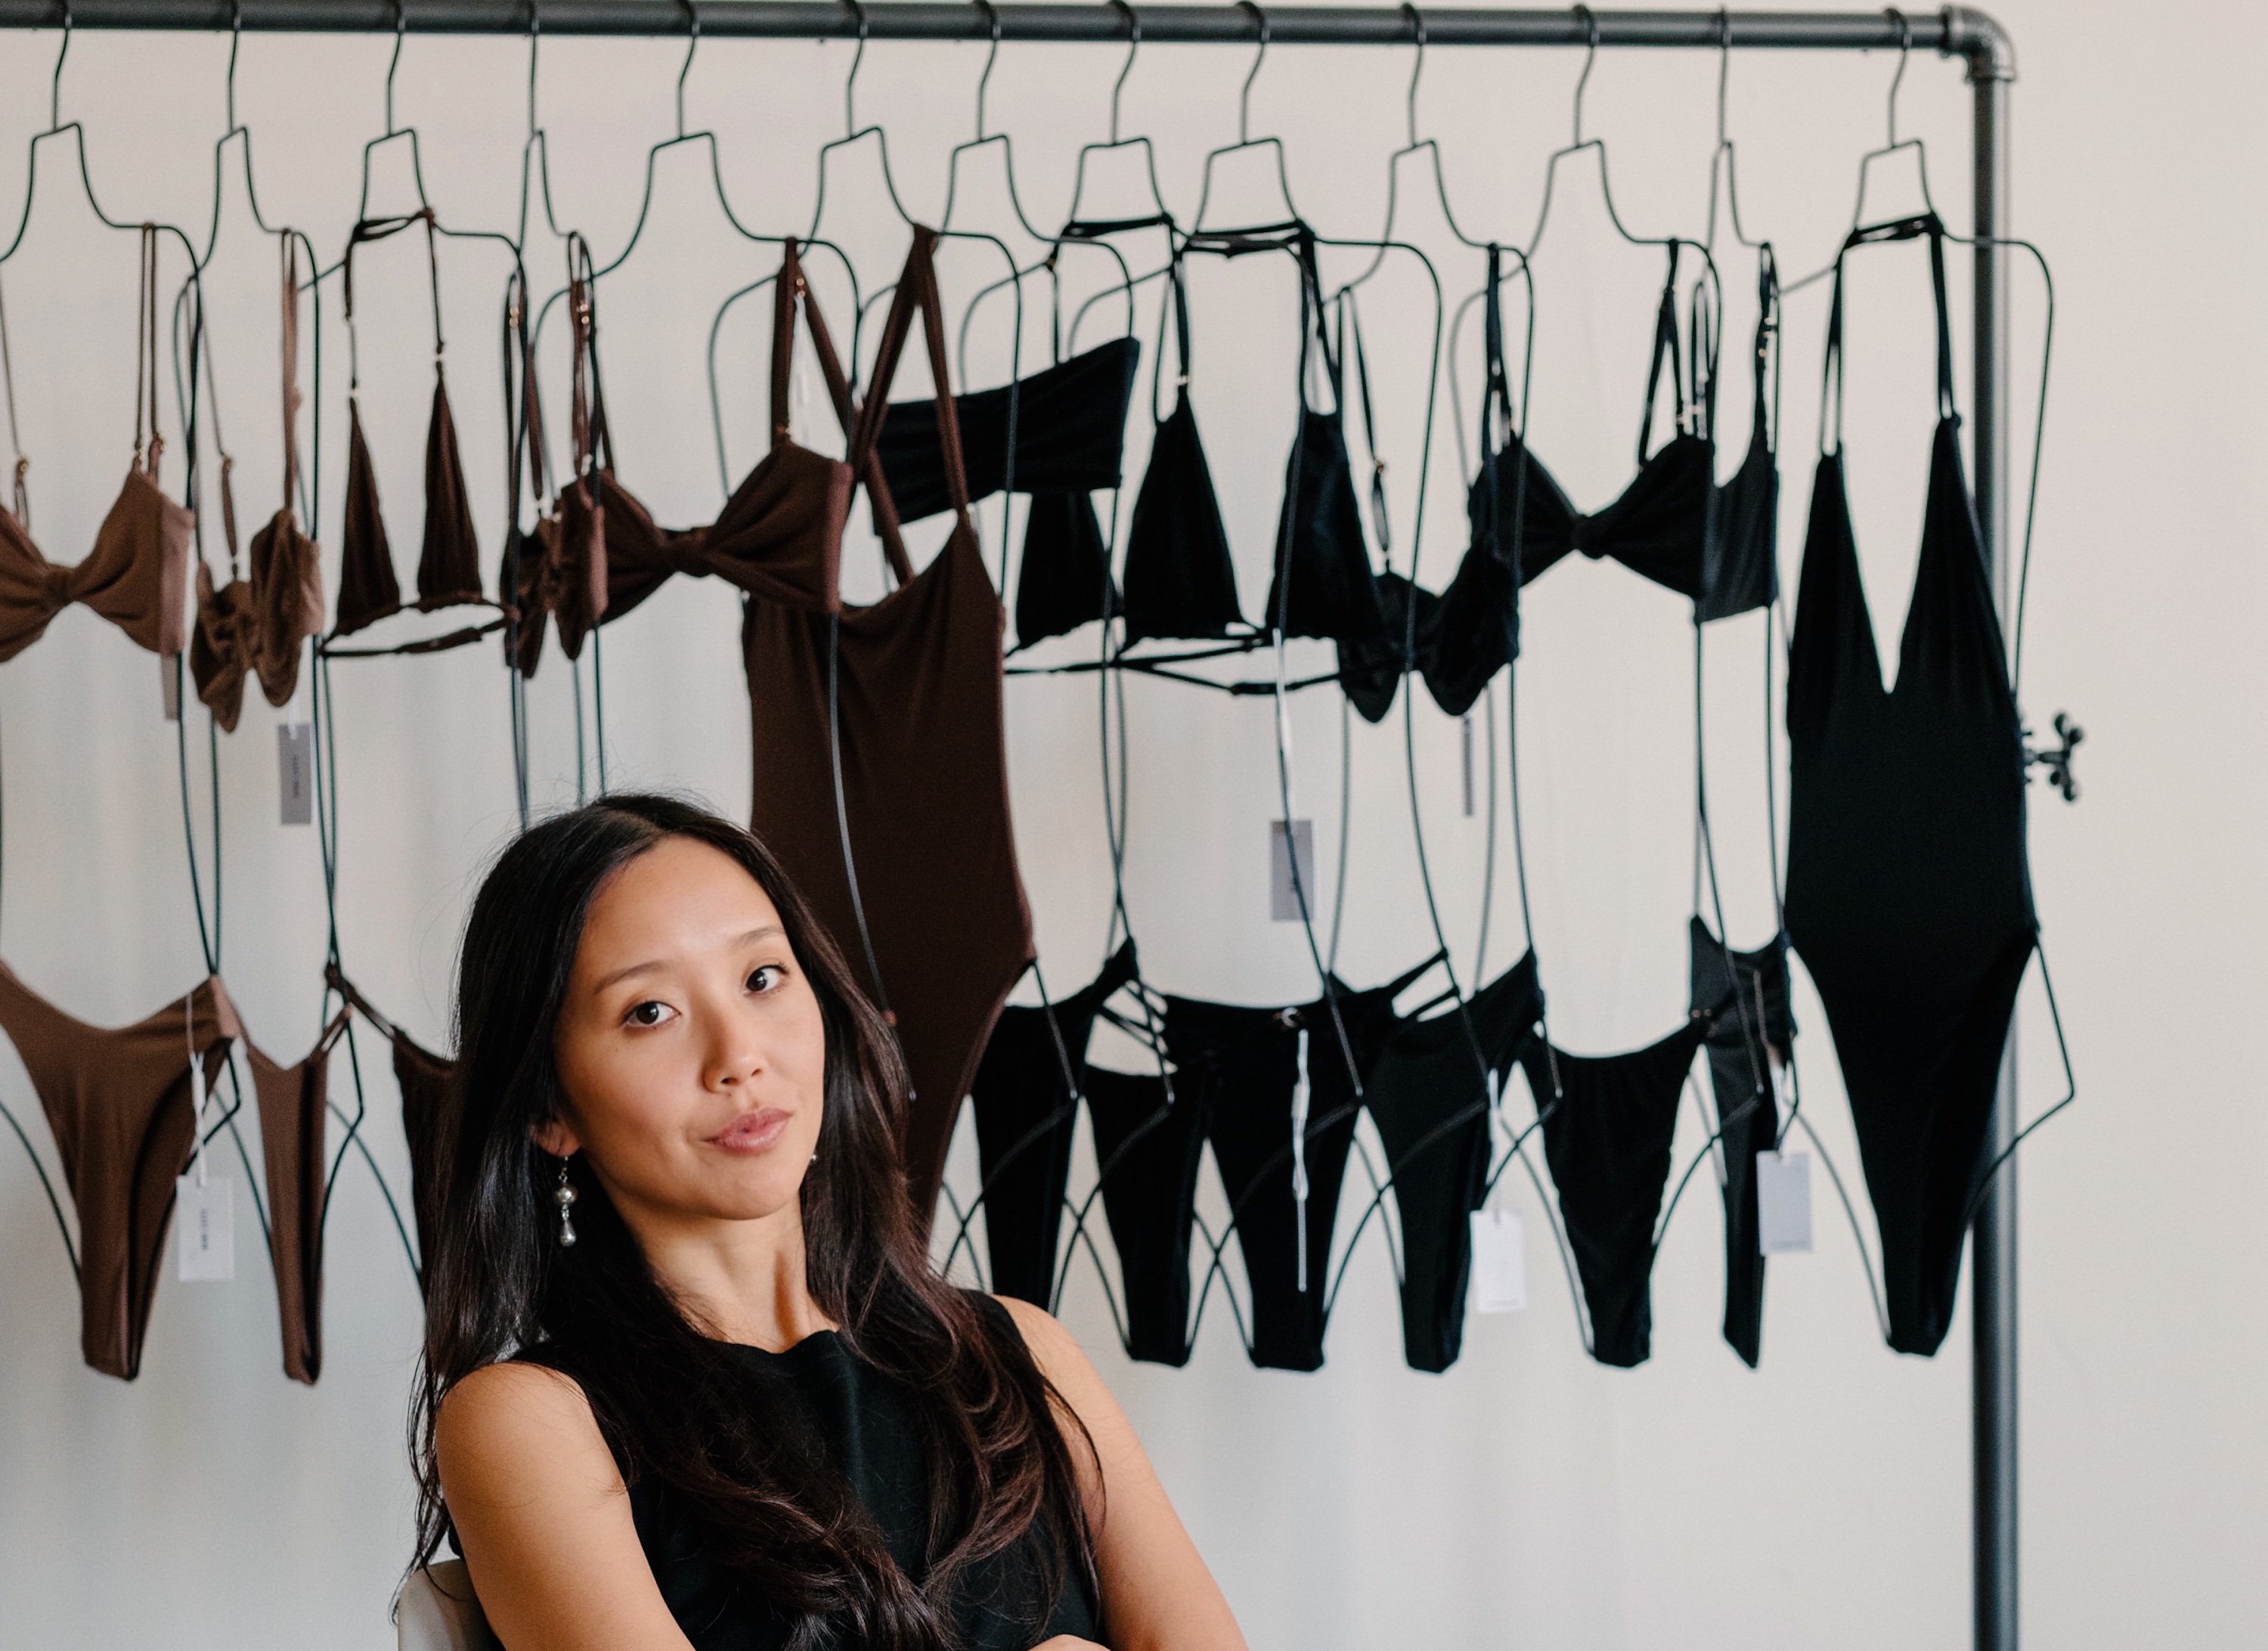
Jessica Liao Mayers. Credit: Slate Swim

After graduating in 2014, Mayers quickly found work as a designer and product developer at lifestyle brand BCBG. She learned fashion design at the company, then switched gears, jumping to apparel company Tobi as a buyer and learning the wholesale retail side of the industry.

At Tobi, Mayers encountered a problem that was good to have: She was quickly completing work. 

“I was very quick,” she says in a new interview with Entrepreneur. “My boss would give me the week’s worth of work on a Monday, and I would finish it in a few hours. I’d be so bored. So I was like, What do I do? I started my own business.”

Identifying a gap in the market

Mayers started Slate Swim in her home in November 2015. She spent $300 on fabric, then made products to order using a sewing machine she already owned.

Mayers would work on Slate on the side during lunches, running around the Fashion District to purchase fabric. Then she would sew when she got home. She was just 21 years old.

“I needed to start the brand because I needed something for myself,” Mayers says. “I got the idea because when I would go to buy swimsuits, I never really found something that was super comfortable.”

Mayers identified a gap in the swimwear market. Mass-produced, thick nylon swimsuits on one end, and high-end, trendy brands on the other. She found nothing minimalist. 

“There wasn’t anything more cool and reserved, and that’s very much my style,” Mayers says. “I like to wear very clean silhouettes, neutrals. I didn’t want to put on a swimsuit and not feel like myself.”

Slate Swim Spring/Summer 2026
Spring/Summer 2026. Credit: Slate Swim

She differentiated her brand from the start. Slate offers swimsuits with minimal seaming, so everything lays flat and smooth on the body. The company uses a thin, soft fabric that feels like a second skin. The first fabrics she experimented with were actually lining fabrics, which was unusual at the time.

Mayers says that in the 11 years she has led Slate, she has seen the industry change tremendously. 

“I think I came in at a really good time when social media really wasn’t being used for brands,” she says. “I think that’s part of why we grew so quickly as well.”

A major leap

Before Mayers had inventory or a manufacturer, Agenda Trade Show discovered Slate’s early Instagram account, which Mayers used to share inspiration and teasers. The surf- and skate-focused show wanted to bring in swim brands and invited her to exhibit. 

Mayers accepted. She signed up for the show even though she was actually supposed to go to that same show as a buyer for her company, Tobi. She had to tell her employer with a week’s notice that she had to quit because she was going to be showing there as a brand.

“They had no idea,” Mayers said. “It was really insane.”

However, the timing of the show created a problem.

Mayers had no production operation in place. To prepare, she made 30 samples herself in her apartment, cutting and sewing every one. At the trade show, Slate landed in 22 retailers, including Diane’s Beachwear.

The orders were a major validation, but they also introduced an immediate operational challenge. Mayers didn’t have a manufacturer yet. At the show, she met someone who connected her with a small Los Angeles production shop. That arrangement helped Slate fulfill its early wholesale orders.

Eventually, Mayers moved production overseas and partnered with a small, family-owned manufacturer run by a contact she already knew through Tobi. The relationship became central to Slate’s growth. Unlike the first local factory, which could be inconsistent, the overseas partner provided more dependable quality and production capacity.

The business expanded gradually. Mayers reinvested revenue into better production, branding, photography and ecommerce rather than trying to build every capability at once.

That deliberate pace was a feature. “Everything kind of grew at a slower pace, but very, very manageable,” she says.

Why she chose focus over expansion

For 11 years, Slate stayed in its lane. Mayers resisted suggestions to expand into menswear, resortwear or other adjacent categories. She believed the brand would be stronger by specializing.

“I would much rather be successful at one thing than mediocre at many things,” she says.

That focus also protected the brand’s identity. Slate was founded around a specific aesthetic: minimalist silhouettes, neutral tones and flattering fits. Mayers learned firsthand that chasing trends could dilute that point of view. She recalls experimenting with trend-forward colors, including neon yellow, in one collection. The products performed poorly.

“After that, I was like, Okay, never again. I’m just going to do my thing,” she says.

Her marketing approach followed the same principle. In Slate’s earliest days, photographers reached out to pull suits for beach shoots and test shoots. Mayers received high-quality imagery in exchange for credit and tags, allowing her to establish an elevated visual identity before she could afford major campaigns.

One influencer posted a photo wearing Slate, which generated 30 orders overnight, an enormous moment for a tiny, early-stage company. Mayers also began gifting products to people who fit the brand, building relationships one by one rather than chasing a single viral breakthrough.

“It didn’t really go so viral in a sense of one thing that happened or blew it up,” she says. “I think it was just consistently investing in those small relationships.”

The compounding effect of that strategy helped lay the groundwork for later growth.

Where she waited too long

Mayers now says she waited too long to embrace paid advertising.

Until 2021, Slate had not invested in ads. When Mayers finally hired an advertising team, the business accelerated. She says in the first year using paid marketing, Slate grew about 76%. The ads used polished campaign imagery to sell the feeling and world of the brand.

Her first outside hire was an ad team with an engineering background, an unconventional choice that appealed to Mayers because of their ability to understand Meta’s systems and data.

In retrospect, she says, “doing ads way sooner” is the one thing she would change about her business journey.

The growth from paid marketing created a chain reaction. More orders required a warehouse or third-party logistics provider. More fulfillment capacity made it easier to handle larger wholesale orders. Delegating allowed Mayers to build beyond the limits of a one-person operation.

Bootstrapping a sellable business

Slate’s financial model remained simple: selling swimwear directly to consumers and through wholesale partners. Mayers says 92% of the business came from direct-to-consumer sales and 8% from wholesale.

More notably, she never raised outside capital. Instead, she reinvested what the company earned. This meant moving carefully with inventory and avoiding premature expansion into too many stock-keeping units. It also gave Mayers more ownership and flexibility when it came time to sell.

Over Slate’s final three years under her ownership, the company grew 36% year over year, she says. In July 2026, Mayers completed a seven-figure acquisition after listing the brand with an online brokerage shortly after Slate’s 10-year anniversary.

The decision to sell was not just financial. Mayers had long thought of Slate as her “baby,” but she also felt ready to pursue her original passion: contemporary womenswear. She wanted a buyer who would understand the business, value its identity and maintain the relationships she had built.

She found that in a buyer with a swim background, fashion knowledge and strong instincts for marketing and media. Mayers says the fit brought a sense of calm.

“It was like an inner peace,” she says.

Because Slate was organized, profitable and supported by contractors rather than full-time salaried employees, the acquisition moved quickly. Her lawyer, she says, described it as the fastest acquisition he had seen.

Plans to launch a new brand

Mayers is staying involved with Slate to support the transition, but she’s turning her attention to Knitte, a contemporary minimalist womenswear brand she plans to launch in spring 2027.

“Womenswear and clothing is where I think my creativity shines the most, because I’m able to create without bounds,” she says. “With swim, it’s been so incredible, but there’s only so much fit-wise you can do with swimwear because it all has to be tight and formed to your figure.”

Mayers is going to be playing with silhouettes and different materials and fabrics that she wasn’t able to do for so many years. “I’m extremely excited about that,” she says. 

Her advice for founders reflects the way she built Slate: Start with a genuine point of view, be resourceful and stay committed for the long haul.

“You have to have that passion that’s going to wake you up every morning,” Mayers says. “If you don’t have that, you’re just not going to get far.”


Source link

She Created a Swim Brand With Just $300, Sold It for 7 Figures Read More »

Raising Money Isn’t the Hard Part. Here’s What Founders Get Wrong After the Check Clears.

Raising Money Isn’t the Hard Part. Here’s What Founders Get Wrong After the Check Clears.


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Funding doesn’t guarantee progress. Cash raises the stakes of every decision, and founders who go quiet after a raise lose the support that could help them use it well.
  • Build guidance into your routine. Choose investors you can work with, and schedule regular check-ins before you need them so honest conversations happen early, not in a crisis.

A founder I backed once raised capital, set the vision and then disappeared.

There were no updates, no emails and no sign of what was happening inside the company. Months went by. Then one day, I came across his LinkedIn profile and saw he had started a new job. That was how I learned the company I’d invested in was effectively over. No note. No explanation. No reflection on what went wrong.

That experience stuck with me because the problem had nothing to do with money. The company had funding. What it lacked was communication, accountability and a willingness to lean on the people who were there to help. A short monthly update or one honest conversation could have changed the outcome, or at least preserved trust.

I’ve seen versions of this play out more than once. Founders chase capital hard, then go quiet the moment they get it. They treat investors as a transaction instead of a resource, and that’s where things start to break.

Cash solves one problem at a time

Capital helps you hire, test, market and extend your runway. Those are real advantages, and every founder should respect them. But money can create a false sense of progress when it arrives before the company has built the habits to use it well.

I’ve watched founders celebrate a closed round as if the hardest part were behind them. In reality, the stakes rise the moment the money lands. Every decision carries more weight. Hiring mistakes cost more. Strategic drift burns more time. Silence creates more confusion. Cash gives you the ability to act. It doesn’t tell you what the right action is.

Guidance shapes how decisions get made

Every founder faces moments when the next step feels unclear. Do you double down on your current strategy or change course? Hire ahead of revenue or wait? Prioritize growth or efficiency?

These decisions rarely come with perfect data, and that’s where experienced guidance matters. The right investor or mentor helps you think through tradeoffs, pressure-test your assumptions and focus your energy where it actually moves the business forward. There’s also a difference between criticism and coaching. Anyone can point out what’s wrong. Far fewer people can help you fix it in a way that builds confidence and momentum. Founders need people who can turn problems into next steps.

I think of it like working with a personal trainer. One trainer tells you you’re out of shape. Another shows you what to do next, how often to do it and how to measure progress. The first discourages you; the second builds discipline.

Every founder needs someone to call

Building a company can be isolating. Founders are expected to project confidence even when things feel uncertain behind the scenes, and that gap between appearance and reality is where mistakes tend to grow.

The strongest founders I work with make room for honest conversations. They have people they can call when something breaks, a deal falls through or they need a second opinion. That might be an investor, an advisor or a mentor who has been through something similar.

Those conversations aren’t about having someone else run the company. They’re about gaining clarity faster. Sometimes a short discussion is all it takes to reframe a problem and find the next move. Without that outlet, founders often get stuck in their own heads. They delay decisions, overcorrect or avoid issues that need immediate attention.

Choose investors you can actually work with

Founders spend a lot of time optimizing for valuation, brand name or check size. Those factors matter, but they skip a more practical question: When things get hard, is this someone you’d actually want to work through problems with?

The right investor relationship feels like a working partnership, built on trust, mutual respect and a shared interest in solving problems. You can be direct about what’s going wrong without worrying about how it will be perceived.

I’ve worked with founders who stay engaged, send clear updates and ask for help when they need it. Those are the founders I naturally want to support more. Their communication shows they care about the business and the relationship, and it makes it easier for me to offer useful input because I have context.

I’ve also seen founders disappear after funding. They skip updates, avoid conversations and resurface only when they need something. That pattern erodes trust quickly and limits how much any investor can help.

Set a rhythm for guidance early

One simple habit can make a big difference: Schedule recurring time with your key investors or advisors before you think you need it. A standing monthly or biweekly check-in creates consistency. It gives you a natural place to share updates, ask questions and think through decisions, and it removes the awkwardness of reaching out only when something goes wrong.

These conversations don’t need to be long or formal. What matters is that they happen consistently. Over time, they build a track record of communication and a deeper understanding of the business. Guidance works best as part of the process, not as an emergency response.

Turn capital into progress

Cash is a tool. It extends your runway and expands your options. What determines success is how you use that time and those options. Guidance helps you focus, avoid preventable mistakes and stay accountable when momentum slows. Most importantly, it keeps you moving in the right direction when the path ahead is unclear.

If you’re building a company, ask yourself: Do you have people around you who can challenge your thinking, support your decisions and help you through the hard moments? If the answer is no, that’s the gap to fix.

Key Takeaways

  • Funding doesn’t guarantee progress. Cash raises the stakes of every decision, and founders who go quiet after a raise lose the support that could help them use it well.
  • Build guidance into your routine. Choose investors you can work with, and schedule regular check-ins before you need them so honest conversations happen early, not in a crisis.

A founder I backed once raised capital, set the vision and then disappeared.

There were no updates, no emails and no sign of what was happening inside the company. Months went by. Then one day, I came across his LinkedIn profile and saw he had started a new job. That was how I learned the company I’d invested in was effectively over. No note. No explanation. No reflection on what went wrong.

That experience stuck with me because the problem had nothing to do with money. The company had funding. What it lacked was communication, accountability and a willingness to lean on the people who were there to help. A short monthly update or one honest conversation could have changed the outcome, or at least preserved trust.


Source link

Raising Money Isn’t the Hard Part. Here’s What Founders Get Wrong After the Check Clears. Read More »

Why It’s Time to Rethink Your Hiring Best Practices

Why It’s Time to Rethink Your Hiring Best Practices


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Degree cutoffs, resume rules and “safe’”career progression rarely predict on-the-job success. Most of these became “standard” simply because they were repeated long enough, and few leaders ever revisit them.
  • Resume structure, job titles and career history are conventions — signals of how someone packaged their experience, not proof of what they can do.
  • Employers should track who gets screened out and whether requirements actually predict performance, then remove criteria that don’t.

Ask any hiring manager what makes a “safe” candidate, and you’ll get the same list: steady career progression, no unexplained gaps, the right degree, a resume that follows the rules. Ask them why those things predict success, and the list gets a lot shorter. Most hiring practices grew out of habit, then got repeated until they felt like law.

That’s not automatically a problem — some rules earned their place. But few companies ever go back and check which ones still do. Careers are getting less linear. Hiring technology is getting more automated. That makes this question overdue: What evidence do we have that this practice helps us make a better hire?

Your hiring rules started as habit, not evidence

Resume conventions, degree cutoffs, years-of-experience minimums, expectations about steady upward movement — most of these became “standard” simply because they were repeated for long enough. Few leaders ever revisit them once they’re written into a job description or an applicant tracking system. In my experience, that’s rarely a deliberate choice; it’s inertia. Nobody owns the question of whether a rule still works, so nobody asks it.

Screening technology is no different. A 2026 audit of 14 mainstream AI models used to screen resumes found real movement: the oldest model, built in 2023, still favored “white-sounding” names in callbacks, while models built from 2024 onward showed no gap, or reversed it. Assumptions built into a process don’t disappear until someone tests them.

Presentation isn’t the same as ability

Presentation and ability aren’t the same thing, though hiring often treats them as interchangeable. Resume structure, job titles and career history are conventions — signals of how someone packaged their experience, not proof of what they can do.

Enhancv’s own research into resume photos found something similar: Candidates who included a photo, even in markets like the U.S. and Canada where the practice is discouraged, landed jobs at a higher rate, especially in senior, client-facing roles. The rule most recruiters treat as settled measured almost nothing about the candidate. It measured how comfortable the reviewer felt.

Unconventional candidates aren’t the risk you think

Career gaps, industry switches, non-linear progression and candidates applying below their previous seniority all tend to read as red flags. The evidence doesn’t back that up as consistently as hiring teams assume.

Research from the Burning Glass Institute and Harvard Business School found that employees hired without a degree into roles that previously required one had a two-year retention rate 10 percentage points higher than their degree-holding peers. The candidates who looked riskier on paper stayed longer in practice.

The screening process was never neutral

ATS filters and scoring rubrics get sold as neutral, but they’re not. They’re someone’s assumption, coded once and rarely revisited, applied to every resume that hits the pile. Add AI to that process, and the assumption gets automated at scale.

University of Washington researchers found that when an AI tool recommended candidates from a particular racial group, human reviewers followed that recommendation up to 90% of the time, even when they rated the AI’s suggestions as low-quality or unimportant. Nobody chose that outcome. The system did, and nobody was checking.

Policy changes rarely change who gets hired

Adopting a new policy and changing what happens in hiring are two different things. The same Burning Glass Institute research examined more than 11,000 roles at large firms that had removed degree requirements, then tracked roughly 65 million career histories to see if hiring behavior changed.

It mostly didn’t — fewer than one in 700 new hires in 2023 benefited from the reform. Some companies changed who they hired, but most just edited the job description. The only way to know which one your company is doing is to compare who you screen out against who performs once hired.

Recruiters need permission to push back

None of this sticks without hiring managers feeling authorized to say a requirement doesn’t make sense. NACE’s Job Outlook 2026 survey found 70% of employers now use skills-based hiring, up from 65% the year before, and GPA screening has dropped to 42% of employers from 73% in 2019. More than half of U.S. state governments have adopted similar policies. 

The shift is already underway. Most companies already have the technology and the templates. What’s missing is a recruiter with standing to say a requirement doesn’t hold up and a manager willing to back them.

Make your hiring criteria earn their keep

Treat hiring criteria the way you’d treat any other business process — something you check on a regular schedule rather than defend on instinct. Look at who your filters reject, and ask whether you’re protecting hire quality or protecting yourself from a bad hire. Follow the people who made it through far enough to see whether the requirement predicted anything about how they performed. When it didn’t, retire it.

Employers already doing this lean on behavior-based interviews, competency-based job descriptions, targeted resume scans and structured interview rubrics, aimed at replacing untested criteria with ones that have been checked.

A final word

I’ve spent years helping candidates get past exactly these filters, and I keep seeing the same pattern. Most hiring criteria were never built to find the best person. They were built to give whoever’s hiring an easy answer if someone asks why later.

Treating those two jobs as the same is how companies lose candidates who would have worked out fine. The leaders willing to ask what a requirement predicts, and drop the ones that fail, end up hiring the people their competitors screened out for reasons that had nothing to do with ability.

Key Takeaways

  • Degree cutoffs, resume rules and “safe’”career progression rarely predict on-the-job success. Most of these became “standard” simply because they were repeated long enough, and few leaders ever revisit them.
  • Resume structure, job titles and career history are conventions — signals of how someone packaged their experience, not proof of what they can do.
  • Employers should track who gets screened out and whether requirements actually predict performance, then remove criteria that don’t.

Ask any hiring manager what makes a “safe” candidate, and you’ll get the same list: steady career progression, no unexplained gaps, the right degree, a resume that follows the rules. Ask them why those things predict success, and the list gets a lot shorter. Most hiring practices grew out of habit, then got repeated until they felt like law.

That’s not automatically a problem — some rules earned their place. But few companies ever go back and check which ones still do. Careers are getting less linear. Hiring technology is getting more automated. That makes this question overdue: What evidence do we have that this practice helps us make a better hire?

Your hiring rules started as habit, not evidence

Resume conventions, degree cutoffs, years-of-experience minimums, expectations about steady upward movement — most of these became “standard” simply because they were repeated for long enough. Few leaders ever revisit them once they’re written into a job description or an applicant tracking system. In my experience, that’s rarely a deliberate choice; it’s inertia. Nobody owns the question of whether a rule still works, so nobody asks it.


Source link

Why It’s Time to Rethink Your Hiring Best Practices Read More »

Your Customer Experience Starts Before the First Sale

Your Customer Experience Starts Before the First Sale


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Having a put-together, clean, organized brick-and-mortar location and a user-friendly website are both paramount to the customer journey.
  • When there’s a problem with a product or a customer service experience, unpack the entire situation or product life cycle and uncover where friction could be hiding rather than assuming where it exists.
  • Businesses can create a seamless customer experience in multiple ways. Sometimes it’s through culturally relevant campaigns that resonate with customers in a fresh way, and other times, it’s through amplifying the world-class, repeatable customer service that earns recognition and trust.

In small business, every customer interaction is a marketing opportunity. While attracting new customers is essential, long-term growth emerges from the experiences that keep people coming back.

From strong first impressions and seamless service to operational excellence and lasting loyalty, small moments that shape the customer journey can become your greatest competitive advantage. Read on, small business owners, for strategies to strengthen your customer experience and turn awareness into preference.

Exploring the rise of ‘micro-expectations’

Before you can even think about the customer experience, consider your business “front door” of sorts. Whether your business offers a brick-and-mortar location or connects to customers in virtual spaces, first impressions are everything, no matter if they happen in the physical environment or online.

For a storefront, for instance, simple things like dirty windows, broken fixtures or wilting plants may seem insignificant in the broader scheme of things. But they immediately suggest to prospective customers that their welcome is an afterthought. In the digital world, websites that are difficult to navigate for customer service or “about us” information pose a similar problem. Experiences that were once “nice-to-haves” have migrated to something much bigger: the baseline of the customer experience.

Any brand space needs dedicated attention from you and your team to send the right signals to your prospective and current customers from the start. Customers expect personalized experiences and speed from all businesses now, regardless of size. In fact, McKinsey reports that 80% of consumers expect personalized interactions, and 71% get frustrated if they don’t receive them. That personalization polish can start with your front door signaling in both what customers see and how they’re greeted. The moment a customer walks through your door or lands on your website, they’re already forming opinions about whether you value their time and business.

Identifying friction

Even the most resilient businesses can experience setbacks when misfires happen. These missteps are often small moments rather than dramatic situations, where a customer’s experience stumbles due to unclear processes, slow responses, repeat information or gatekept access to real people when the situation requires it. The key here is to unpack the entire experience or product life cycle and uncover where friction could be hiding rather than assuming where it exists.

Consider common friction points: A customer places an order but receives no tracking number or confirmation email, leaving them wondering if their transaction went through. A returning customer calls your business and has to repeat their account information to multiple employees because there is a lack of information-sharing across your team. Your FAQ page answers generic questions but not the common problem a customer could experience. A customer service line puts them on hold indefinitely during your busiest hours. These small moments compound, and research finds that 92% of customers will abandon a company after negative experiences like these.

The transactions between you and your customer could be flawless, but lack of a confirmation email could result in a missed shipment or back-end organizational issue. The same goes for internal departments. If your teams fail to receive an important announcement about a change to your service offerings, your customers, partners and stakeholders may experience misaligned messaging in simple interactions.

Providing end-to-end communication eliminates friction. When you establish processes and ways of working that share critical information between your teams, customers and other stakeholders, you create operational excellence built on connection. Start by documenting your processes — how orders flow, how customer information is tracked, how issues are escalated. When a process only exists in your head, you become the bottleneck. When it’s written down, anyone can follow it, and your customer is on the receiving end of a quality workflow.

Turning operational excellence in your marketing advantage

Seamless experiences warrant positive attention, and efficient operations are the foundation. When processes are seamless — when customers know what to expect, when your team can solve problems, when clarity removes friction — something shifts. Customers feel valued. That earned trust comes from predictability, clarity and empowerment, all of which compounds into loyalty.

In practice, businesses approach this in multiple ways. Sometimes it’s through culturally relevant campaigns that resonate with customers in a fresh way. One example is our recent introduction of Blu, our first-ever brand character, whose friendly, helpful and uplifting personality brings to life the personalized service, local expertise and breadth of resources that The UPS Store franchisees provide to small business owners in their communities. Other times, it’s amplifying the world-class, repeatable customer service that earns recognition and trust.

What remains constant across both: Service speaks for itself. When your operations are solid, you can afford to take bigger risks because you have confidence in flawless delivery.

For local business owners especially, this is an advantage. Many customers think of “their” local business as exactly that — theirs — because they’ve experienced consistent, reliable service from people they know. This investment in operational excellence creates a foundation that allows them to take creative risks and stay top of mind with customers.

Building loyalty through consistency, reliability and memorable service

Customer trust relies on accountability, consistency and memorable moments. Consistency means delivering the same quality and experience every time, whether it’s your busiest day or your slowest. Reliability means owning your brand commitments even when it requires extra hours and difficult conversations to ensure every touch point meets expectations.  

Memorable service goes deeper: from personalization, like remembering a customer’s name or preferences, to serving as a proactive problem-solver, to small gestures that show appreciation like a handwritten note. Meaningful wins create authentic connections that are often more valuable than grand gestures or expensive rewards.

That’s what loyalty looks like: the quiet confidence that comes from being consistently, reliably cared for in small moments throughout the customer journey itself. They’re what transforms awareness into preference, and preference into the kind of lasting loyalty that drives real growth.

Key Takeaways

  • Having a put-together, clean, organized brick-and-mortar location and a user-friendly website are both paramount to the customer journey.
  • When there’s a problem with a product or a customer service experience, unpack the entire situation or product life cycle and uncover where friction could be hiding rather than assuming where it exists.
  • Businesses can create a seamless customer experience in multiple ways. Sometimes it’s through culturally relevant campaigns that resonate with customers in a fresh way, and other times, it’s through amplifying the world-class, repeatable customer service that earns recognition and trust.

In small business, every customer interaction is a marketing opportunity. While attracting new customers is essential, long-term growth emerges from the experiences that keep people coming back.

From strong first impressions and seamless service to operational excellence and lasting loyalty, small moments that shape the customer journey can become your greatest competitive advantage. Read on, small business owners, for strategies to strengthen your customer experience and turn awareness into preference.

Exploring the rise of ‘micro-expectations’

Before you can even think about the customer experience, consider your business “front door” of sorts. Whether your business offers a brick-and-mortar location or connects to customers in virtual spaces, first impressions are everything, no matter if they happen in the physical environment or online.


Source link

Your Customer Experience Starts Before the First Sale Read More »

5 Startup Rules Worth Breaking, and How to Know When

5 Startup Rules Worth Breaking, and How to Know When


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Startup advice is built on someone else’s context. Rules like “raise as much as you can” or “move fast and break things” worked in specific situations and may not fit yours.
  • Question advice before you follow it. Ask why it exists and whether those conditions apply to your business, and seek out people who have faced situations like yours.

Every founder gets advice, and most of it comes with conviction. Find a clear market gap. Raise as much as you can. Get a technical co-founder. Much of it is useful, but very little of it comes with the context that made it true in the first place.

I learned this firsthand while building a company in real estate technology. When we were raising our Series A, an investor told us the market was too competitive and already had too many players. Standard advice for early-stage startups is to find an open lane before going in. That advice made sense in the situations the investor had seen succeed. It didn’t make sense for ours.

Real estate tech was crowded, but it was crowded with mediocre software. There was no clear winner, which meant there was still room to win.

We focused on a segment most people had written off as too small, the top 1% of agents, and built premium software and service for them first. We bootstrapped to $1 million in revenue before raising anything. By the time we took investor money, we understood our customers well enough to know which conventional wisdom applied to us and which didn’t.

That distinction, between advice that’s generally true and advice that’s true for your situation, is something I come back to whenever I talk with founders, whatever their industry.

Why startup advice turns into rules

Most startup advice comes from pattern matching. Someone succeeded doing X, so X becomes gospel. The advice travels faster than the context behind it. The problem isn’t that the advice is wrong; it’s that it stops being advice and becomes instruction.

Wisdom specific to one situation gets turned into a rule everyone follows, whether it fits or not. We chose our own route, knowing we didn’t fit the pattern the advice was designed for. Here are five startup “rules” we broke.

1. Raise at the highest valuation you can get

The conventional wisdom is to take the best terms available. There’s logic to that, but raising at 200 times revenue means spending years trying to grow into numbers that were never grounded in your actual business.

We raised at valuations that let us keep the right partners, limit dilution and run a company that worked. Some companies in our market raised too much at valuations that were too high, and they’re now stuck because their last round set a bar that may take a decade to clear. We didn’t want that to be us.

2. Raise as much as you can

This is a related trap. The argument is that more capital means more runway and more options. In many cases, it actually produces waste and a company that never has to make the hard choices that force you to understand what matters. We raised what we needed to reach the next milestone, plus a buffer, and that discipline paid off.

3. You need a technical co-founder

I’m a solo founder who hired great engineers instead. For a long time, investors flagged that as a structural weakness. I don’t think it is, and with what AI makes possible now, the argument has only gotten weaker. You do need strong technical talent, but you can hire for it.

4. Move fast and break things

This piece of startup doctrine has aged poorly faster than almost any other. With AI coding tools, anyone can ship software quickly, so the supply of mediocre products is now essentially unlimited. The only way to win is to build things that are actually great: well-designed, well-tested and genuinely useful.

That’s especially true in high-trust industries. In real estate, customers are making the largest financial decisions of their lives, so the tolerance for broken things was never high. Trust takes years to build and can be lost quickly. Moving carefully where it matters isn’t a concession. It’s a product strategy.

5. Disrupt from the low end

The classic playbook says to enter at the bottom of the market, undercut on price and work your way up. We started at the top and built from there. Those early customers gave us deep product knowledge, a strong reputation and references that eventually carried us further into the market than a low-end entry would have.

None of this was the “right” approach according to startup playbooks. It worked because we understood our customers and market well enough to know where the standard rules applied and where they didn’t.

The better question to ask

When you’re early in building a company, you’re surrounded by people with strong opinions about what you should do: investors, advisors and other founders. Much of that advice is offered in good faith. But a lot of it is based on situations that look similar to yours on the surface and are actually quite different. Listening is smart. Accepting it without question, as if context didn’t matter, is the mistake.

A better habit is to treat advice as a prompt for questions rather than a directive. Why does this advice exist? What conditions made it true? Do those conditions apply to my business, my market and my customers? Sometimes they will, and sometimes they won’t. The answer is almost always more valuable than the advice itself.

My recommendation: Find people who have done the specific thing you’re trying to do, in conditions that resemble yours. Ask them why they made their choices, not just what those choices were. The context is the useful part. Without it, you’re following someone else’s map through terrain that may look nothing like theirs.

Key Takeaways

  • Startup advice is built on someone else’s context. Rules like “raise as much as you can” or “move fast and break things” worked in specific situations and may not fit yours.
  • Question advice before you follow it. Ask why it exists and whether those conditions apply to your business, and seek out people who have faced situations like yours.

Every founder gets advice, and most of it comes with conviction. Find a clear market gap. Raise as much as you can. Get a technical co-founder. Much of it is useful, but very little of it comes with the context that made it true in the first place.

I learned this firsthand while building a company in real estate technology. When we were raising our Series A, an investor told us the market was too competitive and already had too many players. Standard advice for early-stage startups is to find an open lane before going in. That advice made sense in the situations the investor had seen succeed. It didn’t make sense for ours.

Real estate tech was crowded, but it was crowded with mediocre software. There was no clear winner, which meant there was still room to win.


Source link

5 Startup Rules Worth Breaking, and How to Know When Read More »

The Biggest ChatGPT Update Yet Gives Entrepreneurs 7 Ways to Grow Fast

The Biggest ChatGPT Update Yet Gives Entrepreneurs 7 Ways to Grow Fast


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • See how a solo founder can hand recurring research, content and follow-up to a dot, OpenAI’s new always-on AI agent inside ChatGPT, while keeping the decisions that matter.
  • Talk a job through with your dot on a voice call, then let it keep working after you hang up.
  • Explore seven practical business uses for these agents, from spotting missed invoices to planning your day and reviewing marketing results.

OpenAI’s dots, the always-on AI agents now built into ChatGPT, arrive just as many solo founders are hitting the limits of chat-based AI. You may already use ChatGPT to draft an email, summarize a meeting or brainstorm a launch. Yet the research, follow-up and checking still land back on your desk. Adding another tool does little if you remain the person holding every thread.

The video above shows what changes when an AI agent has an ongoing assignment, relevant context and clear limits. With its own cloud computer, connected apps and saved instructions, a dot can notice relevant changes and keep authorized work moving between conversations. You can even call your dot, talk through the assignment and let it continue after you hang up. The interesting question is which job deserves that kind of attention first.

Start small, but start with a job. In Chapter 4 of my book, The Wolf Is at The Door, I ask readers to identify cognitive tasks they could automate to ease their workload without putting their work or business at risk. That question is a useful filter for dots: find a recurring task that consumes your attention, define a good result and decide what still requires your judgment.

The gap between trying AI and relying on it is real. In QuickBooks’ July 2026 small-business survey, only 18% of businesses using AI said it was core to their operations. For the rest, the challenge may be moving from occasional prompts to a repeatable process that fits the business.

A dot could compare competitor offers and surface customer questions before you build a new product. It could turn a video transcript into social drafts, identify launch materials affected by a changed date, or prepare a revised sales proposal while flagging the questions you have not answered. It could compare completed work with billing records to catch a possible missed invoice. These are assignments you can inspect, correct and improve, not one-off requests that disappear into a chat.

Researching an opportunity is not permission to pursue it. Drafting a proposal is not approval to promise its terms. In the video, I walk through seven business uses, including daily planning and a weekly marketing review, and show where your instructions, evidence checks and approvals belong. The point is to take work off your plate while keeping the decisions that matter in your hands.

Pick one recurring responsibility, give your dot the information it needs and ask for a result you can verify. That first assignment will teach you more than collecting another list of AI tools.

For a limited time, download the free AI Marketing Team Setup, which includes a team map, role instructions and a starter skill to help you build your first marketing agent. You’ll also get a free chapter of my book, The Wolf Is at The Door: How to Survive and Thrive in an AI-Driven World, to help you navigate what comes next as AI changes how we work and build businesses.

Key Takeaways

  • See how a solo founder can hand recurring research, content and follow-up to a dot, OpenAI’s new always-on AI agent inside ChatGPT, while keeping the decisions that matter.
  • Talk a job through with your dot on a voice call, then let it keep working after you hang up.
  • Explore seven practical business uses for these agents, from spotting missed invoices to planning your day and reviewing marketing results.

OpenAI’s dots, the always-on AI agents now built into ChatGPT, arrive just as many solo founders are hitting the limits of chat-based AI. You may already use ChatGPT to draft an email, summarize a meeting or brainstorm a launch. Yet the research, follow-up and checking still land back on your desk. Adding another tool does little if you remain the person holding every thread.

The video above shows what changes when an AI agent has an ongoing assignment, relevant context and clear limits. With its own cloud computer, connected apps and saved instructions, a dot can notice relevant changes and keep authorized work moving between conversations. You can even call your dot, talk through the assignment and let it continue after you hang up. The interesting question is which job deserves that kind of attention first.

Start small, but start with a job. In Chapter 4 of my book, The Wolf Is at The Door, I ask readers to identify cognitive tasks they could automate to ease their workload without putting their work or business at risk. That question is a useful filter for dots: find a recurring task that consumes your attention, define a good result and decide what still requires your judgment.


Source link

The Biggest ChatGPT Update Yet Gives Entrepreneurs 7 Ways to Grow Fast Read More »