Young Americans Skip College for No-Degree Jobs Paying 0K+

Young Americans Skip College for No-Degree Jobs Paying $100K+


Key Takeaways

  • New college graduates are struggling in the worst entry-level job market in years.
  • Here are the no-degree-required roles that pay the most, per a new study from NetCredit.

For some young people in the U.S., higher education is losing its luster.

New college graduates are currently facing the worst entry-level job market since the pandemic, per The Guardian

What’s more, the average tuition for both public and private four-year colleges has essentially doubled over the past 30 years when adjusted for inflation, NPR reported last year

Undergraduate enrollment was 15% lower in fall 2021 than in fall 2010, with 42% of the dropoff taking place amid the pandemic, according to the National Center for Education Statistics.

High school graduates who plan to join the workforce right away might wonder which no-degree-required roles pay the most.

Online lender NetCredit’s new study, which examined occupations that don’t require a degree (per the BLS Occupational Handbook) and the average yearly salary for each role, reveals the highest-paying job options in the U.S. 

The top seven no-degree roles boast national average salaries ranging from $102,482 (gambling managers) to $122,824 (nuclear power reactor operators). 

Transportation, storage and distribution managers, with an average wage of $116,022, and police sergeants and captains, with an average wage of $110,989, rounded out the top three best-paying occupations that don’t require a college degree. 

Read on to see all of NetCredit’s no-degree, six-figure jobs, along with 18 others that offer national average wages starting at about $85,000:

Image Credit: NetCredit

Key Takeaways

  • New college graduates are struggling in the worst entry-level job market in years.
  • Here are the no-degree-required roles that pay the most, per a new study from NetCredit.

For some young people in the U.S., higher education is losing its luster.

New college graduates are currently facing the worst entry-level job market since the pandemic, per The Guardian

What’s more, the average tuition for both public and private four-year colleges has essentially doubled over the past 30 years when adjusted for inflation, NPR reported last year

Undergraduate enrollment was 15% lower in fall 2021 than in fall 2010, with 42% of the dropoff taking place amid the pandemic, according to the National Center for Education Statistics.

High school graduates who plan to join the workforce right away might wonder which no-degree-required roles pay the most.

Online lender NetCredit’s new study, which examined occupations that don’t require a degree (per the BLS Occupational Handbook) and the average yearly salary for each role, reveals the highest-paying job options in the U.S. 

The top seven no-degree roles boast national average salaries ranging from $102,482 (gambling managers) to $122,824 (nuclear power reactor operators). 

Transportation, storage and distribution managers, with an average wage of $116,022, and police sergeants and captains, with an average wage of $110,989, rounded out the top three best-paying occupations that don’t require a college degree. 

Read on to see all of NetCredit’s no-degree, six-figure jobs, along with 18 others that offer national average wages starting at about $85,000:

Image Credit: NetCredit


Source link

Young Americans Skip College for No-Degree Jobs Paying $100K+ Read More »

They Built a 3 Million Franchise From a Single Location

They Built a $103 Million Franchise From a Single Location


Key Takeaways

  • Weed Man is a lawn care franchise that generates around $450 million in total annual revenue.
  • Terry and Andy Kurth, a father-son team, play a significant role in generating revenue for the franchise.
  • Terry is the founder of Epic3, Weed Man’s largest multi-unit ownership group, which generated $103 million in sales last year.

Terry Kurth, 77, says that choosing the right life partner is the most important decision an individual can make — and he knows the truth of this statement firsthand. Nearly 50 years ago, his wife was in labor. She was in the hospital lying on her side with severe back pain because their daughter, Amanda, was turned 180 degrees in the womb.

Terry was there for his wife — but he also didn’t stop working. 

“I had one hand on the small of her back to relieve pain and the other on the phone calling prospects to sell lawn care,” Terry tells Entrepreneur in a new interview. “She didn’t complain because she knew we were about to have another mouth to feed, and failure wasn’t an option.”

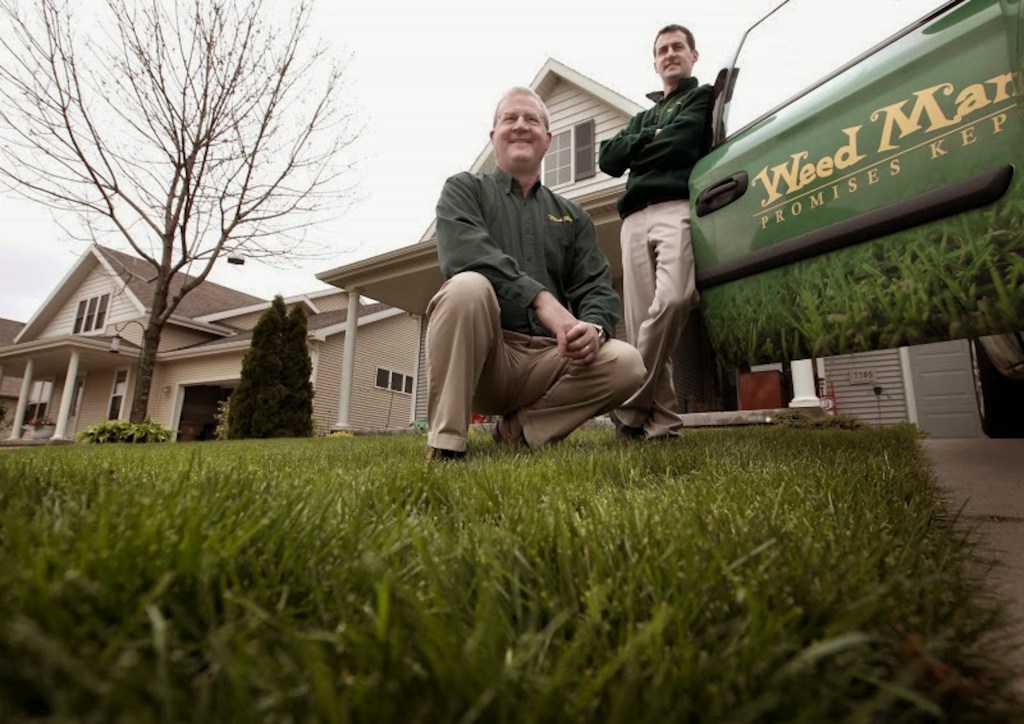
Terry entered the Weed Man system in 2000 after exiting his own lawn care ventures and searching for his next chapter. He quickly saw an opportunity to expand the Canadian brand in the U.S. and founded Epic3, which would become Weed Man’s largest multi-unit ownership group. Starting with a single territory in Madison, Wisconsin, Terry steadily scaled the operation into a nationwide footprint.

Andy Kurth’s entry into the business was far less strategic. As Terry’s son, he joined while in college simply to earn extra cash, working in sales and as a lawn care technician. But what began as a temporary gig evolved into a long-term career. Over time, Andy took on increasing responsibility, eventually rising to become president and CEO of Epic3 and leading the continued expansion of the business his father helped build.

The following interview with Terry and Andy has been lightly edited for clarity and concision.

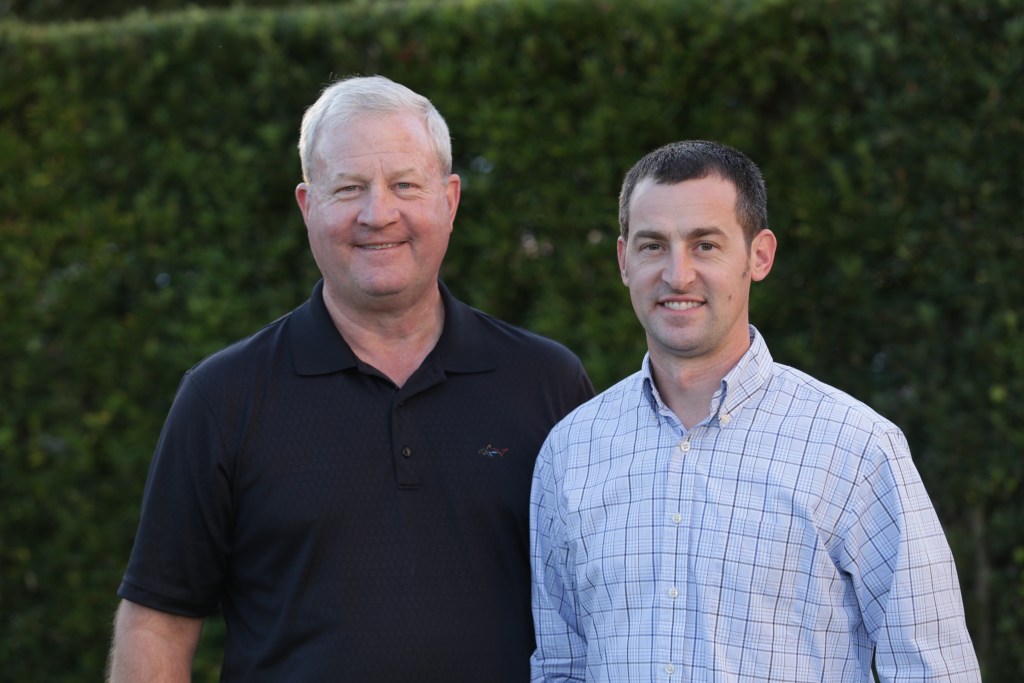
Terry (left) and Andy Kurth. Credit: Weed Man

Early days

How did you end up in lawn care and franchising?
Terry: I was going to be an engineer and went to the University of Wisconsin, graduating in 1975. While I was there, I started working at a golf course and fell in love with being outside and working with turf.

I ended up getting a degree in agronomy, which is essentially plant science, and became a golf course superintendent right out of college. Later, I went to work for the Scotts Company in its professional turf division and traveled around the country giving educational seminars to golf course superintendents, landscape contractors and early lawn care operators.

Eventually, I came into contact with a company called Barefoot Grass, became one of its first franchisees in 1978, built that up and ultimately sold when Barefoot Grass was acquired by TruGreen. It ended well, and I found myself gainfully unemployed in my mid‑40s with the proceeds from that sale.

What did you do after exiting Barefoot Grass?
Terry: After Barefoot Grass was sold and I completed that chapter, I became past president of what was then the Professional Lawn Care Association of America (PLCAA), which gave me a strong network of operators across the country. Weed Man is headquartered in Toronto, and through that network, I got to know their leadership. They flew me up; I met the franchisor and a Canadian franchisee who had acquired the master rights to the United States, and together we came up with the idea of creating regional sub‑franchisors. My region included Minnesota, Wisconsin, Illinois, North Dakota and South Dakota. I sold franchises there, kept the largest share of the royalties, and passed the remainder up to the master group in Toronto.

How did you transition back into operating a lawn care franchise yourself?
Terry: When I sold to TruGreen, I had a three‑year non‑compete that restricted me from operating in the cities where I had locations — places like Madison, Appleton, Green Bay, Lexington and Peoria. Once that non‑compete expired in January 2001, I re‑entered the business as a Weed Man franchisee. I started the Madison operation with one of my wife’s nephews, and when he chose to pursue something else, we hired a manager.

That’s around the time Andy, who had been helping me sell during college, stepped in and ultimately became the manager in Madison. From there, Andy and I began working closely together, growing the business organically into new markets and then merging additional markets into our holding company over time. Our first billing year in Madison in 2001 was about $110,000 in revenue; today, we’re around $103 million, so it’s been quite a run over roughly twenty‑five years.

Terry and Andy Kurth, Credit: Weed Man

Secrets to scaling Weed Man

What are your secrets to growth? How do you scale from $110,000 to $103 million?
Terry: A big inflection point was when I met Roger Mongeon, who held the U.S. rights to Weed Man and is one of the smartest people I’ve ever met, both in business and in general. He’s a former chemical engineer, and we developed a deep mutual trust and respect. He showed me the systems Weed Man had built, and I quickly realized that to handle significant growth, you must have robust systems. People talk about breaking through glass ceilings in their careers; growth in a business is similar — you can’t get to the next level without systems that ensure nothing falls through the cracks as you add people and locations. You also need a relentless attitude — failure can’t be an option.

Take me back 26 years. What did that very first Weed Man location look like day to day, and what convinced you both that it was worth betting your careers on?
Andy: From my perspective as a college kid at the time, I wasn’t initially thinking of a long‑term career. I’d show up on Saturdays to an almost vacant shell of an office and be the only person there selling lawn care. We used old‑school telemarketing to generate leads, and my cousin, who had started the business with my dad, was out treating lawns nearly by himself.

That first year, revenue was around $100,000, so there simply weren’t many people involved. Each year, as we added revenue, we’d bring in another technician, then another and eventually a senior technician, gradually building out the team.

Solving mistakes

Andy, can you share an instance when you made a mistake running the company and how you fixed it?
Andy: Early in my leadership career, I was wearing 10 hats and constantly chasing people around. When we first introduced door‑knocking for lead generation, I found myself running after supervisors every morning because they kept forgetting door hangers. One day, I realized how unsustainable that was. Instead of continuing to chase people, I focused on developing better systems — start‑of‑day procedures, checklists and clearer role ownership — so that team members owned their responsibilities. That experience was a catalyst for me to shift from being a task‑oriented manager to a leader focused on developing other leaders.

Hand-raising culture

Andy, you have described the organization as having a hand-raising culture. What does that mean?
Andy: Hand‑raising culture describes leaders inside our organization who literally raise their hands to take on new challenges and uproot their lives. For example, a gentleman from Green Bay volunteered to move to Austin to start that branch, and another teammate from Madison, who had also worked in Milwaukee, raised his hand to move to Denver.

Those markets are now among our top performers — Denver, for example, grew from around $250,000 in first‑year revenue to over $8 million. We keep building stables of leaders who breathe our mission — people, opportunity, community — in that order. They buy into that mission and carry it into their branches and departments, which creates new opportunities in new areas and truly changes lives. Many people in our company have careers they never imagined, and they, in turn, pass that mindset to the people they lead.

Long-term vision

What are your plans for growth and succession?
Andy: We plan to keep doing what we do best: changing people’s lives for the better and building a culture where people want to advance that mission of people, opportunity, community. If our people are taking care of each other and building something they can call their own, we’ll be fine.

Terry: At the system level, Weed Man as a whole generates around $435 million to $450 million in annual revenue, and with Epic3 at around $103 million, we’re a significant contributor. The broader goal is to become a billion‑dollar company, and we want to help drive that by innovating and supporting other franchisees within the Weed Man family. Together, we intend to reach that billion‑dollar milestone while maintaining the culture and systems that got us here.

Key Takeaways

  • Weed Man is a lawn care franchise that generates around $450 million in total annual revenue.
  • Terry and Andy Kurth, a father-son team, play a significant role in generating revenue for the franchise.
  • Terry is the founder of Epic3, Weed Man’s largest multi-unit ownership group, which generated $103 million in sales last year.

Terry Kurth, 77, says that choosing the right life partner is the most important decision an individual can make — and he knows the truth of this statement firsthand. Nearly 50 years ago, his wife was in labor. She was in the hospital lying on her side with severe back pain because their daughter, Amanda, was turned 180 degrees in the womb.

Terry was there for his wife — but he also didn’t stop working. 

“I had one hand on the small of her back to relieve pain and the other on the phone calling prospects to sell lawn care,” Terry tells Entrepreneur in a new interview. “She didn’t complain because she knew we were about to have another mouth to feed, and failure wasn’t an option.”


Source link

They Built a $103 Million Franchise From a Single Location Read More »

The Pace of Work Has Outrun Your Capacity. Here’s What to Do.

The Pace of Work Has Outrun Your Capacity. Here’s What to Do.


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Overwhelm is a leadership challenge, not a personal weakness.u003cbru003e
  • You can’t control the pace of change, but you can control how you respond to it.u003cbru003e
  • Reduce mental load instead of just trying to work harder.

Talk to any founder, manager or entrepreneur right now, and you will hear the same word. Overwhelm. People are trying to keep up with a pace that never slows.

AI is reshaping industries before leaders can absorb the last change. Even the high performers who usually stay calm under pressure say they feel stretched thin. Leadership capacity is dropping at the exact moment when demands are rising. Many workplaces feel like they are running out of room to breathe.

Overwhelm is not a personal failure. It is a structural reality. Leaders are trying to make good decisions while the ground keeps shifting under them. Economic conditions change without warning. New tools appear faster than people can learn them. Policies and regulations move in ways that force teams to rethink plans they made only days earlier. Supply chains wobble and require constant recalibration. The volume of change is so high that even experienced leaders feel like they are running a race where the course keeps moving.

I kept thinking about this during marathon training. The breakthrough didn’t happen during a long run. It happened on a rest day. Training had a rhythm. Some days focused on endurance. Some days focused on speed. Some days focused on strength. And then there were planned days off, which were just as important as the work. That recovery is the missing piece in today’s workplace. Most leaders operate in environments that never pause and never reset. Overwhelm keeps building because there is no chance to regain capacity. We cannot slow the world down, but we can learn to move through it with steadiness. That is the work of endurance.

Why this matters now

Overwhelm is becoming the defining condition of modern work. The pace of change is now faster than the pace of human adaptation, and that gap is widening. AI is accelerating decisions, expectations and competitive pressure. Markets are shifting in weeks instead of quarters. Teams are being asked to absorb more information than their cognitive systems were designed to handle.

Leaders who do not adjust will see slower decision cycles, rising conflict and declining performance. The organizations that thrive will be the ones whose leaders build endurance skills that match the speed of the environment. This is not about surviving chaos. It is about learning to operate confidently inside it.

What overwhelm looks like for leaders today

The familiar challenges are still here. Work-life balance. Office politics. Managing personalities. Endless decisions. Constant context switching.

What is new is the speed and instability surrounding them. One colleague told me, “The strategy we launched on Monday doesn’t work by Wednesday.” Another said, “I’m not between a rock and a hard place. I’m in a rock tumbler.” These comments are not exaggerations. They are honest descriptions of what overwhelm feels like in real time.

Leaders need a training plan for a world that does not include rest days. Endurance comes from small, repeatable practices that help you stay steady under prolonged strain.

Below are five endurance skills that reduce overwhelm at the source.

1. Reduce cognitive load at the source

Most leaders try to manage overwhelm by working harder. Endurance leaders reduce the inputs that create overwhelm in the first place.

Practical moves:

  • Shrink the number of priorities in play at any moment.
  • Collapse decision pathways so teams know exactly how choices get made.
  • Remove optional meetings and optional reporting.
  • Standardize anything that repeats.

This is not time management. It is load management, which is the real antidote to overwhelm.

2. Shorten the distance between signal and action

Overwhelm grows when leaders sit in ambiguity. Endurance leaders shorten the time between noticing a problem and addressing it.

Practical moves:

  • When something feels off, act within twenty-four hours.
  • When a project drifts, reset expectations immediately.
  • When a team is confused, clarify the path the same day.

This prevents small issues from becoming system-wide strain.

3. Build a recovery rhythm into the workweek

Most leaders think recovery is a luxury. Endurance leaders treat it as infrastructure.

Practical moves:

  • Protect one meeting-free block every day.
  • Add a weekly capacity check with your team.
  • Use microbreaks to reset your cognitive system before it hits overload.

Recovery is capacity maintenance, not rest. It keeps overwhelm from compounding.

4. Practice emotional neutrality under pressure

Overwhelm spikes when leaders absorb the emotional intensity of the moment. Endurance leaders stay neutral long enough to choose a response.

Practical moves:

  • Notice your first reaction and delay it by sixty seconds.
  • Label the emotion without acting on it.
  • Respond only when your heart rate drops.

This is emotional regulation, which is the foundation of endurance.

5. Anchor every decision to purpose

Overwhelm grows when leaders lose sight of the destination. Endurance leaders use purpose as a filter.

Practical moves:

  • Ask whether the work moves you toward the mission before saying yes.
  • Remove tasks that do not serve the purpose.
  • Reconnect your team to the mission weekly.

Purpose is directional clarity. It cuts overwhelm in half.

The world is moving fast. You can still finish strong.

A world without enough rest breaks is not ideal. But it is the world we have. Leaders need endurance. Not the heroic kind. The practical kind. The kind built through small habits that help you stay steady in a world that keeps accelerating.

These practices will not slow the world down. They will help you move through it without losing yourself. And they will help you lead others who are feeling the same overwhelm you are.

Key Takeaways

  • Overwhelm is a leadership challenge, not a personal weakness.u003cbru003e
  • You can’t control the pace of change, but you can control how you respond to it.u003cbru003e
  • Reduce mental load instead of just trying to work harder.

Talk to any founder, manager or entrepreneur right now, and you will hear the same word. Overwhelm. People are trying to keep up with a pace that never slows.

AI is reshaping industries before leaders can absorb the last change. Even the high performers who usually stay calm under pressure say they feel stretched thin. Leadership capacity is dropping at the exact moment when demands are rising. Many workplaces feel like they are running out of room to breathe.

Overwhelm is not a personal failure. It is a structural reality. Leaders are trying to make good decisions while the ground keeps shifting under them. Economic conditions change without warning. New tools appear faster than people can learn them. Policies and regulations move in ways that force teams to rethink plans they made only days earlier. Supply chains wobble and require constant recalibration. The volume of change is so high that even experienced leaders feel like they are running a race where the course keeps moving.


Source link

The Pace of Work Has Outrun Your Capacity. Here’s What to Do. Read More »

Here’s What It Really Takes to Support Other Entrepreneurs

Here’s What It Really Takes to Support Other Entrepreneurs


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • When my brother and I created our roofing business, we discovered an opportunity to educate other members of the industry and provide resources to help them improve their services — a dealer network.
  • Establishing this dealer network helped us give back to our community and taught us valuable lessons about empowerment.
  • It taught us that setting people up for success means providing resources (like training), that valuable partnerships depend on mutual benefit and that oversight isn’t the same as surveillance.

Most founders who eventually find success remember their major accomplishments. But they also remember their close calls: the times when things almost fell apart because of knowledge gaps, missing resources, a lack of support or simple bad luck.

Most of us tell ourselves that if we’re ever in a position to set other entrepreneurs up for success, we’ll make sure they have the training, education and networking opportunities we didn’t have. But not every well-intentioned entrepreneur ends up with that chance.

When I set out to create Roof Maxx with my brother Todd, our main goal was to provide an alternative to roof replacement for homes with aging asphalt shingles. But along the way, we discovered a golden opportunity to educate members of the roofing industry and provide resources to help contractors across the country improve their services.

As former roofers who spent 15 years struggling to survive in the industry ourselves, that had personal value to us beyond what it achieved for the business. Here’s how the dealer network we established to scale our company also helped us give back to our community, and what it taught me about empowerment.

Setting people up for success is usually a resourcing issue

I will be the first person to tell you that culture and core values play an important role in mentorship. You want to create a supportive and productive environment that facilitates healthy growth. But all of that is just wishful thinking if you aren’t willing to put your money where your mouth is.

This can look different depending on how your company is structured. In a company where most of your employees are on salary, that might look like investing in paid training and upskilling opportunities or ensuring that department heads have the budget they need to comfortably and consistently hit KPIs so that they don’t experience widespread burnout and unsustainable turnover.

Roof Maxx isn’t built that way. Our dealership model means the roofers who carry our product are independent contractors who purchase it from us so they can sell restoration services to their customers. They’re not on our payroll, but we still have a responsibility to help them succeed because they’re our most effective brand ambassadors.

So for us, resourcing looks like investing in training and support. Roof Maxx Connect, our proprietary dealer management software, was expensive to develop and doesn’t generate a dollar of direct revenue. What it does do, however, is streamline the same tasks for our dealers that Todd and I found most grueling when we were roofers: handling leads, managing warranties, training with Roof Maxx University and more.

Dealers who have that kind of support are more efficient and provide more consistent service, which helps them sell our product and makes them more likely to keep purchasing it from us. As a former roofer who was once responsible for handling all those tasks independently and who almost went out of business, I see the impact every day.

Valuable partnerships depend on mutual benefit

Over the course of your career, you’ll probably meet at least a few businesspeople who think every deal needs to have a winner and a loser. I don’t just think this attitude is simplistic; I think it’s self-defeating.

This kind of win-lose bargaining strategy depends on securing concessions from others, which in practice means forcing them to settle for less. That may help you acquire short-term gains, but it is not a recipe for respectful and lasting partnerships. In my experience, people who think you’ve given them a raw deal tend to remember it, and they are rarely inclined to go the extra mile on your behalf.

Our dealers carry the Roof Maxx product, but they’re partners rather than subordinates. They don’t carry it because they have to; they choose to carry it because it allows them to offer genuine value to the homeowners they serve. In turn, we make a commitment to keep earning their business by working to ensure that our product remains competitive and effective. This is one of the primary differences between the kind of dealer model we rely on and a franchise.

Oversight is not the same as surveillance

As a roofer, Todd and I were personally involved at every level of our business. With Roof Maxx, we can’t afford to be.

Our dealership network currently extends across North America. Even with Roof Maxx Connect, it’s impossible to have total visibility into every single thing our dealers do — but more importantly, we don’t need to.

When you run a small business, handling everything yourself is a practical strategy for quality control. When you’re an eight-figure national brand, it’s a recipe for founder burnout. Moreover, forcing your dealers — or employees, if that’s how your company operates — to report their every move to you creates unnecessary operational obstacles for them and eventually causes friction in those relationships.

Thanks to our platform, we know how leads are being routed. We can see how invoices are fulfilled, check to see whether individual dealers have policies that comply with applicable laws and industry regulations, and view reports of completed jobs. We don’t need more than that, and to ask for it would put a stumbling block in the way of people we need as much as they need us.

At the end of the day, the best ways to empower an entrepreneur are by investing tangible resources in the tools they need, grounding your relationships on a foundation of mutual respect, and trusting their expertise. Every contractor I can give that to via Roof Maxx is someone I can trust to go out every day and improve the state of the industry for all of us.

Key Takeaways

  • When my brother and I created our roofing business, we discovered an opportunity to educate other members of the industry and provide resources to help them improve their services — a dealer network.
  • Establishing this dealer network helped us give back to our community and taught us valuable lessons about empowerment.
  • It taught us that setting people up for success means providing resources (like training), that valuable partnerships depend on mutual benefit and that oversight isn’t the same as surveillance.

Most founders who eventually find success remember their major accomplishments. But they also remember their close calls: the times when things almost fell apart because of knowledge gaps, missing resources, a lack of support or simple bad luck.

Most of us tell ourselves that if we’re ever in a position to set other entrepreneurs up for success, we’ll make sure they have the training, education and networking opportunities we didn’t have. But not every well-intentioned entrepreneur ends up with that chance.

When I set out to create Roof Maxx with my brother Todd, our main goal was to provide an alternative to roof replacement for homes with aging asphalt shingles. But along the way, we discovered a golden opportunity to educate members of the roofing industry and provide resources to help contractors across the country improve their services.


Source link

Here’s What It Really Takes to Support Other Entrepreneurs Read More »

Why the Silent Rules Nobody Made Are Killing Your Company

Why the Silent Rules Nobody Made Are Killing Your Company


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • If no one can name who authorized a rule or why it exists, it’s probably not a real policy — it’s a habit wearing a costume. Kill it.
  • Each extra approval or check costs a minute. Multiply across every employee, every week, and you’re paying salaries to wait, not produce.
  • Removing friction is cheaper than buying growth. Cut the red tape you never approved before adding another headcount.

Every successful business relies on policies and procedures. Policies and procedures create consistency, improve quality and allow organizations to move in a unified direction.

For this reason, most successful companies have policies and procedures manuals and other written policies. Without them, companies become chaotic and inconsistent as they grow. But there is an important distinction between systems that are intentionally designed and those that simply evolve over time.

The most damaging policies in a business are often the ones that were never actually created.

These can be called made-up rules — unwritten practices that slowly become accepted as official policy, even when no owner, executive, or person with authority ever approved them. They emerge quietly and gradually. An employee assumes something is required in every circumstance. Another employee observes that behavior and repeats it. Before long, an entire department believes a process is a mandatory policy when, in reality, it is not at all.

As organizations grow, these unofficial rules have a way of growing. Each one may seem insignificant on its own, but together they create a layer of legalism that slows decision-making, frustrates employees, delays customer service and quietly limits growth. It can also upset employees by creating an abundance of rigid rules that make the employees feel restricted. Unlike obvious problems such as declining sales or rising expenses, these self-made policies and procedures are rarely visible on a financial statement. Yet, their impact can be enormous.

Good intentions can create bad processes

One of the biggest challenges is that these rules often originate from good intentions. An employee wants to avoid making a mistake, so an extra rigid rule is added to prevent a situation from repeating itself. In other instances, someone encounters an unusual circumstance and begins treating that exception as the standard procedure. Over time, isolated events become permanent rules that harm, not help the company.

The problem is that businesses rarely struggle because of one unique situation. Instead, hundreds of small, unnecessary rules accumulate over months and years. Each additional email, approval, signature, or verification adds only a minute or two. Standing alone, that seems inconsequential. Collectively, however, those minutes become hours, days and eventually weeks of lost productivity, revenue or efficiency across an organization.

Imagine an employee who must wait for an internal confirmation before beginning work, even though all of the information needed to proceed is already available. Perhaps no owner, CEO or senior leader required this waiting period. It simply became “the way we’ve always done it.” If that delay happens dozens of times each week across multiple employees, the organization begins paying people to wait rather than to produce. Customers experience slower service, revenue decreases and management wonders why the business feels less efficient despite hiring more people.

Growth often brings more red tape

This scenario becomes even more pronounced in growing companies. Startups often move quickly because communication is simple and decisions are made by a small group of people. As headcount increases, however, there is a natural temptation for mid or lower level employees to add more approvals, more meetings, more documentation and more checkpoints. While some of these additions are necessary, many are simply reactions to isolated situations rather than thoughtful improvements to the business as a whole.

Over time, employees begin confusing caution with excellence. Instead of asking, “What is the best way to accomplish this?” they begin asking, “What is the safest way to avoid criticism?” Those are fundamentally different questions. The first encourages innovation and efficiency. The second often produces bureaucracy and red tape out of a desire for self-protection.

Perhaps the most dangerous aspect of made-up rules is that no one takes responsibility for them. Ask employees why they follow a particular procedure, and familiar responses usually emerge: “That’s just what we’ve always done,” or “I thought that was company policy.” Continue asking questions, and it frequently becomes clear that no one can identify when the rule started or who authorized it. The process has simply taken on a life of its own.

Challenge every unwritten process

Business owners should periodically examine their organizations with fresh eyes. Rather than asking employees whether they are following procedures, leaders should ask why those procedures exist in the first place and who authorized them. Every recurring process should have a clear purpose. If no one can explain why a particular step is necessary, it deserves careful scrutiny. In many cases, the unwritten rule should be disavowed and eliminated.

One effective exercise is asking managers to identify the biggest obstacles that slow their teams each day. Their answers are often revealing. Employees are rarely frustrated by hard work. They are frustrated by preventable delays — waiting for approvals, tracking down information, duplicating work or complying with procedures that no longer serve a meaningful purpose. These bottlenecks consume time without creating additional value for customers or employees.

It is also important to recognize that removing unnecessary rules does not mean lowering standards. High-performing organizations absolutely need accountability, quality control and thoughtful procedures. The goal is not to eliminate structure. The goal is to eliminate red tape that adds complexity without improving outcomes. Every policy should either reduce risk, improve quality, enhance the customer experience or increase efficiency. If it accomplishes none of those objectives, or it creates more problems than it helps, it is reasonable to question whether it should continue to exist.

Speed is a competitive advantage

Business leaders often focus tremendous energy on generating more revenue. They invest in advertising, marketing, recruiting and technology to accelerate growth. Yet, they sometimes overlook the operational drag occurring inside their own organizations. A company can spend millions of dollars attracting new customers while simultaneously slowing those customers’ experience through unnecessary internal processes. Removing friction is often one of the least expensive — and most profitable — ways to improve performance.

In today’s competitive environment, speed has become a meaningful differentiator. Customers have more choices than ever before, and they increasingly expect prompt responses, efficient service and straightforward interactions. Organizations that eliminate unnecessary delays position themselves to deliver a better experience without spending additional money on customer acquisition.

The best leaders understand that their role is not simply to create new policies. It is also to challenge existing assumptions. They recognize that every process should earn the right to continue existing—and should not be professed as policy without the company specifically authorizing it. As businesses evolve, procedures that once made perfect sense may become outdated. Failing to revisit them allows yesterday’s solutions to become tomorrow’s obstacles.

Eliminate the unnecessary rules

Every organization accumulates unwritten rules over time. Meetings become longer, approvals become more numerous and workflows become increasingly complicated. Left unchecked, these changes gradually reduce the agility that once fueled growth. Successful companies recognize that maintaining operational excellence requires periodic auditing and removal of these unwritten rules. Just as businesses routinely evaluate expenses, marketing efforts and financial performance, they should also evaluate the rules employees create or follow every day.

Sustainable growth is not achieved simply by working harder or hiring more people. It is achieved by creating an organization where talented employees can perform meaningful work without being slowed by unnecessary red tape. The companies that consistently outperform their competitors are often not those with the most elaborate systems. They are the ones disciplined enough to remove the systems that no longer serve a purpose.

Sometimes the greatest improvement a leader can make is not introducing another policy. It is eliminating unwritten rules that were never approved in the first place.

Key Takeaways

  • If no one can name who authorized a rule or why it exists, it’s probably not a real policy — it’s a habit wearing a costume. Kill it.
  • Each extra approval or check costs a minute. Multiply across every employee, every week, and you’re paying salaries to wait, not produce.
  • Removing friction is cheaper than buying growth. Cut the red tape you never approved before adding another headcount.

Every successful business relies on policies and procedures. Policies and procedures create consistency, improve quality and allow organizations to move in a unified direction.

For this reason, most successful companies have policies and procedures manuals and other written policies. Without them, companies become chaotic and inconsistent as they grow. But there is an important distinction between systems that are intentionally designed and those that simply evolve over time.

The most damaging policies in a business are often the ones that were never actually created.


Source link

Why the Silent Rules Nobody Made Are Killing Your Company Read More »

“The Lifestyle Looper” – America’s Fastest Growing Financial Trap

“The Lifestyle Looper” – America’s Fastest Growing Financial Trap


A financial planner named Ted Jenkin coined a term recently that I haven’t been able to stop thinking about.

Lifestyle loopers.

He uses it to describe a rapidly growing population of Americans between 30 and 50 who earn six figures and are somehow still going nowhere financially. Every raise gets absorbed. Every bonus evaporates. The income climbs. The wealth doesn’t.

I’ve watched this pattern play out for years through SparkRental and the Co-Investing Club. Smart, capable people with impressive salaries who, when you look at their actual financial picture, have very little to show for it. Not because they’re reckless. Because they’re caught in a loop they can’t quite see from the inside.

Lifestyle creep is not a new concept. The idea that spending rises with income is well documented. But what doesn’t get talked about enough is how completely natural and justified each individual step feels.

You get a promotion. You move to a better apartment because you can now afford it, and the old one was genuinely a bit cramped. Reasonable.

You get another raise. You lease a better car because your commute is long and you spend a lot of time in it. Reasonable.

Your income climbs further. You start eating out more, traveling more, upgrading more. Each decision is defensible on its own. Together, they form a structure where your expenses perfectly track your income, and the gap between what you earn and what you accumulate stays exactly the same.

The Goldman Sachs finding that about 40% of people earning over $500,000 a year report living paycheck to paycheck isn’t about irresponsibility. It’s about structure. When spending is the default and saving is the afterthought, income alone doesn’t determine financial progress. Behavior does.

Most financial advice treats this as a discipline problem. Track your spending. Cut the subscriptions. Stop eating out so much. Set a budget and stick to it.

The problem is that this advice fails consistently for high earners. Not because they lack discipline in other areas. Because budgeting and willpower are reactive systems. You’re fighting against the current every month, deciding in the moment whether to spend or save.

And in any given moment, spending usually wins. It’s immediate. It’s concrete. The benefit is right there. The cost of not saving is abstract and distant. Even people who know exactly what compound interest looks like in 20 years still spend the money today.

This is not a character flaw. It’s how human psychology works. We’re wired to prioritize the present. Every financial decision is a battle between the person you are now and the person you’ll be in 20 years, and the person you are now has a significant home-field advantage.

The only reliable solution to a behavioral problem is to remove the behavior from the equation entirely.

Pay yourself first is the phrase. Automate the savings. Move the money before you feel it. The version of this that actually works for high earners isn’t a monthly transfer to a savings account you can see and access. It’s routing capital into something that genuinely locks it away.

This is one of the reasons illiquid investments have a real advantage over liquid ones for people with good incomes and lifestyle-creep tendencies. When the money is in an index fund you can sell in two clicks, the temptation to deploy it for something else exists constantly. When it’s committed to a three-to-five year real estate investment, that temptation is gone. The decision was made once, up front, and the money is doing its job in the background while you get on with your life.

I’ve seen this dynamic firsthand through the club. Members who describe themselves as poor savers but have done remarkably well as passive investors, because the investment commitment removes the daily friction. The money leaves. It works. Distributions arrive. The loop breaks.


Source link

“The Lifestyle Looper” – America’s Fastest Growing Financial Trap Read More »

The Exact Investment “Stack” We’re Using to Retire Early (Not Just Rentals)

The Exact Investment “Stack” We’re Using to Retire Early (Not Just Rentals)


Don’t want to wait until 65 to retire? With a combination of rental properties and some of the other investments we’re covering on today’s show, you may not have to. Whether you’re starting from zero or diligently building your nest egg, use these eight steps to build a diversified portfolio and reach financial freedom much faster!

Welcome back to the Real Estate Rookie podcast! Today Ashley and Tony are pulling back the curtain on their actual retirement plans—what they’re doing, why they’re doing it, and what they wish they’d known sooner. They share how they first got into real estate investing and how they’ve adjusted their portfolios over time. They also break down the investment “order of operations,” a sequence of financial moves that will help you build long-term wealth!

Along the way, we’ll get into things like the 401(k) employer match, the triple-tax-advantaged HSA account, and the often-misunderstood 529 college savings plan. Whether you want to gradually step away from your W-2 job or simply have “enough” when you reach traditional retirement age, this episode gives you a clear roadmap for achieving your long-term financial goals!

Ashley:
Most people spend 40 years working so they can stop working, but what if you could build a life where work is optional way before 65?

Tony:
Ashley and I are pulling back the curtain today on our actual retirement plans, what we’re doing, why we’re doing it, and what we wish we would’ve known sooner because no one handed us a roadmap. And if you’re a real estate investor trying to figure this out on your own, well then this episode is for you.

Ashley:
This is the Real Estate Rookie Podcast. I’m Ashley Kehr.

Tony:
And I’m Tony J. Robinson.

Ashley:
So I have actually put together a list of questions for Tony and I to actually go through to share our own journey saving for retirement. And hopefully this will help a lot of you be able to plan for your own retirement. So Tony, the first thing I kind of want to go over is the beginning. When were we first introduced to retirement? And I think for me, it was when I graduated college and I started my first job and I got a 401k with that first job.

Tony:
Yeah, I think same for me. And I’ll just add context for the entire audience that between me and Ashley, Ashley’s definitely the resident retirement expert between the two of us and she educates me on a lot of these things. But yeah, I think it was for me too. When I graduated college, actually my first job after college did not offer a 401k and that job did not last very long, but my first real big boy job after college I think was a few months afterwards. And yeah, I got a 401k and I had to sit there with my other coworkers who were recent college grads and were trying to figure out, okay, how do we put these percentages there and what does this mean? But yeah, it was a first job after college with the 401.

Ashley:
Yeah, my first job only lasted six months, my accounting job before I quit and went into property management. But from that first job, I had very little vested. So a lot of times a 401k, you have to work there for so many years before they’ll actually give you the employer contribution of it. So it was very little. And when I left there, I ended up rolling it over into a Roth IRA. Still really didn’t know a lot about retirement at all. It was actually a friend that told me and helped me go through that. I didn’t really know a lot about it. And I actually had a financial advisor then. So after I had left that job, the new investor I started working for, the property management company had a financial planner. I was like, “This is probably a good idea for me. ” And I went to him and all I had was my little money.
Honestly, it was probably like $500. I don’t remember. But it rolled over into that. And then we just did some financial planning of what to do for the future. And I probably had the financial advisor for maybe five years. One thing he did do for us was set up 529 plans for the kids, which we’ll talk about that more later. But other than that, I really didn’t use the financial planner at all. I think it was like $700 to $1,000 just to meet with him and go over stuff and definitely was not worth the money. And then my second job, I didn’t even get any benefits at first. I worked there for several years. I was part-time. I worked whenever I wanted. And it actually came to a point where I asked for benefits and I got health insurance and then I got 401. And I believe it was a 3% match and I had to contribute 3% for them to give me that match, which is pretty common.
So Tony, do you remember at Tesla at all when you would, did they have a match at all?

Tony:
Yeah. So Tesla was slightly different, but I’ll go back to that first job. I actually worked for Target before working at Tesla and Target did have a match. I don’t remember what it was. It was so many years ago at this point, but I remember I just invested up to that match, whatever the match was, that’s what I invested up to. So I maxed it out there and I can’t remember what it was, but that’s what I did at Target.

Ashley:
So kind of our next investment for retirement, which we really probably didn’t think of it at the time, but was purchasing our rental properties, my long-term properties and your short-term rentals. So Tony, at the time that you were going to ignore your long-term rentals because you sold them, but your short-term rentals, when you were purchasing those, did you have anything in your mind thinking about this, I will use these properties for retirement? In any sense, were you thinking about that down the road?

Tony:
I mean, that was really the main reason that I got into real estate was because my dad growing up always said, “Unless you want to get up and go to a job every single day until you’re much, much older, you’ve got to have some assets that pay you on a regular basis.” And he’s like, “Real estate’s one of the best ways to do that. ” So that was just drilled into me very, very early on. So I don’t know if I thought about it as retirement, but for me, it was just always having that financial freedom, I guess, more so. And that’s what pulled me into real estate to begin with.

Ashley:
Yeah, that was definitely my framing and thinking too, but it was more like now. How can these assets give me the financial freedom now as in retired? But we all know landlording, short-term rental operations, a lot of that isn’t a quiet retirement sailing off into the sunset. There’s still a lot of work to do, but I never thought about what… I knew I wanted to hold properties long-term, but I never actually saw what mortgage pay down appreciation and an increase in rental income every year can actually do to just be a ton of equity by the time I’m 65. Hopefully a ton of equity before that. I have to say that it probably took me about eight years before I actually really started strategizing what properties I was keeping and which ones I was selling to think about later on in life. So I wanted to think about which properties would have a lot of appreciation where I would have options with them.
Where before, when I first started investing, it was a cashflow play. I didn’t care if they appreciated, I just wanted cashflow. Well, some of those properties were like $20,000 duplexes, but they cash flowed a lot, but they were headache properties. They were in areas that saw no appreciation. I was super, super lucky where I bought them at the right time and I sold them just after COVID when prices went crazy. And so I was able to sell them and get rid of them at a good time. But even if I would’ve held onto them for a long time, the appreciation just wouldn’t be what it was for other areas where I went for higher dollar amount properties in better areas, better school districts and things like that. So as I’ve started to weed out my portfolio, I put a lot of thought into down the road in the future.
I want salable assets that I have a easy exit strategy. They’ll have a lot of equity built up into them and I can tap into that at any time that I need to. Tony, what about you? Have you kind of changed or pivoted your strategy at all thinking more about the future when you’re ready to just retire?

Tony:
Not necessarily. I mean, I think we’ve been fortunate enough that I think the long-term prospects of all the markets we’ve invested into, we’ll probably continue to see pretty good appreciation, like a good chunk of our portfolios in California, which typically does pretty well. So I don’t know if we have anything that we’ve purchased where I question it’s the long-term viability in the portfolio. There are some properties that are just like headaches for other reasons, but I truly think if I hold all these properties for 30 years, we’ll probably be in a pretty good position in terms of loan paydown and appreciation.

Ashley:
We’re going to take a short break, but when we come back, we’re actually going to go through the retirement stack. And this is from Scott Trench from BiggerPockets Money. And this is going to tell you multiple options of what you can do for retirement and his recommended order of how to invest in these things. So we’ll be right back. Okay, welcome back. So we got into a little bit about Tony and I’s real estate for retirement, but we also want to talk on other investment vehicles that you can do for retirement because it is important to diversify and there are a lot of advantages to using some of these other retirement vehicles. I was listening to a podcast the other day with Scott Trench and Mindy Jensen on BiggerPockets of Money, and Scott went through and put together his retirement contribution order of operations. So this was for specifically a high-income W-2 household, but really I think this would work for any W-2 income household.
And if you are self-employed, you’re not going to get an employer 401k match, but you could still go through these orders of operations in some sense, but obviously you’re not going to be able to have access to all of them. But also there will be other options for you too because you are self-employed and don’t have a 401 employer option available to you. Okay, so the first one is take your employer 401 match because this is in a sense free money, but I mean technically it’s worked into your compensation package, but you should take it. Don’t leave it on the table because that’s money lost. So sometimes you don’t have to contribute, you just automatically get the match from your employer. So that’s even better. But that is step number one is to take that.

Tony:
Step number two, and this is the one that literally changed my life, but it’s the employee stock purchase program or ESPP where companies allow you to buy stock at a discounted rate. So again, I spent the majority of my W-2 career working at Tesla and I was very fortunate that during that time the company did incredibly well in the stock market. And we were able to purchase from every paycheck that would take out however much you wanted to allocate, but you could buy Tesla shares at a 15% discount. So just imagine the amount of wealth you’re able to build of every single paycheck. I think we were paid biweekly. So it was at 26 times a year I was able to go out and buy Tesla stock at a 15% discount while the stock was also increasing at this pretty rapid pace. And gosh, I want to say I might be confusing the bonuses with the employee stock purchase, but I want to say that there was a fixed price that you would be able to buy it for the quarter.
So even if it went up a little bit, you still even got maybe a bigger discount. But either way, for me, that’s where I put the majority. I think I was just putting in to match at Tesla as well for the 401k. Actually, I don’t even know if Tesla offered a match. I really can’t remember because I know most of my money was going into ESPP because that’s where I saw the biggest opportunity. But guys, when I lost that job, it was all of that stock that I’ve been piling into for years and years at that point that allowed us to have the foundation to build our portfolio and go full-time into real estate. So truly one of the best returns that I’ve ever had on any investment.

Ashley:
Yeah, I’ve never worked anywhere that had that as an option. So the next one, step three is to max out your HSA. So I believe not everyone can actually get an HSA. You usually have to be in a high deductible plan, but with the HSA, you’ve put in pre-tax money and it gross tax-free. And if you use it for medical, it’s tax-free when you pull that money out too. So it’s like a triple tax advantage. So this is great to save as you get older. You may have more medical expenses in your elderly age and you’ll have all this money to pull out tax-free to be able to use. Also, even now as you have medical things that come up, but to pay your deductible for your high deductible plan and other medical bills that you may have that you can use that money for.
But that’s a huge advantage because it’s like a triple savings on taxes right

Tony:
There. And 7.4 is to max out your dependent care FSA. I’ve actually never used this before and I’ve had kids almost my entire life now at this point and I’ve never used this. Are you using a dependent care FSA at all, Ash, or have you used one in the past?

Ashley:
No, I’m not. So it’s like a pre-tax employer sponsored. So again, if you have a W-2 job and your employer has to offer this, but it’s used to pay for childcare expenses.

Tony:
My brother-in-law works for a global tire distribution company and they offer an FSA and that’s how he pays for his babysitters through that account or for his nanny through that account. So just a good way to save on taxes on something you’re going to spend money on anyway.

Ashley:
Okay. So step five is to max your 401 contributions. So as of 2025, if anyone’s still filing those tax returns for 2025, the max contributions you could do is up to 23,500. So this is pre-tax contributions. And I mean that’s a lot of money for a lot of people to be able to put $23,500 after you’ve already contributed to a lot of these other things too. So this would be just maxing out your 401k.

Tony:
Ash, I’ll let you take maybe six and seven just because I feel like I can’t speak confidently to the IRAs.

Ashley:
Okay. Then the next thing is the Roth IRA. But this is if you are a high net come earner, you’re not eligible for an IRA. So for single head of household, you have to be $153,000 or under. You can’t make more than that. If you’re married filing jointly, it has to be under $242,000 to be able to contribute into the Roth IRA. The Roth IRA is where you contribute after tax income and then your money grows tax-free. One thing I really like about the Roth IRA is that really at any time, unless you’re using an employer sponsored plan, they may not allow this, but if you just go to Vanguard, Fidelity, open your own account, what you contribute, you can pull out at any time tax-free and penalty-free because you already paid taxes on that money when you put it in there. So you want a down payment for a property and you have the money that you’ve contributed over the years in a Roth IRA, so you’ve contributed $50,000, maybe it’s grown to 70,000, you could pull out 50,000 of that and use it for a down payment on a rental property.
So that’s what I like about the Roth IRA is you can still access that money without having to pay any penalties or fees. If you do make over that amount of money and aren’t eligible for a Roth IRA, there is something called a backdoor Roth IRA. And first of all, I’m going to urge you to go over and listen to this episode of BiggerPockets Money. It was with Amanda Hahn, who’s a CPA, who talks about the benefits of how you could actually do a Roth IRA. But basically what you do is you’d contribute to a traditional IRA and then convert it immediately into a Roth IRA. And the limitation for 2026 for a Roth IRA is $7,500 that you’re able to contribute to it. Okay, then you can even take it a step further and do a mega to a Roth IRA. And once again, you have to check that your plan administrator allows this, but if you can make after tax contributions to your 401k, so it’s like a Roth 401k, then you can contribute it up to 72,000.
But then remember, this is a combined limit with what you’ve already put in, but then you can go ahead and convert that into a Roth IRA. And Amanda Hahn had said on this episode as to this is all legal, but it’s like the IRS, they always just make you jump through a hoop to get something done. It’s not like you can just easily go ahead and go into a Roth IRA. You have to do these hoops to be able to access this tax benefit. But talk to your CPA, talk to your financial advisor if these are options for you.

Tony:
And then the final step, step number eight here is the 529 college savings plan. And again, I’m 35. My son is 18, so it’s like more than half my life I’ve been a parent, but I didn’t even know about this when he was born. And now that we’ve got younger kids again, this might be something we end up using. But effectively, this allows you to take money after tax money. So you’ve already paid taxes on it. You can put this into this 529 plan and it grows and all of that growth is tax-free as long as it’s used for educational purposes. So sending your kid to college, to trade school, to apprenticeship program, something to that effect. And actually, I don’t know, Ash, do you know if there’s contribution limits on the 529?

Ashley:
It’s basically like a gift tax. So it’s 19,000 but 38,000 for married couples without having to report a gift tax.

Tony:
I mean, that’s a meaningful amount. If you’re doing that, you can send your kid to a very, very expensive school if you continue to do that over the course of their lifetime. So if you’ve got young kids, it is a great tool to allow you to set money aside and let it grow that you can then use for college.

Ashley:
So New York State, you can deduct if you’re individual up to 5,000. And if you’re married, you can deduct up to $10,000. So if that makes a big difference on your income tax return, but that’s another benefit depending on what state you’re in, it could reduce some of your reported income on your taxes for the state tax return. Another benefit of the 529 plan is I believe it’s 36,000 of that can actually convert into a retirement plan. So it actually convert into an IRA. So if the kids don’t use it for school, then you can actually save that money for their retirement and then they can pull it out when they’re at retirement age and they don’t have to use it for school. But there is a limitation, a cap on how much money can be used for that. But also the 529 plan, it can be used for private school, for high school, even I believe elementary too.
So even if you have a kid going to private school right now, you could contribute to it just to get the New York State tax write off, then pay the school out of it to have that deduction. But you can pay for books. I had seen this post before where it was an accountant that posted it on social media where they had said what you should do is put all this money into the 529 plan and then when your kids go to college, you buy a house there and have your kids use the money out of the 529 plan to pay you rent. So it’s guaranteed rental payments. The money that you contributed is coming back to you. One thing that people totally missed in the comments, and I actually started kind of arguing with someone, which I never ever engaged with. And the person who posted it finally responded like, yes, you’re absolutely correct.
Is that just remember that’s not tax-free money. That still rental income coming back to you. So you’re still paying taxes on that, but not as much as you would’ve when you first earned that money from your W-2 job.

Tony:
And then you do something like a cost segregation setting, you get some bonus depreciation and you qualify for rep status and material participation and you can still write off all those earnings, hopefully.

Ashley:
Okay. We’re going to take a short break and we’ll be right back after this to tell you what our plans are for the future for our retirement. Okay, welcome back. Thank you guys so much for watching or listening. If you haven’t already, make sure you are subscribed to our YouTube channel at RealEstateRookie. Okay, so we went over some retirement options that you may have, a recommended order of operations from Scott Trench, but let’s get into what Tony and I are actually doing now with these retirement options that are available and what we see for ourself down the road. So Tony, what is currently happening right now? Are you contributing to any kind of retirement plan that’s available out there?

Tony:
I do have a retirement plan. Yeah. Not a lot is in there because I just started it recently. I’m very overly concentrated in real estate right now. I still do have a Tesla stock for my time working there, but obviously that’s just one entity. So there’s still some risk there. I think that’s part of the reason I love when we talk about this is because you remind me there’s a lot of other options out there, but I think I get so focused on what’s in front of me and like, hey, real estate is a thing that I know so well, but there’s a benefit to having a diversified portfolio. So I think for me, it’s looking into some of these other options and seeing how I can expand those things.

Ashley:
I think too, real estate is so addicting. It’s like, okay, over the course of the year, I could contribute this money to a retirement account or even a brokerage account or whatever, or I could go and buy another property or I can add an upgrade to my short-term rental to increase the revenue there. Think about how many pools you put in. Those could have been money funneled into a retirement account for you, but that is your retirement, these properties too.

Tony:
But I think diversification is good. And I talk with a lot of folks who are coming from the opposite end where all of their retirement is in the stock market and they’re like, “Hey, I just want to diversify and have something that’s a little bit more tangible. And I’ve got so much that’s tangible that I probably need a little bit more that’s in the market.” So got to balance it out a little bit.

Ashley:
Yeah, I’m contributing right now to retirement plans and I maxed out my contributions last year, but this year I’ve been not as much. I’ve definitely slowed down my contributions just because like you said, there’s other things I want to do in real estate right now. So definitely not contributing to the max and I don’t think I’ll max out this year at all. But another thing is the 529 plans I did that financial planner, I guess maybe he was worth the $1,000 because I did contribute to my kids’ 529 plans when they were very little. And I think my oldest was two or three and then the other ones basically have them since they were born. And I’m pretty sure I’ve put, I think it’s like $50 a month I put in each one of them. And when I started them, I probably put in a thousand to fund them or something like that each maybe.
But they each have 12 to $14,000 in them right now at the age of eight, nine, and 12. So that makes a big difference being able to start and then if they decide not to go to college, you can actually change the beneficiary on them too. So I am the owner of the 529 plans, but at any time I could change the beneficiary. So actually my sister, she’s going to school right now to be a PA. And my aunt had money left in a 529 plan and she changed the beneficiary to my sister so she could use the money to finish out school. So that was really awesome. I

Tony:
Didn’t know that that was one of the features of the 529. Yeah. Are you able to use it for, say that you have a kid that wants to go to, they want to become a surgeon, so they’ve got to go to regular undergrad, medical school, residency, all those other things. Can you use it across all those different stages or does it stop at a certain stage? Do you know?

Ashley:
I don’t think it does. I don’t know for sure, but I’m pretty sure you can use it for any education. And that makes me wonder too, if you were a real estate agent, could you use it for your CE classes? Things like that. I’m not sure on the specifics of that. But one thing I like about it too is you can go into your 529 plan and you can print off little vouchers and you give these out to grandparents and say, “Hey, they don’t need another toy to clutter their house. Here’s a voucher. You can mail in a check and this will go into their 529 plan.”

Tony:
That’ll get all the kids excited on Christmas morning.

Ashley:
I mean, not that it’s worked for me yet. I haven’t noticed any increase in any of their accounts. It wasn’t Ruby, but that is an option out there. And I’ve read too a lot of articles about grandparents starting them also for kids and then they’re being the owners of it and then the kids being the beneficiary, the grandkids. So yeah, Tony and I are really interested as to how you are diversifying your retirement, what options you have available. One thing that’s been really important to me this year is financial opportunity and that is having many different ways to access capital. So if I have a medical emergency, I have a Roth IRA I can withdraw from. I have an investment property I can sell. I have a store full of liquor that I can liquidate going out of business sale. So I think that’s the biggest thing for me is I want to have financial options, not only in retirement, but now in life too.
So it’s been intriguing to me to talk about all these different ways to build financial freedom alongside real estate because I do think it is really important to diversify. Well, thank you guys so much for joining us. I’m Ashley and he’s Tony and we’ll see you guys on the next episode of Real Estate Rookie.


Help us reach new listeners on iTunes by leaving us a rating and review! It takes just 30 seconds and instructions can be found here. Thanks! We really appreciate it!

Interested in learning more about today’s sponsors or becoming a BiggerPockets partner yourself? Email [email protected].


Source link

The Exact Investment “Stack” We’re Using to Retire Early (Not Just Rentals) Read More »

Most Bet бонусы и акции (KZ): разбор механик и условий для игроков

Бонусная программа оператора — это не маркетинговый баннер, а математически выверенный инструмент управления банкроллом и удержания аудитории. В случае с Most Bet казахстанские пользователи получают доступ к локализованной системе поощрений, где все расчёты ведутся в тенге, а условия адаптированы под региональные платёжные привычки и законодательные особенности рынка. Вместо поверхностных обещаний быстрого подъёма баланса здесь важно понимать, как именно формируются вейджеры, какие игры учитываются в отыгрыше и где скрываются ограничения по времени. Этот разбор составлен для опытных игроков, которые ценят прозрачность и хотят оценивать предложения через призму реальной ценности, а не рекламной подачи. Мы рассмотрим структуру акций, влияние верификации на вывод средств и типичные сценарии, где бонус превращается в дополнительную нагрузку на игровой счёт.

Архитектура бонусной системы: от активации до отыгрыша

Бонусная механика платформы построена на классической модели депозитных матчей и пакетов бесплатных вращений, однако её эффективность напрямую зависит от понимания правил конвертации. Приветственные предложения обычно активируются при первом пополнении, но размер отыгрыша варьируется в зависимости от выбранного раздела. Для игровых автоматов коэффициент вейджера чаще всего находится в диапазоне от тридцати до пятидесяти, при этом не все разработчики участвуют в программе на равных условиях. Слоты с высоким процентом возврата или встроенной функцией покупки бонусных раундов могут иметь пониженный коэффициент зачисления, а в некоторых случаях полностью исключаются из расчёта. Это стандартная отраслевая практика, но игроки регулярно упускают её из виду, рассчитывая на линейную отдачу.

Most Bet бонусы и акции (KZ): разбор механик и условий для игроков

Важно сверять актуальные коэффициенты в разделе правил перед активацией, так как условия могут корректироваться без громких анонсов. Система автоматически фиксирует каждую ставку, и если игра не входит в список разрешённых, прогресс отыгрыша не начисляется. Для краш-механик и настольных игр правила ещё строже: большинство из них либо не учитываются вовсе, либо зачисляются с коэффициентом от пяти до двадцати процентов. Это создаёт естественный фильтр, направляющий активность пользователей в слотовый сегмент, где математическое ожидание оператора выше. Понимание этой архитектуры позволяет избежать ситуаций, когда бонусный баланс блокируется из-за неправильного выбора игры.

Математика предложений: как оценивать реальную ценность

Чтобы понять, стоит ли активировать предложение, необходимо сопоставить размер вейджера с математическим ожиданием выбранных автоматов. Если коэффициент отыгрыша равен сорока, а средний возврат игроку составляет девяносто шесть процентов, теоретический возврат на дистанции будет ниже суммы, необходимой для выполнения условий. Это не означает, что предложение бесполезно — оно увеличивает время игровой сессии и даёт доступ к турнирным сеткам или периодическим кэшбэкам, но воспринимать его как гарантированный доход некорректно. Опытные пользователи рассматривают бонус как страховой инструмент или способ протестировать новые механики без риска собственным банкроллом.

При этом стоит учитывать лимиты на максимальную ставку во время отыгрыша: превышение порога часто приводит к аннулированию прогресса или заморозке средств. Чёткое планирование сессий и выбор игр с умеренной волатильностью помогают минимизировать дисперсию и сохранить баланс в рабочем состоянии до выполнения условий. Для детального изучения актуальных параметров и проверки статуса активных предложений вы можете перейти https://mostbets-casino-kz.com и сверить данные перед началом сессии. Сравнительная таблица ниже показывает, как разные типы предложений влияют на расчёт банкролла:

Тип предложенияСредний вейджерУчтённые игрыЛимит ставкиРеальная цель
Приветственный матчх35–х45Слоты (кроме прогрессивных)500 ₸Увеличение времени игры
Пакет фриспиновх30–х40Конкретный автомат провайдера300 ₸Знакомство с механикой
Еженедельный кэшбэкх1–х5Все разрешённые разделыБез ограниченийКомпенсация просадок
Турнирные призовыеБез вейджераУказанные слотыПо правилам турнираКонкурентный розыгрыш

Анализ показывает, что предложения без вейджера или с минимальным коэффициентом всегда обладают более высокой практической ценностью, однако их активация требует строгого соблюдения временных рамок и правил участия. Игрокам рекомендуется вести учёт ставок и сверять прогресс в личном кабинете, чтобы избежать расхождений между ожидаемым и фактическим результатом.

Платёжная инфраструктура Казахстана и влияние на активацию

Локализация платформы под рынок Казахстана проявляется в первую очередь через поддержку национальной валюты и интеграцию с привычными платёжными каналами. Пополнение через Kaspi или банковские карты проходит в тенге, что исключает скрытые комиссии за конвертацию и упрощает расчёт банкролла. Однако бонусные условия часто привязаны к минимальной сумме депозита и способу ввода средств. Транзакции через мобильные операторы или криптовалюты могут иметь отдельные лимиты, которые не всегда совпадают с требованиями для активации приветственного пакета.

Кроме того, система требует прохождения верификации до первого вывода: без подтверждения документов и адреса средства могут быть заморожены до завершения проверки. Это стандартный комплаенс-механизм, направленный на предотвращение мультиаккаунтинга и отмывания средств, но он напрямую влияет на скорость доступа к выигранным бонусным средствам. Игрокам рекомендуется завершать процедуру подтверждения заранее, чтобы не сталкиваться с задержками в момент, когда отыгрыш уже выполнен. Использование одного платёжного метода для пополнения и вывода снижает риск дополнительных запросов от службы безопасности и ускоряет обработку заявок.

Ограничения, комплаенс и типичные ошибки пользователей

Главная сложность работы с бонусами кроется не в самих условиях, а в их интерпретации. Наиболее распространённая ошибка — активация нескольких акций одновременно, что приводит к блокировке средств из-за конфликта правил отыгрыша. Платформа, как правило, разрешает использовать только один активный бонус, и попытка обойти это ограничение через создание дополнительных аккаунтов нарушает пользовательское соглашение и ведёт к полной блокировке профиля. Также стоит учитывать временные рамки: большинство предложений действует от семи до тридцати дней, после чего неиспользованные средства и начисленные вращения сгорают.

Игроки часто игнорируют этот параметр, пытаясь отыграть вейджер в спешке, что приводит к агрессивным ставкам и быстрому снижению баланса. Ответственный подход подразумевает установку личных лимитов, отказ от погони за гарантированными выигрышами и понимание того, что бонус — это инструмент развлечения, а не инвестиционный продукт. При соблюдении базовых правил риск потери контроля над банкроллом существенно снижается. Важно помнить, что азартные игры несут финансовые риски, и участие в них должно оставаться контролируемым и осознанным процессом.

Можно ли отыграть бонус на краш-играх вроде Aviator?

Большинство краш-механик либо исключаются из расчёта вейджера, либо учитываются с пониженным коэффициентом. Точные параметры зависят от текущих правил раздела, поэтому перед активацией рекомендуется проверить список разрешённых игр в условиях акции.

Влияет ли способ пополнения на размер бонуса?

Да, минимальная сумма для активации может различаться в зависимости от платёжного канала. Транзакции через Kaspi и банковские карты обычно соответствуют стандартным требованиям, тогда как криптовалютные переводы или оплата через мобильный баланс могут иметь отдельные лимиты.

Что происходит с бонусными средствами при нарушении лимита ставки?

Превышение допустимого размера ставки во время отыгрыша часто приводит к заморозке прогресса или аннулированию бонусного баланса. Система фиксирует каждую транзакцию, поэтому рекомендуется строго придерживаться параметров, указанных в правилах конкретной акции.

Об авторе: Сергей Лебедев — аналитик игровых платформ, специализирующийся на разборе бонусных механик, оценке реальной ценности предложений и адаптации игровых стратегий для пользователей из Казахстана.

Источники: Официальные правила бонусной программы Most Bet, документация по комплаенсу и верификации, данные провайдеров по проценту возврата и волатильности, отраслевые стандарты расчёта вейджеров и платёжной интеграции.

Most Bet бонусы и акции (KZ): разбор механик и условий для игроков Read More »

Rancher Steven McBee Cuts Out Middlemen With Snacks Model

Rancher Steven McBee Cuts Out Middlemen With Snacks Model


Opinions expressed by Entrepreneur contributors are their own.

For most ranchers, the hardest part isn’t raising the cattle, but what happens after they leave the farm. Once they’re loaded onto someone else’s truck, so is most of the control. Processing, distribution and, too often, the biggest share of the profit all belong to somebody else. 

Steven McBee Jr. looked at that system years ago and decided he wasn’t going to keep playing by its rules. 

So while Washington is now investing up to $500 million to strengthen small and midsize meat processors, the 33-year-old rancher has spent the better part of a decade building his own way around the bottleneck.

Credit: Steven McBee Jr.

“Everybody in this industry gets told to raise your cattle, sell them into the commodity system and take the price you’re given,” McBee said. “We looked at that and thought, Why stop there? If we wanted more control over our future, we had to own more of what came next.”

It’s the mindset that built McBee Farm & Cattle Co. on a first-generation family farm in Gallatin, Missouri, where McBee works alongside his father, Steve Sr., and brothers Jesse, Cole and Brayden. There was no inherited land, no inherited cattle, no generations-old banking relationships. What the McBees did have, they put on camera. 

Since The McBee Dynasty: Real American Cowboys premiered in 2024, viewers have watched the family build the business in real time, setbacks and all. “We never wanted the polished version,” McBee explained. “The equipment failures and the expensive lessons made the cut right alongside the wins, and that’s the point. It’s the same fight every farmer and rancher in America is in right now.”

The numbers behind that fight are brutal. The four largest beef packers controlled about a quarter of the U.S. market in the early 1970s. Today, they handle roughly 85 percent of U.S. beef processing, leaving independent producers with few options once their cattle are ready for market. Add rising input costs and unpredictable weather on top, and the margins go from thin to gone.

The way out, McBee figured, was hiding in plain sight. Americans were buying more protein, meat snacks were taking off, and very little of that value was making its way back to the producers themselves. “At some point, we quit asking how to get a better price for our cattle, and we started asking how to build something people could actually buy from us.”

Credit: Steven McBee Jr.

That “something” was a snack stick. McBee had been circling the idea since 2017, but selling a branded, shelf-stable product meant taking on parts of the business most ranch families never touch. “We had to become beginners over and over,” he said. “There wasn’t a shortcut. Every new part of the business came with a learning curve of its own.”

The first brand launched in 2020, and once demand proved real, a production facility followed two years later. The biggest leap came in 2023 with the purchase of the company’s own meat processing plant. After months of upgrades, it earned federal inspection and SQF certification, a top-tier food safety standard. A fulfillment center came next, built right on the farm so every order now ships from the same place the cattle are raised. 

“We built the ladder one rung at a time, and each step was funded by the one before it. Farm, facility, fulfillment. One family, zero middlemen, and we can stand behind exactly what’s in the package and how it got there,” McBee said.

The timing couldn’t have been much better. Meat snack sales have climbed more than 45% over the past four years to a $4.4 billion category, and McBee says demand for the company’s snack sticks is already outpacing what the current facility can produce. Today, the products ship directly to customers through McBeeFarms.com and sit on shelves in more than a dozen states.

Growth hasn’t pulled the business away from Gallatin, either. The next facility is going up in the same rural Missouri community, built with local labor and expected to create 25 full-time jobs on top of the more than 30 the company already supports.

That local focus extends beyond the business, too. Along with donating snack sticks to nearby schools, the company brings children from underserved Kansas City neighborhoods to the farm through its Kids in the Outdoors program for horseback riding, fishing and a firsthand look at where their food comes from.

McBee’s next project is a little different. He’s building a men’s retreat program on the farm that combines the outdoors with conversations around emotional regulation and mental health.

For him, all of it comes back to the same goal. 

“I want McBee to be proof that the American family farm isn’t dying. It just needs a different business model,” he said. “However big this gets, the rhythm won’t change. My brothers and I work side by side every day, and we still all sit down to dinner together every night. If we do this right, the next generation of farmers won’t have to invent a thing. They’ll just copy us.”

For most ranchers, the hardest part isn’t raising the cattle, but what happens after they leave the farm. Once they’re loaded onto someone else’s truck, so is most of the control. Processing, distribution and, too often, the biggest share of the profit all belong to somebody else. 

Steven McBee Jr. looked at that system years ago and decided he wasn’t going to keep playing by its rules. 

So while Washington is now investing up to $500 million to strengthen small and midsize meat processors, the 33-year-old rancher has spent the better part of a decade building his own way around the bottleneck.


Source link

Rancher Steven McBee Cuts Out Middlemen With Snacks Model Read More »

1XBet: что важно знать о платформе и её возможностях

Для новичка 1XBet удобнее всего рассматривать не как «просто казино», а как большую игровую экосистему, где рядом существуют букмекерская часть и казино-раздел. Это важно для понимания логики платформы: у таких брендов обычно разный юридический контур, разный набор функций и разные ожидания по платежам, верификации и доступности игр. Для рынка Казахстана особенно полезно сразу отделять локальную легальную часть от международной витрины, чтобы не путать правила, ограничения и способы входа.

В этом материале я разберу, как новичку ориентироваться в интерфейсе, на что смотреть в ассортименте, где обычно возникают ошибки и какие компромиссы нужно принять заранее. Если вам нужен быстрый вход в тему, удобнее начинать с официальной страницы казино 1XBet, но дальше всё равно стоит проверить базовые вещи: условия, лимиты, способы пополнения, правила вывода и инструменты контроля расходов.

1XBet: что важно знать о платформе и её возможностях

Как устроен бренд 1XBet для Казахстана

Главная особенность 1XBet в Казахстане — двойная природа. С одной стороны, есть локальная букмекерская деятельность на домене 1xbet.kz, которую в открытых фактах связывают с ТОО «UAK A LLP» и лицензией №22006899. С другой — существует международная версия бренда, которую игроки воспринимают прежде всего как казино и многопрофильную игровую платформу. Для новичка это не мелочь, а основа понимания: правила, доступность отдельных разделов и юридические условия могут различаться.

Из этого следует простой вывод: если вы оцениваете бренд, не стоит смешивать всё в один сценарий. Букмекерская линия, live-формат и казино-лобби решают разные задачи. Беттинг чаще выбирают те, кому важны спортивные события, коэффициенты и роспись. Казино — те, кто ищет слоты, live-столы и мини-игры. На практике один и тот же аккаунт может давать доступ к разным активностям, но риск-профиль у них разный: в казино выше эмоциональная нагрузка, а в ставках — выше влияние анализа и дисциплины.

Для пользователя из РК полезно помнить и про правовой контекст. В Казахстане букмекерская деятельность регулируется, а казино-сегмент в онлайне остаётся более чувствительной зоной по сравнению с наземными игорными зонами. Поэтому перед регистрацией важно читать именно актуальные правила площадки и не делать выводов только по рекламным обещаниям. Если в описании платформы нет чётких подтверждений по конкретному юридическому лицу, лучше считать это информационным пробелом, а не поводом для догадок.

Что обычно видит новичок внутри платформы

Первые шаги на подобных площадках почти всегда похожи: регистрация, вход в личный кабинет, выбор раздела, пополнение и попытка разобраться, где находятся игры или ставки. У 1XBet структура обычно строится вокруг нескольких больших блоков: спорт, live, казино, мобильный доступ и служебные разделы с условиями. Новичку важно не разбрасываться, а пройти по ним последовательно.

Практически это выглядит так:

  • сначала проверяете, есть ли нужный язык интерфейса и понятная навигация;
  • затем смотрите, как устроен поиск игр или событий;
  • после этого оцениваете, насколько удобно пополнение в тенге;
  • и только потом переходите к ставке или запуску игры.

Сильная сторона бренда обычно в широте выбора. В казино-разделе международной версии упоминаются слоты, настольные игры, live-казино, лотереи, бинго и собственные мини-игры. Для новичка это плюс, потому что можно не ограничиваться одним жанром и быстро понять, что именно вам подходит по темпу и бюджету. Но у широты есть и обратная сторона: чем больше лобби, тем легче потерять контроль и начать перескакивать между режимами без системы.

Отдельно стоит отметить мобильный сценарий. Для Казахстана это особенно важно, потому что многие пользователи заходят с телефона чаще, чем с компьютера. В таких случаях ценится не только наличие адаптивной версии, но и стабильность загрузки, быстрый вход и нормальная работа в условиях слабого сигнала. Если платформа тяжело открывается, даже хороший ассортимент не спасает пользовательский опыт.

Игры, спорт и live-формат: в чём разница для новичка

Новички часто считают, что «казино» — это один сценарий. На деле внутри платформы есть несколько разных моделей поведения, и каждая требует своей логики. Слоты — это темп, случайность и быстрые сессии. Live-казино — более медленный формат с ощущением реального стола и дилера. Спорт — это уже аналитика, линия, коэффициенты и работа с банкроллом. Если смешивать всё подряд, итог почти всегда один: хаотичные решения.

В Казахстане особенно заметна популярность live и динамичных игр. Это объяснимо: людям нравится ощущение процесса, а не только результат кнопки «спин». Но именно live и быстрые игры чаще провоцируют перерасход, потому что пауза между действиями небольшая, а эмоции накапливаются быстро. Поэтому новичку полезно заранее выбрать один основной формат на старт, а не пытаться освоить всё одновременно.

Чтобы проще сориентироваться, удобно сравнить сценарии:

ФорматЧто важноГде чаще ошибаются
СлотыВолатильность, частота выплат, размер ставкиСтавят слишком крупно и быстро сливают банк
Live-казиноТемп игры, лимиты стола, дисциплинаПутают азарт наблюдения с реальной управляемостью результата
Ставки на спортЛиния, роспись, коэффициент, рискСобирают экспрессы без понимания маржи и дисперсии
Мини-игрыСкорость раундов, лимиты, холодная головаДелают слишком много повторных входов подряд

Если смотреть трезво, самая полезная стратегия для новичка — не искать «идеальный» раздел, а определить, какой темп игры вы реально выдерживаете без импульсивных действий. Это важнее красивой витрины и заметных коэффициентов.

Платежи, тенге и бытовая логика для игроков в Казахстане

Для местного рынка вопрос платежей часто важнее списка игр. В Казахстане привычка пользователя строится вокруг тенге, банковских переводов и понятных способов пополнения. Поэтому многие сначала смотрят не на бонус, а на то, можно ли удобно завести и вывести деньги. В локальном контексте особенно часто ожидают поддержку Kaspi, Halyk и других привычных для страны инструментов. Если способ пополнения неудобный, конверсия падает сразу — даже если сама платформа выглядит убедительно.

Но здесь есть нюанс: не нужно автоматически считать, что любой удобный метод доступен в каждом сценарии. Для новичка правильнее проверять доступные опции прямо в личном кабинете и читать условия именно перед первым депозитом. Особое внимание — лимитам, комиссии и возможной верификации. У многих игроков проблема не в самом пополнении, а в том, что они заранее не знают правила вывода и потом удивляются задержкам.

Практический чеклист перед первым платежом:

  • проверьте, в какой валюте открыт баланс;
  • смотрите минимальный депозит и минимальный вывод;
  • уточните, нужна ли верификация до первого снятия средств;
  • проверьте, есть ли ограничения на бонусные средства;
  • не пополняйте счёт на сумму, которую не готовы потерять как расходы на досуг.

Ещё один важный момент для игроков в РК — налоги и правила местного рынка. В открытых фактах отдельно отмечается, что легальная букмекерская деятельность может подразумевать автоматическое удержание налога с выигрыша. Это значит, что одинаковая сумма выигрыша в разных моделях может по-разному отражаться на фактическом выводе. Новичку полезно понимать эту разницу заранее, чтобы не сравнивать платформы только по «грязной» сумме.

Сильные стороны и ограничения: что реально важно

Если убрать маркетинговый шум, у 1XBet как у крупной экосистемы обычно выделяются три практических преимущества: масштаб, разнообразие сценариев и мобильная доступность. Но у этого же набора есть и обратная сторона: сложность, не всегда прозрачная структура и необходимость внимательнее читать условия. Для новичка это не повод избегать платформу, а повод пользоваться ею аккуратно.

Сильные стороны:

  • широкий выбор игровых и спортивных сценариев;
  • удобство для мобильного использования;
  • многоуровневая навигация, если вы любите выбирать из большого каталога;
  • возможность быстро переключаться между формами досуга.

Ограничения и trade-off:

  • чем больше разделов, тем выше риск импульсивной игры;
  • непрозрачность юридической структуры требует отдельной проверки;
  • без дисциплины даже удобный интерфейс превращается в источник лишних расходов;
  • бонусы и акции почти всегда идут с условиями, которые нужно читать полностью.

Есть и ещё один важный нюанс: многие пользователи переоценивают значение бонуса. Бонус — не подарок без условий, а инструмент с ограничениями по отыгрышу, срокам и допустимым играм. Если новичок видит только размер предложения и не смотрит вейджер, он часто получает не выгоду, а лишнюю путаницу. Лучше воспринимать бонус как дополнительную опцию, а не как основу стратегии.

Как не ошибиться новичку: простой алгоритм

Если вы впервые знакомитесь с платформой, держите простой порядок действий. Он не даст «чудесного результата», но поможет избежать типичных ошибок.

  1. Сначала изучите условия: регистрация, вывод, лимиты, верификация.
  2. Потом определите один основной формат игры или ставок.
  3. Задайте личный банкролл и не выходите за него.
  4. Проверьте, насколько удобно пополнять счёт в тенге.
  5. Только после этого тестируйте интерфейс и дополнительные функции.

Для большинства новичков полезно ввести правило одной сессии: один бюджет, один формат, один заранее понятный лимит времени. Это особенно актуально для live-режима и быстрых игр, где эмоции подталкивают к повторным ставкам. Если же вы замечаете, что начинаете «догоняться», лучше остановиться сразу, чем пытаться отыграться на импульсе.

И ещё одна мысль: не стоит сравнивать платформу по одной характеристике. Хороший бренд в гэмблинге — это не только красивый лобби-дизайн, а совокупность трёх вещей: понятные правила, приемлемый платежный сценарий и честная для вас модель риска. Если хотя бы один элемент проваливается, общий опыт будет слабым.

Mini-FAQ

1XBet — это только казино?
Нет. Бренд связан и со ставками на спорт, и с казино-сценарием. Для новичка важно понимать, что это разные форматы с разной логикой игры и разными рисками.

Что проверять в первую очередь перед регистрацией?
Условия вывода, валюту баланса, требования к верификации, лимиты и доступные способы пополнения. Это важнее, чем любой баннер или бонус.

Почему для Казахстана так важны платежи в тенге?
Потому что локальный пользователь обычно ориентируется на привычные банковские сценарии и не хочет терять деньги на лишних конвертациях или сложных переводах.

Стоит ли новичку сразу пробовать и спорт, и казино?
Лучше нет. Сначала выберите один формат, чтобы понять темп, лимиты и собственную реакцию на проигрыш и выигрыш.

Короткий вывод

1XBet для рынка Казахстана проще всего понимать как крупную игровую экосистему, где удобство, масштаб и мобильность сочетаются с необходимостью внимательно читать правила. Для новичка здесь особенно важны не громкие обещания, а три практических вопроса: как устроены платежи, какой формат подходит вашему стилю игры и где именно спрятаны ограничения. Если держать эти вещи в фокусе, платформа становится понятнее и предсказуемее.

Об авторе: Динара Смагулова, аналитический автор о гемблинге и пользовательских сценариях в Казахстане. Пишу о том, как платформы работают на практике, где у них сильные стороны и какие риски важно видеть заранее.

Источники: открытые сведения о правовом статусе 1xbet.kz и 1xBet в Казахстане; данные о лицензировании и операторе ТОО «UAK A LLP»; общие правила рынка РК; публично доступные характеристики интерфейса и функциональности платформы.

1XBet: что важно знать о платформе и её возможностях Read More »