Blog

How to (Legally) Pay Less in Taxes as a Rookie Real Estate Investor

How to (Legally) Pay Less in Taxes as a Rookie Real Estate Investor


Have you ever seen a “tax hack” online and wondered if it’s actually legal? Putting your logo on your car, renting your home to your business, or moving everything into a trust: a lot of what goes viral is only half true. The other half can draw the IRS’s attention. Here’s how to tell the difference, from people who do this for a living.

Welcome back to the Real Estate Rookie podcast! Live from BPCON 2026 in Orlando, Ashley and Tony sit down with Amanda Han and Matt MacFarland, CPAs and tax strategists at Keystone CPA. They’re also the authors of The Book on Tax Strategies for the Savvy Real Estate Investor. Together they explain the difference between filing your taxes and actually planning them, and which popular real estate tax myths don’t hold up under scrutiny.

You’ll learn how to rent your house to your business (without paying taxes), and why you don’t need an LLC to claim real estate tax benefits. Plus, how the short-term rental loophole creates write-offs for W-2 earners (and where people push it too far), and how it compares to real estate professional tax status. Amanda and Matt even share the one question to ask when vetting a CPA, so you find someone who actually understands rental property investing.

Before you take tax advice from a 30-second TikTok, listen to this episode first, so you can get the tax benefits without the audit!

Ashley:
Welcome to Real Estate Rookie. I’m Ashley.

Tony:
And I’m Tony.

Ashley:
And today we are live from the BiggerPockets Conference in Orlando, Florida. And we’ve been going through the halls and pulling some of our favorite speakers to come and talk with you guys today on the podcast. So if you missed BP Con this year, make sure you come to the one next year. It was just released. We are going to Denver, Colorado in October of 2027. Make sure you check out biggerpockets.com/conference to see all the details so you can join us next year. Well, let’s give a big welcome to Matt and Amanda who actually did a tax session this morning, a workshop for investors who came a little bit early today to BPCon to get some tax advice. So what did you guys talk about in your session today?

Matt:
Nothing about taxes.

Amanda:
Well, it was a sold out session and it was three hours long. So first of all, I was super grateful that everybody stayed the whole time. We gave people a bathroom break in the middle and I really thought people wouldn’t come back. Yeah, but they came back. Yeah, but we talked about the life cycle of an investor and the different tax implications, starting with people brand new, maybe doing house hacking to those people doing burst, scaling the real estate, and also people doing into wholesale, fix and flip and then into syndications. And what are some of the tax planning opportunities as you go through each phase of your investing journey?

Matt:
Yeah. Some of the different foundational strategies that people can utilize as they move along in their journey and wealth building and stuff. So cool.

Ashley:
Now, who are you guys? Why should we listen to you for tax advice?

Matt:
Because you pulled us out of the hallway. So I’m Matt McFarlane, CPA and tax strategist at our firm, Keystone CPA. We work with real estate investors all over the country to help them proactively save on taxes, keep more of their hard-earned money and build wealth through real estate and other vehicles as well.

Amanda:
Yes. And I’m Amanda Hahn. You probably see me on some of the BiggerPockets podcasts. Matt and I wrote two books for BiggerPockets, the Tax Strategies book for real estate investors and then the advanced book for real estate investors.

Tony:
And just big disclaimer, those were both pre-AI. So you guys wrote every single word yourself. There was no chat or claw to help out at that time so you can believe it’s all

Matt:
Good

Tony:
Stuff. Before we jump in guys, because we talk about this often, but what is the difference between someone who files your taxes and someone who helps you with tax strategy? Because I think a lot of folks don’t have that distinction yet.

Matt:
Yeah. I think you think about tax filing, what you’re doing really is just taking numbers for stuff that’s already happened and putting it on a form and reporting what’s gone on in the past where true tax planning is actually looking at the future and what’s coming up, what are your goals, what are you trying to accomplish? Are you trying to build wealthy real estate? Are you trying to sell a business? Whatever it might be, thinking about the future and planning for it ahead of time versus sitting down in April when you drop off your tax stuff and saying, “Hey, what can I do differently?” That’s not tax planning, that’s just filing your taxes.

Tony:
Let me ask a question because the goal for a lot of people who invest in real estate is to leverage the tax benefits associated with it. I posted something a while ago and some nameless profile with a weird picture, but the comment stuck with me.

Ashley:
A troll,

Tony:
They call it. A troll. Yeah, it was a troll. Basically tried to make me feel bad for talking about how I’m able to reduce my tax bill. Hey, you’re part of the problem and yada yada yada. What is your guys’ take as CPAs? Are we as real estate investors and people who use tax strategy in general, are we somehow part of the problem?

Ashley:
Taking advantage of the system.

Tony:
Just what’s your take on that?

Amanda:
Yeah, I mean it’s really interesting because if you think about it, the tax rules are designed by the government and it’s really just a set of incentives on what the government wants you to do and the way they’re incentivizing us to do those things is through tax law and tax savings. And so really we get tax benefits when we invest and when we stimulate the economy. If you’re doing stocks or if you own a business and you hire people, we get tax benefits for that. And real estate, the government is not in the business of providing housing, so that’s why we get incentives as investors to provide housing for people. And so it’s definitely when done right, you’re basically just helping out the economy by doing what the government wants you to do and as a result you get incentivized for it.

Tony:
And it’s so true because I think about even just one property that I put together, it’s like I have to hire an agent on both sides for the transaction to buy it. There’s escrow companies involved, there’s insurance agents involved.

Ashley:
In New York there’s attorneys involved.

Tony:
There’s attorneys involved. When I actually close in the property, I have to hire electricians and people to put in the flooring and roofers and landscapers and someone to build the pergola. We’re employing so many people. And even for us in our short-term rentals, once we’re alive, now people are paying money to come save our properties and there’s cleaners and there’s property taxes being paid and occupancy taxes. We are very, very much even with one single property simulating the economy. So I just wanted to get your take because I’m sure you guys have gotten that question before, but that troll just, sometimes I’m laying in bed at night like, yeah, right?

Ashley:
Disclosure, it’s me because I know it bothers them so much.

Amanda:
Yeah, I do. I think SCPA suit, because we’re also on social media and we get that too. You’re the bad person helping rich people to avoid taxes.

Matt:
I mean it’s no secret that the tax code favors investors, business owners, but it’s up to people to change their facts. Are you willing to change the facts to take advantage of that situation, that strategy? And that’s what it really comes down to.

Amanda:
When I think for us SCPA suit, we see it when it works out well, the law does impact your decision as an investor. When they give us better depreciation rules, then we’re more inclined to buy more real estate or to improve on the property, which then just makes a better experience for the tenant. So yeah, I think when it works well together in the intended way, it actually helps everyone out. But I think some of those comments come from people who don’t understand. On the surface level, they feel like, wow, why do you get the better?

Tony:
We’re just getting free money it feels like from the government, right?

Ashley:
Now are there some other maybe TikToks that you have watched where there are some of these, not exactly backlash from society in general, but maybe just myths that are going out there or information that so-called influencers are spreading about taxes and the advantages and different things maybe you could write off that maybe are a gray area or not actually true that we should be aware of?

Tony:
And the reason we want to highlight this guy is because I mean a lot of people right now get their main source of information is from short form content and you don’t have to have any sort of certification to make a reel or TikTok about something. And if it gets enough views, enough people see it, enough people think that it’s true. So we would just want to kind of lay the foundation for what is true versus what isn’t true. I’ll give you an example. One of the ones that I saw recently, it was a well-known entrepreneur and he was talking about how he had this very expensive suit on and he just put his logo on the inside of his jackets. I know that guy. Yeah, on the inside of his jacket suit. And he’s like, oh, because I did this, this is now right after my business.
Is that a true statement?

Amanda:
No. So the true statement is that if you have, let’s say a polo shirt and you put your logo on it where people can visually see it, then yes, we’re using it as marketing purposes. But clearly when you just put it in the sleeve or inside your jacket pocket, who’s going to see that and what part of that makes it a business deduction? Unless you’re in the business of selling those suits, sure. But just a normal day. And I think that’s what a lot of what we see happening on TikTok and Instagram is they take real tax law, but then they spin it in a way to make it somehow a loophole or easier. But it’s losing the original context of the law. And that’s what we’re seeing, unfortunately, because you don’t have to be licensed to give out –

Matt:
Tax advice.

Amanda:
New tax advice.

Matt:
So Matt – Similar situation as a vehicle, same thing. People put their logo in a car and all of a sudden, it doesn’t matter if I don’t drive it 100% of the time, now it’s a tax deduction. That’s farthest thing from the truth. Obviously you still need to use your vehicle for business purposes, but just because you got a logo on it doesn’t mean everything’s a business model.

Ashley:
So is that one of the biggest things you’re seeing that maybe are one of those discrepancies or myths as write-offs that people are considering advertising their business in certain ways that really aren’t?

Amanda:
Yeah. I think like Matt was saying, people tend to think if I put a logo on it, then it is what it is. But you still have to look at… Another one I think we hear people talk a lot about is Augusta Rule where you can rent out your home to your business for 14 days and not pay taxes on it. The strategy by itself is valid. The tax law does allow you to do that. But I think what often goes wrong is the implementation of it, then people just think, oh, okay, I can just say I rented it to my business and not really look at what did I rent to my business for? What was I doing?

Ashley:
You had a 14-day camp with all your employees.

Matt:
Training camp. They were all staying at my house.

Amanda:
14 days.

Matt:
Yeah.

Amanda:
We actually had a client who said they were going to use the role, but no one was allowed to go to their house. So they’re just using their house to record. They were doing a Zoom, hosting a Zoom to charge the 14 days. But I’m like, well, you can just do that in your home office. As a home office, I’m kind of doing the same thing. But to say that you need your entire house for a Zoom video unless you’re live streaming.

Tony:
Show up the whole place.

Amanda:
So I think a lot of those things are either paying your kids or using a trust, there’s validity, but it’s just really about how do I actually use it correctly and not just blindly follow an influencer saying I could do it without knowing the details of what has actually happened.

Ashley:
Okay. So what should we be doing to actually document these things correctly? You’re saying don’t just slap a logo on something or is there different procedures we should be following so that if we are audited, here’s something we can at least show. Example, the Augusta rule, how are you documenting that?

Tony:
Is there an app? Is there an audit proof app where it’s just like, “Hey, here are all the different deductions you’re trying to take and here’s the way to track it correctly?”

Ashley:
If not, let’s create that.

Matt:
Let me trademark that.

Amanda:
Auto deduction protection app. Yeah, I mean it’s really interesting. I think different types of expenses and write-offs, there’s different ways to document it. So if we’re talking about Augusta rule, we have to be able to show reasonable rent. So that depends on how big your house is, what you’re using it for, are you charging by the hour? We can simply go on peer space, for example, to figure out what are other similar properties charging for the hour. And then I’m going to have documentation to show what is the business renting it from us. So for us, if we’re having an employee training, okay, what’s the dates? Make sure the money actually moves from the company to me.

Matt:
Got notes from the meeting, obviously the training that people are, you’re taking notes, you’re implementing them a week later, whatever, right?

Amanda:
Yeah. I would just say the simplest thing is everything you do from that context is to think about how would documentation work if it wasn’t me and my own company. So if I was renting my house to Tony, what are all the things that I would want to make sure he’s paying me reasonable rent? I would want to make sure he signs something. I’d want to make sure he actually pays –

Matt:
Well, we would charge him above market.

Amanda:
Yeah, above market. And so the same thing, paying your kids, all the same. How much would I pay if it was Ashley’s kids? That has to be reasonable.

Matt:
Yeah, the meetings have to take place. If you’re paying your kids, the kids actually have to be working. It’s not just, oh, I can give them $15,000 because that’s tax-free. No, you actually have to go through and do the process. And so I think it goes back to planning and who are you working with? Are you working with… Well, one, are you doing it yourself? Is this DIY or is this your meeting with a tax strategist or you’re meeting in April for last year like, “Hey, can I do income shifting from last year?” I was like, no. So I think working with the right people can help you put those guards in place, obviously.

Ashley:
I got one more question on the Augusta rule, then we can move on. And this just kind of came to me as something I haven’t thought about before, but is actually a big money near me where a lot of people do this is renting out their homes and their yard as wedding venues. So does that mean you could rent out to a wedding venue for 14 Saturdays and have that money tax-free? Because that is big money by me. You’re getting into a lot.

Matt:
Yeah. I mean, that’s what the law was intended for, like the Augusta Golf Tournament, same ideas. Yeah, you could rent it out for 14 events and obviously you can make a lot of money that way. Or we were talking earlier today at our workshop, just maybe you live in the area where the Super Bowl’s coming or something, and it’s like you could rent it out for four days and make a killing and totally tax-free.

Tony:
Does it not have to be 14 consecutive days? Oh, it’s just 14 days at any point.

Matt:
Yeah, that’s what

Ashley:
I was asking about the wedding.

Tony:
I always thought it had to be a consecutive day.

Matt:
Another misconception too is it’s 14 days or less. So if you hit 15 days, it’s all taxable. It’s not just an extra day. It’s important that people understand that if they’re going to, like what you’re talking about, I’m going to do it at X number of times.

Amanda:
Okay. And we have clients too who when they travel for an extended amount of time, they’ll rent out their primary home on Airbnb. So that’s the same concept. If you’re home, you rent it out for 14 days or less, then you don’t have to pay taxes on any of that income too.

Tony:
What are some other maybe bigger misconceptions that you’re seeing in terms of tax advice that people should be aware of right now?

Amanda:
I’m seeing a lot of information on social media about trusts. So always the thesis is –

Tony:
Can you define a trust just for people who aren’t familiar with that?

Amanda:
Yeah, trust is a type of an entity. We have LLCs, we have partnerships, we have corporations, and then there’s trust. So a lot of the content talks about how if you have an LLC or a corporation, you’re doing it wrong because you should do a trust and the trust somehow magically makes all of your income tax-free. And it’s a huge misconception because when we talk about trusts, trusts are taxed one of two ways. One way is disregarded, which means we don’t even care. It’s the same as if you still own the assets, you have all the income, all the expenses. So from that context, of course, there’s no additional tax savings, same as me. Or the trust could be its own taxpaying entity, in which case you don’t pay income, but the trust still has to pay income. So I think there’s a lot of misconception when people say, “Well, if you have a trust, you don’t pay taxes.” Well, you don’t pay taxes, but your trust is paying taxes.

Ashley:
So your properties, your cash flow from those properties are still being paid to taxes.

Amanda:
Yeah. The trust and the trust rate, tax rates are less favorable than individuals. Interesting. So a lot of times you end up paying more taxes. I think it just sounds so sexy.

Tony:
Sexy and here’s this crazy secret.

Ashley:
I mean, really is one of the big benefits just for your kids.ate planning,

Matt:
Transferring assets to another generation, things like that. I mean, it can be used for other things, but that’s one of the main purposes for sure.

Tony:
One of the other questions that I have is people feel that they have to have these really complex legal structures to take advantage of any of the tax benefits. But let’s say that I’m just Tony and I start buying real estate, there’s no LLC, there’s nothing. I’m buying loans are in my personal name. Everything’s just me. Can I still take advantage of the real estate related tax benefits or do I have to set up an LLC to –

Matt:
No, that’s a great question because we get that a lot. I think it’s a misconception is that absolutely, you don’t have to have an entity hold title to rental real estate to get the tax benefits, the deductions. Basically how much income you pay, what you can deduct, what strategy, basically the same way you own it personally or you own it through an LLC that’s single member LLC, a partnership. Either way, the tax law doesn’t change. It’s more of a, why would you do that? You would do it for asset protection reasons. So if somebody slips and falls, they have to sue the owner, which is the LLC and not Tony. So yeah, I think a lot of people think that they have to have an LLC before they even buy my first rental real estate. I got to get this in place before I do that.
It’s like, no, you just have to go take action. Go buy.

Tony:
And that’s why I ask that question, Matt, because I feel like a lot of folks are like, “Hey, I need to get all these things in place first.” But you don’t even have a deal yet. Go get the deal first and then figure out how to asset protect, but you don’t have any assets yet.

Amanda:
We don’t have assets. And we unfortunately as CPAs, we see that a lot where somebody goes to a conference, not BiggerPockets, but some other conference where –

Matt:
Full disclosure, not BiggerPockets.

Amanda:
And they are told they have to have all these entities, a baby LLC, a holding company, and a management company, and a nonprofit. And so they spend a ton of money forming these entities. And like you said, if at the end of the year they still don’t own anything, well, guess what? Every entity still has obligations to file a tax return, to pay the state, to pay the attorney. So we actually tell our clients the opposite. Let’s not hurry to do it. Let’s find out what are you going to buy? Where are you going to buy? When we’re close to acquisition, then let’s form the entity so we’re not pre-spending money that we don’t need.

Matt:
Yeah. Another way to look at it too, it’s always a bad sign if we ask a question like, “Well, what’s that entity going to be used for?” And they can’t explain it like, “Well, I think they said it was going to be this.” All right, you already know you’re in past what you need.

Ashley:
Are there any other myths that you can think of or fleshy things?

Matt:
One that we’ve seen recently is the… Obviously we talk about short-term rentals a lot, and the one we’ve seen recently is the buy a property, close on an air in December, you don’t even have to furnish it. You can rent it out for one day to –

Amanda:
The seller.

Matt:
The seller, somebody else. I don’t know. Some related party of some whatever. It’s just rent it for one day and now I have a short-term rental. And then January 1st, you can turn it into a long-term rental. There’s aspects of that that are true, but when you put it all together like that, that’s not the intent of the rules. The intent of the rules that you are renting it out as a short-term rental. I don’t know who rents out unfurnished short-term rentals.

Tony:
Can I give you a counterexample to that? Because sometimes you’re the end of the year, we’re recording this in October, near the end of the year, we maybe buy a property that isn’t designed the way that we wanted it to. There’s still furniture in there. It’s still a safe and usable space. And say I closing a property on December 15th, I spent a week there getting some version of it set up. I hit my 100 hours to be able to qualify. I have someone check in, maybe one or two people check in, average iteration is seven days or less. And then on January 1st, I shut it down to finish off my setup. Is that strategy fine?

Amanda:
Yeah. Yes, because in this year you had a valid rental property. With furnishing, you had guests coming in and out, paying fair market value rent.

Ashley:
Two star reviews,

Tony:
But… Very unhappy that they stayed there, but the IRS doesn’t care about that part.

Amanda:
And I think everybody, it’s so interesting because short-term rental is a loophole in itself. It’s where people who are W-2 income earners and they don’t have to quit their job and real estate could really be a side hustle and they get all the depreciation and write-offs. But again, the original intent of the law is great, but people try to add a loophole to the loophole and just say, “Well, actually, who said we need furniture?” Well, I mean –

Matt:
Who said we need tenants?

Amanda:
The public says. If I’m paying for STR, then I’m expecting to have a place to

Tony:
Send furniture.

Matt:
And it’s not to say that your property can’t be a short-term rental that gets turned into a long-term rental or mid-term rental. Every tax year does stand on its own. But again, what we tell people is if you were to get audit for some reason and they audit 2026 taxes, well, they’re going to ask for a copy of 25 and they’re going to ask for a copy of 27, and all of a sudden they see that your property was a long-term rental for 365 days. Just seems like it begs them to want to just dig deeper and get into it. So we tell clients, “Hey, you can turn into long-term rental, but maybe not do it January 1st. Maybe let it play out for as a short-term rental for a few months and then the market changes or whatever.” So there’s ways to do it, but it’s –

Ashley:
You could do the Airbnb experience though, like a squatters experience. You’re moving into a vacant home if there’s no furniture in the short-term rental, so you don’t have to buy the furniture.

Tony:
We were saying sell it as an experience with experience.

Ashley:
You move into a vacant home with no furniture or anything.

Tony:
No running water, no lights.

Ashley:
The utility shut up.

Amanda:
Parents will pay for that experience for your kids who they’re not doing well in school.

Tony:
We’re going to book this for you. For folks who aren’t familiar though with the short-term rental tax loophole, how do short-term rentals differ from traditional long-term rentals in the eyes of the IRS? And why are so many high income earning individuals focused on short-term rentals right now?

Amanda:
Well, because the traditional rule for regular rental properties is if you create these tax losses through write-offs and depreciation, you or your spouse, if you’re married, one of you has to be a real estate professional if you want to use the losses against W-2 income. But to be a real estate professional, you or your spouse have to basically have more hours in real estate than your job. And so if you’re talking to a couple who are both high income earners working at a job, it’s almost impossible for them to be able to use long-term rental losses against W-2. But for short-term rentals, it’s different in that you don’t have to be a real estate professional. So you could, as long as you meet material participation, and like you said, that could be as little as a hundred hours as long as nobody else has more time than you.
So real estate could really be a side hustle for you, and you could be able to use that to offset W-2 income. So that’s why it’s termed a loophole, because it goes against the traditional rule of being a real estate professional.

Matt:
It’s almost like they look at it like it is a business obviously, but instead of treating it like in that rental real estate world, they treat it as like a business and you can show that you’re materially participating in the business and you’ve created these losses, then you can use them.

Tony:
Let me ask, I know I get this question a lot, but it’s like if we go back to that same example of like, “Hey, I get the property set up, I get my couple guests in, and then on January 1st, instead of turning into a long-term rental, I pass it off to a property management company.” Is that fine in the eyes of the IRS or should we also hopefully maybe extend the self-management a little bit further?

Amanda:
I mean, I typically recommend, I mean, technically under the law, it is a year by year. Every year, is it a short-term rental or not? Did you meet the hours or not? But for best practice, we typically recommend our clients, especially if you put it in service at the very end of the year, is to try to self-manage it for a couple months. How many months is it safe? I mean, it’s hard to say, but if you managed it for one month, it’s better than none. If you did three, it’s better than two. So it’s kind of up to how much you’re willing to do. I mean, you guys know when we talk about short-term rentals or real estate in general, we’re not saving 500 bucks in taxes or a thousand. Sometimes it’s 30,000 or 50,000 or you’re wiping out all of your taxes. And so to do a little bit more work for a couple months just to make sure you are safer if you’re ever audited could go a really long way versus what if you have an aggressive auditor who then disallows it because you turned it over to a management immediately on January 1st.

Tony:
Aside from the short-term rental tax loophole, if I’m a high income earning W-2 employee, is that the best tax strategy right now to reduce your income or are there any other strategies where you guys like, actually this might stack up just as well or if not better than short-term?

Ashley:
And it doesn’t have to be real estate.

Tony:
It could be – Even just anything outside.

Amanda:
I would say if real estate, then you can always marry a real estate professional.

Tony:
That’s always a good one.

Amanda:
If you’re single. But I mean on a serious –

Matt:
R-E-Pmatch.com.

Tony:
We just came up with two great business ideas on this podcast. We got the app. The dating connection and the audit app.

Amanda:
Yes. But I mean, the reality is we do have a lot of clients who are married couples both working. And when you do an analysis, sometimes it makes more sense for one of them to stop working and build the real estate portfolio because you can come out ahead where, okay, if somebody was making 60,000 or less and they stopped working, they could save 80 or $100,000 in taxes by not working. So that is something to consider if we’re talking about real estate. But I guess, I don’t know, investment

Matt:
Wise… Outside of real estate, we have high income clients that do invest in oil and gas drilling partnerships and looking for oil to earn royalties. One of the reasons from a tax perspective they do that is because they do let you take a big write-off in the first year and you can deduct it against your W-2 income even though you’re not doing anything for the oil, you’re obviously not drilling it yourself. So that’s one of the rare exceptions in the tax code that makes it a tax efficient investment. Obviously you’re investing in to make money, that should be first and foremost, obviously, but that’s one that we see.

Amanda:
Yeah. But oil drilling is not as –

Matt:
Sexy?

Amanda:
No, not as safe as real estate.

Ashley:
Yeah, I watch Landman.

Tony:
I haven’t seen that. Is that with Billy Bob Thornton?

Ashley:
Yes.

Tony:
Yes.

Amanda:
It’s a depleting asset. It’s a good

Tony:
Show.

Amanda:
It’s a depleting asset. I mean, traditional stuff for high income earners, 401ks and health savings account, all those things that are not business related, but just saving for your own future, saving towards your health future. Those are all really good. We have clients who are pitched all types of different investments, film. I don’t know if you guys have seen those on TikTok, film investing or crypto mining. Heavy equipment I’ve seen. Heavy equipment. All those are kind of the same pieces as real estate where we put some money in, there’s leverage that we get, and so we take on the debt and we somehow earn the hours in that investment asset and write it off. But I always tell our clients, outside of taxes, you have to really understand what’s actually going on. And if we use heavy equipment as an example, yes, we can write it off, but that is actually an asset that is depreciating.
I’ve never heard of an equipment that became more valuable to him either. And so it’s just a very different thing. For real estate, when we take on debt, most of the time is non-recourse. So the worst thing, bank takes the asset. But in all, I don’t want to say all, but most all other investment classes, you have to take on a personal guarantee. And so that’s the risk. Well, that’s also a sexy investment, but am I willing to take on additional debt where I’m on the hook for? And once people understand all those different intricacies, they usually just say, “Well, I think I’m just going to have more real estate.”

Ashley:
Now, before we wrap up here, is there an example of maybe another job industry? Because you work with a lot of real estate investors. Is there another job industry that maybe a lot of people come to you for that’s maybe to offset their income besides just a standard W-2 high income earner that’s maybe looking for things like this?

Matt:
Yeah, we have a lot of business owners come to us that are doctors, dentists, attorneys, service providers, businesses like that that make a good living obviously, but are looking for tax strategies for the business itself. It actually transitions to tax strategies for the individual too. But that’s the important thing is looking at the whole picture. What can we do to help you in the business? What can you do to help you personally? So yeah, there’s definitely people like that where we can talk about different strategies for the business too.

Amanda:
Yeah. If you’re a business owner, one of the levers to look at is does it make sense for me to own the property where my business is being operated out of? So dentists owning their own medical building, doctors owning the medical building, things like that. If you are operating a business where you own the real estate, a lot of people don’t know this, but you actually don’t have to be a real estate professional, then you can use the losses from the building directly against your active income. Interesting. It’s called a grouping election in the tax world where I’m saying, “Well, I have my medical business here, but I have my rentals in an LLC over there. I’m going to group it together for tax purposes, so one incomposite.”

Ashley:
Interesting.

Matt:
So that works really well when the tenant is obviously your medical practice and you own another entity, you’re setting it up that way, one, for asset protection because you don’t want to segregate the real estate and the liability from the business. But then there’s that way You can still utilize the benefits of the depreciation.

Amanda:
Oh, I will say we do. For some reason, in the past couple years, we’ve had more influencer clients on social media and a lot of them, because influencing is not real estate, so they would have to be a real estate professional doing short-term rental loophole. And short-term rental loophole works really well for those people because they already have a captive audience on whatever their content is. And so it’s much easier for them to also

Tony:
Showcase the properties

Amanda:
And just a lot of write-offs in general.

Tony:
On that note, you guys talked about different clients coming in. If I’m a rookie who’s maybe shopping for my first CPA, my first tax strategist, because you talk a lot about how do you find a good agent? How do you find a good lender? Very rarely do we talk about how do you find a good tax strategist? So if I’m a rookie and I’m sitting across the table from someone, what questions should I be asking them to know if they’re actually a right fit for me as a real estate investor?

Matt:
I mean, I think one question is, I guess one question not to ask is, do you work with clients in real estate? Because they’re always going to say yes because they’re going to have somebody who owns real estate. More it’s like, what are your successful real estate investors doing? If you’re trying to get into some avenue, if I’m trying to do the short-term rent, what are your successful short-term rental investors doing to make money? What are they doing to save tax? Whatever the question might be, because then you’re forcing them to elaborate and you can quickly tell whether they can talk to talk or not. I think that’s one tip that has worked well for a lot of people that we’ve talked to.

Amanda:
Yeah. And you also just want to know whether they invest in real estate because real estate people, we have our own little language of acronyms and stuff and just very different creative transactions that I know you guys talk about a lot. So you never want to be the person teaching your accountant real estate or taxes or strategy. So just give me understanding, do you invest in real estate? Just talk to them like you would any other investor. I think you’ll quickly be able to see, do they know what you’re talking about or they just have no idea? It’s kind of a different dictionary.

Ashley:
I’ve been somewhere where I was with someone and they were at their accountant, it was a new accountant for them and I went with them

Amanda:
And

Ashley:
I’m just sitting there, whatever, but they have the screen, so it’s facing you as they’re doing your taxes right there. And so I asked about real estate professional status. I said, he has the hours, all this stuff or whatever. And I was like, it’s that little box right there that you check. And he’s like, oh, I don’t think I ever checked that. Let’s see what happens and check the box.

Tony:
Oh

Ashley:
Yeah,

Tony:
Your

Ashley:
Taxes

Tony:
Went

Ashley:
Down. Okay, cool. And I was just like, I think you should ever come here anymore.

Tony:
A little bit more than

Matt:
That.

Tony:
I’ve never seen that box before. Let’s see what it does. You definitely don’t want to hear it.

Matt:
We talk about sometimes people do the do-it-yourself TurboTax and it’s as good as the input you put in. So it’ll do whatever you want it to do if you answer the questions a certain way.

Ashley:
And he had even specifically asked when he called this place because his old accountant had retired when he called, he specifically asked, I have a rental property, do you do taxes with a schedule and stuff like that? And the person was like, “Yeah, yeah, yeah. No problem. Bring it in.”

Amanda:
And that’s the thing like Matt was saying, if you ask him, Hey, do you work with people who own real estate? The answer is always going to be yes. But then if you say, okay, what are your successful clients doing right now in real estate? And if their answer is, oh, well, one of my clients turned their home into a rental five years ago, then you know, okay, that’s who they determine as a successful investor. And if you are already way beyond, I’m renting out my home from time to time, then you just never want to be their biggest client or the one with all of the different questions and intricacies because then they’re just learning on you. So that’s the thing. We get clients like that sometimes where they come to us for real estate, but they also do manufacturing and they’re like, can you just do it?
Can you learn it? And I’m like, I’m saying no for your benefit. You don’t want me to learn manufacturing with you being the case. I

Tony:
Don’t want to do

Amanda:
That.

Tony:
So it sounds like when you shop for your CPA, it’s almost like in the medical field, how there’s specialists, you go to an orthopedic surgeon, you go to a cardiologist, you go to a neurologist, this, that, and the other. Is the tax strategy role the same way where you want to find someone who’s that niche down?

Amanda:
It’s so interesting you say that because that’s something I feel like we’ve been saying for so many years because we also teach pretty frequently at medical conferences and it’s so common. I’m a dermatologist and you’re a nephrologist and they all have their specialty, but then they work together. But in the tax world, no, very rarely do you have somebody who says, I’m a real estate CPA and I’m a manufacturing CPA because I think when we go through school, it’s like, well, you’re a CPA, you’re going to service everyone. And if you think of a traditional person starting out building their business, they’re going to take all the clients. It’s just money I’m not going to turn away. And I think that’s why, because in our society it’s so accepted that CPAs don’t specialize.

Ashley:
And too, it puts you, especially I feel like in my area, at least a lot of people go to their CPA to get their taxes done. They hire someone local where it’s harder. Okay, if you’re going to specialize on just this one niche, you’re very limited in your local area where if you’re nationwide, it’s a lot easier. But in my area, everyone goes very local too.

Amanda:
Well, that’s what even during our workshop today, one of the ladies came up afterwards and said, “Oh, I’m in X, Y, Z city. Do you have a CPA for me?” So I was telling her it’s not so much about being local, but you just want to find somebody who understands what you are doing. If it’s flipping, if it’s wholesale, if it’s rental real estate. Because also for real estate investors, we don’t always invest locally. People invest out of state where the cash flow is. So you need an accountant who understands multi-state, especially if you’re going to be in different locations too.

Matt:
And I think obviously post – COVID, it’s become a little more of a norm of working with people remotely. You send all your documents online. Moving the right direction, but there’s still the people that feel like they got to sit across somebody and prepare my.

Tony:
Your situation is actually a good thing to make sure that they check that

Ashley:
Box. Yeah,

Tony:
It’s a good thing. That’s got to be the scariest tax situation.

Ashley:
I mean, I did get an accounting degree, but I still feel like that wasn’t some degree I needed to know that that needed to be checked on that situation.

Tony:
What was the name of that tax firm? Was it like, we’ll figure it out together, tax firm LLC?

Ashley:
Honestly, I feel like it was like we got it or we get it.

Tony:
I’m pretty sure this is

Ashley:
Right. Well, Matt and Amanda, thank you so much for joining us today on Real Estate Rookie. Where can people reach out to you and find out more information about what you guys do?

Matt:
Well, thank you for having us. Super fun. Best place to find us is our website, which is keystonecpa.com. A lot of free resources on there and some good information.

Amanda:
Yeah. And you can find me mostly on Instagram, Amanda Han CPA. Try to put daily tax tips and financial tips as well to help people save on taxes, but also make sure we just make smarter money decisions.

Ashley:
Well, rookies, thank you for listening to this episode live from Orlando from BP Con 2026. We hope that you will join us for BP Con in 2027. You guys are missing out. I’m Ashley He’s Tony and we’ll see you guys on the next episode.


Help us reach new listeners on iTunes by leaving us a rating and review! It takes just 30 seconds and instructions can be found here. Thanks! We really appreciate it!

Interested in learning more about today’s sponsors or becoming a BiggerPockets partner yourself? Email [email protected].


Source link

How to (Legally) Pay Less in Taxes as a Rookie Real Estate Investor Read More »
AI Is Changing the Economics of SaaS Partnerships. Here’s How Founders Can Capitalize.

AI Is Changing the Economics of SaaS Partnerships. Here’s How Founders Can Capitalize.


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Now that SaaS has made software easier to buy and deploy, partners are moving towards lower-margin services.
  • By enabling partners to deliver tailored AI solutions built around customer workflows, data, integration and governance, vendors can unlock new, higher-value revenue streams.
  • To capitalize on this shift, SaaS companies must move beyond referral programs and build partner ecosystems that reward expertise, implementation and measurable customer outcomes.

A typical SaaS referral deal gives a partner 10-15% of first-year revenue, rarely enough to support sales, implementation and future growth. As SaaS made software easier to buy and deploy, much of the surrounding work became repeatable, pushing partners toward lower-margin services. Without a more profitable business to build around the platform, they will invest elsewhere.

AI gives partners something back

AI gives partners something SaaS gradually took away: high-value work built on the platform, shaped by the customer’s context and sold as expertise rather than access. Not every AI engagement will be unique, nor should it be. The reusable parts like connectors, retrieval patterns, evaluation frameworks and managed operations will become more standard. But the decisions that make an AI system useful do not travel so easily from one customer to another. Which workflow should change? Which data can be used? Where does human review belong? What counts as a good answer, and who is accountable when it is wrong?

That is where a strong partner has something meaningful to sell. A bank may need an AI-assisted compliance workflow with escalation paths and audit evidence. A hospital system may need an intake process that respects privacy, system permissions and clinical review. A law firm may need clause triage with firm-specific limits on what an agent can recommend.

The building blocks may be familiar, but making the workflow safe, useful and adopted is not. It relies on industry judgment that the partner has built from years of being the person the client calls when something breaks.

This is not an argument that every partner should go train a model, or that every SaaS company should suddenly become a services business. Most customer deployments will be about workflow design, permitted data, integration, evaluation, governance and adoption, not fine-tuning a foundation model. The point is simpler: AI creates a new layer of work above the subscription, and the partners best placed to capture it are the ones who know the customer’s business well enough to make that layer valuable.

Futurum Research’s 2H 2026 partner survey found that 71% of active partners named custom application development as a primary growth driver, even as sentiment toward packaged enterprise software weakened. But that does not mean every bespoke build will be profitable. It does suggest that customers are looking beyond generic software for tailored engineering and that partners see more room in services than in a shrinking resale margin.

Build a partner business, not a referral program

For SaaS founders, that changes the question from “How do we get partners to refer more deals?” to “What can partners build profitably with us?” Start by running the full math: referral and renewal income, plus the gross profit from partner-delivered implementation and AI services, minus the cost of acquiring and serving the account. If a partner can create a healthy contribution margin while making the product more useful to the customer, the program has a foundation. If it cannot, a higher referral percentage is just a more expensive version of the same problem.

The program should then make that work easier to do well. Give capable partners a sandbox that resembles production, not just a demo login. Train them on integration, evaluation, governance and escalation — not only on product features. Certify them against real use cases. Bring the strongest partners into the harder solutions early, before the vendor has decided every implementation detail in-house. That is how a platform becomes a place where partners can build expertise instead of merely resell a discount.

Measure the result accordingly. Referred ARR still matters, but it is only part of the picture. Track services revenue and margin where they can be observed, time to production, active use, product adoption, support burden, retention and the customer outcome the solution was designed to improve. Outcome-based incentives can work, too, if they are tied to milestones the partner can actually influence: a verified deployment, adoption by an agreed user group, a successful evaluation or a retained account after a defined period.

None of this removes the need for discipline. A vendor still needs clear data rights, guardrails, support boundaries and a view of who is accountable when a workflow fails. Partners need room to earn services revenue without creating a maintenance burden the vendor cannot support. Those are not reasons to stay with the old model. They are the operating details that turn the AI thesis into a business model.

The point is not that AI work will never commoditize. Some of it will, and it should. The point is that AI gives partners a larger, more defensible role while the work still depends on customer data, workflow knowledge and practical judgment. A program built around that role is harder to reduce to a commission table. It gives partners more reason to invest, gives customers more value from the platform, and gives the vendor something more durable than a better percentage to compete on.

Key Takeaways

  • Now that SaaS has made software easier to buy and deploy, partners are moving towards lower-margin services.
  • By enabling partners to deliver tailored AI solutions built around customer workflows, data, integration and governance, vendors can unlock new, higher-value revenue streams.
  • To capitalize on this shift, SaaS companies must move beyond referral programs and build partner ecosystems that reward expertise, implementation and measurable customer outcomes.

A typical SaaS referral deal gives a partner 10-15% of first-year revenue, rarely enough to support sales, implementation and future growth. As SaaS made software easier to buy and deploy, much of the surrounding work became repeatable, pushing partners toward lower-margin services. Without a more profitable business to build around the platform, they will invest elsewhere.

AI gives partners something back

AI gives partners something SaaS gradually took away: high-value work built on the platform, shaped by the customer’s context and sold as expertise rather than access. Not every AI engagement will be unique, nor should it be. The reusable parts like connectors, retrieval patterns, evaluation frameworks and managed operations will become more standard. But the decisions that make an AI system useful do not travel so easily from one customer to another. Which workflow should change? Which data can be used? Where does human review belong? What counts as a good answer, and who is accountable when it is wrong?

That is where a strong partner has something meaningful to sell. A bank may need an AI-assisted compliance workflow with escalation paths and audit evidence. A hospital system may need an intake process that respects privacy, system permissions and clinical review. A law firm may need clause triage with firm-specific limits on what an agent can recommend.


Source link

AI Is Changing the Economics of SaaS Partnerships. Here’s How Founders Can Capitalize. Read More »

Apple’s Cost-Cutting Push Is Coming for Employee Budgets

Apple’s Cost-Cutting Push Is Coming for Employee Budgets


Key Takeaways

  • Apple is cutting internal budgets as it seeks to avoid overspending on AI.
  • According to a new report, some Apple engineers have had their daily AI spending limits cut from $300 to $200.
  • Employees are divided, with some seeing the cuts as reasonable, while others worry they could signal broader cost reductions and layoffs.

Even Apple, the most valuable company in the world with a market capitalization of $4.98 trillion, is watching its AI bill.

The tech giant is tightening internal spending limits as it looks to cut costs, Bloomberg reported this week. Apple is reducing how much employees can spend on AI tools to lower costs while simultaneously working to make the technology central to its business.

Some Apple engineers saw their daily AI spending limits fall from $300 to $200 last month, per Bloomberg. The company is considering another reduction that could bring the allowance down to $100 a day for certain engineering groups.

Non-engineering teams also face steep cuts. Apple currently gives these organizations a $100 daily cap for AI use but is considering lowering the limit to as low as $25. Employees who need a higher budget to do their jobs can ask senior executives for an exception.

The spending limits apply to tokens, or the pieces of text and other data that AI models process to complete a request. Providers usually bill according to how many tokens employees use, with more sophisticated AI models typically carrying higher prices. Writing code or processing software can use a substantial amount of tokens.

Apple’s mindset

Apple wants employees to rely more on AI but spend less doing so, according to Bloomberg. The company’s tighter budgets highlight the tension between controlling costs and using AI to overhaul engineering workflows and other internal processes.

The trend isn’t limited to Apple. Across the tech industry, the enthusiasm for letting employees freely experiment with AI is becoming overshadowed by closer oversight of its cost. Companies now have to decide where to cut spending without sacrificing the productivity improvements they hoped to achieve by using the tools.

Bloomberg reported that Apple employees are divided over the lower limits. Some said that the $300 daily budget was more than what most workers needed. Meanwhile, others worried that the cuts signal a wider effort to reduce spending that could eventually result in job cuts.

These concerns have grown as Apple brings in outside consultants to review how the company operates and where it could become more efficient. Bloomberg previously reported in late September that Apple’s new CEO John Ternus, who took over on September 1, wants a faster, leaner organization with fewer layers of management.

Apple’s spending is rising

Apple’s bills are still climbing despite its internal push to cut costs. The company said this week that its research and development spending rose 32% in fiscal year 2026, reaching $45.8 billion. Higher infrastructure and AI expenses drove the growth. 

Other tech giants are also watching their AI spending. In June, Uber limited all employees to $1,500 in monthly token spending. The same month, Meta said it planned to cut employee AI usage by adding token limits. One month later, Tesla informed staff that it would cap employee AI spending at $200 a week. 

Key Takeaways

  • Apple is cutting internal budgets as it seeks to avoid overspending on AI.
  • According to a new report, some Apple engineers have had their daily AI spending limits cut from $300 to $200.
  • Employees are divided, with some seeing the cuts as reasonable, while others worry they could signal broader cost reductions and layoffs.

Even Apple, the most valuable company in the world with a market capitalization of $4.98 trillion, is watching its AI bill.

The tech giant is tightening internal spending limits as it looks to cut costs, Bloomberg reported this week. Apple is reducing how much employees can spend on AI tools to lower costs while simultaneously working to make the technology central to its business.

Some Apple engineers saw their daily AI spending limits fall from $300 to $200 last month, per Bloomberg. The company is considering another reduction that could bring the allowance down to $100 a day for certain engineering groups.


Source link

Apple’s Cost-Cutting Push Is Coming for Employee Budgets Read More »

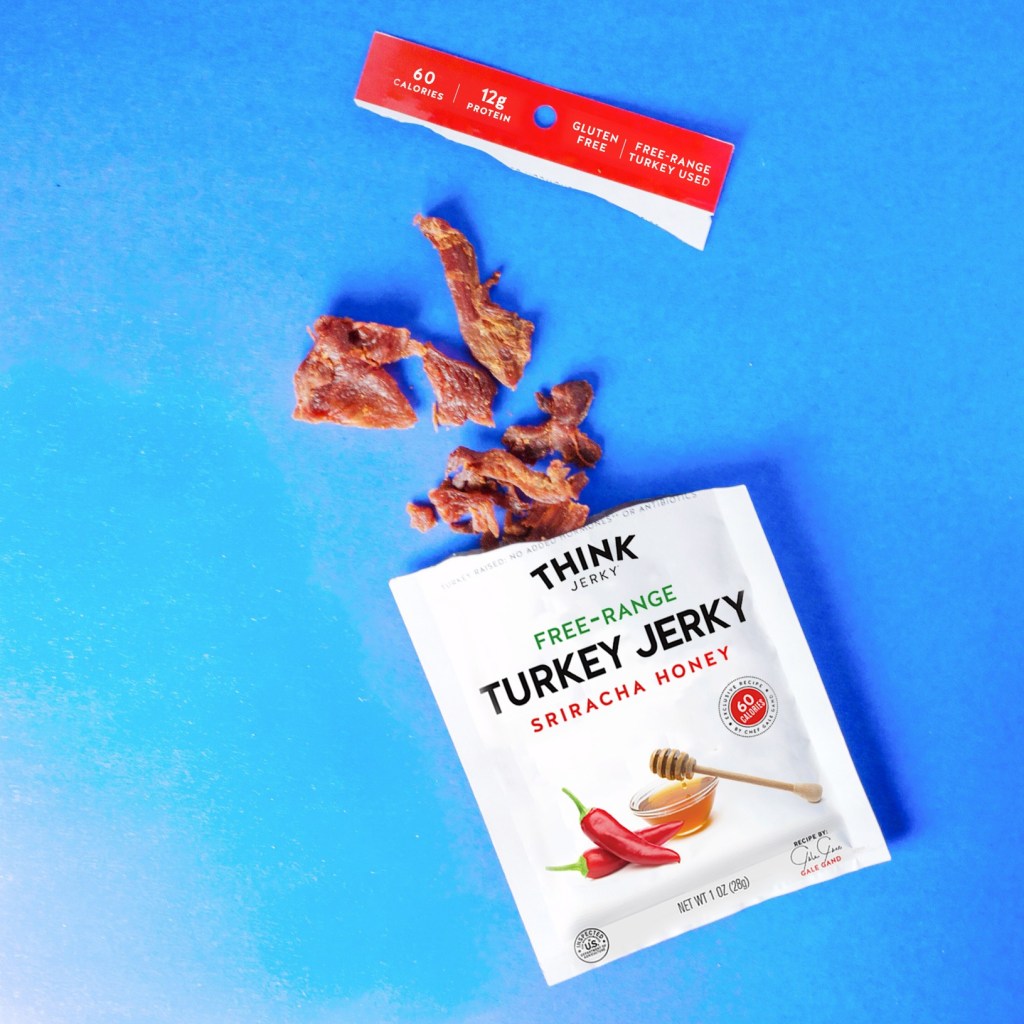
Elizabeth Holmes Ate Think Jerky, Changed the Business: ‘Wild’

Elizabeth Holmes Ate Think Jerky, Changed the Business: ‘Wild’


Key Takeaways

  • Hirsch founded Think Jerky, a meat snack focused on chef-crafted flavors, in 2015.
  • Elizabeth Holmes eats the brand’s honey sriracha flavor in ‘You Can See Everything.’
  • Sales spiked 345% — and Hirsch is committed to capitalizing on the unexpected virality.

On October 16, Ricky Hirsch’s meat snack startup Think Jerky experienced an unscripted marketing moment so crazy it’s “not even once in a lifetime,” the founder and CEO tells Entrepreneur. 

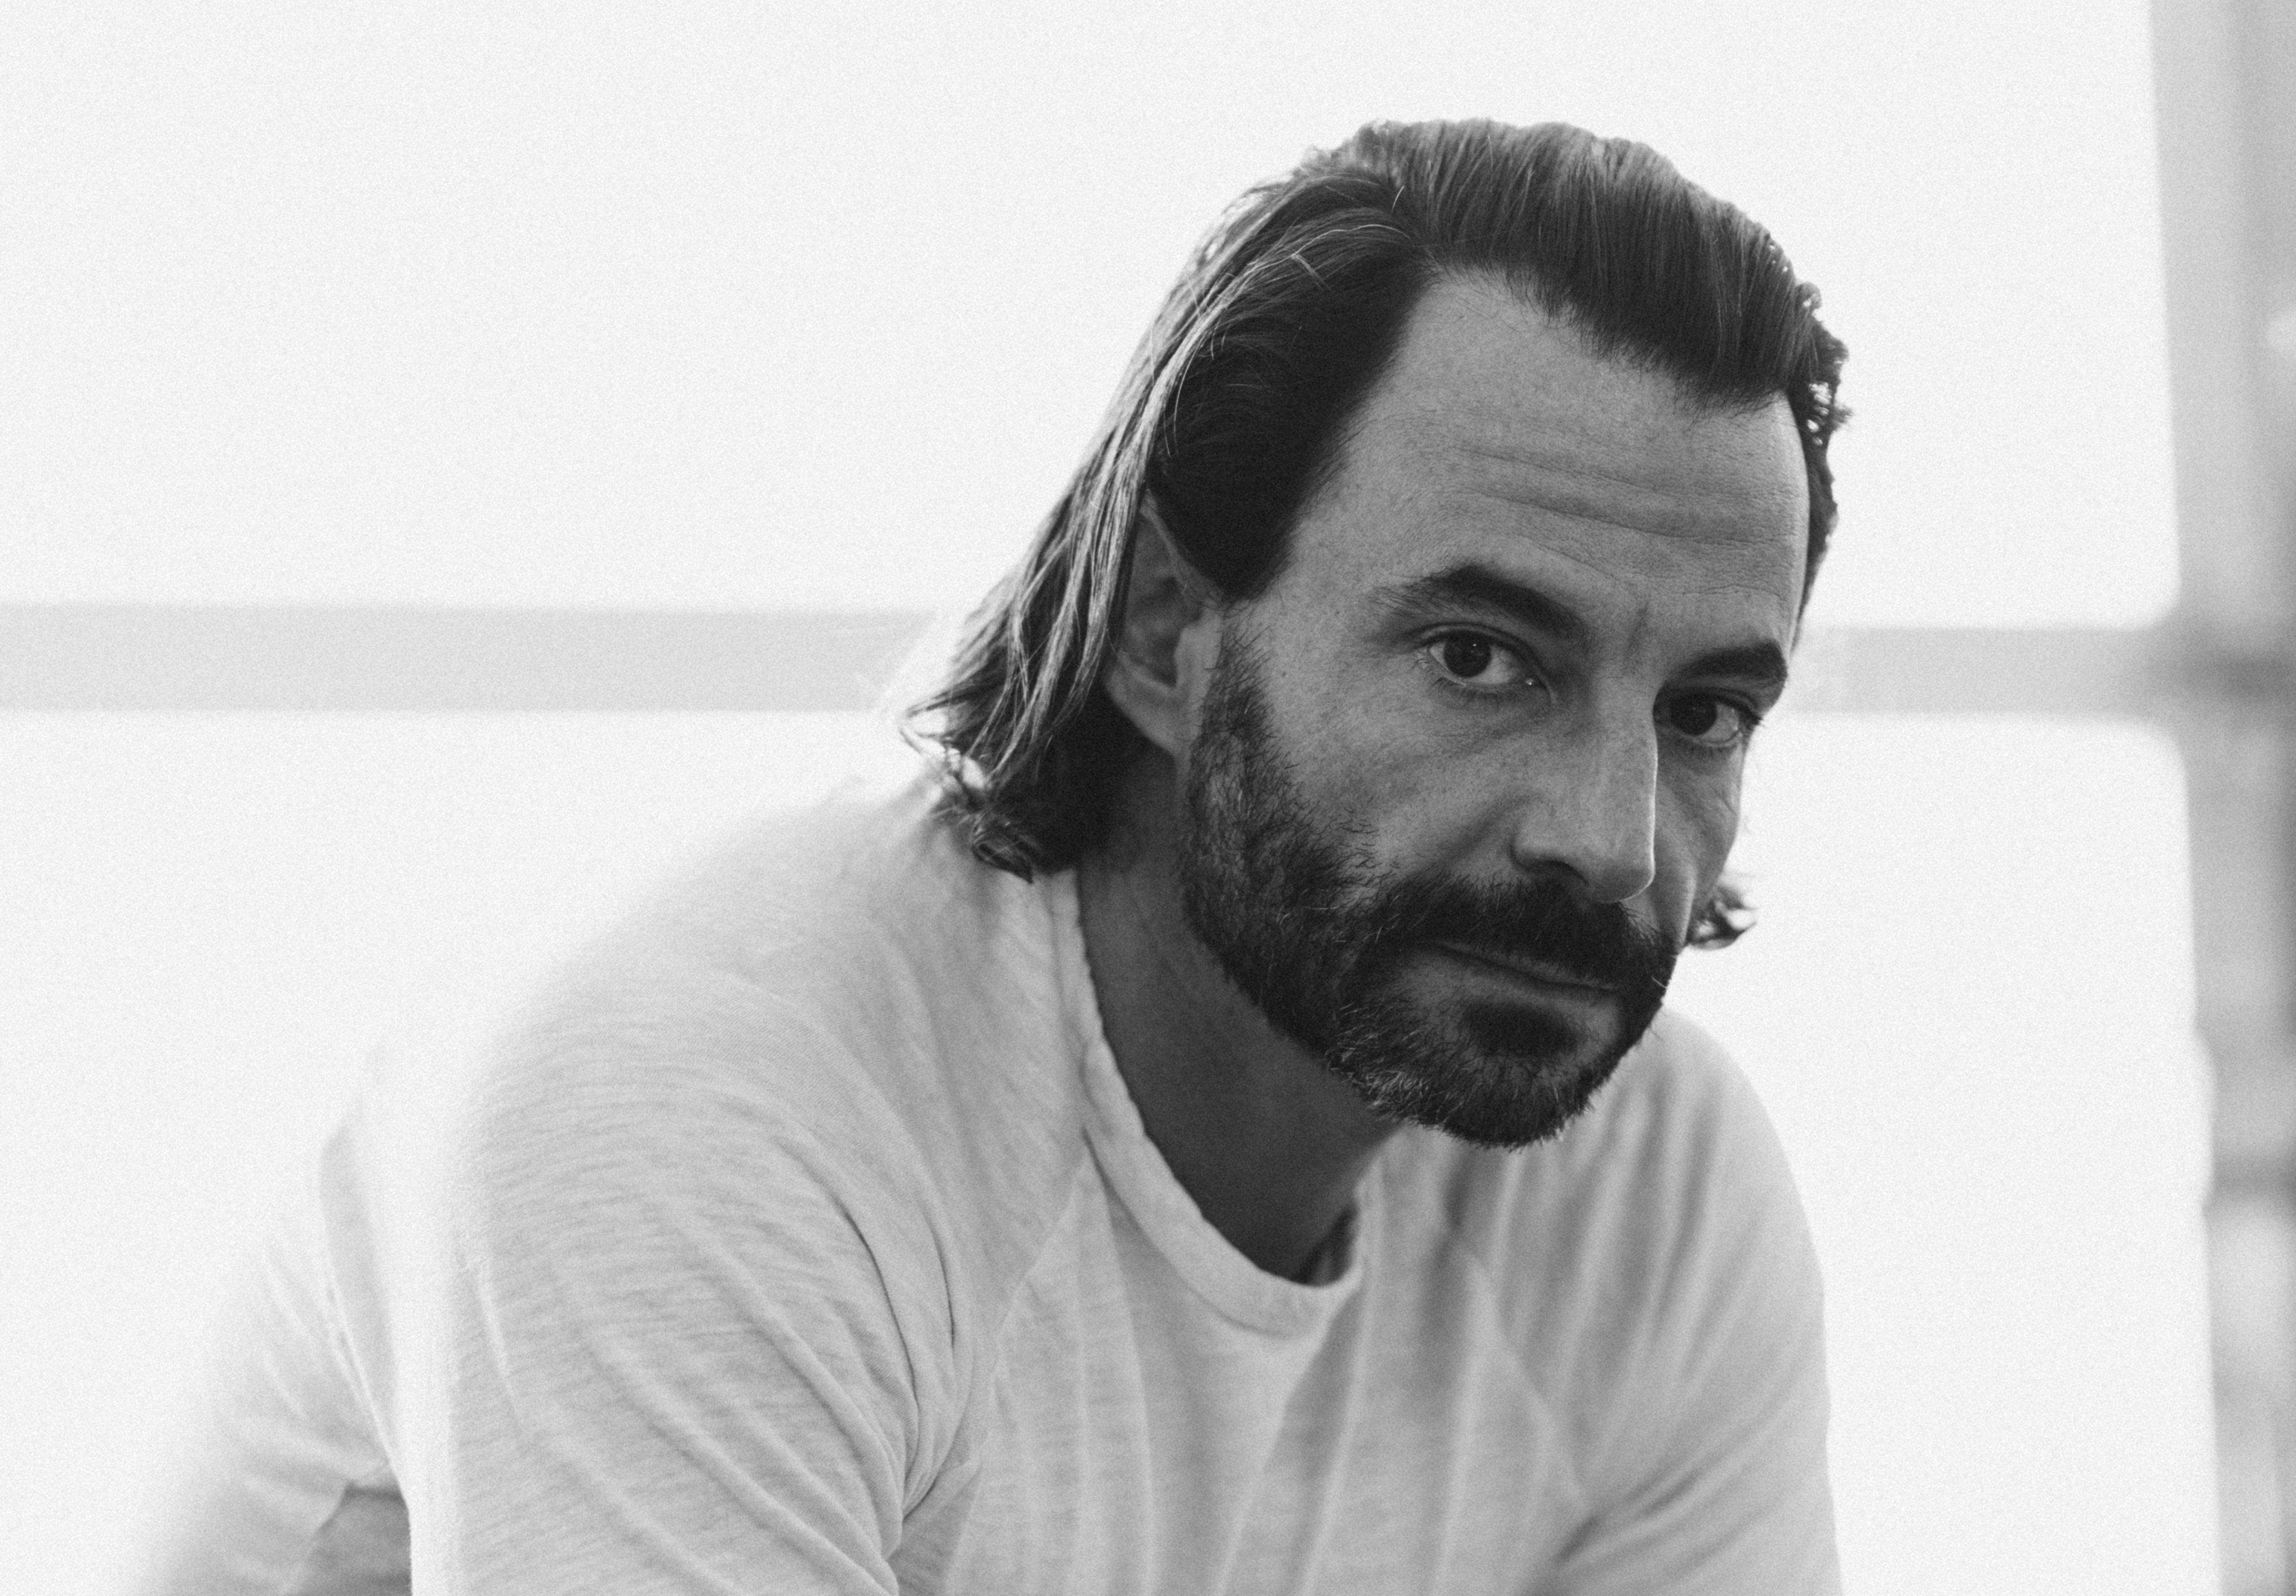
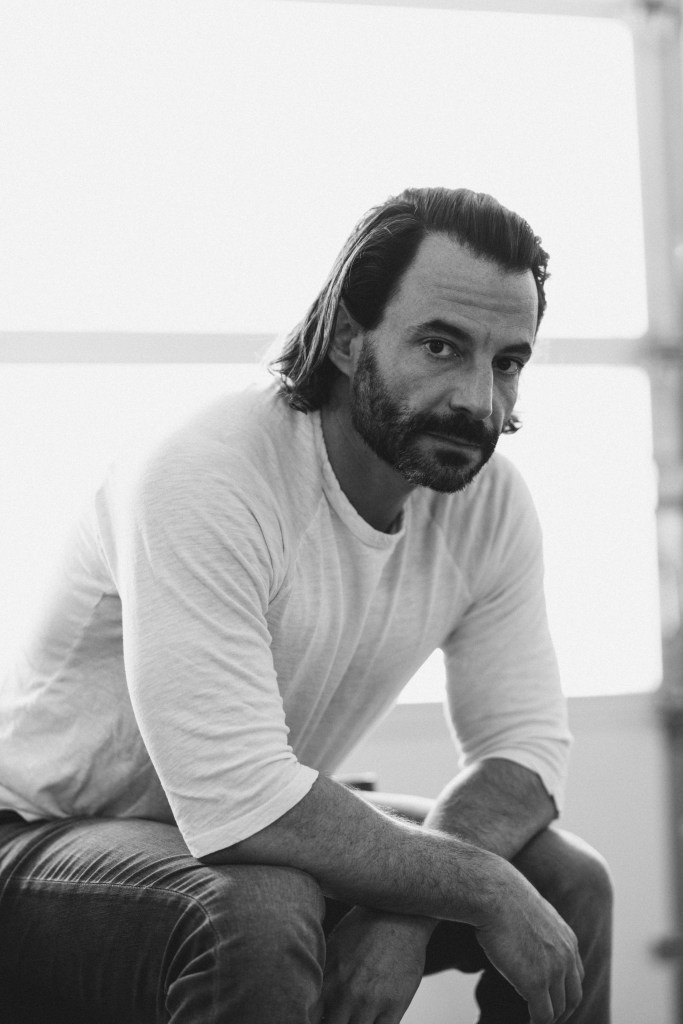
Founder and CEO Ricky Hirsch. Image Credit: Courtesy of Think Jerky

Hirsch launched Think Jerky in 2015, building on his finance background and creative inclinations to start a “cool” jerky brand with a minimalist design and unique, chef-crafted flavors. 

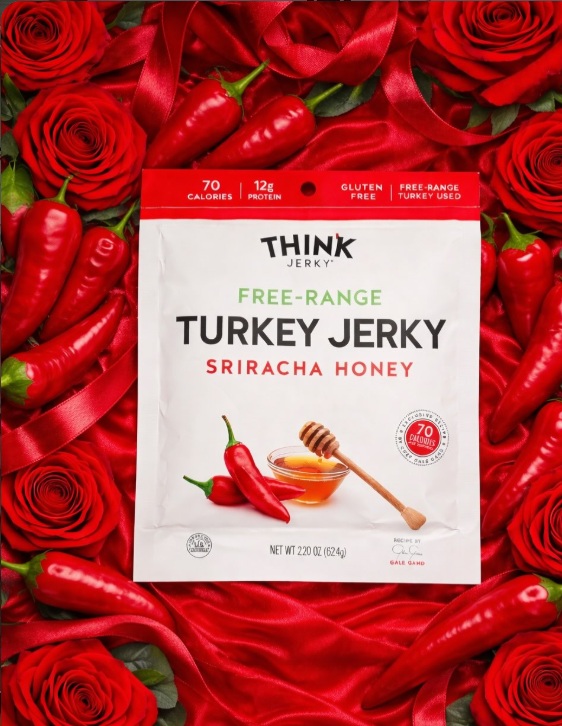
The brand’s sriracha honey flavor, created by Michelin-starred and two-time James Beard Award-winning chef Gale Gand, landed in the spotlight last month. 

It was completely unexpected. 

Think Jerky makes a cameo in You Can See Everything

Hirsch was watching poker on television at his home in Austin, Texas, when he received a text from one of his employees. 

She was in New York and had just attended a screening of You Can See Everything, Nathan Fielder and Lance Oppenheim’s A24 meta-documentary featuring Theranos founder Elizabeth Holmes in the lead-up to her federal prison sentence.

Holmes was convicted of one count of conspiracy alongside three wire fraud charges stemming from more than $140 million in investor losses in 2022.

“ I was familiar with Elizabeth Holmes,” Hirsch says. “I’m in the business world, so that always intrigued me. And I saw the Hulu series. I was not familiar with Nathan Fielder at all.”

Hirsch’s employee was “freaking out” over Think Jerky’s cameo, the founder recalls. 

Image Credit: Courtesy of Think Jerky

In You Can See Everything, Holmes requests turkey jerky from the prison vending machine. The scene is reenacted with Amanda Seyfried, who plays Holmes in Hulu’s The Dropout. At one point, the camera pans to the vending machine — “it’s like product placement, the best, most beautiful shot,” Hirsch says.

The film ends with Holmes and her husband Billy Evans eating Think Jerky. 

Handing out Think Jerky in front of the theater

Hirsch decided to see the film for himself the next day, but he still had no idea how much the on-screen moment would change his business. “I brought some jerky with me,” Hirsch says. “And when it came on screen, I was overwhelmed. I was like, This is wild.”

The founder walked out of the theater in Austin with about 30 bags of jerky in tow. He started handing them out to people — and they “were freaking out.” It was a sign of things to come. 

Within two weeks, Think Jerky’s honey sriracha sales were up 345% on the company’s website and 92% on Amazon. Someone posted on X that the Texas supermarket chain H-E-B had sold out of “the Elizabeth Holmes jerky.”

Image Credit: Courtesy of Think Jerky

Reddit forums dissected what Think Jerky might represent as a narrative symbol. (“They think it symbolizes manipulation or control. There’s all these theories”). Fans dressed up as the Think Jerky bag for Halloween (“You have to make that costume”). YouTube videos discussed it. Restaurants reached out for collaborations. People hawked fake merchandise. 

“If somebody wanted to pay for this publicity, it’s in the millions of dollars,” Hirsch says. 

Hirsch chalks up some of the virality to how the brand’s name — “Think” Jerky — plays right into the “wild,” layered film and becomes its own sort of small character.

Adding fuel to Think Jerky’s marketing fire

Now, the founder is determined to add as much fuel to the marketing fire as possible. 

But that’s a tall order for a fully bootstrapped company with four employees. “People are stepping up, our significant others are stepping up and all that, but we are not a big business,” Hirsch says. “We do not have a big team. We never raised money, which is very unique in my industry.”

Hirsch acknowledges that people might not remember Think Jerky’s logo or company name in five years, but they might remember the shot of that bag. So he’s doing his best to make it a meme and keep the conversation going. 

The team is going to San Diego for the Food & Wine festival. Gale Gand will make an egg dish (another humorous nod to the film) and top it with the jerky. The team is also planning lookalike contests, where they’ll hand out jerky and display a cutout of Holmes. 

Image Credit: Courtesy of Think Jerky

Continuing to lean into the viral moment

Sales remain strong, and Hirsch anticipates selling out. Think Jerky has about 60 days’ worth of finished inventory in reserve to meet the demand. 

Currently, the brand is revamping its website, which will be complete in about a month, for a “soft rebrand” that fully captures the product’s chef-crafted approach. Think Jerky is also launching new products, including a Thanksgiving turkey stick made with four-time James Beard Award-winner Andrew Zimmern. 

Looking ahead, Hirsch would be very interested in raising money for Think Jerky with the right partner. “ If Daniel Lubetzky wants to talk to me, I would love to talk to Daniel Lubetzky,” the founder says. 

Hirsch is excited to continue leaning into Think Jerky’s surprise breakout and explosive growth.

“ I thought it was going fade maybe, after the third weekend, but it’s growing,” Hirsch says. “People are reaching out, people want to collaborate. I want to introduce my creative marketing and hopefully bring our company to a new level.”

Key Takeaways

  • Hirsch founded Think Jerky, a meat snack focused on chef-crafted flavors, in 2015.
  • Elizabeth Holmes eats the brand’s honey sriracha flavor in ‘You Can See Everything.’
  • Sales spiked 345% — and Hirsch is committed to capitalizing on the unexpected virality.

On October 16, Ricky Hirsch’s meat snack startup Think Jerky experienced an unscripted marketing moment so crazy it’s “not even once in a lifetime,” the founder and CEO tells Entrepreneur. 

Founder and CEO Ricky Hirsch. Image Credit: Courtesy of Think Jerky

Hirsch launched Think Jerky in 2015, building on his finance background and creative inclinations to start a “cool” jerky brand with a minimalist design and unique, chef-crafted flavors. 

The brand’s sriracha honey flavor, created by Michelin-starred and two-time James Beard Award-winning chef Gale Gand, landed in the spotlight last month. 


Source link

Elizabeth Holmes Ate Think Jerky, Changed the Business: ‘Wild’ Read More »

This Violinist Became Snoop’s K-a-Month Ice Cream Taster

This Violinist Became Snoop’s $10K-a-Month Ice Cream Taster


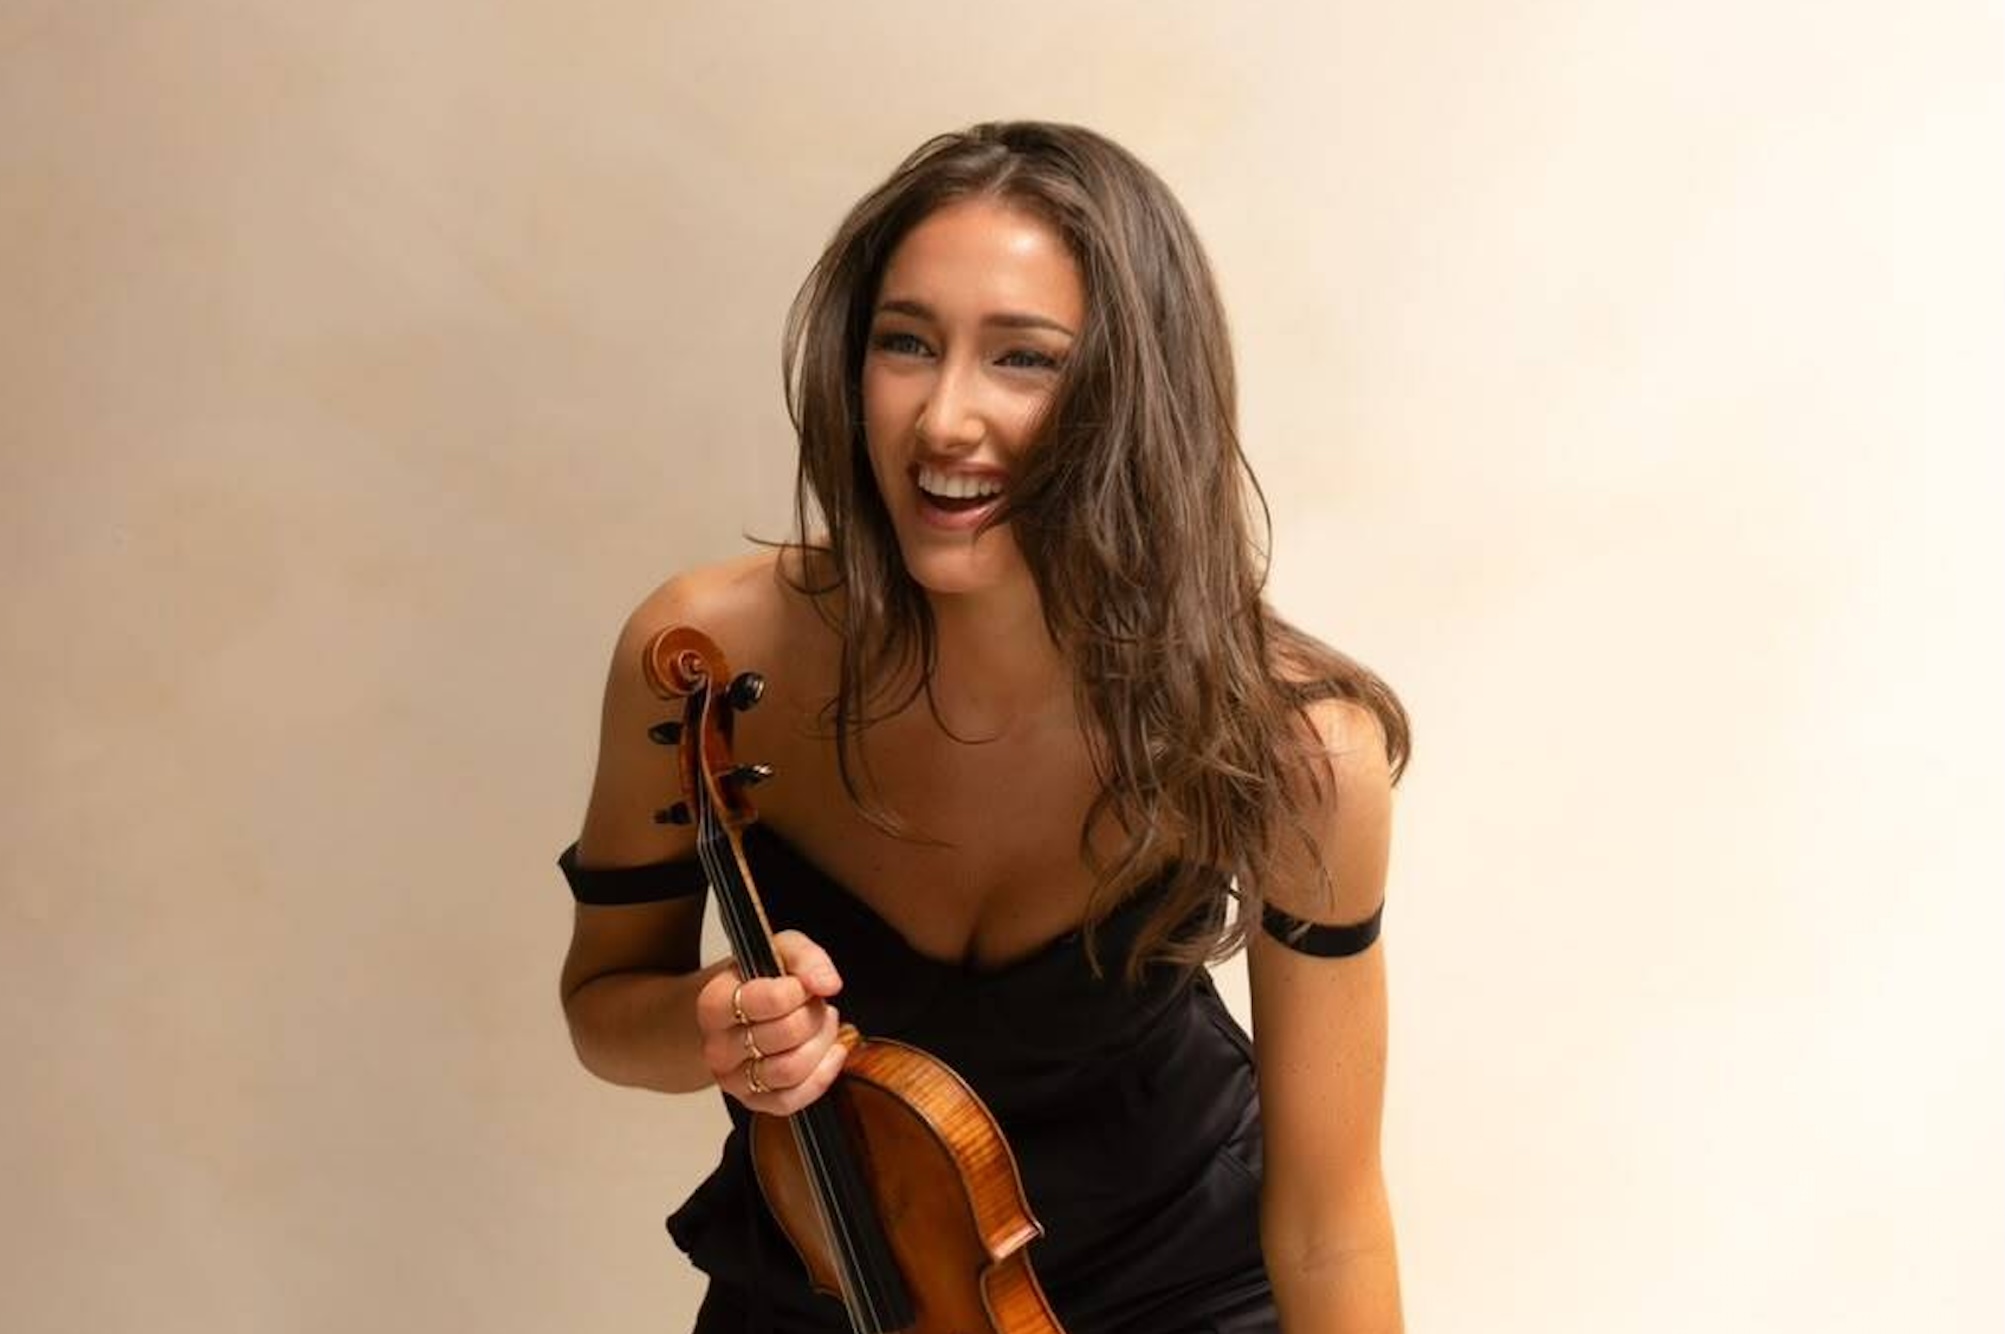
How did Annabelle Traves land the sweetest job on the planet? Let’s just say she pulled some strings.

The concert violinist, who has soloed at Carnegie Hall and the Sydney Opera House, was just named Dr. Bombay’s first International Ice Cream Taster. In August, Snoop Dogg’s ice cream brand put out a call for the job, which pays $10,000 a month. More than 350,000 people from 130+ countries applied through HR and payroll platform Deel, which ran the search.

Traves, an Australian based in Dubai, starts a three-month contract helping Dr. Bombay expand into new markets, dream up new flavors and create a Deel-themed ice cream. Entrepreneur caught up with Traves to talk about her latest gig.

What did you submit to beat out all those other applicants?
I decided to play to my strengths. Many of the other applicants owned dairy farms or had spent years researching dairy. I love ice cream, but I wouldn’t call myself a dairy expert, so I leaned on what I knew best. In my application video, I plucked a little of one of Snoop’s famous melodies on my violin. When I made the top 15, I doubled down with my own cover of “Young, Wild & Free.” I think that musical connection is part of what caught Snoop’s attention.

You’re already a very successful violinist. Why go after a gig like this?
The timing was perfect. I had just come off a world tour with André Rieu, and for the first time in years I didn’t have a schedule that I had to coordinate a year in advance. Then there was the ice cream, and who doesn’t love ice cream? And of course, Snoop himself. I love all genres of music and have always loved his, so the chance to bond with him as a fellow musician was hugely appealing.

What do you look for when you’re tasting a new flavor?
In one word, novelty. I want a flavor I’ve never tried before. Vanilla has been done a billion times. Dr. Maya, who develops the flavors at Dr. Bombay, introduced me to the idea that ice cream flavors develop over time. A couple of seconds in, a different flavor comes through. People talk about that with wine, but I’d never experienced such sophisticated flavors in ice cream until I tried Dr. Bombay. The nostalgia of the brand also stands out. Flavors like Sherbet take you right back as a 90s kid, and Peanut Butter Jelly Time does the same. I’d love to find flavors based on popular candies or afternoon snacks from those days.

How did Annabelle Traves land the sweetest job on the planet? Let’s just say she pulled some strings.

The concert violinist, who has soloed at Carnegie Hall and the Sydney Opera House, was just named Dr. Bombay’s first International Ice Cream Taster. In August, Snoop Dogg’s ice cream brand put out a call for the job, which pays $10,000 a month. More than 350,000 people from 130+ countries applied through HR and payroll platform Deel, which ran the search.

Traves, an Australian based in Dubai, starts a three-month contract helping Dr. Bombay expand into new markets, dream up new flavors and create a Deel-themed ice cream. Entrepreneur caught up with Traves to talk about her latest gig.


Source link

This Violinist Became Snoop’s $10K-a-Month Ice Cream Taster Read More »

The Unique Hiring Strategy I Used to Build a Global Team

The Unique Hiring Strategy I Used to Build a Global Team


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Relying solely on the talent in your immediate geographic area is a self-inflicted mistake. 
  • Although there is an entire global industry built to help companies hire remote talent, you don’t need to rely on it. 
  • As solopreneurs, we can hire in a more effective way if we are ready to build relationships in online communities. And it does not cost any money.

Solopreneurship, despite its name, is anything but a solo pursuit. As we find success in our agency work, we inevitably need to build a team that can help us serve our clients and expand our footprint.

As MVRK, my CRM strategy and implementation consulting agency, starts its seventh fiscal year, I’m very happy to say that my team is now composed of seven individuals who operate from six different countries. What’s more, none of us live in the three countries where we mainly do business (USA, Canada and the UK).

I have hired each of the individuals who are on the team myself. And I discovered them in a unique but repeatable way. In this article, I’m going to review the method that I’ve used to build those relationships with potential talent and share how I’ve been able to make them a part of my team. All with zero dollars spent.

Use the offshore recruiting industry — it’s an easy way to start 

For the first three years of running my business, I operated fully solo. But as I started to build success, I had an important realization: The clients that enjoyed working with me did not want to leave.

That meant I faced two options:

  1. Either I had to tell some of my clients that I didn’t want to work with them any longer. This didn’t feel like the right choice, because I really enjoyed working with all my existing clients.
  2. Or I had to find an additional pair of hands to assist me.

One of the projects that I worked on in my early years was implementing an entire Salesforce CRM system from the ground up for a Philippines-based recruitment agency. This agency was staffing talent in North America, so I knew I had a connection I could leverage to find that initial team member.

I defined the requirements, and that recruitment agency put some talent in front of me. From there, I selected somebody who I felt was going to work. I believe that I got quite lucky with my first hire because that individual is still a member of my team.

While I support the recruitment agency model and believe it works for many companies, the reality is that an agency is still a middleman that does not add a tremendous amount of value.  In my case, eventually, the individual in question wanted to continue working with me, without having to go through the agency. As a result, we formed a relationship directly.

Of course, it’s important to check any terms of service that you’ve signed before you make this kind of transition. But using an agency is not the only option. There is a way that you can leverage remote talent without relying on the offshore recruiting industry. It’s a little bit more work, but it’s a lot more rewarding for both you and the talent that you hire.

As we come to the end of 2026 and move towards 2027, you need to realize that relying on talent only in your immediate geographic area is limiting your ability to grow. Except for industries where in-person presence is required for regulatory or delivery purposes, there is no reason why you should limit yourself to hiring people in your city, in your state or province, or in your country.

This world is big, and there’s talent to be found in a lot more places than just your backyard. The best way that I have found to discover that talent is to go to the online communities where they hang out, share their knowledge and build a network. Crucially, these are also the places where they can discover you without tremendous costs.

I have found Reddit in particular is an incredible source of talent. What’s more, I haven’t spent a single dollar on advertising job ads or on recruiter fees. I’ve been able to build those relationships myself. Reddit has various communities, many that are specifically niched to your industry, and it is those places where individuals from across the world are hanging out.

To find talent via Reddit communities, I’ve built simple intake forms asking the right questions to vet individuals. Forget about asking for resumes. Instead, my process is simple. I share a request for talent in a relevant community, ensuring I follow the rules of that community. Within that request, I ask people to fill in my form as a first step. This gives me everything I need to find individuals who look like the best potential options and invite them for an interview.

From here, I vet them using the standard process and offer extended initial term contracts to those who are a good fit. Extended initial term contracts are ideal in this situation. They allow you to extend the term if you find you work together effectively, but also provide a clean separation if things don’t work out.

As you can see, there’s no need to pay somebody else to find talent for you. For many solopreneurs, this is a waste of money and time. Instead, go to relevant online communities (Reddit is just one option) where those individuals hang out, build real relationships with them and hire the right people for your team. It’s a valuable route to solopreneur success.

Key Takeaways

  • Relying solely on the talent in your immediate geographic area is a self-inflicted mistake. 
  • Although there is an entire global industry built to help companies hire remote talent, you don’t need to rely on it. 
  • As solopreneurs, we can hire in a more effective way if we are ready to build relationships in online communities. And it does not cost any money.

Solopreneurship, despite its name, is anything but a solo pursuit. As we find success in our agency work, we inevitably need to build a team that can help us serve our clients and expand our footprint.

As MVRK, my CRM strategy and implementation consulting agency, starts its seventh fiscal year, I’m very happy to say that my team is now composed of seven individuals who operate from six different countries. What’s more, none of us live in the three countries where we mainly do business (USA, Canada and the UK).

I have hired each of the individuals who are on the team myself. And I discovered them in a unique but repeatable way. In this article, I’m going to review the method that I’ve used to build those relationships with potential talent and share how I’ve been able to make them a part of my team. All with zero dollars spent.


Source link

The Unique Hiring Strategy I Used to Build a Global Team Read More »

7 Simple Ways to Make Your Business More Visible to AI

7 Simple Ways to Make Your Business More Visible to AI


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Test how customers actually ask for recommendations, rewrite the opening of your most important page, and answer the five questions that recur right before someone books a meeting or requests a quote.
  • Replace vague credibility claims with evidence, remove technical barriers before adding new content, make your expertise verifiable beyond your website, and measure qualified demand, not just mentions.
  • AI search has changed the way some buyers research providers, but it has not removed the need for fundamentals.

Imagine a prospect asking an AI assistant to recommend a business in your category. Three competitors appear. Yours does not. You have a functioning website, years of experience and a steady stream of content. Yet the customer never learns you exist.

That scenario is worth investigating, but not because AI has a single secret ranking formula. Different tools generate different responses. Some retrieve live web pages; others depend on a combination of search results and existing knowledge. A recommendation can change with the question, location, timing and context. One test is not proof that your business is universally invisible.

The real opportunity is simpler. Make it easier for a person, a search engine and an AI-powered discovery tool to understand exactly what you offer, who benefits and what evidence supports your claims. You can begin with seven manageable improvements, many of which strengthen traditional search and conversions at the same time.

1. Test how customers actually ask for recommendations

Start with customer language, not marketing jargon. If you sell cybersecurity services to banks, someone may ask, “Who helps regional banks prepare for a security audit?” They are less likely to type your carefully crafted positioning statement. Your first job is to understand the questions that occur before a buying decision.

Write five to 10 realistic prompts from sales calls, customer emails and proposal requests. Include a category question, a problem question, a comparison question and one that names your market. Test them in more than one AI search experience. Record the date, precise wording, companies mentioned, cited sources and whether your own website is among those sources.

Keep branded prompts separate. “Tell me about Acme Consulting” checks brand recognition; “Which firms can improve manufacturing supply-chain forecasting?” investigates discovery by an unfamiliar buyer. Confusing the two creates false confidence.

Your 20-minute action: Create a spreadsheet with columns for prompt, platform, date, cited source, competitor and opportunity. Treat observations as directional research, not an audited visibility score. Repeat the same prompt set monthly to look for persistent patterns.

2. Rewrite the opening of your most important page

Too many homepages use language that could describe any company: “We unlock transformational growth through next-generation solutions.” It sounds sophisticated but leaves a buyer wondering what is actually for sale. If a customer cannot understand the offer in ten seconds, that is a messaging problem long before it becomes a technical SEO problem.

Replace abstraction with a simple structure: “We help [specific audience] solve [specific problem] through [specific product or service], so they can [realistic outcome].” For example: “We help multi-location clinics improve patient acquisition and appointment conversion through search, content and website optimization.”

Then add proof nearby: industries served, a concrete capability, a customer example or a documented credential. Do not paste an entire keyword list into your opening paragraph. Make the first 100 words accurate, readable and specific, with one primary H1 that matches the subject of the page.

Your 20-minute action: Ask someone outside your organization to read the first screen of your homepage. Can they explain whom you serve, what you deliver and what action to take next? If not, rewrite it before investing in additional content.

3. Answer the 5 questions that prevent a purchase

Businesses often publish broad thought leadership but hide the details a buyer needs: price ranges, implementation steps, eligibility, limitations and alternatives. That leaves both customers and answer-generating systems with incomplete information.

Ask sales and customer-service teams which questions recur immediately before someone books a meeting or requests a quote. Select five. Build accurate answers into the relevant service or product pages, not a disconnected wall of generic FAQs. Use a descriptive H2 question and answer it directly in the first sentence, followed by examples, constraints and the next decision a buyer needs to make.

If pricing varies, explain the variables rather than inventing a price. If delivery timelines depend on approvals, say so. If the product is not suitable for every customer, acknowledge that explicitly. Useful answers increase confidence because they reduce uncertainty, not because they repeat a search phrase.

This approach aligns with a broader shift toward commercially useful content. For additional perspective, Entrepreneur has covered how businesses can earn leads across both AI search and conventional Google discovery.

Your 45-minute action: Publish one complete answer on each of your top five revenue-driving pages. Review the result on mobile. Does a buyer get the information without opening an accordion, guessing terminology or scheduling a sales call?

4. Replace vague credibility claims with evidence

“Trusted,” “innovative” and “industry-leading” are not proof. Any competitor can make the same claims. Instead, help a skeptical prospect verify what you say. That might mean a named subject-matter expert, clear methodology, customer references with consent, original observations, dated research, documented product features or a candid case study.

An effective case study explains the initial problem, what changed, how success was measured and what the outcome means. A claimed 300% improvement without a baseline is less persuasive than a transparent account of the metric, time period and relevant limitations. Not every business can disclose client names, but permissioned or anonymized evidence can still be useful if presented accurately.

For expertise-led services, include author credentials, an updated bio and an explanation of who is responsible for the advice. For regulated industries, prioritize accurate, appropriately reviewed content over speed.

Your 30-minute action: Select your most profitable service page and add one piece of verifiable evidence plus a short explanation of why it matters to the buyer. Then identify what proof is still missing.

5. Remove technical barriers before adding new content

You can write a perfect page and undermine it with a noindex directive, a broken canonical tag, restrictive robots rules or weak internal linking. Start by checking the pages that generate or could generate revenue. Avoid treating technical optimization as a giant sitewide project when a focused inspection of five pages will reveal practical priorities.

Use Google Search Console to inspect indexing and important search queries. Confirm that key page content is present as readable text, accessible from relevant navigation and consistent with its title and meta description. Structured data can support eligible search features when it accurately represents visible content, but no special schema guarantees inclusion in AI answers.

Google’s official guidance for generative AI search reinforces that strong SEO foundations and distinctive, useful content remain central. There is no requirement to purchase a special AI markup package.

If you want public pages eligible for inclusion in ChatGPT Search, examine bot-access policies too. OpenAI distinguishes its search crawler from other crawlers, so site owners should review the current documentation rather than assuming all AI bot traffic serves the same purpose.

Your 30-minute action: Inspect five commercially important URLs for index eligibility, broken links, visible text and relevant internal links. Assign each issue to a named owner with a completion date.

6. Make your expertise verifiable beyond your own website

A website is necessary, but it is also a controlled channel. Buyers often validate a company through independent sources, including industry associations, credible media, customer reviews, professional directories and expert participation. Those sources are valuable because they can corroborate facts, not because a business purchased a large volume of mentions.

Start with accuracy: Is your business name consistent? Are leaders and services described correctly? Are your credentials up to date? Can a customer find substantive contributions rather than a directory entry alone? Then focus on places that matter in your market. A healthcare founder may benefit more from a recognized professional association or reputable sector publication than a generic syndication network.

Entrepreneur has also examined the role of credible outside recognition in a changing search environment. The practical lesson is to earn citations and mentions through work worth referencing rather than mechanically distributing the same press release everywhere.

Your 45-minute action: Correct three important third-party profiles, then identify one legitimate opportunity to contribute an original data point, expert explanation or customer insight to an industry publication.

7. Measure qualified demand, not just mentions

It is tempting to turn AI visibility into a single number. But being named frequently does not guarantee revenue, and AI answers are inconsistent enough that screenshots are a weak stand-alone measurement system. Separate the signals you can observe from the outcomes your organization actually needs.

Track whether your brand appears for a consistent set of buyer questions. Record citations where platforms expose them. Review identifiable AI referral traffic in analytics, but recognize that some journeys will not carry an obvious referral label. Combine those indicators with form submissions, qualified meetings, pipeline and revenue. Ask new prospects how they discovered you, while understanding that self-reported attribution is imperfect.

For leadership reporting, a simple monthly scorecard beats a glossy dashboard that cannot explain its methodology. Show changes to priority pages, visible search and referral trends, sales opportunities and what you plan to test next. Make it clear which trends are observed, estimated or unavailable.

Your 30-minute action: Establish a baseline this month and choose one commercial metric to improve. A rise in citations may be encouraging; a rise in qualified opportunities is the outcome the business can use.

The 7-day AI visibility reset

  • Monday: Document 10 customer questions and test them across two AI-powered discovery tools.
  • Tuesday: Clarify your homepage offer and next step.
  • Wednesday: Answer five real buying questions on relevant pages.
  • Thursday: Add one meaningful proof point to your top service page.
  • Friday: Check index eligibility, crawl access and internal links.
  • Saturday: Correct three authoritative external profiles.
  • Sunday: Review your baseline and assign ownership for the next month.

Do not confuse a seven-day implementation sprint with seven-day rankings. Search systems can take time to discover and process changes. Results depend on competition, platform behavior, website quality and the strength of your evidence. The point of the sprint is to eliminate obvious weaknesses and create a defensible plan.

The bottom line: Clarity is a competitive advantage

AI search has changed the way some buyers research providers, but it has not removed the need for fundamentals. A clear offer, useful answers, accessible pages, credible evidence and disciplined measurement improve the experience for the human buyer first. They also give discovery systems more accurate material to work with.

The question for business owners is not, “How do I trick AI into recommending me?” It is, “Have I given customers and credible sources enough useful information to understand why my company belongs on the shortlist?” That is a much more productive place to begin.

For organizations that want to examine these issues more systematically, I use an AI visibility assessment approach through Bullzeye Media Marketing’s GEO practice. The same starting principle applies whether you work with an advisor or manage it internally: Diagnose the gaps before spending on execution.


Source link

7 Simple Ways to Make Your Business More Visible to AI Read More »

Gen Z Is Sick of Greenwashing — It’s Time to Focus on Authenticity

Gen Z Is Sick of Greenwashing — It’s Time to Focus on Authenticity


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Gen Z grew up with a phone in their hand and a search bar at their fingertips. They don’t read your ad copy and take it at face value. They look into your business and whether you have the proof to back up your claims.
  • To win customer trust today, startups need to rethink how they talk to people. Show the receipts, name the trade-offs and stop waiting to be perfect.

Walk into any corner store or scroll past a sponsored post, and you see it right away. Everything is suddenly “eco-friendly,” “sustainably sourced” or “carbon-neutral.” Companies slap a leaf icon on a plastic wrapper, paint the box olive green and call it a day.

They think this trick still works. It doesn’t.

If your marketing plan leans on empty claims to win over younger buyers, you’re playing a risky game. Greenwashing won’t save your startup. It might actually sink it faster than bad cash flow. Gen Z is rewriting the rules of brand honesty, and they have zero patience for corporate spin.

The death of the eco-icon

For two decades, big brands got away with soft marketing. Slap a vague promise about 2050 goals on a billboard, hire a PR agency to write a press release about planting trees and watch sales climb.

Gen Z grew up with a phone in their hand and a search bar at their fingertips. They don’t read your ad copy and take it at face value. They check your supply chain. They search your brand name on TikTok to see if employees are calling out bad workplace habits. They can even look up your parent company’s tax filings.

When a brand gets caught lying about its footprint, the backlash is fast, loud and it doesn’t go away. A fake green label doesn’t make you look responsible. It makes you look dishonest.

Why straight answers beat pretty packaging

Young shoppers don’t expect your startup to be perfect. They know running a business takes resources and that shipping physical goods creates carbon output. What actually bothers them is the theater.

Take a small digital-first startup that sells modular workspace gear. Instead of hiding behind vague terms like “100% Earth-Friendly,” they list the exact components: 80% recycled aluminum, 20% new ABS plastic because of structural limits, made in a factory that runs on a grid with a high coal mix.

That kind of honesty instantly sets them apart from competitors shouting about saving the planet.

Gen Z wants hard facts over soft poetry. They’d rather buy from a business that admits where it falls short than one that pretends to have no flaws at all.

Being upfront is a real market advantage

To win customer trust today, startups need to rethink how they talk to people. Here’s how honest brands are changing the story:

Show the receipts: Don’t just say your sourcing is ethical. Prove it. If you run a fast-casual food stall, put the actual invoices from local farm suppliers near your register or post them online every week.

Name the trade-offs: If recycled paper packaging doubles your unit cost and pushes up your retail price, just say so. Customers respect the honesty.

Stop waiting to be perfect: You don’t need a flawless environmental record to speak up. Share your current numbers today, set short-term goals for next month and report back when you fall short.

The flawless company myth is dead

Modern shoppers know every purchase involves some kind of trade-off. When you pretend your product has zero impact, you insult their intelligence.

Take a modern specialty tea brand as an example. Instead of claiming their tea bags are fully biodegradable, when most actually need industrial composting facilities that regular city systems don’t have, they put a warning label right on the front of the pouch:

“These tea bags need commercial high-heat composting. If you toss them in your garden, they’ll take years to break down. Here’s how to dispose of them the right way.”

That one blunt line builds more brand trust than a million-dollar ad campaign built on fluffy green claims. It shows respect for the buyer’s intelligence.

How startups can shift right now

If you want your business to survive this shift, you need to drop the corporate buzzwords and rebuild how you talk to people, starting now.

  1. Ditch the buzzword dictionary

Cut words like “green,” “pure,” “natural” and “conscious” from your site unless you back them up with a specific third-party certification or a real number. If a claim can’t be checked, delete it.

  1. Open up the backend

Use your social channels to show operational hiccups. If a supplier fails to meet your material standards, post about the delay. Explain why you turned down the shipment. Turn your operational struggles into proof of your standards.

  1. Keep it rough around the edges

Big-budget, super-polished video ads read as dishonest to an audience raised on user-generated content. A quick, unedited founder video shot on a phone explaining a packaging decision lands far deeper than a slick commercial.

The bottom line

Gen Z isn’t asking every business to solve global problems on its own. They’re asking businesses to stop using those problems as a sales tactic.

If your product is good, let it stand on its own. If your operations are still a work in progress, show the process. Drop the green paint, publish your real numbers and talk to your customers like actual people.

Trust is not something you buy with a clever campaign anymore. It’s something you earn by showing up, dropping the spin and telling the whole truth every single time.

Key Takeaways

  • Gen Z grew up with a phone in their hand and a search bar at their fingertips. They don’t read your ad copy and take it at face value. They look into your business and whether you have the proof to back up your claims.
  • To win customer trust today, startups need to rethink how they talk to people. Show the receipts, name the trade-offs and stop waiting to be perfect.

Walk into any corner store or scroll past a sponsored post, and you see it right away. Everything is suddenly “eco-friendly,” “sustainably sourced” or “carbon-neutral.” Companies slap a leaf icon on a plastic wrapper, paint the box olive green and call it a day.

They think this trick still works. It doesn’t.

If your marketing plan leans on empty claims to win over younger buyers, you’re playing a risky game. Greenwashing won’t save your startup. It might actually sink it faster than bad cash flow. Gen Z is rewriting the rules of brand honesty, and they have zero patience for corporate spin.


Source link

Gen Z Is Sick of Greenwashing — It’s Time to Focus on Authenticity Read More »

A Familiar Neighborhood Spot Is Helping Consumers Spend Less

A Familiar Neighborhood Spot Is Helping Consumers Spend Less


Key Takeaways

  • Rising cost of living is driving people to their neighborhood libraries.
  • Libraries offer savings on books, streaming services and even newspaper subscriptions.
  • People can spend time in libraries without the pressure to buy something, like at a coffee shop or bookstore.

Shoppers looking to cut costs are rediscovering an old favorite location in their neighborhoods: their local library.

According to a new report from NPR, consumers are returning to the library to get more without stretching their paychecks.

One avid reader, Izzy Rivera, picks up at least one book a week from local libraries near her residence in Topeka, Kansas. She said in an interview with NPR that it “just isn’t realistic” for her to regularly buy new books as she saves up for law school.

Rivera checks out both physical books and digital ones through the Libby library app. She isn’t ruling out buying books altogether. Last month, she went to her local library’s used book sale and bought 15 books for around $20.

There are other instances where the library provided Rivera with free or low-cost materials. For example, she watches movies on the streaming app Kanopy, which requires a library card or university login.

Her library card also provides her with free access to The New York Times online, a perk that extends beyond her neighborhood. For example, The New York Public Library began offering visitors free access to The New York Times in January if they accessed the digital newspaper while on the library’s Wi-Fi network.

Rivera said she spends a lot of time at her local library.

“It’s somewhere I can go where I’m not expected to spend money,” she said. “If I were to go to a coffee shop just to get out and do something, the expectation would be to buy a coffee, even though I probably didn’t want a coffee.”

Librarians and library-goers across the country told NPR that financial pressures are drawing consumers into libraries. The pattern is familiar to library staff: When money gets tight, demand for their services grows.

Americans are struggling to afford basic needs

Americans are cutting spending on optional items as they try to afford the necessities. A Pew Research Center report released last month found that 44% of Americans struggled to afford at least one basic necessity, like medical care or housing, over the previous year.

Meanwhile, 70% said they had trimmed spending on nonessentials like dining out and streaming subscriptions across the same time period. Pew Research conducted the survey in late August, and about 5,000 Americans responded.

Several of the nation’s largest public library systems showed NPR data reflecting recent increases in membership. More library-goers are also borrowing materials and attending events.

Maria McCauley, president of the American Library Association, said in an interview with NPR that she attributes some of that growth to “heightened awareness” of what libraries offer. 

Libraries “are especially popular right now, I think, because people are aware that everything that we provide is free or very low cost,” McCauley said. 

Key Takeaways

  • Rising cost of living is driving people to their neighborhood libraries.
  • Libraries offer savings on books, streaming services and even newspaper subscriptions.
  • People can spend time in libraries without the pressure to buy something, like at a coffee shop or bookstore.

Shoppers looking to cut costs are rediscovering an old favorite location in their neighborhoods: their local library.

According to a new report from NPR, consumers are returning to the library to get more without stretching their paychecks.

One avid reader, Izzy Rivera, picks up at least one book a week from local libraries near her residence in Topeka, Kansas. She said in an interview with NPR that it “just isn’t realistic” for her to regularly buy new books as she saves up for law school.


Source link

A Familiar Neighborhood Spot Is Helping Consumers Spend Less Read More »