Blog

Why Customer Complaints Should Shape Your Marketing

Why Customer Complaints Should Shape Your Marketing


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • When customers complain, better messaging isn’t always the answer. Recurring complaints can reveal problems that no marketing campaign can fix.
  • When the same complaint keeps appearing, marketers should ask: Are we failing to deliver the promise, or are we making the wrong promise?
  • Reviews, social posts, support conversations and sales calls are valuable sources of intelligence. The point isn’t to react to every angry customer. It’s to look for patterns.

When customers complain, companies tend to focus on the complaint.

They respond to the bad review. They apologize on social media. They ask customer service to smooth things over. If the problem shows up often enough, someone eventually asks what marketing can do to improve the company’s reputation.

That’s often the wrong question. The better question is whether customers are pointing to a real problem. If they are, the most useful thing marketing can do may be to help the company see it.

PwC’s 2025 Customer Experience Survey found that 52% of consumers had stopped using or buying from a brand because of a bad experience with its products or services.

Better messaging can only take you so far.

Customers don’t separate the brand from the experience

Inside a company, everything has an owner. A late delivery is an operations issue. A software bug belongs to product. An unanswered call might be customer service.

Customers don’t make those distinctions. They experience the company as a whole.

A hotel can promote exceptional service, but guests will remember waiting 20 minutes at an empty front desk. Once customers share experiences like that, they become part of your brand story.

That’s especially important as AI becomes part of how people research companies. An Idea Grove survey of 1,000 U.S. consumers found that only 2% would buy from an unfamiliar brand based on an AI recommendation without additional research. Reviews were the top trust signal respondents evaluated.

AI may change how customers discover you. It doesn’t prevent them from checking whether your claims hold up.

Complaints can expose two different problems

When the same complaint keeps appearing, marketers should ask: Are we failing to deliver the promise, or are we making the wrong promise?

Those aren’t the same problem.

If a hotel promises a fast, frictionless check-in and routinely leaves guests standing at the front desk, that’s an execution problem.

But imagine a company that markets itself around white-glove service while its business model is deliberately low-cost and self-service. Customers complaining about limited support may not be exposing an operational failure. Marketing may have created an expectation the company was never designed to meet.

In that case, the answer isn’t to fix operations. It’s to fix the promise.

Marketers naturally look at complaints through the lens of perception. But sometimes the market doesn’t misunderstand the company. The company has misrepresented itself to the market.

Good marketing can make a bad problem worse

There’s another uncomfortable possibility: Sometimes doing our jobs well can make a company’s reputation worse.

Suppose customers are already complaining about a recurring product or service problem. Marketing launches a successful campaign, demand increases and thousands of new customers encounter the same problem.

Now the company has more disappointed customers, more negative reviews and more evidence contradicting its own claims.

Marketing didn’t cause the problem. But it amplified it.

Before pouring more customers into the top of the funnel, marketers should understand what’s happening at the other end.

Complaints tell you what customers actually experience

Companies shouldn’t wait for customers to tell them directly. Qualtrics XM Institute’s 2026 consumer research found that only about three in 10 consumers now explain directly why they’re leaving.

That makes reviews, social posts, support conversations and sales calls valuable sources of intelligence. The point isn’t to react to every angry customer. It’s to look for patterns.

A 2026 survey from property technology company Rently offers a simple example. Only 11% of 800 U.S. renters surveyed said they fully trust security claims in apartment listings, while 56% said they had lived somewhere where a security feature existed but didn’t work.

A property can promote itself as a gated community. But if renters arrive and discover the gate doesn’t work, fixing the marketing isn’t the answer. Fixing the gate is.

Marketing should bring the outside world inside

Marketing teams spend enormous amounts of time trying to understand the market. That gives them a perspective other departments may not have: They can see the gap between what the company says and what customers experience.

When a pattern emerges, quantify it. How often does the complaint appear? Is it affecting reviews, renewals or sales? Then take that evidence to whoever can address it.

Sometimes that’s operations or product. Sometimes it’s customer service. And sometimes it’s marketing itself.

Once the problem is fixed, marketing has something better than a claim: evidence. Show customers how their feedback led to improvements, whether that’s faster service, a simpler product or a better experience.

That’s the difference between telling customers what they should believe and giving them a reason to believe it.

When complaints keep contradicting your marketing, the problem may not be the story you’re telling. It may be the experience customers are having. Before you change the message, find out what needs to change in the business.

Key Takeaways

  • When customers complain, better messaging isn’t always the answer. Recurring complaints can reveal problems that no marketing campaign can fix.
  • When the same complaint keeps appearing, marketers should ask: Are we failing to deliver the promise, or are we making the wrong promise?
  • Reviews, social posts, support conversations and sales calls are valuable sources of intelligence. The point isn’t to react to every angry customer. It’s to look for patterns.

When customers complain, companies tend to focus on the complaint.

They respond to the bad review. They apologize on social media. They ask customer service to smooth things over. If the problem shows up often enough, someone eventually asks what marketing can do to improve the company’s reputation.

That’s often the wrong question. The better question is whether customers are pointing to a real problem. If they are, the most useful thing marketing can do may be to help the company see it.


Source link

Why Customer Complaints Should Shape Your Marketing Read More »

What Really Separates Successful CEOs From the Rest — A Private Equity Founder’s Unfiltered Take

What Really Separates Successful CEOs From the Rest — A Private Equity Founder’s Unfiltered Take


Tide Rock CEO Ryan Peddycord shares the principles that shaped his career and the no-debt private equity strategy most firms keep to themselves.

By

Trent Bryson


|


edited by
Maria Bailey


|


Oct 13, 2026

Opinions expressed by Entrepreneur contributors are their own.

Ryan Peddycord is the CEO and founder of Tide Rock, an evergreen holding company built on an unlevered approach to private equity: permanent capital, no bank debt and a focus on economically resilient B2B businesses. Before Tide Rock, he built his reputation as an operator, leading Business.com as CEO and chairman and growing a string of B2B companies to double-digit growth year-over-year. He holds a degree from UC Santa Barbara and furthered his business education through Harvard Business School’s Executive Education program.

In this episode of Grit Rising, Ryan opens up about what actually separates successful CEOs from the rest, the core principles he’s built his career around and the private equity strategy most firms keep close to the vest. It’s a rare, unfiltered look at radical transparency in an industry known for anything but. You will not want to miss this episode.


Entrepreneur Leadership Network® VIP

Trent Bryson, CEO of Bryson Financial, has established success as the leader of one of… Read more


Source link

What Really Separates Successful CEOs From the Rest — A Private Equity Founder’s Unfiltered Take Read More »

How These Friends Opened a Color Me Mine Pottery Franchise

How These Friends Opened a Color Me Mine Pottery Franchise


Key Takeaways

  • Antima Jain and Pooja Choudhary met 11 years ago through a mutual friend at a party in Minnesota.
  • They were both immigrants from India, had a lot in common and lived three minutes away from each other.
  • They ultimately pooled their personal funds to open their own Color Me Mine paint-your-own pottery studio franchise in March 2025.

A few months ago, a customer walked into Antima Jain and Pooja Choudhary’s Edina, Minnesota pottery-painting studio, Color Me Mine, with a plan to propose to his girlfriend.

Color Me Mine allows customers to pick a piece of pottery like a mug, plate or bowl, and paint it. The studio then glazes and fires it, and the customer can pick up in about a week. 

The customer wanted to paint a jewelry tray with the question, “Will you marry me?” and use it to propose. Usually it took about seven days for Jain and Choudhary to process a customer’s pottery after they painted it. This time, they agreed to have his piece ready sooner.

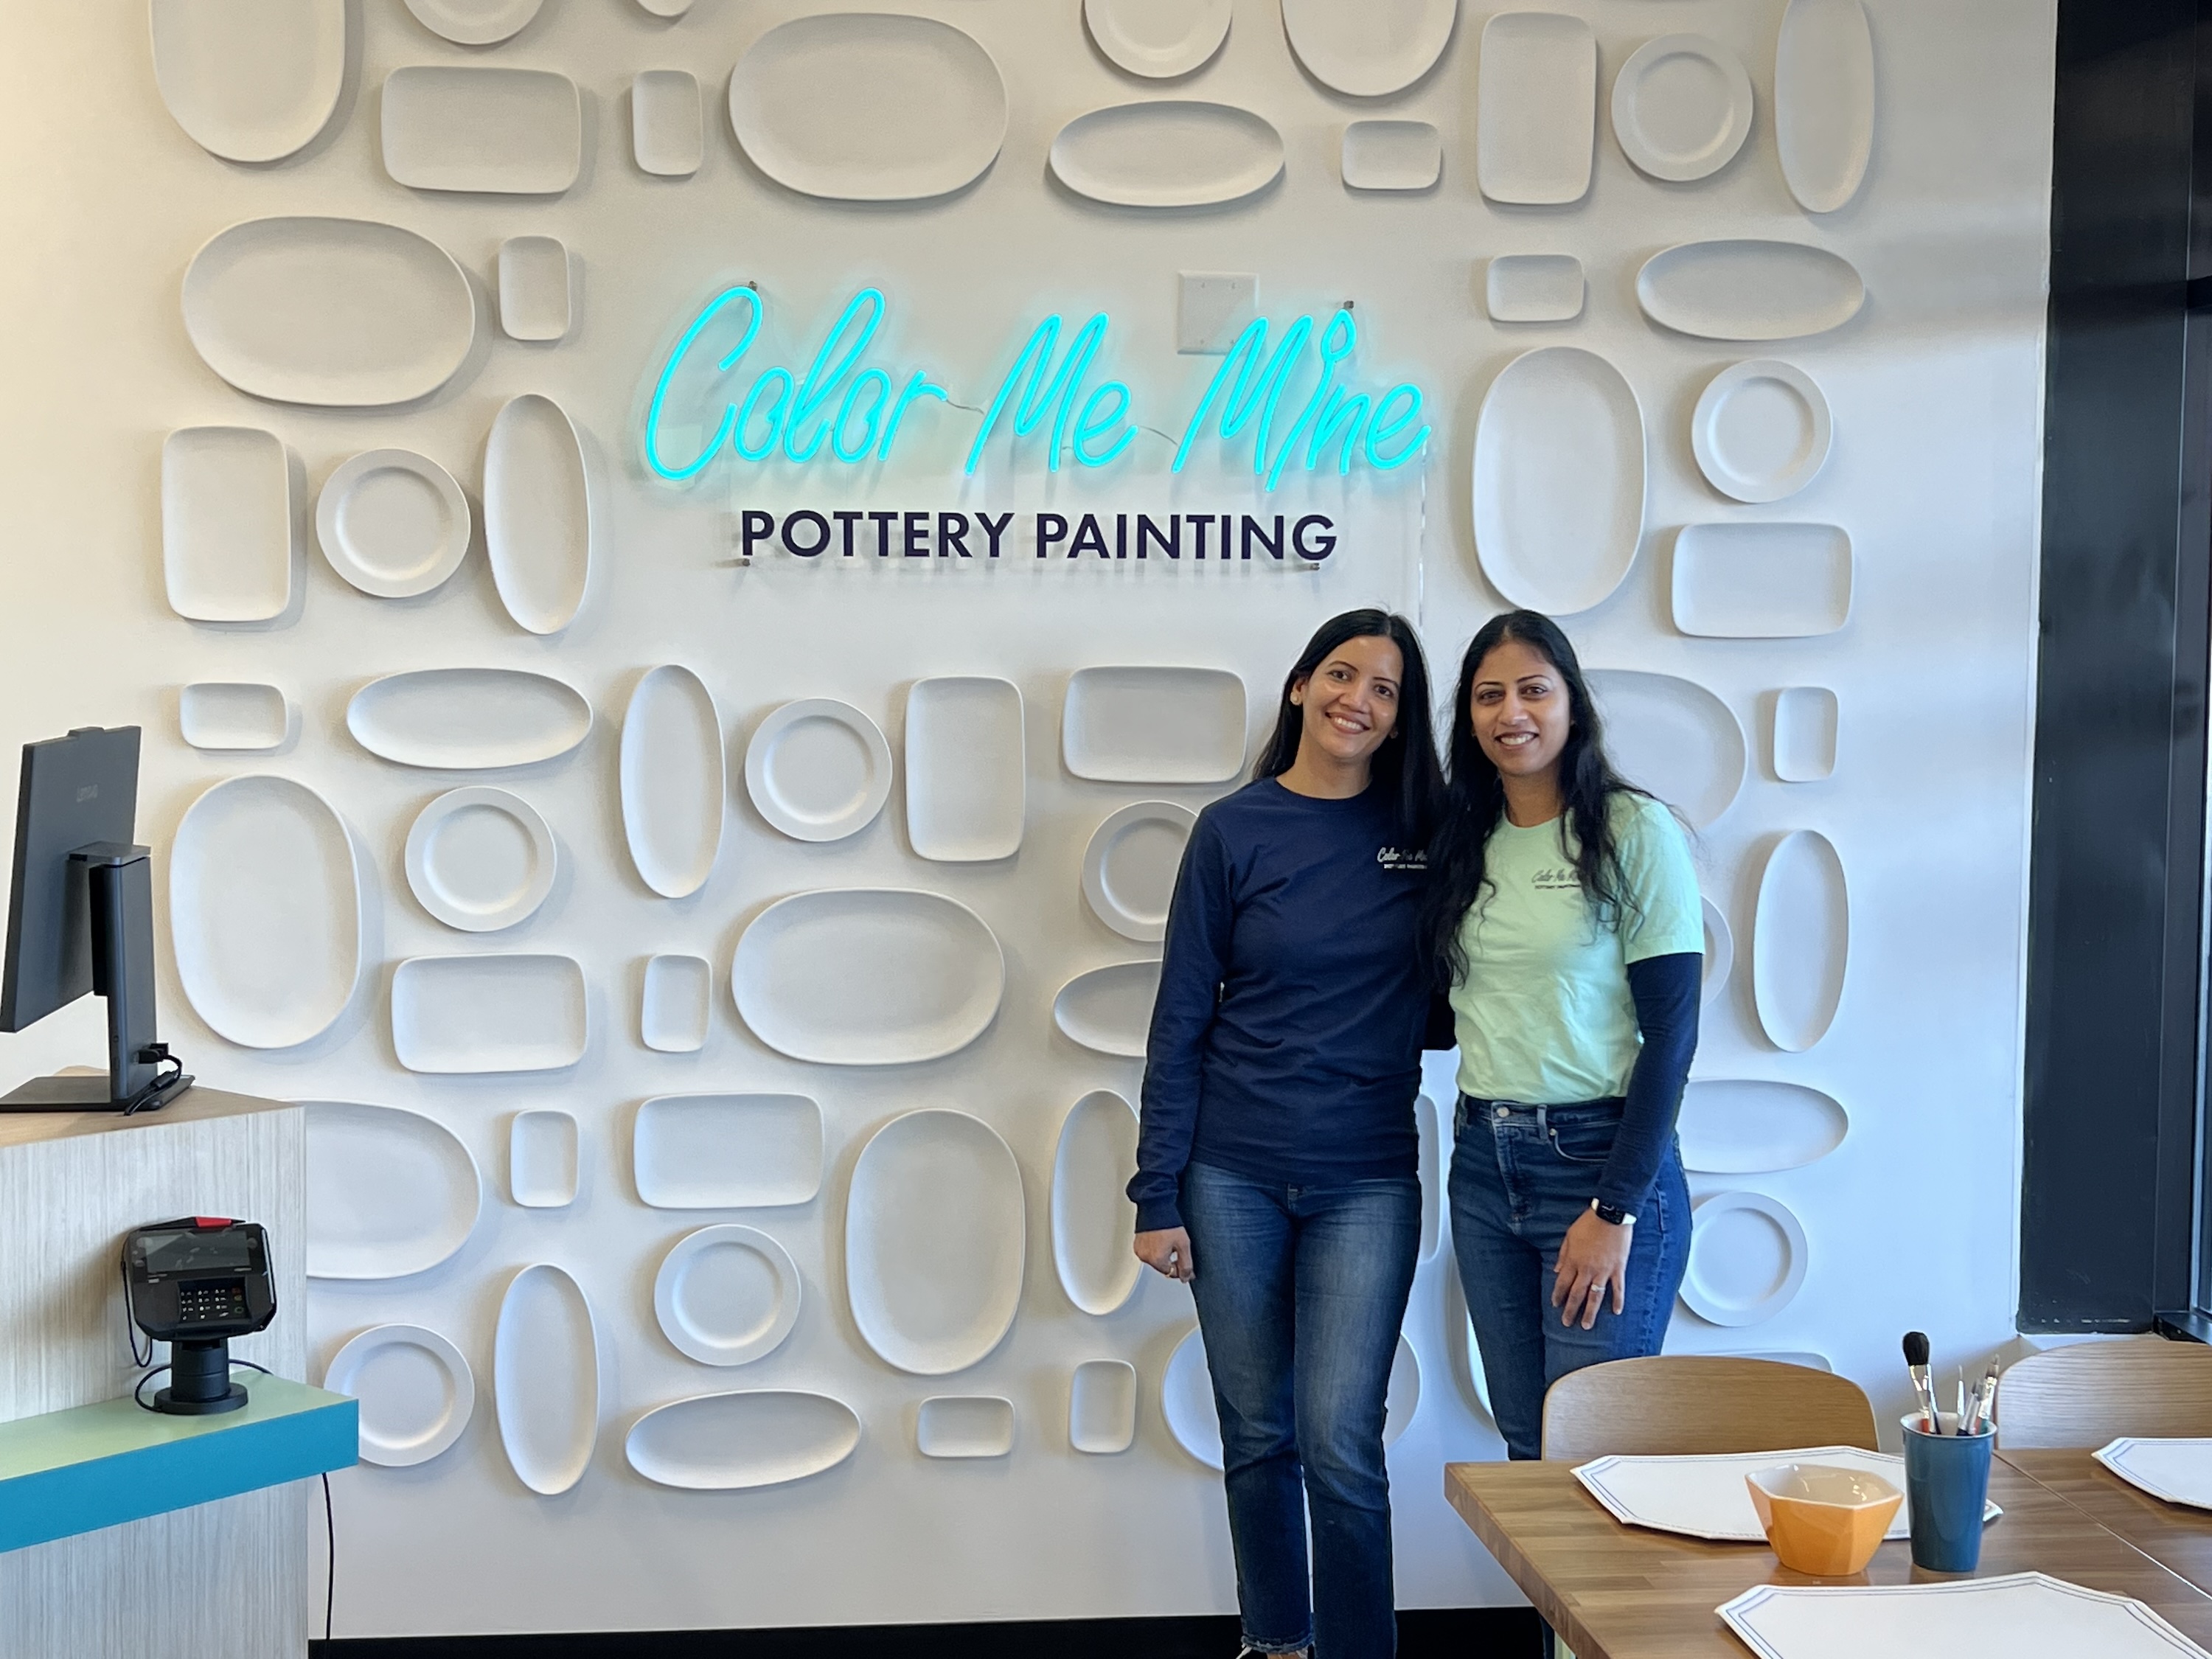
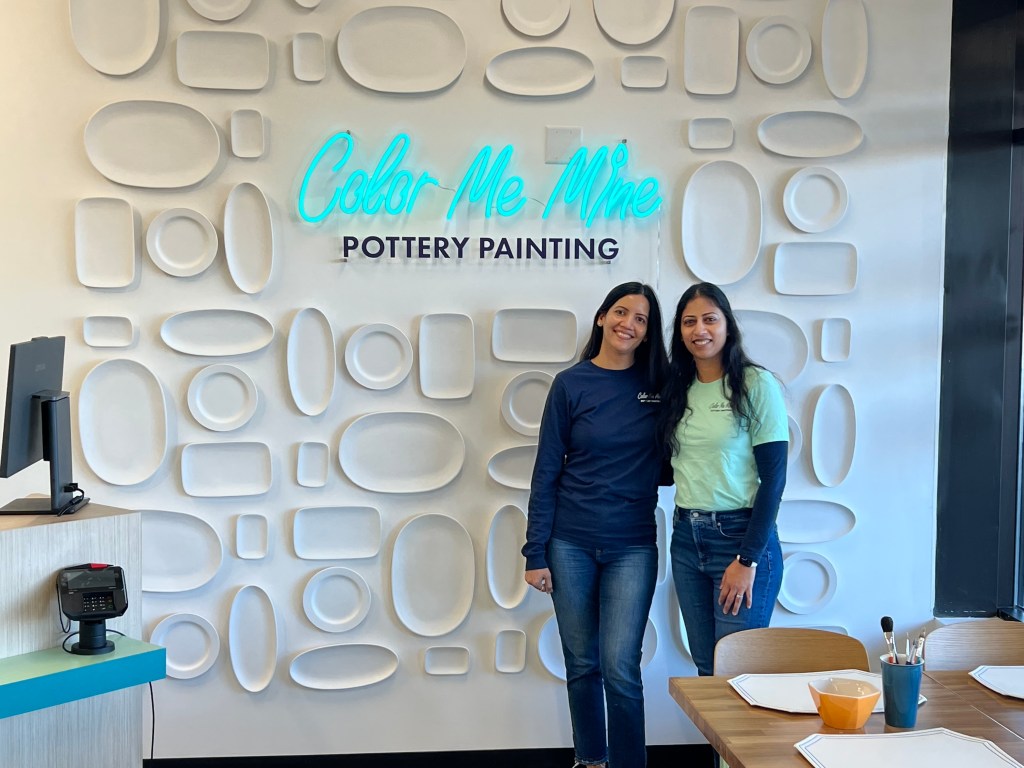
Antima Jain and Pooja Choudhary. Credit: Color Me Mine Edina, MN
Antima Jain (left) and Pooja Choudhary (right). Credit: Color Me Mine Edina, MN

Jain and Choudhary also helped create the atmosphere that the customer wanted in the studio. Later, the couple brought them a save-the-date card that mentioned the studio. For Jain and Choudhary, it was a reminder of their impact. They were creating a space where customers could connect and build lasting memories. 

A lot in common

That sense of connection is also the foundation of their partnership. Jain and Choudhary met 11 years ago through a mutual friend at a party in Minnesota. Both had moved to the United States from India, were raising children and enjoyed creative projects. 

“We started talking and realized we have so many things in common, and just like each other’s company,” Choudhary tells Entrepreneur in a new interview. “We started meeting up.” 

They lived a three-minute drive from each other. As their children grew more independent, the friends began imagining building a business together. When they started their search in 2023, they explored franchises and visited a nearby Color Me Mine studio. 

“We just loved the whole vibe,” Jain says. “It was such a clean environment, very organized, very colorful. It just felt calming. We both had the same impression.”

They ultimately pooled their personal funds and spent about $300,000 to open their own Color Me Mine location in March 2025. But before becoming business partners, they made a pact: Friendship would come first. Whatever challenges arose, they would keep talking rather than let the business divide them.

The following interview has been edited for length and clarity.

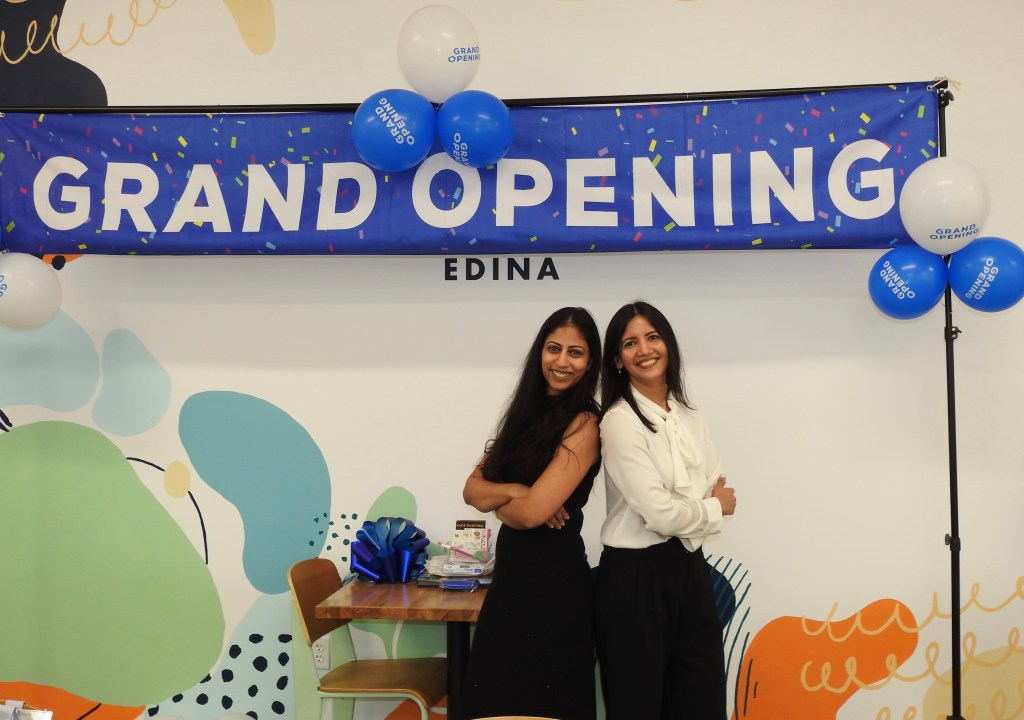
Pooja Choudhary (left) and Antima Jain (right). Credit: Color Me Mine Edina, MN

Their immigrant stories

Tell me about your backgrounds before you became franchise owners.
Jain: I first came to the United States in 2003 because of my husband’s work project. We went back and forth between India and the U.S. a few times, and then we came here in 2012 and have been here since.

I have a bachelor’s degree in commerce from India. I taught preschool there, and here I worked at Kumon. I was working part-time while my kids were growing up. Now they’re both in college, so this seemed like the perfect time to get into something we would enjoy and have time to invest in.

Choudhary: My husband was already here when we got married, and I moved to the United States afterward. I finished my master’s in electrical engineering. We lived in different states before coming to Minnesota around the same time Antima did.

I have an investment property business on the side, which I still continue. I have two girls: one in high school and one finishing middle school at the time of this interview.

Deciding to franchise

Why choose a franchise rather than create an independent studio?
Choudhary: We didn’t have experience running this kind of business, and that was the scary part: How were we going to do it?

A franchise felt like a balance between owning an independent business and working in a corporate environment. They provide the platform, but we still have independence in running the studio.

Jain: Everything was laid out for us. The guidance and support have helped a lot. Even after our first year, they were still introducing things to make the business easier to operate, including a new point-of-sale system across Color Me Mine studios. We haven’t regretted choosing a franchise.

How did you find your location and fund the business?
Choudhary: The franchisor gave us a territory, and we hired a real estate agent to help find a space. We looked at many places before choosing our location in Edina. There are parks and shopping nearby. The franchise team helped us shortlist locations and think about what to look for, including visibility.

Jain: The startup cost was roughly in the low-$300,000 range. We both invested from our personal accounts rather than taking out a loan. Being partners made it easier to split that investment.

Acquiring customers

How have you worked to bring in customers and grow?
Jain: We joined the local chamber of commerce, which helped spread the word. We participated in an art festival near our location and held Mother’s Day and Father’s Day events. We run recurring promotions and include discount cards with finished pieces to encourage people to return within a month. We also advertise through a platform the franchise recommended.

Choudhary: We’ve donated to local organizations and participated in school fundraising, too. That has helped.

The realities of ownership

What surprised you most about operating the studio?
Jain: Hiring. I never thought keeping a full staff would be such a challenge. It’s a constant process of hiring and rehiring because most of our employees work part-time.

We give opportunities to high school and college students. Their education comes first, and when they finish high school, they may leave for college. We understand that, but before opening, we hadn’t really thought about how continuously we would need to work on staffing.

What does a typical day look like for you?
Choudhary: It’s busy. We don’t currently have a full-time manager, so we handle staffing ourselves. Sometimes we’re both at the studio; sometimes we alternate days. There’s also glazing, payroll, social media, the calendar and other online work. Every day, something needs attention.

Beyond staffing, what has been difficult?
Jain: Calling customers when something happens to their pottery in the kiln. They may have spent hours creating a piece, and then it doesn’t come out perfectly. Telling them that is hard. It happens very rarely — we estimate less than 1% of pieces — but we still dread those calls.

Choudhary: We offer a replacement piece and waive the studio fee so they can come back and paint again. We try to do whatever we can to make the experience better.

Planning ahead and protecting the partnership

How do you keep business disagreements from affecting your friendship?
Choudhary: We knew things would happen because we were new to this. We agreed to keep an open dialogue and talk if something wasn’t working. We’re doing this because we’re friends. If we weren’t going to stay friends, there would be no point in having the business together.

Jain: We’re like sisters. There will be disagreements; we can’t always agree. But I wouldn’t have chosen anyone else to do this business with. If I open another studio, I’ll do it with Pooja.

What are your goals for the business?
Jain: We would love to open another studio. We also want to reach the top five in the franchise’s sales rankings. We’ve been in the top 25 and reached sixth place for one month, but we haven’t made the top five yet.

Choudhary: We have similar goals and the same vision for the studio. That alignment is what makes the partnership special. Most of the time, we’re thinking along the same lines.


Source link

How These Friends Opened a Color Me Mine Pottery Franchise Read More »

AI Companies Are Privately Planning for a Large-Scale Disaster

AI Companies Are Privately Planning for a Large-Scale Disaster


Nothing to worry about over here, just the fact that the people building AI are preparing for it to go badly wrong, very soon. Axios reports that top executives at Anthropic, OpenAI and other AI companies are privately planning for a public and political backlash after a catastrophic AI event. Many insiders expect this to happen within six to 12 months, most likely as a cyberattack that knocks out financial services, internet access or even power and water.

Anthropic CEO Dario Amodei raised the alarm last month, warning that a swarm of AI agents could take over the internet, “potentially causing hundreds of billions of dollars in damage.” Some security pros pushed back. Expel CTO Greg Notch called the idea “far-fetched.”

Real examples are happening, though. A hacker allegedly used Chinese models, including DeepSeek, to steal data from tens of thousands of South Korean bank customers, then used Anthropic’s Claude Code to look for buyers, according to CrowdStrike.

The companies’ planning focuses on educating Congress. OpenAI says its preparedness exercises cover many scenarios. “These scenarios are not treated as inevitable,” a spokesperson told Axios. Anthropic declined to comment.


Source link

AI Companies Are Privately Planning for a Large-Scale Disaster Read More »

How to Recover from a Bad Performance Review and Rebuild Trust

How to Recover from a Bad Performance Review and Rebuild Trust


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Before you respond to a bad performance review, stop and really listen to what your manager is saying. You can listen without agreeing to everything in the review.
  • Assess your company’s review culture; do they prioritize development after a poor review, or is it the first step to your exit?
  • Launch what I call an “internal PR campaign.” It might feel unnatural and uncomfortable to talk about your accomplishments at first, but internal visibility is important.
  • Read the writing on the wall. If your company has a history of laying off its employees after a bad review, prepare yourself in advance.

A senior director of engineering came to me after receiving a bad performance review. He had received feedback that he wasn’t strategic enough, didn’t communicate at a high enough level and needed to learn to delegate. After years of getting great reviews, he felt blindsided.

During my career coaching executives managing thousands of direct and indirect reports, I’ve learned that a performance review isn’t necessarily a reflection of your performance but of your PR skills. And these days, your boss probably has less visibility into your work than ever. Gallup reports that, as of 2025, the average number of people reporting to a manager is roughly 12. Team sizes have grown nearly 50% since Gallup began measuring in 2013, when the average was just eight.

If you recently received a bad review, the steps you take next matter much more than the review itself.

1. Listen before you respond

Your first job during the review is to listen. It’s easy to become defensive when someone criticizes your work, but defensiveness can confirm the reviewer’s conclusions about you.

Instead, respond with a line like: “Thank you for sharing this feedback.” Since I coach a lot of tech clients who like numbers, I remind them that feedback is data. Your job is to decide how to turn that data into insights and action.

You can listen without agreeing with everything in the review. You can request time to return with examples that ensure your manager sees your full contributions. This might sound something like, “I plan to get back to you next week with my response to the review.” There’s a big difference between arguing with a review in the moment and presenting evidence a week later.

2. Diagnose your company’s review culture

Before you decide on a response strategy, you need to know what kind of company you’re working at. I’ve seen firsthand that some companies truly invest in developing leaders after a bad review, while others issue a bad review as a formal notice that they’re going to fire you.

How do you tell the difference? Reflect on what happened to the last few people who received bad reviews. You can also ask your HR business partner directly whether there’s a realistic path to the other side of this review. It sounds obvious, but HR will often tell you the truth. If you have a peer you trust, you can also disclose your concerns to them and compare notes. Your boss’s nonverbal signals during the conversation will give you information as well. Together, this data will tell you whether to invest in rebuilding or start planning your exit.

When the senior director I’m working with probed further, he learned that his company regularly gave tough reviews but didn’t always fire people afterward. Instead, the people he talked to said leadership was truly invested in development. Learning this informed our strategy.

3. Launch an internal PR campaign

With the senior director, we first had to understand why executives saw him this way. It turned out that he had been at the company for more than a decade and had been promoted several times, so executives still saw the engineering manager he used to be rather than the senior director he had become. This pattern is common among leaders who have grown their scope, including a client I’m currently coaching who is navigating the tension of becoming his former peers’ boss.

Part of the fix was how he showed up. Another part was how executives perceived him. Because of this, we ran what I call an internal PR campaign. Every three to four weeks, we identified one thing he had achieved and discussed a way to publicize his progress to his boss, his boss’s boss and the C-suite. Promoting himself felt unnatural given his technical background, so we practiced small steps first, like sharing updates in Microsoft Teams and via email. For example, he broadcast to his colleagues that his team had identified major bugs leading up to a major software launch. In the past, he would have just assumed that everyone would notice.

Truthfully, most clients resist this kind of promotional campaign at first. It can feel like bragging, and they believe their work will speak for itself. But in my experience, it rarely does. Imagine your boss has seven direct reports, and each of them has seven of their own. That makes you just one of 49 voices competing for the attention of a leader whose attention resources are limited. A lack of internal visibility is also a big reason high performers get passed over for promotions.

Six months later, at his next review, he received an “exceeds expectations” rating. He was also tapped to lead a special project in another country that was a high priority for the CEO, all because he had rebuilt trust at every level, from his boss to the senior executive team.

4. Read the writing on the wall

Sometimes a bad review means the company has already made up its mind. I worked with a C-suite executive at a company with a track record of laying people off shortly after giving them bad performance reviews. Unlike the senior director, he didn’t feel like he could turn around this perception before the company acted.

He decided to launch a stealth job search. Simultaneously, he made sure his work was airtight, assuming his boss was looking for any reason to terminate him. This required working harder than ever while applying for positions and interviewing on the side. He landed a new role in four months, ahead of his next review, when he believed the company would move to terminate him.

(If you have repeated experiences like this across companies, it may point to a deeper question about whether you keep landing in the wrong leadership roles.)

Final thoughts on recovering from a bad performance review

You can recover from a bad review, and better yet, often prevent one. Your goal is to make sure you’re never surprised again. While it’s your boss’s job to provide you with feedback, it’s also your job to seek it out. I encourage clients to ask for feedback often, and to ask more than once. Clarifying that you want critical feedback, not just praise, is what makes the habit work. When you build regular feedback into your approach, the formal review tends to become a recap of conversations you’ve already had. You’ve got this!

Key Takeaways

  • Before you respond to a bad performance review, stop and really listen to what your manager is saying. You can listen without agreeing to everything in the review.
  • Assess your company’s review culture; do they prioritize development after a poor review, or is it the first step to your exit?
  • Launch what I call an “internal PR campaign.” It might feel unnatural and uncomfortable to talk about your accomplishments at first, but internal visibility is important.
  • Read the writing on the wall. If your company has a history of laying off its employees after a bad review, prepare yourself in advance.

A senior director of engineering came to me after receiving a bad performance review. He had received feedback that he wasn’t strategic enough, didn’t communicate at a high enough level and needed to learn to delegate. After years of getting great reviews, he felt blindsided.

During my career coaching executives managing thousands of direct and indirect reports, I’ve learned that a performance review isn’t necessarily a reflection of your performance but of your PR skills. And these days, your boss probably has less visibility into your work than ever. Gallup reports that, as of 2025, the average number of people reporting to a manager is roughly 12. Team sizes have grown nearly 50% since Gallup began measuring in 2013, when the average was just eight.

If you recently received a bad review, the steps you take next matter much more than the review itself.


Source link

How to Recover from a Bad Performance Review and Rebuild Trust Read More »

3 Steps to See a Payroll Shortfall Coming While You Can Still Fix It

3 Steps to See a Payroll Shortfall Coming While You Can Still Fix It


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Late customer payments and fixed payroll dates can turn a small cash gap into a serious problem within weeks.

A great business with no cash behind it is like a car with an empty tank. No matter how good it is, it isn’t going anywhere. I’ve watched promising companies grind to a halt because they couldn’t get on top of their cash flow. It is the most important part of running a small business, and it tends to get the least attention from the people who run them.

Payroll doesn’t wait

Small businesses in the U.S. and Canada are routinely paid late: by around eight days on average in the U.S. and 11 days in Canada, according to Xero Small Business Insights. The bills that keep the business alive don’t move on that schedule, and payroll is the clearest example. It arrives on the same day every cycle whether or not your customers have paid you, which is how a small, temporary gap becomes a serious problem in a matter of weeks. After years of talking about this, I am still struck by how many owners can’t tell you what their cash position will look like 30 days out. They are flying blind.

According to survey data from Innovation, Science and Economic Development Canada, roughly 45% of Canadian small businesses that sought debt financing needed it to fund day-to-day operations, not growth, and payroll is often the largest piece of that. Yet only 40% say payroll data guides how they run things. By the time you are seeking financing to cover payroll, you are negotiating from a weaker position, and it shows in the terms.

The problem compounds. The expensive money you borrowed to make one payroll comes out of the next, so the gap you closed in March is slightly wider in April. Worse, if you are ever late on payroll, you lose trust from your team that cash can’t buy back.

Plan before you panic

Most founders talk themselves out of the first step, which is making a plan. They tell me they’re a startup with no five-year history to forecast from, so there’s no point trying. There is a point, and it doesn’t take a finance background.

Map out three versions of the year:

  • A best case, where you hit your plan
  • A likely case, built on the fixed costs you already carry
  • A worst case, where very little goes your way

For each one, work out how much cash you have on hand and how long it lasts. Then decide ahead of time what you would do as the year starts leaning toward one of them. Your fixed costs will always be there, so variable costs are usually the first place to look. The value is in having thought it through calmly and early, well before payroll is due and your biggest customer goes quiet.

Get a live view of your cash

I picture planning as a mid-January drive from Calgary to Edmonton. Your budget is the plan: your honest estimate of how long the trip should take. Once you’re on the road, things change. A flat tire or a snowstorm means you are re-estimating when you will arrive, and those updates are your forecast. Real-time data is the GPS on the dashboard, showing where you really are and whether a three-hour drive has turned into four. Plenty of owners have the budget, and some have the forecast. Many lack the GPS.

Getting that live view is a job for good software, because a spreadsheet you open every couple of months will never keep pace. You want your accounting, payroll and industry tools connected so information flows through in real time. It doesn’t have to be one system, but it does have to be joined up, because a cash-flow forecast that leaves out upcoming payroll isn’t complete.

Plenty of businesses buy the right tools and still work after the fact, reconciling once a quarter and looking backward. With clean, current data, AI can do more than you might think: categorize your transactions, keep the books live and start building forward projections for you. Experiment safely and a little each week, while the pressure is low, and you won’t fall far behind.

You don’t have to do it alone

The most important takeaway is that you don’t have to carry all of this yourself. Small businesses tend to run on spreadsheets or even paper. The smarter approach is to lean on a trusted advisor and adopt technology.

Bookkeeping has changed. Many bookkeepers now work alongside you week to week and take on the tasks that were never your strength, at a cost that makes sense once you weigh it against the value of your own time. If you’re an architect or an engineer, your best hours belong in the architecture or the engineering. The evenings you spend buried in reconciliations are taken from that work, or from your family.

Many owners still think of their accountant as the person who files a tax return once a year. The best ones set you up properly from day one, keep your numbers current and help you understand what those numbers are telling you. When an owner says they’re too small to afford that kind of help, I turn the question around: Can you afford not to?

Can you afford to borrow on the back foot? Can you risk a late payroll run and the trust you’ve built with your team? Every business has peaks and valleys, but even short-term visibility into cash flow can turn a wide gap into a manageable one.

Key Takeaways

  • Late customer payments and fixed payroll dates can turn a small cash gap into a serious problem within weeks.

A great business with no cash behind it is like a car with an empty tank. No matter how good it is, it isn’t going anywhere. I’ve watched promising companies grind to a halt because they couldn’t get on top of their cash flow. It is the most important part of running a small business, and it tends to get the least attention from the people who run them.

Payroll doesn’t wait

Small businesses in the U.S. and Canada are routinely paid late: by around eight days on average in the U.S. and 11 days in Canada, according to Xero Small Business Insights. The bills that keep the business alive don’t move on that schedule, and payroll is the clearest example. It arrives on the same day every cycle whether or not your customers have paid you, which is how a small, temporary gap becomes a serious problem in a matter of weeks. After years of talking about this, I am still struck by how many owners can’t tell you what their cash position will look like 30 days out. They are flying blind.

According to survey data from Innovation, Science and Economic Development Canada, roughly 45% of Canadian small businesses that sought debt financing needed it to fund day-to-day operations, not growth, and payroll is often the largest piece of that. Yet only 40% say payroll data guides how they run things. By the time you are seeking financing to cover payroll, you are negotiating from a weaker position, and it shows in the terms.


Source link

3 Steps to See a Payroll Shortfall Coming While You Can Still Fix It Read More »

The Startup Hiring Mistake That Looks Like a Win

The Startup Hiring Mistake That Looks Like a Win


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Many founders make the mistake of hiring a senior leader before the infrastructure exists to support it. They expect the leader to produce results off of a strategy that doesn’t exist yet.
  • Read the signs before you hire: no repeatable way leads or customers come in, the budget depends on whoever’s cheapest rather than what’s working, no one knows which channel actually drives revenue.
  • Set them up before day one: They need clear business goals, real decision-making authority, access to data and alignment with the founder on priorities.
  • Consider fractional leadership: Real work gets done, and you learn what the role actually requires before you commit to a salary and a title.

In July, WHOOP hired Dirk-Jan van Hameren, Nike’s former chief marketing officer, to run marketing for the wearable-tech company. On paper, it looked like a typical senior marketing hire. In practice, van Hameren walked into a company that had just closed a $575 million funding round at a $10.1 billion valuation, crossed 3 million members and was already cash-flow positive.

He didn’t build a marketing function. He inherited one: a 65-person team already in place, reporting directly to him from day one. 

That’s the part founders miss when they look at a hire like this and think, “We’re ready for that, too.” I’ve spent years placing marketing talent inside growth-stage companies, and the mistake I see most often is making a senior hire before the infrastructure exists to support it. 

Here’s how to tell whether your company is actually ready to hire a marketing VP or CMO, and what to do if it isn’t yet: 

1. Read the signs before you hire 

These signs usually mean the infrastructure isn’t there yet for a VP or CMO, even if the ambition is: There’s no repeatable way leads or customers come in yet, the marketing budget depends on whoever’s cheapest that quarter rather than what’s working, and no one on the team could tell you which channel actually drives revenue. 

I worked with one founder who got excited about a strong résumé, made the hire and then wondered, six months in, why nothing had changed. The new leader was spending most of their time on hands-on execution instead of building a team or a strategy, while the rest of the leadership team kept expecting immediate growth results. That expectation was the real problem.  

A senior marketing leader‘s first few months should go toward diagnosing what’s actually working, not producing results off a strategy that doesn’t exist yet. Skip that step, and any growth you do see won’t hold. In most cases like these, the company would have been better served by a strong director-level marketing leader first, then an executive once the complexity and scale actually justified the title. 

A director-level hire costs less, comes with lower expectations attached and is often more comfortable doing the hands-on work the company actually needs right now. That’s the hire that fits what the company can currently support — nothing about it is a step down. 

2. Set them up before day one  

A senior marketing leader needs four things in the first 90 days: clear business goals, real decision-making authority, access to data and alignment with the founder on priorities. They also need context, including what’s been tried before, what’s working now and where the company wants to go. Without it, a new hire will spend their first month rediscovering things the company already learned the hard way, such as channels that never converted or messaging that fell flat with the sales team. 

Founders fall short here constantly, changing priorities every few weeks, withholding real authority while still expecting ownership or demanding results before the leader has had time to build a strategy grounded in the company’s actual data. A 2025 Gartner survey of CEOs and CFOs found only 34% see eye-to-eye with their CMO on marketing’s role in supporting growth, which is exactly the kind of misalignment that turns a strong hire into a six-month disappointment. 

3. Close the gap without the full-time price tag 

Fractional leadership exists to help close this gap. It makes sense when a company needs senior-level strategy and expertise but isn’t ready for the cost, scope or workload of a full-time executive — particularly during periods of growth or transition, or when the marketing function itself still needs to be built before anyone commits to a permanent leader.  

Alina Vandenberghe, co-founder and co-CEO of Chili Piper, used this approach after running marketing herself for a stretch, hitting her numbers but exhausting the model. Rather than hiring a full-time CMO right away, she brought on a fractional marketing executive to test what skills and attributes her permanent hire actually needed. A short, defined engagement (three to six months, with specific goals attached) gives you the same clarity. 

Real work gets done, and you learn what the role requires before you commit to a salary and a title. Vandenberghe landed on a full-time VP of marketing once that was clear. Van Hameren’s move to WHOOP shows the other end of that same process. The team, the budget and the scale were already there waiting for him, which is precisely why a full-time hire made sense. 

Before you hire the VP or the CMO, ask whether your company looks anything like that. If it doesn’t yet, that’s not a reason to wait indefinitely. It is a reason to build the infrastructure first, so that when you do make the hire, you’re not asking someone to do a job you were never set up to give them. 

Key Takeaways

  • Many founders make the mistake of hiring a senior leader before the infrastructure exists to support it. They expect the leader to produce results off of a strategy that doesn’t exist yet.
  • Read the signs before you hire: no repeatable way leads or customers come in, the budget depends on whoever’s cheapest rather than what’s working, no one knows which channel actually drives revenue.
  • Set them up before day one: They need clear business goals, real decision-making authority, access to data and alignment with the founder on priorities.
  • Consider fractional leadership: Real work gets done, and you learn what the role actually requires before you commit to a salary and a title.

In July, WHOOP hired Dirk-Jan van Hameren, Nike’s former chief marketing officer, to run marketing for the wearable-tech company. On paper, it looked like a typical senior marketing hire. In practice, van Hameren walked into a company that had just closed a $575 million funding round at a $10.1 billion valuation, crossed 3 million members and was already cash-flow positive.

He didn’t build a marketing function. He inherited one: a 65-person team already in place, reporting directly to him from day one. 

That’s the part founders miss when they look at a hire like this and think, “We’re ready for that, too.” I’ve spent years placing marketing talent inside growth-stage companies, and the mistake I see most often is making a senior hire before the infrastructure exists to support it. 


Source link

The Startup Hiring Mistake That Looks Like a Win Read More »

From /Hour to 3 Rental Properties and Traveling the World

From $12/Hour to 3 Rental Properties and Traveling the World


Anyone can invest in real estate. You don’t need a fancy degree, a big bank account, or a high-paying job to get started. Arden Williams and his then-girlfriend were both making just $12 an hour when they bought their first house.

How did they do it? They got uncomfortable, slashed their expenses, and threw every extra dollar toward a down payment. Then, they brought that same approach to real estate investing—jumping from one house hack to the next and sharing space with multiple tenants.

These “small” sacrifices paid off in a big way. Today, Arden owns three rental properties, and he just broke ground on his first accessory dwelling unit (ADU). But that’s not even the best part. With this simple strategy, Arden and his wife quit their jobs and used their rental income to fund a year-long trip around the world.

Whatever financial freedom means to you—retiring early, spending more time with family, or traveling the world—real estate makes it possible. And in this episode, Arden will give you a repeatable blueprint for building the life you’ve always wanted.

Henry:
Anyone can invest in real estate. You don’t need a fancy degree, a big bank account, or a high paying job to get started. Arden Williams and his wife were both making just $12 an hour when they bought their first house. So how’d they do it? They got uncomfortable. They slashed their expenses and they threw every extra dollar toward a down payment. Then they brought that same approach to real estate investing, jumping from one house hack to the next and sharing space with multiple tenants. But these small sacrifices paid off in a big way. Today, Arden owns three rental properties and he just broke ground on his first ADU, but that’s not even the best part. With this simple strategy, Arden and his wife quit their jobs and used their rental income to fund a year-long trip around the world. Whatever financial freedom means to you, retiring early, spending more time with family, or following your passion, real estate can make that possible.
And in this episode, Arden will give you a repeatable blueprint for building the life you’ve always wanted. What’s going on, everybody? I’m Henry Washington, co-host of the BiggerPockets Podcast. And today we’re bringing you an investor story with Arden Williams from Wilmington, North Carolina. So let’s jump in. Mr. Arden Williams, welcome to the BiggerPockets Podcast.

Arden:
Thank you. Thank you. I’m honored to be here, honestly. Why

Henry:
Don’t you tell us a little bit about your background and how the heck you got into real estate in the first place?

Arden:
Back in 2017, I graduated college and after college I didn’t really have much of a plan besides all I wanted to do was travel and be outside. Still something I do today. So I ended up getting a job out in Hawaii and worked there for about six months and then somehow found my way to the US Virgin Islands where I ended up moving there with my now wife. And then after COVID, we decided we needed some stability and I ended up getting a job as a firefighter in Wilmington, North Carolina, where I am today. So November of 2021, I was finishing up the fire academy and at the time we were both making like 13, $14 an hour, if that. And me and my wife ended up getting a house and ended up house hacking it with two of my fellow firefighters.

Henry:
Did you purposefully buy that deal as a house hack investment because you had been researching real estate or did you buy a single family and house hack it because that’s what you needed to do to be able to afford a place?

Arden:
Maybe a little bit of both. Back in Hawaii, I found a YouTube video of Brandon riding out buy a house every 10 years, one house every year, and ended up just kind of having it in the back of my mind of like, “That’s a great idea. Should probably look at doing that.” I remember telling my wife about it. I was like, “Hey, we could just get roommates and we’ll save a bunch of money. And if we want to rinse and repeat this, we could and hopefully continue to go and travel and do all the things we love to do.” We were basically breaking even on our mortgage with just our two roommates and it worked out great for us.

Henry:
So there was some intentionality in the kind of home you selected because I assume you planned on keeping it after you moved out.

Arden:
Yeah. So we pretty much only look at three bed, two bath, single family homes in our area for our price point. That’s kind of all we could afford. So we ended up getting it for 285, which was 20K over asking at the time, which we though we were absolutely insane, but it was 2021. It was

Henry:
2021. That was the game

Arden:
You had to play buddy. Yeah, it was the game we had to play.

Henry:
What’s your interest rate though?

Arden:
We got 3%.

Henry:
Okay, that’s awesome. So 285, paid over asking was a little scary. Got a 3% interest rate. Boo. Yeah, that’s amazing.

Arden:
Yeah.

Henry:
What was your mortgage payment?

Arden:
So at the time, I think it was like 1300 something.

Henry:
Did you put 5% down or did you put 20% down?

Arden:
So when we left the US Virgin Islands, we had saved up a good amount for our down payment. So it wasn’t our plan to save it. We were just both, me and my wife are really frugal. So we ended up putting down about $30,000 actually.

Henry:
What were you renting each room out for?

Arden:
So since they were my friends, I was trying not to gouge them on prices, but I think we ended up renting both out for about $700 a month.

Henry:
So you’re living for free essentially?

Arden:
Basically. I think we ended up basically just paying the utilities, insurance, and stuff like that.

Henry:
That’s really cool. That’s the whole point of a house hack. Well, that’s half the point of a house hack. The second part of house hacking is it’s only financially beneficial if you don’t let life creep come in. So in other words, you’ve got to pretend to pay yourself rent or mortgage so that you can actually realize the savings, not just absorb it into your lifestyle. Awesome. So that was 2021. House hack, conventional mortgage, put about 30,000 down, obviously living for free. I assume you moved out and kept it. So what kind of rent does the entire house pull in now that you’re not living there?

Arden:
Yeah, so we actually just lost our original tenants from three years ago after we and my roommates moved out. They just left and so we just got new tenants and they are renting it for 2,450 a month. Our mortgage has gone up to about 1,550 a month with insurance and taxes and hurricane stuff. That’s

Henry:
Still pretty cool. I mean, debt service of 1,550, but that includes taxes and insurance and you’re bringing in 2,450. So that’s a $900 surplus if you count a little bit for maintenance and some expenses. That’s a decent amount of cash flow for a property that you just buy on the MLS that you got to live in for free. I’d say that’s a win.

Arden:
Yeah, we’re very happy with that house.

Henry:
I’m curious to know how that led to your second deal and how different those deals are, but we’re going to dive into that right after the break. All right, we are back on the BiggerPockets podcast. I’m speaking with investor Arden Williams who successfully pulled off one of my favorite strategies, which is the house hack. I house hacked when I first got started. It was absolutely game changing. So I love hearing stories of people house hacking. So you pulled off your successful first one, you bought a three bed, two bath, paid 285. You’re pulling in about 900 bucks a month in cash flow now. Did you do it again or did you change strategies on your next one?

Arden:
We basically did the exact same thing.

Henry:
How long in between them? Was it a year, two years? How long did it take you?

Arden:
So it took us about a year and a half. So we bought November of 2021 and bought our next one in July of 2023.

Henry:
All right. Tell me about this one. Give me the stats. Beds, bath, square footage. What’d you pay?

Arden:
We have a 3-2, 1,100 square foot house downtown Wilmington. Nothing super special. It’s actually 123 years old now. Oh

Henry:
Wow. Yeah.

Arden:
Remodeled, paid 325 for it. I think at the time we had a 6.8% interest rate, but then we did something really silly about a year later, but it came with an additional lot.

Henry:
Oh, dope. I love deals like that.

Arden:
I still feel like I overpaid for that house, but then I have to remind myself that I got a lot basically for free because when we split it, they valued it as we paid like $5,000 for it and there’s lots that size are selling for $70,000 now.

Henry:
Oh yeah.

Arden:
Right now it’s funny because when we got it appraised when we first bought it to when we got the Zestimate now, it’s almost the exact same, but that doesn’t have the allot attached anymore.

Henry:
That’s super cool. Sweet. So you paid a little more for this one, 325, 6.8% interest rate for the time being. Who’d you get to live in the house with you and your wife this time?

Arden:
We had a friend of a friend move in and then we found random one we put up on Zillow and we had them both renting from us. I think one was $800 a month and the other one was $700 because one was a smaller bathroom.

Henry:
Okay. And so what was your debt service on that mortgage?

Arden:
So we ended up putting a lot down on that one. We saved as much as we could from the last house hack. We knew that interest rates had gone up. I didn’t realize how big of a deal that was until after we bought this one. And we ended up putting like $52,000 down. I think at the time it was around a little over $1,900 for the mortgage.

Henry:
Looks like you were bringing in 15. The mortgage was 19, so you had to pay a couple hundred dollars a month this time. But still you got an additional lot. So I love that you repeated it for your second one. Even though you paid a little more, you had a higher interest rate, you had high debt service, you were still able to offset your income, you were only paying a couple hundred dollars a month. On this one when you moved out, were you able to rent it for a similar amount to the other one or is this one rent for more because it’s downtown?

Arden:
So it rents only for a little bit more. We’ve had the same tenant since we left. Now they’re great. I’m also a realtor now as well. And they’re my clients and they’re actually looking to purchase a house now, which is a shame because they’re great tenants.

Henry:
You’re like, “Oh, I’ve been looking. I just can’t find anything for you guys. I guess you have to

Arden:
Stay for them.” So they paid $2,500 a month, but it has gone up. We did the silly thing of refinancing.

Henry:
Did you pull cash out?

Arden:
No. So what we did is, so we had to split the lot off.

Henry:
Oh, got it. So you got a

Arden:
New home

Henry:
And you did the lot split.

Arden:
Yeah. So we ended up splitting it and we didn’t really think… Again, we were like, “What’s one point? That’s not going to be anything.” So we split the lot off because we were going to build on it the next year. That was our plan was to build and then move on.

Henry:
Can I give you a piece of advice? Do not do the math on what the price difference is in what you’re going to pay over the life of the loan when you paid that extra 1% interest versus where you were. Just don’t look at it. It’s

Arden:
Done. Yeah.

Henry:
It’s done.

Arden:
Yep. Yeah.

Henry:
Okay. So let’s focus on the good part. The good part is another successful house hack. I assume you were just finding these on the market with an agent. You buy them. I like that you’re putting a substantial amount of money down because then you’re essentially manufacturing cash flow, you’re buying equity. And then I love the back-to-back house hack method, and I’m very curious what the next deal looked like.

Arden:
Yeah, so the next deal was actually a little different. So we actually decided to do a flip, reno, burr kind of live in flip was ultimately what it was.

Henry:
Hey, again, I think this is another great owner occupied strategy, but it’s not as cut and dry as a buying a house hack because now you have to figure out how to take on a renovation. You have to figure out how you’re going to fund that renovation. Did you have a plan in mind of what size of a renovation you wanted to take on ahead of time? Did you know what you’re looking for or were you just perusing, hoping to find something you thought might be decent?

Arden:
We wanted to do a cosmetic flip. So we wanted to do floors, paint, and then there was a… It’s actually the room I’m in now. There was a wall literally right where the computer is, and we just wanted to tear that down, but we did get a contractor for that one. And then we ended up adding some projects on and now I’m redoing the things that I didn’t know how to do the first time.

Henry:
Classic. Okay. So

Arden:
First

Henry:
Question, the obvious question is what did you pay for the property?

Arden:
So for the property, we ended up getting it for 270.

Henry:
Is it a three-two like the other ones or did you make it a three-two?

Arden:
3-2. This one’s about the same size, 11, 1200 square feet. And it’s on a half acre lot in Wilmington, which is pretty rare. Oh

Henry:
Wow. That’s

Arden:
Pretty cool. Which is going into our next strategy with this house. Actually, we just got a permit to build an ADU on the back.

Henry:
All right. So you paid 270. How much did you budget for the renovation and then did you stay on budget?

Arden:
So I think we budgeted $30,000 for a renovation and we actually did 25,000, just over 25,000.

Henry:
Nice.

Arden:
Nice. Half of that was just the contractor blowing out the wall and putting drywall on the vaulted

Henry:
Ceilings. Awesome. What kind of loan did you use to purchase this? Did you just buy it on a conventional and then fund the renovation yourself or did you use a 203K loan?

Arden:
30 year fixed.

Henry:
Because there are live-in flip loans. We’ve talked about them before. They’re pretty tedious, but are very helpful.

Arden:
Yeah. I just was listening the other day to one of those and I was like, “Well, that would’ve been good to know a year ago.”

Henry:
Okay. Okay. So you bought it conventional. How much did you put down on this one?

Arden:
So we ended up putting $40,000 down on this one as well.

Henry:
Great. So I mean, I don’t think there’s anything wrong with the strategy. I think if you’ve got the capital to be able to pull it off, this is a great way to do it. If you don’t have as much capital, yes, you can use things like a FHA 203K loan. There’s a home path renovation loan that either Sally or Freddie has that you can use. So there’s definitely options for you if you want to do a live and flip. This is cool because you’re kind of doing all of the owner-occupied real estate investment strategies. So it’s really fun to hear somebody that’s pulled that off. So have you had it appraised since you’ve done it? Do you have an idea of what it might sell for if you were to sell it soon?

Arden:
So we actually just got appraisal done for the HELOC for the ADU that we ended up pulling out and it appraised for 300, which I was less than thrilled about, but I’m long-term investor, so I’m not planning on selling it anytime soon.

Henry:
Okay. So it appraised at 300, you’re all in just under 300. But for the people that are listening, on paper, he’s all in for less than that because the renovation money was your own money and you put $50,000 down. So your actual loan balance is lower than 300, but in real dollars, you’re in it about 295.

Arden:
So

Henry:
When you say you were able to appraise for enough to do the HELOC, you had equity, you have equity because of how much money you put down and because you funded the renovation out of your pocket.

Arden:
Yeah.

Henry:
All right. So it’s on this half acre lot. You said you have started the process of doing an ADU. Did this come up after you bought it when you realized the potential or did you see the potential for ADU when you purchased it? Because this was, it looks like 2024. ADUs were just kind of becoming a thing around then, well, popularity-wise.

Arden:
Yeah, so it wasn’t really the original idea. I was probably listening to BiggerPockets and I probably heard something come up about it and I was like, “That’s a good idea.” And shortly after the city of Wilmington changed the zoning rules that basically almost any lot in Wilmington can build an ADU. So I was like, “Game on.”

Henry:
Where are you in the process of building the ADU?

Arden:
We actually just got our permit today.

Henry:
Oh, wow.

Arden:
So I have to go tear down a shed and get the lot opened up for it.

Henry:
What are the steps you had to go through to get to essentially the step where you are today? Because I am willing to bet there are tons of people listening to this episode who either are interested in buying a house that has a lot where they can put an ADU on it or probably already have property and their city is now allowing them to build ADUs and are pretty curious about how the process all works. Now keep in mind everybody, every city municipality is going to operate a little differently. So just because this is the way Arden’s done it doesn’t mean it’s going to be the way that you are going to be able to pull it off in your market, but I think this will be still helpful. So you’ve got the house, it’s sitting on a half acre lot, you know you can do an ADU.
What was your first step?

Arden:
Yeah, so the first step is really one, just determining whether or not you can build because at least the way Wilmington works, it can’t be bigger than half the size of your main structure. So if you’re going to build a 300-foot ADU, it’s kind of nothing to it. Next is quotes. We talked to, I don’t know, every general contractor in town who does it and then some specific ADU companies now that it’s been our thing for about a year, there’s a few companies I’ve opened up and we talked to all of them, got quotes from all of them, and finally found one that we just meshed with the best, wasn’t necessarily the cheapest, but just seemed like the highest quality for the best price. Next is their site planning. They have to figure out exactly what they need to do, if there’s utilities that are going to need to be ran or where that’s going to come from.
And then from there, for us, it was financing, figuring out exactly how we’re going to get the funds. Is it going to be cash? Is it going to be a HELOC? And then from there, at least in my book, the third party company has really taken it on to go to the city, get the permits and all of that. So for us, hopefully now it’s just choosing the color of the cabinets.

Henry:
Yeah. Well, that’s the benefit to hiring a third party to do it. So if you’re shopping around for third parties to do it, finding a contractor who’s going to go fight all the battles with the city and get the permits for you is definitely the way to go. And I like that you got multiple bids from multiple contractors. When you were getting bids, did you already have to know your floor plan or what you wanted to build when you were going to these people? Or did you just go to them and say, “Hey, I have this lot. I can build an ADU. Can you show me what you can do or what I can do here?”

Arden:
Yeah, so I knew about the rule of ADUs. I looked into it, especially with our other lot. I was looking at what we could build there and found the ADUs. Funny enough, I actually stole one of the ADU guys’ free plans that was on the show and took it because it fit almost perfectly in our lot. Oh, man. We ended up having to not go with it because it was a little more expensive than what we wanted to spend. But I took them that plan and was like, “I want something roughly this size and I know it needs to be under 600 square feet.” And then they would come back with a quote on exactly that plan or exactly a plan that was the most similar to it. Most of them had a plan that was close enough. Oh,

Henry:
That’s pretty cool, man. Shout out to Derek, man, the ADU guy on Instagram. If you haven’t checked out what the ADU guy does, he’s such a great resource for being able to build ADU. See this is what he does for a living. He’s been on the BiggerPockets podcast. Great resource. Sweet, man. Thank you for taking us through that. So now you’re at the step where hopefully you can break ground soon, it sounds like. So do you have a timeline on when you expect it to be finished?

Arden:
So they said 150 days from permit, so 150 days from today.

Henry:
Hey, start the clock.

Arden:
Yeah, start it right now.

Henry:
Okay. And do you mind sharing the specs? How big of an ADU, one story, two story, and what’s the total build going to cost?

Arden:
So the total build is going to cost $128,000.

Henry:
That’s amazing.

Arden:
Yeah. So I think it has to be exactly 570 feet, but that doesn’t include the outside area. So we have two outside patios we’re putting, front and back, and it’s going to be a one bed, one bath.

Henry:
Is it like a studio or is it going to be actual bedroom, bathroom, living room?

Arden:
Actual bedroom, bathroom, living room. And right now, one bed, one baths in our area, at least rent from 14, $1,500 a month.

Henry:
That’s cool.

Arden:
Yeah.

Henry:
The next question is the question everybody wants an answer to, which is how the heck did you go about financing this thing? Because that’s the struggle I think people have with building ADUs is there’s not a lot of ADU specific loans out there yet. I think we’re going to get some of that in the future as this becomes more popular, but right now you kind of have to figure out how to bootstrap the money to do these builds. So I’m guessing that’s what part of that HELOC was for, you know?

Arden:
Yeah, so we ended up getting a HELOC for about $45,000, and then the rest is on us. Okay. I don’t really have any other magic way of getting money. Yeah, no,

Henry:
That’s the thing people need to hear. It takes capital to do this, and I would encourage anybody who’s curious about this is don’t just research ADUs, but research any loan programs, grants, help from your cities or municipalities. There are options out there to help supplement some of the financing, but if you’re building an ADU on a property you already have, it’s going to take some cash. You’re going to have to shell out some money to do it because there just aren’t a ton of loans out there for this

Arden:
Yet. We’re actually in talks about getting a roommate again, so we’re going right back to our original strategy of, all right, if we’re here, we got to have a roommate.

Henry:
Yeah. Okay. And do you have any concept of what the entire property might appraise for after it’s all said and done?

Arden:
What I’ve seen is about 70% of the cost of the ADU seems to be added to the home, which would put us probably roughly at 380, 390, which that’s the hard part, but we’re realistically going to be making almost a thousand dollars a month in rent just from the ADU.

Henry:
If your goal is to rent it out and cash flow it, you will absolutely be cashflow positive because you’re going to be able to get around $1,200 a month on the ADU, plus you’re going to be living in the house, so you’re going to be able to have less of a mortgage, especially if you get another roommate. And then if you move out down the road or when you move out down the road, you rent the house, you rent the ADU, and you’re super cashflow positive. So I think that that works. You have to understand real estate’s not a short-term gain. It’s a long-term play. And so in the future, your equity’s going to continue to build, your debt service will continue to go down. I don’t think that that’s a bad thing at all.

Arden:
Yeah. And we actually have an alternative strategy that if depending on finances, we’re actually debating moving into our ADU and renting out the main house because it’s more expensive.

Henry:
All right, Arden, thank you for sharing that story and thank you for being so transparent. I do have a few more questions for you. I want to dive just a little bit into this concept of living frugally and living a little uncomfortably in the short term so that you can truly live the life you want to for the long term, but we’re going to do that right after the break. All right, we are back on the BiggerPockets podcast. I’m speaking with investor Arden Williams, who has pulled off two house hacks and now a living flip and is now taking on an ADU. Before we get out of here on the investment side, I want to talk a little bit about this concept of living frugally. What did living frugally look like for you? What kind of sacrifices did you make in your lifestyle? And then how has making those sacrifice manifested itself in your life now?

Arden:
Living frugally has been probably one of our key strategies. I have a great wife who’s also just as frugal as I am and very conscious on money. She’s our spreadsheet guru, so she tracks all of our spending, which is amazing. We’ve had lots of different ways of just saving a little money. Some of them I don’t recommend at all. House hacking is probably actually the least uncomfortable because if you find someone who you actually generally get along with, it’s not that bad. It could actually be a lot of fun. Doing a live in flip is probably the next step into rough. You come in, your kitchen’s destroyed and your floor is destroyed and the only thing you can do is work after you get off work. That’s not great. But other than that, we’ve always been very mindful on what we spend eating out. And then there for about four years while I was a firefighter, I strictly drove a motorcycle, rain, shine, snow, sleet.
That’s intense. Yeah.

Henry:
Did you have any rules of thumb you lived by in terms of how much you were spending in relation to what you were making? And remind everybody that’s listening, what were you guys making when you first started this real estate investment journey and what were you spending versus what you were making?

Arden:
At the time when I first started, I was making 12, $13 an hour as a firefighter. And then my wife was at the time a teaching assistant and making 12, $13 an hour. And now both of us make roughly about $60,000 a year, so not crazy. We don’t really have a key target that we follow, but we mostly just really focus heavily on not eating out. That’s our biggest, that’s the hardest one for us.

Henry:
People ask me what I do. I eat all my money, guys. That’s what

Arden:
Happens. Yeah. So the big thing is just figuring out what works and the things that you want to spend your money on, and then just trying to limit the things that you’re like, “I don’t actually need this.”

Henry:
And I think the other thing that keeps people from living frugally is this fear of missing out on the fun parts of life or the things that you enjoy. After living frugally for so long, do you feel like you’ve missed out on life or missed out on adventures or missed out on experiences?

Arden:
No, not at all. So between the time we got our first property to the end of 2024, we had three houses. We ended up renting them all out and we actually got just off the money that we were making, we ended up getting to go travel the world for almost a year.

Henry:
That’s really cool. So while both making 60,000 a year?

Arden:
No. So we both quit our jobs.

Henry:
Just traveled?

Arden:
Yeah.

Henry:
That’s super frugal.

Arden:
So after traveling across the country, we were like, “We want to do something cool every five years.” I don’t know if that’ll stay forever, but it just happened to be right at five years. We ended up being like, “Okay, this could be our last chance to do a big adventure.” And so we just saved and saved and saved and saved and saved, cut as many expenses as we could. And this was also during the renovations. So we’re renovating the house, trying to save money because we knew we were going to quit our jobs, and we ended up just saving as much as we could. And then the income we were making from just three properties was enough to cover half of our year of travel.

Henry:
I love it, man. I mean, this is why people invest, right? Being a little uncomfortable so that you can invest in real estate allows you to bring in an income that allows you to live the life that you want to live. And I love that you are the walking embodiment of that. This has been really cool. Before we get out of here, why don’t you give us just a quick recap of what your total portfolio looks like? How many units?

Arden:
Yeah, so all we have is three single family units, and we’re breaking ground on an ADU, hopefully in the next week or two, and we’ll have four units and a piece of dirt.

Henry:
And I like that. And you started in 2021. It’s now 2026, so you didn’t have to scale super fast. You’ve been able to enjoy your life. What are the plans for the future? Are you going to do more real estate deals? Are you going to house hack again? It sounds like you might not do another live and flip, but

Arden:
What’s the plan? Yeah, we’ll see about that one. That one will probably be the hardest to convince my wife of. Yeah, so the plan, definitely to keep doing real estate. I just got my real estate license back in February, so it was mostly for me and my wife in case we wanted to sell something, save us a little money. But I also really enjoy talking to people about this. And a lot of our friends who know us and know what we do have asked us questions about it. So it’s something that we’re definitely pushing. And then realistically, my goal is six to 10 properties. We self-manage everything, so we don’t want a huge headache all the time. Anything more than that, I don’t really need. I’m just looking to make enough money that I can continue to do the trips I want to do and just try and live a little bit.

Henry:
All right. Well, thank you so much, Arden, for sharing your journey, for sharing your experiences. What I love about your story is it is such an achievable path. Anybody can go down this route. You should be proud of what you built. And again, thank you for being open and honest with us and sharing your journey. And I wish you nothing but success as you continue to grow and scale your business.

Arden:
Thank you so much. It was great talking to you.

Henry:
And if you’re listening and you think you’ve got a pretty cool story you’d like to share on the BiggerPockets podcast, then go on over to biggerpockets.com/guest and fill out the form. We could select you, and before you know it, you could be right here on the podcast with Dave or I sharing your story for the benefit of our BiggerPockets community. Once again, thank you everyone for listening to the BiggerPockets Podcast. We’ll see you on the next episode.


Help us reach new listeners on iTunes by leaving us a rating and review! It takes just 30 seconds and instructions can be found here. Thanks! We really appreciate it!

Interested in learning more about today’s sponsors or becoming a BiggerPockets partner yourself? Email [email protected].


Source link

From $12/Hour to 3 Rental Properties and Traveling the World Read More »

Ron Kamler on turnkey reverse mortgage solutions for credit unions

Ron Kamler on turnkey reverse mortgage solutions for credit unions


Ron Kamler on turnkey reverse mortgage solutions for credit unions


What’s New?

Updated 5 minutes ago


Source link

Ron Kamler on turnkey reverse mortgage solutions for credit unions Read More »

Are You Wasting Your Startup’s Runway With the Wrong Product?

Are You Wasting Your Startup’s Runway With the Wrong Product?


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Most product teams struggle because the structure around ideas and team talent isn’t optimized for impact.
  • A framework is a set of best practices, not an ironclad rulebook. The teams that get this right understand why each step exists, but also know when to use judgment instead.
  • Orient everything toward impact because that’s the only metric that actually matters.

The most common way startups burn through financial runway isn’t a bad hire or a botched launch. It’s building the right product, but for the wrong reason, at the wrong time and without enough validation that customers will actually want it. I’ve seen it happen at companies with great teams, strong funding and real market opportunity. 

Here’s what we’ve learned about keeping a product team oriented toward impact and away from the kind of well-intentioned “busywork” that can kill off startups.

1. Prototype the process itself

Most founders are rigorous about validating products before launching them. Fewer apply that same discipline to how their product team actually operates. They convene large groups, whiteboard a process, roll it out… and then watch it fall apart under real conditions because nobody pressure-tested it first.

The solution is to treat your process itself like a product. Start with a small group — perhaps two or three people with genuine cross-functional exposure — then run through real decisions fast. What you’re looking for are the questions that surface every single time you evaluate an opportunity. Those recurring questions become the foundation of the evaluation framework. As CEO, your job is to help make sure that framework exists and that the team is working within it, not to be in every room where decisions get made.

For example, a two-person team at a software development company might discover that every feature discussion comes back to one question: “Will our enterprise clients’ legal teams actually approve this?” Surfacing issues like this early and building them into the evaluation framework saves weeks of wasted effort. 

Or consider a consumer app team that kept building features users said they wanted in surveys, only to see flat adoption at launch. This could be because they never validated whether each feature fit the actual usage context and wasn’t just answers to a survey.

The goal is a process blueprint you can pressure-test and evolve as needed.

2. Put cross-functional generalists at the center of the process

From a founder’s perspective, one of the most consequential hiring and organizational decisions you’ll make is who sits at the center of your product process. Product teams naturally play a connector role between engineering, client success, legal, marketing and operations. But that role only works if the people filling it have genuine exposure across those domains, not just a passing familiarity. 

The most valuable contributors in your product process aren’t necessarily the most senior people in a function. Instead, the people who wear enough hats and can represent multiple perspectives, anticipate friction from teams they don’t officially belong to and make judgment calls that account for a fuller picture are the ones you want driving the conversation.

Be intentional about identifying those types of team members. They’re often not the ones with the most obvious titles. But they are often the ones identifying early issues in your roadmap.

3. Front-load validation

Runway is finite, and every build decision is actually a capital allocation decision. One of the most expensive mistakes is a well-built feature that nobody wants. By the time teams discover a post-launch product-market fit problem, they’ve already spent the time building it, absorbed the opportunity cost and potentially confused target customers.

Before committing serious build time, pressure-test every idea against a few essential questions: Does this solve a real problem your customer actually has and not just one they described in a survey? Is there a plausible path to revenue generation? And relative to the level of effort, does it have meaningful revenue potential?

Rank ideas by impact divided by effort. It doesn’t need to be a sophisticated formula; a simple high/medium/low estimate on both axes can get you most of the way there. And complete the customer validation before you build, not after. By the time the product ships, you should already know who will want it.

4. Measure the machine, not just the output

CEOs monitor revenue. But if you’re only measuring what ships and what it earns, you’re seeing the outcome without understanding the process behind it. The health of your product function shows up earlier in the pipeline. If you’re not watching those signals, problems compound before they show up in the P&L. 

The most useful process signal to track is adoption rate at launch. If validation was done correctly upfront, customers should already be lined up when it ships. A feature with no adoption is basically just sitting in a “warehouse;” unsold and unused. 

Earlier in the product pipeline, track the volume and quality of ideas moving through each product validation stage. A well-functioning product team should be like a machine, consistently outputting impact. And as CEO, you should be able to see how well this machine is running before it impacts your financials.

5. Process should accelerate throughput, not create bureaucracy

The word “process” makes founders cringe, because processes can often be bureaucracy in disguise.

The only process worth keeping is one that makes your team faster at value creation. Every checkpoint in a process should exist because it demonstrably reduces wasted effort downstream. If it doesn’t, cut it. And trust your team to interpret process frameworks intelligently. Empower them to skip a step when it’s warranted, as long as it’s flagged so everyone stays aligned. 

The common thread

The common thread across all five of these principles is intentionality: being intentional about who’s in the room, what gets built, in what order and why. Most product teams struggle because the structure around ideas and team talent isn’t optimized for impact. As CEO, it’s ultimately your responsibility to get structure right. 

A framework is a set of best practices, not an ironclad rulebook. The teams that get this right understand why each step exists, but also know when to use judgment instead. Orient everything toward impact because that’s the only metric that actually matters.

Key Takeaways

  • Most product teams struggle because the structure around ideas and team talent isn’t optimized for impact.
  • A framework is a set of best practices, not an ironclad rulebook. The teams that get this right understand why each step exists, but also know when to use judgment instead.
  • Orient everything toward impact because that’s the only metric that actually matters.

The most common way startups burn through financial runway isn’t a bad hire or a botched launch. It’s building the right product, but for the wrong reason, at the wrong time and without enough validation that customers will actually want it. I’ve seen it happen at companies with great teams, strong funding and real market opportunity. 

Here’s what we’ve learned about keeping a product team oriented toward impact and away from the kind of well-intentioned “busywork” that can kill off startups.

1. Prototype the process itself

Most founders are rigorous about validating products before launching them. Fewer apply that same discipline to how their product team actually operates. They convene large groups, whiteboard a process, roll it out… and then watch it fall apart under real conditions because nobody pressure-tested it first.


Source link

Are You Wasting Your Startup’s Runway With the Wrong Product? Read More »