Blog

Why Your Business Plan Needs Room to Change

Why Your Business Plan Needs Room to Change


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • A business plan can provide direction, but when market conditions or regulations change, sticking to it at all costs can put growth at risk.
  • Changing a plan doesn’t mean giving up on the goal. It might mean delaying a launch, scaling back expansion spend, shifting to a different jurisdiction or narrowing the product to what you can responsibly deliver.
  • You can create habits that help the business respond well to changes: regular strategy and financial reviews, scenario planning and crisis preparedness, and building a culture of adaptability

One of the hardest decisions for entrepreneurs is not making a plan. Changing the business roadmap can feel like a loss of credibility. It’s admitting that a plan you believed in, invested in and asked your team to follow no longer makes sense.

To me, true business maturity is knowing when to let go of the original plan, adapt to changing circumstances and move forward in a new direction. Throughout my career running a legal consulting firm that advises fintechs on licensing and expansion, I’ve dealt with compliance every day. 

My experience has shown that regulatory developments can reshape the business landscape with little warning, and sometimes, growth begins with recognizing that the assumptions behind the original plan no longer hold.

It’s not an unusual challenge for business leaders. KPMG’s 2025 Global CEO Outlook reads that 72% of CEOs had already adjusted their growth strategies in response to interconnected challenges.

That figure doesn’t tell us whether those changes succeeded or whether the CEOs changed their ambitions. It does show, however, that revisiting a strategy is a familiar part of leading through uncertainty, not necessarily an admission that the original plan was badly conceived.

For fintech and crypto firms, the distance between a business plan and reality can widen rather swiftly. According to The Atlantic Council’s September 2026 tracker, digital currencies are classified as legal in 45 countries, partially banned in 20 and generally banned in 10. 

Consider a company preparing to enter a new market. It has budgeted for licensing, hired a local team and set a launch date. Then regulatory requirements change, banking partners become harder to secure, and the cost of entering the market rises.

The question is no longer whether the team can deliver the original plan. It is whether doing so still makes business sense. In an environment this fragmented and dynamic, I would start with a straightforward question: “Given what we know now, would we make the same decision today?” If the answer is no, it’s worth understanding why before committing further money or people.

Tweak your vision without losing sight of the goal

Changing a plan doesn’t mean you’ve given up on the objective. It might just involve postponing a launch, scaling back expansion spend, shifting focus to a different jurisdiction or narrowing the initial product to what the company can responsibly deliver.

I learned this firsthand when a geopolitical shift caused us to lose half our market virtually overnight. It was a stark reminder of how costly it can be to rely on a fixed roadmap because the plan was built for conditions that no longer existed. It reinforced a lesson I’ve carried into later decisions: Strategy needs room to adapt when circumstances change.

We still hold a five-year vision of where we want to be, alongside an annual plan that guides our priorities. We review our metrics and assumptions every month and conduct a deeper strategic review every three to four months. In some cases, we adjust these roadmaps even more often, because industry regulation moves faster than any planning cycle can keep up with.

My business decisions rest on concrete questions:

  • Can we operate lawfully and sustainably in this market?
  • Do we understand the full cost and likely timeline?
  • Are qualified banking, payment and technology partners available?
  • Can our teams support the expansion or restructuring without compromising existing customers?
  • What evidence would make us confident enough to proceed?

They help me decide whether to move ahead, pause or change course, and stop “being cautious” from becoming an excuse to avoid making a decision.

The real reason changing a plan feels so hard

Changing course is also hard because clients, employees, investors and business partners may have already invested time, money and trust in the original plan. Changing direction means reconsidering not only your own decisions but also the commitments and expectations you’ve created for others. And this is exactly why it calls for honesty about uncertainty.  You simply need to explain what the company knows now, what remains unclear and what it will do next.

From a practical standpoint, your employees need to know what changes in their work, customers need realistic expectations, while investors and partners need to understand which risks the company is reducing and what conditions would justify resuming investment.

“We are delaying the launch because we cannot yet support it responsibly under the current conditions” is more helpful than a fog of corporate euphemisms. 

To make future course corrections easier, it’d be good practice to create habits that help the business respond well to whatever changes come next:

  • Regular strategy and financial reviews: Put a monthly review of your finances, strategy and priorities on the calendar. Check whether the assumptions behind your plan still hold, and move resources when they don’t.
  • Scenario planning and crisis preparedness: Think through the risks that could disrupt your business. Decide what you would protect, what you could pause and who would make the call.
  • Build a culture of adaptability: Make it normal for people to raise concerns and question assumptions. You want to hear about a problem while you still have options, not after it has become expensive.

Ultimately, business maturity is not about sticking to the original plan at all costs. It is about understanding that a plan is a tool for reaching your goals, not a promise to ignore reality.

For entrepreneurs, real leadership means questioning their own assumptions, acknowledging when a strategy no longer works and changing direction when circumstances demand it. The responsibility of a leader is not to defend yesterday’s decisions, but to make the best possible decisions based on what they know today.

Key Takeaways

  • A business plan can provide direction, but when market conditions or regulations change, sticking to it at all costs can put growth at risk.
  • Changing a plan doesn’t mean giving up on the goal. It might mean delaying a launch, scaling back expansion spend, shifting to a different jurisdiction or narrowing the product to what you can responsibly deliver.
  • You can create habits that help the business respond well to changes: regular strategy and financial reviews, scenario planning and crisis preparedness, and building a culture of adaptability

One of the hardest decisions for entrepreneurs is not making a plan. Changing the business roadmap can feel like a loss of credibility. It’s admitting that a plan you believed in, invested in and asked your team to follow no longer makes sense.

To me, true business maturity is knowing when to let go of the original plan, adapt to changing circumstances and move forward in a new direction. Throughout my career running a legal consulting firm that advises fintechs on licensing and expansion, I’ve dealt with compliance every day. 

My experience has shown that regulatory developments can reshape the business landscape with little warning, and sometimes, growth begins with recognizing that the assumptions behind the original plan no longer hold.


Source link

Why Your Business Plan Needs Room to Change Read More »

How to Generate 818K Impressions With Just Your Local Expertise

How to Generate 818K Impressions With Just Your Local Expertise


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Your audience isn’t opening social media for a lecture. They’re looking for signals — buy now or wait, hire the specialist or DIY it, follow the conventional wisdom or trust the contrarian take.
  • Expert content says “here’s what I know.” Decision content says “here’s how I’d think about the choice you’re facing.”
  • For one real estate client, that shift alone drove 818,000 impressions and 25% follower growth in four months.

Most entrepreneurs have been told to “educate the audience.” It sounds right, since educated buyers make better decisions and useful content builds trust.

But a lot of educational content behaves like a textbook in a room full of people who came to make a decision.

Your audience isn’t opening social media for a lecture. They’re looking for signals. Should I buy now or wait? Should I hire the specialist or keep doing it myself? Should I follow the conventional wisdom or trust the contrarian take?

That’s why one of the biggest shifts we’ve made for clients is moving from “expert content” to what I call “decision content.” Expert content says, “Here is what I know.” Decision content says, “Here is how I would think about the choice you’re facing.”

In a recent campaign for a real estate client, we weren’t starting from scratch. The client already had what most professionals in the category lack: real local market knowledge, genuine investment experience and a clear point of view. The issue wasn’t a lack of expertise. Too much of the category sounds the same, with everyone explaining interest rates, neighborhood trends and generic buying tips.

So we stopped treating the content calendar like a list of topics and started treating it like a list of decisions. Instead of explaining a neighborhood, we framed the conversation around whether that neighborhood was undervalued. Instead of posting a broad investment tip, we turned it into a framework for spotting a good investment property. And instead of making a polite market observation, we created comparison content that helped viewers choose between two places, strategies, or assumptions.

The performance changed because the content asked the audience to participate. They could agree. They could disagree. They could imagine themselves making the same call. That’s the difference between content people scroll past and content they stop for.

From May through August, the organic campaign generated:

  • 818,000 impressions
  • 11,515 interactions
  • 25% follower growth
  • A top post that reached 48,000 impressions and drove 1,678 interactions on its own

The common thread wasn’t production complexity or a trend we’d copied. It was the framing. The highest-performing short-form videos helped people make sense of a real decision.

Here’s the framework we used, and how entrepreneurs in almost any industry can apply it.

1. Replace topics with tension

A topic is “how to choose a CRM.” Tension is “the CRM features founders overpay for before they have a real sales process.” A topic is “email marketing tips.” Tension is “why your best customers may not need another discount.”

Tension doesn’t mean being inflammatory. It means identifying the real trade-off your customer is weighing and naming it plainly.

2. Make your audience choose

People engage when content gives them a doorway into the conversation. “Here are three options” is fine. “Which of these three options would you choose if your budget were cut in half?” is stronger, because it gives the audience a role instead of a readout.

This matters most when your buyers are stuck between competing priorities: speed vs. quality, customization vs. simplicity, growth vs. margin and stability vs. experimentation. Your content shouldn’t flatten those trade-offs. It should bring them to the surface.

3. Use comparisons more often than explanations

Comparison is one of the cleanest ways to make expertise usable. “This versus that” forces specificity, and it mirrors how people actually buy, hire and invest. They’re rarely deciding whether a solution is good in the abstract. They’re deciding whether it’s better for them than the alternative.

A strong comparison doesn’t have to crown a universal winner. The best version explains who each option is right for, giving the audience a practical decision rule (way more useful than another list of tips).

4. Give your point of view before your proof

Many entrepreneurs pile on context, credentials and caveats before saying what they believe, and by the time the point arrives, the audience has moved on.

Decision content works better when you lead with your point of view. Say what you believe. Then explain how you got there. That doesn’t mean being careless with nuance. It means respecting the audience’s attention enough to lead with what matters.

Consider two openers:

  • “I’d pay 20% more for a vendor who hits deadlines than save money on one who doesn’t.”
  • “Price isn’t the only factor to weigh when comparing vendors.”

The first gives you an action to take while the second would still be true no matter which vendor you picked.

5. Measure the quality of the reaction, not just the reach

Views matter, but they don’t tell the whole story. Decision content often shows itself in the comments, saves, shares and messages that follow. If people are tagging someone, arguing with the premise, saving the framework or asking a follow-up question, the content is doing more than filling the feed. It’s helping the market think.

Many entrepreneurs make the mistake of believing they need more content ideas. Usually, they don’t. They need sharper decisions inside the ideas they already have.

If you sell software, stop explaining only features and start comparing moments when one workflow beats another. If you run a retail brand, stop only describing product benefits and start helping customers choose the right product for a real situation. And if you advise other businesses, stop only sharing best practices and start naming the tradeoffs leaders are afraid to say out loud.

The internet is overflowing with people who can explain things. Explanation is no longer enough on its own. The entrepreneurs who stand out are the ones who help their audience make a call.

Decision content works because it respects the real reason people pay attention. They’re not just collecting information. They’re trying to reduce uncertainty, defend a choice and move forward with more confidence.

So before you publish your next post, ask one question: What decision does this help my buyer make?

If the answer isn’t clear, the content probably isn’t either.

Key Takeaways

  • Your audience isn’t opening social media for a lecture. They’re looking for signals — buy now or wait, hire the specialist or DIY it, follow the conventional wisdom or trust the contrarian take.
  • Expert content says “here’s what I know.” Decision content says “here’s how I’d think about the choice you’re facing.”
  • For one real estate client, that shift alone drove 818,000 impressions and 25% follower growth in four months.

Most entrepreneurs have been told to “educate the audience.” It sounds right, since educated buyers make better decisions and useful content builds trust.

But a lot of educational content behaves like a textbook in a room full of people who came to make a decision.

Your audience isn’t opening social media for a lecture. They’re looking for signals. Should I buy now or wait? Should I hire the specialist or keep doing it myself? Should I follow the conventional wisdom or trust the contrarian take?


Source link

How to Generate 818K Impressions With Just Your Local Expertise Read More »

What Doing Everything Myself Taught Me as a Founder

What Doing Everything Myself Taught Me as a Founder


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • When I launched my business with an $8,000 credit card, I couldn’t afford a team. Instead, I packed boxes, handled customer service and learned the company from the ground up.
  • Doing the work myself taught me how much work was involved and what customers needed. When I started hiring, I knew what I was asking people to do because I’d already done it myself.
  • I spent money where it mattered. I had to think carefully about what the business needed, rather than what I wanted it to look like in a few years. 

I started my medical business, MedLab International, with only an $8,000 credit card. I used that money to pay for my website and the first batch of inventory, but it also left me in a difficult position. Unless I could start bringing in orders and delivering on my promises to customers fast, I wouldn’t be able to pay my rent.

So, with no outside investment and very little money to work with, I couldn’t afford to hire people to do the work for me back then. I had to figure out how to run the business myself.

I didn’t realize it at the time, but having to do everything myself taught me how my business actually worked. When I eventually started hiring, I had a much better idea of what I needed from people because I’d already done their jobs myself.

Do the work yourself

When you’re bootstrapping a business, you don’t always have the money to hire someone every time a new job needs doing. In the early days of MedLab, that meant I had to do pretty much everything myself.

I packed boxes in the warehouse, managed inventory and negotiated directly with suppliers. I couldn’t afford a forklift, so I climbed warehouse racks to move boxes around. I even drove packages to the post office at 3 p.m. on Saturdays to make sure customers got their orders on time.

Outside the warehouse, I also handled customer support and onboarding. I continued doing much of this work myself as the business grew because I couldn’t afford to build the right team overnight and didn’t want to rush that process.

The hours were long, but doing those jobs taught me how much work was involved and what customers needed from us. When I eventually started hiring, I knew what I was asking people to do because I’d already done it myself.

Spend money where it matters

When you first start a business, it’s very tempting to spend money on things that will make it feel like a proper company. There’s an impulse to splash out on an office, hire a big team or bring outside experts on board. But none of those things necessarily help you make your first sale.

Because I didn’t have venture capital or money to fall back on, I had to be careful about where every dollar went. I negotiated with suppliers, kept costs down wherever I could and put money back into the business rather than buying things we didn’t really need back then.

I couldn’t afford to spend money just because something would make my life easier. I had to think carefully about what the business needed, rather than what I wanted it to look like in a few years. 

Don’t get me wrong, there’s a time to invest in offices and bigger teams. But there’s no point spending money you don’t have on things you don’t need yet.

Know when it’s time to grow

As the business grew, there were more orders to pack, customers to deal with and work than I could realistically handle myself. That’s when I knew it was time to start bringing people in. Luckily, when I started hiring, I knew exactly which jobs I needed help with because I’d already spent countless hours doing them myself.

But knowing which jobs needed filling was only part of it. I also had to find the right people. I’ve always liked hiring people with a chip on their shoulder. People who might not have the most impressive qualifications but have something to prove. I look for people who are willing to work hard and learn as they go.

Some of those early hires from around 10 years ago are still with us today. Seeing them grow with the business, buy homes and support their families has been one of the best parts of the whole experience.

Keep building, even when you succeed

MedLab started out in a warehouse that was around 600 square feet. We then moved into a 1,100-square-foot space and eventually grew into a 160,000-square-foot operation. We also made the Inc. 5000 list, which is something I never would have imagined when I was packing boxes myself and only sleeping a few hours a night.

But even then, I didn’t spend much time celebrating. I put the Inc. 5000 plaques in a closet and got back to work. I’ve since gone on to build several other businesses, and I still love the process of starting something from nothing. I think those early years, when I had no choice but to do everything myself, taught me more than anything else.

Success is not arrival; it is becoming. There is no finish line. The price is the point, and I will keep inching forward every single day forever.

Key Takeaways

  • When I launched my business with an $8,000 credit card, I couldn’t afford a team. Instead, I packed boxes, handled customer service and learned the company from the ground up.
  • Doing the work myself taught me how much work was involved and what customers needed. When I started hiring, I knew what I was asking people to do because I’d already done it myself.
  • I spent money where it mattered. I had to think carefully about what the business needed, rather than what I wanted it to look like in a few years. 

I started my medical business, MedLab International, with only an $8,000 credit card. I used that money to pay for my website and the first batch of inventory, but it also left me in a difficult position. Unless I could start bringing in orders and delivering on my promises to customers fast, I wouldn’t be able to pay my rent.

So, with no outside investment and very little money to work with, I couldn’t afford to hire people to do the work for me back then. I had to figure out how to run the business myself.

I didn’t realize it at the time, but having to do everything myself taught me how my business actually worked. When I eventually started hiring, I had a much better idea of what I needed from people because I’d already done their jobs myself.


Source link

What Doing Everything Myself Taught Me as a Founder Read More »

How This HGTV Star Bought and Revived a 35-Year-Old Salon

How This HGTV Star Bought and Revived a 35-Year-Old Salon


Every great small business has a story, and Entrepreneur’s America’s Favorite Mom and Pop Shops series goes on location to hear them firsthand. In this episode, editor in chief Jason Feifer visits Bethlehem, Pennsylvania, a former steel town that has spent 30 years figuring out what comes next.

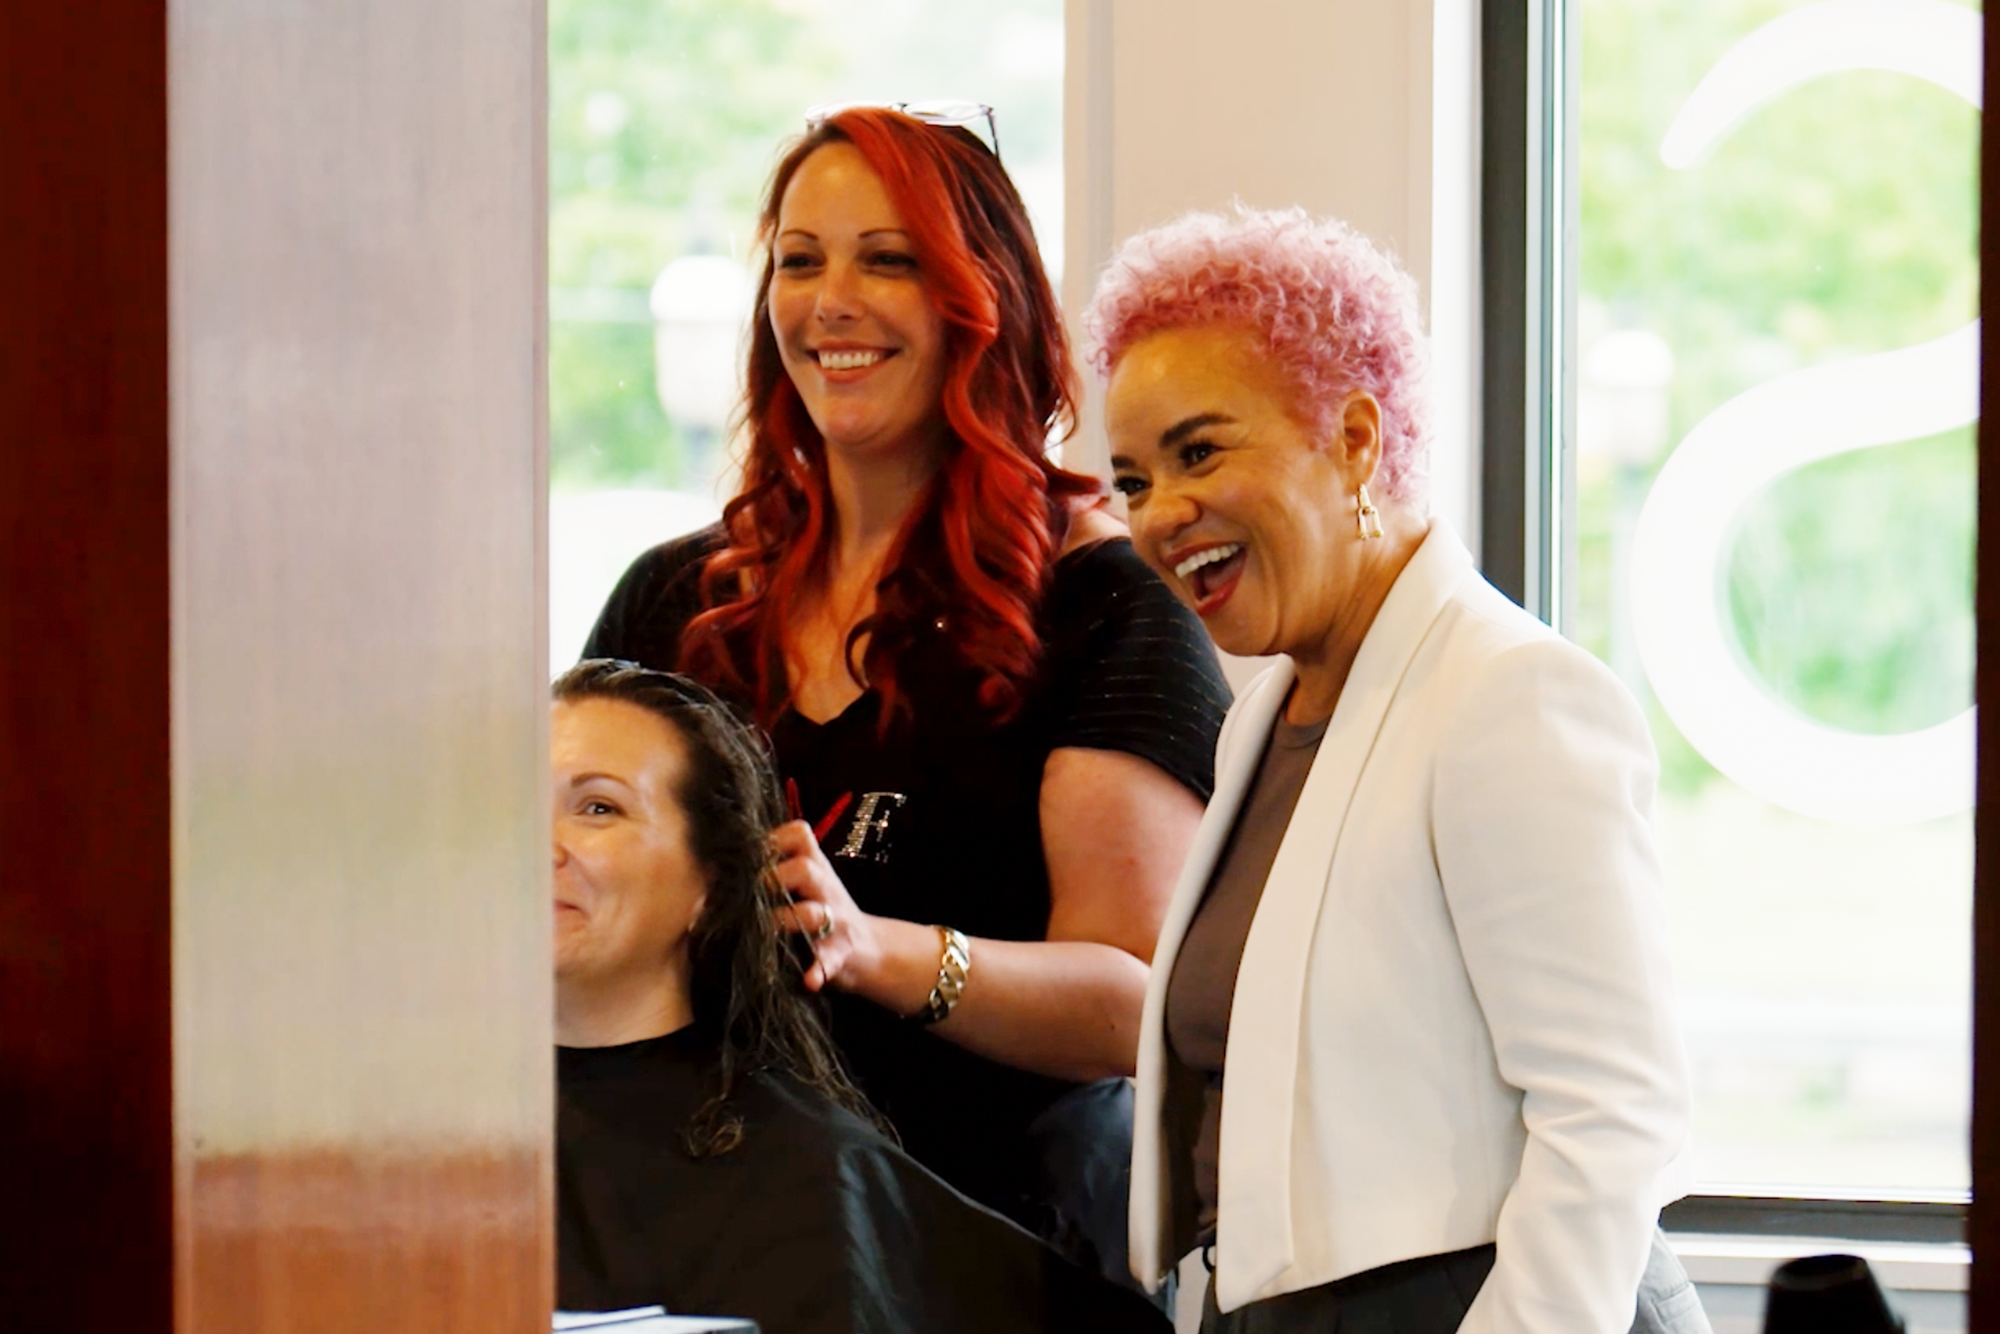
That’s where he meets Kim Myles, who won HGTV’s Design Star and spent two decades on television. A year ago, she and her husband, Scott, bought Gadzooks, a Lehigh Valley salon that has been on the same corner for more than 35 years.

Her first move was doing nothing. Kim promised her team she wouldn’t change a thing for six months, aside from sprucing up the interior. “You be curious, and you shut up, and you listen,” she advises entrepreneurs buying beloved local businesses. The strategy worked, keeping loyal customers coming through the door, while making gradual changes to bring in new ones.

Another out-of-the-ordinary move: While Kim has skills, she doesn’t cut hair at Gadzooks. As Jason puts it, “If a company can’t run without its owner, you didn’t buy a business, you bought a job.”

Gadzooks offers perks that are rare in the salon world, including 401(k)s, maternity leave and mental health leave. Next, Kim and Scott plan to make Gadzooks employee-owned. “We hope by making this an employee-owned company that this outlives us,” Kim says.

Watch the video above to see how Kim redesigned the salon without closing its doors, what building community really means, and why she believes the long way is the right way.

America’s Favorite Mom and Pop Shops® is brought to you by ‪CLA‬. Learn how CLA can help your small business grow.


Source link

How This HGTV Star Bought and Revived a 35-Year-Old Salon Read More »

Why Is Europe Exporting Its Best Tech Founders to the U.S.?

Why Is Europe Exporting Its Best Tech Founders to the U.S.?


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • American AI companies raised $355.9 billion in the first half of 2026 alone, more than eight times the roughly $42 billion Europe raised for AI in the same six months, a gap that keeps pulling ambitious founders west.
  • France carries one of the heaviest tax burden of any major economy, and its exit tax specifically targets founders who leave, taxing paper gains on a company they haven’t even sold yet.
  • Mistral just raised the largest equity round in European tech history, but that same announcement revealed it has quietly stepped back from competing head on for the best model, and is opening its platform to Chinese models instead.

Europe trains excellent AI researchers, and then watches a disproportionate share of them build their companies in the United States. The reasons aren’t mysterious once you look at the numbers, and the last few weeks gave us an unusually clear picture of what Europe is actually competing with.

I’m an AI engineer building ChatMakr, an AI-powered platform that creates multi-agent chatbots in seconds, from France. I also spent two years at an innovation financing firm, working closely with hundreds of Parisian tech founders. Here is what I’ve learned.

Why the European talent keeps leaving

Europe doesn’t have a talent problem. One mapping of global AI professionals estimates that it has roughly 30% more AI talent per capita than the United States. What it has is a capital and customer problem.

The first half of 2026 made that gap concrete: according to AI Weekly, American AI companies attracted $355.9 billion of the $412.7 billion invested by U.S. venture capital, about 86% of all U.S. venture dollars deployed during the period, while Europe’s entire AI venture haul for the same period was roughly $42 billion, about 8% of the global AI funding total.

Even European success stories bend toward the U.S. eventually: Klarna had to rebuild its product “nearly from the ground up” for the American market before its US revenue grew 58% year over year. Nvidia agreed to acquire Hugging Face for $12.93 billion in early September, and the deal represents an extraordinary exit for its three French founders, but Hugging Face was founded in 2016 in New York City, not Paris. Swedish startup Lovable is one of the rare exceptions, reaching a $6.6 billion valuation and $400 million in revenue without restructuring around a U.S. move.

The tax cost

Funding is only half the story. What happens once a company actually succeeds matters just as much, and this is where France in particular becomes a concern for founders. In the latest OECD data, covering 2024, France had a tax-to-GDP ratio of 43.5%, the second-highest in the OECD.

Then there’s the exit tax itself. If a founder has been a French tax resident for at least 6 of the previous 10 years and holds shares with an aggregate value exceeding €800,000, or shares representing at least 50% of a company’s profit rights, moving their tax residence out of France triggers taxation of the unrealized gain on those shares. A founder sitting on millions in paper gains can therefore face a potentially six- or seven-figure tax liability triggered by the move, even without having sold the shares.

A different funding mix

The funding that does exist in Europe also looks structurally different from what’s available in the U.S. Y Combinator and the broader American VC system give founders relatively fast equity financing in exchange for ownership and the expectation of rapid growth.

Europe, by contrast, has a much larger ecosystem of public and non-dilutive funding. In France, Bpifrance’s Prêt d’Amorçage can provide €50,000 to €100,000, rising to €300,000 where a regional guarantee is involved; the EIC Accelerator offers grants of up to €2.5 million without requiring equity if a company applies for grant-only support; and Germany’s ZIM programme provides substantial R&D subsidies, with eligible costs for individual projects now reaching €690,000. These programmes can help founders preserve their equity, but they generally come with more eligibility requirements, documentation and application processes than a VC round, and they don’t provide the same investor network or direct pressure to scale that an equity investor does.

Two French tax mechanisms are genuinely generous on paper. The Crédit d’Impôt Recherche gives companies a 30% tax credit on eligible R&D spending, with immediate reimbursement available to qualifying SMEs and other eligible companies, and the IP Box also offers a 10% preferential regime for qualifying IP income, including income from certain copyright-protected software, something the U.S. has no direct equivalent for. In practice, however, they can be difficult to use. R&D tax claims face detailed eligibility rules and scrutiny, and plenty of founders I’ve worked with either underclaim out of caution or skip these programs entirely because they don’t know the filing process well enough to trust it.

Mistral is betting beyond the frontier-model race

On Sept. 8, Mistral raised €3 billion in a Series D round led by Samsung at a post-money valuation over €21 billion, described as the largest equity funding round in European tech history. That’s genuinely a record, and it should be treated as one.

But read past the headline number and the strategy shift is just as notable. Mistral is no longer consistently at the top of the raw model benchmarks. On SWE-bench Verified, a widely used coding benchmark, DeepSeek V4 Pro leads at 80.6% and Qwen 3.6-27B scores 77.2%, while Mistral isn’t competitive at that tier. The strategy is broadening beyond the race to build a single best-in-class model. Mistral is investing heavily in compute, infrastructure and sovereign AI, while opening its platform to third-party models. The first one Mistral added wasn’t a European model: GLM-5.2, built by the Chinese lab Z.ai. The strategy suggests that Mistral sees owning the sovereign infrastructure layer as potentially as strategically valuable as competing at the model layer, even if that means hosting a Chinese competitor’s weights.

The bottom line

None of this means Europe is out of the race. Mistral’s move toward sovereign infrastructure is a genuinely different bet than trying to out-model OpenAI or Anthropic, and it might be the smarter one long term if European governments actually prioritize data control the way they say they do. The Hugging Face outcome shows that European founders can build category-defining companies. If Europe wants that story to end differently next time, the fix isn’t more talent. It’s more capital willing to bet on that talent before it boards a flight to San Francisco.

Key Takeaways

  • American AI companies raised $355.9 billion in the first half of 2026 alone, more than eight times the roughly $42 billion Europe raised for AI in the same six months, a gap that keeps pulling ambitious founders west.
  • France carries one of the heaviest tax burden of any major economy, and its exit tax specifically targets founders who leave, taxing paper gains on a company they haven’t even sold yet.
  • Mistral just raised the largest equity round in European tech history, but that same announcement revealed it has quietly stepped back from competing head on for the best model, and is opening its platform to Chinese models instead.

Europe trains excellent AI researchers, and then watches a disproportionate share of them build their companies in the United States. The reasons aren’t mysterious once you look at the numbers, and the last few weeks gave us an unusually clear picture of what Europe is actually competing with.

I’m an AI engineer building ChatMakr, an AI-powered platform that creates multi-agent chatbots in seconds, from France. I also spent two years at an innovation financing firm, working closely with hundreds of Parisian tech founders. Here is what I’ve learned.

Why the European talent keeps leaving

Europe doesn’t have a talent problem. One mapping of global AI professionals estimates that it has roughly 30% more AI talent per capita than the United States. What it has is a capital and customer problem.


Source link

Why Is Europe Exporting Its Best Tech Founders to the U.S.? Read More »

5 Psychology Tips for High-Stakes Negotiations


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Prepare emotionally, not just strategically. Stay calm and know your bottom line before you walk in, so pressure doesn’t push you into concessions you’ll regret.
  • Communicate with clarity and restraint by stating facts, impact, needs and consequences, then pausing to let them land. The goal is a deal that leaves the relationship intact.

Negotiation is never just about the terms on the table. Beneath every exchange is a psychological layer shaped by stress, emotion, boundaries and our need for safety and control. That layer runs through every difficult business conversation — and ignoring it can be costly.

I’ve spent much of my career running businesses and navigating high-stakes negotiations within them. Across those experiences, one lesson has stayed constant: Be human first. The most effective negotiations I’ve been part of were the ones where both people walked away with the relationship intact, because neither became so focused on controlling the outcome that they stopped paying attention to what was happening in the room.

These are the five principles I return to again and again.

1. Regulate before you negotiate

Our nervous systems affect one another in ways we can’t see. In clinical work, we call this co-regulation: One person’s ability to stay calm and grounded can become a stabilizing reference point for the other.

That’s why I treat regulation as part of preparation. Before an important negotiation, I notice whether I’m rushing, tense, angry or carrying stress from something unrelated. Sometimes the most useful preparation isn’t another 10 minutes refining an argument but 10 minutes walking, breathing, moving and becoming aware of what’s happening internally. Grounding reduces impulsive reactions and emotional spirals because it brings our attention back to the conversation in front of us rather than the threat we think we’re facing.

As leaders, our job is to stay regulated enough to keep our judgment. If you can’t steady yourself, how will you steady your team?

2. Know your limit before you walk in

Many people enter negotiations knowing what they’d like to achieve. Far fewer know the minimum they’re truly willing to accept, and those aren’t the same thing. The outcome you hope for is your ideal scenario. The minimum you can accept is your boundary.

You need to know your boundaries before you walk in, because they’re much harder to identify under pressure. If you haven’t decided in advance what you’re protecting, it’s easy to make concessions you never intended or to agree to something simply because you’re anxious about losing the opportunity.

That clarity changes how you communicate. We need to remain the authors of our own participation. When we feel we’re losing our autonomy, as leaders or as employees, resentment builds. Knowing our needs before we negotiate preserves our self-respect.

3. State the facts, then the impact, need and consequence

Many high-stakes conversations become needlessly complicated because people speak from their emotional reactions. Facts, interpretations, needs, expectations and pressure get mixed together, and the other person ends up responding to the emotional charge rather than the issue itself. I return to a simple sequence: Describe the facts, explain the impact, name the need and, when necessary, state the consequence.

Start with what’s observable. What happened? What changed? What was actually agreed? Facts create a shared reference point and leave less room to argue about motive or intention. That’s especially important when expectations were never clearly communicated in the first place. A person may agree to one set of terms while privately expecting them to evolve, then feel betrayed months later even though nothing objectively changed. Returning to the facts separates what was agreed from what was assumed.

Next, describe the impact on you. That doesn’t mean accusing the other person of causing your feelings. It means explaining your own experience and taking responsibility for it. From there, name the need beneath the reaction. A need isn’t a demand. It’s information about what will allow you to stay aligned going forward.

This is where negotiations often become more psychologically interesting than the surface issue suggests. A disagreement about compensation may not be only about money. It may be about financial security and fairness. A disagreement over a title may really be about recognition for one’s contribution.

The consequence comes last, and it isn’t a threat. It’s simply what happens if the need can’t be met. Sometimes that means changing the scope of an agreement. Sometimes it means walking away. Good negotiation isn’t about forcing the other side to give you what you want. It’s about being willing to realign your choices with your limits when an arrangement no longer works.

The clearer this sequence becomes, the less likely the conversation is to descend into accusation and defensiveness.

4. Say less than your impulse wants you to

We often mistake speed and volume for confidence. In reality, one of the clearest signs of confidence in a difficult conversation is the ability to pause. Silence is uncomfortable because it takes away our ability to manage the other person’s response. Once we’ve said something important, we often feel an immediate urge to soften it, explain it again, add context, make a joke or fill the space before the other person has had time to think.

In therapy, silence is often used deliberately because it creates room for thought rather than reflex. The same is true in negotiation. A pause lets what’s been said settle. It gives both people a moment to notice what’s happening before reacting. Confidence is being able to state something clearly without arguing for your right to say it.

The same goes for listening. If you’re constantly preparing your next response, you aren’t really listening. Reading the room means paying attention not only to the words being spoken but also to shifts in pace and tone, withdrawal, hesitation and your own physical reactions. Saying less gives you access to more information.

5. Stop treating the conversation like a scoreboard

Most negotiations take place within relationships that need to continue after the meeting ends, and that changes what winning should mean. When a conversation becomes a zero-sum game, where one person’s gain requires the other’s loss, the relationship can become collateral damage. If you secure every term you wanted but destroy the trust you need to work together afterward, is that really a win?

Two people can disagree without the relationship collapsing. For me, winning a negotiation means looking beyond the immediate moment. It isn’t about whether you walked away with everything you wanted. It’s about whether both people leave with their dignity and their ability to work together, intact.


Key Takeaways

  • Prepare emotionally, not just strategically. Stay calm and know your bottom line before you walk in, so pressure doesn’t push you into concessions you’ll regret.
  • Communicate with clarity and restraint by stating facts, impact, needs and consequences, then pausing to let them land. The goal is a deal that leaves the relationship intact.

Negotiation is never just about the terms on the table. Beneath every exchange is a psychological layer shaped by stress, emotion, boundaries and our need for safety and control. That layer runs through every difficult business conversation — and ignoring it can be costly.

I’ve spent much of my career running businesses and navigating high-stakes negotiations within them. Across those experiences, one lesson has stayed constant: Be human first. The most effective negotiations I’ve been part of were the ones where both people walked away with the relationship intact, because neither became so focused on controlling the outcome that they stopped paying attention to what was happening in the room.

These are the five principles I return to again and again.


Source link

5 Psychology Tips for High-Stakes Negotiations Read More »

Megan Thee Stallion Says This Was Her ‘Biggest Mistake’ Early On

Megan Thee Stallion Says This Was Her ‘Biggest Mistake’ Early On


Key Takeaways

  • Megan Thee Stallion is the stage name of the three-time Grammy Award-winning rapper Megan Pete.
  • At Entrepreneur’s Overcoming Impossible event, Pete said that her biggest mistake was being scared to ask questions about her contract.
  • Now, if she doesn’t understand something, she asks about it.

Before Megan Thee Stallion made it big and signed her first record deal, she thought that rappers made a tremendous amount of money. She saw the social media posts they made sporting new cars and fancy clothes. She couldn’t wait to become a rapper and take care of her whole family.

However, the three-time Grammy Award-winning star, whose real name is Megan Pete, said that the reality of her first record deal was that she wasn’t getting paid what she was worth. 

At Entrepreneur’s Overcoming Impossible event last week, Pete said that when she signed her first deal, she knew “it wasn’t the best deal.” What pushed her to sign it was the knowledge that she was going to be able to take care of her mom and pay the bills with the money. She was excited to “take care of her people.”

However, the bigger she got, the more she realized how much her likeness and sound were worth.

“I started realizing I’m not making as much money as I should be making because I kind of just gave my life away to somebody else,” Pete said. “I had to take a step back and think, Okay, let me see what’s going on with my contracts. Let me figure out how I can be my own boss.”

Her biggest mistake

Pete said that her biggest mistake early on was being scared to ask questions about her contract.

“I was a little bit nervous about asking questions,” she said. “I feel like that is one of the biggest things that hold people back, being afraid of sounding stupid.”

Pete said that now, if she doesn’t understand something, she asks.

She added that she didn’t just want to be famous; she wanted to own her own music. Ownership became important to her because she was putting in all the work and felt like she wasn’t receiving anything back.

Asking questions and trying to figure out how she could be her own boss paid off. In 2024, Pete signed a deal with Warner Music Group that allowed her to have full ownership of her masters and publishing. She retains her independence as a musician while tapping into Warner Music for promotion and marketing.

“I do own my masters,” Pete said. “It was important to me, coming out of a situation where I didn’t own anything and I didn’t have control of my career. I just didn’t want to ever be in that position again.”

Her motivations

Only one topic made Pete tear up on stage. 

It happened when she was talking about her “North Star,” or the guiding light that keeps her focused and shows her the way forward.

For Pete, her North Star is her family. Her mom, dad, grandmother and great-grandmother are her foundation.

“I do things that I feel like they would have wanted to see me do,” she said. “I just keep them in mind, and I just know that my mom is proud of me, my dad is proud of me.”

Wiping away tears, Pete said that her responsibility is bigger than herself. She wants to make her family proud and give her fans “little pieces” of her to incorporate into their everyday lives. She filters decisions by how her family would respond to them.

Pete also said that anyone in any career path can achieve success. They just have to follow one principle: Be true to themselves.

“When they’re being authentic to themselves, that’s when they win,” Pete said. “That’s when they’re most successful.”

Key Takeaways

  • Megan Thee Stallion is the stage name of the three-time Grammy Award-winning rapper Megan Pete.
  • At Entrepreneur’s Overcoming Impossible event, Pete said that her biggest mistake was being scared to ask questions about her contract.
  • Now, if she doesn’t understand something, she asks about it.

Before Megan Thee Stallion made it big and signed her first record deal, she thought that rappers made a tremendous amount of money. She saw the social media posts they made sporting new cars and fancy clothes. She couldn’t wait to become a rapper and take care of her whole family.

However, the three-time Grammy Award-winning star, whose real name is Megan Pete, said that the reality of her first record deal was that she wasn’t getting paid what she was worth. 

At Entrepreneur’s Overcoming Impossible event last week, Pete said that when she signed her first deal, she knew “it wasn’t the best deal.” What pushed her to sign it was the knowledge that she was going to be able to take care of her mom and pay the bills with the money. She was excited to “take care of her people.”


Source link

Megan Thee Stallion Says This Was Her ‘Biggest Mistake’ Early On Read More »

Rentals Helped Me Quit My 14-Year Nursing Job (And Start My Own Business)


Lindsay Barrientos didn’t start buying rentals after the 2008 crash or ride the low-interest-rate wave in 2021. She started in late 2022, after home prices and interest rates had already spiked. But she knew about the long-term potential of real estate and trusted the process—buying one house at a time and banking the rental income for the next down payment.

Now, just four years later, Lindsay’s 12-property portfolio has given her the flexibility to go back to school, quit her grueling W-2 job, and start her own business. And she didn’t do anything the average investor can’t do today. She lives in a high-cost-of-living area, so she invests in a real estate market where her money goes further. Her properties are 2,000 miles away, so she leans into her investing team.

No “perfect” timing. No big bank account. Just a plan and simple, consistent action.

Whatever’s keeping you on the sidelines—prices, rates, the economy—Lindsay’s story may be the push you need to get started today.

Henry:
Have you ever thought that maybe real estate investing isn’t worth it anymore? Well, Lindsay Barrientos didn’t start buying rentals after the 2008 crash or ride the low interest wave in 2021. She started in late 2022 after home prices and interest rates had already spiked, but she knew about the long-term potential of real estate and trusted the process, buying one house at a time and banking the rental income for the next down payment. Now, just four years later, Lindsay’s 12 property portfolio has given her the flexibility to go back to school, quit her grueling W-2 job and start her own business. Also, she didn’t do anything the average investor can’t do today. She lives in a high cost of living area, so she invests in a market where her money goes further. Her properties are 2,000 miles away, so she leans into her investing team. There’s no perfect timing, no big bank account, just plain and simple, consistent action.
Whatever’s keeping you on the sidelines, prices, rates, the economy, Lindsay’s story may be the push you need to get started today. What’s going on everybody? I am Henry Washington, co-host of the BiggerPockets Podcast. Dave Meyers here too, and our guest today is Lindsay Barrientos from Los Angeles. Dave, let’s get to it.

Dave:
Lindsay Barrientos, welcome to the BiggerPockets Podcast. Thank you for joining us today.

Lindsay:
Thank you for having me. This is an honor.

Dave:
Tell us a little bit about yourself. Where are you joining us from today and what’s your story with real estate so far?

Lindsay:
Yes, so I live in LA. I’m a nurse and I’ve been working as a nurse for 14, 16 years now. And I’ve been investing in Rosto for the last four, and I also invest in a city that’s not popular, out of state investor in Gary, Indiana.

Dave:
As a nurse living in a very expensive market, what influenced you to not just invest, but to invest halfway across the country?

Lindsay:
So I actually was a pretty happy nurse in the beginning. It wasn’t until 2020 during COVID times that I became a front care worker. So I had to deal with a lot of COVID cases, a lot of deaths, a lot of tragedy and a lot of depression actually. A lot of nurses left the workforce during those times and I came with the realization that maybe nursing is not for me. Maybe nursing is not what I want to do for the rest of my life. And I was just 30. I’m like, okay, I’ve been doing nursing for the last 10 years. What else is there? How am I going to be supporting myself and making this income? At the time, I already purchased a single family home in Los Angeles for myself. I had multiple nursing friends and I was renting out rooms to traveling nurses because I was single and I had a four bedroom house and I could just live with my friends, the single girl life.
But when I became extremely distressed and depressed and rich for therapy and medication and got out of that hump, I decided I have to find something else that’s going to be income producing that’s going to either take me away from nursing part-time or take over completely. So I went to Google and I was just like, okay, what do rich people do? How do they make money?

Henry:
I also Googled that when I was looking for extra ways to make money.

Dave:
That’s Henry’s story too. Yeah.

Henry:
Absolutely.

Lindsay:
And Google said, “Well, you can start a business.” And I’m like, “Well, I don’t know how to start a business or you can invest in real estate.” And at the time I was already renting out rooms in my house, so I was just kind of doing real estate. I’m offsetting my mortgage here in LA by renting out rooms. So let me see what else. Can I buy an additional house in LA? And they were like, “Okay, well, if you’re going to buy an additional house and do a conventional loan, you’re going to have to

Henry:
Put

Lindsay:
20% down.” And I’m like, “20% down at a million dollars, that’s $200,000. I don’t have the kind of money. I’m a nurse. So I’m just going to see where else can I invest, maybe out of state, maybe whatever.” And then that came with also another realization that the rest of the country is less expensive than Los Angeles, California.

Henry:
How about that?

Lindsay:
Yeah. So I started doing my market research and then obviously Google told me, “Listen to BiggerPockets, listen to podcasts, read these books.” So I ended up reading a lot of Brandon Turner’s books initially, and then I turned into BiggerPockets and learn about market indicators and what do you want to look at? Cash flow, cash and cash return, reserves, repairs. So for my situation at the time, I decided I need to be in a state that is landlord friendly and a market on lease that has a high cash on cash return. So the first market that ended up investing is in Northwestern Indiana, Hammond. And that’s when I found a network of investors already investor in Northwestern Indiana. And I was introduced to many property managers and realtors and actually a network of investors there.

Dave:
I want to call out that you’re selling yourself a little bit short, Lindsay, because you were an investor and you did start a business. Even buying a single family home and renting it out to your friend is a successful business in itself. I guess you just never even saw yourself as an investor when you were doing that.

Lindsay:
Yeah, I didn’t. And even after I got A properties, I was going to real estate meetups around my area and I was like, “I guess I’m an investor. I’m not sure.”

Dave:
It’s very humble of you and the opposite of what you hear on social media all the time. But investing in Indiana, it could be scary to do that. We’ve never been to the area, but you at least look back on your time renting out rooms in your home and see the potential for it. Did that give you some confidence at least?

Lindsay:
It gave me confidence in terms of like, okay, I have this much income and I have this much expenses by house hacking at the time I didn’t know I was doing that. I was decreasing the expenses that I had. So I had the extra amount of income to deploy it in an investment. So I was like, “I’m saving this much money and I can just funnel it into this investment that’s also going to bring me more money.” So I was just like, “Okay, I can see how that can compound over time.” Even though at the time I wasn’t looking like, “Oh, I’m going to get 10 houses or 12 houses.” I’m just like, “Two or three houses.”

Dave:
Right.

Henry:
So many new investors or even seasoned investors struggle with the idea of where should I invest? Can you give just a little more context as to how you got comfortable with the decision you made?

Lindsay:
Yeah. Initially I was ready to take a traveling nursing job and I was like, okay, I have to go to a city that it’s going to be competitive for me to get a contract so I could possibly house hack. And I’m like, okay, I could go to New York. And I’m like, what am I going to invest in New York? I could go to Chicago, I can maybe house hack a condo there and I can start renting out rooms like I’m doing in Los Angeles. And I was like, but if I’m going to be in Chicago, let me see what’s near there. Driving distance. And Northwestern Indiana is 30 minutes down south from Chicago. So that’s when I started looking at that. And then I was just like, well, who else is investing there? Let me find out. So BiggerPockets, blogs, podcasts, all of those, reaching out to people online that had a small YouTube channels and small followings that were investing, that were putting their numbers, all social media and being very transparent about their journey.
That’s who I connected with, especially two people, Millennial, Mike, and Masky Finance. And because they were smaller creators, they were willing to talk to me or interact with me via comments or emails or even phone calls at times, like voice audio chats on Instagram that were going on for three minutes at a time. I’m just like, I’m just so happy that I was able to tag into this type of a small community starting. And then so when I looked at Hammond, Indiana, Norwest Indiana, there was already a WhatsApp group chat of investors that had 40 investors at the time. They were sharing tips about realtors, property managers, contractors, and stuff like that. So I felt comfortable because there were vetted people, not just by me, not just out of state. Some people were local. So that’s where I felt, okay, if these people are doing it, then maybe I’m okay to start dipping my toes in it.

Henry:
These were gems. I hope people were listening to this and taking notes. I love that you said, look, I knew I’m going to be in Chicago, so what’s in driving distance? Because if it’s not easy to get to your out-of-state market when you need to get there because something’s going to happen, you’re going to need to get there and it’s going to interrupt your life. And the harder it is to get there, the less likely you are to do it. So including some of these real world scenarios in your market selection is a big deal. The second tier of choices you have to make is very personal. The first tier of choices is about the numbers. You want a market that has a good cash on cash return, that has good jobs, that has enough demand. All the numbers make sense. But once you get past that, the rest is vibes and feelings and are you actually going to go?

Dave:
Also, the people you surround yourself with in that market, that is just so incredibly important. I always tell people, get it down to three to five cities that you like. The vibes are good, the numbers are good. And then where do you have the best people? Because that is going to make a much bigger impact on the performance of your investments than macroeconomics. It really is. Macro, you have to just kind of not screw up, is kind of the way I see it. It’s just find something that’s pretty good. But as anyone will tell you, two investors can invest in the same market. One can be incredibly successful and one can completely fail because they’re not good at it. And so investing out of state is so much about finding people who are good at it.

Henry:
I though that was such a brilliant thing. You said you specifically picked smaller creators. That’s a great niche, a great thing to target. Smaller creators investing in a market that you like, you know they have a tracker, or you at least think they do, and you can do enough research, they can probably have the time to answer you. That’s super smart. Great thing to do.

Lindsay:
Nichingin is definitely whatever market you’re looking at, if it’s Columbus, Ohio, Facebook groups, meetups, whatever you can do to reach out to them and then start talking to maybe not the person that’s a host, but everybody that’s submitting comments or liking or doing anything like, “Oh, have you actually checked out the area? Do you live around it?” Just making conversation and people, especially in Facebook, people going through deep, deep conversations in the comments.

Dave:
That’s great. And I think what you’re showing here, Lindsay, is that this common perception that real estate is really competitive is false. People generally want to help each other. People want to tell you about what they’re doing and want to bring you along. I really love that about real estate, that it’s not this zero sum mentality that if you win, I can’t win. It’s kind of this collective approach. So Lindsay, I want to hear about how specifically you leveraged this community to get your first deal, but we got to take a quick break. We’ll be right back. Welcome back to the BiggerPockets Podcast. I’m here with Henry and investor Lindsay Barrientos talking about how she found a community across the country that helped her buy her first conventional rental out of state. So Lindsay, how did you use the community that you found to identify and ultimately buy your first deal and what did it look like?

Lindsay:
Yeah, and the first step was vetting the people. There’s 40 investors, 40 investors are using about three or four property managers, three or four realtors, different realtors. So you start talking to them and trying to see what they know about the market. And every time, because you don’t know much about the market other than what you find on Google, but the more that you talk to somebody, the more the property manager’s going to be like, “I’m not going to go into that pocket.” And the realtor is going to be like, “Well, most of,” because they can’t really say it, “This zip code doesn’t work for you. Most of my transactions happen in this zip code, right? So you get information from different people, not just the “experts” like property managers, realtors, whatever, but the other investors like, “Oh, this is where a new gymnasium was built.
This is where the casino is coming to be built.” The more data that you have, the better it’s going to be for you.

Dave:
And let me just ask, in this group, were there multiple realtors and property managers or was there just one you knew?

Lindsay:
There was multiple.

Dave:
And how did you decide? Because it sounds like a great group of people. How did you pick which person to work with?

Lindsay:
I think that you have an affinity for certain people when you start talking to them. And then I don’t know about you, Dave, but I feel like I’d like to see more action than talking. You can talk to me on the phone.

Dave:
That’s a good way to put it. Yeah.

Lindsay:
You can talk to me on the phone for two hours, but let me see how many transactions you closed in the last month. What actually are you willing to negotiate for myself? Really test your boundaries a little bit.

Henry:
So Lindsay, what I hear you saying is that you’ve got a good bullshitter, and as you started to talk to people, you could tell who was full of crap and who was actually about their business.

Lindsay:
I would like to think so.

Dave:
I like that. All right, so tell us about this deal. What did you buy?

Lindsay:
Yeah, I did buy a three bedroom, two bath, single family home, 25% down conventional loan. And like I mentioned, I rented the next week that I closed the home and it was rented for $1,400 a month.

Dave:
Wow.

Henry:
135, 25% down. So yeah, 25% of 135 is substantially less than 25% of one million in California. So you did the right math there.

Lindsay:
Yeah.

Henry:
No renovation. Sounds like it was turnkey and you got a decent amount of rent for it. That’s pretty awesome. So just a conventional loan, nothing fancy.

Lindsay:
Nothing fancy. And I think the debt service was 880 at that time because the interest rate had gone up. My interest rate on that first property was 6.01.

Dave:
What was the cash flow at the end of the month?

Lindsay:
1,400 minus 880 plus the property manager is like $400 a month.

Dave:
Wow. Okay, great. And did you have any issues or was it as turnkey as you were expecting?

Lindsay:
It was turnkey. I think I talked to the property manager once in six months about something else. Then after one year, I was trying to make that my proof of concept. So I didn’t want to look at even real estate after that. I bought it. I wanted to be like, “Is this going to work out for me? This is a new venture for me. I’ve never done this.” So let it run for one year. I took it like it was an additional bill, so I just pocketed whatever income I had from the property. And after one year I had $16,000 save and I was like, “Okay, maybe I can look at this Gary Indiana market that my investor friends keep telling me about. They keep buying things over there.” So I’m like, “Okay, maybe I can do that now since I am seasoned. I have one year under my belt of having one rental property.” So I took a look at Gary Indiana and the house was priceless in 2023 when I was looking at it were like 50, 70, 80,000 for a single family home.
So I was just like, “Okay, that’s a significantly less down payment that I have.” But I was like, “Let me try this add value things that BiggerPockets keeps talking about. Buy something that needs a little

Henry:
Bit

Lindsay:
Of work.” So I bought a second home for $55,000 that needed a new roof and new floors, small house, 800 square feet, two bedroom, one bath. And I bought it for 55. I think I put maybe 16 into the house and I rented out for $1,100 to a Section eight voucher holder. So I was just like, “Oh wow, that’s like the 2% rule.”

Henry:
Yeah, you got way better numbers on that deal.

Lindsay:
Yeah. And obviously I’m learning this new market because I did move from Hammonton Gary, which is 15 minutes apart probably by driving, but it is a rougher market and it’s actually according to Business Insider in 2019, one of those most miserable cities in the United States.

Dave:
And you were like, “I want that.”

Lindsay:
Yeah, I want that. There is so much upside.

Dave:
Well, I’m curious. That would scare me.

Lindsay:
So I know that coming into this new market was risky, but the potential for cash flow was higher. And a lot of people think when they look at the tenant pool also there, they think that’s going to be a lot of work. But from my investment strategy, I have a property manager. So majority of the things that I do are through property management because I work a full-time. At the time I was also going to school full-time. So I really needed to see what my set of skill was going to be and my risk tolerance. Am I able to risk more, I guess, headaches for the cash flow? But when I closed on that second property and I rented it right away and I was like, okay, well then my debt service is $388 a month and this is rented for 1,100. Even if the house is empty for a couple months, I’m still pretty much very good about this.
And then the potential for add value was there. So I’m like, okay, let’s do what happens with these two properties. Then the next property, I attempted to do the burn. I attempted to do the burn. And this is a story that’s probably going to, people are going to think I’m crazy, but I bought this house for $33,000.

Henry:
33,000?

Lindsay:
Yes. And I needed to be a whole bird, so I had to put another 30,000 into the house, but my ARB was at 85. So I was like, “Well, I can get most of the money out of this.” And then one of the beauty things about scaling, when you are doing burrs, you can recycle that money. So I was like, “Okay, I don’t have to penny pinch every single paycheck that I have if I’m able to do this successfully or even semi-successfully.” So when I did that burr, I finished, I was getting my refinance done, and I think I had my appraisal scheduled on a Tuesday, and my property manager calls me on a Monday and then tells me there’s been a fire on the house.

Dave:
Oh, no.

Lindsay:
Yeah. So I got on the phone with her. She was like, “I don’t have many details. Let me call you back in two hours. I’m dealing with it right now. The fire department is there.” The house was not occupied at the moment, so that was great. So that already was a relief. Okay, there’s nobody inside the house, but I just finished rehabbing this house last week, and I’m waiting for that refinance. So by the time she comes back, she’s like, “There’s been a faulty lighting on the kitchen that basically burned.” And because it burned, most of the damage that came was from the fire department bolting their way into the door and putting the high pressure hose, right?

Henry:
That’s it.

Dave:
That’s what they sell. I know that came.

Lindsay:
Very nice new drywall painted and everything blown by the pressure of the hose. So that came with the second rehab. At the time I was like, “Oh, maybe I shouldn’t invest in real estate anymore. I don’t know what this looks like.”

Henry:
That’s a fair though to have. I have that moment every week, but go ahead.

Lindsay:
I was talking to Jesus and saying, “Oh, let me just get through this. Maybe I try to do more than I can handle.” Anyways, I talked to my lender and my lender said, “Oh, no worries. Let me know when the house is ready.” Because it ended up being a very small fire. So I was just, okay, I guess I’m going to rehab it again and leave the money that I rehab for the second time into the deal. So I put an additional, I want to say $11,000 into the house to rehab it a second time, obviously going over my ARB, and I was just like, “Oh, I’m just going to leave money behind on the deal.” Refinance the appraisal came back at 160,000 for the house that I bought. So I told myself, “You’re just very bad at comping, comping houses.”

Henry:
You comping way too low.

Lindsay:
Yeah, I did comp it way too low. So I was able to get all my money back from the first rehab, from the second rehab. And then so I did a successful burr and I got the money back. At the time, the money came from a HELOC I leveraged on my single primary residence, so it wasn’t even money I had saved. It was leverage money from the HELOC. So I was like, “I can do this again.” So I did many more times. I ended up racking up 12 properties over the last four years.

Dave:
Wow.

Lindsay:
And the last five had been creative seller financing, and the last one was a 0% down deal.

Dave:
That’s unbelievable. Wow.

Henry:
Yeah, I like those.

Dave:
So I want to hear what you bought. You just casually were like, “Oh, I just bought 12 units,” which is a story in itself that we want to hear about. We do have to take one more quick break though. Stick with us. We’ll be right back. Welcome back to the BiggerPocket Podcast. Me and Henry are here with investor Lindsay Barrientos talking about how she has been scaling up long distance in Indiana. You’ve had some good ones, you had a tough one, but you kept going. What have you been buying?

Lindsay:
Yes, so 12 total now. All of them are single family. I only have one duplex. So the more that I learn about real estate, the more that I talk into wholesalers, but direct front seller, learning about creative financing. When I learned about creative financing throughpocket sales, I was like, “I need to get a house that is creative basically. I got the bug.” So I started telling my realtor to put cash offers and creative offers, and obviously make the creative offer more appealing than the cash offer. So everybody will be determined. But anyways, and that same network that I had, for example, Facebook people that I would talk to online and the WhatsApp group that I would also talk to different investors. There were other investors there that were offloading some of the properties, so that’s where we got connected. That’s how I started getting creative.
I also started a personal brand on YouTube. I opened up a YouTube channel after I think the bird that I did. I felt like maybe this information would be better to be put on videos so people can connect with me or even see what I’m doing or see how the cashflow is possible, even though this was 2024, 2025 with the rates being at seven, eight, you guys have seen it. So I started putting a lot of content out there and then people were offering me deals from Gary Indiana after a while, and that’s how I was able to get creative.

Henry:
You said you had your agent mention that you were willing to do a creative offer. So how did you pitch seller financing or how did you get your agent to pitch it to people as an option for you?

Lindsay:
Yeah, so when you’re a realtor, you can just send a regular offer or you can set an addendum offer, like a regular cash offer or conventional offer or an addendum offers, which if the seller is open to seller finances, they will be able to reply or negotiate the price back. But my experience has been the majority of people that do seller finances because they’ve been investors themself at one point. And so they bought the house a few years ago, so they already had some kind of knowledge. I never been able to convince somebody that’s never heard about seller finance to do a seller finance deal.

Dave:
So you were going out looking for these seller finance deals, and you said you were making cash offers at the same time.

Lindsay:
Yes.

Dave:
You had enough cash to go out and buy these deals, whatever your offer was, if you wanted to, but you gave them two offers at the same time. Can you tell us a little bit more about why you did that?

Lindsay:
Yeah, I heard from Michael Subert, this is something that he used as a technique in the past of when he was buying houses in Fresno. He would present two offers to the seller, especially during these last years where transactions have been low. If you find a motivated seller, you present those two offers. Let’s say it’s a house that I’m buying cash at $60,000. My cash value would be I’m going to offer you $50,000 for the house, but my seller finance deal is going to say, “I will pay you $60,000 for this house, but with my terms.” So that could be lowering the interest rate, that could be a lower down payment, whatever is more preferable to me that also works for the seller. So I would submit those two offers to everybody basically.

Dave:
Wow. I love that. It’s so brilliant. And I think this goes to the exact environment we’re in right now in real estate where sellers, you don’t really know what’s motivating them right now. There are more and more things coming on the market and there’s better opportunities to negotiate, but you don’t necessarily know what they want. Some people want cash and to get out as quickly as possible. Other people, as Lindsay, you stated, if they’ve been an investor before, they might say, “Hey, I’ll take a six or 7% payment well into the future. That’s passive income for me.” And by offering two offers, one, you’re showing the seller that you are willing to understand what they’re looking for and to work with them. And two, it sounds like you can kind of steer them in the direction that you want because you say, “Hey, I could pay cash, that’s probably tempting, but I could pay you less.” And you can sort of orchestrate it so that sellers see the mutual benefit in the seller financing offer.
Curious, how effective is it? How often does that work?

Lindsay:
It works when the market is like this and the sellers are motivated. I was able to get out of the 12, five of them are these seller finance.

Dave:
Yeah, I love that. I mean, that’s better than regular offers, that offers so much better. And how are you identifying people? Because if you’re going 50%, you must have really targeted list of people that you’re approaching for seller financing.

Lindsay:
Yeah, my zip codes are very narrow, so I only invest on three zip codes. And then single family, I know a lot of people like to do multifamily, but in my area, because there’s more supply than renters, I feel that people do want to rent a single family more so than a small rental unit. So that is where basically I’m concentrated. And then it might be a small market, but in Gary, there is a turnkey company that sells houses that flips houses. They also have a podcast. They also are currently posting a lot of content about Gary Indiana and possibly even coming, we have the bears coming to Hammond, Indiana. So just having more information about that. That’s

Dave:
Awesome.

Lindsay:
Yeah. Having more information about that just tells you to exactly reinforces what you invest in already or where you want to be investing.

Dave:
So what’s next for you, Lindsay? I mean, you’ve been scaling up, you’ve been doing a lot, you’re getting the Chicago Bears in Indiana, which is hilarious. What comes next for you?

Lindsay:
Yeah, I also built an ADU in my single family residence. Nice.

Dave:
Are you still in LA?

Lindsay:
Yes. So I did that. I put it as a midterm that’s now rented for $2,000 a month, and I have enough space to put an additional ADU that is in the process of permitting three bedroom, two bath. That will be a small house basically. So hopefully to do a midterm or Airbnb, we’ll see what I can do with it.

Henry:
That strategy in California is just called how to live in California. How to be able to afford to live in California.

Dave:
The good thing is that they are allowing these kinds of developments, right? Because obviously not everyone can do it, but if you can, you are providing housing in a community that really needs it and you are able to make your own cost of living go down. It really is a win-win if you can pull it off. So Lindsay, now that you’ve done this, you’ve done a lot of cool stuff, but your original goal was to get out of nursing. Have you done that yet?

Lindsay:
Not fully, but I’m on my way. So I had two plans. One was to invest in real estate and the other one was to go back to school and get my nurse practitioner license and work outside of the hospital setting. So I achieved that. I worked for the last three years as a nurse practitioner. And since I have the income coming from real estate and I’m house hacking, I decided this is the perfect time to leave my W-2 and start my own business, be a nurse practitioner. So now I’m a psychiatric nurse practitioner.

Dave:
Oh, that’s amazing.

Henry:
So cool.

Dave:
Yes, I like it.

Henry:
That’s

Dave:
So

Henry:
Cool.

Dave:
That is unreal. That is so cool. I’m very happy for you. Wow, what a great story.

Lindsay:
Full circle, right? The Google search in the beginning, invest in real estate, open your own business. That’s basically what I ended up –

Henry:
That’s exactly what you did. That’s exactly what you did.

Dave:
I love it because I mean, you must have been working your butt off the last couple of years. Going to school to become a nurse practitioner is no joke, and investing long distance is no joke, but you did it all. And I imagine you’re feeling like this investment in time and effort has been worth it.

Lindsay:
Yes. And this year it was a whole year plan to quit my W-2. So I had to set myself up for being able to have no paycheck technically, and then it’s still 12 houses, and I still have a house in LA, and I just built an ADU and I’m building another EDU. So I had to set myself up financially to be able to take this big step, and finally the time that I put in my mind has reached, so now I’m fully off W2 being my own boss.

Dave:
So you’re just crushing it is what you’re talking about. You’re just absolutely crushing every part of your life.

Lindsay:
It looks like that from the outside, but in the inside it’s a lot of lack of sleep, I feel like.

Dave:
That does come with it, but there are times to grind, there’s times to enjoy the fruits of your labor, and it seems like you’ve grinded really hard for a couple of years, and now you are reaching your goals. It’s incredible, and you’ve done it in a really fast timeline. I should say that doing it in a couple of years is amazing. And hopefully between having your existing homes, having your own practice, having these ADUs, you can continue to grow in multiple ways. You can be a nurse practitioner, you can grow your practice, and you can grow real estate at the same time. It’s super cool.

Lindsay:
Thank you, thank you. And I also, I built a podcast called Real Estate Chisme, and then this is where we have a free school community online. Anybody can come and check it out. Our goal, I have a co-host, Bileta Sandoval, and we are trying to encourage women, people of color to come and check us out and talk about real estate if that’s something that you want to look at, invest in, or even learn about.

Dave:
Awesome. Thank you so much, Lindsay, for sharing your story and these resources with us. We really appreciate it. And we’d love to have you back soon. We would really like to hear how your story progresses from here.

Lindsay:
Thank you so much.

Dave:
And thank you all for listening and watching this episode of the BiggerPockets Podcast. I’m Dave Meyer. He’s Henry Washington, and we’ll see you all next time.


Help us reach new listeners on iTunes by leaving us a rating and review! It takes just 30 seconds and instructions can be found here. Thanks! We really appreciate it!

Interested in learning more about today’s sponsors or becoming a BiggerPockets partner yourself? Email [email protected].


Source link

Rentals Helped Me Quit My 14-Year Nursing Job (And Start My Own Business) Read More »

The 3 Types of Overload That Hurt Performance

The 3 Types of Overload That Hurt Performance


Opinions expressed by Entrepreneur contributors are their own.

Key Takeaways

  • Leaders and entrepreneurs assume that performance suffers due to a lack of skill, motivation, or effort. Often, the real issue is overload.
  • Overload comes in three forms: Cognitive, emotional and social. Identifying the type is the first step toward managing it effectively.
  • Practice non-reaction to regain control. It creates a deliberate space between what lands on you and what you do about it — a pause just long enough to interrupt reflex.

Open your favorite movie streaming platform tonight, and you’ll choose from something like 100,000 titles. Open your inbox tomorrow morning, and you’ll find five urgent, unrelated projects. Open social media, and you’ll feel, for a few seconds, faintly stupid for not being a multimillionaire yet, because somehow dozens of people your age already are, or say they are.

Open your other social account, and there it is again, the ad for the 60-day calisthenics transformation program, and with it a small shame you’ve watched it three times now and still haven’t started. Scroll for another minute, and you’re no longer sure if what you just read was real or manufactured to look real, and there’s no obvious way to check.

Deadlines, comparison and information movement existed before. What’s new is the volume, the speed, and the fact that it all now arrives at once. Technology moved communication and access faster than anything before it. Organizations got better at generating priorities and initiatives than they ever got at resolving them. The result is a level of input that would have been unthinkable to someone doing your job 20 years ago.

We’ve built an entire industry of tools to sharpen our performance, automate tasks and jobs, even calm us down when it gets to be too much, and many of them are genuinely extraordinary. But they’re built to optimize the load, not to understand it. We say we’re “under pressure” and treat the phrase itself as the explanation, when it’s really just a label for something we’ve never actually looked at closely. Mostly, we default to calling all of it information overload, or to no name at all, just proof that we’re amazing multitaskers, or that we urgently need to become one.

None of this resolves by accident. Two things have to happen. First, you need to know which kind of overload you’re actually dealing with: cognitive, emotional or social, instead of calling all of it “too much” and stopping there. Second, you need a real plan for that specific kind, not just a vague hope to “handle it better.” At first, that plan takes real effort; it feels hard because it’s new. Do it enough times, and it stops feeling like effort. It just becomes how you operate.

Cognitive overload

Start with the one most people already think they know. Cognitive overload is what happens when your mind loses its ability to sort. Long lists are just long lists. The damage starts when everything on it starts looking equally important, so nothing gets the weight it actually deserves.

It takes several recognizable forms, different faces of the same problem. Sometimes it’s an information flood, more data than you can absorb, arriving with no filter attached to decide what matters and what doesn’t. Sometimes it’s the dashboard problem: metrics piled on metrics, numbers updating in real time, and somehow less clarity than you had before you opened the tab.

Sometimes it’s competing priorities, the trickiest version, because they’re often genuinely important, all of them, with no honest way to do justice to more than one or two. Sometimes it’s tech and AI overload — another tool, another notification, another feature promising to save you time that somehow costs you time to learn.

And sometimes it’s strategic distraction: the interesting tangent, the adjacent opportunity, just compelling enough to quietly steal focus from the thing that was actually supposed to matter today.

Emotional overload

Emotional overload develops when emotional demands exceed a person’s capacity to regulate them, through repeated emotional input that never fully clears, until the moment a feeling stops informing your decision and starts making it for you, quietly, without asking permission first.

It has its own set of shapes. There’s emotional contagion, walking into a room and picking up someone else’s stress or bad mood as if it had originated in you. There’s the weight of life-defining choices: education, career, relationships, all of them feeling like a fork in the road you can’t afford to get wrong.

There’s lifestyle performance anxiety, a low, constant hum of pressure to optimize every part of your life at once — your body, your relationships, your morning routine, as if falling behind on any one of them means falling behind on all of them. And at the far end, there’s another real thing: the emotional, financial and reputational fallout of something actually going wrong, a failure that doesn’t stay contained to the one part of your life it started in.

Social overload

This is the one that hides best. From the outside, it doesn’t look like a problem; it looks like being a good colleague, a reliable friend, someone people can count on.

It shows up as communication chaos: chats and emails and calls, all marked urgent, arriving all day without pause. It shows up as endless meetings — too many, too vague, rarely landing anywhere near an actual decision. It shows up as connection overload, the slow accumulation of digital and personal relationships, each one reasonable on its own, all of them expecting a response at the same time.

It shows up as truth distortion, that nagging feeling that what you just read might not even be real. It shows up as verbal exhaustion, conversations that generate plenty of heat and almost no clarity. And it shows up in something smaller and easy to miss: the constant churn of micro-choices, what to watch, what to buy, what to read, what to follow, each one trivial, each one still quietly costing you something.

Modern pressure crowded out the space thinking actually requires, until reacting started to look and feel like competence. It doesn’t always look like speed. Sometimes it looks like rushing forward on the nearest available option, and sometimes it looks like its opposite — endless scanning that never resolves into an actual decision.

Non-reaction

Non-reaction isn’t the opposite of reaction, and it isn’t slowness for its own sake. At its core, it creates a deliberate space between what lands on you and what you do about it, a pause just long enough to interrupt reflex.

Inside that space, something practical happens: Signal gets separated from noise, and competing demands stop being treated as equally important by default. From there, judgment comes back, attention narrows to what actually matters, and decisions regain their proportion.

In practice, it looks like:

  • Observing more and speaking less

  • Choosing deliberately when to engage instead of by reflex

  • Letting an unnecessary argument pass without needing the last word

  • Pursuing the right opportunity instead of every available one

  • Committing to a decision instead of keeping every option open indefinitely, just in case.

  • Focusing on progress and impact, not motion, noise or visible busyness

That’s the shift I explore in full in The Art of Non-Reaction: a structured way to progressively take back control, built around four connected domains. First, leading your inner world — learning to regulate emotion and thinking patterns before they regulate you. Second, anchoring yourself — clarifying the purpose and internal direction that overload is so good at scrambling. Third, creating space, making room, deliberately, for better decisions. Fourth, shaping your surroundings — structuring how the world is allowed to reach you in the first place, instead of absorbing it exactly as it arrives.

Inside those four domains sit actual techniques such as cognitive anchoring, finding strength in solitude, focus frameworks, building real wins into confidence, cultivating observation, cutting the clutter, building resistance to noise and learning to spot what’s fake before it shapes a decision.

The waves haven’t stopped coming; they aren’t going to. But you’re no longer required to meet every one of them the same way.

Key Takeaways

  • Leaders and entrepreneurs assume that performance suffers due to a lack of skill, motivation, or effort. Often, the real issue is overload.
  • Overload comes in three forms: Cognitive, emotional and social. Identifying the type is the first step toward managing it effectively.
  • Practice non-reaction to regain control. It creates a deliberate space between what lands on you and what you do about it — a pause just long enough to interrupt reflex.

Open your favorite movie streaming platform tonight, and you’ll choose from something like 100,000 titles. Open your inbox tomorrow morning, and you’ll find five urgent, unrelated projects. Open social media, and you’ll feel, for a few seconds, faintly stupid for not being a multimillionaire yet, because somehow dozens of people your age already are, or say they are.

Open your other social account, and there it is again, the ad for the 60-day calisthenics transformation program, and with it a small shame you’ve watched it three times now and still haven’t started. Scroll for another minute, and you’re no longer sure if what you just read was real or manufactured to look real, and there’s no obvious way to check.

Deadlines, comparison and information movement existed before. What’s new is the volume, the speed, and the fact that it all now arrives at once. Technology moved communication and access faster than anything before it. Organizations got better at generating priorities and initiatives than they ever got at resolving them. The result is a level of input that would have been unthinkable to someone doing your job 20 years ago.


Source link

The 3 Types of Overload That Hurt Performance Read More »