Opinions expressed by Entrepreneur contributors are their own.
Key Takeaways:
The one barrier locking 99% of people out of your industry — and how a solo founder turned it into an $80 million exit.
Why one company’s $40 million AI win got quietly reversed, and the single line you should never let AI cross.
The “describe it in plain English” move that built a $400 million company with no engineers.
You already know AI is minting a new kind of millionaire. The part that stings is that everyone tells you to “use more AI” — more tools, more prompts, more content — and you are still the one making every decision and wiring five apps together at 11 pm.
Here is the uncomfortable truth. The founders getting rich are not using more AI than you. They are using it in the one or two places that create the most financial leverage, and skipping the rest. In the video above, I break down four of them — how they did it and the exact move you can copy.
Take the no-code builder that lets a non-developer describe an app in plain English and ship it. The obvious lesson is “AI writes code now.” The real one is different: the winner found the exact barrier that locks 99% of people out of an industry — “I can’t code it” — and removed it. That barrier was the product.
That is the pattern underneath all four founders. As I put it in Chapter 6 of The Wolf Is at the Door, “we have constructed barriers around social and economic frameworks that both sustain and confine us,” and pattern recognition is what “allows us to spot the common threads within the problem — and the possibility.” The old gatekeepers — funding, hiring, infrastructure — are gone, and most operators still have not noticed.
And here’s where it gets uncomfortable.
The door is open for you specifically, not just for them. In the 2026 Intuit QuickBooks AI Impact Report, 43% of US businesses now credit AI with revenue gains, against just 2% that say it reduced revenue. The gap is no longer the top 1% — it is operators who put AI on their highest-value constraint versus those who sprinkle it on busywork.
The section in the video worth slowing down for is the reversal. Not because of what worked — but because of what didn’t. One company deployed an AI chatbot that did the work of 700 agents and drove a $40 million profit improvement, then walked it back and rehired humans. Everyone quotes the $40 million. Almost nobody asks which conversations AI should never have touched — and that answer separates founders who make money with AI from those who just spend on it.
Every founder, every reversal and every prompt is walked through in the video above — including the barrier-finder prompt that turns “the thing 99% of people can’t do in my industry” into a product roadmap in a single paste.
The free AI Success Kit, available to download for a limited time, comes with a free chapter from my new book, The Wolf is at The Door – How to Survive and Thrive in an AI-Driven World.
Key Takeaways:
The one barrier locking 99% of people out of your industry — and how a solo founder turned it into an $80 million exit.
Why one company’s $40 million AI win got quietly reversed, and the single line you should never let AI cross.
The “describe it in plain English” move that built a $400 million company with no engineers.
You already know AI is minting a new kind of millionaire. The part that stings is that everyone tells you to “use more AI” — more tools, more prompts, more content — and you are still the one making every decision and wiring five apps together at 11 pm.
Here is the uncomfortable truth. The founders getting rich are not using more AI than you. They are using it in the one or two places that create the most financial leverage, and skipping the rest. In the video above, I break down four of them — how they did it and the exact move you can copy.
Emil Barr built his first company, a social media agency called Step Up Social, from his college dorm room.
He made his first $1 million 14 months after launching the company.
Barr has since started another venture, Flashpass, which targets AI-driven job displacement.
It took Emil Barr just 14 months of work to see his first $1 million hit his bank account. He was 19 years old at the time.
Today, at age 23, the founder and CEO, who created two companies while still inschool, estimates that his personal net worth is around $35 million. He is unapologetically aiming to be a billionaire by age 30.
Born in Russia, Barr moved to the U.S. when he was three years old and grew up in a small Ohio town. He stuck out at an early age.
“I was the weird Russian kid that didn’t speak any English,” he tells Entrepreneur. “I think I always felt out of place. And I think that as an entrepreneur, you have to be comfortable with discomfort and that feeling of cutting against the herd.”
Emil Barr. Credit: Jerry Ta, Fluff Studio
In high school, he made his peace with being different and even leaned into it.
“I’m convinced every high school has at least one weird kid that wears suits to school every day,” he says. “You probably had one. That was me.”
Money, not ambition, first pushed him into entrepreneurship. When it came time to choose a college, Barr enrolled at Miami University, the only college that he could afford. He was looking into transferring to an Ivy League school, but tuition was out of reach.
“I was like, If money is the limiting factor, how hard can it be to make $100,000 [and] go pay for a year’s tuition?” he says.
How he made his first $1 million
Barr was on the lookout for money-making ideas when he met a classmate with 11 million TikTok followers who was barely earning anything from her social media presence.
“She got one brand deal for $200,” Barr says. “This is crazy because on Instagram, even if you had a million followers, that would be your full-time career. This was a platform that everyone was using. There was no revenue there yet.”
Barr started his company, Step Up Social, in his freshman year dorm room. His plan was straightforward: Businesses had no idea what to do with TikTok, but Gen Z did. Step Up Social positioned itself as a social media marketing and advertising agency focused on creating short-form video content.
Starting the company required little more than an iPhone and an Internet connection.
“We grew from $0 to $1 million in revenue in six months,” Barr says of Step Up Social. “As an 18-year-old, I had no idea what I was doing. I never had a corporate internship or anything like that.”
Instead of spending the money, he reinvested in the company’s growth.
“I think the first time I had truly a million dollars in my bank account was 14 months in,” Barr recalls. “It was the start of my sophomore year of college.”
Decisions that led to rapid growth
Growing Step Up Social meant embracing risk, especially debt. When the company adopted 90-day payment terms with large clients, there was a funding gap. Barr had to pay influencers upfront while waiting months for invoices to clear.
“I was basically running around and taking out as many credit cards and bank loans as I could to keep the company afloat,” he says. “I took out about $1 million worth of personally guaranteed unsecured loans, and everyone thought I was crazy.”
His logic was simple: At 19, he had no assets, so the downside was limited. “If we failed, what were they going to do?” he says. “Were they going to take my shirt or my car? I didn’t have anything to take.”
The third key decision, in his view, was prioritizing people over lifestyle. The “absolute best thing” he spent money on was hiring people with “20 or 30 years of experience,” he says.
How he grew Step Up Social
Early on, intent on gathering clients, Barr cold-emailed a few hundred companies. The first serious bite came from Kao, a Japanese consumer giant and Procter & Gamble competitor. Barr drove his old, beat-up car an hour and a half to downtown Cincinnati and walked into a 47th-floor boardroom wearing a university T-shirt and shorts. The executives gathered there asked him for his deck.
Despite underpricing himself at “$2,000 a month,” he landed the account. That one contract gave Step Up Social credibility and opened doors.
“It was exponentially easier for us to get our next 10 to 15 brands, and it was just off to the races,” Barr says.
From there, Step Up Social scaled into a full-service TikTok marketing agency, hiring influencers and managing online presences for brands and celebrities. By the time he sold it last year, the firm, by then acquired and rolled into a larger agency, was working with Procter & Gamble, Nike, Nordstrom, Kroger, Alo and Banana Republic.
“We were doing about $2 million a year in revenue, but it was extremely high margins,” Barr says.
Step Up Social earned revenue by connecting brands with creators. For example, a brand might pay the company $600 for a video. The company would then pay the creator $400 to make it and count the remaining $200 as revenue for arranging and managing the deal.
“Gross transaction revenue was closer to $8 to $9 million,” Barr says.
Convincing his university to pay him
Barr didn’t just build a business while attending college; he turned the school itself into a revenue source and marketing machine. He convinced his university to cover his tuition fees. The school also paid him $200,000 and gave him a faculty parking pass.
Miami University had introduced its entrepreneurship program relatively recently. Barr saw leverage. “I was effectively the only student entrepreneur on campus,” he says. If he dropped out, “they would have no student entrepreneurs. It wouldn’t be a very compelling case study.”
He started with “small asks” like flexible attendance, arguing that it was more important for him to run his company than to participate in group projects. Then, he applied for every grant and pitch competition he could find at the school, winning “$40,000 in a couple of months.”
From there, he reframed himself as both a case study and a vendor. Miami University became a client. Barr’s agency turned the school into “the most-followed public university on TikTok in America,” a result he argues paid back any support many times over.
“For every $1 they spent, whether it was in contracts with us or grants for the business, I’m sure they made at least $10 back in tuition from students who heard of Miami and were drawn to the school,” he says. “So it was probably a good deal for everyone.”
Building Flashpass
Barr’s latest venture, Flashpass, looks very different from a TikTok agency. At its core, Flashpass is his answer to a looming question: What happens to workers if AI replaces 25% to 50% of jobs?
“If we could actually build a way for these 25% to 50% of people who might lose their jobs to be able to quickly get certified online and go find a new job in 30 days, that would be a very valuable service to government as well as to individual users,” Barr explains.
Flashpass is an online platform built around “micro credentials.” Users can learn a new skill in 30 days or less and then be matched with jobs in industries that need talent.
“We have things like natural energy, like oil and gas careers. We have things like medical billing and coding,” he says. “These are all industries where they have a lot of job openings, and they can’t find enough people, and the average pay is over $80,000 a year.”
How Flashpass makes money
The platform doesn’t charge individual users or employers. Instead, Flashpass sells its services to state governments.
“Typically what we do is we’ll partner with a school, and the government will pay the school, and we will split the revenue with the school,” he says.
The school helps build curriculum and recruit candidates; the government treats Flashpass as one more education and workforce tool.
“If we could take this Flashpass idea and actually give it to the government and make it free for everyone who loses their jobs as a result of AI, we could build a very valuable business,” Barr says.
The bet appears to be paying off. Flashpass began with a $4 million, two-year pilot contract in Ohio, with roughly $2 million in annual revenue. Barr says he invested about $75,000 of his own money to build a demo, then used it to land that pilot. Since then, the company has added contracts in Louisiana (about $1 million a year) and Delaware ($2.3 million a year), and has proposals out in 17 states.
“This year, just based on the existing contract volume, we’re set to do at least $8 million, and that’s a four-fold increase over last year,” he says.
Work-life imbalance
Today, Barr estimates his net worth is around $35 million, up from $25 million when he spoke with Business Insider in December. He’s open about the personal cost of becoming a millionaire. In college, his schedule was packed to the minute. He took college classes from 8 a.m. to the early afternoon, then conducted back-to-back calls until 7 p.m. and went to networking dinners. He did his “true work” on the business until 4 a.m., finishing his day with three hours of sleep.
“I gained 80 pounds,” he says. “I lived off of Red Bull…four or five cans of Red Bull each day.” He skipped holidays and ignored invitations to go out.
He’s since lost 30 pounds and hired a trainer who comes to his house twice a day. The hardest part, he says, is realizing “it’s three times harder to undo the damage than to do the damage initially.”
He also has a personal chef, a home assistant and a driver. Barr still works 19-hour days, but he says he’s calmer and more measured as a leader with the extra help.
One lesson he wishes he’d learned earlier: Don’t spend your 18- to 20-hour days chasing small goals.
“It takes the same amount of effort to do something big as it does to do something small,” he says.
Opinions expressed by Entrepreneur contributors are their own.
Key Takeaways
Sustainable growth requires founders to turn their personal judgment into clear decision rights.
Technology can amplify a well-designed process, but automating unclear decisions only spreads confusion faster across a larger organization.
A service business owner usually knows how the work should be done: what a good client interaction sounds like, when an account needs attention, which problems require escalation and where margins can disappear.
That clarity makes the early stages feel manageable. The owner can catch problems, answer questions and keep clients satisfied. But as the business grows, the habits that once held everything together begin to strain.
Ten employees become 30, one market becomes three, and the owner can no longer know what’s happening everywhere. Decisions that once took a quick conversation now require others to have the context and authority to act.
I see versions of this throughout franchising. One of the most revealing questions I can ask an operator is not about revenue or customer acquisition. It’s this: “What happens here when you’re not available?”
The answer shows whether the company has translated the owner’s instincts into operating rhythms others can follow, or whether it still depends on informal knowledge passed along one interruption at a time.
If routine decisions stop without the owner, the company may have strong demand and talented people, but it does not yet have a business that can operate independently of the person who built it.
Growth exposes what the owner has been carrying
Small service businesses can run well on institutional knowledge because a few people carry the details that matter.
Someone knows which client needs a call before a schedule change, which employee can handle a difficult assignment, and which account needs an extra quality check.
Scale changes that. More clients, employees, and locations create a greater distance between the person who knows the answer and the person who needs it.
The systems gap appears when knowledge that once lived comfortably inside a few people’s heads needs to become repeatable across an organization.
Documentation is not the same as a system
Owners often respond by creating more procedures, as if a larger binder or longer checklist will automatically create consistency.
A functioning business system should help someone make the right choice, even when the usual decision-maker isn’t standing beside them.
But employees need more than tasks. They need the desired outcome, decision boundaries, and clear escalation points.
I’ve seen this distinction become especially important in commercial cleaning because the work happens across client locations, often outside traditional business hours. A manager cannot physically supervise every team at every facility.
In that environment, the system must operate independently. Ongoing education, quality controls, communication protocols, and accountability must create consistency even when management is miles away.
Technology cannot repair a broken process
Artificial intelligence and automation make this issue more urgent because service businesses now have more tools to speed up scheduling, communication, reporting, and performance management.
Those tools are valuable, but they can tempt leaders to automate before they’ve defined the process they want to improve.
A bad process does not become a good system because software executes it faster. If decisions are unclear, technology simply moves confusion more efficiently.
The sequence matters: clarify the desired outcome, identify inconsistent decisions, and understand why employees improvise. Then technology can reinforce a process that already works.
The CEO test is whether the business needs the CEO
That can be uncomfortable for founders because being needed often feels productive, especially in the early years.
Answering questions feels like leadership. Solving problems feels like service. Stepping in feels like proof the owner is still close to the business.
Over time, however, those strengths can become constraints when every answer still must pass through the same person.
As a CEO, I’ve learned my job is not to answer every operational question. It’s to build an organization that can reach the right answer without me.
Closing the systems gap
Service businesses often chase growth by adding more clients, employees, markets, and technology.
Sometimes the next stage requires something less visible: examining how decisions get made when the owner isn’t in the room.
Every recurring decision that requires the owner may reveal an opportunity to strengthen the system and make growth more durable.
The work often starts by naming the decisions that repeat each week, then deciding who should own them, what information they need, and when they should escalate. That simple discipline turns experience into guidance and gives managers confidence to act before small issues become larger problems.
Revenue and headcount show size. They don’t show whether the business can function without constant direction.
Sustainable growth requires founders to turn their personal judgment into clear decision rights.
Technology can amplify a well-designed process, but automating unclear decisions only spreads confusion faster across a larger organization.
A service business owner usually knows how the work should be done: what a good client interaction sounds like, when an account needs attention, which problems require escalation and where margins can disappear.
That clarity makes the early stages feel manageable. The owner can catch problems, answer questions and keep clients satisfied. But as the business grows, the habits that once held everything together begin to strain.
Ten employees become 30, one market becomes three, and the owner can no longer know what’s happening everywhere. Decisions that once took a quick conversation now require others to have the context and authority to act.
Kara Swisher spent three decades working for The Washington Post and The Wall Street Journal.
She realized that she could create something herself and launched the technology news site Recode in 2014.
Swisher said that she was more comfortable with uncertainty than many of the journalists around her when she chose to build her own business.
After spending about 30 years covering Silicon Valley for The Washington Post and The Wall Street Journal, Kara Swisher decided that she could build something bigger on her own.
“I thought I could do better,” Swisher told Business Insider’s Dan DeFrancesco during a recent talk with the outlet’s staff.
Swisher went on to launch Recode, the influential technology news site, in 2014. But before becoming a media entrepreneur, she had already built an established reporting career. For example, she helped produce and co-host a conference series for the Journal that became the predecessor to the Code Conference.
Swisher now co-hosts the Pivot podcast with NYU Stern professor Scott Galloway. She published Burn Book, a 320-page memoir about her encounters with founders and executives in the tech industry, in 2024. She has also amassed two million followers across social media channels.
Swisher told Business Insider staff that she was more comfortable with uncertainty than many of the journalists around her when she chose to build her own business. “I was like, what’s the worst thing? I have to come back? I’m a good reporter. That’s always saleable,” she said.
Her advice to workers looking to branch out and start their own business is to take an honest look at the downsides before leaving. Deciding to quit can hinge on factors like financial responsibilities and children to support.
The key to going independent
Swisher said that quitting a job and going independent is not simply a matter of leaving a newsroom or launching a newsletter. It instead requires a point of view strong enough to give an audience a reason to seek out your work rather than another version of what is already available.
Swisher said she has encouraged media professionals to consider building their own companies when they have a distinctive voice and a real desire to create content.
“You can tell when people really have something to say and want to make something,” she said.
The most promising founders — in media and other industries — can identify an unmet audience need and deliver work that feels hard to replace.
That customer focus shaped Swisher’s own move into entrepreneurship. When she left traditional media to build her own company, she concentrated on what audiences already wanted. Her core entrepreneurial principle was to start with the user.
Starting a business isn’t right for everyone
Swisher said that she sometimes tells people to remain in stable jobs rather than force an entrepreneurial path. Building a business requires comfort with uncertainty, she added.
Swisher said most people can strengthen their entrepreneurial instinct over time. However, she noted that the impulse to take risks was a core part of her personality.
“I’m sort of restless as a person in general. I always joke, I’m a bad employee. I hate being an employee,” Swisher said. “I’m like, ‘You’re an idiot.’ And I say it, and then it gets me into trouble.”
Key Takeaways
Kara Swisher spent three decades working for The Washington Post and The Wall Street Journal.
She realized that she could create something herself and launched the technology news site Recode in 2014.
Swisher said that she was more comfortable with uncertainty than many of the journalists around her when she chose to build her own business.
After spending about 30 years covering Silicon Valley for The Washington Post and The Wall Street Journal, Kara Swisher decided that she could build something bigger on her own.
“I thought I could do better,” Swisher told Business Insider’s Dan DeFrancesco during a recent talk with the outlet’s staff.
Swisher went on to launch Recode, the influential technology news site, in 2014. But before becoming a media entrepreneur, she had already built an established reporting career. For example, she helped produce and co-host a conference series for the Journal that became the predecessor to the Code Conference.
Ian Rogers has spent his career at the intersection of tech and culture.
He previously led Apple Music and is now driving security and AI strategy at $1.5 billion security startup Ledger.
Ledger protects digital private property, like Bitcoin and other cryptocurrencies, using secure hardware chips similar to those in credit cards.
He helped build the soundtrack of the internet age, turned a scrappy MP3 player into a Yahoo acquisition, sold Beats to Apple and helped launch Apple Music.
Now, Ian Rogers is betting that the next great consumer platform is not music, but security for your money and identity. He’s building the future from rural Italy as chief human agency officer at the $1.5 billion security startup Ledger.
From Indiana to Apple Music
Rogers grew up in Indiana and discovered computer science in the early 1990s, right as the web took off. “It was a great time to study computer science because when I started, it was sort of like rocket science to people, and then by the end, people were trying AOL,” he tells Entrepreneur. “I was there at the very beginning of the web and made some of the first websites.”
That curiosity quickly collided with music. He dropped out of grad school to go on tour with a band, which took him to California. There, he helped build a popular MP3 player that he sold to AOL in 1999, then another music application that Yahoo acquired. Rogers went on to run Yahoo Music from 2003 to 2008.
He then built Beats Music and sold it to Apple in 2014. He joined Apple as senior director of Apple Music, overseeing the launch of the music streaming service in 2015.
Rogers still feels a personal connection to that product. When he met his now-wife, she questioned his loyalty to Apple Music over Spotify. His answer about why he chose Apple Music was simple: “Because I built it.”
Rogers’ time at Apple continues to shape how he thinks about products.
From Apple, Rogers brought a simple, powerful lesson: People buy an ecosystem. “When you buy an iPhone, you’re not buying a piece of hardware,” he says. “You’re buying blue bubbles instead of green bubbles; you’re buying AirDrop; you’re buying FaceTime. That’s part of the experience of being an Apple user versus being an Android user.”
Apple’s genius was creating an integrated experience that “just works,” from the iPod in the early 2000s through to the modern iPhone, Rogers explains.
After Apple, Rogers moved to Paris to serve as the chief digital officer of LVMH, helping take a traditionally offline luxury group from 3% ecommerce in 2015 to 100% online during the pandemic.
Ian Rogers. Credit: Ledger.
Why Ledger exists
Nicolas Bacca, Eric Larcheveque and Joel Pobeda founded Ledger in 2014, and Rogers came on board in 2021 as its chief experience officer. Ledger was last valued at $1.5 billion in 2021.
The Paris-based company was founded on a simple premise: The same secure chip technology used in credit cards and passports could be used to protect digital assets. To that end, the startup makes physical hardware crypto wallets that store the digital passwords, known as private keys, needed to access and move cryptocurrency. The devices keep these sensitive keys completely offline, so hackers cannot access them.
Today, Rogers’ title is chief human agency officer; he pushed for the change as Ledger doubled down on AI security. “AI security is a top three problem for humanity at the moment,” he says. “What I realized is that that’s not about AI; it’s actually about humans. The job here is keeping humans secure and in control.”
“We will all become the managers of AI agents,” he says. “The same way that we’re all kind of information peddlers today, we’re having an intelligence revolution that is actually computers taking actions on our behalf.”
In his view, humans will be “end to end” by starting processes and validating results, while agents handle the “middle to middle” work. “Therefore, the same way that we all have computers on our desks today, we will all be having agents on our desks tomorrow,” Rogers says. “And so, if I were 25 years old, I would be building skills at managing agents. Period.”
How do you actually do that? Rogers’ advice is to get your hands dirty with the tools, just as he did with web technologies in the 90s and 2000s.
For founders, his hard-won lesson is about market selection and pain points.
“I think the main thing I’ve gotten wrong in my career is sizing the market relative to my own personal interest,” he admits. “There’s a joke that every college student has a business idea that’s about either music or bars, because that’s what they know.”
What impresses him now are founders who dig deep into pressing, unsexy problems, like logistics and insurance, and uncover real pain. “You find the pain, and then you make a painkiller. You don’t make a painkiller and then go looking for pain,” he says.
Key Takeaways
Ian Rogers has spent his career at the intersection of tech and culture.
He previously led Apple Music and is now driving security and AI strategy at $1.5 billion security startup Ledger.
Ledger protects digital private property, like Bitcoin and other cryptocurrencies, using secure hardware chips similar to those in credit cards.
He helped build the soundtrack of the internet age, turned a scrappy MP3 player into a Yahoo acquisition, sold Beats to Apple and helped launch Apple Music.
Now, Ian Rogers is betting that the next great consumer platform is not music, but security for your money and identity. He’s building the future from rural Italy as chief human agency officer at the $1.5 billion security startup Ledger.
From Indiana to Apple Music
Rogers grew up in Indiana and discovered computer science in the early 1990s, right as the web took off. “It was a great time to study computer science because when I started, it was sort of like rocket science to people, and then by the end, people were trying AOL,” he tells Entrepreneur. “I was there at the very beginning of the web and made some of the first websites.”
Opinions expressed by Entrepreneur contributors are their own.
Key Takeaways
A side hustle demands your time, but a managed digital asset demands your capital and then gets out of your way.
A managed digital asset is not one big win — it’s the same disciplined process repeated order after order, month after month, until the compounding becomes obvious on paper.
Four years ago, one of our clients in her early 30s came to us with $30,000 and a simple ask. She wanted her money working for her without turning into a second career. No inventory to manage, no customer service tickets to answer at midnight and no learning curve on Amazon’s backend. Just a real asset that produced real income, month after month, while she kept living her life.
At Elite Automation, we don’t sell “ecommerce businesses,” and we don’t do dropshipping in the way most people picture it. What we build is a fully managed, cash-flowing storefront on Amazon’s infrastructure. Our team handles sourcing, fulfillment, pricing and day-to-day account management. The client owns the account, owns the revenue stream and owns the asset. We operate it so she doesn’t have to.
That difference really does matter. It’s the difference between owning a job and owning an asset. A side hustle demands your time, but a managed digital asset demands your capital and then gets out of your way.
What the numbers actually look like
Her store isn’t a fluke or a one-month spike. Pulling from her own profit tracker, here’s what a recent month looked like in April:
Total sold price: $165,291.14
Units sold: 3,084
Net profit: $25,344.03
ROI: 22.10%
And that wasn’t an outlier. The two months before it told a similar story, with revenue consistently landing in six figures and net profit tracking in the five-figure range each month, ROI holding steady in the high teens to low 20s. This is what four years of consistent operation looks like when the fundamentals are sound and the store is being actively managed by people who do this full time.
That’s the part people underestimate. It’s not one big win — it’s the same disciplined process repeated order after order, month after month, until the compounding becomes obvious on paper.
Why this matters for diversification
Most high-income professionals we work with already have money in real estate, in the stock market and in their own primary business. Those are good things to own. But they’re also correlated in ways people don’t always think about, and none of them are exactly hands off.
A managed Amazon storefront is a different kind of asset. It doesn’t move with the stock market. It doesn’t require you to be a landlord. It doesn’t compete for your time the way your own business does. For our client, it became a genuine fourth pillar, something generating steady monthly cash flow in a lane completely separate from everything else in her portfolio.
That’s the real value of a managed asset. Not that it replaces what you already have, but that it fills a gap none of your other investments can.
Why this should feel encouraging, not out of reach
She didn’t start with a huge war chest. She started with $30,000 and a decision to deploy that capital into something built and operated by people who do this every single day. She never had to become an Amazon expert. She never had to learn fulfillment logistics or supplier negotiations. She just had to trust the process and let it compound.
Four years in, that decision is still paying off, literally, every month.
If you’ve got capital sitting idle and you’re tired of the idea that growing it has to cost you your time, this is what the alternative looks like. Not a side hustle and certainly not another full-time job, but rather a managed digital asset quietly doing its job in the background of a full life.
Diversification isn’t really about chasing more; it’s about not having all of your outcomes tied to the same set of variables. Most people’s version of “diversified” is still just different flavors of the same risk: a primary business that depends on their own time and energy, a stock portfolio that moves with the broader market, maybe a rental property that comes with its own version of a second job.
None of that is wrong, but none of it is actually independent either. True diversification means having at least one asset in your life that doesn’t rise and fall with the same forces as everything else you own, something that isn’t waiting on you to log in, make a call, or put in hours to keep producing. That’s the piece most portfolios are missing: not another version of what they already have, but something genuinely uncorrelated to it.
Key Takeaways
A side hustle demands your time, but a managed digital asset demands your capital and then gets out of your way.
A managed digital asset is not one big win — it’s the same disciplined process repeated order after order, month after month, until the compounding becomes obvious on paper.
Four years ago, one of our clients in her early 30s came to us with $30,000 and a simple ask. She wanted her money working for her without turning into a second career. No inventory to manage, no customer service tickets to answer at midnight and no learning curve on Amazon’s backend. Just a real asset that produced real income, month after month, while she kept living her life.
At Elite Automation, we don’t sell “ecommerce businesses,” and we don’t do dropshipping in the way most people picture it. What we build is a fully managed, cash-flowing storefront on Amazon’s infrastructure. Our team handles sourcing, fulfillment, pricing and day-to-day account management. The client owns the account, owns the revenue stream and owns the asset. We operate it so she doesn’t have to.
Opinions expressed by Entrepreneur contributors are their own.
Key Takeaways
Build your website to get leads and business — not for design awards: Prioritize usability over design, clear instructions over clever messaging and key information over fluffy content.
Bring web visitors back with digital retargeting: By placing a small piece of tracking code on your website, you can target anonymous visitors with digital ads after they leave.
Link up your website to the mailbox: That’s where direct mail retargeting comes in. Instead of serving another online ad to past website visitors, it automatically sends a pre-designed postcard to their mailbox immediately.
I’ve been helping small businesses with their marketing for nearly three decades, and I’ve seen some beautiful websites. But I’ve also encountered a big problem, which is when they don’t convert visitors into prospects and ultimately customers.
There’s nothing wrong with wanting a beautiful website. In fact, a great website should look professional and build confidence. But somewhere along the way, too many businesses mistake looking good for doing its job.
A website isn’t a window dressing. It’s a marketing tool. Every page should help a visitor take the next step in their journey — whether that’s calling your office, requesting a quote, scheduling an appointment, making a purchase or simply learning enough to trust you.
If you want your website to generate more customers, here are three places to start.
1. Build your website to get leads and business — not for design awards
A person forms an impression about your website in just 50 milliseconds! Of course we want the website to be aesthetically pleasing, but what’s even more important is the customer’s journey.
When someone lands on your homepage, they should immediately understand:
What you sell
How your product or service benefits them
What they should do next
Some of the biggest conversion killers prioritize design over usability, clever messaging instead of clear instructions and fluffy content instead of key information. Ideally, every element on your website works towards communicating one of these three purposes.
Trust and affinity builders:
When people land in an unfamiliar place like your website, there’s a slight barrier of distrust that comes up — and it’s your job to overcome that so they feel safe browsing your website and will stick around.
One way to build trust is through familiarity. Here are a few tactics:
Place website navigation tools in expected places (don’t you hate when you want to go somewhere on a site and you can’t find the button or link?).
Include trust signals like professional credentials and certifications, Google reviews, success stories and real photos of your staff, products/services and operations (not stock photos).
Build on the trust by positioning yourself or your company as the expert in the space. You can do this by educating prospects on all aspects of your product or service so they consider you and your brand helpful.
Include strong calls to action that tell people exactly what to do next. On your website, this can be filling out a form, calling a phone number, sending an email or downloading a report. Make sure you keep it direct and clear so it’s as easy as possible for people to turn their interest into action. The call to action should give you minimally their email address so that you can follow up!
Your website exists to remove barriers to the sale, not add more. Take every opportunity to avoid a misstep in the customer journey. Provide as much useful information and calls to action as possible to make your purpose and direction clear.
2. Bring web visitors back with digital retargeting
If a person visits your website and leaves immediately without interacting with other pages or taking an action, this is called a “bounce” — and unfortunately it’s very common. The average bounce rate is 44% across all industries.
A bounce doesn’t mean they’re gone forever, though. In fact, returning visitors make up 50% of website traffic, and there are tools at your disposal to bring people back faster.
By placing a small piece of tracking code on your website, you can target anonymous visitors with digital ads after they leave. Depending on the network you choose, your digital ads will appear through Google’s Display Network, Meta or other online advertising channels while those prospects browse the internet.
This is called digital retargeting, and you’ve likely already seen ads like this following you around. Instead of disappearing after one website visit, your business stays visible.
We can never be sure what made someone leave in the first place. What we do know is that retargeting ads will help bring them back — about 76% of consumers are more likely to convert after being retargeted by digital ads.
3. Link up your website to the mailbox
Online ads are great at generating spur-of-the-moment clicks. But what happens when someone visits your website, looks around and leaves without taking action?
That’s where direct mail retargeting comes in. Direct mail retargeting works much like digital retargeting. Instead of serving another online ad to past website visitors, it automatically sends a pre-designed postcard to their mailbox immediately, usually within 24 hours.
The process is surprisingly simple. A small tracking pixel is added to your website, much like the ones used for Google or Facebook advertising. When an anonymous visitor leaves without converting, the system matches available mailing addresses and automatically triggers a postcard to be printed and mailed.
Instead of competing with dozens of browser tabs, social media posts, emails and digital ads, your message arrives somewhere far less crowded: the mailbox. Recent research found that 84% of consumers read direct mail the same day they receive it.
If you run an ecommerce business, you can take the same approach with abandoned shopping carts. When someone adds products to their cart but leaves before checking out, an automated postcard can remind them what they left behind and encourage them to complete the purchase.
Getting started is easier than many business owners realize. Several direct mail providers now offer website retargeting platforms that integrate with your website, allowing postcards to be triggered automatically based on visitor behavior — just like your digital retargeting campaigns.
So do you want compliments or dollar signs? Focus on a website that converts and builds customer loyalty, and your business will grow more than a flashy reputation.
Key Takeaways
Build your website to get leads and business — not for design awards: Prioritize usability over design, clear instructions over clever messaging and key information over fluffy content.
Bring web visitors back with digital retargeting: By placing a small piece of tracking code on your website, you can target anonymous visitors with digital ads after they leave.
Link up your website to the mailbox: That’s where direct mail retargeting comes in. Instead of serving another online ad to past website visitors, it automatically sends a pre-designed postcard to their mailbox immediately.
I’ve been helping small businesses with their marketing for nearly three decades, and I’ve seen some beautiful websites. But I’ve also encountered a big problem, which is when they don’t convert visitors into prospects and ultimately customers.
There’s nothing wrong with wanting a beautiful website. In fact, a great website should look professional and build confidence. But somewhere along the way, too many businesses mistake looking good for doing its job.
A website isn’t a window dressing. It’s a marketing tool. Every page should help a visitor take the next step in their journey — whether that’s calling your office, requesting a quote, scheduling an appointment, making a purchase or simply learning enough to trust you.
Opinions expressed by Entrepreneur contributors are their own.
Key Takeaways
Community colleges are moving past their pandemic-era enrollment losses as students seek affordable education with a clearer, faster route to a job.
Career outcomes are driving the comeback: 74% of recent community-college students say gaining skills for workplace success matters to their enrollment decision.
For years, community colleges were seen as the overlooked corner of American higher education. They lost millions of students during the pandemic, faced questions about declining enrollment, and often sat in the shadow of four-year universities. They were hit harder by the pandemic, with fall 2020 enrollment dropping 10% compared to the prior year, the steepest decline on record for public two-year institutions, according to the NCES data.
But that narrative is changing. Community colleges are now leading one of the strongest enrollment recoveries in U.S. higher education, driven by a shift in what students value most: affordability, faster pathways to employment, and education that delivers measurable career outcomes.
From pandemic decline to enrollment revival
A 2023 Community College Research Center (CCRC) study at Columbia University found that between fall 2019 and fall 2021, community colleges enrolled 586,000 fewer students aged 18 to 24, compared with a decline of 277,000 students aged 25 and older. More importantly, those students did not simply shift to four-year universities. Enrollment among 18- to 24-year-olds at four-year institutions also declined by roughly 200,000 students during the same period.
The numbers back up that shift. According to the National Student Clearinghouse Research Center’s Spring 2026 Enrollment Trends report, community colleges enrolled 5.8 million students in spring 2026, representing a 5.2% increase compared with spring 2021. The momentum has been building across academic terms.
In fall 2025, community college enrollment grew 3.0% year over year, outperforming several other higher education sectors and reinforcing that the recovery is becoming a sustained trend rather than a temporary rebound.
The comeback isn’t happening because students have suddenly abandoned four-year degrees. Instead, economic realities are reshaping enrollment decisions. Rising tuition costs, employer demand for job-ready skills, the growing popularity of short-term certificates and the return of adult learners are making community colleges an increasingly practical choice. Many institutions have also expanded workforce partnerships, improved transfer pathways and modernized student support, making it easier for learners to move from the classroom into high-demand careers.
Together, these forces are turning community colleges into something more than an affordable alternative. They are becoming a critical part of America’s workforce pipeline and a window into how higher education is evolving.
Students are increasingly choosing career-focused programs
One reason community colleges are having a moment is pretty straightforward: students want to know where their education can take them. Instead of spending four years on a degree with an uncertain payoff, many are looking for programs that help them build practical skills, earn a credential and move into a career faster. Community colleges are well-positioned for this, with certificates, associate degrees, technical programs and other shorter pathways designed around workforce needs.
A Strada Education Foundation study shows just how much career goals matter to community college students. Among recently surveyed community college students, 74% said gaining skills to be successful at work was an important reason for enrolling. Another 69% said advancing their careers and making more money were important motivations. In other words, students aren’t just asking, “What can I study?” They’re increasingly asking, “What will this help me do?”
The enrollment numbers tell a similar story. According to the National Student Clearinghouse Research Center, community college enrollment grew 5.4%, or 288,000 students, in spring 2025. Vocational-focused public two-year colleges saw particularly strong growth, with enrollment nearly 20% higher than it was in spring 2020. That suggests the community college comeback isn’t simply about students returning to college. It’s also about students gravitating toward education with a clearer connection to the workplace.
Affordability matters
There’s another reason community colleges are becoming more attractive: they make the financial equation easier for many students to manage. According to the Strada 2025 study, 77% of respondents found college to be unaffordable.
Affordability is also about more than sticker price. Community colleges offer students access to a range of financial support, from scholarships and grants to emergency aid. Research from New America found that nearly 80% of new and continuing community college students said their institution offered financial aid, while more than half reported actually receiving it.
A 2024 Lumina Foundation–Gallup survey of current, former and prospective college students found that 53% considered financial aid or scholarships very important to their decision to enroll or remain enrolled. The same share said confidence in the value of their degree or credential was very important. And for half of the students, the prospect of increasing their personal income was also a very important factor.
That cost-conscious mindset gives community colleges an obvious advantage. They have traditionally offered a lower-cost route into higher education, while also giving students the option to earn a credential, enter the workforce or transfer to a four-year institution. For students trying to make every education dollar count, that combination is hard to ignore.
Short-term credentials are becoming more attractive
Not every student wants to spend four years earning a degree before stepping into the workforce. More students are looking for a faster way to build practical skills, earn a recognized credential and start creating career momentum. That shift is making certificates, micro-credentials and other short-term programs increasingly appealing.
The interest is already there. Tyton Partners’ Listening to Learners 2025 found that nearly 90% of students expressed at least some interest in non-degree credentials, including certificates, micro-credentials, industry certifications and digital badges. Among community college students, 40% said they were very interested, while another 48% said they were somewhat interested.
The research backs up the trend. The Economics of Education Review 2025 study found that short-term certificates are the fastest-growing type of postsecondary credential in the United States. The study also found that certificates requiring less than a year to complete have grown by about 60% over the past two decades, highlighting the growing appeal of shorter pathways that can lead to employment more quickly.
Key Takeaways
Community colleges are moving past their pandemic-era enrollment losses as students seek affordable education with a clearer, faster route to a job.
Career outcomes are driving the comeback: 74% of recent community-college students say gaining skills for workplace success matters to their enrollment decision.
For years, community colleges were seen as the overlooked corner of American higher education. They lost millions of students during the pandemic, faced questions about declining enrollment, and often sat in the shadow of four-year universities. They were hit harder by the pandemic, with fall 2020 enrollment dropping 10% compared to the prior year, the steepest decline on record for public two-year institutions, according to the NCES data.
But that narrative is changing. Community colleges are now leading one of the strongest enrollment recoveries in U.S. higher education, driven by a shift in what students value most: affordability, faster pathways to employment, and education that delivers measurable career outcomes.
From pandemic decline to enrollment revival
A 2023 Community College Research Center (CCRC) study at Columbia University found that between fall 2019 and fall 2021, community colleges enrolled 586,000 fewer students aged 18 to 24, compared with a decline of 277,000 students aged 25 and older. More importantly, those students did not simply shift to four-year universities. Enrollment among 18- to 24-year-olds at four-year institutions also declined by roughly 200,000 students during the same period.
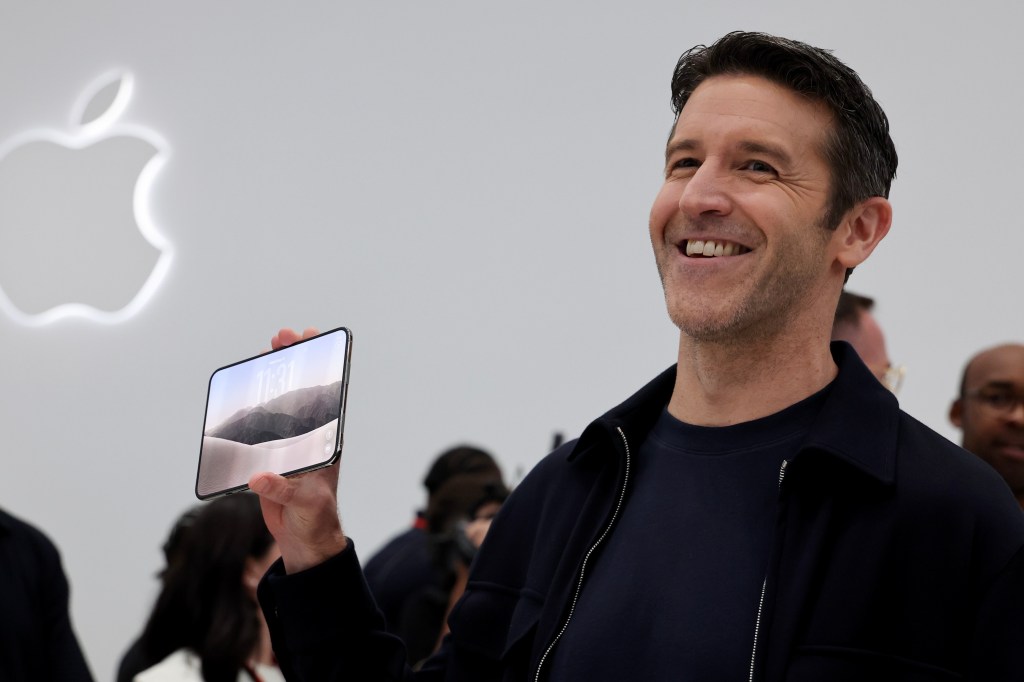
The event, Apple’s biggest launch of the year, also signaled a shift in leadership. The company’s new CEO, former head of hardware engineering John Ternus, took over on September 1 and delivered the opening remarks at the event. He initially focused on AI and the standard it needs to meet to improve lives, from all-day battery life to an enhanced visual experience.
“Today we’re going to take these abilities even further with the next generation of iPhone,” Ternus said at the event.
Here’s what Apple announced.
iPhone Duo foldable phone
“Others have created foldables that feel like two screens stuck together,” Ternus said. “We started with the experience that we would want for ourselves.”
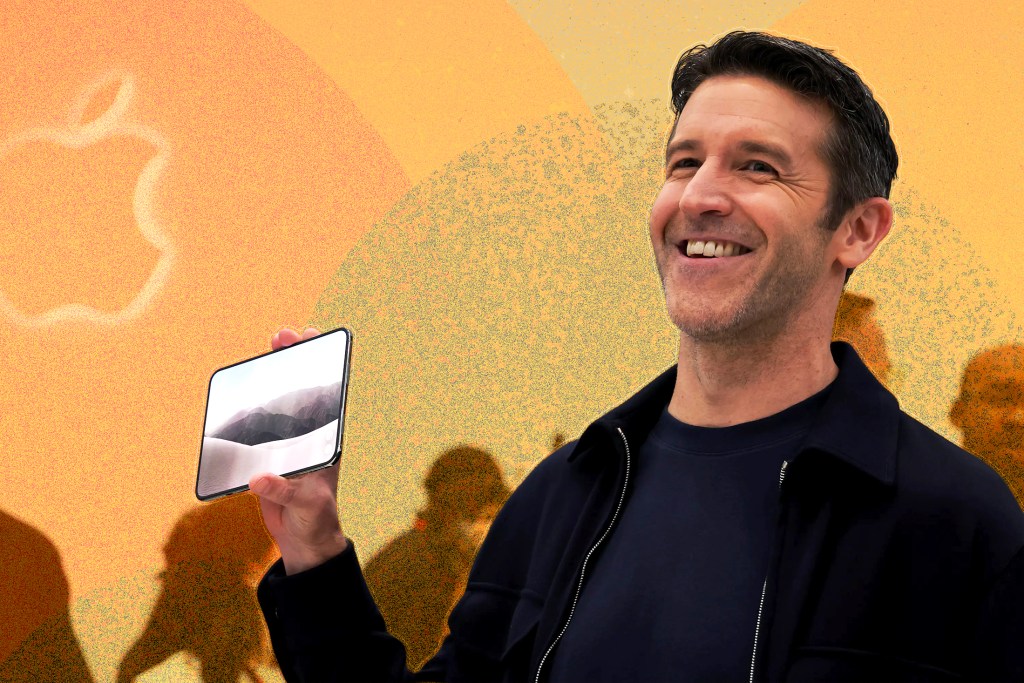
Apple CEO John Ternus holds the iPhone Duo. Photo by Benjamin Fanjoy/Getty Images
The iPhone Duo features a 5.4-inch front screen that transforms into a 7.6-inch screen when opened. You can angle the phone however you want, and the screen will adjust, opening up new possibilities for photos and videos.
iPhone Duo brings an entirely new design to a familiar iPhone display. Its purpose is to give users a larger screen and a phone that can still fit in their pocket. It is also the first iPhone that is compatible with Apple Pencil, so users can annotate documents and highlight text.
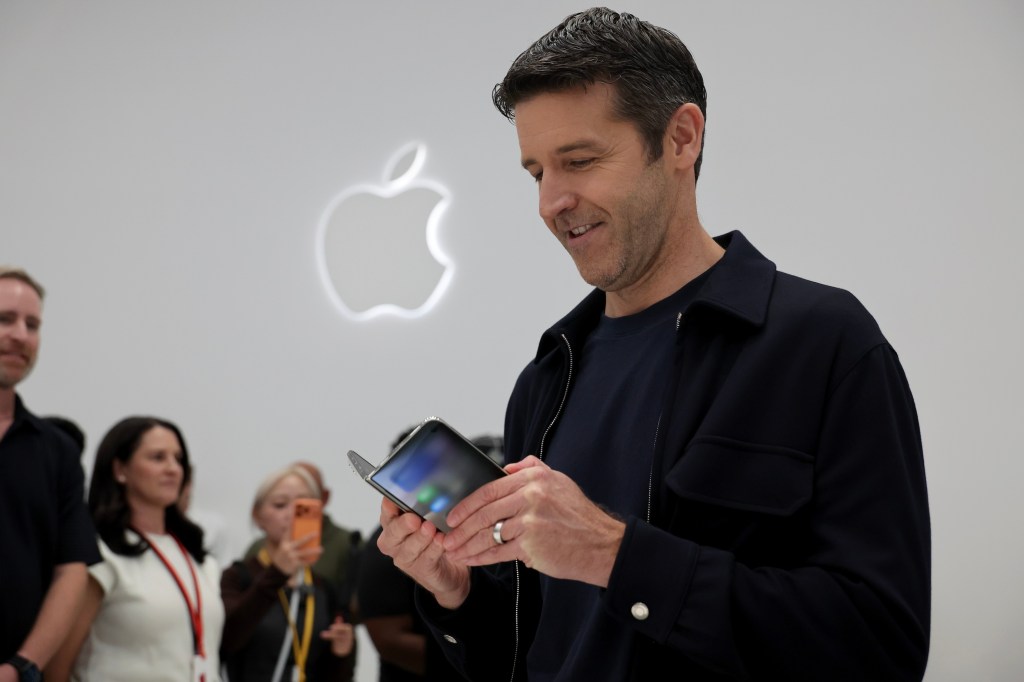
Ternus holds the iPhone Duo. Photo by Benjamin Fanjoy/Getty Images
The new iPhone is made of titanium and is dust- and water-resistant.
“iPhone Duo is the most transformational change to iPhone since the original,” Ternus said.
For customers who are worried about the crease and how it will hold up over time, Apple’s chief hardware officer, Johny Srouji, explained that Apple precisely aligned each individual hinge for durability.
The iPhone Duo starts at $1,999 with 256 GB of storage and is available in white and night sky (dark blue). Preorders start on October 16, and phones will ship starting on October 23.
iPhone 18 Pro and Pro Max
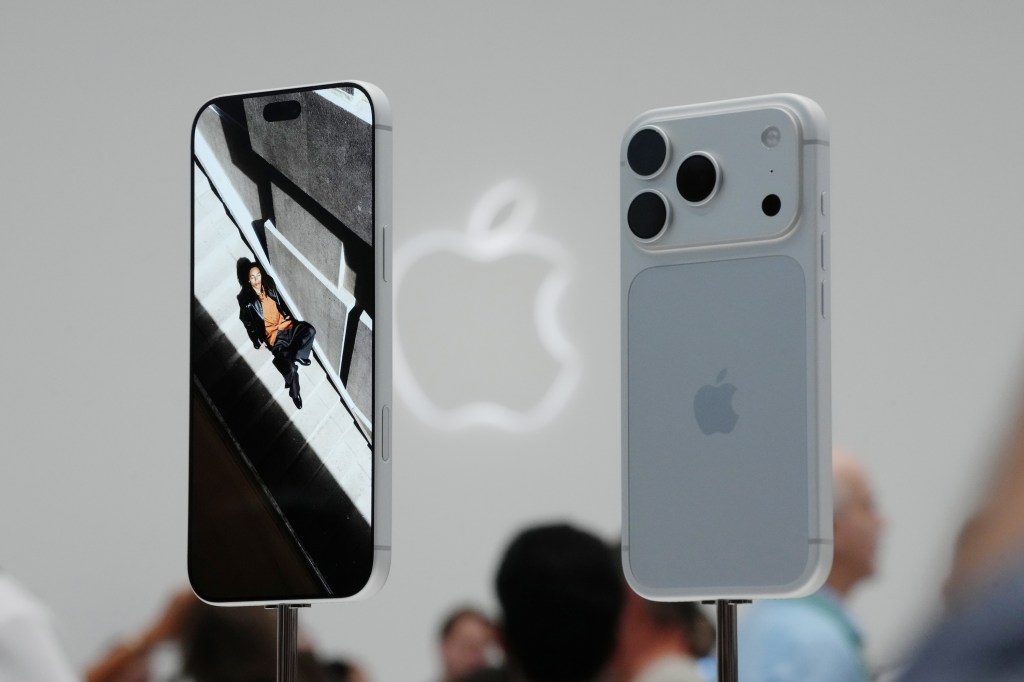
For those not yet ready to hold a foldable phone, Apple offers its latest Pro and Pro Max models. “We made massive advancements in the most important areas,” Ternus said of the iPhone 18 Pro, highlighting longer battery life and an improved camera.
The phone contains a new A20 Pro chip, which powers “massive advancements in the most important areas.” For example, the iPhone 18 Pro takes a “massive leap” in battery life. Due to the new chip’s efficiency, users get 36 hours of battery life on the iPhone 18 Pro and “longest battery life by far” on the 18 Pro Max with 45 hours.
The iPhone 18 Pro and Pro Max come in new colors, including glacier (light blue) and burgundy (dark cherry). The phones also contain “the most advanced camera” Apple has ever made, according to the presentation.
Apple iPhone 18 Pro Max, (left) and Pro (right) smartphones in the new glacier color during a product unveiling event at Apple Park in Cupertino. Photographer: David Paul Morris/Bloomberg
The iPhone 18 Pro costs $1,199 for 256 GB, while the iPhone 18 Pro Max starts at $1,299. The main differences between the phones are screen dimensions and battery life. The iPhone 18 Pro has a 6.3-inch screen, while the larger iPhone 18 Pro Max has a 6.9-inch screen.
Preorders open September 12, and shipping starts September 18.
A new Siri
Siri was also due for an upgrade. The voice assistant now considers personal context and can search apps like Mail and Messages to find answers to queries. It works across 3,000 apps and is built into the Camera app on iPhone, so users can ask questions and take action more quickly. It also has a broader range of expressive voices, allowing users to personalize how human and emotive they want the voice to be.
Users can also write and edit with Siri virtually anywhere they can type. For example, they can write an email to their child’s soccer coach while on the go.
Siri is available in beta in English, with support for other languages coming next month.
AirPods 5
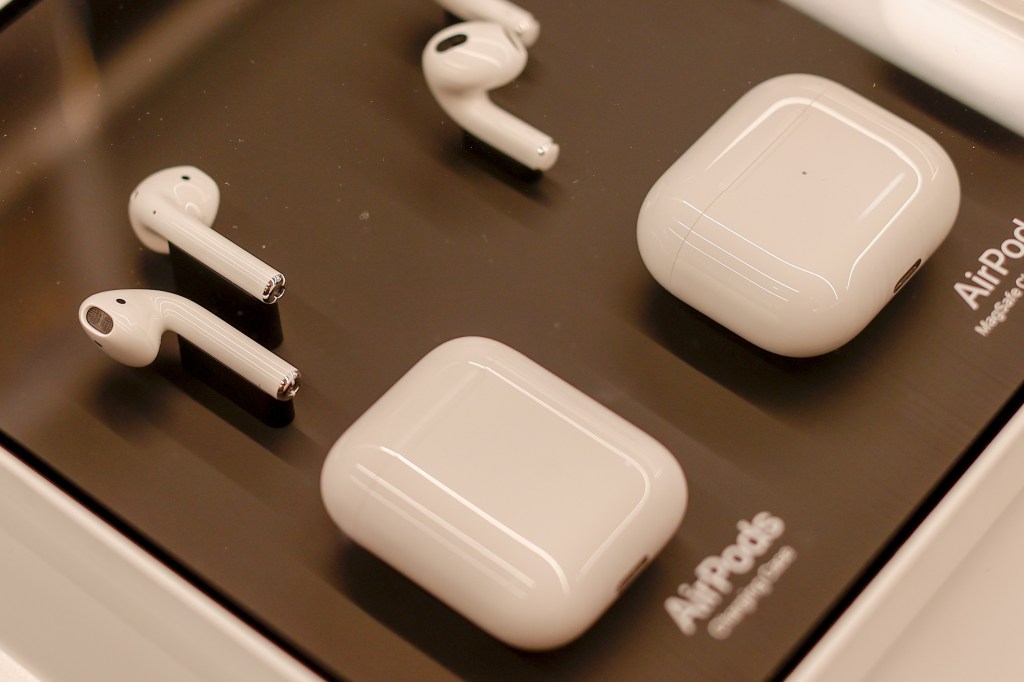
Apple upgraded its popular AirPods with better noise-blocking features. The less expensive $129 model now has active noise cancellation, and the higher-end model that comes with a wireless charging case is $149.
“We’re thrilled that with AirPods 5, we’re able to bring Active Noise Cancellation — one of our most beloved features — to our most affordable AirPods,” Dave Pakula, Apple’s vice president of Hardware Engineering, said in a press release.
AirPods on display. Photo by Sefa Karacan/Anadolu Agency via Getty Images
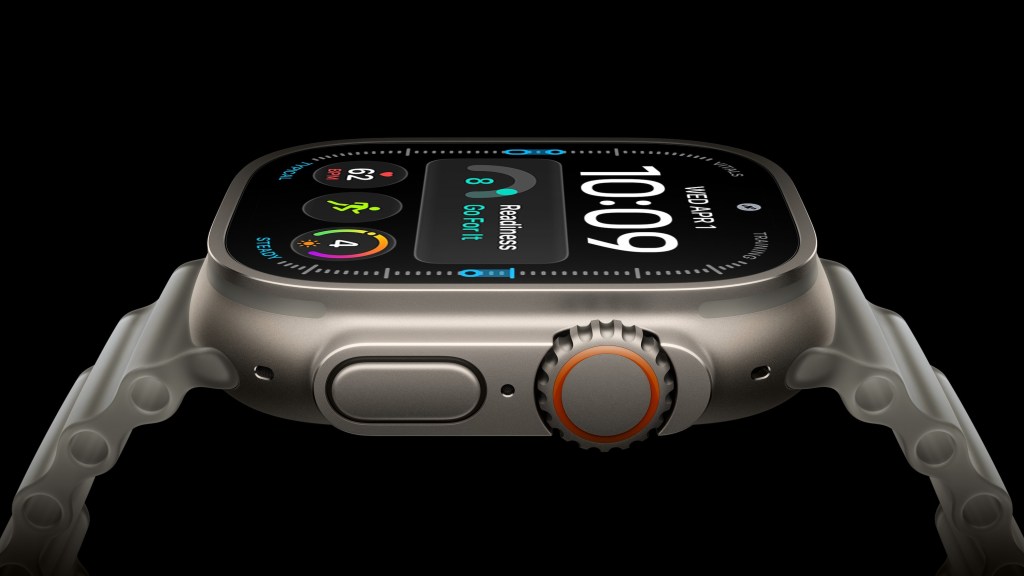
Apple Watch Series 12 and Ultra Watch 4
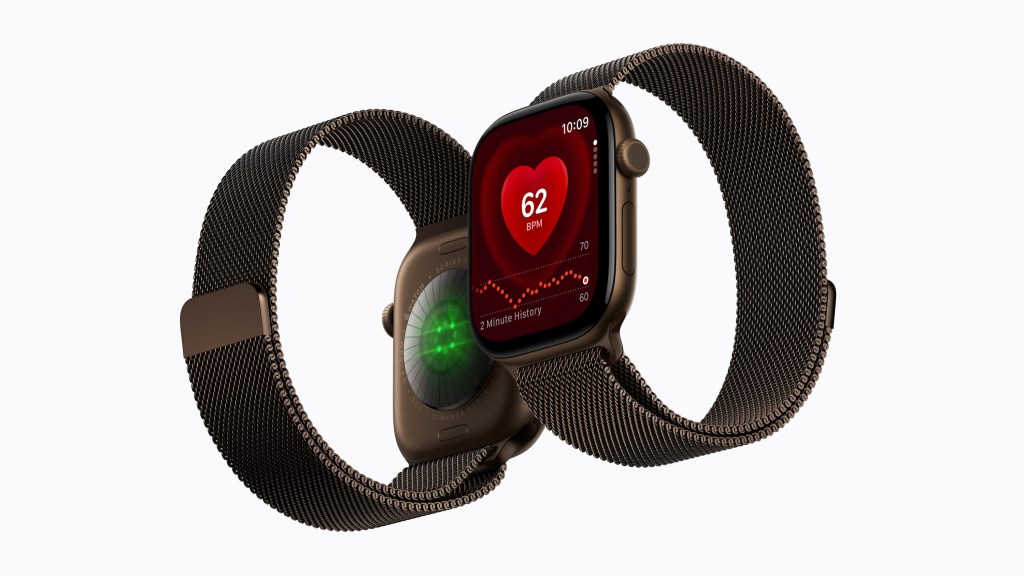
Apple also introduced the newest generation of Apple Watch, the Series 12, and revealed a new Health Sensing System. The company redesigned sensors to provide higher-frequency heart rate data. For example, the new watches measure heart rate data every five seconds, a 60-time frequency increase over previous models.
Apple tested the Apple Watch against other leading wearables in a clinical study, and “Apple Watch has the most accurate heart rate sensing in a variable,” according to the presentation.
Apple Watch Series 12. Credit: Apple
The company is also introducing a new Readiness score, which combines data points from heart rate data to provide a snapshot of health.
It also debuted a new feature called Audio Intelligence, which makes sense of what you hear. It uses Apple Intelligence to register sounds like alarms, sirens and doorbells. It also includes Siri Recap, which generates notes and transcripts from audio. Live Rewind is another new feature within Audio Intelligence. It allows users to go back 15 seconds to transcribe what someone just said.
Apple Watch Ultra 4. Credit: Apple
The Apple Watch Series 12 and Ultra 4, priced at $399 and $799 respectively, are available for preorder now. They both launch on September 18. The main differences between these two options are battery life and case materials. The Ultra 4 is built for more extreme conditions, with a titanium case and up to 50 hours of battery life, while the Series 12 comes in aluminum and ceramic with a standard all-day battery life.
Key Takeaways
On Wednesday, Apple introduced its first foldable phone, the iPhone Duo, which is priced at $1,999.
The company’s new CEO, former head of hardware engineering John Ternus, took over earlier this month and led the event.
Apple also announced the new iPhone 18 Pro and Pro Max, revamped AirPods and upgraded Apple Watches.
The event, Apple’s biggest launch of the year, also signaled a shift in leadership. The company’s new CEO, former head of hardware engineering John Ternus, took over on September 1 and delivered the opening remarks at the event. He initially focused on AI and the standard it needs to meet to improve lives, from all-day battery life to an enhanced visual experience.
“Today we’re going to take these abilities even further with the next generation of iPhone,” Ternus said at the event.
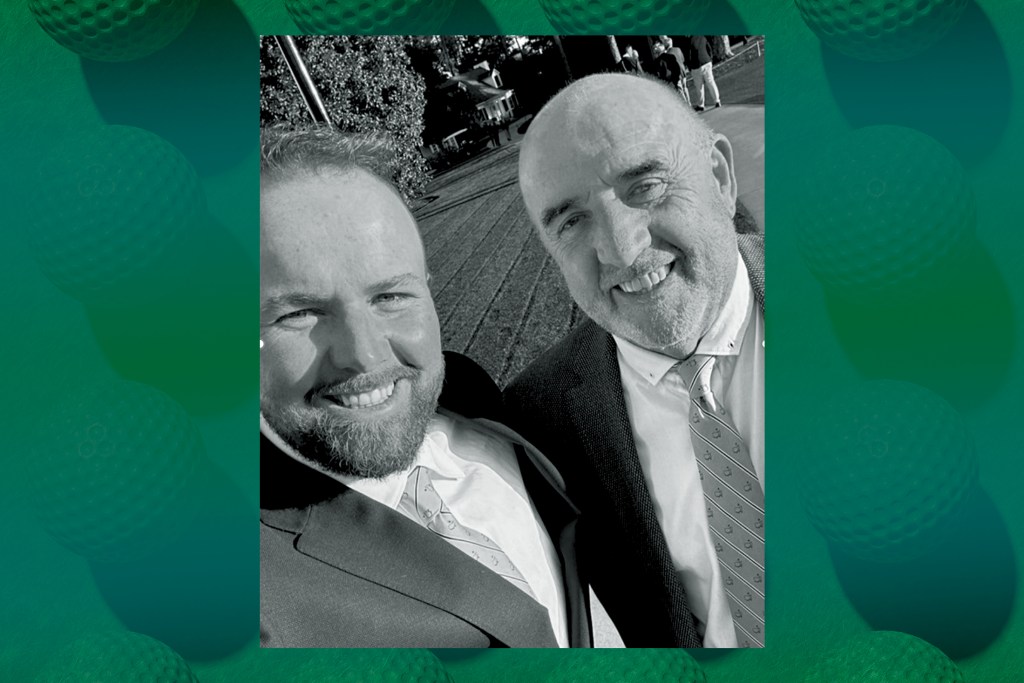
Golfing great Shane Lowry has won a Claret Jug, competed in Ryder Cups, and this year drained a hole-in-one at the Masters in front of a roaring crowd. But ask him about his proudest role, and he brings up his father Brendan, a former Gaelic football player, who needed both a hip and knee replacement. Shane took on the role and responsibilities of caregiver, and that experience is at the heart of his new partnership with Stryker, a global medical technology leader.
The company’s mission, says Joint Replacement division president Katherine Truppi, is simple: “Together with our customers, we are driven to make healthcare better.” Truppi says the Lowry partnership was a chance to shine a light on an “under-recognized role” — the caregiver — and to help other families feel less alone navigating a similar journey. I caught up with Shane as he prepares to battle it out at the 2026 Irish Open to talk about his dad, preventative health, and what it actually feels like to make a hole-in-one on one of golf’s biggest stages.
Dan Bova: What drew you to this partnership with Stryker? Shane Lowry: I’m in a fortunate position where I get the opportunity to meet so many people, and I get to pick the partnerships I choose to get involved with. This one for me was pretty straightforward — my dad had hip replacement surgery 10 or 12 years ago. His hip worked for a while and took pressure off his knee, but ultimately his knee was always the problem, and he ended up getting a knee replacement a few years ago. Both are Stryker products, and he’s still going pretty strong now.
A lot of us find ourselves in that “sandwich generation” — caring for aging parents while raising our own kids. What did it mean to be able to help your dad through this? I’ve got my own 18-month-old, so I’m forging my own path, building my own life, and taking care of my own family. But I feel like I’ve been in a fortunate position where I can take care of my parents, too. When it came time for my dad to get something done about his hip, I was able to go find the right people. My dad’s still only 67 — he’s young, so he doesn’t need that much taking care of. But when you’re able to help him through tougher times, it’s pretty fulfilling, to be honest.
Men in particular aren’t always great about taking care of themselves and tend to put off procedures like this. What would you say to someone who’s putting it off? There’s nothing wrong with going and getting a consultation and seeing how much it can help you. Because when you do that, you’ll realize you can go from not being able to do simple everyday jobs — my dad used to have trouble tying his shoelaces — to being back out there. As you get older, you want to be out and about with your grandkids, kicking a ball, playing golf. I think the hardest part for most people is the original step toward the consultation and starting the ball rolling. But once you do that, you realize it’s the right thing for you.
What do you say to entrepreneurs reading this — hard-charging people working a million hours, probably not eating great, probably not exercising as much as they should? It’s hugely important to take care of yourself, your body and your mind. A small bit of exercise and eating the right stuff and other stuff in moderation — you need to enjoy yourself at times too — but it’s very important to take care of yourself. I think as I’ve gotten older, having kids, I’ve realized I want to stay younger for longer. And I think if you have a friend or family member and you see them limping or struggling through everyday life, don’t be afraid to say something. Don’t be afraid to ask, “Do you think you should get this checked out?”
We’ve talked a lot about physical struggles — let’s talk about something a little more fun. What does it actually feel like to hit a hole-in-one? It’s a funny thing, because you’re obviously aiming there, right? That’s the object of golf — get the ball in the hole as quickly as you can. But you don’t stand up on a hole and go, “Right, I’m going to make a hole-in-one here.” You’re trying to hit the best shot you can, and sometimes it just comes off. I’ve been fortunate to make a few really good ones — most recently this year at the Masters, on the Saturday afternoon, playing with one of my good friends, I made a hole-in-one on the sixth. To put myself right into contention at one of the biggest tournaments in the world — there aren’t many better feelings, to be honest with you. It’s a funny thing too, because when it happens in the middle of your round, your adrenaline goes through the roof, and you actually spend the next twenty minutes trying to get your heart rate back down, because you’ve still got a lot of golf to play. But it’s a very cool thing to have 20,000 people there cheering you on.
Golf, like entrepreneurship, has a lot of highs and lows. What have you learned about staying even-keeled through it all? It’s an interesting sport we play because it’s such a long career, and I think it’s pretty similar to everyday life — nothing is plain sailing. It’s full of ups and downs, highs and lows, and it’s important to try and be as even as you can through it all. The last few months haven’t been the best for me, and I think it’s important to never lose sight of your goals or what you’re working toward — just keep grinding through, day by day, and eventually it’ll turn. It’s a stressful job at times, but it’s an amazing job. I’m very lucky to do what I do. I love competing at the highest level — it’s what I get out of bed for.
Golfing great Shane Lowry has won a Claret Jug, competed in Ryder Cups, and this year drained a hole-in-one at the Masters in front of a roaring crowd. But ask him about his proudest role, and he brings up his father Brendan, a former Gaelic football player, who needed both a hip and knee replacement. Shane took on the role and responsibilities of caregiver, and that experience is at the heart of his new partnership with Stryker, a global medical technology leader.
The company’s mission, says Joint Replacement division president Katherine Truppi, is simple: “Together with our customers, we are driven to make healthcare better.” Truppi says the Lowry partnership was a chance to shine a light on an “under-recognized role” — the caregiver — and to help other families feel less alone navigating a similar journey. I caught up with Shane as he prepares to battle it out at the 2026 Irish Open to talk about his dad, preventative health, and what it actually feels like to make a hole-in-one on one of golf’s biggest stages.
Dan Bova: What drew you to this partnership with Stryker? Shane Lowry: I’m in a fortunate position where I get the opportunity to meet so many people, and I get to pick the partnerships I choose to get involved with. This one for me was pretty straightforward — my dad had hip replacement surgery 10 or 12 years ago. His hip worked for a while and took pressure off his knee, but ultimately his knee was always the problem, and he ended up getting a knee replacement a few years ago. Both are Stryker products, and he’s still going pretty strong now.